
 Global Unified Endpoint Management Market | 2026-2036
Global Unified Endpoint Management Market Size, Share, and Industry Trends Forecast 2026-2036
Global Unified Endpoint Management Market Foresight
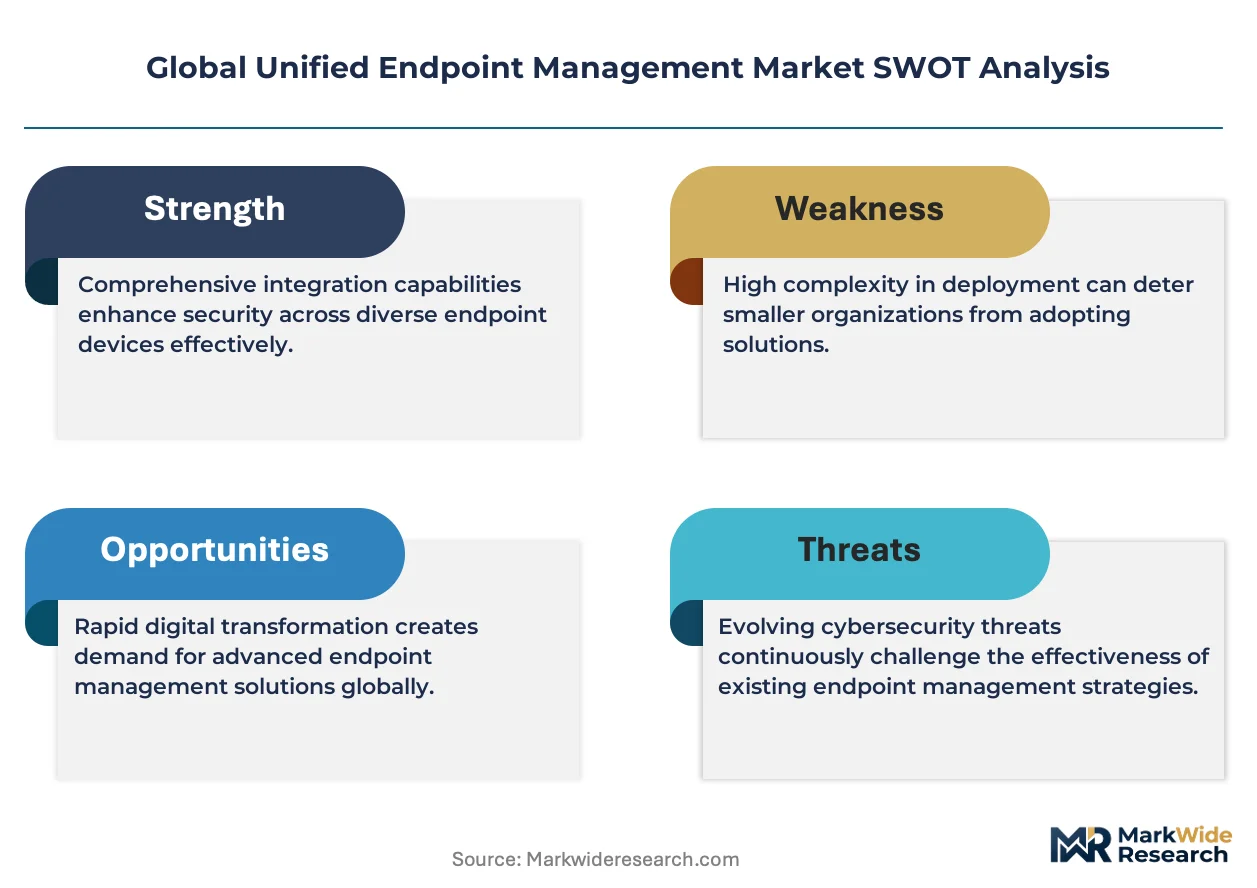
The capability gap between cloud-native platform engineering and legacy on-premises infrastructure is rotating competitive capital allocation across the vendor landscape. Microsoft leverages its Azure ecosystem to anchor enterprise migrations from fragmented endpoint tools. VMware competes through workspace virtualization integration that sustains hybrid workforce deployments. IBM Corporation differentiates via AI-driven threat analytics embedded across its unified endpoint suite.
Unified Endpoint Management denotes an integrated platform architecture that administers smartphones, laptops, tablets, IoT endpoints, and ruggedized field devices through a single policy engine, typically enforcing over-the-air configuration updates, certificate-based authentication, and containerized application segregation. Its primary commercial purpose is to reduce operational overhead while enforcing consistent security posture across geographically dispersed device fleets. Cloud deployment configurations are capturing accelerated enterprise traction as organizations retire data center footprints. Security and compliance solution offerings command premium positioning due to mandatory breach-notification statutes across multiple jurisdictions. Device management functions remain the volume foundation, though margin accretion is shifting toward analytics and reporting modules that feed enterprise security operations centers.
The EU AI Act, GDPR, and NIS2 Directive collectively mandate algorithmic transparency and incident reporting timelines that reshape procurement criteria for endpoint platforms serving European enterprises. The Federal Risk and Authorization Management Program in the United States and India's CERT-In directives impose comparable compliance burdens, fragmenting vendor certification requirements by geography. Stakeholders must evaluate whether their chosen platform architecture can absorb divergent regional audit protocols without parallel infrastructure duplication.
Market Dynamics
Cloud-native policy engines are compressing the operational overhead gap between distributed device fleets and centralized security operations, forcing legacy on-premises vendors to accelerate platform rearchitecture or cede enterprise accounts to hyperscaler-integrated alternatives.
Growth Catalysts
- EU NIS2 Directive:Mandatory incident reporting timelines and supply chain security obligations are compelling European financial institutions and critical infrastructure operators to consolidate fragmented endpoint tools into unified platforms.
- Zero-trust architecture mandates:US federal agencies and defense contractors are retiring perimeter-based security models, driving procurement of certificate-based authentication and continuous device verification capabilities.
- India's CERT-In directives:Data localization requirements and breach notification rules are accelerating enterprise adoption of sovereign cloud-hosted endpoint management among domestic conglomerates and multinational subsidiaries.
Market Restraints
- Hyperscaler concentration risk:Azure, AWS, and Google Cloud control the underlying infrastructure for the majority of cloud-native UEM deployments, creating vendor lock-in exposure for enterprise buyers.
- Legacy system integration friction:Mainframe-dependent financial institutions and manufacturing firms face multi-year migration timelines to achieve API compatibility with modern policy orchestration layers.
- Specialized mobile threat defense substitutes:Point solutions from Lookout and Zimperium compete for security budget allocation against integrated UEM suites in highly regulated mobile-first environments.
Strategic Opportunities
- German industrial IoT expansion:Automotive and machinery manufacturers are deploying ruggedized device management for factory floor equipment, creating demand for OT-IT converged endpoint platforms.
- AI-driven predictive remediation:Machine learning models that anticipate device failures and security anomalies before user impact are shifting procurement criteria toward analytics-native vendors.
- Telecom channel partnerships:Mobile network operators in India and Southeast Asia are bundling UEM with 5G enterprise connectivity, creating embedded distribution paths for platform providers.
Industry Challenges
- Cross-platform identity federation complexity:Enterprises struggle to harmonize Active Directory, Okta, and cloud-native identity providers into unified authentication flows across heterogeneous device fleets.
- Containerized application certification delays:Government and healthcare buyers face extended security evaluation timelines for app sandboxing technologies, compressing sales cycles and delaying revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Unified Endpoint Management Market |
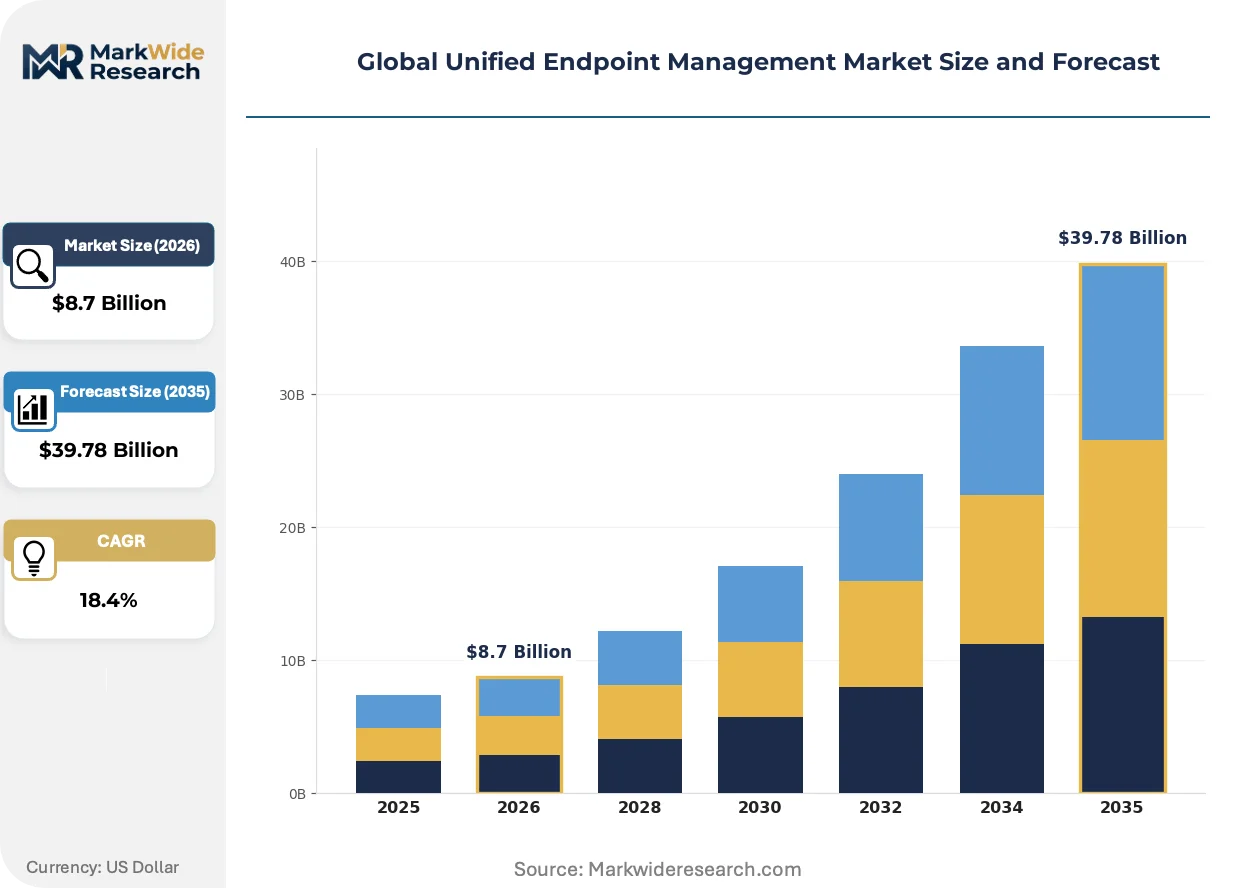
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $39.78 Billion |
| CAGR (2026 – 2036) | 18.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: On-Premises, Cloud, Hybrid, Managed Services Solution Offering: Device Management, Application Management, Security & Compliance, Analytics & Reporting End User: Information Technology Firms, Financial Institutions, Educational Institutions, Government Agencies Service Type: Consulting, Integration, Support & Maintenance, Training |
| Companies Covered | Microsoft, IBM Corporation, VMware, Citrix Systems, Ivanti, BlackBerry Limited, Sophos, SOTI, Zoho Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Unified Endpoint Management Market Shifts & Advancements
Endpoint management architectures are pivoting from device-centric policy enforcement to identity-centric continuous verification, compressing the functional boundary between UEM, zero-trust network access, and security service edge platforms.
Edge-native policy execution is supplanting cloud-roundtrip configuration management for latency-sensitive use cases. Manufacturing firms and healthcare providers are deploying lightweight agents that enforce security posture locally without constant connectivity to central consoles. This architectural shift is enabling real-time device compliance in disconnected or bandwidth-constrained environments while reducing cloud egress costs.
GDPR Article 32 and the EU AI Act are mandating algorithmic transparency in automated endpoint security decisions. Platform vendors must now document how machine learning models classify device risk and provide human-override mechanisms for quarantine actions. European enterprise procurement committees are prioritizing vendors with auditable decision trails and explainable AI certifications.
Consolidated security operations center budgets are compressing standalone endpoint tool procurement. CISOs are demanding that UEM platforms feed telemetry directly into SIEM and SOAR workflows rather than operating as isolated consoles. This integration imperative favors vendors with pre-built connectors to Splunk, Sentinel, and Chronicle, disadvantaging point solution providers without ecosystem partnerships.
Global Unified Endpoint Management Market Segmentation
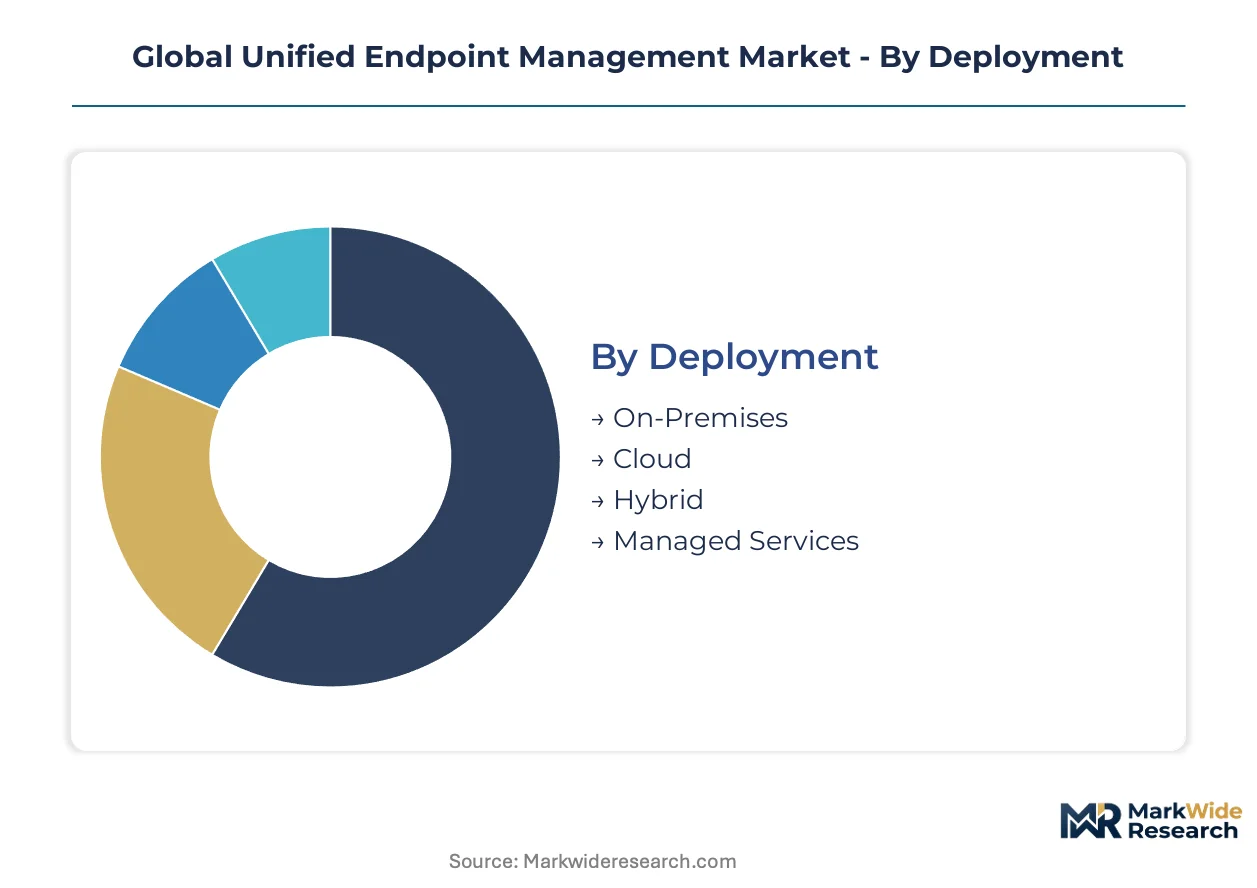
UEM procurement patterns diverge sharply across deployment architectures and buyer sophistication levels. Channel strategy must align with whether segments route through hyperscaler marketplaces, systems integrators, or direct enterprise sales motions.
Deployment:
Cloud-native configurations flow predominantly through hyperscaler marketplaces and managed service provider channels, while on-premises deployments retain direct vendor relationships with systems integrators.
- On-Premises:Legacy data center installations requiring dedicated hardware infrastructure and air-gapped policy orchestration. Financial institutions in Germany and defense contractors in the United States sustain demand due to sovereignty requirements and classified network restrictions.
- Cloud:Multi-tenant SaaS architectures with API-native integration into Azure, AWS, and Google Cloud identity fabrics. Indian conglomerates and Southeast Asian telecoms are migrating fastest to reduce capital expenditure and accelerate deployment timelines.
- Hybrid:Split-policy engines maintaining sensitive workloads on-premises while extending cloud management to distributed field devices. Manufacturing firms across automotive supply chains favor this architecture for OT-IT convergence.
- Managed Services:Third-party operational delegation where MSPs assume full lifecycle management of endpoint fleets. Mid-market enterprises in the United States and United Kingdom purchase through channel partners to address internal skills gaps.
On-Premises dominates installed base. Cloud is where expansion concentrates.
Solution Offering:
Margin profiles stratify across functional modules, with security and analytics commanding premium pricing while device management operates as a volume foundation.
- Device Management:Core enrollment, inventory, and over-the-air configuration capabilities. Every deployment includes this foundation, though pricing pressure intensifies as hyperscalers bundle basic functionality at marginal cost.
- Application Management:Containerized app distribution, license tracking, and enterprise app store curation. Healthcare providers in the United States and logistics operators in Germany prioritize this for field workforce enablement.
- Security & Compliance:Certificate-based authentication, conditional access policies, and breach response automation. This module captures the steepest expansion trajectory as GDPR, NIS2, and CERT-In mandates harden procurement requirements.
- Analytics & Reporting:Telemetry aggregation feeding SIEM and SOAR workflows with predictive risk scoring. Large financial institutions in the United States and India demand native Splunk and Microsoft Sentinel connectors.
Device Management anchors revenue volume. Security & Compliance drives margin expansion.
End User:
Buyer sophistication and procurement cycle length vary dramatically across verticals, with government and financial services imposing the most stringent certification requirements.
- Information Technology Firms:Technology vendors and service providers managing heterogeneous device fleets for clients. These buyers prioritize API extensibility and multi-tenant architecture to support downstream customer segmentation.
- Financial Institutions:Banks, insurers, and payment processors subject to PCI-DSS, SOX, and sector-specific breach notification rules. German and Indian regulators impose particularly granular audit trail requirements.
- Educational Institutions:K-12 districts and universities managing student and faculty device programs. Budget constraints favor cloud deployment with simplified policy templates and parental control integration.
- Government Agencies:Federal, state, and municipal entities with FedRAMP, StateRAMP, or equivalent sovereign certification requirements. United States federal agencies mandate zero-trust architecture compliance.
Financial Institutions contribute the largest deal sizes. Government Agencies present the longest sales cycles.
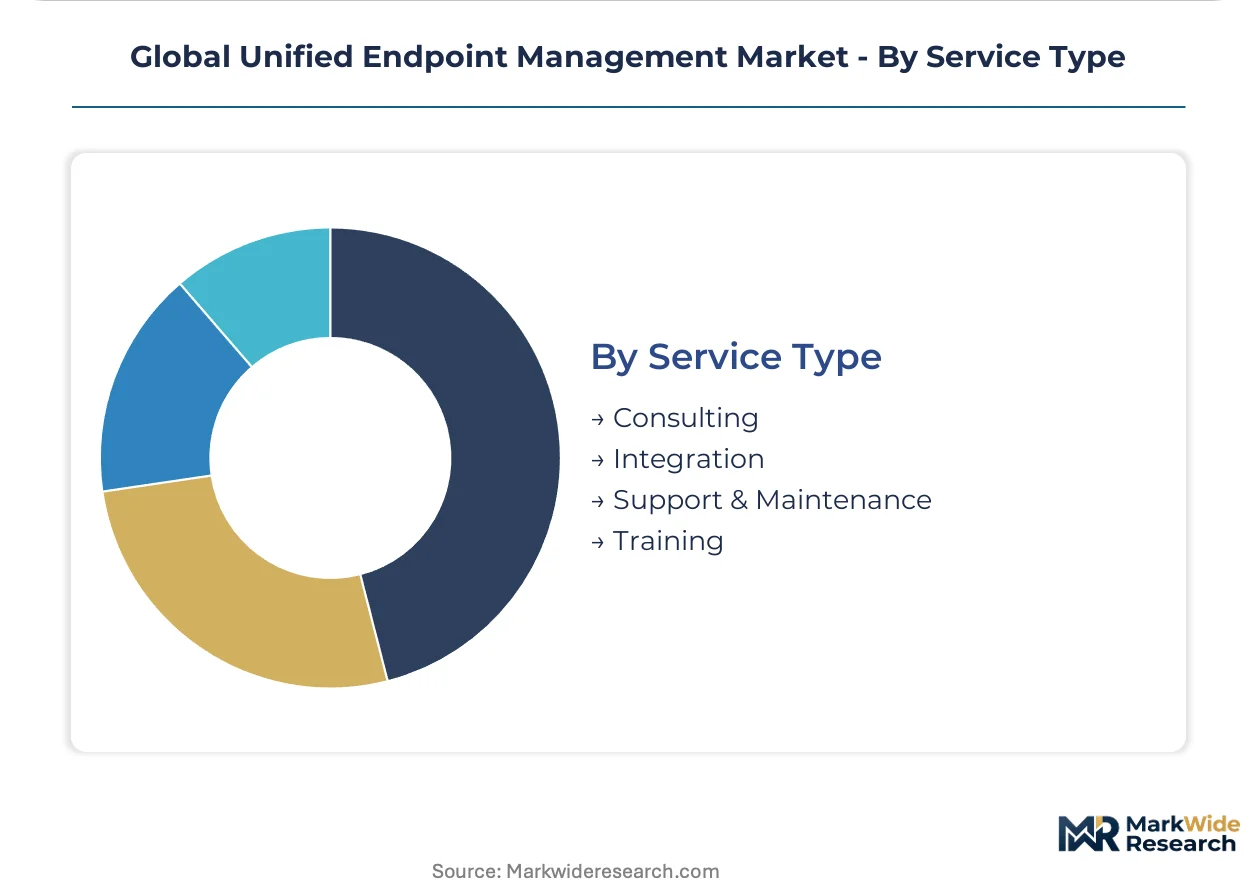
Service Type:
Professional services attach rates correlate inversely with buyer IT maturity, with consulting and integration commanding highest margins in complex legacy migration scenarios.
- Consulting:Architecture assessment, policy design, and compliance gap analysis. European enterprises engaging NIS2 readiness programs and Indian firms navigating CERT-In localization rules drive current demand.
- Integration:Connector development, identity federation, and SIEM workflow configuration. Manufacturing firms in Germany and healthcare networks in the United States require extensive custom integration for OT-IT convergence.
- Support & Maintenance:Tiered technical assistance, patch management, and uptime guarantees. Recurring revenue streams stabilize vendor cash flow across all deployment types.
- Training:Administrator certification and end-user enablement programs. Educational institutions and government agencies mandate structured knowledge transfer for procurement approval.
Integration services capture peak project value. Support & Maintenance underpins recurring revenue predictability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies. Financial institutions in Germany demand sovereign cloud architectures with air-gapped policy engines, while Indian conglomerates prioritize rapid cloud migration to reduce capital expenditure. United States federal agencies mandate zero-trust compliance, creating procurement complexity distinct from commercial buyers.
United States
Federal agencies and defense contractors drive demand for certificate-based authentication and continuous device verification capabilities. FedRAMP mandates impose rigorous certification timelines that filter vendor participation. The Washington D.C. metropolitan corridor concentrates procurement authority for civilian and defense endpoint security frameworks.
Germany
Automotive manufacturers and machinery producers deploy ruggedized device management for factory floor equipment requiring OT-IT convergence. The EU AI Act and NIS2 Directive mandate algorithmic transparency and incident reporting timelines that reshape procurement criteria. Industrial clusters in Bavaria and Baden-Württemberg anchor demand for sovereign cloud-hosted endpoint platforms.
India
Domestic conglomerates and multinational subsidiaries accelerate adoption of sovereign cloud-hosted endpoint management to satisfy data localization imperatives. CERT-In directives impose breach notification rules and data residency requirements that favor domestic cloud providers. Mumbai and Bangalore metropolitan areas concentrate financial services and technology firm procurement activity.
United Kingdom
Mid-market enterprises purchase managed services through channel partners to address internal skills gaps in endpoint lifecycle management. The UK GDPR and sector-specific financial regulations sustain demand for audit-ready compliance modules. London's financial services cluster drives premium pricing for security and analytics integration.
Japan
Manufacturing firms and healthcare providers deploy edge-native policy execution for latency-sensitive use cases in bandwidth-constrained environments. METI industrial security guidelines encourage domestic platform adoption for critical infrastructure protection. The Tokyo-Osaka industrial corridor sustains hybrid deployment architectures balancing cloud agility with on-premises control.
Global Unified Endpoint Management Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier, with hyperscaler-integrated platforms commanding enterprise migrations while point solution vendors defend mobile-first niches. The vendor landscape compresses around three strategic archetypes: cloud-native ecosystem anchors, virtualization-integrated workspace providers, and AI-native security analytics specialists. Competitive intensity manifests through strategic partnership formations with telecom operators and hyperscaler marketplace listings rather than direct price confrontation.
Among ecosystem-integrated platform providers, Microsoft leverages its Azure identity fabric to anchor enterprise consolidations from fragmented toolsets, while IBM Corporation occupies a position exemplifying AI-driven threat analytics embedded across unified endpoint suites. VMware represents the virtualization-integrated archetype sustaining hybrid workforce deployments through workspace orchestration capabilities.
| Leading Market Players |
|---|
| Microsoft |
| IBM Corporation |
| VMware |
| Citrix Systems |
| Ivanti |
| BlackBerry Limited |
| Sophos |
| SOTI |
| Zoho Corporation |
| Others |
Supply & Pricing Matrix
FedRAMP certification requirements in the United States simultaneously gate vendor qualification and stratify price positioning, as only accredited platforms can serve federal agencies while compliance investment justifies premium SaaS tiers over standard commercial offerings.
Pricing Analysis
Long-term enterprise subscription contracts dominate UEM procurement, with three-year offtake agreements locking in volume discounts for financial institutions and government agencies. Price differentiation hinges on FedRAMP authorization tier and native SIEM connector depth, with hyperscaler marketplace listings compressing entry-level SaaS margins. Cost compression in mid-market tiers intensifies as Microsoft bundles baseline device management at marginal cost within Azure subscriptions. Educational institutions exhibit highest price sensitivity due to constrained IT budgets, while defense contractors accept substantial premiums for air-gapped deployment architectures.
Supply Chain Analysis
The United States and India anchor cloud infrastructure supply for UEM platforms, with domestic data center expansion accelerating to meet sovereignty requirements under CERT-In and FedRAMP directives. Platform engineering draws from specialized talent pools in Bangalore and Seattle, while certificate authority partnerships rest on Entrust and DigiCert root trust hierarchies. Single-source vulnerability concentrates in hyperscaler compute layers, as Azure, AWS, and Google Cloud underpin most multi-tenant deployments. Distribution runs through hyperscaler marketplaces, systems integrators, and telecom operator bundles across enterprise segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat arena where regulatory entrenchment creates durable competitive positioning, as compliance certification timelines and audit trail investments erect switching costs that fragment challenger viability.
For Market Incumbents: Secure FedRAMP and StateRAMP authorizations as non-negotiable table stakes for federal agency retention, while embedding predictive analytics modules to defend against AI-native security specialists. Channel control through telecom operator partnerships in India and Southeast Asia limits emerging entrant distribution access. Capacity addition in sovereign cloud regions addresses data localization mandates without duplicating engineering overhead. For New Entrants and Emerging Players: FedRAMP authorization fast-tracks through agency-sponsored pilot programs offer the most viable entry vector against established vendor consolidation. White-space concentrates in German industrial IoT endpoint management, where OT-IT convergence requirements outpace incumbent platform adaptation. Target mid-market manufacturing firms in Baden-Württemberg through MSP channel partnerships, leveraging edge-native policy execution as differentiated positioning against cloud-centric alternatives. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting downward across cloud-native deployment architectures, reducing barrier-to-entry estimates for platform engineering while amplifying certification and compliance cost concentration. Long-term viability favors vendors with embedded hyperscaler relationships and pre-built SIEM connectors. Acquisition targets should demonstrate FedRAMP authorization progress and vertical-specific policy templates. The signal to watch is telecom operator bundling momentum, as 5G enterprise connectivity partnerships indicate distribution leverage inflection.| Strategic Initiative | Industry Significance |
|---|---|
| FedRAMP Authorization Acceleration | Unlocks federal agency procurement pipelines under zero-trust mandates from OMB and CISA directives. |
| Telecom Operator Partnership | Embeds UEM distribution within 5G enterprise connectivity bundles across Indian and Southeast Asian markets. |
| Edge-Native Policy Execution | Addresses latency-sensitive manufacturing and healthcare use cases beyond cloud-roundtrip limitations. |
| SIEM Connector Ecosystem Expansion | Feeds telemetry directly into Splunk, Microsoft Sentinel, and Chronicle workflows for SOC integration. |
| Sovereign Cloud Regional Expansion | Satisfies CERT-In data localization and EU AI Act algorithmic transparency requirements without infrastructure duplication. |
Research Methodology
The analysis maps cloud-native, hybrid, and on-premises deployment architectures, each validated through primary interviews with CISOs, IT procurement officers, platform engineers, and telecom enterprise sales directors. Secondary validation draws from FedRAMP authorization databases, hyperscaler marketplace disclosure filings, SEC 10-K infrastructure segments, and EU NIS2 implementation guidance documents. Bottom-up triangulation across deployment model adoption curves converges with top-down market sizing from vendor revenue disclosures and channel partner volume estimates.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework models segmentation across deployment architecture, solution offering tier, end-user vertical, and regional regulatory cluster. CAGRs derive from installed base migration velocity and net new customer acquisition patterns. Forecast inputs include hyperscaler capex trajectory for sovereign cloud regions and CERT-In compliance deadline pacing for Indian enterprise adoption.
Underlying assumptions cover regulatory implementation timelines, certification backlog clearance rates, and hyperscaler pricing stability, with deviation risk concentrated in NIS2 enforcement variance across EU member states and potential FedRAMP authorization delays. Recalibration cycles align with material shifts in breach notification statute expansion and telecom bundling contract announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Digital Solutions
Digital Experience Technology Market
Digital Solutions
G2P Systems Market
Digital Solutions
Enterprise Asset Management (EAM) Market
Digital Solutions
Enterprise Mobility in Energy Sector Market
Digital Solutions
Customer Engagement Hub (CEH) Market
Digital Solutions
Interactive Projector Market
Digital Solutions
Global Content Moderation Solutions Market
Digital Solutions
Mobile Ticketing Market
Digital Solutions
Saudi Arabia ICT Market
Digital Solutions
Digital Workplace Market
Digital Solutions
Global Cloud POS Market
Digital Solutions
Remote Control Duplicators Market
Digital Solutions
Global Mobile Workforce Management Market
Digital Solutions
Multichannel Order Management Market
Digital Solutions
Data Cleansing Tools Market
Digital Solutions
Application Performance Management Market