
 Asia-Pacific School Furniture Market | 2026-2036
Asia-Pacific School Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific School Furniture Market Outlook
Vocational training centers are hardening their share of institutional procurement across the Asia-Pacific. Steelcase Inc. leverages its ergonomic research infrastructure to serve premium private institutions in Australia and Singapore. Sebel Furniture anchors its position through durable polymer seating lines purpose-built for high-traffic Australian public schools. Haskell Education differentiates via active-learning furniture configurations designed for collaborative STEM classrooms.
Asia-Pacific school furniture encompasses desks, chairs, cabinets, and shelving engineered to ergonomic, safety, and durability specifications for educational environments. Manufacturing typically involves laminated wood composites, powder-coated steel frames, and injection-molded polypropylene to meet load-bearing and flammability standards while supporting 6-8 hour daily student use. The chairs segment leads volume due to universal replacement cycles across public school systems, while composite materials represent the fastest-expanding material category as institutions seek lighter, more durable alternatives to solid wood. Distribution through direct sales channels captures the largest margin pools by bypassing intermediary markups on bulk institutional contracts.
Japan's METI enforces JIS standards for school equipment stability and load capacity, while Australia's state-level education departments impose independent procurement criteria for indigenous content and local manufacturing. India's BIS certification for furniture safety is becoming a de facto gate for suppliers bidding on government school tenders. Stakeholders must monitor how divergent national standards fragment product portfolios and whether regional harmonization efforts emerge to simplify cross-border supply strategies.
Market Dynamics
China's GB standards for student desk dimensions are tightening product specifications nationwide, forcing manufacturers to retool production lines and fragmenting regional supply bases as compliance costs diverge across provinces.
Growth Catalysts
- India's tier-2 K-12 expansion:State governments are building new campuses in secondary cities, creating concentrated demand zones for institutional furniture procurement.
- Japan's JIS stability mandates:METI enforcement of load capacity standards is accelerating replacement cycles for aging classroom equipment in public schools.
- Ergonomic seating adoption:Southeast Asian public school systems are expanding budgets for posture-supportive designs, driven by occupational health research integration into education policy.
Market Restraints
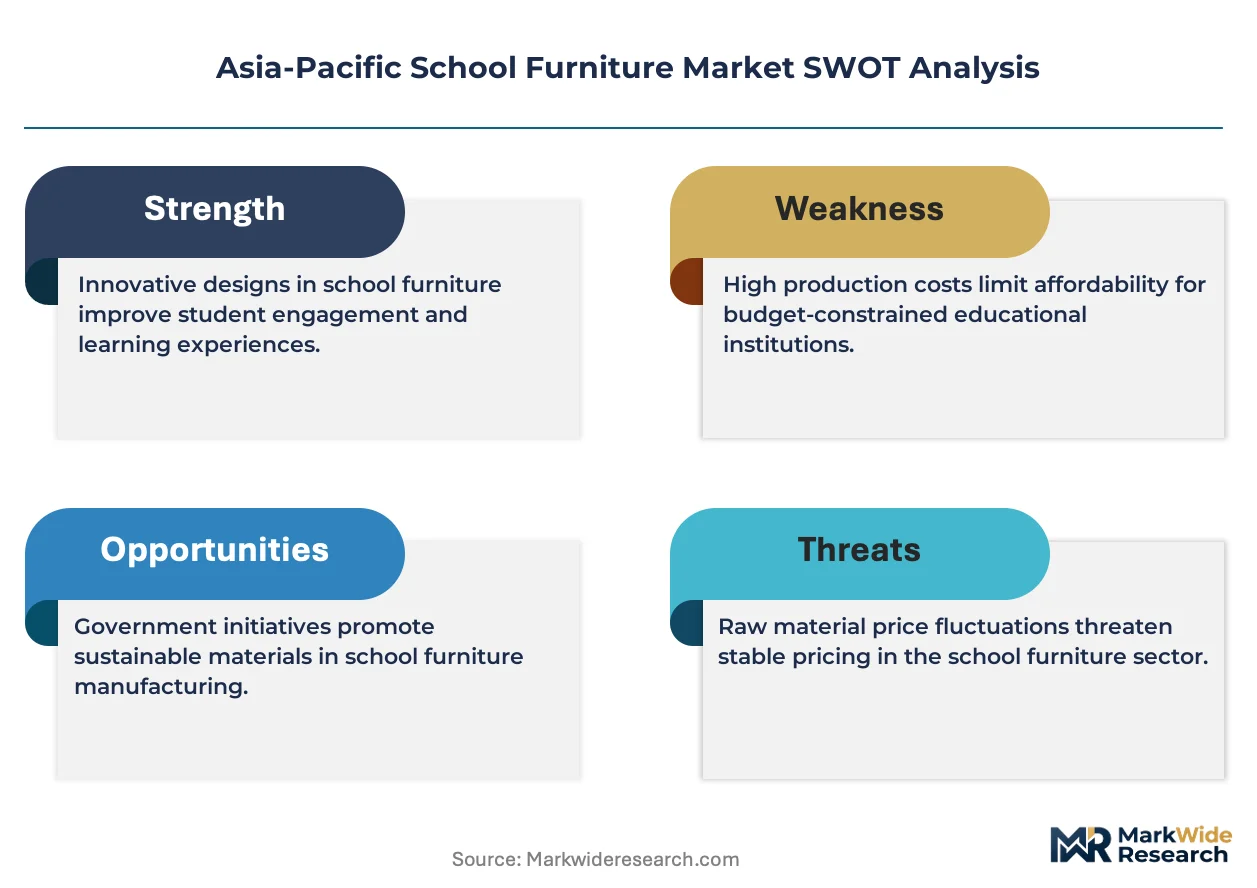
- Steel and polymer input volatility:Powder-coated steel frame costs fluctuate with regional metal markets, compressing margins for mid-tier manufacturers serving price-sensitive government tenders.
- Fragmented certification requirements:Australia's state-level indigenous content rules and India's BIS safety gates create redundant testing burdens that delay product launches.
- Solid wood substitution pressure:Laminated composites and injection-molded polypropylene are displacing timber in institutional specifications, stranding traditional carpentry supply chains.
Strategic Opportunities
- Vocational training center buildouts:Technical institutes across Indonesia and Vietnam are hardening procurement volumes for durable, high-traffic seating configurations.
- Active-learning furniture convergence:Collaborative STEM classroom designs integrating mobility and modularity are penetrating premium private institutions in Singapore and Australia.
- Direct sales channel development:Bulk institutional contracts are bypassing distributor markups, capturing margin pools for manufacturers with dedicated government sales teams.
Industry Challenges
- Cross-border standard harmonization gaps:Divergent national safety protocols between Japan, China, and Australia force product portfolio fragmentation that complicates regional scale economies.
- Ergonomic research talent scarcity:Industrial design capabilities for anthropometric seating development concentrate in Japan and Australia, leaving Southeast Asian manufacturers dependent on licensed foreign designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific School Furniture Market |
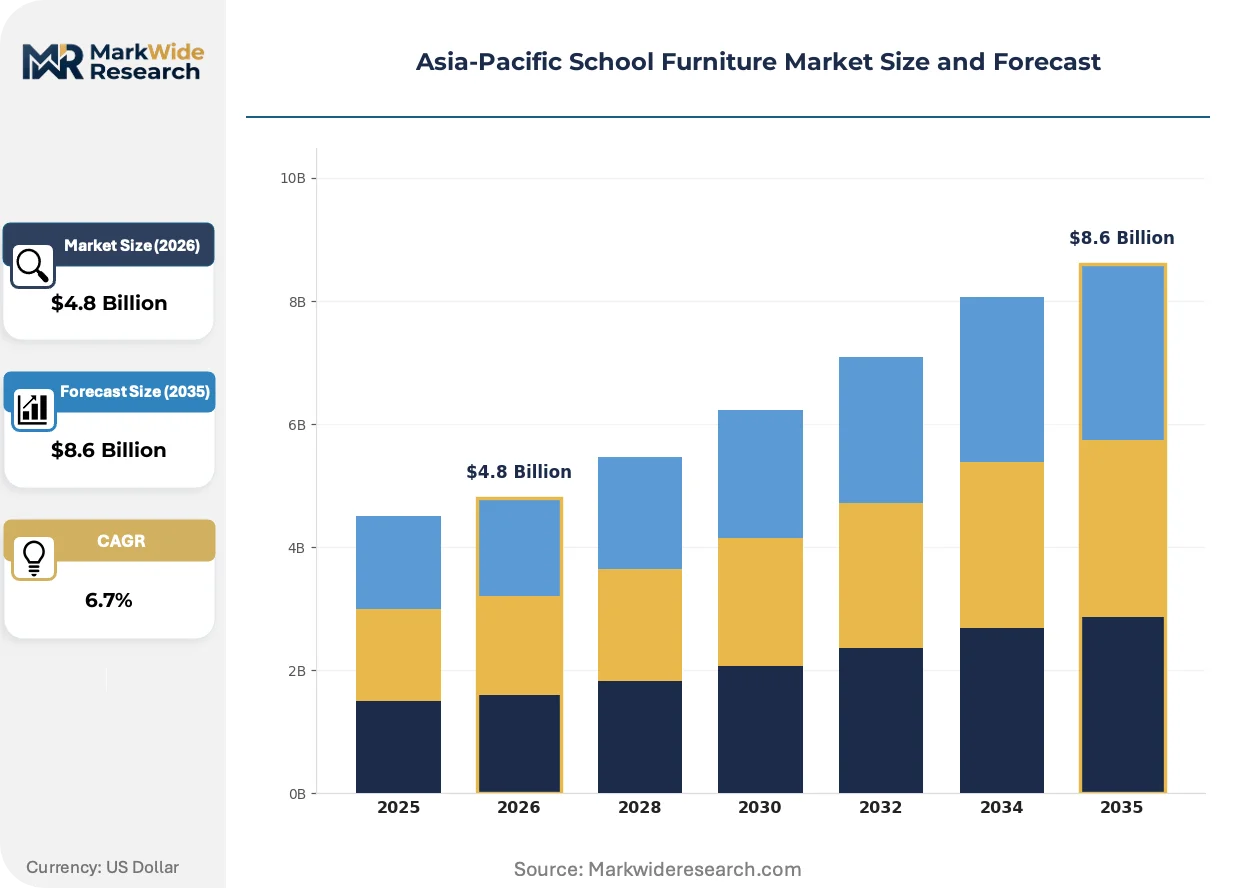
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.6 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Cabinets, Shelves Material: Wood, Metal, Plastic, Composite End User: Public Schools, Private Institutions, Vocational Training Centers, Special Needs Facilities Distribution Channel: Online Retail, Direct Sales, Distributors, Showrooms |
| Companies Covered | Haworth Inc., Steelcase Inc., Knoll Inc., MillerKnoll Inc., Teknion, Haskell Education, Virco Manufacturing Corporation, Sebel Furniture, Fleetwood Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific School Furniture Market Strategic Shifts
Composite material engineering and procurement digitization are restructuring how Asia-Pacific educational institutions source and deploy learning environments, with sustainability specifications and channel disintermediation emerging as parallel transformation vectors.
Injection-molded polypropylene seating with reinforced rib structures is expanding into high-traffic Australian public schools and Indian government campuses. The material's load-bearing capacity and flammability compliance match institutional durability requirements while reducing unit weight for transport efficiency. This expansion is compressing demand for traditional solid wood and metal-frame alternatives in price-sensitive procurement segments.
China's GB standards tightening for student desk dimensions is forcing nationwide retooling of manufacturing lines. The industrial consequence is a bifurcation between compliant suppliers capturing eastern seaboard contracts and non-compliant producers retreating to interior provinces or export markets. India's BIS certification for furniture safety is becoming the parallel gate for government school tenders, with manufacturers accelerating testing timelines to meet state-level bid deadlines.
Institutional buyers are consolidating vendor relationships around full-service contract partners who bundle installation, maintenance, and replacement scheduling. Traditional distributor networks serving small private schools are losing share to manufacturer-direct sales teams with dedicated government liaison capabilities. This consolidation is most visible in Australia's state education departments and India's centralized state procurement authorities, where multi-year framework agreements now dominate volume allocation.
Asia-Pacific School Furniture Market Segmentation
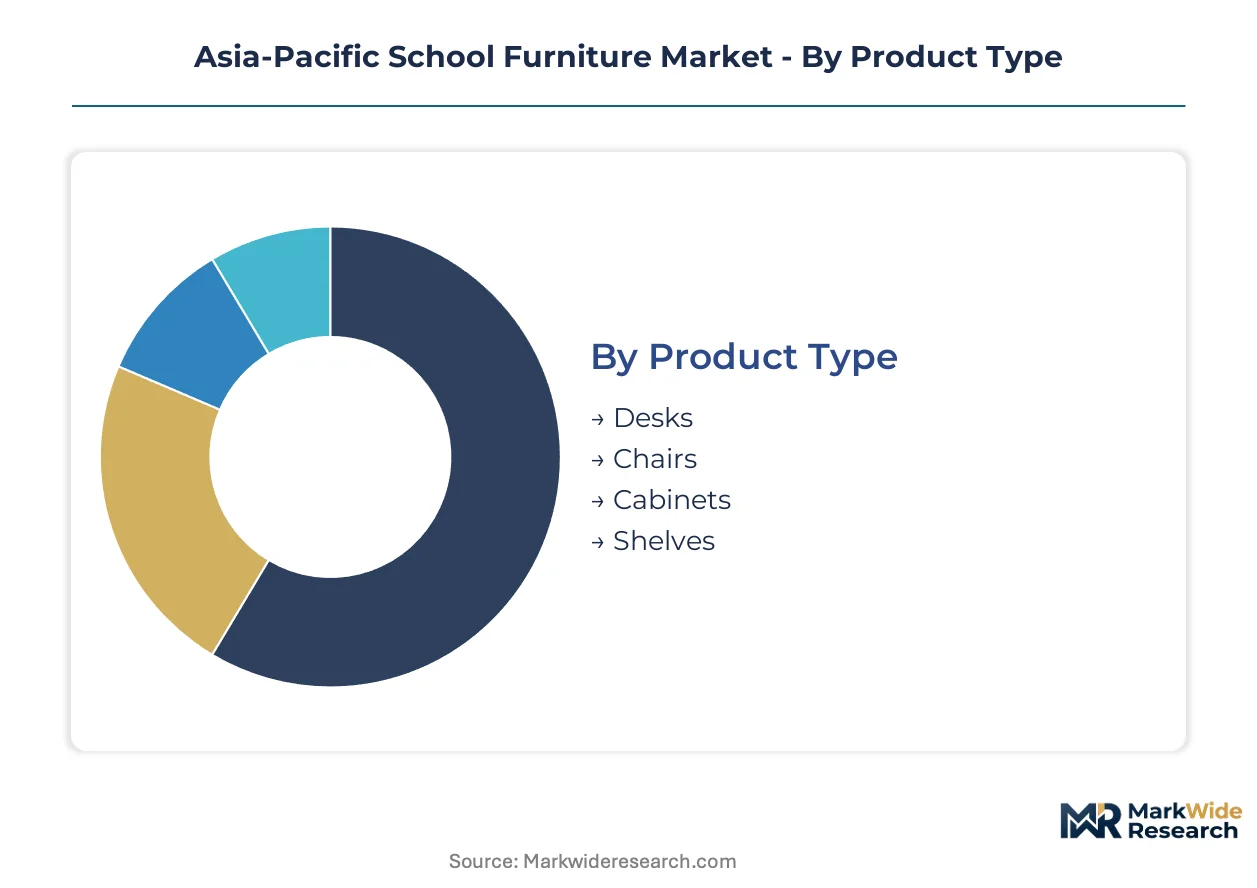
Segmentation in Asia-Pacific school furniture reveals how procurement specifications diverge across institutional tiers. Material choices and distribution channels fragment as national standards tighten, forcing suppliers to maintain parallel product portfolios for different compliance environments.
Product Type:
Ergonomic specifications and replacement cycles differentiate demand across furniture categories, with institutional buyers prioritizing durability metrics over aesthetic considerations.
- Chairs:Posture-supportive designs with adjustable seat heights dominate procurement volumes across Southeast Asian public systems. India's state governments specify reinforced polypropylene frames for high-traffic government campuses, while Australian state departments mandate lumbar support integration for extended student use periods.
- Desks:Laminated wood composite surfaces with powder-coated steel frames balance load capacity against unit weight for transport efficiency. China's GB standards tightening for desk dimensions is fragmenting regional supply bases as eastern seaboard manufacturers retool for compliance.
- Cabinets:Lockable storage units with fire-retardant finishes serve administrative and classroom organization needs in Japanese public schools under METI stability mandates.
- Shelves:Modular shelving systems support library and STEM resource centers in Singapore's premium private institutions.
Chairs lead on scale; desks lead on momentum as dimensional standardization accelerates replacement timelines.
Material:
Cost-performance tradeoffs and sustainability specifications are restructuring raw material sourcing across institutional procurement tiers.
- Composite:Engineered wood-polymer laminates and reinforced rib structures deliver load-bearing capacity at reduced unit weights. Australian public schools and Indian government campuses are consolidating procurement around these specifications to cut transport and installation costs.
- Plastic:Injection-molded polypropylene seating lines from Sebel Furniture anchor high-traffic deployments through flammability compliance and surface durability. The material's substitution pressure is stranding traditional timber supply chains in price-sensitive segments.
- Metal:Powder-coated steel frames remain standard for desk support structures despite input cost volatility from regional metal markets.
- Wood:Solid timber specifications persist in premium private institutions but face displacement from laminated alternatives in mass procurement.
Composite materials lead on momentum; plastic leads on deployment scale across high-volume institutional contracts.
End User:
Procurement centralization and budget allocation patterns create distinct demand profiles across institutional categories.
- Public Schools:State-level tender processes in India and Australia's education departments concentrate volume through multi-year framework agreements. India's tier-2 city expansion is creating concentrated demand zones for bulk institutional contracts.
- Vocational Training Centers:Technical institutes across Indonesia and Vietnam are hardening procurement volumes for durable, high-traffic seating configurations designed for workshop and laboratory environments.
- Private Institutions:Premium schools in Singapore and Australia source active-learning furniture configurations with mobility and modularity features for collaborative STEM classrooms.
- Special Needs Facilities:Adaptive furniture with enhanced stability and accessibility specifications serves specialized educational environments under distinct procurement criteria.
Public schools lead on scale; vocational training centers lead on procurement momentum as technical institute buildouts accelerate.
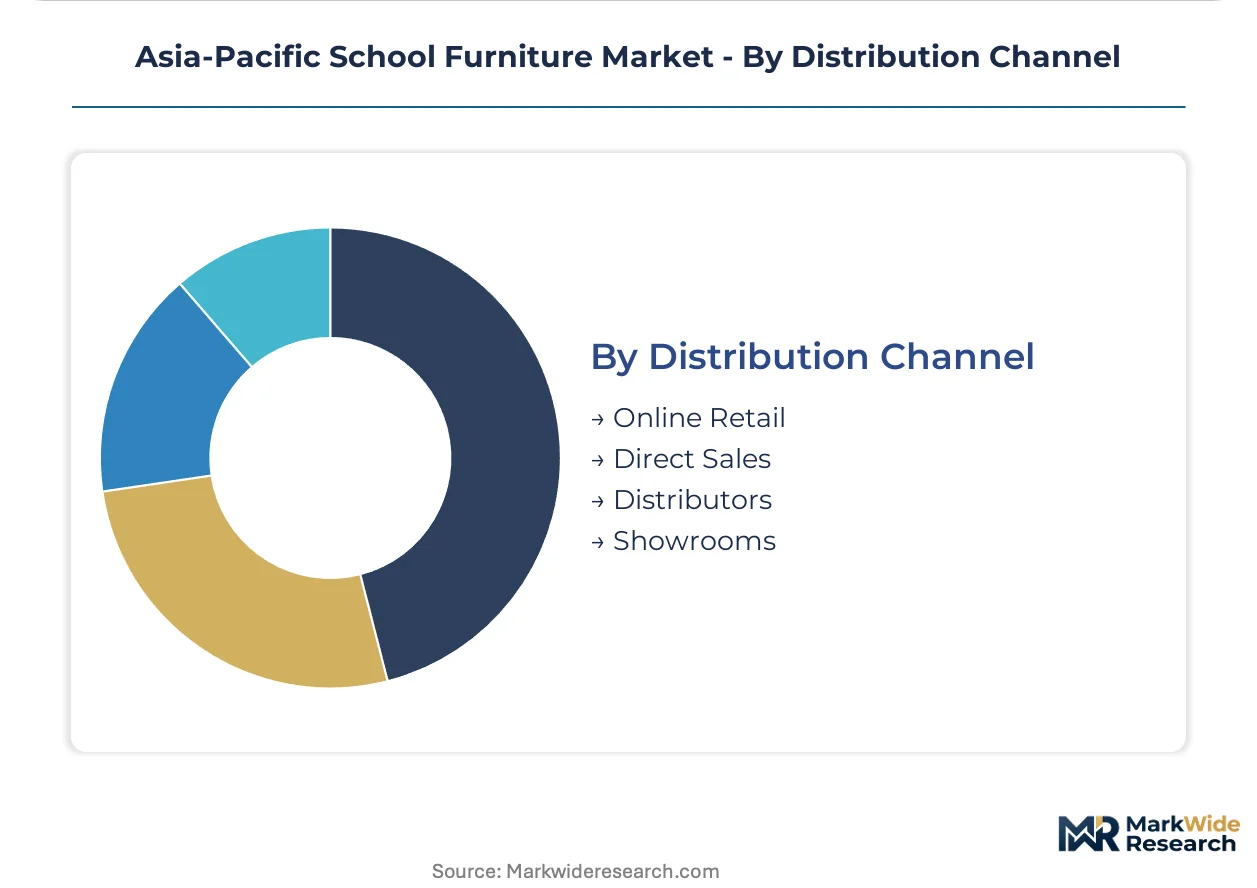
Distribution Channel:
Channel economics and government liaison capabilities determine margin capture across institutional sales.
- Direct Sales:Manufacturer teams with dedicated government procurement expertise bypass distributor markups on bulk contracts. Australia's state education departments and India's centralized state authorities now allocate volume primarily through multi-year framework agreements with direct vendors.
- Distributors:Traditional networks serving small private schools are losing share as institutional buyers consolidate vendor relationships around full-service contract partners.
- Online Retail:Digital procurement platforms facilitate specification comparison for smaller institutional buyers and replacement part sourcing.
- Showrooms:Physical display spaces support premium private school selection processes where ergonomic testing and material evaluation precede purchase decisions.
Direct sales lead on momentum; distributors retain residual scale in fragmented private school segments.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are reshaping manufacturing footprints across the Asia-Pacific school furniture sector. Compliance cost divergence between standardized and non-standardized markets is driving production migration toward provinces and countries with harmonized certification regimes.
China
GB standards tightening for student desk dimensions is forcing nationwide retooling of manufacturing lines. MIIT oversight of industrial quality frameworks is accelerating compliance investments in eastern seaboard provinces. Zhejiang and Guangdong clusters are absorbing contract volume from interior manufacturers retreating toward export markets.
India
State government K-12 campus construction in tier-2 cities is generating concentrated procurement demand for institutional furniture. BIS certification requirements for furniture safety are becoming mandatory gates for government tender participation. Maharashtra and Gujarat industrial corridors are scaling polymer seating production to meet state-level bid deadlines.
Japan
METI enforcement of JIS stability and load capacity standards is accelerating replacement cycles for aging public school equipment. JIS certification mandates for school equipment stability are filtering supplier eligibility for municipal contracts. Osaka-Nagoya manufacturing belt is specializing in high-durability steel-frame desk configurations.
Australia
State education departments are consolidating procurement through multi-year framework agreements with direct vendors. Indigenous content rules and local manufacturing criteria are fragmenting supplier compliance requirements across Queensland, New South Wales, and Victoria. Melbourne-Sydney corridor is anchoring polymer seating production for high-traffic public school deployments.
Vietnam
Technical institute buildouts are hardening procurement volumes for durable workshop and laboratory seating. National technical standards for educational equipment are formalizing under Ministry of Education and Training oversight. Ho Chi Minh City industrial zones are attracting contract manufacturers serving ASEAN vocational training center demand.
Asia-Pacific School Furniture Market Competitive Environment
Branded specialists and contract manufacturers split share differently across segments, with premium private institutions favoring design-forward portfolios while public systems prioritize cost-engineered durability. The vendor base concentrates around three strategic archetypes: multinational ergonomic research specialists, regional polymer seating fabricators, and state-affiliated contract manufacturers serving government tenders. Competitive positioning hardens through dedicated government liaison capabilities and multi-year framework agreement capture. M&A activity and direct sales channel development represent the dominant competitive moves reshaping margin capture.
Within the multinational specialist tier, Steelcase Inc. and Haworth Inc. exemplify research-backed positioning for premium institutional segments. Haskell Education occupies a position within the active-learning configuration niche. Sebel Furniture anchors the regional polymer durability archetype for high-traffic public school deployments. Virco Manufacturing Corporation represents the scale-driven contract manufacturing model serving price-sensitive government procurement channels.
| Leading Market Players |
|---|
| Haworth Inc. |
| Steelcase Inc. |
| Knoll Inc. |
| MillerKnoll Inc. |
| Teknion |
| Haskell Education |
| Virco Manufacturing Corporation |
| Sebel Furniture |
| Fleetwood Group |
| Others |
Value Chain & Pricing Dynamics
China's dual carbon goals are tightening emissions benchmarks for laminated wood composite production, gating qualified supply to eastern seaboard manufacturers and bifurcating premium-tier pricing access from interior province competitors. This environmental mandate concentrates compliant capacity while forcing non-compliant producers toward discount export channels or domestic economy segments.
Pricing Analysis
Distributor margin layers of 15-25% compress as Australia's state education departments and India's centralized procurement authorities consolidate volume through direct manufacturer contracts. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and after-sales bundling, with BIS-certified and JIS-compliant products commanding sustained premiums. Cost compression in the standard tier is intensifying because powder-coated steel frame input volatility feeds through from regional metal markets. Government tender participants exhibit highest price sensitivity, while premium private institutions in Singapore prioritize ergonomic specification over unit cost.
Supply Chain Analysis
Workforce availability for injection-molding and powder-coating operations concentrates manufacturing gravity in China's Zhejiang and Guangdong clusters, India's Maharashtra-Gujarat corridor, and Vietnam's Ho Chi Minh City industrial zones. Raw material dependencies rest on laminated wood composites from certified sustainable forestry, powder-coated steel from regional metal markets, and polypropylene resin from petrochemical feedstock. Single-source vulnerability looms where BIS and JIS testing capacity bottlenecks delay product qualification for government tenders. Distribution runs through manufacturer-direct sales teams with dedicated government liaison capabilities, bypassing traditional distributor networks on bulk institutional contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Asia-Pacific school furniture market compounds steadily as state-funded K-12 expansion across India and Southeast Asia generates predictable replacement-driven procurement cycles. Public education budget hardening provides durable demand visibility regardless of private-sector cyclicality.
For Market Incumbents: Acquire dedicated government sales and liaison capabilities to deepen framework agreement capture. Sebel Furniture's polymer seating durability and Steelcase's ergonomic research infrastructure demonstrate how specialized asset bases defend against mid-tier price competition. Capacity addition in India's Maharashtra-Gujarat corridor aligns with tier-2 city campus buildout timelines. Certification investment in BIS and JIS compliance accelerates bid eligibility for concentrated government volume.
For New Entrants and Emerging Players: The mid-tier price gap between premium ergonomic configurations and economy-grade polypropylene seating offers white-space entry for hybrid durability-value positioning. India's vocational training center segment remains penetrable given technical institute procurement formalization under Ministry of Education and Training oversight. Direct sales channel development with state-level tender expertise provides the most viable go-to-market angle against entrenched distributor relationships.
For Investors and Strategic Acquirers: Roll-up economics work for regional polymer seating fabricators because fragmented state-level procurement authorities favor local manufacturing presence for logistics efficiency and indigenous content compliance. The 5-10 year viability window hinges on continued public education infrastructure investment across Indonesia, Vietnam, and Philippines. Acquisition target archetype: mid-scale manufacturers with existing BIS or JIS certification and underutilized molding capacity. Watch for harmonization signals between Japan's METI and China's MIIT on school equipment stability standards as inflection indicator for cross-border scale economies.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Resin Supply | Captive polypropylene sourcing insulates margin compression from petrochemical feedstock volatility affecting competitors. |
| Multi-Year Framework Agreement Capture | Australia's state education departments and India's centralized authorities now allocate volume primarily through direct vendor relationships. |
| Active-Learning Furniture Configuration Launch | Collaborative STEM classroom designs penetrate premium private institutions in Singapore and Australia with mobility and modularity features. |
| BIS and JIS Certification Acceleration | India's safety gates and Japan's stability mandates filter supplier eligibility for municipal and state government contracts. |
| Vocational Training Center Partnership | Technical institutes across Indonesia and Vietnam harden procurement volumes for durable workshop and laboratory seating configurations. |
Study Parameters
Direct dialogue with school furniture procurement officers at India's state education departments, Australia's state-level tender authorities, and Japan's municipal school boards grounded qualitative insight development. Plant managers at Zhejiang and Guangdong manufacturing clusters, polymer resin procurement leads, and distributor channel partners provided operational perspective. Secondary validation drew from customs and trade data on laminated wood composite imports, BIS certification registries, METI school equipment stability reports, and SEC filings from publicly traded furniture manufacturers. Bottom-up and top-down triangulation reconciled production capacity assessments with institutional procurement volume aggregation.
Bottom-up modeling segmented demand across product type, material composition, end-user institution tier, and distribution channel, then aggregated through the projection horizon. Top-down validation cross-checked against public education budget allocations in India, Australia, Japan, and Vietnam. CAGRs were derived from replacement cycle analysis for aging equipment under JIS mandates, GB standards retooling timelines, and tier-2 city campus construction schedules. Industry-specific forecast inputs incorporated BIS certification penetration rates and direct sales channel share capture trajectories.
Caveats apply where regulatory harmonization between Japan, China, and Australia could materially shift the outlook through simplified cross-border supply strategies or where steel and polymer input volatility exceeds historical ranges. Forecasts reflect assumptions about continued state-funded K-12 infrastructure investment and vocational training center buildout momentum. Material deviation in public education budget allocation or certification timeline acceleration warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
Oman Private K12 Education Market