
 Oman Private K12 Education Market | 2026-2036
Oman Private K12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
Oman Private K12 Education Market Insights
Annual subscription-based learning management platforms is shifting how Omani private schools package technology access alongside tuition. British School Muscat leverages integrated digital portfolios to differentiate its British Curriculum offering. Indian School Muscat anchors its competitive position through specialized Hindi-language streams and cultural programming. A'Soud Global School competes on price-performance by operating multiple campuses under centralized administrative control.
Oman Private K12 Education encompasses fee-based primary and secondary schooling delivered by non-government institutions to students aged three through eighteen, incorporating standardized assessment frameworks, certified teaching staff, and purpose-built facilities designed to meet Ministry of Education infrastructure codes. The British Curriculum segment dominates enrollment volume among expatriate professionals in petroleum and logistics sectors, while the International Baccalaureate stream captures premium tuition fee categories from diplomatic and corporate executive households. Faith-Based Schools sustain steady demand from Omani national families seeking integrated religious instruction alongside secular accreditation pathways.
Oman's Ministry of Education and the Education Council jointly enforce curriculum equivalence standards, teacher qualification requirements, and facility safety protocols that determine operational licensing for all private institutions. The country's national pharmaceutical regulator equivalent oversight body for education quality assurance conducts periodic accreditation reviews that directly affect enrollment eligibility and fee-setting authority. Stakeholders must monitor evolving localization mandates requiring increased Omani national student quotas and staffing ratios as these policies reshape market access conditions and capital deployment timelines.
Market Dynamics
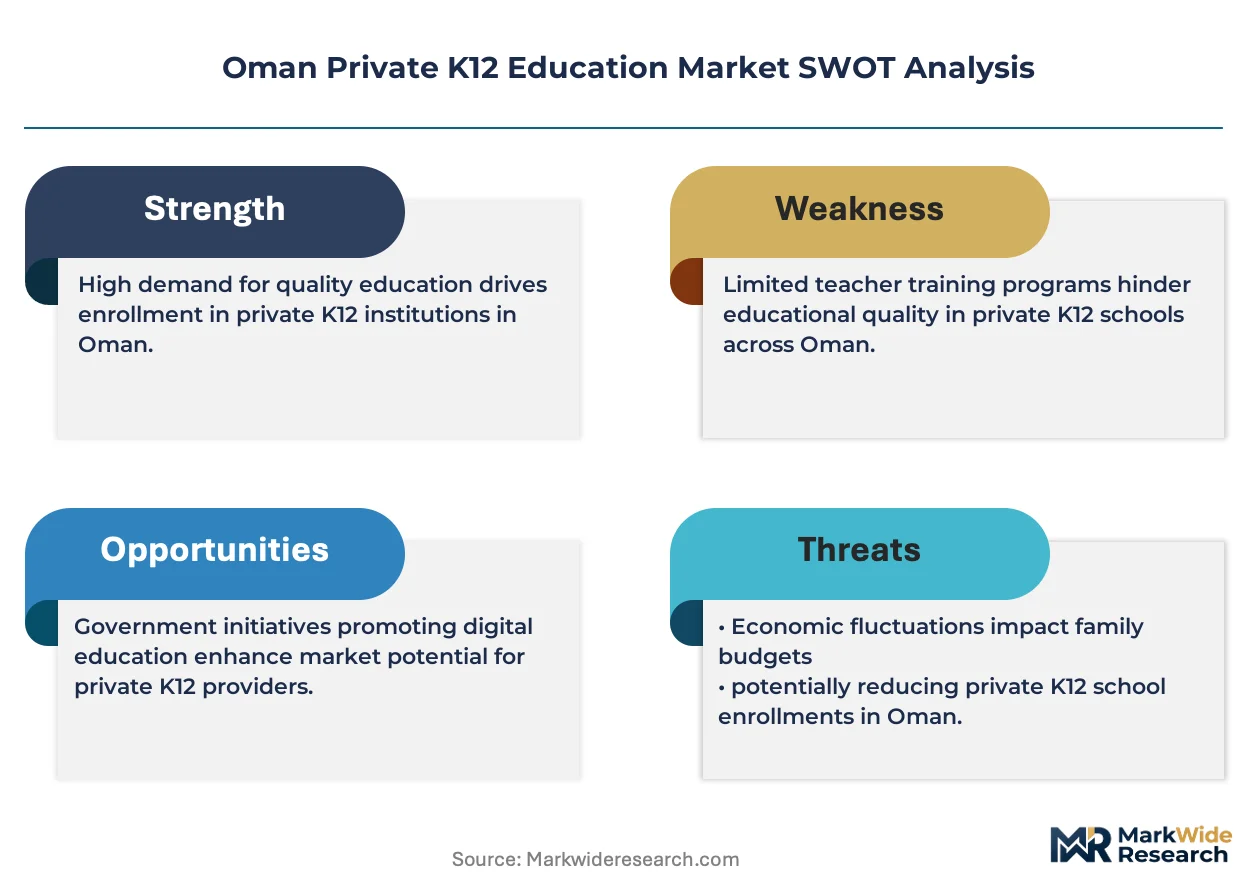
Localization mandates from Oman's Education Council are compressing enrollment timelines for expatriate-heavy institutions while forcing capital redeployment toward Omani national recruitment infrastructure. Schools must now balance immediate capacity expansion against longer-term quota compliance.
Growth Catalysts
- Education Council bilingual mandates:Arabic-English instruction requirements create sustained demand for certified bilingual teaching staff and curriculum adaptation services.
- South Asian expatriate concentration:Petroleum and logistics sector families in Muscat drive enrollment volume for British Curriculum and Indian curriculum streams.
- Coastal corridor construction permits:Accelerated licensing in Muscat and surrounding governorates enables greenfield campus development with modern Ministry of Education-compliant facilities.
Market Restraints
- Teacher supply concentration:Certified bilingual educators cluster in Muscat, creating wage pressure and recruitment bottlenecks for interior governorate campuses.
- Facility code compliance costs:Ministry of Education infrastructure mandates require purpose-built campuses, blocking low-cost conversion of existing commercial properties.
- Localization quota uncertainty:Evolving Omani national student ratio requirements prevent long-term enrollment planning and tuition pricing stability.
Strategic Opportunities
- Interior governorate underpenetration:Sohar, Nizwa, and Salalah lack sufficient premium private capacity relative to expatriate workforce growth in logistics and mining.
- Subscription-based learning platforms:Annual LMS licensing models allow schools to bundle technology access into tuition, differentiating against traditional fee structures.
- Faith-Based accreditation pathways:Integrated religious instruction with secular certification attracts Omani national families seeking values-aligned alternatives to purely secular curricula.
Industry Challenges
- Bilingual teacher certification pipelines:Ministry of Education qualification requirements exceed domestic training capacity, forcing reliance on expatriate recruitment with visa processing delays.
- Multi-campus administrative integration:Centralized control systems struggle to maintain curriculum consistency across geographically dispersed locations with varying local regulatory interpretations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oman Private K12 Education Market |
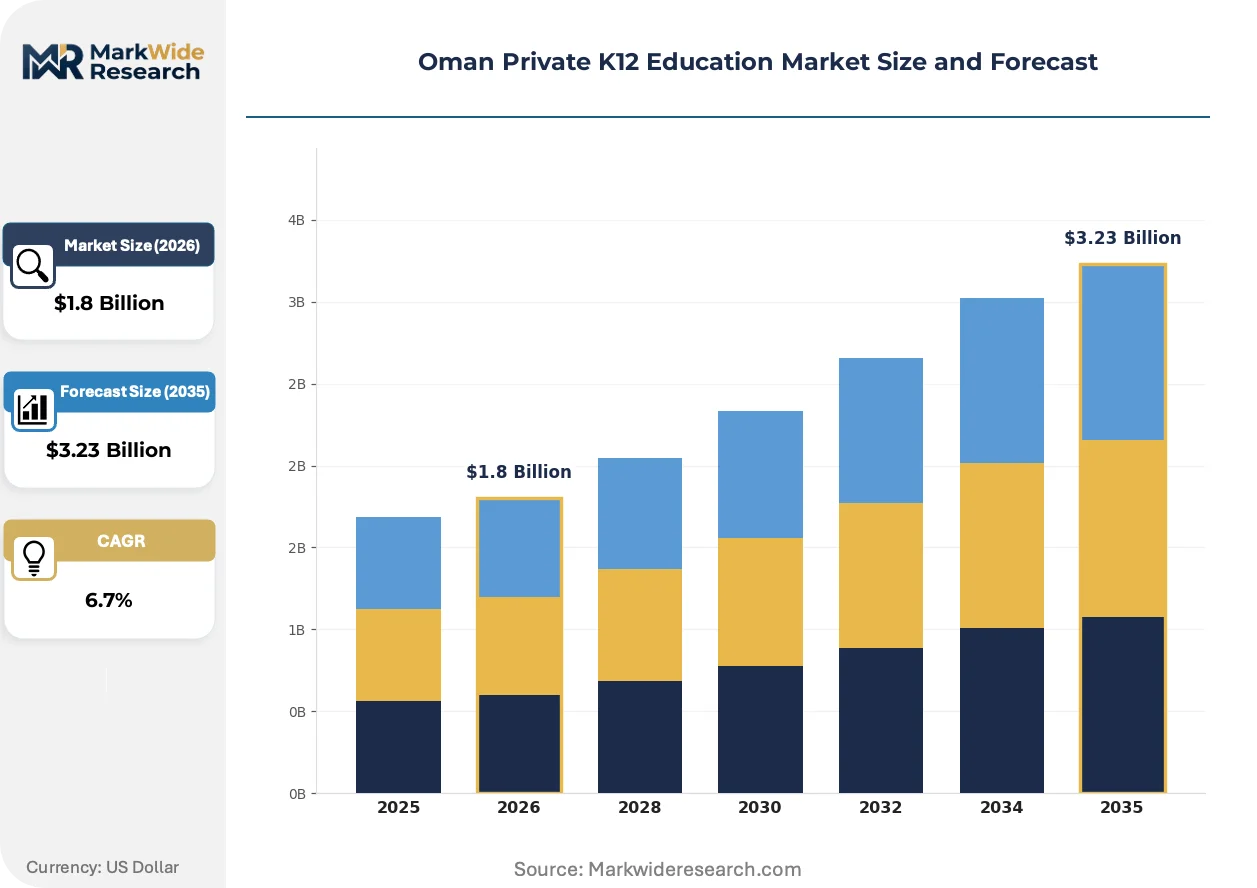
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Curriculum Type: International Baccalaureate, British Curriculum, American Curriculum, Indian Curriculum School Type: International Schools, Private Schools, Montessori Schools, Faith-Based Schools Grade Level: Preschool, Primary, Secondary, Higher Secondary Tuition Fee Category: Low Fee, Medium Fee, High Fee, Premium Fee |
| Companies Covered | British School Muscat, Indian School Muscat, American International School Muscat, The Sultan's School, Alruwad International School, Pakistan School Muscat, A'Soud Global School, American British Academy, Knowledge Gate International School, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oman Private K12 Education Market Trends and Innovations
Digital portfolio systems and centralized administrative platforms are restructuring how Omani private schools deliver curriculum consistency and parent transparency. Technology investment now determines competitive positioning as much as physical campus quality.
Integrated learning management platforms are converging with student information systems to create unified administrative environments. British Curriculum schools in Muscat adopt these stacks fastest, driven by parent expectations from corporate expatriate backgrounds. This convergence compresses IT vendor selection cycles and raises switching costs for institutions locked into multi-year platform contracts.
Oman's Education Council periodically revises curriculum equivalence standards through accreditation review protocols. These updates directly affect enrollment eligibility and fee-setting authority for private institutions. Faith-Based Schools and International Baccalaureate streams face the steepest compliance adaptation costs when standards shift.
Parent purchasing patterns now prioritize bundled technology access over à la carte fee transparency. Annual subscription models for digital portfolios and learning platforms displace traditional per-service charging in Muscat's premium segment. British School Muscat and Indian School Muscat both structure tuition to absorb these costs, masking technology expenditure within headline fees.
Oman Private K12 Education Market Segmentation
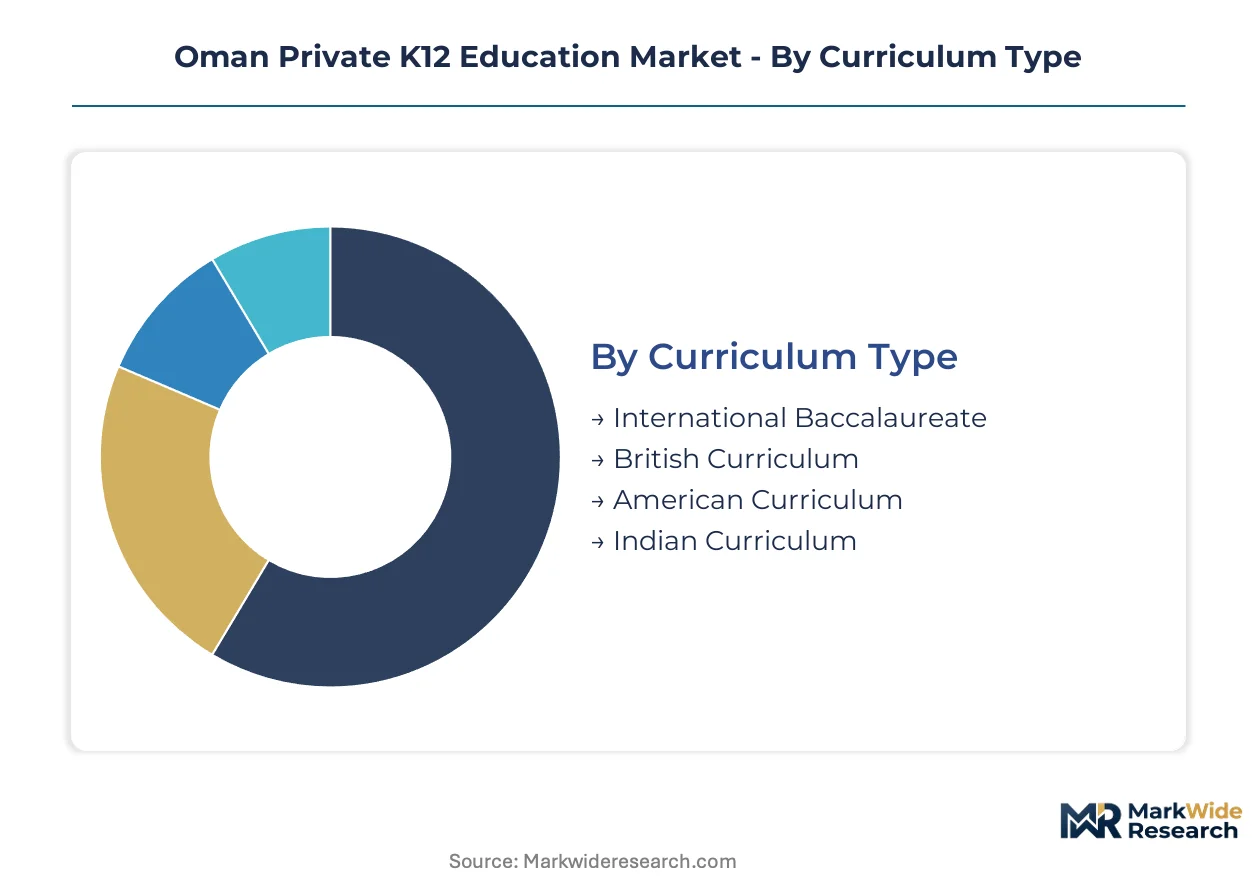
Segmentation in Oman's private K12 market reveals how curriculum choice, institutional model, and fee positioning determine competitive boundaries. Each category carries distinct regulatory obligations and capital requirements that shape operator strategy.
Curriculum Type:
British Curriculum providers concentrate teaching talent in Muscat's coastal corridor, creating supply bottlenecks for interior expansion.
- British Curriculum:Structured around IGCSE and A-Level examinations with standardized assessment frameworks. Petroleum and logistics sector families in Muscat drive sustained enrollment pressure for this stream, though bilingual teacher certification delays constrain new campus development.
- International Baccalaureate:Delivers inquiry-based PYP, MYP, and Diploma programming with global university recognition. Diplomatic and corporate executive households in Muscat's premium residential zones generate demand that outstrips current seat availability, pushing waitlist periods upward.
- American Curriculum:Follows Common Core-aligned progression with SAT/ACT preparation tracks. Energy sector expatriates from North American markets sustain niche demand clusters.
- Indian Curriculum:Implements CBSE or ICSE syllabi with Hindi-language stream options. South Asian professional families in petroleum and healthcare sectors anchor enrollment volume.
British Curriculum absorbs the bulk of installed capacity; International Baccalaureate is expanding most quickly.
School Type:
Cost tier differentiation separates capital-intensive international campuses from leaner faith-based operations serving Omani national families.
- International Schools:Deliver multiple curriculum streams under single administrative structures with purpose-built Ministry of Education-compliant facilities. These institutions face the steepest localization quota compliance costs as Education Council mandates tighten.
- Faith-Based Schools:Integrate religious instruction with secular accreditation pathways, attracting Omani national families seeking values-aligned alternatives. Lower land acquisition costs in interior governorates enable expansion beyond Muscat's saturated coastal zone.
- Private Schools:Operate as standalone commercial entities with single-curriculum focus and localized governance structures.
- Montessori Schools:Apply child-centered early childhood methodologies with specialized educator certification requirements.
International Schools command the dominant revenue share; Faith-Based Schools demonstrate the steepest expansion trajectory in interior governorates.
Grade Level:
Volume concentration in secondary tiers reflects expatriate family lifecycle patterns and university preparation demand.
- Secondary:Encompasses grades 9-12 with examination preparation and university counseling services. IGCSE and IB Diploma programming in Muscat attracts corporate expatriate families seeking seamless tertiary transition pathways.
- Primary:Covers grades 1-8 with foundational literacy and numeracy instruction. British Curriculum and Indian Curriculum streams in Muscat's coastal corridor face acute seat shortages.
- Preschool:Serves ages 3-5 with early childhood development programming.
- Higher Secondary:Provides grades 11-12 specialization with advanced subject concentration.
Secondary enrollment dominates current capacity utilization; Primary is gaining share fastest as young expatriate families expand.
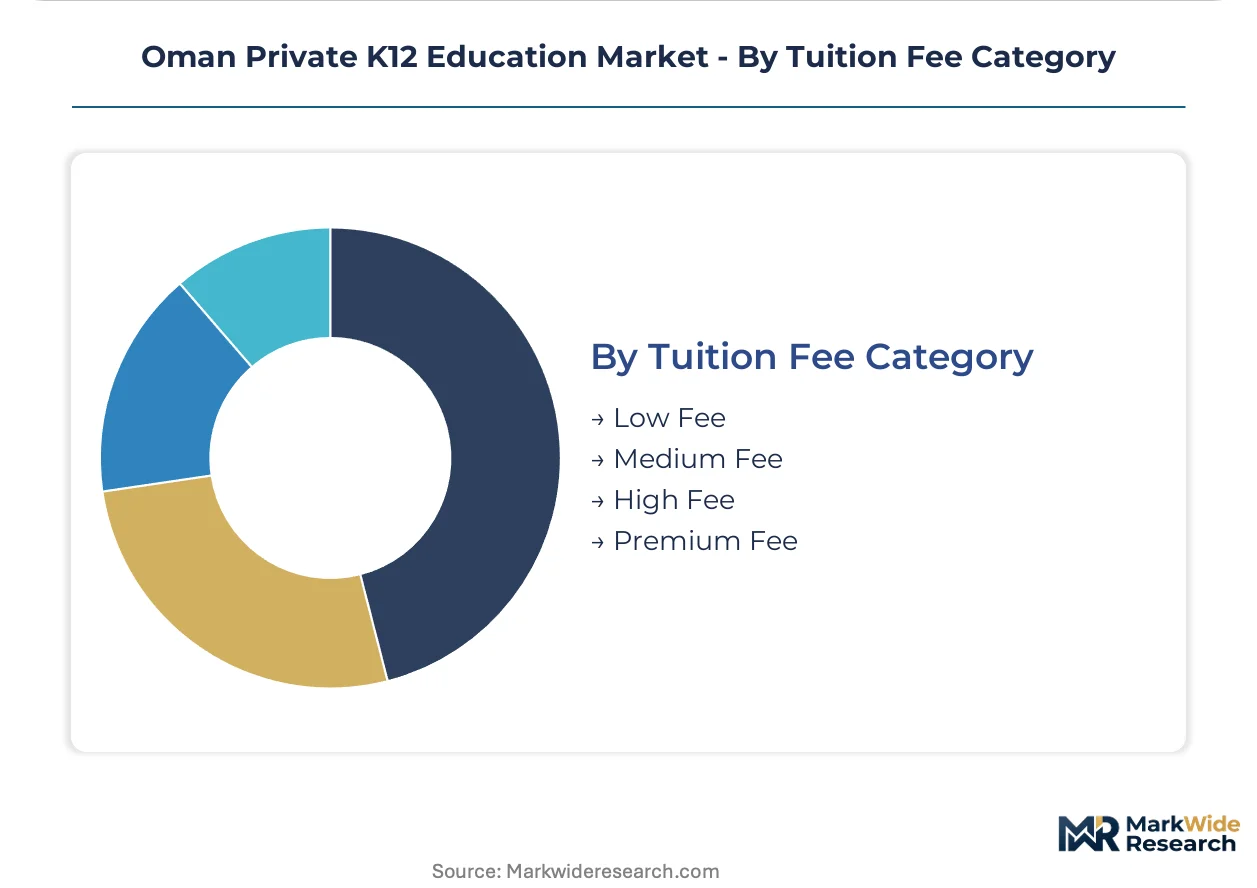
Tuition Fee Category:
Margin structure varies sharply across tiers, with premium operators bundling technology access while low-fee institutions struggle with facility code compliance costs.
- Premium Fee:Exceeds standard market rates by substantial multiples, incorporating learning management platforms, digital portfolios, and extracurricular programming. Corporate executive and diplomatic households in Muscat absorb these bundled costs without price sensitivity.
- High Fee:Positions above median market rates with selective technology inclusion and enhanced facility specifications. Professional expatriate families in petroleum and logistics sectors form the core customer base.
- Medium Fee:Targets mid-tier professional households with basic curriculum delivery and limited ancillary services.
- Low Fee:Serves price-constrained segments with minimal technology integration and higher student-teacher ratios.
Premium Fee captures the largest margin pool; High Fee is climbing the fastest as bundled technology becomes standard expectation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Muscat anchors enrollment demand within Oman's private K12 sector, concentrating petroleum and logistics sector expatriate families along the coastal corridor. Interior governorates present expansion frontiers where mining and logistics workforce growth outpaces school capacity.
Muscat Governorate
British Curriculum and International Baccalaureate streams attract petroleum sector executives and diplomatic households to Muscat's premium residential zones. Oman's Education Council enforces bilingual Arabic-English instruction standards that shape teacher recruitment across all private institutions. The Al Qurum and Al Khuwair districts host the densest concentration of Ministry of Education-compliant campuses with purpose-built facilities.
Al Batinah North and South
Sohar's port expansion and aluminum smelting operations generate expatriate workforce demand for Indian Curriculum and British Curriculum seats. The Education Council's localization mandates require schools to balance immediate capacity expansion against longer-term Omani national student quotas. New school construction permits in Sohar and Rustaq have accelerated, though certified bilingual teacher supply lags behind seat growth.
Ad Dakhiliyah
Nizwa's logistics hub development and tourism infrastructure projects attract mid-tier professional families seeking medium-fee private schooling options. Ministry of Education facility codes block low-cost conversion of existing commercial properties, forcing greenfield construction. The Nizwa corridor remains underserved relative to expatriate workforce growth in mining support services.
Dhofar
Salalah's port modernization and free zone expansion create demand clusters for American Curriculum and British Curriculum streams among North American and European energy sector assignees. The Education Council's periodic accreditation reviews directly affect enrollment eligibility and fee-setting authority for new market entrants. Campus development in Salalah faces higher per-student construction costs due to distance from Muscat-based contractor networks.
Al Sharqiyah North and South
Sur's industrial port and petrochemical investments sustain niche demand for Indian Curriculum programming among South Asian technical workforce families. Faith-Based Schools capture Omani national enrollment through integrated religious instruction with secular certification pathways. The Sur-Ibra corridor lacks sufficient premium private capacity relative to workforce housing expansion timelines.
Oman Private K12 Education Market Competitive Landscape
Capital-intensive campus developers compete with leaner single-site operators for enrollment share across Oman's governorate markets. The competitive structure fragments between multi-campus networks with centralized administrative control and standalone institutions with localized governance. Three archetypes dominate: premium international schools bundling technology access into headline tuition, faith-based operators leveraging lower land costs in interior markets, and price-performance chains optimizing seat density across multiple locations. Dominant competitive moves include geographic expansion into underpenetrated governorates and strategic partnerships with learning management platform vendors to differentiate bundled offerings.
Among Muscat-based international school operators, British School Muscat and Indian School Muscat exemplify the premium-tier archetype through established curriculum specialization and coastal corridor positioning. A'Soud Global School represents the multi-campus price-performance model with centralized administrative control spanning several locations. These named institutions anchor competitive dynamics without exhausting the operational diversity present across the sector.
| Leading Market Players |
|---|
| British School Muscat |
| Indian School Muscat |
| American International School Muscat |
| The Sultan's School |
| Alruwad International School |
| Pakistan School Muscat |
| A'Soud Global School |
| American British Academy |
| Knowledge Gate International School |
| Others |
Pricing and Supply Chain Analysis
Learning management platform convergence with student information systems is restructuring cost economics across Oman's private K12 sector while concentrating technology procurement leverage among Muscat-based multi-campus operators. This shift simultaneously elevates fixed cost bases for standalone institutions and compresses margin flexibility for late technology adopters.
Pricing Analysis
Outcome-based pricing anchored to university admission rates and examination performance metrics dominates tuition architecture across Muscat's premium segment. Three-tier pricing structure across premium, standard, and economy levels separates British School Muscat's bundled technology offerings from A'Soud Global School's centralized administrative model and low-fee operators struggling with Ministry of Education facility code compliance. Cost compression in the medium-fee tier is intensifying because localization mandates force unplanned recruitment infrastructure spending. Corporate executive and diplomatic households in Al Qurum demonstrate minimal price sensitivity, while mid-tier professional families in Sohar and Nizwa face acute affordability constraints.
Supply Chain Analysis
Certified bilingual teacher availability bottlenecks in the United Kingdom, India, and South Africa constrain expansion timelines for British Curriculum and Indian Curriculum operators seeking to comply with Education Council mandates. Campus development draws from specialized construction labor pools in the Philippines and India, with finishing materials and educational technology hardware sourcing from China and the United Arab Emirates. Single-source vulnerability around Ministry of Education accreditation review scheduling creates enrollment eligibility uncertainty that disrupts fee-setting authority cycles. Distribution runs through Muscat-based contractor networks that extend unevenly to Salalah and Sur, inflating per-student construction costs in Dhofar and Al Sharqiyah.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Integrated learning management platforms are displacing legacy administrative systems across Oman's private K12 sector, creating a technology-transition window where competitive positioning depends on digital infrastructure deployment speed.
For Market Incumbents: Cement coastal corridor dominance by accelerating centralized administrative platform integration across multi-campus networks before Education Council localization mandates tighten further. Acquire certified bilingual teaching talent pipelines through direct partnerships with United Kingdom and Indian teacher training institutions, offsetting visa processing delays that threaten seat expansion timelines. For New Entrants and Emerging Players: The price-point gap between premium bundled-technology tuition and economy-tier basic delivery creates immediate white-space opportunity in Nizwa and Sohar's medium-fee segment. Target logistics and mining sector professional families seeking British Curriculum access without Muscat premium pricing, leveraging lower land acquisition costs in Ad Dakhiliyah and Al Batinah to undercut coastal operators on facility amortization. For Investors and Strategic Acquirers: Exit pathways concentrate in multi-campus networks with proven centralized administrative control and established Ministry of Education accreditation histories. Long-term viability hinges on compliance adaptability rather than scale alone, with faith-based operators in interior governorates offering defensive positioning against localization quota uncertainty. Watch Education Council periodic accreditation review timing as the critical inflection signal for fee-setting authority disruptions.| Strategic Initiative | Industry Significance |
|---|---|
| Learning Management Platform Integration | British School Muscat bundles digital portfolios into tuition to differentiate against traditional fee structures. |
| Multi-Campus Administrative Centralization | A'Soud Global School optimizes seat density across locations through unified governance and procurement. |
| Interior Governorate Greenfield Development | Faith-Based Schools exploit lower land costs in Nizwa and Sohar to expand beyond saturated Muscat markets. |
| Bilingual Teacher Pipeline Partnerships | Indian School Muscat secures Hindi-language stream staffing through direct Indian training institution alliances. |
| Accreditation Review Timing Optimization | Premium operators align capital deployment with Education Council review cycles to protect fee-setting authority. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, supplemented by primary interviews with school administrators, curriculum directors, Education Council compliance officers, and construction contractors active in Oman's education infrastructure sector. Oman Ministry of Education licensing databases, Education Council accreditation review protocols, and Muscat Municipality construction permit records provided quantitative foundation. Bottom-up enrollment modeling triangulated against top-down governorate-level expatriate workforce estimates from national labor statistics.
Granularity-level modeling operated at individual campus capacity, curriculum stream, and tuition fee tier dimensions across the projection horizon. CAGRs derived from enrollment trend extrapolation weighted by construction permit issuance velocity and teacher supply pipeline constraints. Forecast inputs incorporated localization mandate implementation phasing, coastal corridor land availability curves, and learning management platform adoption saturation thresholds.
Inputs from Education Council accreditation review schedules and Ministry of Education facility code compliance databases were available through the study window; gaps in interior governorate real-time enrollment data introduce uncertainty bands around Sohar and Salalah market sizing. Forecasts reflect assumptions regarding visa processing timelines for expatriate teaching staff and coastal corridor construction labor availability. Material deviation in localization quota enforcement intensity or bilingual teacher certification requirement changes warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Europe K12 Education Market