
 GCC Private K12 Education Market | 2026-2036
GCC Private K12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Private K12 Education Market Foresight
UAE KHDA licensing reforms is expanding the compliance burden for new market entrants seeking operational permits in Dubai and Abu Dhabi. GEMS Education leverages its multi-campus network to sustain enrollment density across price tiers. Taaleem anchors its position through British curriculum specialization in premium Dubai locations. Aldar Education competes via integrated real-estate and school development models in Abu Dhabi and Al Ain.
GCC Private K12 Education denotes fee-based primary and secondary schooling delivered by non-government institutions, encompassing structured academic programs from early childhood through grade twelve with standardized assessment frameworks and certified instructional staff. International curriculum schools dominate fee revenue pools, while STEM-focused programs represent the fastest-growing curriculum category as Gulf governments prioritize technical workforce pipelines. The fee structure dimension stratifies sharply, with elite-fee institutions capturing disproportionate margin concentration in Dubai and Riyadh metropolitan zones.
UAE KHDA, Saudi ETEC, and Qatar SEC collectively enforce curriculum standards, teacher certification, and facility accreditation that determine market access and operational continuity. These bodies increasingly mandate bilingual instruction ratios and digital infrastructure benchmarks that elevate fixed-cost thresholds for license maintenance. Stakeholders must monitor regulatory divergence between emirates and kingdoms as compliance fragmentation reshapes expansion economics and capital allocation priorities.
Market Dynamics
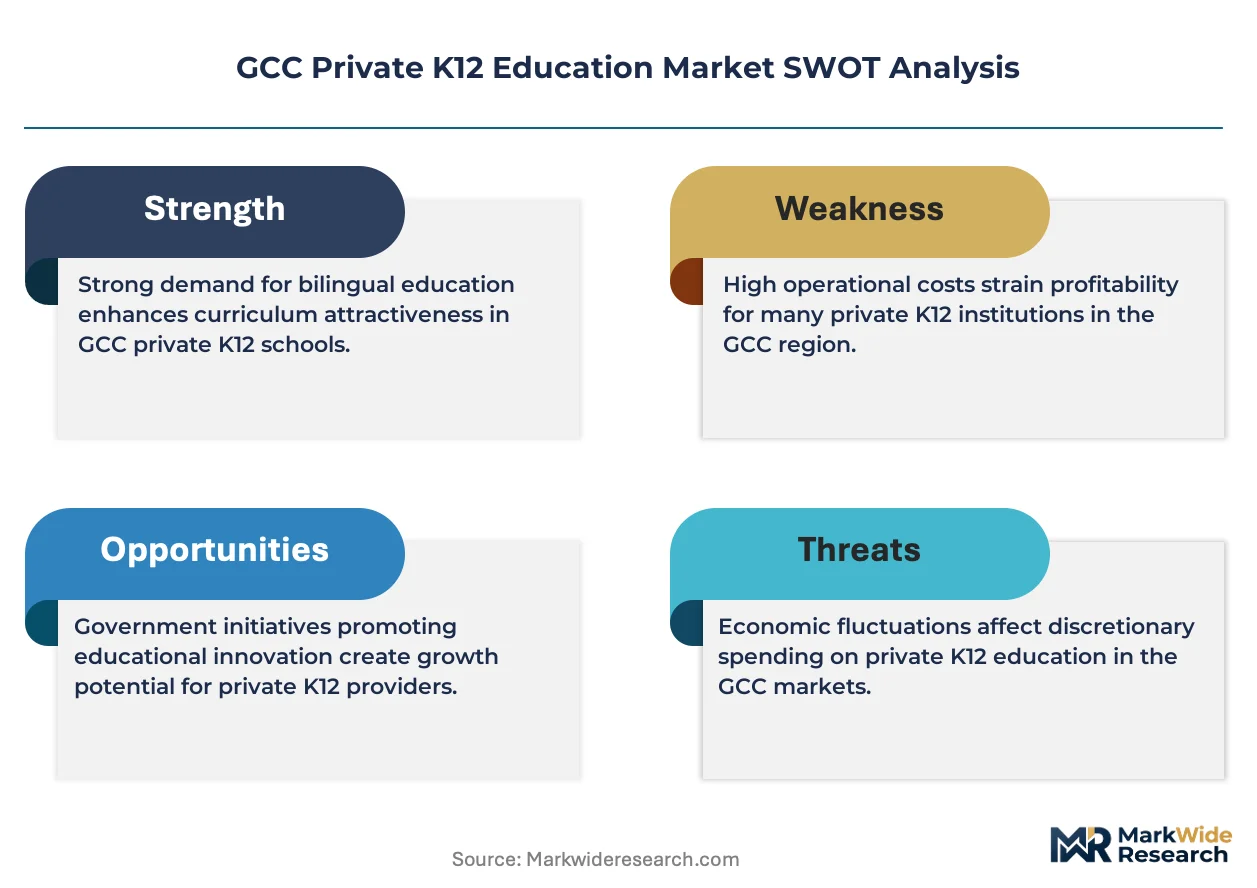
Government localization mandates across Saudi Arabia, the UAE, and Qatar are forcing curriculum adaptation and bilingual instruction ratios that reshape operational cost structures and license maintenance requirements for private school operators.
Growth Catalysts
- Expatriate family concentration:Professional migration into Dubai, Riyadh, and Doha sustains enrollment pipelines for British and American curriculum institutions. KHDA, ETEC, and SEC licensing frameworks validate quality signals for relocating households.
- ETEC curriculum localization mandates:Saudi Arabia's requirement for Arabic-language humanities integration creates captive demand for compliant instructional materials and certified bilingual faculty.
- STEM workforce pipelines:Gulf national visions prioritize technical education pathways, accelerating specialized lab infrastructure investment and industry partnership programs in secondary schools.
Market Restraints
- Fixed-cost escalation from digital infrastructure benchmarks:KHDA and SEC now mandate learning management systems, device-per-student ratios, and cybersecurity protocols that elevate capital intensity for license renewal.
- Teacher certification bottlenecks:Supply of British QTS and US state-certified instructors concentrates in UK and North American labor markets, creating recruitment friction and compensation inflation.
- Real estate lock-in effects:Premium campus locations in Dubai Marina, Riyadh Diplomatic Quarter, and Doha West Bay carry long-term lease commitments that constrain geographic repositioning.
Strategic Opportunities
- Abu Dhabi and Al Ain expansion corridors:Aldar Education's integrated development model demonstrates viable pathways for new campus deployment in underserved emirate sub-markets.
- AI-powered adaptive learning platforms:Convergence of natural language processing and learning analytics enables personalized instruction pathways that differentiate premium-tier offerings.
- Outcome-based fee structures:Performance-linked tuition models tied to university placement rates and standardized assessment outcomes are gaining traction among value-conscious expatriate segments.
Industry Challenges
- Bilingual faculty scarcity:Recruiting instructors with native English proficiency and certified Arabic instruction capability creates persistent staffing gaps in humanities and social science departments.
- Curriculum adaptation timelines:ETEC and KHDA review cycles for program modifications extend 18-24 months, delaying market-responsive course launches in emerging fields like data science and climate studies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Private K12 Education Market |
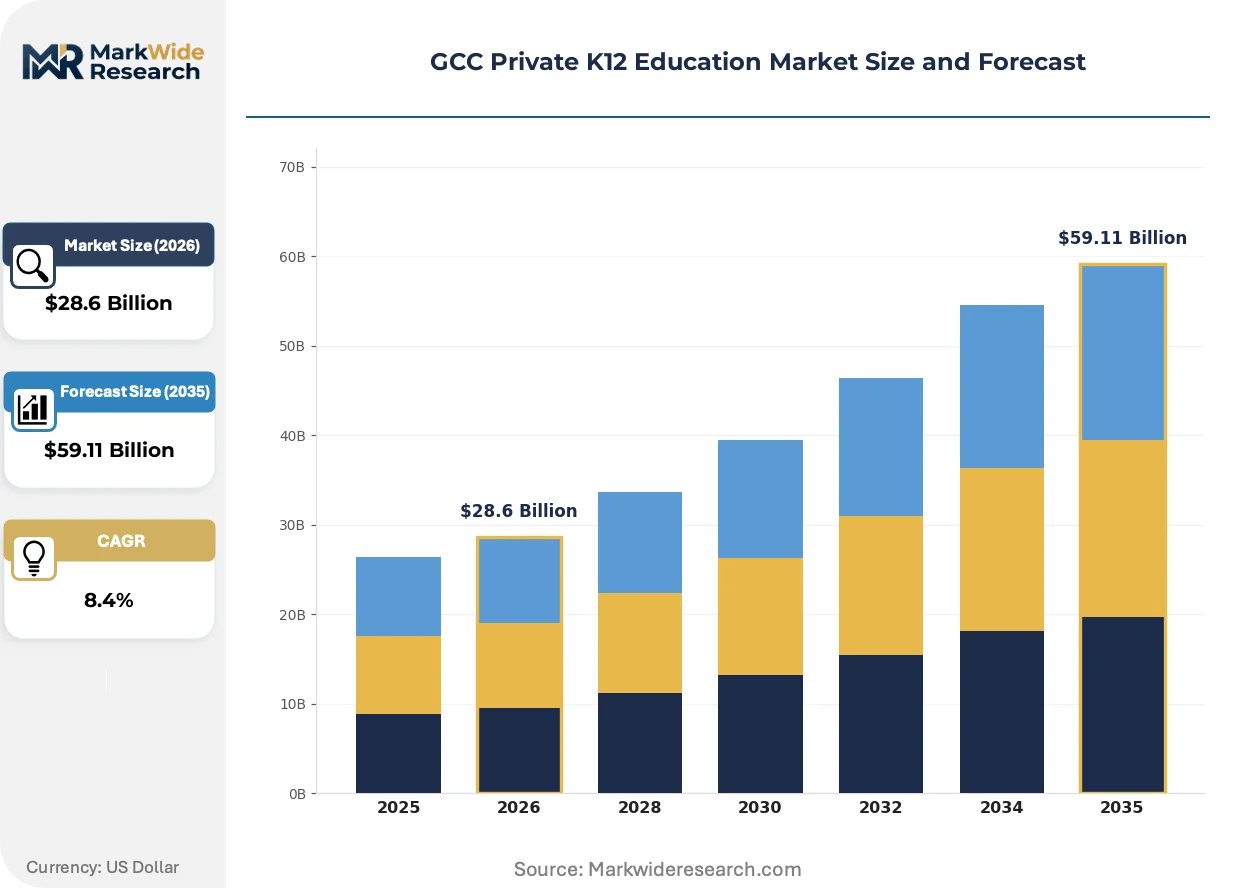
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $59.11 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | School Type: International Schools, British Curriculum Schools, American Curriculum Schools, French Curriculum Schools Curriculum Type: IB Curriculum, National Curriculum, STEM Curriculum, Montessori Curriculum Student Age Group: Preschool, Primary, Secondary, High School Fee Structure: Low Fees, Moderate Fees, High Fees, Elite Fees |
| Companies Covered | SABIS, International Schools Group, GEMS Education, Nadeen International School, Al-Jazeera Academy, Taaleem, Nord Anglia Education, Beaconhouse, Aldar Education, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Private K12 Education Market Shifts & Advancements
Digital infrastructure mandates and AI-enabled personalization tools are redefining capital allocation priorities for school operators, while regulatory divergence between emirates creates compliance complexity that favors multi-campus networks with dedicated government relations capacity.
Immersive virtual reality laboratories are absorbing capital expenditure previously directed toward physical science facilities. Premium-tier institutions in Dubai and Riyadh are deploying VR chemistry and biology modules at scale. This technology compression enables smaller campuses to offer competitive STEM programming without proportional facility investment.
KHDA's 2024 teacher licensing reforms now require continuous professional development credits and digital pedagogy certification for permit renewal. The policy elevates training budget burdens for standalone operators. Multi-campus networks with centralized professional development infrastructure are absorbing compliance costs more efficiently than single-site competitors.
Parental purchasing patterns are fragmenting across curriculum types and fee tiers as relocation packages compress and employer education subsidies contract. British curriculum institutions in Dubai face enrollment pressure from mid-tier American curriculum alternatives. This demand rotation is most visible among South Asian professional families reassessing value propositions in Sharjah and Ajman sub-markets.
GCC Private K12 Education Market Segmentation
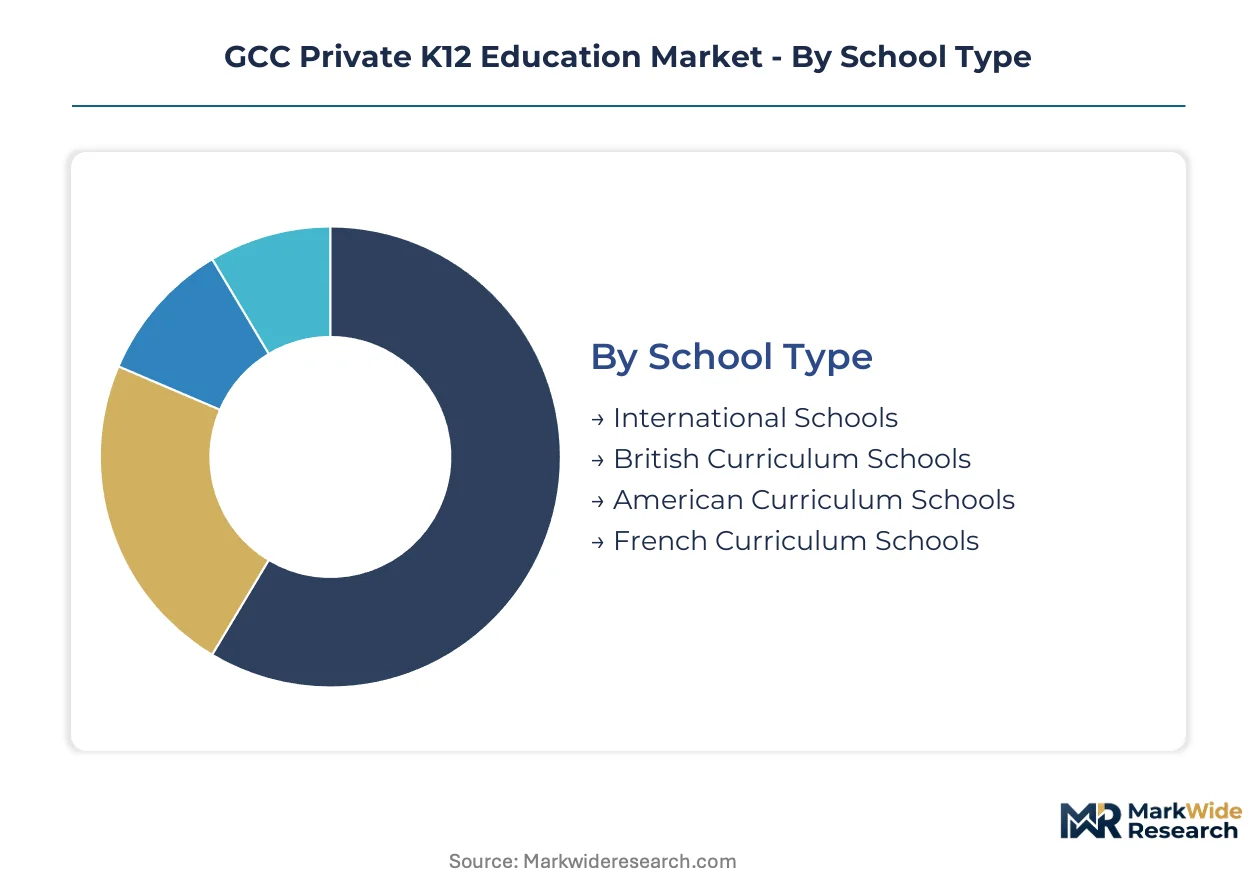
Segmentation in GCC private K12 education reveals how capital allocation, regulatory compliance, and parental purchasing power fragment across distinct operational models. Operators must match facility investment and faculty certification to specific segment requirements.
School Type:
Capital intensity varies sharply across school type, with purpose-built campuses and curriculum licensing fees creating divergent entry barriers.
- International Schools:Multi-curriculum institutions serving globally mobile families with diverse accreditation requirements. Dubai Marina and Riyadh Diplomatic Quarter host concentrated demand from corporate relocation packages.
- British Curriculum Schools:IGCSE and A-Level programs dominate premium fee tiers. These institutions absorb the highest faculty certification costs due to native English QTS requirements and KHDA inspection protocols.
- American Curriculum Schools:AP and Common Core pathways appeal to North American expatriate families. Saudi ETEC mandates for Arabic integration create hybrid operational models in Riyadh and Jeddah.
- French Curriculum Schools:Smaller addressable market serving Francophone diplomatic and corporate families. Abu Dhabi and Doha host viable enrollment density through bilateral government agreements.
International schools absorb the bulk of installed capacity; British curriculum schools are expanding most quickly.
Curriculum Type:
Curriculum selection determines lab infrastructure requirements and teacher specialization depth.
- IB Curriculum:Diploma and Middle Years programs command premium positioning through rigorous assessment frameworks. Dubai and Abu Dhabi show concentrated demand from families targeting university admissions in North America and Europe.
- National Curriculum:Country-specific programs aligned with Saudi, UAE, or Qatari ministry standards. These segments face ETEC and SEC localization mandates that elevate bilingual faculty requirements.
- STEM Curriculum:Specialized science, technology, engineering, and mathematics pathways with dedicated laboratory investment. Gulf national visions prioritize this category for technical workforce pipeline development.
- Montessori Curriculum:Early childhood-focused experiential learning models with lower capital intensity. Sharjah and Ajman sub-markets show rising adoption among value-conscious South Asian professional families.
National curriculum programs anchor current enrollment volume; STEM curriculum is gaining share fastest.
Student Age Group:
Age group targeting shapes facility design specifications and regulatory oversight intensity.
- Preschool:Early childhood programs with specialized safety and space requirements. Dubai's nursery licensing reforms under KHDA have tightened operational standards.
- Primary:Foundational literacy and numeracy instruction with highest enrollment density across all fee tiers. Riyadh and Jeddah show sustained demand from young expatriate families.
- Secondary:Standardized assessment preparation with specialized subject faculty. Abu Dhabi's Aldar Education network concentrates capacity in this segment.
- High School:University placement-focused programming with career counseling infrastructure. Doha's West Bay cluster serves diplomatic families with intensive college advisory services.
Primary enrollment absorbs the bulk of current capacity; high school programming is climbing the fastest.
Fee Structure:
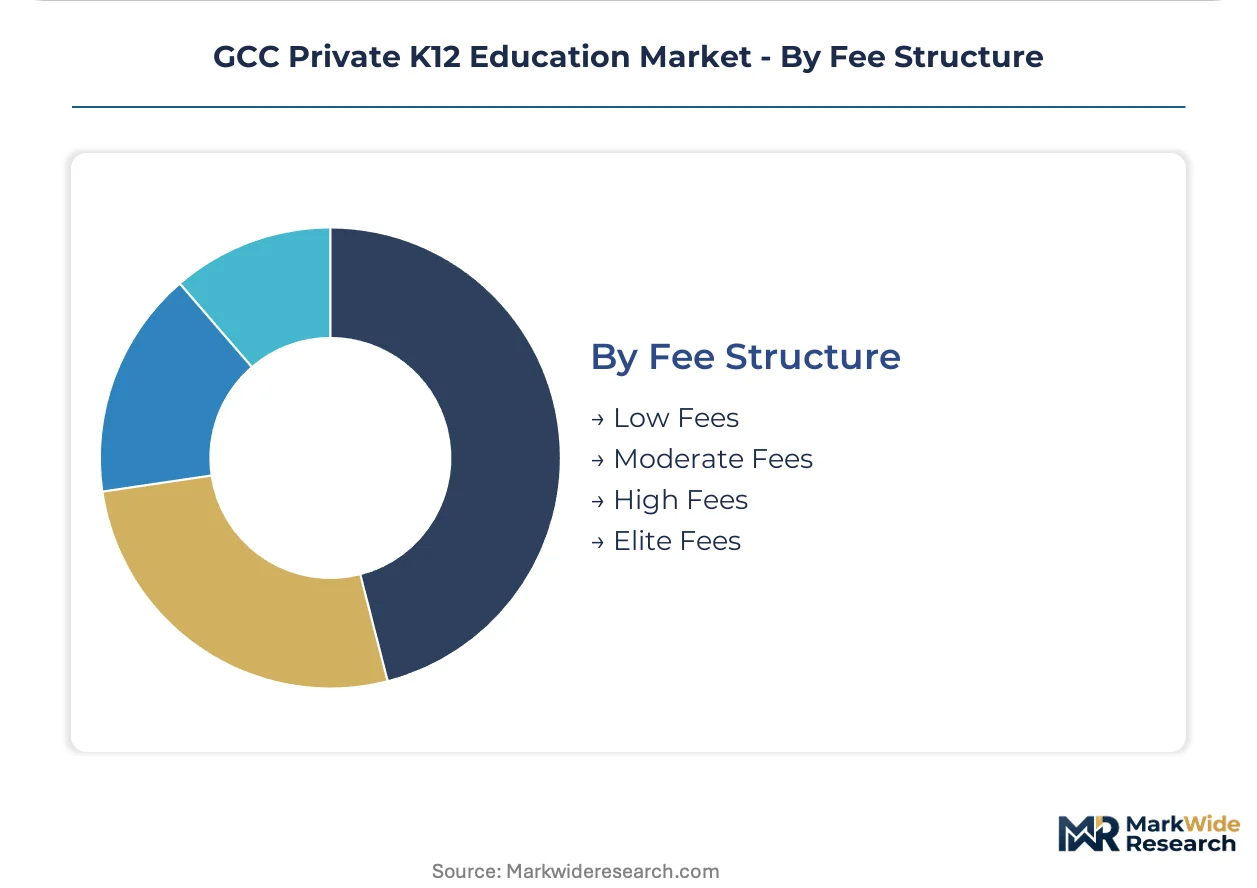
Fee tier positioning determines real estate location, faculty compensation benchmarks, and technology investment depth.
- Low Fees:Accessible pricing targeting mid-income expatriate families in Sharjah, Ajman, and Al Ain. These operators face margin compression from rising compliance costs.
- Moderate Fees:Mid-tier positioning with balanced curriculum breadth and facility quality. Saudi Arabia's expanding professional class sustains enrollment growth in Riyadh secondary cities.
- High Fees:Premium positioning with specialized programs and smaller class sizes. Dubai's established British curriculum institutions dominate this tier through brand recognition.
- Elite Fees:Ultra-premium segment with extensive extracurricular and university placement services. Abu Dhabi and Doha diplomatic quarters concentrate this limited addressable market.
High-fee institutions capture the bulk of revenue concentration; moderate-fee operators are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Free zone incentives in Dubai Knowledge Park and Dubai International Academic City concentrate school operator headquarters and administrative functions. These tax-advantaged clusters lower operational cost bases for multi-campus networks. Regulatory harmonization remains incomplete across the six GCC member states.
United Arab Emirates
Expatriate professional migration into Dubai Marina and Downtown Dubai sustains enrollment pipelines for British curriculum institutions. KHDA inspection protocols and teacher licensing reforms elevate compliance burdens for standalone operators. Abu Dhabi's Al Reem Island and Saadiyat Island host emerging campus clusters as Aldar Education expands integrated real-estate school developments.
Saudi Arabia
Vision 2030 localization mandates drive demand for bilingual faculty capable of Arabic humanities integration. ETEC curriculum standards and facility accreditation requirements reshape operational cost structures for international school operators. Riyadh's Diplomatic Quarter and Jeddah's Al Hamra district concentrate premium-fee British and American curriculum institutions serving corporate relocation packages.
Qatar
Diplomatic and energy sector expatriate families in Doha's West Bay and The Pearl-Qatar sustain addressable markets for elite-fee international schools. SEC bilingual instruction ratios and digital infrastructure benchmarks elevate fixed-cost thresholds for license maintenance. Education City partnerships between Qatari institutions and foreign universities create secondary school feeder relationships.
Kuwait
Long-tenured expatriate communities in Salmiya and Hawalli districts sustain demand for American curriculum programming. The Ministry of Education's private school oversight division enforces facility and staffing standards that determine operational permits. British curriculum alternatives face enrollment pressure from established American school networks with deeper historical presence.
Bahrain
Financial services expatriate concentration in Manama's Seef district supports mid-tier international school demand. The Education and Training Quality Authority mandates curriculum alignment and teacher qualification verification for license renewal. Saar and Riffa residential corridors host emerging campus locations as operators seek alternatives to saturated Manama core markets.
GCC Private K12 Education Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across curriculum type and fee tier positioning. Market structure exhibits moderate consolidation with multi-campus networks capturing disproportionate enrollment share in premium metropolitan zones. Strategic archetypes include integrated real-estate developers, curriculum-specialist operators, and global education brands with standardized delivery models. Dominant competitive moves encompass campus network expansion into underserved emirate sub-markets and technology-enabled differentiation through adaptive learning platforms.
Within the integrated development archetype, Aldar Education anchors Abu Dhabi and Al Ain expansion through captive real-estate pipelines. GEMS Education exemplifies multi-campus network scale with density across Dubai price tiers and curriculum types. Taaleem occupies a focused position through British curriculum specialization in premium Dubai locations. These operators represent contrasting pathways for navigating KHDA, ETEC, and SEC compliance fragmentation.
| Leading Market Players |
|---|
| SABIS |
| International Schools Group |
| GEMS Education |
| Nadeen International School |
| Al-Jazeera Academy |
| Taaleem |
| Nord Anglia Education |
| Beaconhouse |
| Aldar Education |
| Others |
Supply & Pricing Matrix
Elite-fee versus mid-tier fee divergence in Dubai and Riyadh creates distinct supply chain configurations, with premium institutions absorbing certified British QTS faculty scarcity through long-term recruitment contracts while value-tier operators source from Philippine and South Asian labor markets with higher turnover velocity.
Pricing Analysis
Short lead-time premiums for certified bilingual faculty command 40-60% compensation uplifts over standard recruitment cycles in Saudi Arabia and Qatar. The dominant pricing structure rests on annual tuition contracts with sibling discounts and multi-year enrollment commitments. Price differentiation stems from curriculum accreditation tier and KHDA inspection rating. Cost compression in mid-tier Sharjah and Ajman markets is intensifying because South Asian professional families reassess relocation package subsidies. Employer-sponsored segments show least price sensitivity; self-paying mid-income expatriates exhibit highest elasticity.
Supply Chain Analysis
Workforce availability constraints in the United Kingdom, United States, and Canada concentrate certified teacher supply for British and American curriculum institutions. Instructional material production draws from UK-based Pearson and Cambridge Assessment networks, with localized Arabic humanities content sourced from Saudi ETEC-approved domestic publishers. Single-source vulnerability runs through QTS certification bottlenecks where UK regulatory bodies control credential issuance timelines. Distribution runs through direct-hire recruitment agencies and international teacher placement fairs rather than domestic labor exchanges.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a vertical-integration race where captive real-estate pipelines and centralized professional development infrastructure represent the decisive downstream and upstream levers separating multi-campus networks from standalone operators.
For Market Incumbents: Hedge against KHDA and ETEC compliance fragmentation by consolidating government relations capacity across emirate and kingdom boundaries. Deepen backward integration into teacher training academies to reduce QTS recruitment friction and compensation inflation. Absorb standalone competitors in underserved Abu Dhabi and Al Ain corridors before Aldar Education captures remaining sub-market density.
For New Entrants and Emerging Players: Real estate developers with integrated school development capabilities offer the most penetrable partnership channel for market access without legacy compliance burdens. Target moderate-fee American curriculum positioning in Riyadh secondary cities where Saudi professional class expansion outpaces established British curriculum capacity. Deploy AI-powered adaptive learning platforms as immediate differentiation against incumbent technology lag.
For Investors and Strategic Acquirers: Re-rating potential sits with multi-campus networks possessing centralized professional development infrastructure given KHDA's 2024 continuous certification mandates. Long-term viability over a multi-year horizon favors operators with demonstrated ETEC and SEC compliance track records across multiple regulatory jurisdictions. Monitor ETEC curriculum localization timeline announcements as the critical inflection signal for bilingual faculty demand spikes.
| Strategic Initiative | Industry Significance |
|---|---|
| Campus Network Expansion | Captures enrollment density in underserved Al Ain and Riyadh secondary corridors before competitor saturation. |
| Backward Integration into Teacher Training | Reduces QTS certification bottlenecks and recruitment costs through in-house credentialing pipelines. |
| AI-Powered Adaptive Learning Deployment | Differentiates premium-tier offerings through personalized instruction pathways in Dubai and Riyadh markets. |
| Integrated Real-Estate Development | Locks in captive campus locations via Aldar-style development models in Abu Dhabi and emerging sub-markets. |
| Regulatory Compliance Consolidation | Absorbs KHDA, ETEC, and SEC fragmentation costs through dedicated government relations infrastructure. |
Research Methodology
Independent corroboration across school operator executives, KHDA and ETEC regulatory affairs officers, and international teacher placement agency directors underwrites the qualitative findings. Primary interviews with curriculum development leads, campus facility managers, and expatriate family association representatives combined with secondary validation from KHDA inspection reports, ETEC curriculum standards documentation, and SEC licensing frameworks. Bottom-up enrollment data triangulates against top-down education expenditure estimates from national statistical authorities.
Comparable historical enrollment and fee trajectories anchored the projection framework across the analysis window. Segmentation modeling incorporated school type, curriculum category, student age group, and fee tier dimensions with regional regulatory cluster overlays. CAGRs derived from enrollment pipeline analysis and capital expenditure cycle timing. Forecast inputs included expatriate professional migration patterns and government localization mandate implementation schedules.
Caveats apply where ETEC curriculum review cycle extensions or KHDA teacher licensing reform accelerations could materially shift the outlook. Forecasts reflect assumptions regarding sustained corporate relocation package structures and stable regulatory enforcement intensity across the GCC. Material deviation in bilateral government education agreements or sudden expatriate policy reversals warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Oman Private K-12 Market