
 In-Person Learning Market | 2026-2036
In-Person Learning Market Size, Share, and Industry Trends Forecast 2026-2036
In-Person Learning Market Analysis
India's coaching hub expansion in Kota and Hyderabad is reconfiguring capacity allocation for competitive exam preparation. Kaplan leverages its standardized test heritage to sustain premium positioning in North American metro corridors. INSEAD anchors executive education through its Fontainebleau and Singapore campuses, competing on cross-border faculty mobility. Vibrant Academy dominates JEE preparation in Rajasthan, occupying a concentrated geography that limits replication costs.
In-person learning denotes educational delivery conducted through physical co-presence of instructors and learners, typically requiring classroom infrastructure, scheduled synchronous sessions, and face-to-face assessment protocols. Its primary commercial purpose centers on credential attainment, skill verification, and network formation where physical proximity enables tacit knowledge transfer. The classroom delivery mode leads revenue contribution due to institutional bundling with housing and administrative services, while skill development courses represent the fastest-expanding course type as employers demand verified competency over degree proxies. Corporate trainees within the target audience dimension command superior margin pools through customized cohort pricing and employer-sponsored reimbursement structures.
The US Department of Education enforces Title IV eligibility standards that shape institutional access to federal student aid, directly filtering which providers achieve sustainable enrollment scale. India's National Council for Teacher Education mandates recognition for educator training programs, restricting unaccredited operators from degree-conferring status. China's Ministry of Education and its provincial subsidiaries supervise private tutoring licensing under post-2021 curriculum reform guidelines. Stakeholders must monitor accreditation portability as cross-border degree recognition agreements fragment under divergent national quality frameworks.
Market Dynamics
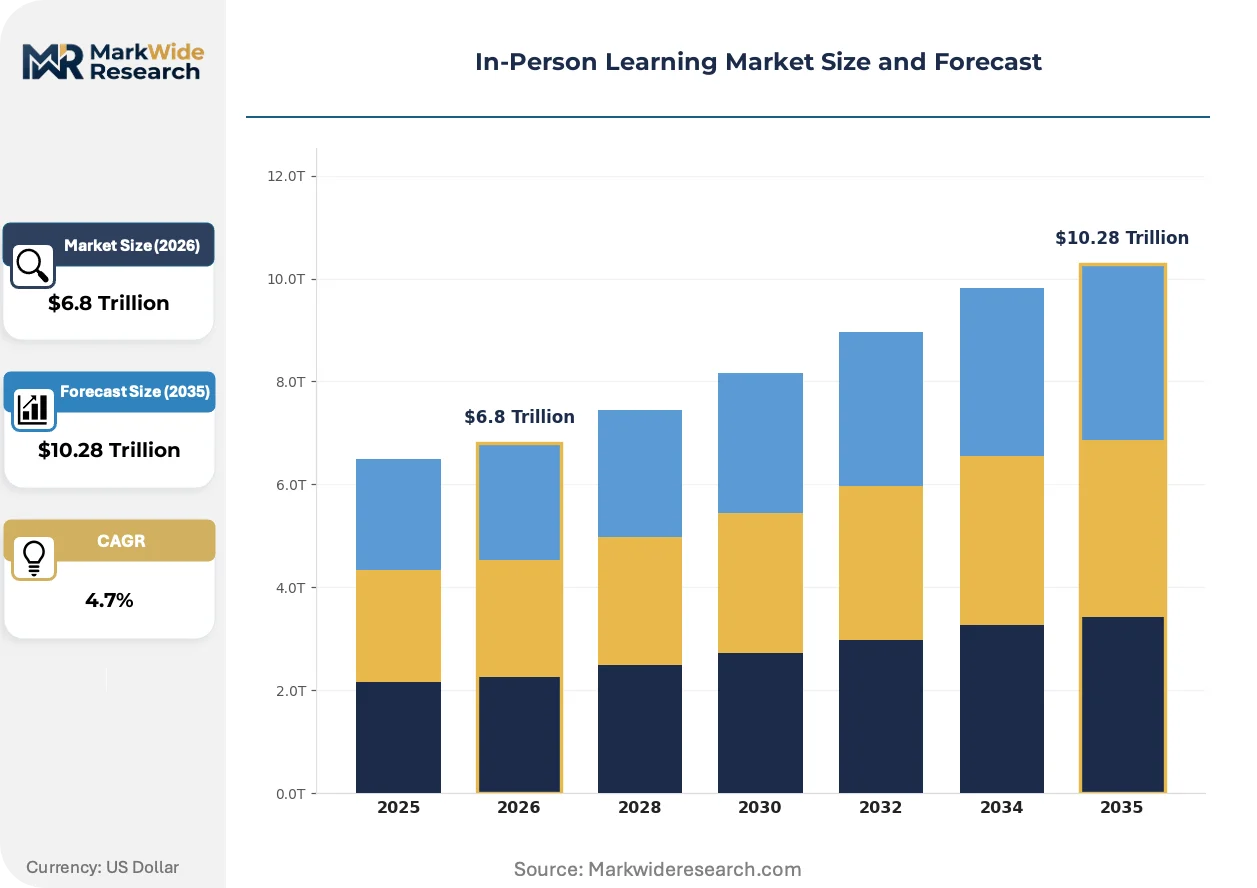
Corporate training budgets are stabilizing after hybrid work normalization, yet physical credential verification and tacit knowledge transfer sustain institutional demand for classroom delivery. China's Ministry of Education accreditation tightening and India's NCTE recognition mandates are reshaping provider compliance structures across major enrollment corridors.
Growth Catalysts
- Fortune 500 training budget expansion:Employer-sponsored reimbursement structures for verified competency programs are pulling corporate cohorts back into physical classrooms as hybrid work models mature.
- India's tier-2 city density:Engineering coaching institutes in Kota and Hyderabad are driving enrollment concentration that lowers per-student acquisition costs through geographic clustering.
- Title IV eligibility pathways:US Department of Education federal aid access filters institutional scale, creating sustainable enrollment moats for accredited providers.
Market Restraints
- Fixed facility cost structures:Classroom infrastructure, housing bundling, and synchronous scheduling requirements lock in high operating leverage that compresses margins during enrollment volatility.
- China's provincial licensing fragmentation:Post-2021 curriculum reform guidelines under Ministry of Education supervision have multiplied compliance touchpoints for private tutoring operators.
- Digital substitution pressure:Asynchronous learning platforms and remote assessment tools are capturing share in standardized test preparation segments.
Strategic Opportunities
- Cross-border degree recognition gaps:Divergent national quality frameworks are creating demand for accreditation portability services and bilateral verification infrastructure.
- Skill development course premiumization:Employer demand for verified competency over degree proxies is opening pricing power in non-credit workforce training.
- Executive education campus networks:Multi-location delivery models leveraging faculty mobility between hubs like Fontainebleau and Singapore capture international cohort premiums.
Industry Challenges
- Accreditation timeline compression:India's NCTE recognition mandates and China's tightened standards are extending compliance cycles while freezing new entrant capacity.
- Faculty credential scarcity:Cross-border mobility requirements and specialized subject expertise gaps constrain program expansion velocity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | In-Person Learning Market |
| Market Size in 2026 | $6.8 Trillion |
| Market Size in 2035 | $10.28 Trillion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Delivery Mode: Classroom, Workshop, Internship, Seminar Target Audience: Students, Professionals, Educators, Corporate Trainees Course Type: Vocational, Academic, Certification, Skill Development Duration: Short-term, Long-term, Weekend, Intensive |
| Companies Covered | ISACA, Sylvan Learning, Wyzant, Kaplan, INSEAD, British Study Centers, Triumphant Institute of Management Education, Vibrant Academy, All A's Tuition, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
In-Person Learning Market Emerging Trajectories
Physical learning infrastructure is being reconfigured by hybrid delivery expectations, regulatory accreditation pressures, and employer verification demands that privilege face-to-face assessment protocols over remote alternatives.
Immersive simulation technology is virtualizing portions of hands-on training previously requiring physical co-presence. Medical and technical institutes are adopting haptic feedback systems and VR laboratories at measured pace. This compression of physical facility requirements is virtualizing capacity planning while preserving credential integrity through supervised assessment.
China's Ministry of Education has implemented curriculum reform guidelines that restrict private tutoring licensing to accredited operators. Provincial subsidiaries now supervise compliance through post-2021 frameworks that mandate facility inspections and instructor certification. Private tutoring centers in tier-one cities are responding through formal partnerships with recognized institutions.
Employer procurement of workforce training is consolidating around verified outcome metrics rather than seat-time proxies. Corporate learning and development departments are unbundling traditional degree partnerships in favor of competency-based contracts with assessment guarantees. This pattern is most visible in North American manufacturing and healthcare verticals where regulatory audit trails require documented skill verification.
In-Person Learning Market Segmentation
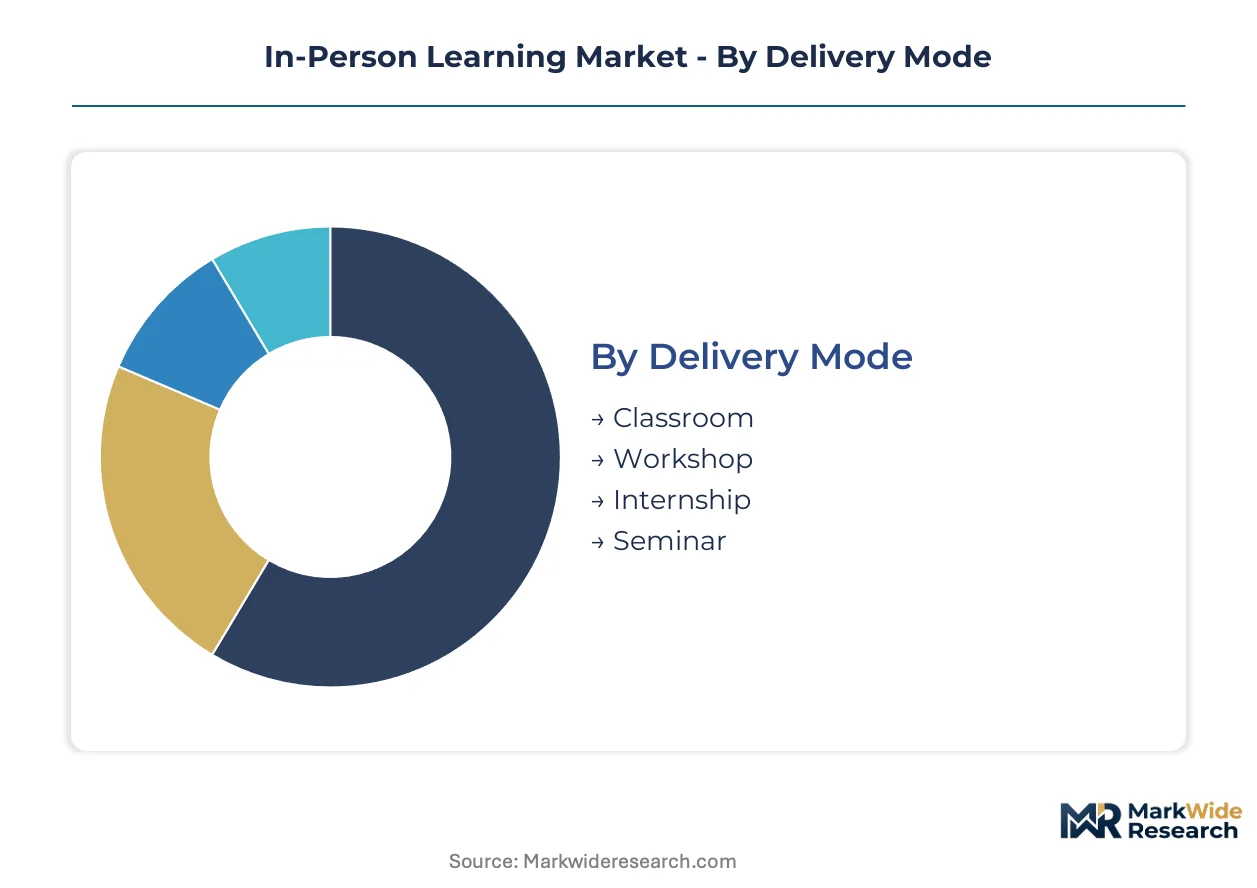
In-person learning markets fragment across delivery infrastructure, learner profiles, and credential objectives. These divisions determine facility investment requirements, pricing power, and regulatory exposure for providers.
Delivery Mode:
Mature synchronous formats coexist with emerging experiential modalities that compress time-to-competency.
- Classroom:Scheduled instructor-led sessions in dedicated physical facilities with fixed seating capacity and bundled administrative services. India's Kota coaching corridor concentrates enrollment density here, leveraging geographic clustering to amortize real estate costs across large cohorts.
- Workshop:Compressed hands-on sessions emphasizing equipment access and supervised practice. Manufacturing and healthcare verticals in Germany's industrial regions drive demand for these intensive formats where tacit skill transfer requires physical co-presence.
- Seminar:Expert-led discussion forums with limited enrollment for peer networking. Executive education providers deploy these for cross-border cohorts seeking relationship capital formation.
- Internship:Workplace-embedded learning with structured mentorship and assessment protocols. Regulatory audit requirements in US healthcare and aviation sectors mandate documented supervised hours.
Classroom delivery handles the majority of throughput; workshop formats are gaining share fastest among employer-funded programs.
Target Audience:
Customer type stratification separates institutional procurement from individual payment, reshaping acquisition economics.
- Corporate Trainees:Employer-sponsored cohorts with customized curricula and outcome-based pricing. US Fortune 500 procurement departments negotiate these contracts with verified competency guarantees, creating superior margin pools through reimbursement structures.
- Students:Degree-seeking learners in accredited programs with federal aid eligibility. China's Ministry of Education accreditation tightening has restricted provider participation for this segment.
- Professionals:Mid-career learners pursuing certification or licensure maintenance. India's tier-2 city engineering coaching institutes target this group for competitive exam preparation.
- Educators:Pre-service and in-service teacher training requiring NCTE recognition in India. Compliance timelines for this segment extend capacity planning horizons.
Corporate trainees command premium pricing; professionals represent the steepest expansion trajectory as degree proxies lose employer favor.
Course Type:
Volume concentration varies by credential authority and employment linkage.
- Academic:Degree-conferring programs with Title IV eligibility pathways in the US. Federal aid access filters sustainable enrollment scale for accredited providers.
- Skill Development:Non-credit workforce training with competency verification. North American manufacturing and healthcare procurement is consolidating around these outcome-based contracts.
- Certification:Third-party validated credentials for regulated professions. Kaplan sustains premium positioning here through standardized test heritage.
- Vocational:Trade-specific training with equipment-intensive facility requirements. China's provincial licensing fragmentation has multiplied compliance touchpoints for private operators.
Academic programs anchor enrollment volume; skill development courses are climbing the fastest on employer demand for verified competency.
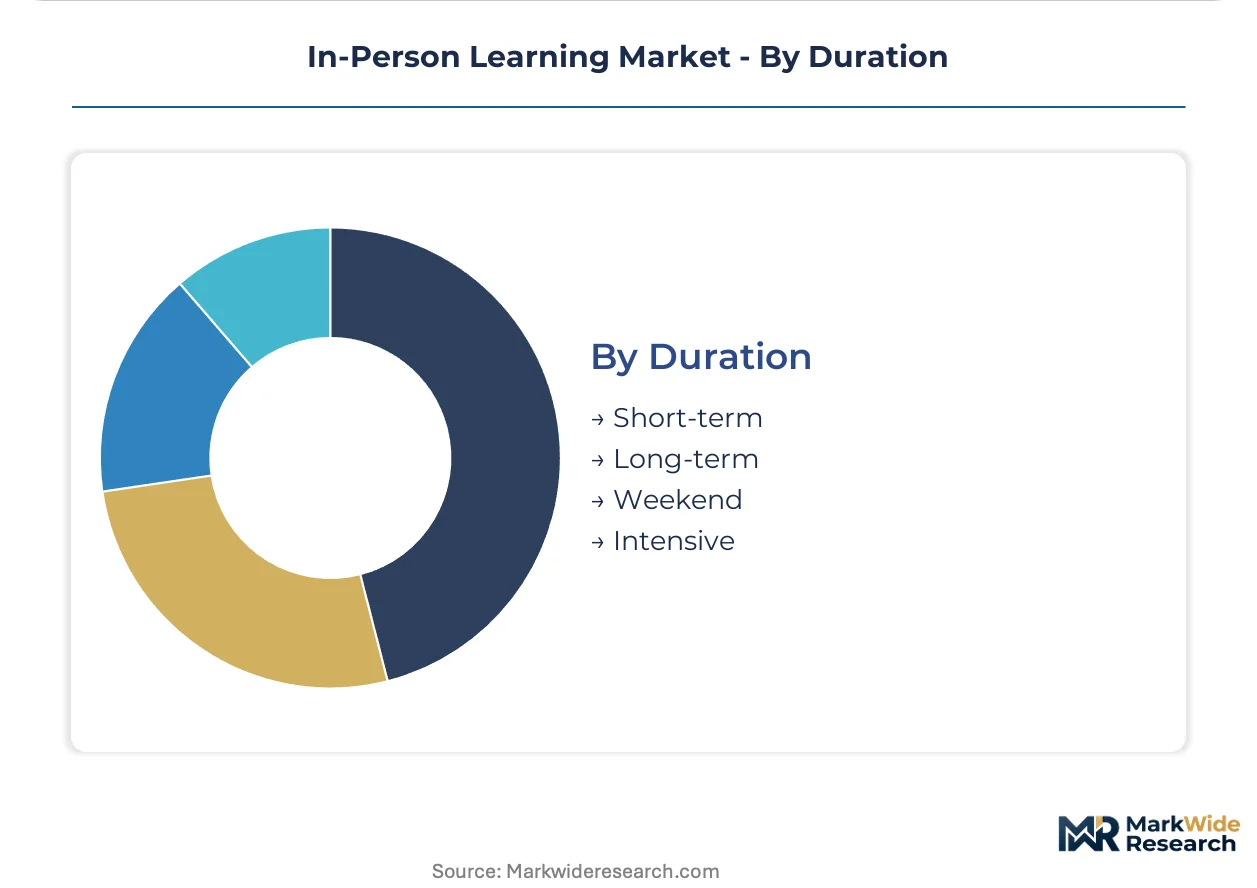
Duration:
Scheduling flexibility separates consumer-paid from employer-funded segments.
- Long-term:Semester or multi-year degree programs with housing bundling. INSEAD's Fontainebleau and Singapore campuses anchor executive education through these extended formats.
- Intensive:Compressed full-immersion schedules with accelerated assessment. India's Vibrant Academy dominates JEE preparation through Rajasthan-based intensive models.
- Short-term:Brief modules for discrete skill acquisition. Digital substitution pressure is most acute here as asynchronous platforms capture share.
- Weekend:Part-time formats for employed learners. These accommodate professional schedules but constrain facility utilization rates.
Long-term programs lock in facility commitments; intensive formats are expanding most quickly where competitive exam preparation concentrates demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Facility-intensive providers cluster where regulatory accreditation creates sustainable enrollment moats. Federal aid access, provincial licensing frameworks, and national quality standards filter which operators achieve viable scale.
United States
Corporate training procurement and degree-conferring institutions drive demand concentration. The US Department of Education enforces Title IV eligibility standards that filter institutional access to federal student aid. Kaplan leverages standardized test heritage to sustain premium positioning in North American metro corridors.
China
Private tutoring licensing restrictions and curriculum reform guidelines reshape provider compliance structures. The Ministry of Education and its provincial subsidiaries supervise accreditation under post-2021 frameworks. Tier-one city operators respond through formal partnerships with recognized institutions to maintain market presence.
India
Engineering coaching institutes in tier-2 cities concentrate enrollment density through geographic clustering. The National Council for Teacher Education mandates recognition for educator training programs. Kota and Hyderabad coaching hubs reconfigure capacity allocation for competitive exam preparation at lower per-student acquisition costs.
Germany
Manufacturing and healthcare verticals drive demand for intensive workshop formats requiring equipment access. Federal and state-level vocational training regulations mandate documented supervised hours for regulated professions. Industrial regions sustain tacit skill transfer through compressed hands-on sessions with structured mentorship protocols.
United Kingdom
Executive education and professional certification segments attract mid-career learners pursuing credential maintenance. The Office for Students and sector-specific regulators supervise quality assurance for degree-conferring providers. London and Southeast England anchor seminar formats for cross-border cohorts seeking relationship capital formation.
In-Person Learning Market Vendor Landscape
Accredited institutional providers and specialized coaching operators split the market into distinct competitive spheres. Title IV eligibility and national recognition mandates create enrollment moats that sustain incumbent positions against unaccredited entrants. Two strategic archetypes dominate: heritage test-prep brands with standardized assessment legacies, and geography-bound coaching specialists leveraging local clustering economics. Competitive moves concentrate on accreditation portability services and cross-border campus network expansion.
Within the heritage test-prep tier, Kaplan and INSEAD exemplify divergent positioning strategies. Kaplan occupies a position anchored in North American standardized test markets, while INSEAD represents the multi-location executive education model leveraging faculty mobility between Fontainebleau and Singapore. Among geography-bound specialists, Vibrant Academy sits within the Rajasthan-based intensive preparation segment where concentrated enrollment density limits replication costs for engineering exam coaching.
| Leading Market Players |
|---|
| ISACA |
| Sylvan Learning |
| Wyzant |
| Kaplan |
| INSEAD |
| British Study Centers |
| Triumphant Institute of Management Education |
| Vibrant Academy |
| All A's Tuition |
| Others |
Supply Flow & Price Mechanics
Kota's coaching corridor in Rajasthan anchors capacity allocation for India's competitive exam preparation sector, where concentrated enrollment density enables per-student acquisition cost compression that downstream providers translate into pricing power across tier-2 city markets.
Pricing Analysis
Title IV eligibility standards dictate the pricing tier structure for US degree-conferring institutions, with federal aid access creating sustainable enrollment moats that separate premium-accredited providers from unaccredited economy-tier operators. Price differentiation rests on certification grade and geographic delivery cost, with classroom-housing bundled programs commanding premiums over standalone workshop formats. Pricing pressure stems from digital substitution in standardized test segments, compressing margins for asynchronous-vulnerable course types. Corporate trainees exhibit lowest price sensitivity due to employer-sponsored reimbursement structures, while individual degree-seekers face highest sensitivity where federal aid coverage gaps persist.
Supply Chain Analysis
Extended payment terms from facility landlords and supply-chain finance facilities from equipment vendors sustain working capital for India's coaching institute operators. Geographic supply concentration centers on India, China, and the United States as primary enrollment corridors. Raw material dependencies include classroom infrastructure, residential housing stock, and immersive simulation hardware. Single-source vulnerability runs through provincial licensing authorities in China, where Ministry of Education supervision fragments compliance touchpoints. Distribution runs through direct institutional enrollment, corporate L&D procurement departments, and third-party aggregator platforms for test preparation services.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
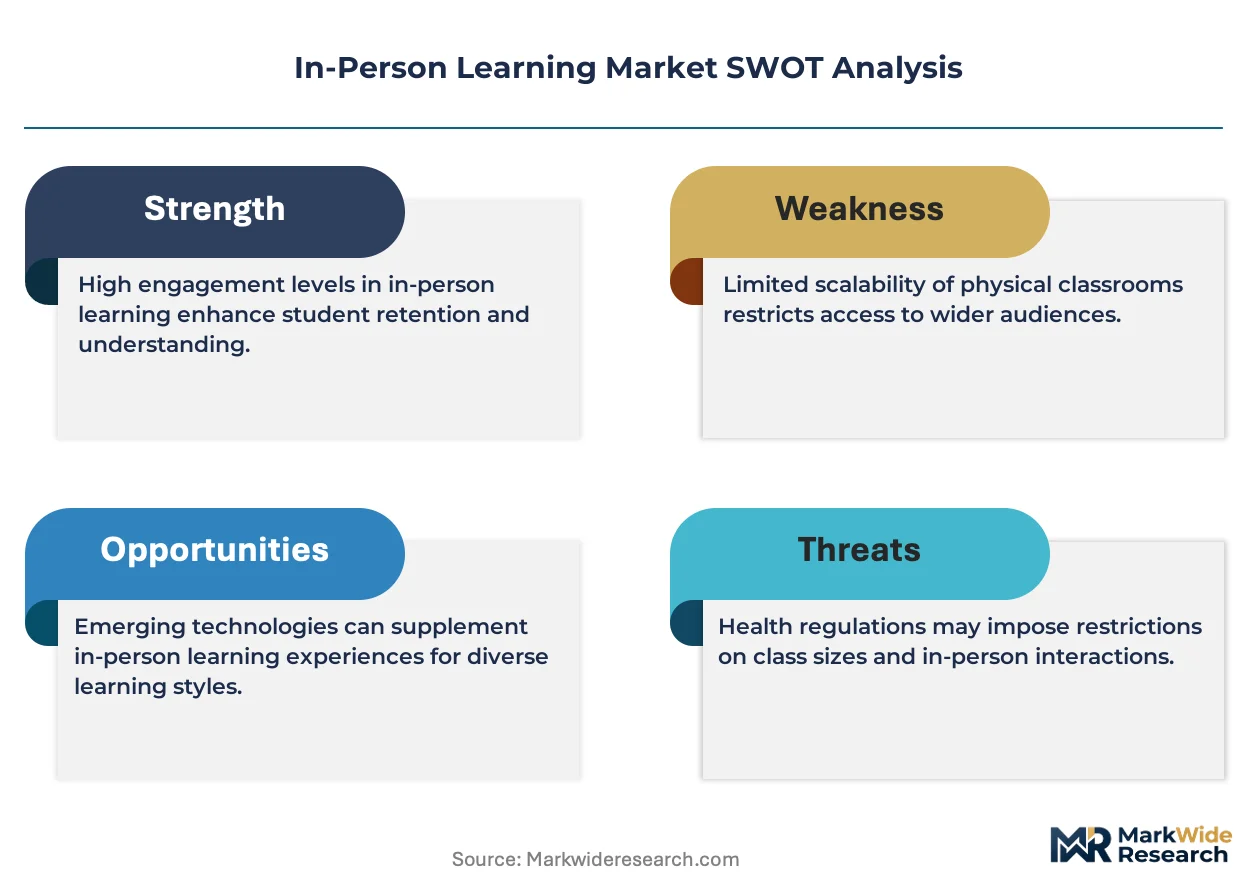
Employer unbundling of degree partnerships creates fragmentation opportunity across verified competency segments, as procurement departments demand outcome-based contracts that favor specialized providers over bundled institutional offerings.
For Market Incumbents: Insulate enrollment scale through accelerated Title IV certification investments and backward integration into assessment technology. Digital substitution pressure from asynchronous platforms threatens classroom-delivery margins; vertical integration into immersive simulation hardware preserves credential integrity while virtualizing facility requirements. Cross-border campus networks leveraging faculty mobility between Fontainebleau and Singapore archetypes capture international cohort premiums. For New Entrants and Emerging Players: Mid-market skill development courses in North American manufacturing and healthcare verticals represent the most penetrable entry point, where employer procurement consolidation around verified outcome metrics favors nimble competency-based contracts over legacy degree partnerships. India's tier-2 city engineering coaching density offers secondary white-space for specialized exam preparation formats. Go-to-market execution should anchor in direct corporate L&D procurement relationships with assessment guarantee structures. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among corporate training providers with employer-sponsored reimbursement structures, where multi-year competency contracts generate predictable cash flow streams. Long-term viability over a five-to-ten year window favors accredited institutional operators with sustainable enrollment moats. The acquisition target archetype centers on geography-bound coaching specialists with concentrated enrollment density and limited replication costs. Monitor accreditation portability agreement fragmentation as early signal for cross-border degree recognition service demand inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Accreditation Portfolio Expansion | Title IV eligibility pathways filter sustainable enrollment scale for US degree-conferring providers. |
| Immersive Simulation Integration | VR laboratories and haptic feedback systems virtualize capacity planning while preserving credential integrity. |
| Cross-Border Campus Network | Multi-location delivery models leveraging faculty mobility capture international executive education premiums. |
| Corporate L&D Direct Contracting | Outcome-based procurement relationships with Fortune 500 training departments secure superior margin pools. |
| Provincial Licensing Partnership | Formal alliances with recognized institutions navigate China's post-2021 curriculum reform compliance requirements. |
Methodological Framework
The analysis maps classroom delivery, workshop formats, seminar models, and internship structures, each validated through institutional enrollment officers, corporate L&D procurement directors, regulatory affairs specialists at accreditation bodies, and facility operations managers. Primary interviews with these stakeholders combined with secondary validation from US Department of Education Title IV databases, India's NCTE recognition filings, China's Ministry of Education provincial licensing records, and employer training expenditure disclosures. Bottom-up enrollment modeling and top-down market sizing triangulate volume estimates.
Assumptions held fixed include hybrid work normalization stability, current accreditation portability frameworks, and employer preference trajectory toward verified competency over degree proxies. Variables tested across the analysis window span regulatory tightening intensity, digital substitution penetration rates, and cross-border faculty mobility recovery patterns. Segmentation dimensions modeled encompass delivery mode, target audience, course type, and duration tier. CAGRs derive from enrollment trend extrapolation adjusted for capacity constraints and compliance cycle extensions. Forecast inputs include corporate training budget trajectories and provincial licensing approval timelines.
Practitioners should monitor accreditation timeline compression and digital platform substitution rates for early signals of demand migration. Forecasts reflect these documented assumptions; macroeconomic contraction, regulatory deviation, or immersive technology disruption would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
UAE Private K12 Education Market