
 UAE Private K12 Education Market | 2026-2036
UAE Private K12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
UAE Private K12 Education Market Analytics
Annual subscription models for digital learning platforms and software-defined adaptive assessment tools is rebalancing how tuition revenue gets structured across the academic year. GEMS Education leverages its multi-campus network to sustain enrollment density across Dubai and Abu Dhabi. Taaleem Holdings anchors its position through specialized British and IB curriculum offerings. Aldar Education competes via integrated facilities management and captive real estate in Abu Dhabi's investment zones.
Private K12 education in the UAE comprises independently operated primary and secondary institutions delivering accredited curricula to students from pre-kindergarten through grade twelve, typically under 40-student classroom caps with technology-integrated instruction. These schools serve the country's majority expatriate population, which lacks access to free public education. The British curriculum segment occupies the largest enrollment share among international offerings, while the blended learning methodology category is expanding fastest as schools deploy hybrid classroom-digital delivery models. The premium tuition fee tier captures the dominant revenue pool, though mid-range institutions are broadening accessibility for middle-income expatriate households.
MOHAP's school health and safety standards, the UAE Ministry of Education's licensing requirements, and ADEK's quality assurance frameworks in Abu Dhabi collectively shape operational compliance and facility investment thresholds for private operators. KHDA's inspection ratings in Dubai directly influence parent choice dynamics and tuition pricing flexibility. Stakeholders must monitor how evolving federal curriculum localization mandates interact with international accreditation requirements to determine program design and capital allocation priorities.
Market Dynamics
The UAE Ministry of Education's mandatory licensing framework for private schools is compressing operational timelines and forcing capital redeployment toward compliance infrastructure. This regulatory pressure is reshaping how operators sequence facility investments and curriculum accreditation.
Growth Catalysts
- ADEK Quality Assurance Frameworks:Abu Dhabi's inspection regime rewards high-performing institutions with enrollment caps and tuition flexibility. Premium-tier operators capture density in Khalifa City corridors.
- Blended Learning Methodology:Hybrid classroom-digital delivery models reduce per-student physical space requirements. Schools deploy adaptive assessment platforms to extend instructional reach.
- Dubai Free Zone School Clusters:Jebel Ali and Dubai South education zones offer 100% foreign ownership and streamlined licensing. Expatriate enrollment concentrates in these purpose-built developments.
Market Restraints
- Real Estate Captivity:Aldar Education and integrated facility operators lock mid-tier competitors out of prime Abu Dhabi investment zones. Lease premiums in Dubai's established districts consume 25-35% of operating budgets.
- Curriculum Localization Mandates:Federal Arabic language and Emirati history requirements add instructional hours without corresponding tuition adjustment mechanisms. IB and British curriculum schools face program design friction.
- Teacher Supply Concentration:Recruitment pipelines from the UK, Ireland, and South Africa face post-pandemic mobility constraints. Visa processing delays extend onboarding cycles by 60-90 days.
Strategic Opportunities
- Mid-Range Fee Tier Expansion:Sharjah and Ras Al Khaimah present underpenetrated demand from middle-income expatriate households. Current premium-heavy supply leaves 40,000+ student seats unaddressed.
- Annual Subscription Revenue Models:Digital learning platforms and software-defined assessment tools enable recurring revenue streams. Operators rebalance cash flow across academic terms.
- KHDA Rating Premium Mechanism:Dubai's inspection-driven parent choice dynamics allow Outstanding-rated schools to command 15-20% tuition premiums. Investment in inspection preparedness yields direct pricing power.
Industry Challenges
- Accreditation Timeline Compression:Dual British/IB curriculum schools face overlapping inspection cycles from KHDA, ADEK, and external accreditors. Compliance staff requirements strain administrative bandwidth.
- Facility Reconfiguration Costs:Post-pandemic ventilation standards and flexible classroom specifications demand HVAC upgrades and modular furniture systems. Capex cycles compress from seven to four years.
- Digital Platform Integration Complexity:Legacy student information systems resist API connectivity with adaptive learning engines. IT procurement must sequence vendor consolidation before pedagogical deployment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | UAE Private K12 Education Market |
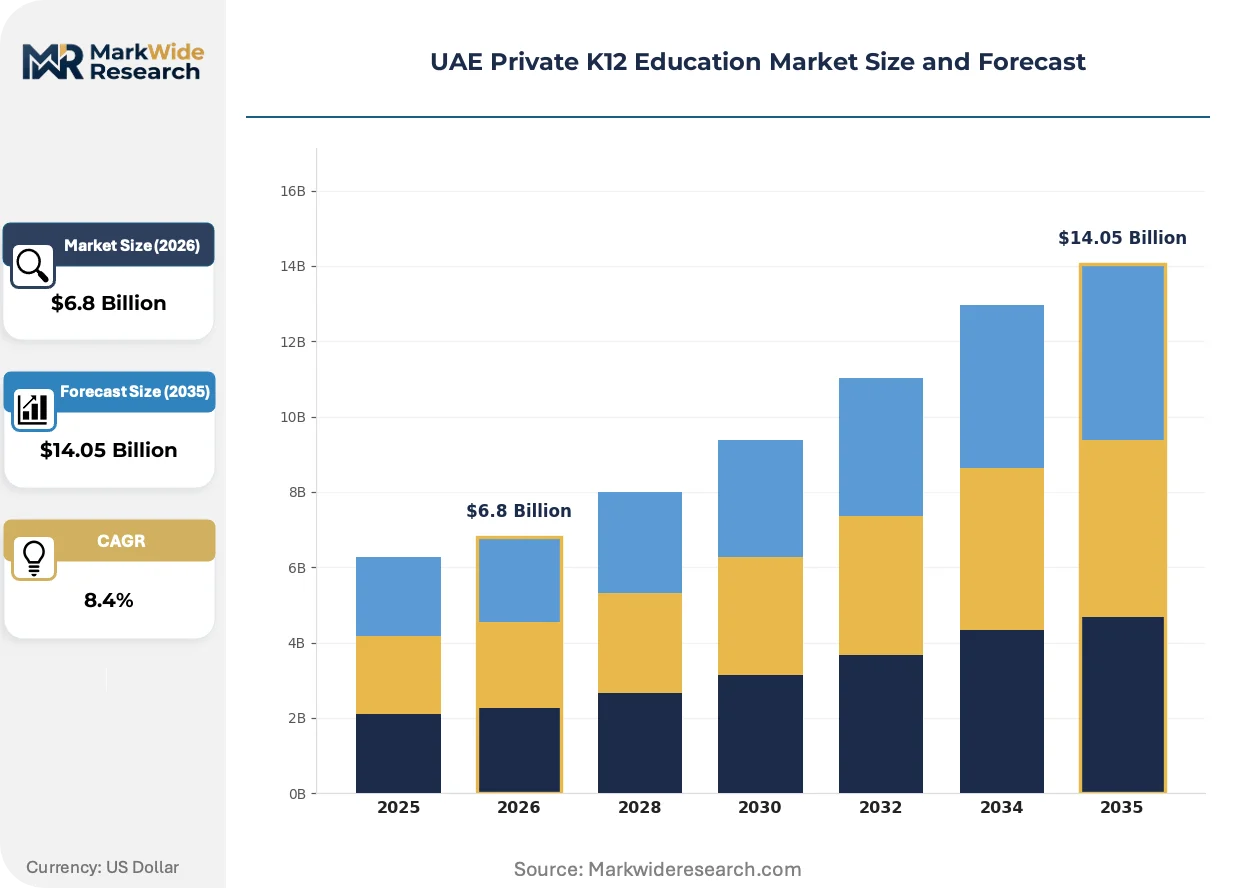
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $14.05 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Curriculum Type: British, American, International Baccalaureate, Indian Grade Level: Primary, Secondary, Pre-K, High School Teaching Methodology: Montessori, Traditional, Blended Learning, Project-Based Learning Tuition Fee Range: Low Cost, Mid Range, Premium, Luxury |
| Companies Covered | Taaleem Holdings, Esol Education, GEMS Education, Innoventures Education, Kings’ Schools Group, SABIS Education Services, Athena Education, Nord Anglia Education, Aldar Education, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
UAE Private K12 Education Market Evolving Landscape
Adaptive learning infrastructure is absorbing capital allocation that previously flowed to physical expansion. Operators now prioritize data architecture over square footage as the primary competitive differentiator.
AI-powered diagnostic assessment engines are absorbing instructional planning functions previously executed by department heads. GEMS Education and Taaleem Holdings deploy these platforms across multi-campus networks to standardize learning outcomes. The technology is absorbing variance in teacher quality, compressing the performance gap between flagship and satellite campuses.
KHDA's mandatory wellbeing indicators and MOHAP school health standards are tightening facility specifications for mental health support spaces. Operators must dedicate 8-12% of gross floor area to counseling suites and sensory rooms. The British curriculum segment faces the steepest compliance ramps as inspection frameworks integrate socio-emotional metrics alongside academic benchmarks.
Parent selection behavior is rotating toward inspection transparency and outcome data over brand heritage. Dubai's KHDA rating database enables direct school-to-school comparison on 90+ performance indicators. Sharjah families increasingly commute to Dubai free zone clusters rather than accepting uninspected local alternatives.
UAE Private K12 Education Market Segmentation
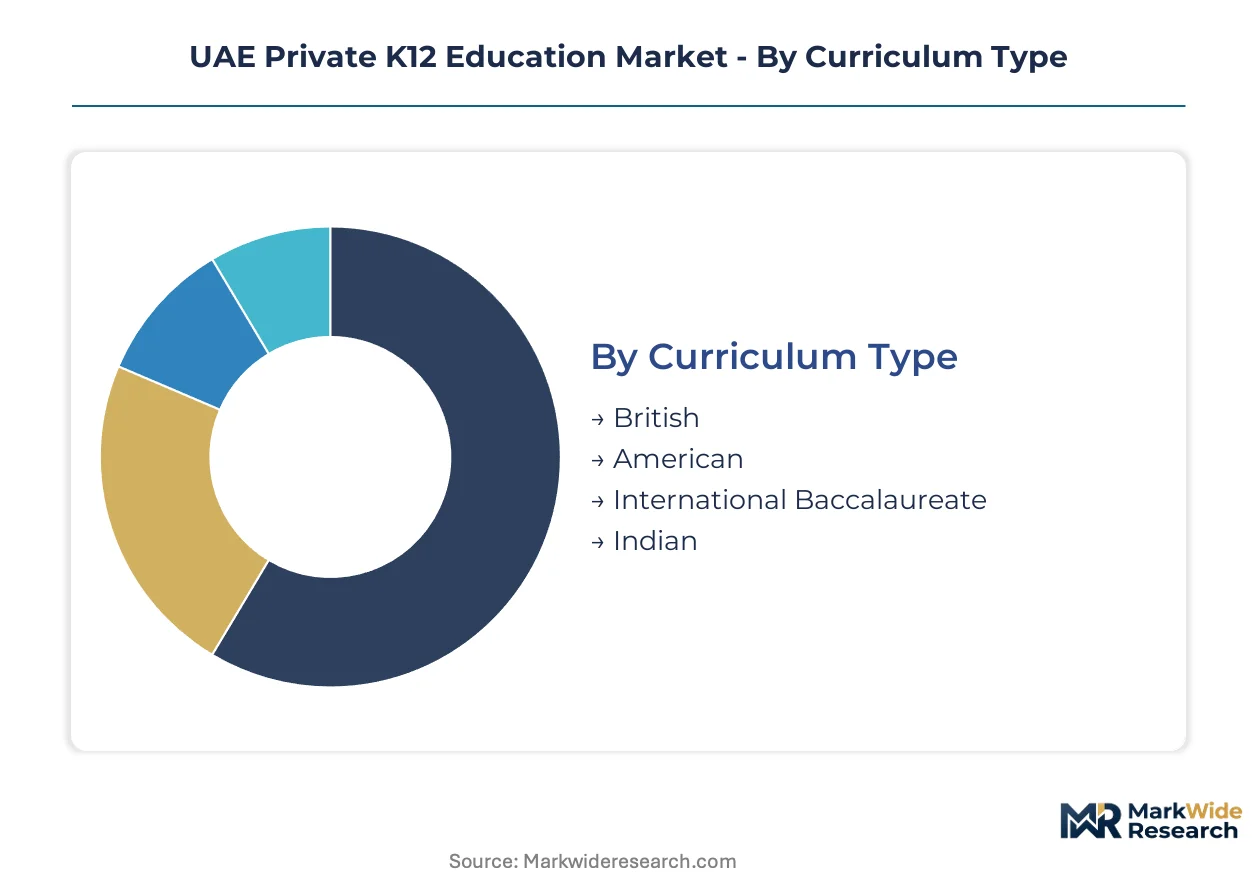
Segmentation in the UAE Private K12 Education Market reveals how expatriate family preferences, regulatory frameworks, and real estate economics fragment demand across distinct operational models. Curriculum accreditation and tuition positioning determine competitive boundaries more sharply than in mature education markets.
Curriculum Type:
Parent selection behavior gravitates toward accreditation portability and university recognition in home countries.
- British:The GCSE and A-Level pathway dominates enrollment density across Dubai and Abu Dhabi. Families from Commonwealth nations cluster in KHDA Outstanding-rated British curriculum institutions, driven by UK university admission familiarity and KHDA inspection transparency.
- International Baccalaureate:Full IB continuum schools command the steepest fee premiums and attract globally mobile corporate expatriates. Demand concentrates in Dubai's free zone clusters where multinational employers subsidize tuition as retention tools.
- American:AP-focused programs serve North American diplomatic and energy sector families concentrated in Abu Dhabi's diplomatic quarter and Dubai's Jumeirah district.
- Indian:CBSE-affiliated schools address South Asian middle-income household demand in Sharjah and Deira, with fees positioned 40-60% below premium-tier alternatives.
British curriculum leads on scale; International Baccalaureate leads on momentum.
Grade Level:
Facility investment intensity and staffing ratios vary dramatically across developmental stages.
- Primary:Foundation Stage through Year 6 requires specialized early years facilities and 1:8 teacher-student ratios. Capital allocation concentrates in purpose-built campuses with dedicated outdoor learning zones.
- Secondary:Years 7-13 absorb the majority of science laboratory and examination infrastructure spend. ADEK and KHDA inspection weighting intensifies at this level, driving exam outcome investment.
- Pre-K:Nursery and early childhood provision operates under MOHAP health and safety standards with separate licensing timelines from K-12 operations.
- High School:The final examination years trigger university counseling suite investments and career guidance technology platforms.
Secondary enrollment leads on scale; Pre-K leads on momentum.
Teaching Methodology:
Technology integration depth and physical space flexibility differentiate operational models.
- Blended Learning:Hybrid classroom-digital delivery reduces per-student square footage requirements while extending instructional reach through adaptive assessment platforms. Operators deploy this model to compress facility costs in high-rent Dubai districts.
- Montessori:Child-directed learning environments demand specialized materials and 3-year mixed-age classroom configurations. Premium positioning in Jumeirah and Al Raha Beach attracts sustainability-conscious European expatriates.
- Traditional:Teacher-centered instruction maintains cost discipline and standardized outcome predictability for mid-range fee positioning.
- Project-Based Learning:Interdisciplinary curriculum design requires flexible furniture systems and extended class block scheduling, absorbing higher administrative coordination overhead.
Traditional methodology leads on scale; Blended Learning leads on momentum.
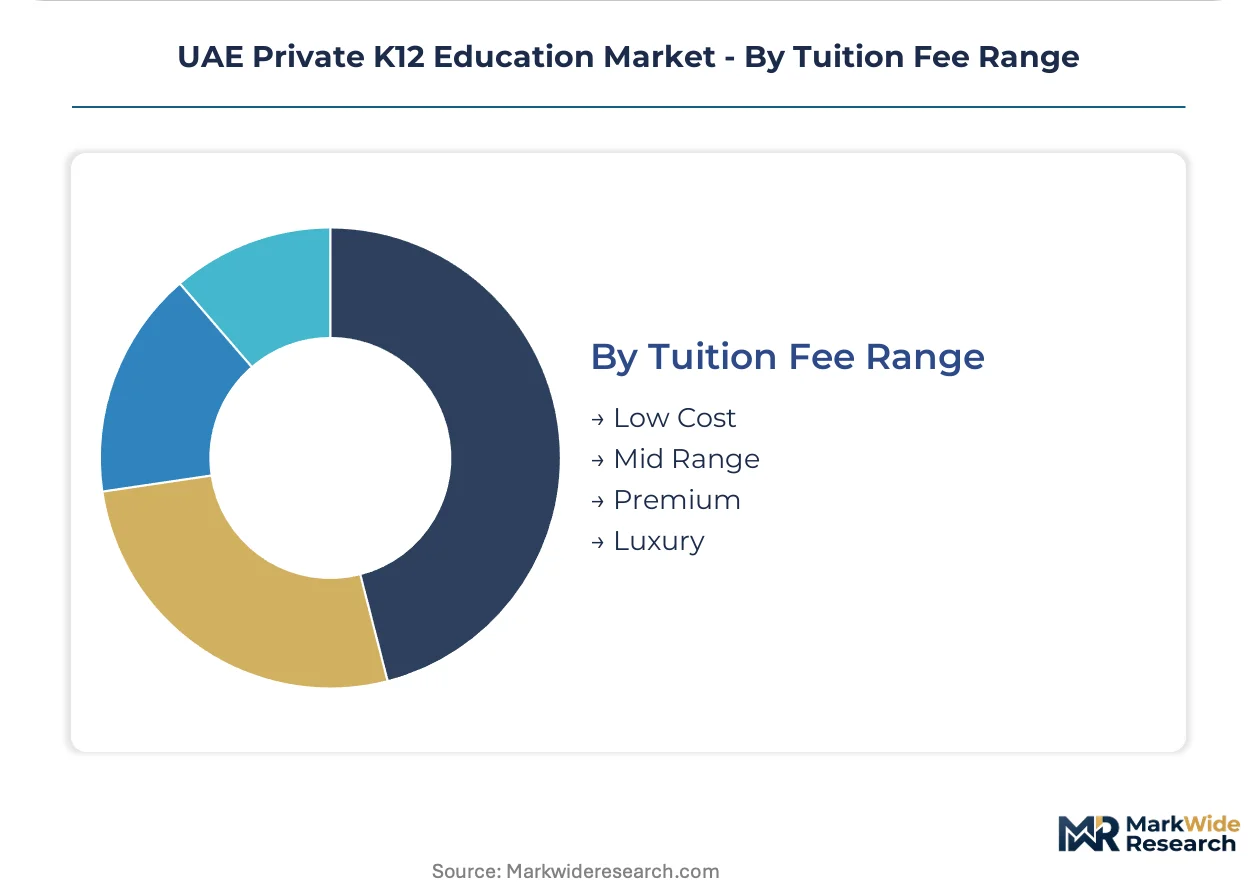
Tuition Fee Range:
Real estate captivity and regulatory compliance costs stratify the addressable market.
- Premium:Annual fees above AED 50,000 capture the dominant revenue pool across Dubai's established districts. KHDA Outstanding ratings enable 15-20% pricing power over Good-rated competitors.
- Mid Range:AED 25,000-50,000 positioning targets middle-income expatriate households in Sharjah and Ras Al Khaimah corridors, where 40,000+ student seats remain unaddressed.
- Low Cost:Sub-AED 25,000 operations concentrate in Ajman and Northern Emirates, competing on accessibility rather than facility specification.
- Luxury:Ultra-premium positioning above AED 80,000 integrates concierge services, elite sports academies, and boarding facilities for UHNWI families.
Premium tier leads on scale; Mid Range leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Dubai commands premium tuition density while Abu Dhabi scales through integrated development models, yet Sharjah and Ras Al Khaimah reveal the most acute supply gaps for middle-income households.
Dubai
Expatriate corporate families and KHDA inspection transparency drive enrollment concentration in Jebel Ali and Dubai South free zones. The Knowledge and Human Development Authority mandates wellbeing indicators alongside academic benchmarks. Jumeirah and Al Barsha host Outstanding-rated British curriculum clusters where operators capture 15-20% tuition premiums.
Abu Dhabi
ADEK quality assurance frameworks reward high-performing institutions with enrollment flexibility and pricing power. The Abu Dhabi Department of Education and Knowledge enforces stricter facility standards than federal baselines. Khalifa City education corridors concentrate premium-tier campuses near investment zone employment centers.
Sharjah
Middle-income South Asian households generate unmet demand estimated at 40,000+ student seats below premium pricing tiers. The Sharjah Private Education Authority licenses institutions under MOE-aligned standards with longer approval timelines. University City and Muwaileh commercial zones attract mid-range operators seeking lower real estate costs than Dubai.
Ras Al Khaimah
Northern Emirates manufacturing and logistics employment creates steady demand for affordable international schooling. The Ras Al Khaimah Economic Zone offers streamlined licensing for education investors. Al Hamra and Al Marjan Island developments host emerging campus clusters serving cross-emirate commuter families.
Northern Emirates
Ajman and Fujairah operate as cost-competitive alternatives with sub-AED 25,000 fee positioning. The Ministry of Education's federal licensing applies without free zone exemptions available in Dubai. Downtown Ajman and Fujairah City concentrate Indian curriculum providers serving blue-collar expatriate communities.
UAE Private K12 Education Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with multi-campus networks consolidating density in premium corridors while single-site operators defend niche positioning. The vendor base concentrates around three strategic archetypes: integrated real estate-education platforms, curriculum-specialized holding companies, and global school brand licensors. M&A activity targets mid-tier assets in secondary emirates, while technology partnerships absorb capital previously directed toward physical expansion.
Within the integrated platform tier, Aldar Education anchors Abu Dhabi's captive real estate model, Taaleem Holdings exemplifies curriculum-specialized consolidation through British and IB offerings, and GEMS Education represents multi-campus network density across Dubai and Abu Dhabi. These three operators occupy distinct competitive positions without overlapping geographic or segment focus, allowing each to extract pricing power from regulatory inspection regimes and location-specific demand concentration.
| Leading Market Players |
|---|
| Taaleem Holdings |
| Esol Education |
| GEMS Education |
| Innoventures Education |
| Kings' Schools Group |
| SABIS Education Services |
| Athena Education |
| Nord Anglia Education |
| Aldar Education |
| Others |
Value Network & Pricing Analysis
Adaptive learning platform deployment is compressing traditional facility cost structures while concentrating procurement power among multi-campus operators who negotiate enterprise software licenses across Dubai and Abu Dhabi networks. This technology transition simultaneously reduces per-student physical space requirements and elevates digital infrastructure spending, reshaping how schools allocate capital between fixed real estate and recurring technology subscriptions.
Pricing Analysis
Capacity additions in Sharjah and Ras Al Khaimah are reshaping price floors for mid-range fee positioning as new entrants absorb lower real estate costs than Dubai incumbents. Three-tier pricing structure across premium, mid-range, and economy levels stratifies by KHDA inspection rating and curriculum accreditation tier, with Outstanding-rated British curriculum schools commanding measurable premiums over Good-rated alternatives. Cost compression in the economy tier intensifies because Ajman and Northern Emirates operators compete on accessibility without comparable facility investment. Middle-income South Asian households in Sharjah exhibit highest price sensitivity, while multinational corporate assignees in Dubai free zones demonstrate lowest sensitivity due to tuition subsidy structures.
Supply Chain Analysis
Technology refresh cycles and modular furniture redeployment create secondary procurement flows as schools reconfigure classrooms for blended learning delivery. Hardware procurement concentrates in China, software licensing flows from United States and United Kingdom vendors, and specialized educational materials originate from British curriculum publishers. Supply chain risk centers on single-source vulnerability for proprietary adaptive assessment platforms that resist API interoperability with legacy student information systems. Distribution runs through direct enterprise sales relationships with multi-campus networks, bypassing traditional educational supply distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UAE Private K12 Education Market functions as a regulatory compounder where KHDA inspection transparency and ADEK quality assurance frameworks create self-reinforcing demand concentration around rated institutions. Federal curriculum localization mandates represent the pivotal regulatory milestone accelerating facility reconfiguration and compliance staffing investments across all tiers.
For Market Incumbents: Anchor enrollment density through multi-campus network effects in Dubai free zones and Abu Dhabi investment corridors. Defensive consolidation should prioritize backward integration into captive real estate development to neutralize lease premium volatility that consumes 25-35% of operating budgets. Accreditation timeline compression from overlapping KHDA, ADEK, and external inspectorate cycles demands dedicated compliance infrastructure investment as the critical lever against administrative bandwidth strain. For New Entrants and Emerging Players: Capture the 40,000+ unaddressed student seats in Sharjah and Ras Al Khaimah mid-range segments where premium-heavy incumbent supply leaves demand exposed. White-space targets include British curriculum positioning below AED 50,000 annual fees and blended learning methodology deployment to compress facility costs in lower-rent corridors. Go-to-market execution should emphasize KHDA rating pursuit from launch to unlock tuition flexibility and parent choice advantages. For Investors and Strategic Acquirers: Valuations sit cheapest among single-site operators in secondary emirates lacking inspection transparency and brand recognition. Long-term viability across the analysis window favors curriculum-specialized holding companies with demonstrated ADEK or KHDA rating achievement and scalable technology infrastructure. Acquisition targets should demonstrate operational compliance with MOHAP health standards and MOE licensing frameworks. The signal to watch is regulatory acceleration in federal curriculum mandates that would compress accreditation timelines and strain undercapitalized competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Adaptive Learning Platform Integration | Standardizes learning outcomes across GEMS Education and Taaleem Holdings multi-campus networks. |
| KHDA Outstanding Rating Pursuit | Unlocks 15-20% tuition premiums for Dubai British curriculum institutions. |
| Mid-Range Fee Tier Expansion | Addresses 40,000+ unmet student seats in Sharjah and Ras Al Khaimah corridors. |
| Captive Real Estate Development | Neutralizes lease premium volatility consuming 25-35% of operating budgets. |
| Blended Learning Methodology Deployment | Reduces per-student physical space requirements in high-rent Dubai districts. |
Research Methodology
Coverage spans Dubai, Abu Dhabi, Sharjah, and Ras Al Khaimah, with primary inputs from each emirate's regulatory environment and competitive landscape. Primary interviews combined school operators, curriculum accreditation specialists, and real estate development executives with secondary validation from KHDA inspection reports, ADEK quality assurance publications, and Ministry of Education licensing records. Bottom-up enrollment data triangulated against top-down tuition revenue estimates across premium, mid-range, and economy fee tiers.
Rate-of-change decomposition anchored the analytical framework, segmenting growth drivers by curriculum type, teaching methodology, and emirate-specific regulatory intensity across the projection horizon. Segmentation dimensions modeled include curriculum accreditation tier, grade level band, tuition fee positioning, and teaching methodology integration depth. CAGRs derived from enrollment elasticity to expatriate population flows, facility capacity expansion timelines, and inspection rating distribution shifts. Forecast inputs incorporated teacher supply pipeline constraints from UK, Ireland, and South Africa recruitment corridors.
Underlying measurement precision varies by segment; Dubai KHDA-rated institutions carry tighter precision than Sharjah uninspected alternatives due to published performance indicators. Forecasts reflect assumptions about regulatory enforcement consistency, expatriate employment stability, and technology adoption curves. Practitioners should monitor federal curriculum localization mandate implementation pace and teacher visa processing efficiency for early signals of operational constraint or competitive release.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
Oman Private K-12 Market