
 Saudi Arabia Private K12 Education Market | 2026-2036
Saudi Arabia Private K12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
Saudi Arabia Private K12 Education Market Foresight
Adaptive learning platforms powered by AI-driven assessment engines are reshaping instructional delivery across Saudi private K12 institutions. GEMS Education leverages its transnational curriculum architecture to sustain premium positioning in Riyadh and Jeddah. Ataa Educational Company anchors its expansion through backward integration into teacher training and content development. Ma'arif for Education & Training differentiates via its focus on national curriculum modernization aligned with Vision 2030 objectives.
Saudi Arabia Private K12 Education encompasses fee-based primary and secondary schooling serving students from preschool through grade twelve, typically operating under Ministry of Education oversight with curricula spanning British, American, IB, and national standards. These institutions function as regulated alternatives to public education, delivering instruction through physical campuses, blended modalities, or digitally enhanced classrooms designed to prepare students for university admission and workforce entry. International schools command the dominant share of fee revenue, reflecting sustained preference among expatriate professionals and globally oriented Saudi families for credentials transferable to overseas higher education. The British Curriculum segment leads in enrollment velocity within premium tiers, while National Curriculum schools capture expanding mid-range demand as localization policies strengthen domestic workforce pipelines.
SFDA oversight of student health services, Ministry of Education licensing requirements, and SASO building safety standards collectively shape facility investment cycles and operational compliance costs for private operators. The National Transformation Program's education privatization targets create direct procurement opportunities for established chains while raising barriers for unaccredited entrants. Stakeholders must monitor how curriculum localization mandates and teacher Saudization quotas reshape competitive positioning between international and national school models.
Market Dynamics
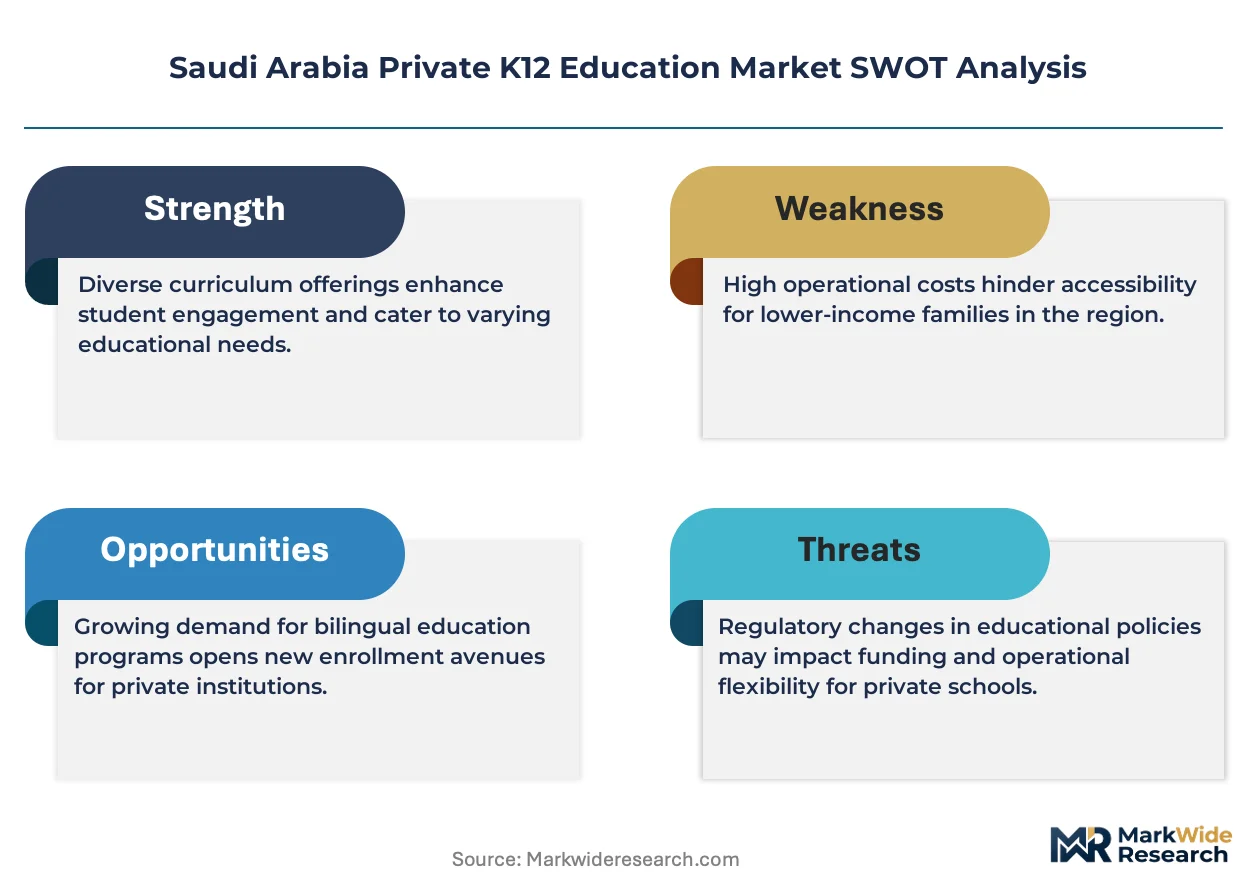
SFDA health service mandates and Ministry of Education licensing reforms are compressing facility investment cycles while accelerating digital infrastructure deployment across Saudi private K12 campuses.
Growth Catalysts
- Vision 2030 Localization:National curriculum modernization policies are expanding domestic workforce pipelines and elevating demand for Arabic-English bilingual instruction models.
- Expatriate Professional Influx:Corporate and diplomatic communities in Riyadh and Jeddah are sustaining enrollment velocity in British and American curriculum schools.
- AI-Driven Assessment Engines:Adaptive learning platforms are enabling personalized instruction pathways and reducing teacher-student ratio constraints in premium tier institutions.
Market Restraints
- Teacher Saudization Quotas:Ministry of Human Resources mandates are constraining availability of internationally certified educators for specialized STEM and IB programs.
- SFDA Facility Compliance:Student health service infrastructure requirements are elevating capital expenditure thresholds for new campus approvals.
- Real Estate Concentration:Premium land scarcity in Riyadh's northern corridor and Jeddah's Al Hamra district is inflating site acquisition costs for tier-one operators.
Strategic Opportunities
- Eastern Province Expansion:Dammam and Khobar corporate zones present underdeveloped demand for international curricula serving Aramco and petrochemical sector families.
- Blended Learning Convergence:Integration of physical campuses with cloud-based learning management systems is opening mid-market segments previously inaccessible to premium operators.
- National Transformation Program Procurement:Government privatization targets for 50% private sector participation in education delivery are creating direct contract opportunities for accredited chains.
Industry Challenges
- Digital Pedagogy Certification:Teacher training programs lag behind Ministry of Education mandates for technology-integrated classroom competencies.
- Curriculum Localization Complexity:Reconciling international accreditation standards with Saudi cultural content requirements is extending program development timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Saudi Arabia Private K12 Education Market |
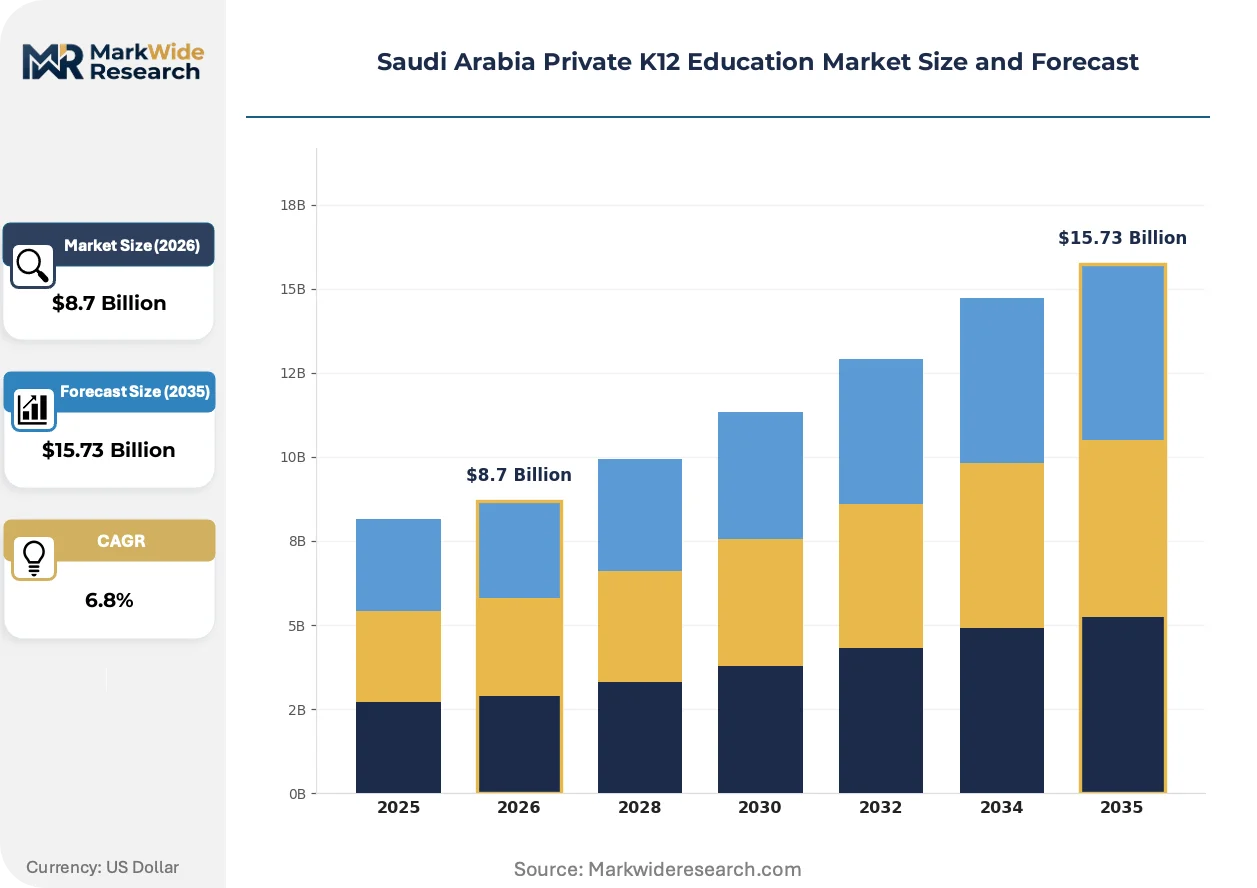
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.73 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | School Type: International Schools, National Schools, Bilingual Schools, Montessori Schools Curriculum: British Curriculum, American Curriculum, IB Curriculum, National Curriculum Student Age Group: Preschool, Primary, Secondary, High School Tuition Fee Range: Low-Cost, Mid-Range, High-End, Premium |
| Companies Covered | Ataa Educational Company, Ma'arif for Education & Training, GEMS Education, Al-Khaleej Training & Education, Al-Rowad International Schools, British International School of Jeddah, Kingdom Schools, American International School, Spark Education Platform, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Saudi Arabia Private K12 Education Market Shifts & Advancements
Instructional delivery models are fragmenting across physical, blended, and fully digital modalities while regulatory frameworks accelerate standardization of health and safety infrastructure.
Learning management infrastructure is migrating from on-premise server installations to cloud-native platforms with embedded analytics. Premium tier schools in Riyadh and Jeddah are adopting these systems at accelerated pace to support hybrid attendance models. This migration from capital-intensive hardware to subscription-based software is compressing upfront technology investment and shifting operational expenditure profiles.
SFDA oversight of campus health services is mandating on-site nursing stations, automated external defibrillator deployment, and mental health counseling access. These requirements are elevating facility design standards and operational staffing ratios. International curriculum schools are responding fastest by integrating wellness architecture into new construction plans.
Parental evaluation criteria are pivoting from brand prestige metrics toward measurable graduate outcome data including university placement rates and standardized test performance. This behavioral shift is pressuring established operators to publish transparent accountability metrics. The phenomenon is most visible in Jeddah's Al Rawdah district where new entrants are capturing share through outcome-based marketing.
Saudi Arabia Private K12 Education Market Segmentation
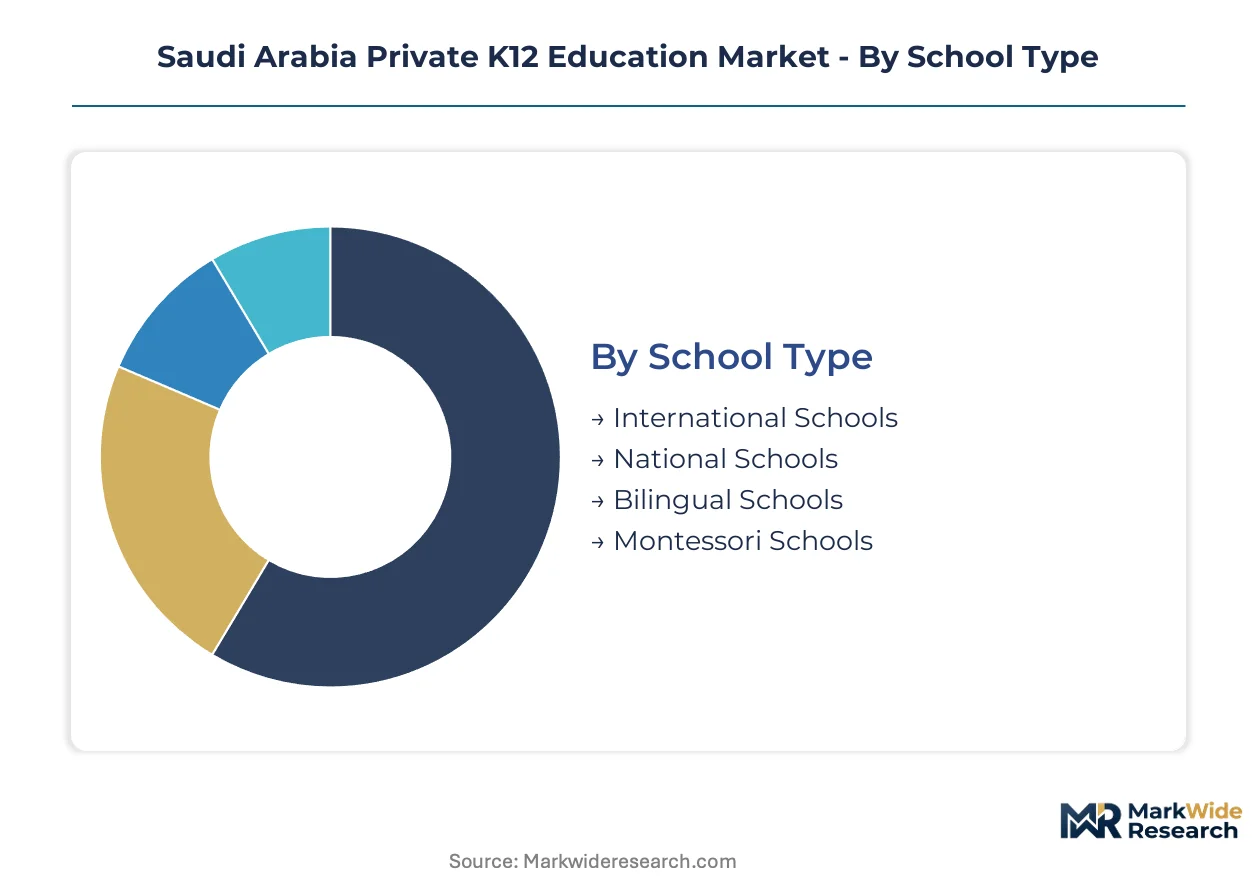
School operators in Saudi Arabia segment their offerings across four critical dimensions: institutional model, instructional framework, student developmental stage, and fee accessibility. These divisions determine capital deployment patterns, regulatory compliance pathways, and competitive positioning within Riyadh and Jeddah's concentrated demand clusters.
School Type:
After-sales service intensity varies dramatically across institutional models, with international schools demanding continuous curriculum updates and accreditation maintenance while national schools require deeper government liaison support.
- International Schools:These institutions deliver foreign-accredited programs under British, American, or IB frameworks, requiring sustained investment in overseas curriculum licensing and expatriate teacher recruitment. Demand concentrates in Riyadh's northern corridor and Jeddah's Al Hamra district, where corporate and diplomatic families prioritize credentials transferable to overseas universities.
- National Schools:Operators here align strictly with Ministry of Education standards, emphasizing Arabic-medium instruction and Islamic studies integration. Ataa Educational Company and Ma'arif for Education & Training dominate this segment, capitalizing on Vision 2030 localization mandates that strengthen domestic workforce pipelines.
- Bilingual Schools:Hybrid models combine national curriculum core requirements with English-intensive STEM and humanities tracks, appealing to Saudi families seeking overseas university readiness without full international school fees.
- Montessori Schools:Child-centered pedagogical approaches emphasizing self-directed learning and mixed-age classrooms attract affluent early-education households in Riyadh's premium residential zones.
International Schools hold the largest share; momentum sits with Bilingual Schools as localization policies reshape family preferences.
Curriculum:
Cost tier differentiation separates these four frameworks, with British and IB programs commanding the highest per-student revenue while National Curriculum operations optimize for volume and government procurement eligibility.
- British Curriculum:IGCSE and A-Level pathways dominate premium tier enrollment velocity, particularly among expatriate professionals from Commonwealth nations. GEMS Education leverages its transnational architecture to sustain positioning in this segment across Riyadh and Jeddah.
- American Curriculum:Advanced Placement and SAT-aligned programs attract families targeting North American higher education destinations, with demand clustering around Aramco and petrochemical corporate compounds in the Eastern Province.
- IB Curriculum:Full Diploma Programme authorization requires substantial upfront investment in teacher certification and facility standards, limiting authorized providers to a handful of established operators.
- National Curriculum:Modernization aligned with Vision 2030 objectives is elevating this segment's perceived quality, particularly as university admissions officers recognize strengthened domestic standards.
British Curriculum captures the steepest expansion trajectory in fee revenue; National Curriculum is gaining share fastest as localization strengthens.
Student Age Group:
Application-based segmentation reveals divergent operational models, with early childhood requiring specialized facilities and high school demanding career counseling and university placement infrastructure.
- Preschool:Nursery and kindergarten operations emphasize sensory-motor development spaces and heightened staff-to-student ratios, with SFDA health service mandates elevating facility design standards.
- Primary:Foundational literacy and numeracy instruction in grades one through five represents the highest enrollment volume tier, particularly for National Curriculum operators building student pipelines.
- Secondary:Grades six through nine introduce subject specialization and external examination preparation, driving demand for science laboratories and technology-integrated classrooms.
- High School:Terminal grades ten through twelve concentrate university placement outcomes and standardized test performance, with parental evaluation criteria pivoting toward measurable graduate data.
Primary holds the largest share; momentum sits with High School as outcome transparency pressures reshape competitive positioning.
Tuition Fee Range:
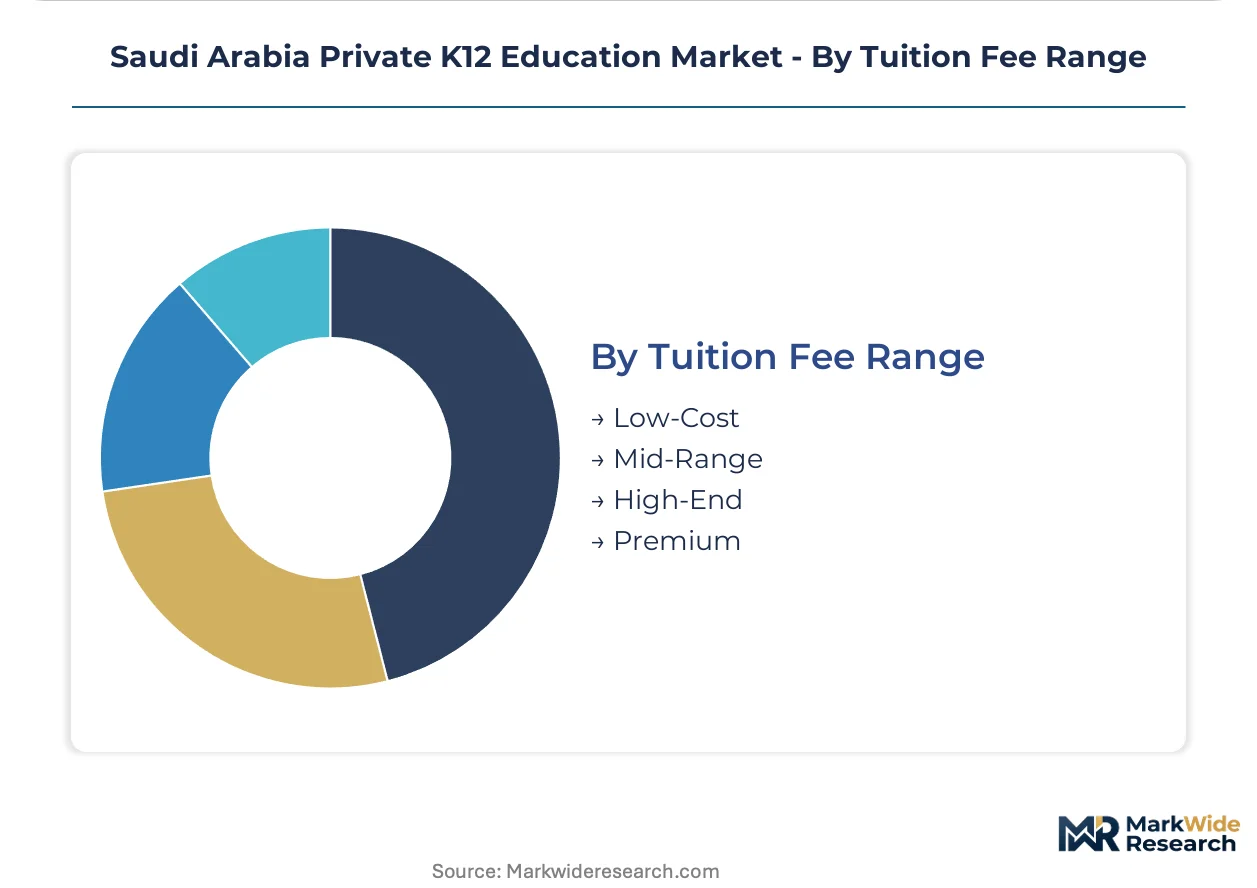
Customer type stratification creates distinct operational archetypes, from low-cost volume operators serving price-sensitive Saudi families to premium institutions capturing expatriate corporate allowances.
- Low-Cost:Streamlined facilities and Saudi-national teaching staff enable accessible pricing for middle-income families, though teacher Saudization quotas constrain specialized program availability.
- Mid-Range:This expanding segment blends national curriculum foundations with selective international programming, capturing families seeking value-engineered bilingual pathways.
- High-End:Comprehensive extracurricular offerings, advanced placement tracks, and dedicated university counseling justify elevated fees in Riyadh and Jeddah's competitive premium clusters.
- Premium:Ultra-low student-teacher ratios, bespoke facilities, and exclusive accreditation partnerships serve diplomatic and C-suite executive families with unrestricted education budgets.
Mid-Range holds the largest share; momentum sits with Premium as corporate and diplomatic communities expand in Riyadh and Jeddah.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Saudi Arabia's private K12 education sector operates as a net importer of curriculum frameworks and pedagogical expertise, with British, American, and IB accreditation systems requiring ongoing licensing fees and foreign teacher recruitment. Domestic operators balance this dependency through backward integration into Arabic content development and national curriculum modernization aligned with Vision 2030 workforce objectives.
Riyadh
Corporate headquarters relocation and diplomatic community expansion are concentrating premium international school demand in Riyadh's northern corridor. Ministry of Education licensing reforms require new campuses to demonstrate SFDA-compliant health infrastructure before approval. The King Abdullah Financial District and Diplomatic Quarter host the densest clusters of British and American curriculum institutions serving expatriate professionals.
Eastern Province
Aramco and petrochemical sector families are generating underdeveloped demand for international curricula in Dammam and Khobar. The National Transformation Program's privatization targets are creating direct procurement opportunities for accredited operators willing to establish presence outside traditional demand centers. Dhahran's corporate compounds represent the most concentrated addressable market for American curriculum expansion.
Western Region
Jeddah's Al Hamra and Al Rawdah districts anchor the kingdom's most competitive premium school clusters, where outcome-based marketing is displacing brand prestige as the primary parental selection criterion. SASO building safety standards and SFDA health mandates are elevating facility investment thresholds for new entrants. The city's proximity to Mecca sustains consistent demand from religious tourism sector families.
NEOM Northwest
The giga-project's planned residential communities are projected to generate demand for innovative schooling models blending international accreditation with sustainability-focused campus design. Regulatory frameworks for NEOM remain under development, creating uncertainty around Ministry of Education oversight scope and curriculum localization requirements. Early-phase international school operators are positioning for preferred vendor status through memoranda of understanding with project developers.
Saudi Arabia Private K12 Education Market Competitive Landscape
On the supply side, the industry is bifurcating between established multi-campus chains with transnational curriculum licensing and emerging national operators leveraging Vision 2030 localization mandates. Three strategic archetypes dominate: international curriculum specialists maintaining premium positioning through expatriate teacher recruitment, national curriculum modernizers capturing mid-range demand through bilingual programming, and hybrid operators blending physical campuses with cloud-based delivery infrastructure. Competitive intensity concentrates on accreditation maintenance, teacher retention, and outcome transparency metrics rather than price competition.
Within the international curriculum tier, GEMS Education exemplifies transnational architecture deployment, while Ataa Educational Company anchors national curriculum expansion through backward integration into teacher training and content development. Ma'arif for Education & Training occupies a distinct position aligning institutional growth with Vision 2030 workforce pipeline objectives. These operators represent contrasting strategic responses to Ministry of Education licensing reforms and SFDA facility compliance requirements.
| Leading Market Players |
|---|
| Ataa Educational Company |
| Ma'arif for Education & Training |
| GEMS Education |
| Al-Khaleej Training & Education |
| Al-Rowad International Schools |
| British International School of Jeddah |
| Kingdom Schools |
| American International School |
| Spark Education Platform |
| Others |
Supply & Pricing Matrix
SFDA facility compliance mandates act as a regulatory chokepoint that compresses capital deployment timelines while simultaneously widening spreads between premium and mid-tier tuition bands. This single-source dependency on Ministry of Education licensing approvals forces operators to front-load infrastructure investment before revenue recognition, reshaping supply chain priorities toward health service equipment and digital learning platforms rather than traditional classroom construction.
Pricing Analysis
The generational technology gap separating cloud-native learning management systems from legacy on-premise installations drives fee stratification across the Saudi private K12 sector. Three-tier pricing structure across premium, standard, and economy levels reflects after-sales service intensity and accreditation maintenance costs rather than pure instructional quality. Price differentiation hinges on IB or British curriculum licensing fees and expatriate teacher recruitment premiums. Cost compression in the mid-range tier intensifies as bilingual operators capture families seeking international pathways without premium fees. Corporate and diplomatic households show least price sensitivity, while middle-income Saudi families concentrate in economy tiers constrained by teacher Saudization quotas.
Supply Chain Analysis
Export-control restrictions on educational technology hardware from the United States and European Union limit flows of AI-driven assessment engines and adaptive learning platforms into Saudi campuses. Curriculum licensing draws from the United Kingdom, United States, and Switzerland for IB authorization, while physical infrastructure components source from China, Turkey, and the UAE. Single-source vulnerability concentrates in British and IB curriculum providers, where accreditation renewal cycles create dependency on foreign examination boards. Distribution runs through direct procurement relationships between school operators and transnational education service providers, bypassing traditional wholesale channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Saudi private K12 sector operates as a defensive-moat market where Ministry of Education licensing entrenchment creates substantial switching costs for families and high barriers for unaccredited competitors.
For Market Incumbents: Pre-empt emerging bilingual operators by securing exclusive IB or British curriculum partnerships in Riyadh's northern corridor before localization policies fully mature. Deepen backward integration into teacher training academies to offset Saudization quota constraints on STEM and specialized program delivery. Channel control through direct corporate relationships with Aramco and petrochemical sector employers protects against mid-range price erosion. For New Entrants and Emerging Players: Eastern Province corporate zones around Dammam and Khobar present the most penetrable geography for American curriculum expansion, with Aramco compound demand currently underserved relative to Riyadh and Jeddah saturation. Cloud-based learning management system partnerships enable asset-light entry into mid-market segments previously inaccessible to capital-intensive campus operators. White-space capture depends on outcome-based marketing transparency rather than brand prestige investment. For Investors and Strategic Acquirers: National curriculum modernizers with established Ministry of Education procurement relationships represent the most defensible acquisition archetype for long-term positioning through the Vision 2030 implementation window. Monitor teacher Saudization quota enforcement intensity as the primary inflection signal for international curriculum viability versus bilingual model economics.| Strategic Initiative | Industry Significance |
|---|---|
| SFDA Health Infrastructure Pre-Certification | Accelerates Ministry of Education licensing timelines by demonstrating compliance before formal submission. |
| Backward Integration into Teacher Training | Captures margin from expatriate recruitment agencies while meeting Saudization mandates. |
| Cloud-Native Learning Management Deployment | Shifts capital expenditure to operational models accessible to mid-market family segments. |
| Corporate Partnership Direct Procurement | Bypasses competitive enrollment cycles through Aramco and diplomatic sector block contracts. |
| Outcome Transparency Platform Development | Publishes university placement metrics to capture share from prestige-dependent competitors in Jeddah. |
Research Methodology
Desk research of Ministry of Education licensing databases, SFDA facility compliance filings, and curriculum accreditation records preceded structured interviews with school operations directors, education technology procurement officers, and corporate HR managers responsible for expatriate family relocation. Primary fieldwork with Riyadh and Jeddah campus administrators combined with secondary validation against National Transformation Program privatization targets and Vision 2030 workforce pipeline reports. Bottom-up enrollment modeling and top-down addressable market sizing triangulated through cross-reference with hyperscaler cloud education platform deployment disclosures.
Assumptions held fixed include Ministry of Education regulatory enforcement intensity and SFDA health mandate scope, while curriculum localization policy pace and teacher Saudization quota thresholds varied across sensitivity scenarios. The analytical framework segmented by school type, curriculum framework, student age group, and tuition tier across the analysis window. CAGRs derived from enrollment velocity trends, fee escalation patterns, and capacity expansion pipelines. Forecast inputs incorporated expatriate professional influx projections from corporate relocation announcements and diplomatic community expansion timelines.
Macroeconomic conditions sit as an overlay; deviation in oil revenue allocation to education privatization or expatriate visa policy would shift the trajectory. Material shifts in IB or British curriculum licensing costs or Ministry of Education localization mandate enforcement would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
In-Person Learning Market