
 North America K12 Education Market | 2026-2036
North America K12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
North America K12 Education Market Analytics
Curriculum-aligned digital content tiers is rotating the North America K12 Education Market toward outcome-based procurement models. Pearson plc leverages its assessment infrastructure to dominate state-level testing contracts. McGraw-Hill Education anchors its position through curriculum development partnerships with large urban districts. Cengage Group specializes in career and technical education pathways that sustain premium pricing in secondary markets.
North America K12 Education comprises structured instructional delivery systems serving students from kindergarten through twelfth grade, integrating physical textbooks, software-based learning environments, and administrative management platforms with specifications tied to state academic standards and federal accessibility requirements. The primary commercial purpose centers on equipping school systems with scalable content and operational tools that improve measurable student achievement while reducing per-pupil administrative overhead. E-Learning Solutions and Assessment Tools capture expanding margin pools as districts prioritize data-driven instruction and remote readiness. Blended Learning delivery modes lead structural growth by combining in-person supervision with digital flexibility, while In-Person Classes retain volume dominance in rural and under-connected communities.
The U.S. Department of Education enforces ESSA accountability frameworks that shape district purchasing priorities toward evidence-backed interventions, while the FCC's E-Rate program subsidizes broadband infrastructure that determines market access for online and hybrid providers. State education agencies across the region layer additional procurement standards that filter vendor eligibility. Stakeholders must monitor how evolving federal special-education funding formulas and state textbook adoption cycles redistribute contract opportunities across delivery modes and service types.
Market Dynamics
ESSA accountability mandates are compressing district purchasing cycles toward evidence-validated interventions, forcing vendors to restructure sales approaches around measurable learning outcomes rather than content volume.
Growth Catalysts
- FCC E-Rate subsidies:Federal broadband infrastructure funding expands district connectivity budgets, enabling blended learning platform adoption in previously bandwidth-constrained rural counties across the United States.
- Charter school enrollment concentration:Texas and Florida corridors generate disproportionate procurement volume as autonomous school networks bypass traditional textbook adoption cycles for agile digital content licensing.
- Career and technical education pathways:State workforce development mandates in secondary schools sustain premium pricing for competency-based credentialing systems aligned with regional labor market needs.
Market Restraints
- Special-education compliance fragmentation:IDEA funding formula variations across state agencies create procurement friction for unified platform solutions requiring localized IEP management modules.
- Rural connectivity infrastructure gaps:Last-mile broadband deployment lags in Appalachian and Great Plains sub-regions, capping addressable market for cloud-dependent assessment tools.
- Legacy LMS integration debt:Decades-old student information systems in large urban districts impose technical barriers requiring costly middleware development for seamless data interoperability.
Strategic Opportunities
- Underconnected Canadian provinces:Northern Ontario and Prairie regions present whitespace for satellite-enabled blended learning solutions as federal connectivity investments lag U.S. E-Rate scale.
- AI-driven formative assessment:Real-time learning analytics convergence with natural language processing creates new product category between summative testing and classroom instruction.
- State-level microcredential marketplaces:Emerging competency-based credit transfer systems in California and New York enable platform vendors to capture recurring transaction fees from stackable certification pathways.
Industry Challenges
- Instructional designer talent scarcity:Specialized workforce combining pedagogy expertise with UX development capability commands premium compensation, constraining vendor scaling velocity.
- Multi-state certification timelines:Individual state education agency approval processes for digital content extend sales cycles by 18-24 months, delaying revenue recognition.
- Data privacy compliance layering:CCPA in California, PIPEDA in Canada, and emerging state student privacy laws create fragmented legal engineering requirements for cross-border platform deployments.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America K12 Education Market |
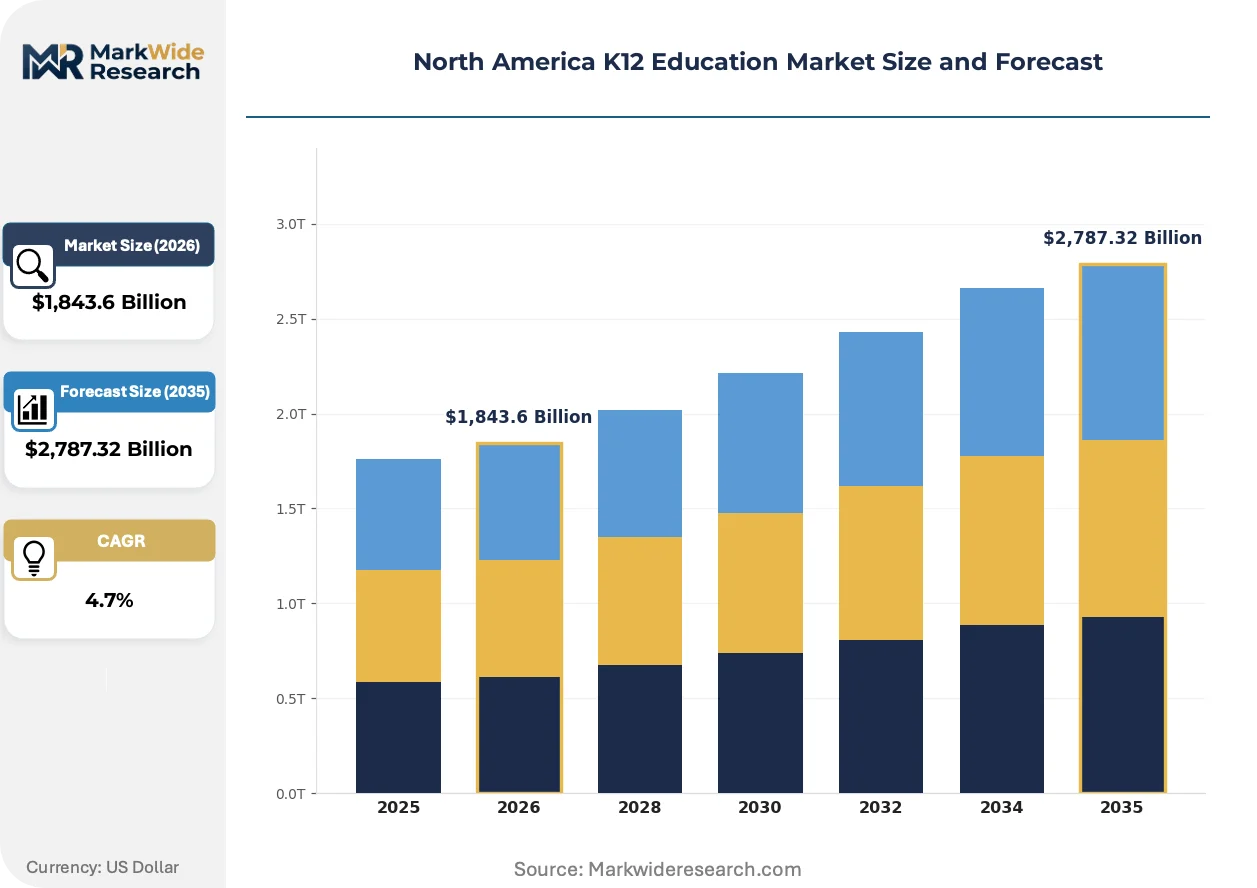
| Market Size in 2026 | $1,843.6 Billion |
| Market Size in 2035 | $2,787.32 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textbooks, E-Learning Solutions, Mobile Applications, Assessment Tools End User: Students, Teachers, Administrators, Parents Delivery Mode: Online Learning, Blended Learning, In-Person Classes, Hybrid Models Service Type: Consulting Services, Technical Support, Training Programs, Curriculum Development |
| Companies Covered | Pearson plc, McGraw-Hill Education, Cengage Group, Stride Inc., Houghton Mifflin Harcourt, Graham Holdings Company, Discovery Education, Oracle Corp, Smart Technologies, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America K12 Education Market Evolving Landscape
Adaptive learning engines are compressing the boundary between curriculum delivery and real-time assessment, forcing traditional content publishers to rearchitect product roadmaps around continuous evaluation loops rather than static textbook releases.
Embedded formative assessment technology is miniaturizing. These systems ingest student response patterns during routine digital coursework to generate immediate instructional adjustments without separate testing events. Large suburban districts in Georgia and North Carolina are deploying these tools district-wide after pilot programs demonstrated measurable gains on state accountability metrics. The technology is miniaturizing the traditional assessment calendar, compressing summative testing windows and reallocating instructional time toward intervention blocks.
The U.S. Department of Education's ESSA evidence tiers are tightening procurement eligibility. Districts now require vendors to demonstrate statistically significant effect sizes from randomized controlled trials or quasi-experimental designs before contract award. This policy shift most acutely affects supplemental intervention providers serving Title I schools, who must invest in third-party efficacy studies or risk disqualification from RFP shortlists. Vendors are responding by embedding research partnerships directly into product development cycles.
District buying committees are consolidating vendor relationships around integrated platform suites. Previously fragmented procurement of separate LMS, assessment, and content licenses is yielding to unified enterprise agreements with single accountability for student outcome metrics. This concentration is most visible in Texas and Florida metropolitan areas where procurement authority has centralized at district-level rather than school-level. Smaller point-solution vendors face channel compression as incumbent platform providers bundle competing functionality at marginal cost.
North America K12 Education Market Segmentation
North American K12 procurement patterns diverge sharply across product formats, user roles, and service delivery methods. District-level purchasing authority and state funding mechanisms reshape how vendors must configure their go-to-market approaches for each segment cluster.
Product Type:
Domestic demand concentrates in curriculum-aligned formats, while cross-border licensing from Canadian publishers supplies supplemental niches in northern U.S. markets.
- Textbooks:Print and digital basal curricula remain the procurement anchor for large urban districts in Texas and California, where state adoption cycles lock in multi-year purchasing commitments. Physical textbook volume is compressing in the U.S. Southeast as charter networks bypass traditional adoption frameworks.
- E-Learning Solutions:Cloud-hosted learning management platforms integrate assessment, content, and analytics into unified architectures. ESSA evidence-tier requirements are filtering vendor eligibility for Title I intervention funding in Florida and Georgia districts.
- Mobile Applications:Supplementary skill-building tools target parent-funded acquisition in suburban markets.
- Assessment Tools:State testing contracts and formative analytics platforms serve district accountability mandates.
Textbooks hold the largest share; momentum sits with E-Learning Solutions.
End User:
Procurement authority and budget control vary dramatically across user categories, reshaping sales cycle complexity and contract structure.
- Students:Direct consumption of core instructional materials and adaptive practice platforms. Texas and Florida districts are expanding 1:1 device programs that bundle student-facing software licenses into hardware refresh cycles.
- Teachers:Classroom management tools, lesson planning resources, and professional development content. Ontario school boards prioritize French-language instructional supports that U.S. vendors must localize for Canadian procurement.
- Administrators:District-wide SIS integration and compliance reporting systems.
- Parents:Supplemental tutoring subscriptions and college readiness tools.
Administrators command the largest procurement budgets; parent-funded segments are climbing the fastest.
Delivery Mode:
Connectivity infrastructure and state policy frameworks determine which delivery formats achieve viable scale in specific geographies.
- Online Learning:Fully remote instruction depends on broadband penetration that FCC E-Rate subsidies have expanded in rural counties. Appalachian districts remain constrained by last-mile gaps that cap platform adoption.
- Blended Learning:Rotation and flex models combine in-person supervision with digital coursework. Georgia and North Carolina suburban districts are deploying these formats district-wide after pilot programs demonstrated accountability metric gains.
- In-Person Classes:Traditional delivery retains volume dominance where bandwidth constraints or special-education requirements limit digital substitution.
- Hybrid Models:Synchronous remote options layered onto physical classroom infrastructure.
In-Person Classes retain the largest footprint; Blended Learning shows the steepest expansion trajectory.
Service Type:
Revenue stability and margin profiles diverge between project-based consulting and recurring support contracts.
- Consulting Services:District transformation advisory and curriculum audit engagements. Large urban districts in California and New York procure these services through RFP processes that extend sales cycles.
- Technical Support:Help desk and platform maintenance contracts generate recurring revenue streams. Canadian Prairie provinces present whitespace for satellite-enabled support infrastructure as federal connectivity investments lag U.S. scale.
- Training Programs:Professional development and platform certification for district staff.
- Curriculum Development:Custom content creation aligned to state standards.
Technical Support commands the most predictable revenue; Consulting Services deliver the highest per-contract value.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The United States runs a substantial education technology trade surplus with Canada, while Mexico remains a net importer of K12 digital infrastructure. Cross-border procurement flows concentrate in curriculum licensing and platform development services.
United States
Texas and Florida charter networks drive disproportionate procurement volume through autonomous purchasing authority. FCC E-Rate subsidies expand broadband budgets for rural districts in Appalachian and Great Plains sub-regions. Georgia suburban districts deploy blended learning district-wide after pilot programs demonstrated accountability metric gains.
Canada
Ontario school boards prioritize French-language instructional supports requiring vendor localization. Federal connectivity investments lag U.S. E-Rate scale, creating whitespace for satellite-enabled solutions in Northern Ontario and Prairie regions. Provincial procurement standards filter vendor eligibility differently than state-level U.S. frameworks.
Mexico
Secretaría de Educación Pública mandates reshape procurement priorities toward digital infrastructure in urban corridors. State-level textbook adoption cycles in Mexico City and Nuevo León generate concentrated demand for bilingual curriculum materials. Northern border states leverage cross-border partnerships for technical training program development.
North America K12 Education Market Competitive Landscape
Listed leaders compete with private specialists across platform integration capabilities, creating a tiered structure where scale advantages concentrate in assessment infrastructure and curriculum development. The vendor base separates into three archetypes: diversified publishers with testing assets, specialized career-and-technical pathway providers, and integrated learning management platforms. Consolidation pressure intensifies as district buying committees favor unified enterprise agreements over fragmented point solutions. Dominant competitive moves include curriculum audit partnerships and state-level certification timeline acceleration.
Within the diversified publisher tier, Pearson plc and McGraw-Hill Education occupy positions anchored by assessment infrastructure and urban district partnerships respectively. Cengage Group exemplifies the specialized pathway archetype through its focus on secondary career and technical education markets. These three entities represent distinct strategic postures: one leveraging testing contracts, one anchoring through curriculum co-development, and one sustaining premium pricing in workforce-aligned credentialing systems.
| Leading Market Players |
|---|
| Pearson plc |
| McGraw-Hill Education |
| Cengage Group |
| Stride Inc. |
| Houghton Mifflin Harcourt |
| Graham Holdings Company |
| Discovery Education |
| Oracle Corp |
| Smart Technologies |
| Others |
Value Network & Pricing Analysis
Ninety-day content development cycles for curriculum-aligned digital platforms concentrate supplier leverage with established publishers possessing state-level certification infrastructure, compressing margin pools for smaller vendors lacking assessment-integrated product architectures. District procurement committees exploit this concentration by demanding outcome-based pricing tied to measurable student achievement gains, shifting contract value from perpetual licensing toward performance-contingent fee structures.
Pricing Analysis
Large urban district buyers anchor North America K12 Education pricing through enterprise-wide platform negotiations that bundle content, assessment, and professional development into multi-year agreements. Three-tier pricing structure across premium, standard, and economy levels stratifies by ESSA evidence-tier certification, with Tier 1 efficacy validation commanding substantial premiums over quasi-experimental support claims. Cost compression in supplemental intervention tiers is intensifying because Title I funding accountability requires third-party efficacy studies that smaller vendors cannot finance. Charter school networks exhibit lowest price sensitivity due to autonomous procurement authority bypassing traditional adoption cycles, while rural districts dependent on E-Rate subsidies demonstrate highest sensitivity to per-pupil licensing costs.
Supply Chain Analysis
Ninety-day content development cycles compress vendor response times for state textbook adoption deadlines, forcing publishers to maintain dedicated curriculum teams in Texas, California, and Florida. Digital platform development draws from cloud infrastructure concentrated in U.S. data centers, instructional design talent pools in metropolitan corridors, and assessment psychometric expertise anchored in established testing organizations. Single-source vulnerability sits with specialized formative assessment engine providers lacking redundant development capacity. Distribution runs through direct district sales forces for large urban contracts, supplemented by regional education service agencies serving smaller districts with aggregated procurement and implementation support.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement fragmentation across fifty U.S. state frameworks and thirteen Canadian provincial systems creates multiple entry niches for specialized vendors, as ESSA evidence-tier requirements and localized accessibility mandates prevent platform standardization.
For Market Incumbents: Fortify assessment-integrated platform positions by embedding AI-driven formative analytics that compress the boundary between curriculum delivery and real-time evaluation, neutralizing point-solution competitors. Accelerate state-level certification timeline investments to capture charter school procurement in Texas and Florida corridors before emerging learning management platforms achieve multi-state approval. Vertical integration into professional development delivery captures recurring revenue streams that pure content licensing cannot match. For New Entrants and Emerging Players: Lead with satellite-enabled blended learning solutions targeting Northern Ontario and Prairie regions where federal connectivity investments lag U.S. E-Rate scale, exploiting whitespace created by infrastructure gaps. Prioritize competency-based microcredential marketplaces in California and New York where emerging credit transfer systems enable platform vendors to capture recurring transaction fees. Deploy direct-to-district sales models bypassing traditional education service agency intermediaries that incumbent publishers control. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified media conglomerates seeking to divest non-core education assets amid district buying committee consolidation around unified enterprise agreements. Position holdings for sustained viability through the ESSA reauthorization horizon by prioritizing vendors with demonstrated Tier 1 efficacy validation and established state testing contracts. Monitor FCC E-Rate funding allocation patterns as the critical inflection signal for rural district digital infrastructure investment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Assessment Infrastructure Integration | Pearson plc leverages state testing contracts to anchor curriculum platform adoption across large urban districts. |
| Career Pathway Certification Development | Cengage Group captures premium pricing through workforce-aligned credentialing systems in secondary markets. |
| Charter Network Direct Licensing | Stride Inc. bypasses traditional adoption cycles through autonomous procurement authority in Texas and Florida. |
| AI-Driven Formative Analytics | Discovery Education compresses summative testing windows by embedding real-time instructional adjustment engines. |
| Satellite-Enabled Rural Connectivity | Smart Technologies addresses last-mile gaps in Appalachian and Canadian Prairie sub-regions through blended delivery infrastructure. |
Research Methodology
Operator-level perspectives from district curriculum directors, state education agency procurement officers, charter school network administrators, and instructional technology coordinators anchored the qualitative base for this analysis. Primary fieldwork combined structured interviews with secondary validation against FCC E-Rate disbursement records, state textbook adoption calendars, ESSA evidence-tier registries, and district bond referendum disclosures. Bottom-up segment sizing triangulated against top-down education expenditure forecasts from federal and provincial statistical agencies.
Sensitivity analysis frameworks tested demand projections across multiple connectivity investment scenarios and policy continuity assumptions. Segmentation modeling incorporated product format, end-user role, delivery mode, and service type dimensions alongside state-level regulatory cluster variations. CAGRs were derived from enrollment trend extrapolation, per-pupil expenditure elasticity estimates, and technology substitution rate assumptions calibrated to pilot program outcome data.
Forecasts assume regulatory continuity in ESSA accountability frameworks and FCC E-Rate subsidy structures; material policy shifts would require re-modeling procurement incentive structures and district technology refresh cycles. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
K-12 Education Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Asia-Pacific School Furniture Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market