
 K-12 Education Market | 2026-2036
K-12 Education Market Size, Share, and Industry Trends Forecast 2026-2036
K-12 Education Market Outlook
Teacher digital literacy gaps in emerging economies is reorganizing how curriculum publishers allocate training resources and platform support. Pearson plc leverages its institutional relationships across Commonwealth education systems to sustain print-to-digital transitions. McGraw-Hill Education anchors K-12 assessment markets through its established state testing contracts in the United States. TAL Education Group dominates after-school tutoring ecosystems through localized content adaptation and live-streamed instruction models.
K-12 education encompasses structured primary and secondary learning systems serving students from approximately ages five through eighteen, incorporating standardized curricula, credentialed instruction, and compulsory attendance frameworks governed by national or subnational authorities. E-Learning Platforms now integrate adaptive algorithms, real-time progress dashboards, and API interoperability with student information systems to deliver personalized pacing and automated competency tracking. Textbooks retain durable revenue pools in lower-connectivity regions, while Educational Software captures expanding budgets as districts prioritize formative assessment automation and learning analytics dashboards. The Hybrid delivery model is gaining structural traction as infrastructure investments enable synchronous remote supplementation of traditional classroom hours.
India's Central Board of Secondary Education mandates digital literacy integration across affiliated institutions, while the country's PLI scheme incentivizes domestic manufacturing of educational hardware. The EU AI Act imposes risk-classification requirements on automated grading and student monitoring tools sold into European member states. GDPR data-localization provisions constrain how US-based platforms process European student records, creating compliance costs that reshape vendor competitive dynamics. Stakeholders must monitor evolving national curriculum standardization efforts and procurement centralization trends to anticipate which delivery models and content formats will secure long-term institutional commitments.
Market Dynamics
Public procurement centralization in India and the EU AI Act's risk-classification mandates are compressing vendor margins while forcing platform redesigns around automated grading and student data governance.
Growth Catalysts
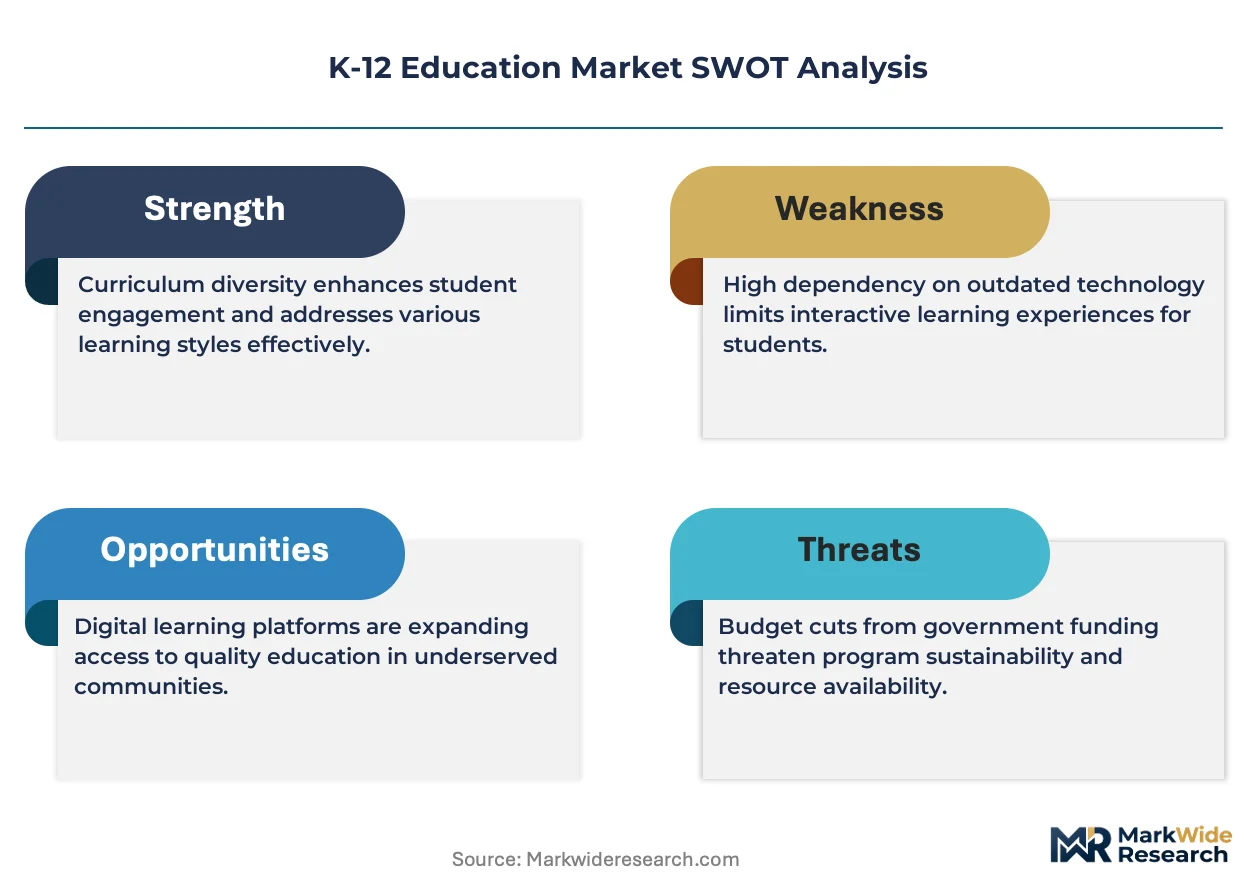
- India's PLI scheme:Domestic manufacturing incentives for educational tablets expand hardware affordability across government-funded smart classroom initiatives.
- Adaptive learning algorithms:Real-time competency tracking and personalized pacing engines pull district technology budgets toward software subscriptions.
- EU AI Act:Automated grading tools face mandatory risk-classification requirements that accelerate compliance-oriented platform upgrades.
Market Restraints
- GDPR data-localization:European student record processing constraints raise operational costs for US-based platform providers.
- Teacher digital literacy gaps:Emerging economy educators require intensive training before curriculum publishers can realize software adoption targets.
- Textbook revenue durability:Lower-connectivity regions sustain print demand that fragments procurement budgets away from digital infrastructure.
Strategic Opportunities
- Rural India enrollment expansion:Low-cost tablet distribution programs penetrate previously unreachable student populations.
- Hybrid delivery models:Synchronous remote supplementation of classroom hours creates new platform categories between pure software and hardware.
- API interoperability standards:Student information system integration requirements open vendor ecosystems to modular assessment tool providers.
Industry Challenges
- Curriculum standardization fragmentation:National and subnational authorities maintain divergent content requirements that complicate cross-border platform scaling.
- Assessment contract lock-in:Established state testing relationships in the United States create high switching costs for new formative automation entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | K-12 Education Market |
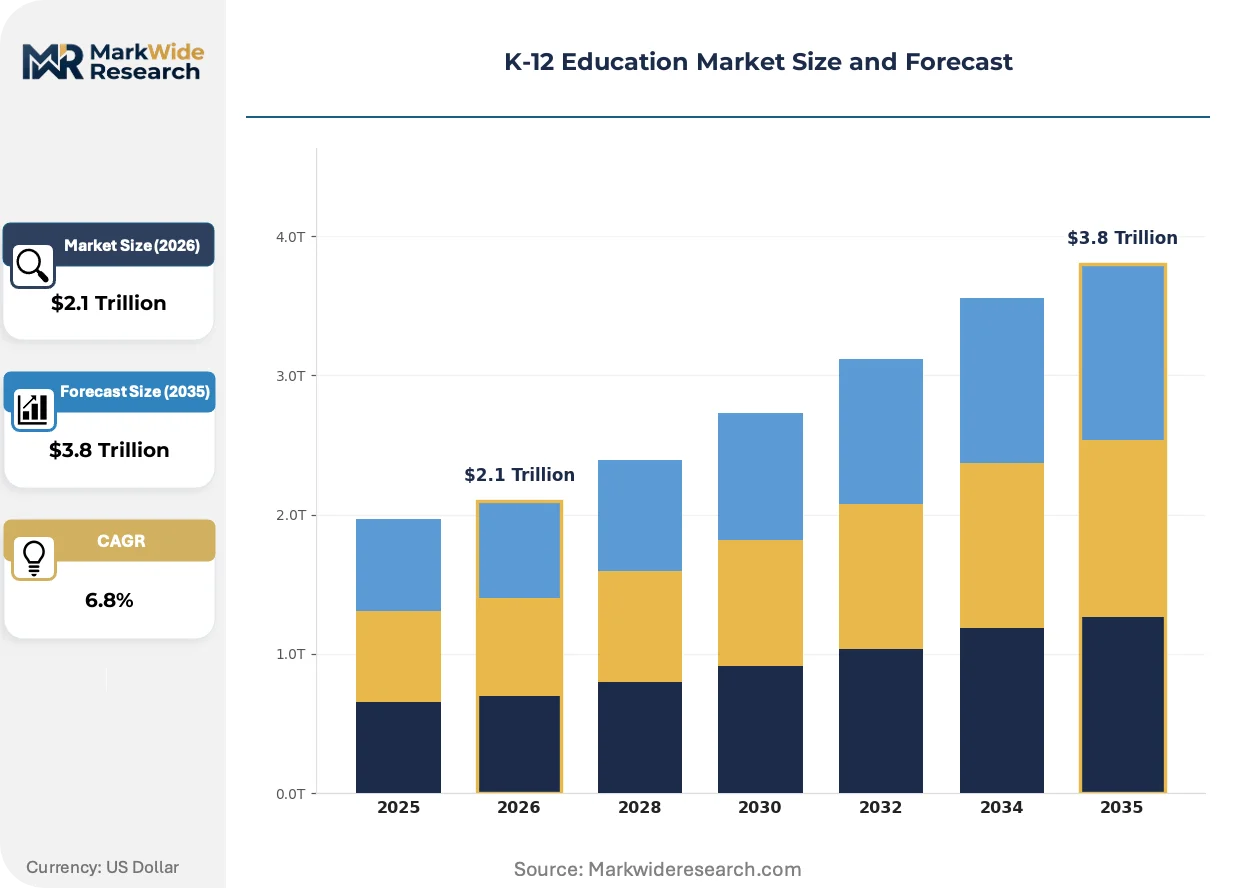
| Market Size in 2026 | $2.1 Trillion |
| Market Size in 2035 | $3.8 Trillion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Textbooks, E-Learning Platforms, Classroom Supplies, Educational Software Delivery Model: In-Person, Online, Hybrid, Blended End User: Students, Teachers, Administrators, Parents Custom Solution: Curriculum Development, Student Assessment Tools, Learning Analytics, Tutoring Services |
| Companies Covered | Pearson plc, McGraw-Hill Education, Cengage Group, Stride Inc., TAL Education Group, PowerSchool Group, Microsoft, Follett School Solutions, BYJU'S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
K-12 Education Market Strategic Shifts
Adaptive algorithm deployment is decomposing traditional classroom pacing structures while regulatory pressure on automated student monitoring forces architectural redesigns of learning analytics systems.
Generative AI tutoring engines are decomposing the one-to-many instruction model by enabling real-time, personalized feedback loops. Suburban US districts with fiber infrastructure are piloting these tools for mathematics remediation. The technology is decomposing after-school tutoring economics by collapsing geographic access barriers that previously favored urban concentration.
The EU AI Act imposes strict transparency obligations on automated grading systems deployed in European member states. Edtech vendors must now document algorithmic decision logic and maintain human-in-the-loop review protocols. French and German education ministries are requiring platform providers to submit conformity assessments before procurement eligibility.
District purchasing committees now demand outcome-linked pricing where software fees tie to measurable literacy gains rather than seat licenses. This unbundling of subscription models pressures vendors to demonstrate efficacy through standardized assessment data. The shift is most pronounced in US states with centralized procurement offices and publicly reported achievement metrics.
K-12 Education Market Segmentation
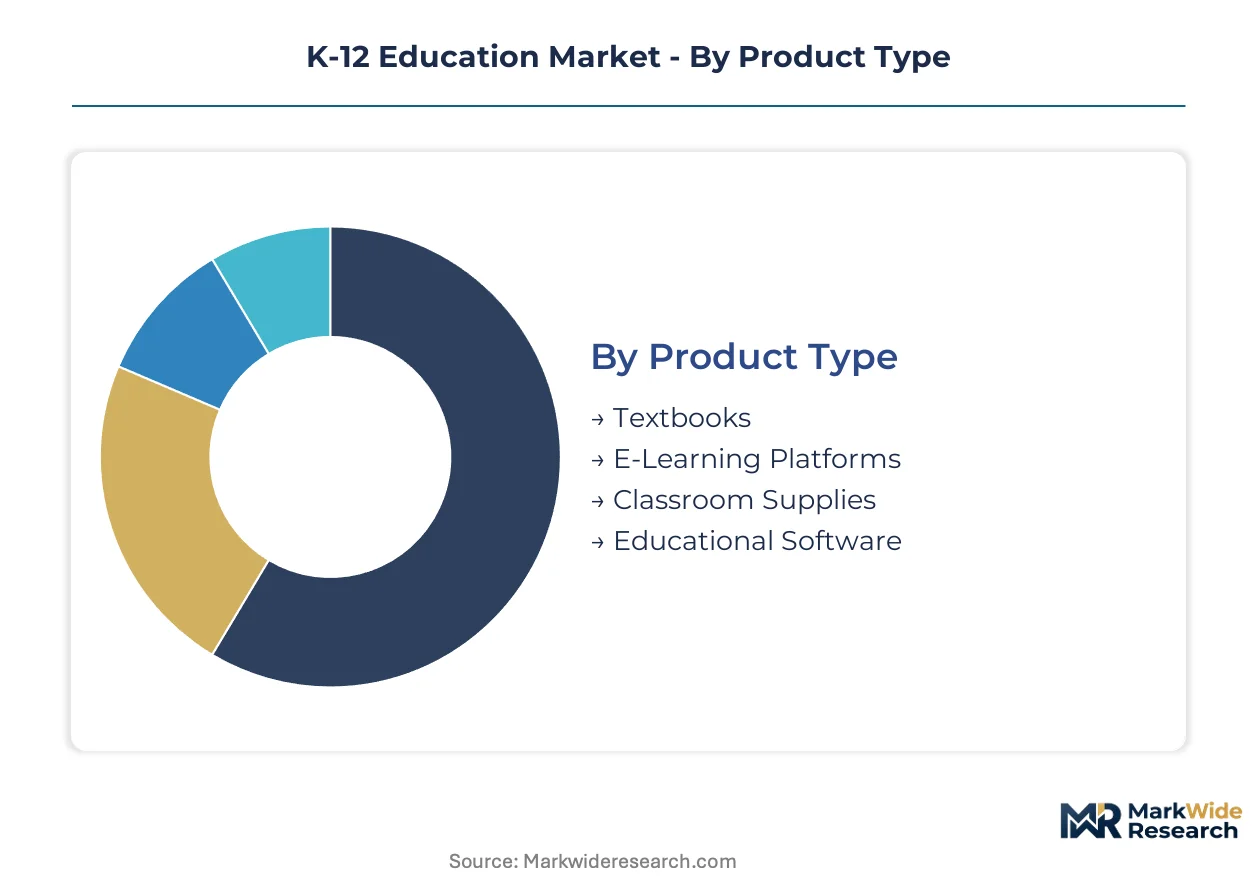
Segmentation in K-12 education reveals how procurement budgets fragment across legacy formats and emerging delivery modes. District purchasing committees weight interoperability requirements differently depending on whether investments target core instruction, administrative efficiency, or supplemental support services.
Product Type:
Channel mix varies sharply: textbooks flow through state-approved vendor lists, while educational software and e-learning platforms route through district technology offices with API compliance requirements.
- Textbooks:Print and digital formats bound to state curriculum standards. Demand concentrates in lower-connectivity Indian states and rural US districts where procurement committees prioritize durability over interactivity.
- E-Learning Platforms:Cloud-hosted environments with adaptive algorithms and real-time dashboards. Indian smart classroom initiatives and EU AI Act compliance requirements are pulling investment toward GDPR-aligned architectures with human-in-the-loop review protocols.
- Classroom Supplies:Physical materials from whiteboards to science kits. Procurement runs through centralized purchasing cooperatives in US suburban districts.
- Educational Software:Formative assessment automation and learning analytics tools. Districts with fiber infrastructure and standardized achievement metrics are adopting outcome-linked pricing models tied to measurable literacy gains.
Textbooks dominate installed base across emerging economies. E-learning platforms are where expansion concentrates as infrastructure investments enable synchronous remote supplementation.
Delivery Model:
Cost tier stratification separates premium fiber-enabled synchronous platforms from economy asynchronous modules, with hybrid models capturing mid-budget allocations.
- In-Person:Traditional classroom hours with credentialed instructors. Remains the default in regions with unreliable connectivity and where teacher unions resist automation.
- Online:Fully remote instruction via live-streamed or asynchronous content. TAL Education Group's localized adaptation models in China demonstrate how geographic access barriers collapse when broadband penetration reaches threshold levels.
- Hybrid:Scheduled remote supplementation of physical classroom hours. US suburban districts pilot these configurations for mathematics remediation using generative AI tutoring engines.
- Blended:Integrated rotation models where students alternate between digital self-pacing and face-to-face instruction. Requires substantial teacher training investments that fragment adoption timelines in emerging economies.
In-person delivery retains the largest enrollment footprint. Hybrid configurations are climbing the fastest as procurement offices seek flexibility without full infrastructure replacement.
End User:
Application focus shifts procurement authority: student-facing tools require parent consent frameworks, while administrator-facing systems prioritize student information system integration.
- Students:Primary beneficiaries of adaptive pacing and competency tracking. India's low-cost tablet distribution programs target this segment in previously unreachable rural populations.
- Teachers:Digital literacy gaps in this cohort reorganize how curriculum publishers allocate training resources before software adoption targets become achievable.
- Administrators:Procurement decision-makers evaluating outcome-linked pricing and API interoperability requirements for district-wide platform consolidation.
- Parents:Emerging gatekeepers for student data permissions under GDPR and emerging US state privacy laws.
Student-facing tools command the largest absolute spending. Teacher enablement represents the steepest expansion trajectory as publishers recognize adoption bottlenecks.
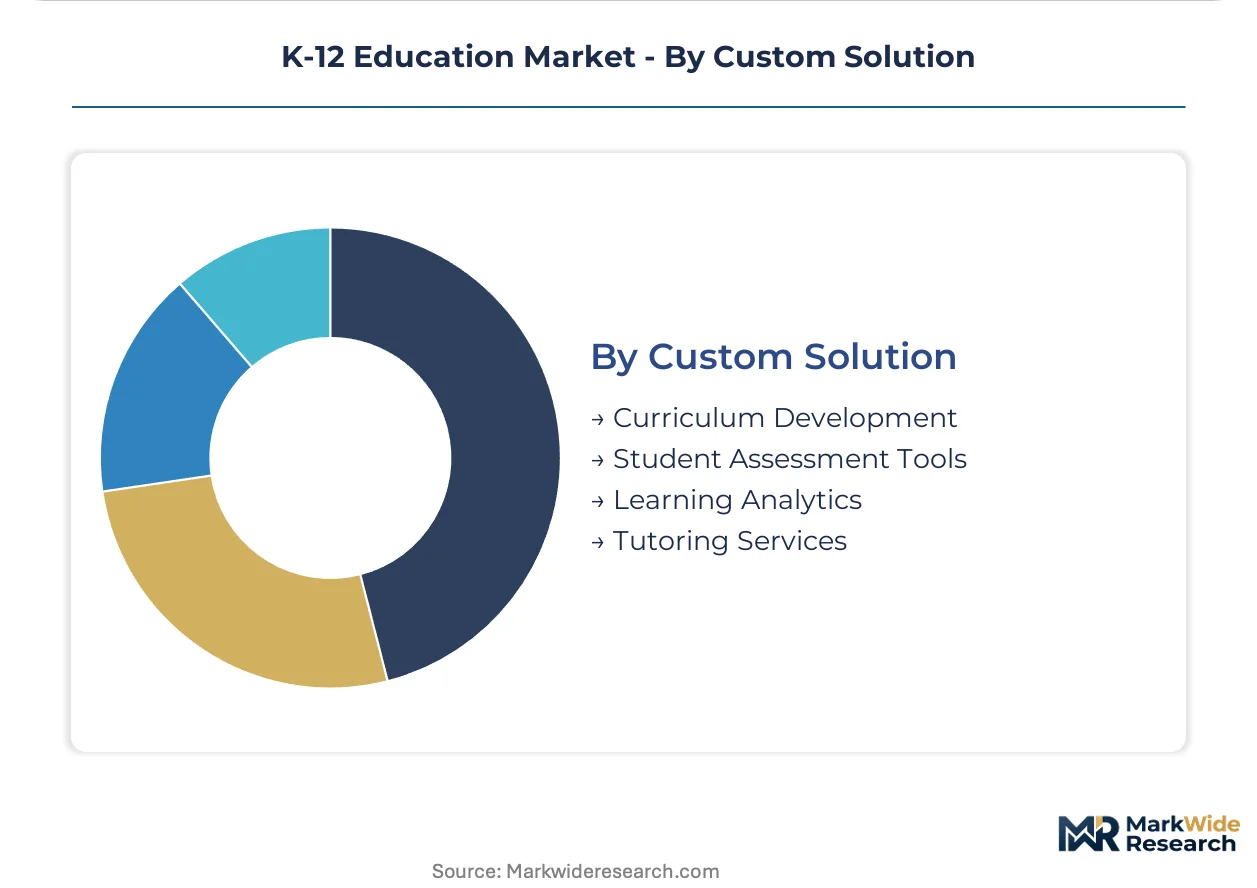
Custom Solution:
Margin structure favors high-touch services over standardized products, with curriculum development and tutoring services capturing premium pricing from affluent districts and after-school markets.
- Curriculum Development:Bespoke content aligned to national or subnational standards. Fragmentation across India's Central Board of Secondary Education, US state standards, and EU national curricula complicates cross-border scaling.
- Student Assessment Tools:Automated grading and formative feedback systems. EU AI Act risk-classification mandates and French conformity assessment requirements are reshaping vendor competitive dynamics in European markets.
- Learning Analytics:Dashboards aggregating student progress data. GDPR data-localization provisions constrain how US-based platforms process European records.
- Tutoring Services:Live instruction models delivered in-person or via streaming. After-school economics are decomposing as generative AI collapses geographic access barriers that previously favored urban concentration.
Curriculum development holds the deepest incumbent relationships. Tutoring services are gaining share fastest as supplemental education demand outpaces formal system capacity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India deploys low-cost tablets for mass enrollment expansion while the United States concentrates spending on assessment automation and hybrid infrastructure, revealing a stark consumption-mix differential between emerging economy hardware-first strategies and developed market software prioritization.
United States
Suburban districts with fiber infrastructure are piloting generative AI tutoring engines for mathematics remediation. State procurement offices with centralized purchasing authority are mandating outcome-linked pricing where software fees tie to measurable literacy gains. Greater Boston and the Pacific Northwest host edtech clusters where formative assessment vendors compete for district technology budgets.
India
The Central Board of Secondary Education mandates digital literacy integration across affiliated institutions while PLI scheme incentives expand domestic tablet manufacturing. Government-funded smart classroom initiatives and low-cost tablet distribution programs penetrate previously unreachable rural populations in Maharashtra and Karnataka. Telangana's technology corridor anchors vendor ecosystems serving state-level procurement centralization.
Germany
The EU AI Act imposes strict transparency obligations on automated grading systems deployed in German education ministries. KBA and federal education authorities require platform providers to submit conformity assessments before procurement eligibility. Berlin-Brandenburg and Bavaria concentrate edtech development clusters navigating GDPR data-localization constraints on student record processing.
United Kingdom
Pearson plc leverages institutional relationships across Commonwealth education systems to sustain print-to-digital transitions. GDPR compliance requirements reshape how edtech vendors design data governance for student information systems. London and the Southeast anchor curriculum development specialists serving both domestic and export markets.
China
TAL Education Group dominates after-school tutoring ecosystems through localized content adaptation and live-streamed instruction models. MIIT standards and national curriculum frameworks govern platform interoperability requirements. The Yangtze River Delta and Pearl River Delta clusters concentrate tutoring service providers collapsing geographic access barriers through broadband-enabled synchronous delivery.
K-12 Education Market Competitive Environment
A small set of integrated leaders sits above a broader specialist tier, with curriculum publishers and assessment platforms occupying distinct competitive spaces. The market structure fragments across legacy print-to-digital transition specialists, cloud-native platform providers, and regional tutoring service operators. Three archetypes dominate: established publishers with institutional procurement relationships, technology-native platforms with API-first architectures, and localized service providers with live-streaming capabilities. Competitive moves concentrate on strategic partnerships for student information system integration and portfolio diversification into adjacent assessment automation.
Within the established publisher tier, Pearson plc and McGraw-Hill Education exemplify archetypes anchored by state testing contracts and Commonwealth institutional relationships. TAL Education Group occupies a position representing the localized service provider model, with its China-based structure demonstrating how geographic concentration enables live-streamed instruction scale. These three entities illustrate how vendor competitive dynamics split between legacy relationship maintenance and technology-native platform development.
| Leading Market Players |
|---|
| Pearson plc |
| McGraw-Hill Education |
| Cengage Group |
| Stride Inc. |
| TAL Education Group |
| PowerSchool Group |
| Microsoft |
| Follett School Solutions |
| BYJU'S |
| Others |
Value Chain & Pricing Dynamics
Tablet manufacturing scale economies in India and China compress per-unit hardware costs while expanding procurement volumes across government-funded smart classroom initiatives. This concentration of production capacity in Asia anchors price floors for educational hardware and creates tiered software pricing structures that stratify by connectivity infrastructure and institutional purchasing power.
Pricing Analysis
Contract-based long-term offtake agreements dominate procurement for large-scale tablet deployments under India's PLI scheme, while SaaS-tiered subscriptions capture district technology budgets for adaptive learning platforms. Price differentiation hinges on API interoperability certification and state testing contract eligibility, with premium tiers commanding fees tied to measurable literacy outcomes. Cost compression in hardware procurement intensifies as domestic manufacturing incentives expand supply capacity. Rural districts with limited fiber infrastructure exhibit highest price sensitivity, whereas suburban US districts with centralized purchasing offices prioritize efficacy-linked pricing over per-seat costs.
Supply Chain Analysis
China and India anchor educational tablet manufacturing through PLI scheme incentives and established electronics assembly ecosystems. Component sourcing draws from Taiwanese semiconductor fabs for processing chips, Korean display manufacturers for LCD panels, and domestic battery cell production. Single-source vulnerability concentrates in advanced processor supply where geopolitical export controls disrupt procurement timelines. Distribution runs through state-approved vendor lists for textbooks, district technology offices for software licensing, and centralized purchasing cooperatives for classroom supplies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Service-attach opportunities in teacher training and platform support expand faster than hardware margins as digital literacy gaps in emerging economies prolong software adoption timelines. Recurring revenue from outcome-linked pricing models and API integration services now outpaces one-time device sales in procurement priority.
For Market Incumbents: Secure state testing contract renewals through conformity assessment investments aligned with EU AI Act risk-classification mandates. Deepen vertical integration into curriculum development capabilities to defend against cloud-native platform entrants displacing legacy print-to-digital transitions. Channel control through student information system integration partnerships remains critical for procurement committee influence. For New Entrants and Emerging Players: Anchor in rural Indian districts where low-cost tablet distribution programs penetrate previously unreachable enrollment populations. Target hybrid delivery model configurations in US suburban districts piloting generative AI tutoring engines for mathematics remediation. API-first architectures with modular assessment tool positioning offer the most penetrable go-to-market angle against established platform incumbents. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors curriculum publishers with institutional procurement relationships and compliance-ready GDPR architectures over hardware-dependent vendors. Long-term viability over the projection horizon rests on adaptive algorithm capabilities and human-in-the-loop review protocol integration. Monitor EU AI Act enforcement patterns and French conformity assessment timelines as inflection indicators for vendor competitive dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | API interoperability with student information systems opens vendor ecosystems to modular assessment providers. |
| Strategic Partnership | State procurement office relationships secure outcome-linked pricing contracts tied to literacy metrics. |
| Geographic Expansion | Rural India enrollment penetration leverages PLI scheme hardware affordability and government-funded initiatives. |
| Product Launch | GDPR-aligned e-learning architectures capture EU AI Act compliance-driven procurement upgrades. |
| Acquisition of Specialist Firm | Formative assessment automation capabilities consolidate district technology budgets around analytics dashboards. |
Study Parameters
Initial hypotheses were tested against primary input from district technology officers, curriculum development directors, state procurement managers, and edtech platform engineers and refined through secondary validation. Primary interviews captured procurement decision-making processes, software adoption barriers, and compliance investment patterns. Secondary sources encompassed SEC filings from listed education publishers, EU regulatory filings under GDPR and the AI Act, Indian government procurement databases tracking PLI scheme utilization, and state education budget disclosures. Bottom-up enrollment projections and top-down technology spending forecasts were triangulated against vendor revenue segmentation.
Variance decomposition across product type, delivery model, end user, and geographic adoption pattern shaped the analytical framework over the projection horizon. CAGRs were derived from enrollment expansion trajectories, per-student technology spending trends, and procurement centralization shifts. Modeled inputs included fiber infrastructure penetration rates, teacher digital literacy training completion metrics, and regulatory compliance cost burdens by jurisdiction.
Material uncertainties — curriculum standardization fragmentation, assessment contract lock-in durability, and geopolitical semiconductor export restrictions — sit outside the modeled envelope. Forecasts reflect documented assumptions about infrastructure investment continuity and regulatory enforcement timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Primary and Secondary Education
Europe K12 Education Market
Primary and Secondary Education
GCC Private K12 Education Market
Primary and Secondary Education
UAE Private K12 Education Market
Primary and Secondary Education
Back to School Market
Primary and Secondary Education
Oman Private K12 Education Market
Primary and Secondary Education
Oman Private K-12 Market
Primary and Secondary Education
Qatar Private K12 Education Market
Primary and Secondary Education
In-Person Learning Market
Primary and Secondary Education
Saudi Arabia Private K12 Education Market
Primary and Secondary Education
North America K-12 Furniture Market
Primary and Secondary Education
North America K12 Education Market
Primary and Secondary Education
Asia-Pacific School Furniture Market