
 Low Calorie Olive Oil Market | 2026-2036
Low Calorie Olive Oil Market Size, Share, and Industry Trends Forecast 2026-2036
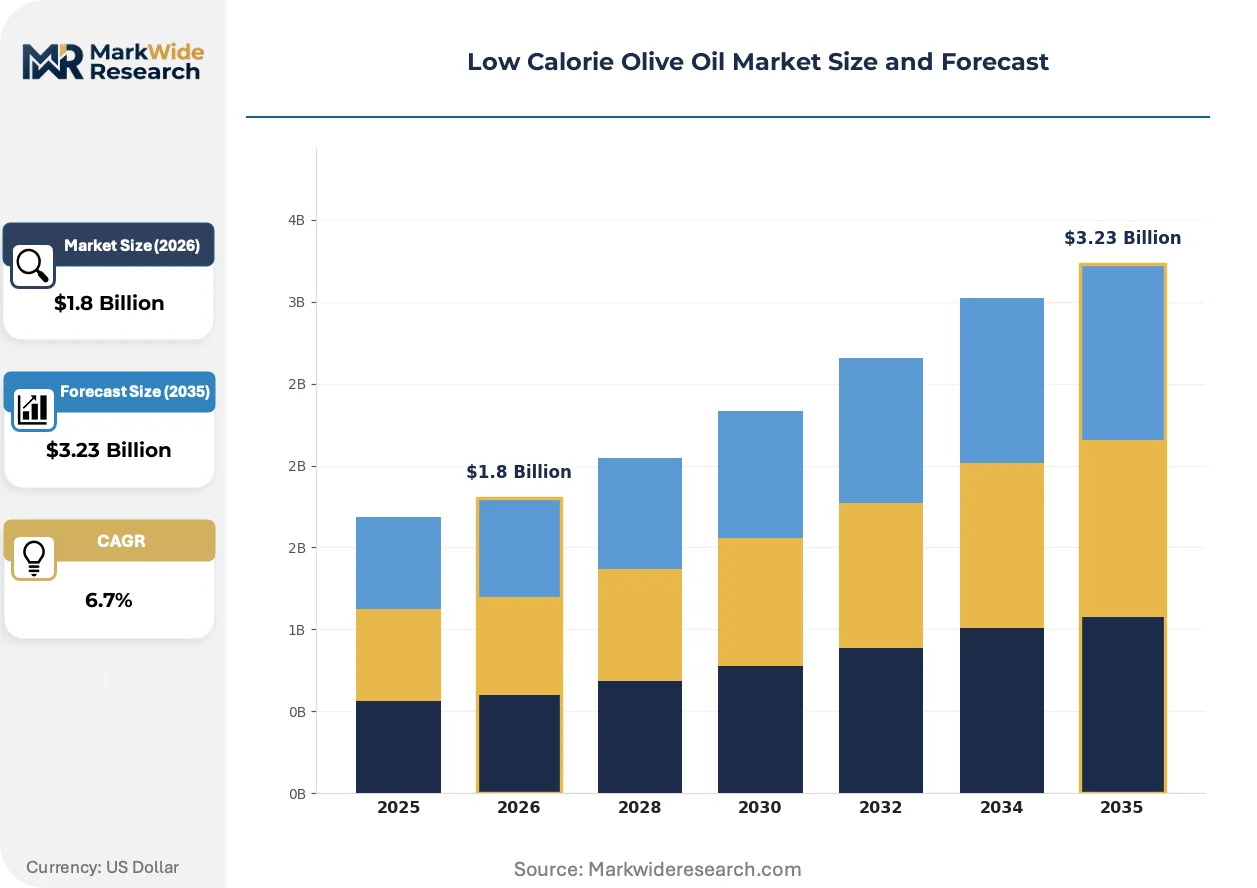
Low Calorie Olive Oil Market Analytics
The food services vertical is broadening its share of low calorie olive oil procurement as restaurants reformulate menus to meet wellness-oriented dining trends. Sovena leverages integrated crushing and bottling assets across Iberia to sustain cost discipline in private-label supply. Deoleo S.A. anchors European retail shelf presence through multi-brand architecture spanning premium and everyday tiers. Borges International Group competes on Mediterranean origin certification, while California Olive Ranch dominates North American extra virgin positioning with estate-controlled orchards.
Low calorie olive oil denotes olive oil formulations processed to reduce energy density per serving while retaining monounsaturated fat profiles and smoke-point stability for cooking applications. Cold-pressed extraction at temperatures below 27 degrees Celsius preserves polyphenol content, a functional parameter that distinguishes premium grades from solvent-refined alternatives. Extra virgin variants command the deepest margin pools due to organoleptic certification requirements and limited geographic yield. E-commerce distribution registers the fastest structural expansion as direct-to-pantry subscription models displace traditional wholesale intermediation. Pouch packaging remains nascent but attracts sustainability-focused buyers seeking reduced freight intensity versus glass bottles.
EU REACH frameworks govern extraction solvent residues in imported olive oils, while FDA nutrition fact panel rules in the United States mandate calorie disclosure precision that shapes label claim permissibility. EFSA health claim evaluations for olive oil polyphenols create divergent marketing latitude between European and American jurisdictions. Stakeholders must monitor evolving front-of-pack labeling mandates across their priority markets to anticipate reformulation investment cycles and certification renewal timelines.
Market Dynamics
EU nutrition labeling mandates are tightening disclosure requirements for food service operators, forcing rapid menu reformulation and procurement switches toward verified low-calorie olive oil grades.
Growth Catalysts
- REACH solvent residue thresholds:ECHA enforcement on extraction purity is filtering out unrefined imports and elevating certified cold-pressed grades in European retail channels.
- Food service wellness menus:Mediterranean restaurant chains are mandating reduced-calorie oil specifications to align with front-of-pack calorie transparency rules.
- California cold-pressed clusters:Estate-controlled orchards in the Sacramento Valley are setting import-parity quality benchmarks that reshape North American buyer expectations.
Market Restraints
- Input cost volatility:Harvest yield fluctuations in Andalusia concentrate supply risk and compress margin predictability for bulk purchasers.
- Technical smoke-point limitations:Reduced-calorie formulations sacrifice thermal stability versus standard extra virgin grades, restricting high-heat cooking applications.
- Substitution threat from avocado oil:Neutral-flavor alternatives with comparable monounsaturated profiles capture price-sensitive segments in North American retail.
Strategic Opportunities
- Direct-to-pantry subscriptions:E-commerce platforms are bypassing wholesale intermediation to capture recurring household revenue with traceable origin storytelling.
- Pouch packaging innovation:Flexible film formats reduce freight intensity versus glass and attract sustainability-focused food service buyers in Nordic markets.
- EFSA polyphenol health claims:Approved cardiovascular benefit language creates marketing latitude for premium European brands that American competitors cannot replicate under FDA rules.
Industry Challenges
- Certification timeline compression:Organic and extra virgin audit cycles strain quality control staffing at mid-scale crushing facilities.
- Cold chain reconfiguration:Polyphenol-preserving storage requirements demand capital investment in temperature-controlled logistics that legacy distributors lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Low Calorie Olive Oil Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $3.23 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Extra Virgin, Pure, Light, Blend Packaging Type: Bottle, Jar, Pouch, Can End User: Household, Restaurants, Food Services, Catering Distribution Channel: Retail, E-commerce, Wholesale, Direct Sales |
| Companies Covered | Sovena, Deoleo S.A., Borges International Group, Salov S.p.A., Cargill, California Olive Ranch, Pompeian, Del Monte Foods, Catania Oils, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Low Calorie Olive Oil Market Evolving Landscape
Extraction technology and packaging format innovation are compressing traditional quality hierarchies while regulatory disclosure rules reshape how calorie claims reach end consumers.
Cold-pressed extraction below 27 degrees Celsius is consolidating quality differentiation in premium tiers. Food service procurement teams in Spain and Italy are specifying temperature-verified crushing protocols in supply contracts. This technical specification is consolidating market share among producers with integrated crushing and bottling assets versus toll-processing competitors.
EFSA health claim evaluations for olive oil polyphenols are tightening the gap between European and American marketing permissions. Approved cardiovascular benefit language in the EU creates regulatory arbitrage that American brands cannot exploit under FDA nutrition fact panel constraints. Premium European labels are leveraging this divergence to defend shelf positioning in domestic retail while export-oriented producers face claim standardization costs.
Subscription-based replenishment models are displacing conventional wholesale distribution for household buyers. Direct-to-pantry platforms in California and New York are capturing recurring revenue with harvest-dated origin transparency that supermarket private labels cannot match. This channel shift is most visible among urban millennial households seeking traceability verification beyond bottle labeling.
Low Calorie Olive Oil Market Segmentation
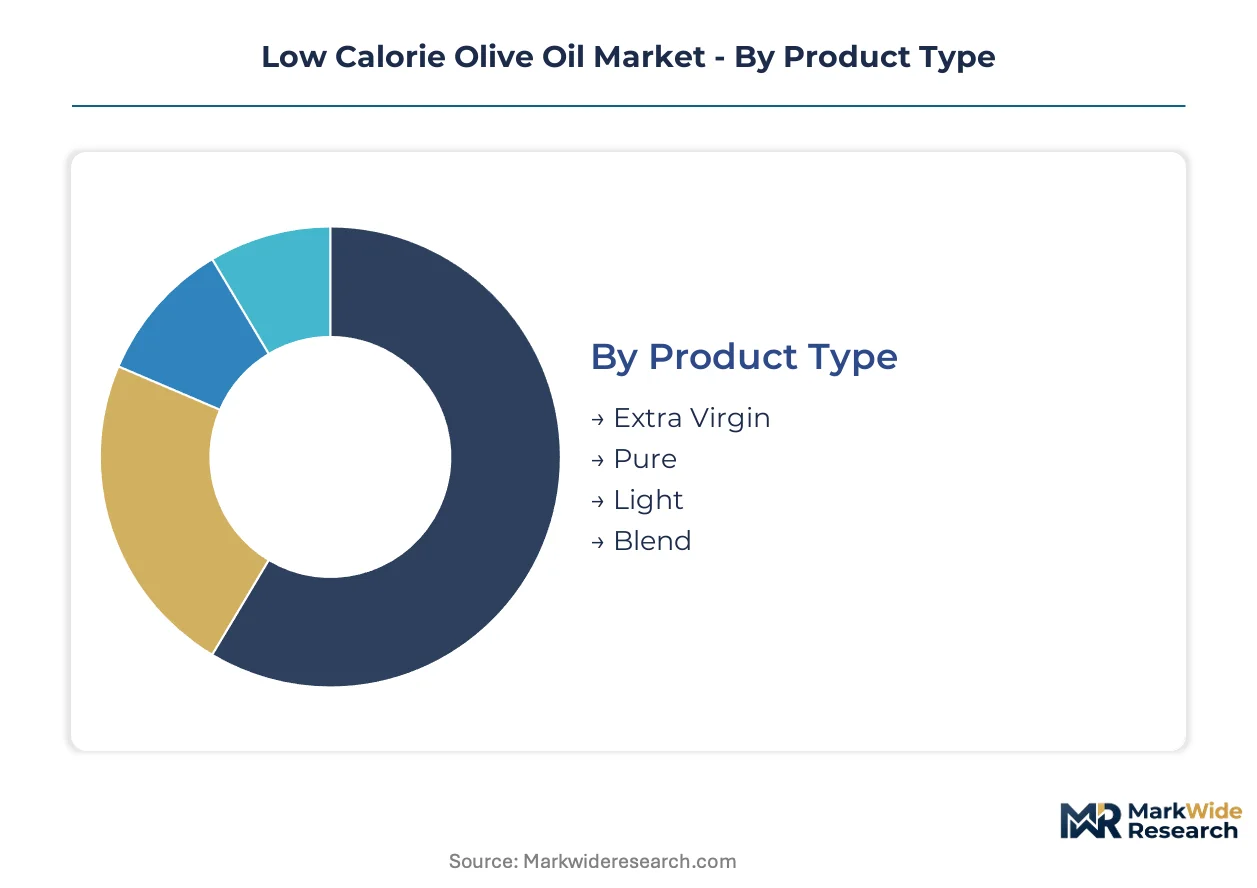
Segmentation in low calorie olive oil reveals how procurement specifications diverge across food service operators, retail buyers, and direct-to-pantry subscribers. Each dimension exposes distinct margin structures and technical requirements that reshape competitive positioning.
Product Type:
Upgrade cycles in this category track shifting polyphenol awareness and smoke-point requirements among Mediterranean food service buyers.
- Extra Virgin:Cold-pressed extraction below 27 degrees Celsius preserves maximum polyphenol content and organoleptic certification. Spanish and Italian restaurant chains specify this grade for finishing applications where flavor intensity justifies per-liter premiums.
- Light:Refined processing reduces color intensity and caloric density per serving while extending smoke-point stability. North American household buyers in California and New York metro areas select this variant for daily cooking where thermal performance outweighs origin storytelling.
- Pure:Blended refined and virgin oils balance cost discipline with minimum quality thresholds for mid-tier retail placement.
- Blend:Multi-origin formulations enable price positioning across private-label supermarket tiers.
Volume placements concentrate in Light variants for household cooking; the faster expansion belongs to Extra Virgin as polyphenol health claims gain regulatory traction in EU markets.
Packaging Type:
Cost tier differentiation separates premium glass presentations from emerging flexible formats targeting sustainability-conscious procurement teams.
- Bottle:Dark glass remains the default for extra virgin grades requiring UV protection during extended retail shelf exposure.
- Pouch:Flexible film reduces freight intensity by 60% versus glass and attracts Nordic food service buyers with explicit carbon accounting mandates. Stockholm and Copenhagen catering operators now specify pouch-only procurement for bulk kitchen applications.
- Jar:Wide-mouth formats dominate deli-counter and specialty retail channels where sampling drives trial conversion.
- Can:Metal packaging serves institutional food service with high-rotation volume requirements and minimal origin verification needs.
Glass bottle shipments dominate current volume; pouch formats are climbing the fastest as EU packaging waste directives tighten.
End User:
Application-specific requirements create divergent specification sheets across consumption occasions and preparation methods.
- Restaurants:Mediterranean chains in Barcelona and Milan mandate temperature-verified crushing protocols and front-of-pack calorie transparency compliance. Menu reformulation cycles now embed low calorie olive oil specifications into standard procurement contracts.
- Household:Direct-to-pantry subscription models in California and New York capture recurring revenue with harvest-dated traceability that supermarket private labels cannot replicate.
- Food Services:Institutional operators prioritize smoke-point stability and volume pricing over origin certification.
- Catering:Event-based demand fluctuates seasonally with wedding and corporate calendar concentration in Q2-Q3.
Restaurant procurement commands the deepest quality specifications; household subscription channels are gaining share fastest through recurring revenue capture.
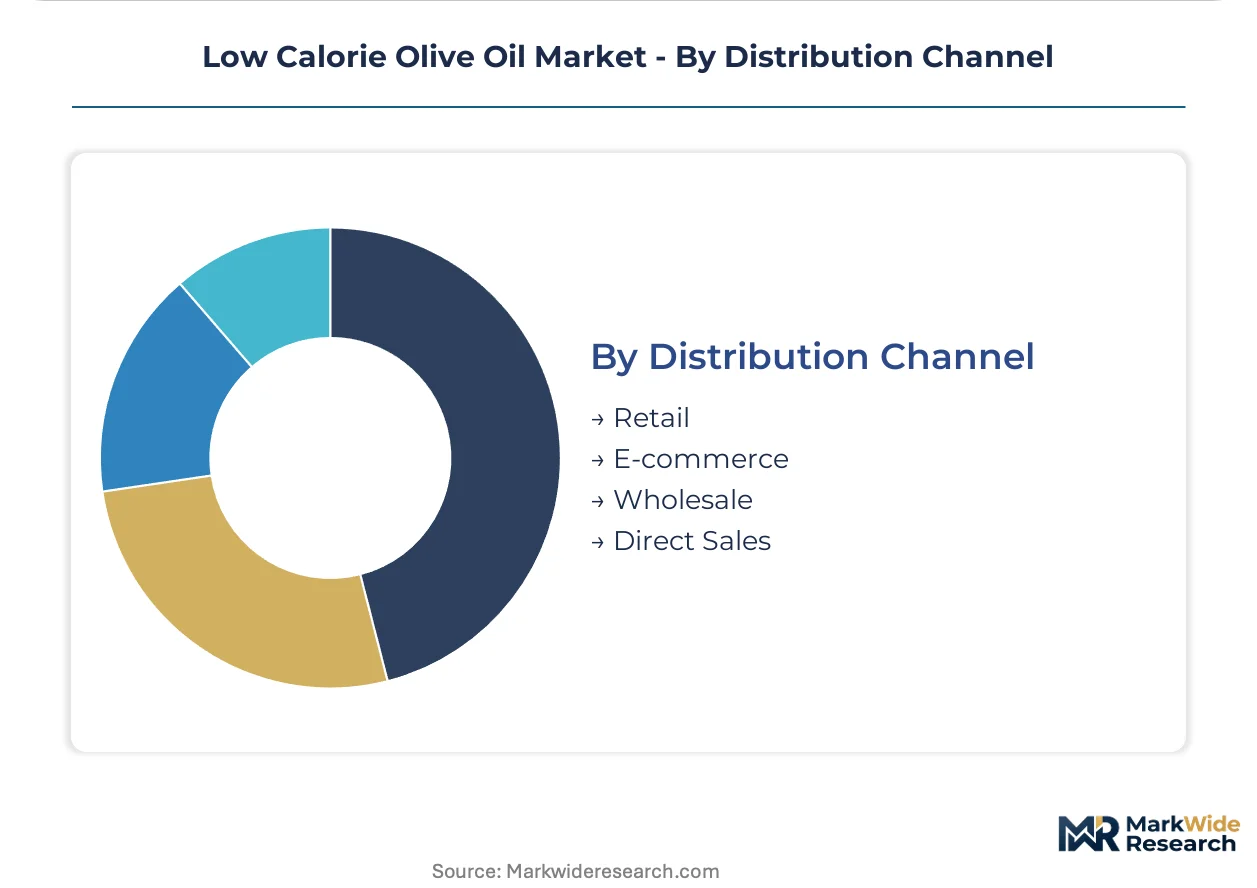
Distribution Channel:
Customer type and purchase frequency reshape channel economics from bulk wholesale to traceable direct relationships.
- E-commerce:Platform-based subscription services bypass traditional wholesale intermediation with origin-verified storytelling. Urban millennial households in San Francisco and Brooklyn drive recurring purchase velocity through harvest-specific transparency.
- Retail:Supermarket placement requires slotting fee investment and multi-brand architecture spanning premium and everyday tiers.
- Wholesale:Bulk distribution to food service operators concentrates in Andalusia-based crushing facilities with integrated logistics.
- Direct Sales:Estate-controlled orchards in California's Sacramento Valley sell harvest-limited releases to verified buyer lists.
Wholesale volumes retain scale dominance; e-commerce platforms are expanding most quickly as subscription models displace intermittent retail purchase patterns.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Andalusia's protected designation of origin zones concentrate crushing infrastructure and attract EU cohesion fund investment for cold-pressed capacity expansion. This tax-advantaged clustering shapes procurement patterns across Mediterranean Europe and sets import parity benchmarks for North American buyers.
Spain
Andalusian cooperatives in Jaén and Córdoba dominate extra virgin output as restaurant chains mandate temperature-verified crushing protocols. EFSA polyphenol health claim approvals enable premium positioning that American competitors cannot replicate. Seville-based bottlers now supply Nordic food service operators with pouch-format bulk shipments.
Italy
Apulian and Sicilian estates command finishing-grade premiums through DOP certification rigor. REACH solvent residue enforcement filters unrefined imports and elevates certified cold-pressed grades in domestic retail. Milan restaurant procurement teams embed low-calorie specifications into standard supply contracts.
United States
Sacramento Valley estate orchards set import-parity quality benchmarks with estate-controlled crushing and direct-to-pantry subscription models. FDA nutrition fact panel rules constrain polyphenol marketing claims versus European latitude. California producers capture recurring urban household revenue through harvest-dated traceability platforms.
Greece
Peloponnese and Crete cultivation zones supply bulk refined grades for North African and Middle Eastern food service. EU packaging waste directives accelerate pouch format trials among Athens-based exporters. Thessaloniki crushing facilities strain under compressed organic certification audit cycles.
Portugal
Alentejo estates expand cold-pressed capacity to capture Spanish procurement spillover. The country's national agricultural regulator enforces origin verification standards that align with EU nutrition labeling mandates. Lisbon-based traders now intermediate between Andalusian bulk suppliers and Brazilian retail distributors.
Low Calorie Olive Oil Market Competitive Landscape
Branded specialists and contract manufacturers split share differently across segments, with integrated crushing-to-bottling assets commanding premium tiers while toll processors serve private-label volume. The structure concentrates among Iberian and Italian origin-certified players with estate-controlled supply, mid-scale regional bottlers with flexible format capabilities, and North American orchard-direct specialists with subscription distribution. Competitive moves center on backward integration into orchard ownership and geographic expansion through origin certification stacking.
Within the integrated Iberian tier, Sovena and Deoleo S.A. exemplify multi-brand architecture spanning premium and everyday retail positioning. California Olive Ranch anchors North American extra virgin positioning through estate-controlled Sacramento Valley orchards. These three occupy positions that reflect divergent strategic bets: European regulatory arbitrage through EFSA claim leverage versus American direct-channel recurring revenue capture.
| Leading Market Players |
|---|
| Sovena |
| Deoleo S.A. |
| Borges International Group |
| Salov S.p.A. |
| Cargill |
| California Olive Ranch |
| Pompeian |
| Del Monte Foods |
| Catania Oils |
| Others |
Value Network & Pricing Analysis
EU packaging waste directives now gate qualified supply and premium-tier pricing access, forcing producers to absorb flexible-format conversion costs or surrender shelf positioning to certified competitors. Cold-pressed extraction protocols and pouch-format compliance separate price-advantaged suppliers from legacy glass-dependent operators facing margin compression.
Pricing Analysis
Short lead-time premiums now dominate contract negotiations, with temperature-verified crushing protocols commanding per-liter markups from Mediterranean restaurant chains facing compressed menu-reformulation deadlines. Three-tier pricing structure across extra virgin, light, and pure grades stratifies by polyphenol certification intensity and smoke-point performance. Price differentiation hinges on EFSA health claim eligibility and origin-verified traceability that American competitors cannot replicate under FDA constraints. Food service procurement teams in Barcelona and Milan show least price sensitivity due to regulatory compliance mandates, while North American private-label retailers absorb maximum pressure from avocado oil substitution.
Supply Chain Analysis
Domestic-content mandates in EU nutrition labeling rules are reshaping sourcing toward Andalusian and Apulian crushing clusters with integrated bottling assets. Supply concentrates in Spain, Italy, and California's Sacramento Valley, with harvest yield fluctuations in Jaén province creating single-source vulnerability for bulk purchasers. Raw material dependencies rest on olive cultivar availability, cold-pressed equipment capacity, and polyphenol-preserving storage infrastructure. Tariff exposure on North African refined imports compounds input cost volatility. Distribution runs through estate-controlled orchard direct sales for premium tiers, wholesale intermediation for institutional food service, and subscription platforms for recurring household revenue.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
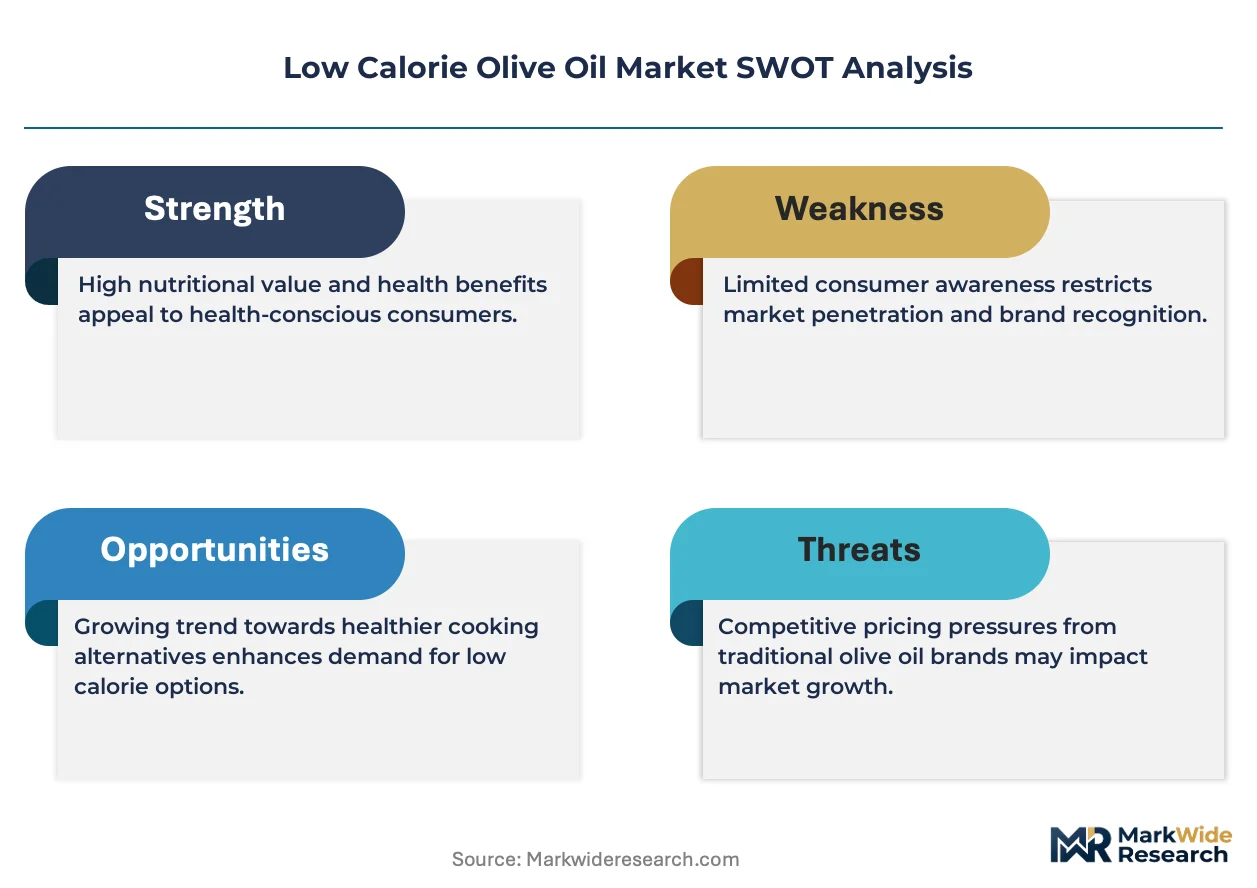
Consolidation pressure from REACH solvent residue enforcement is eliminating toll-processing competitors without integrated crushing assets, compressing the viable supplier base toward origin-certified estate operators.
For Market Incumbents: Lock in backward integration into orchard ownership across Jaén and Córdoba provinces to secure cultivar supply against harvest volatility. Capture channel control through direct-to-pantry subscription infrastructure that supermarket private labels cannot replicate, while investing in cold-chain logistics to defend polyphenol certification against emerging California competitors. For New Entrants and Emerging Players: Subscription platform partnerships offer the most penetrable entry vector for urban millennial households in San Francisco and Brooklyn seeking harvest-dated traceability. White-space targets include Nordic food service pouch-format procurement and mid-tier retail light oil segments where thermal performance outweighs origin storytelling. Go-to-market execution should leverage sustainability certification stacking to bypass incumbent slotting fee barriers. For Investors and Strategic Acquirers: Compressed organic certification audit timelines at mid-scale crushing facilities is the leading indicator that quality-control staffing constraints will force asset sales. Long-term viability favors estate-controlled operators with captive supply and integrated bottling over toll-dependent processors. Acquisition targets should display EFSA claim leverage and flexible-format production capacity. Watch for polyphenol health claim standardization costs triggering American export-oriented producer distress.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Orchard Ownership | Captive supply from Jaén estates secures cultivar access against Andalusian harvest volatility. |
| Pouch Packaging Format Conversion | Flexible film compliance with EU packaging waste directives opens Nordic food service procurement. |
| Direct-to-Pantry Subscription Launch | Recurring revenue capture in California and New York displaces intermittent retail purchase patterns. |
| EFSA Health Claim Certification Investment | Cardiovascular benefit language creates regulatory arbitrage unavailable to FDA-constrained American competitors. |
| Cold Chain Logistics Expansion | Temperature-controlled storage infrastructure defends polyphenol content against quality degradation penalties. |
Research Methodology
Multi-period observation of extraction protocol adoption, packaging format shifts, and procurement contract specifications anchored the trend analysis, supplemented by interviews with crushing facility quality control directors, restaurant chain procurement managers, retail category buyers, and cold-chain logistics operators. Secondary validation drew from EU REACH enforcement disclosures, FDA nutrition fact panel rulemakings, EFSA health claim evaluation archives, and customs trade data on olive oil import grades. Bottom-up volume estimates triangulated against top-down value projections.
Segment-weighting across product type, packaging format, end user, and distribution channel dimensions shaped the analytical framework over the projection horizon. CAGRs were derived from modeled growth trajectories in each segment, with cross-validation against historical elasticity patterns in premium edible oil categories. Forecast inputs included polyphenol certification penetration rates, e-commerce subscription adoption curves, and EU packaging waste directive implementation timelines.
Several conditions sit outside the modeled scope, including extreme weather events affecting Mediterranean harvest yields, abrupt shifts in FDA polyphenol marketing permissibility, and geopolitical disruptions to North African refined oil import flows. Forecasts reflect documented assumptions about regulatory continuity and consumer wellness trend persistence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Ingredients
Curcuma Longa (Turmeric) Root Extract Market
Ingredients
Global Palm Kernel Oil and Coconut Oil Based Natural Fatty Acids Market
Ingredients
Self-Rising Flour Market
Ingredients
Citrus Pectin Market
Ingredients
Liquid Egg Market
Ingredients
Fish Feed Ingredients Market
Ingredients
Native Whey Protein Ingredients Market
Ingredients
Peanut Ingredients Market
Ingredients
Horehound Extract Market
Ingredients
Calcium Caseinate Market
Ingredients
Cooking Oil Market
Ingredients
Banana Flour Market
Ingredients
Barley Malt Extract Market
Ingredients
Prenatal Vitamin Ingredients Market
Ingredients
Wheat Protein Concentrates Market
Ingredients
Starch Market