
 Global Palm Wax Market | 2026-2036
Global Palm Wax Market Size, Share, and Industry Trends Forecast 2026-2036
Global Palm Wax Market Foresight
Malaysia's capacity expansion across Peninsular Malaysian oleochemical corridors is reshaping trade flows for hydrogenated and fractionated grades. BASF leverages its integrated oleochemicals network to sustain supply security for European cosmetic producers. Guangdong Zhongke Hongtai New Materials anchors regional distribution through its South China manufacturing base. Clariant specializes in performance wax blends for high-end candle and polish applications.
Palm wax comprises triglycerides extracted from Elaeis guineensis fruit, refined through bleaching, deodorization, and fractional crystallization to yield melting points between 58°C and 62°C for candle and coating applications. Refined palm wax leads volume due to its standardized color and burn profile, while hydrogenated palm wax captures expanding margin pools in cosmetics as formulators replace petroleum-derived rheology modifiers. Fractionated palm wax exhibits the fastest trajectory among product types, driven by narrow-cut specifications for luxury candle makers seeking controlled crystalline structure.
REACH registration requirements in Europe govern chemical safety documentation for imported palm wax derivatives, while the EU Deforestation Regulation imposes geolocation traceability obligations on supply chains entering member states. The Roundtable on Sustainable Palm Oil certification operates as a de facto market access filter for North American and European buyers. Stakeholders must monitor evolving deforestation enforcement timelines and calibrate sourcing contracts against emerging due diligence liabilities.
Market Dynamics
EU Deforestation Regulation geolocation mandates are forcing Southeast Asian exporters to rebuild traceability infrastructure from plantation to port, while candle manufacturers in North America accelerate procurement of certified refined grades to meet clean-label formulation commitments.
Growth Catalysts
- EU Green Deal deforestation-free mandates:Importers into European member states now require satellite-verified geolocation data, creating certified supply premiums that reward compliant Malaysian and Indonesian producers.
- Clean-label candle formulation:North American manufacturers are replacing petroleum-derived paraffin with hydrogenated palm wax to satisfy consumer preference for plant-based burn profiles.
- Fractionation technology diffusion:Narrow-cut crystallization capabilities in Peninsular Malaysian oleochemical corridors enable luxury candle makers to specify controlled thermal properties.
Market Restraints
- Crude palm oil price volatility:Feedstock costs swing with El Niño weather patterns and Indonesian export levy adjustments, compressing margin predictability for hydrogenated grade producers.
- Supply concentration risk:Indonesia and Malaysia collectively control upstream crude extraction, leaving refiners exposed to bilateral trade policy shifts and biodiesel diversion mandates.
- Paraffin substitution economics:Petroleum-derived alternatives retain cost advantages in price-sensitive packaging and industrial coating segments.
Strategic Opportunities
- Brazilian cosmetics formulators:ANVISA registration pathways for plant-derived rheology modifiers remain underpenetrated relative to saturated European and North American markets.
- RSPO certification arbitrage:Segregated supply chains command measurable premiums in German and Dutch procurement tenders as CSRD disclosure requirements expand.
- Biodegradable coating applications:Food packaging manufacturers in Japan are piloting palm-derived barrier coatings to replace polyethylene laminates under METI plastic reduction guidelines.
Industry Challenges
- Traceability system integration:Smallholder plantation data capture requires interoperable digital platforms that many Malaysian mid-tier processors lack capital to deploy.
- REACH dossier maintenance:European importers face escalating ECHA compliance costs for derivative substance registrations, particularly for novel fractionated grades.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Palm Wax Market |
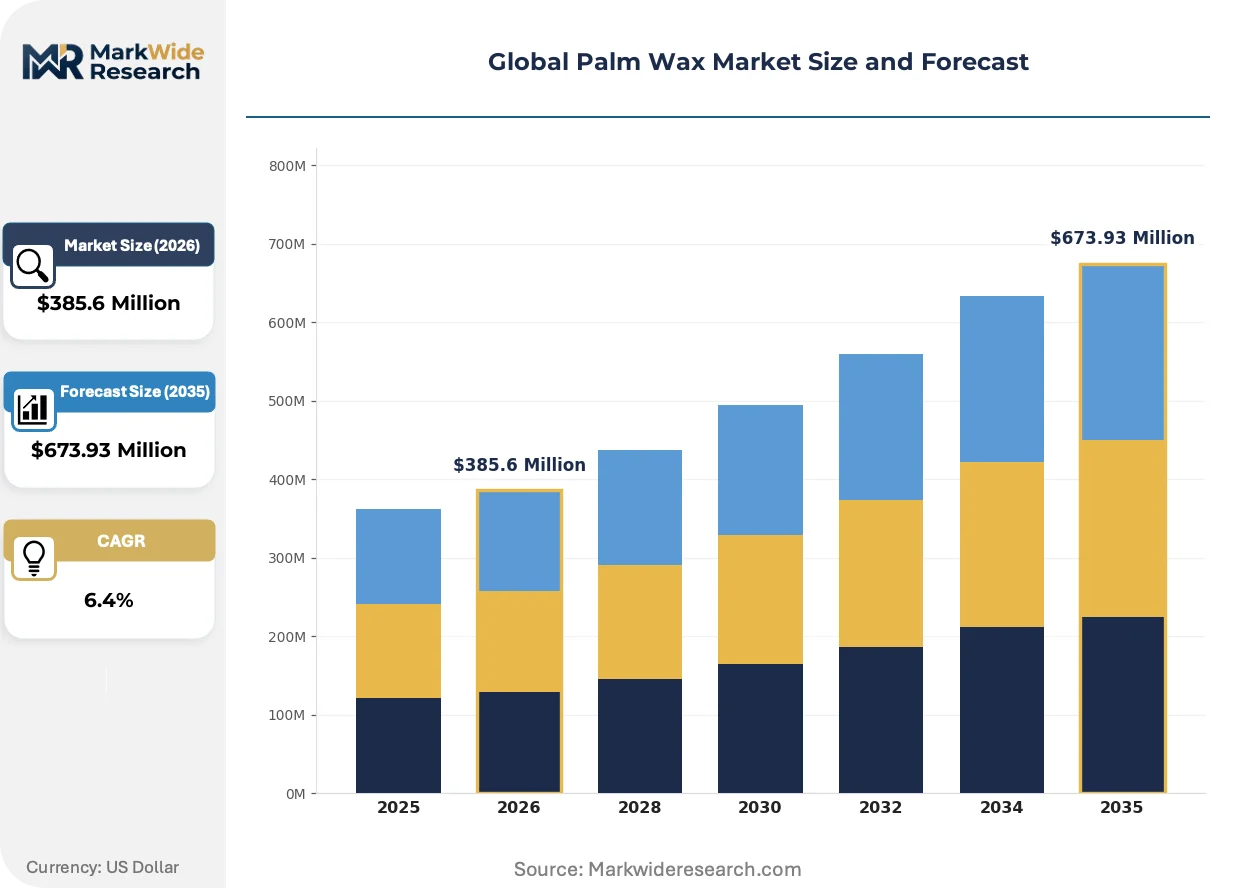
| Market Size in 2026 | $385.6 Million |
| Market Size in 2035 | $673.93 Million |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Refined Palm Wax, Unrefined Palm Wax, Hydrogenated Palm Wax, Fractionated Palm Wax, Blended Wax Application: Candle Manufacturing, Cosmetics, Packaging, Polishes, Crayons, Lubricants End User Industry: Candle Makers, Cosmetic Producers, Packaging Industry, Art Supplies, Automotive Care, Textile Finishers Packaging Type: Blocks, Pellets, Sheets, Beads, Granules |
| Companies Covered | Jiangsu Haian Petrochemical Plant, Guangdong Zhongke Hongtai New Materials, BASF, Weihai Huaen Rubber & Plastic New Material, Guangdong Nanhui New Material, Clariant, Shanghai Greening Chemical Technology, HaiAn GuoLi Chemical, Michelman, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Palm Wax Market Shifts & Advancements
Digital supply chain verification and precision fractionation are converging to create tiered product differentiation, while regulatory disclosure requirements reshape competitive positioning across export corridors.
Enzymatic interesterification is hybridizing conventional hydrogenation pathways, enabling cosmetic formulators to achieve customized melting profiles without trans-fat labeling triggers. Specialty chemical divisions at major oleochemical groups are adopting these biocatalytic routes to serve European personal care brands demanding cleaner ingredient narratives. The technology is compressing the performance gap between palm-derived and synthetic rheology modifiers in premium skin care applications.
EU Deforestation Regulation enforcement timelines are accelerating third-party audit investments across Indonesian and Malaysian export channels. Supply chain operators must now deploy satellite monitoring and blockchain documentation to satisfy due diligence obligations before product enters Rotterdam or Hamburg ports. Fractionated and hydrogenated derivatives face the steepest compliance cost increases given their multi-origin blending complexity.
Direct contracting between North American candle manufacturers and certified Malaysian refiners is displacing traditional trader-mediated procurement. Large-scale buyers are negotiating multi-year offtake agreements tied to RSPO segregation standards, capturing supply security while bypassing spot market volatility. This pattern is most visible in California and Texas formulation facilities serving clean-label retail channels.
Global Palm Wax Market Segmentation
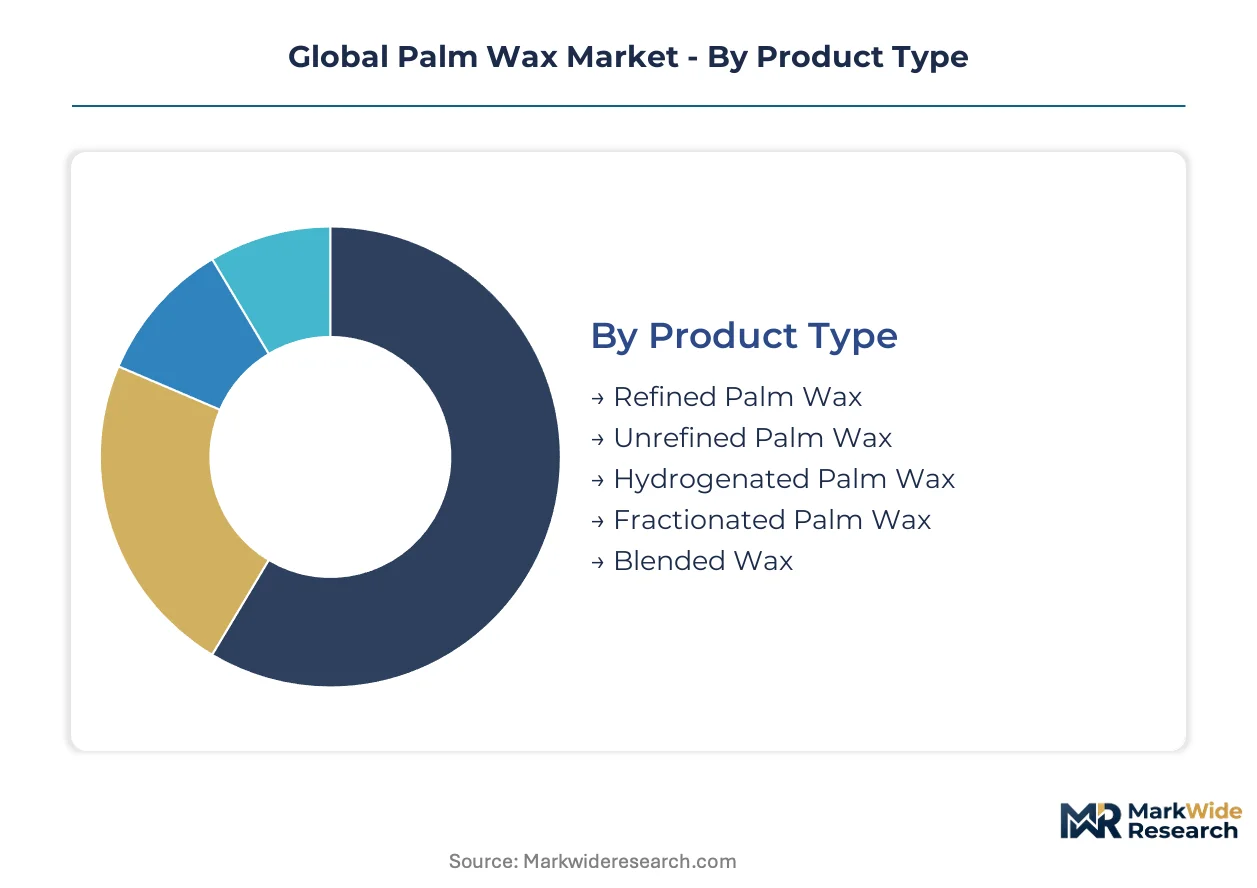
Palm wax segmentation reflects divergent processing intensities and specification tolerances across end-use applications. Candle manufacturers prioritize standardized burn profiles while cosmetic formulators demand narrow-cut thermal properties that command formulation premiums.
Product Type:
Cycle times vary sharply across refining stages, with hydrogenated and fractionated grades requiring extended crystallization and hydrogenation sequences compared to standard refined output.
- Refined Palm Wax:Bleached and deodorized triglyceride matrices deliver consistent color indices and standardized melting points between 58°C and 62°C. North American candle manufacturers anchor procurement contracts around this grade to meet clean-label retail commitments without premium outlays.
- Hydrogenated Palm Wax:Saturation-controlled molecular structures enable customized hardness and opacity profiles for cosmetic rheology applications. European personal care brands under REACH documentation requirements specify this grade to replace petroleum-derived modifiers in premium skin care formulations.
- Fractionated Palm Wax:Narrow-cut crystallization yields controlled thermal properties for luxury candle specifications.
- Blended Wax:Performance-optimized mixtures combining palm derivatives with complementary natural waxes.
- Unrefined Palm Wax:Crude extraction output serving industrial coating segments with lower specification thresholds.
Refined palm wax anchors the volume base while fractionated palm wax gains share at the steepest rate.
Application:
Cost tiers separate commodity-scale consumption from specification-driven procurement, with packaging and crayon applications tolerating broader quality variance than cosmetics or premium candles.
- Candle Manufacturing:Dominant consumption channel spanning container candles, pillars, and tapers. California and Texas formulation facilities drive RSPO-certified offtake through direct Malaysian refiner contracts, bypassing spot volatility.
- Cosmetics:Skin care and color cosmetic applications demand hydrogenated and fractionated grades with documented thermal stability. ANVISA registration pathways in Brazil remain underpenetrated relative to saturated European markets.
- Packaging:Barrier coatings and laminates for food contact applications.
- Polishes:Floor and automotive care formulations leveraging palm wax hardness.
- Crayons:Art supply manufacturing with moderate specification requirements.
- Lubricants:Industrial and specialty lubricant bases.
Candle manufacturing commands the largest volume allocation while cosmetics applications expand most quickly on value terms.
End User Industry:
Customer concentration patterns diverge between fragmented artisan candle makers and consolidated cosmetic multinationals with integrated procurement functions.
- Candle Makers:Spanning artisan producers to industrial-scale manufacturers. Direct contracting trends displace traditional trader mediation as large buyers negotiate multi-year RSPO-segregated agreements.
- Cosmetic Producers:Multinational personal care brands with dedicated oleochemical sourcing teams. BASF's integrated network supplies European cosmetic producers with REACH-compliant documentation packages.
- Packaging Industry:Food and consumer goods laminates and coatings.
- Art Supplies:Crayon and modeling material manufacturers.
- Automotive Care:Polish and protective coating formulators.
- Textile Finishers:Fabric softening and water-repellency applications.
Candle makers absorb the highest absolute tonnage while cosmetic producers generate the steepest margin premiums.
Packaging Type:
Handling economics and melting equipment compatibility determine format selection across downstream processing configurations.
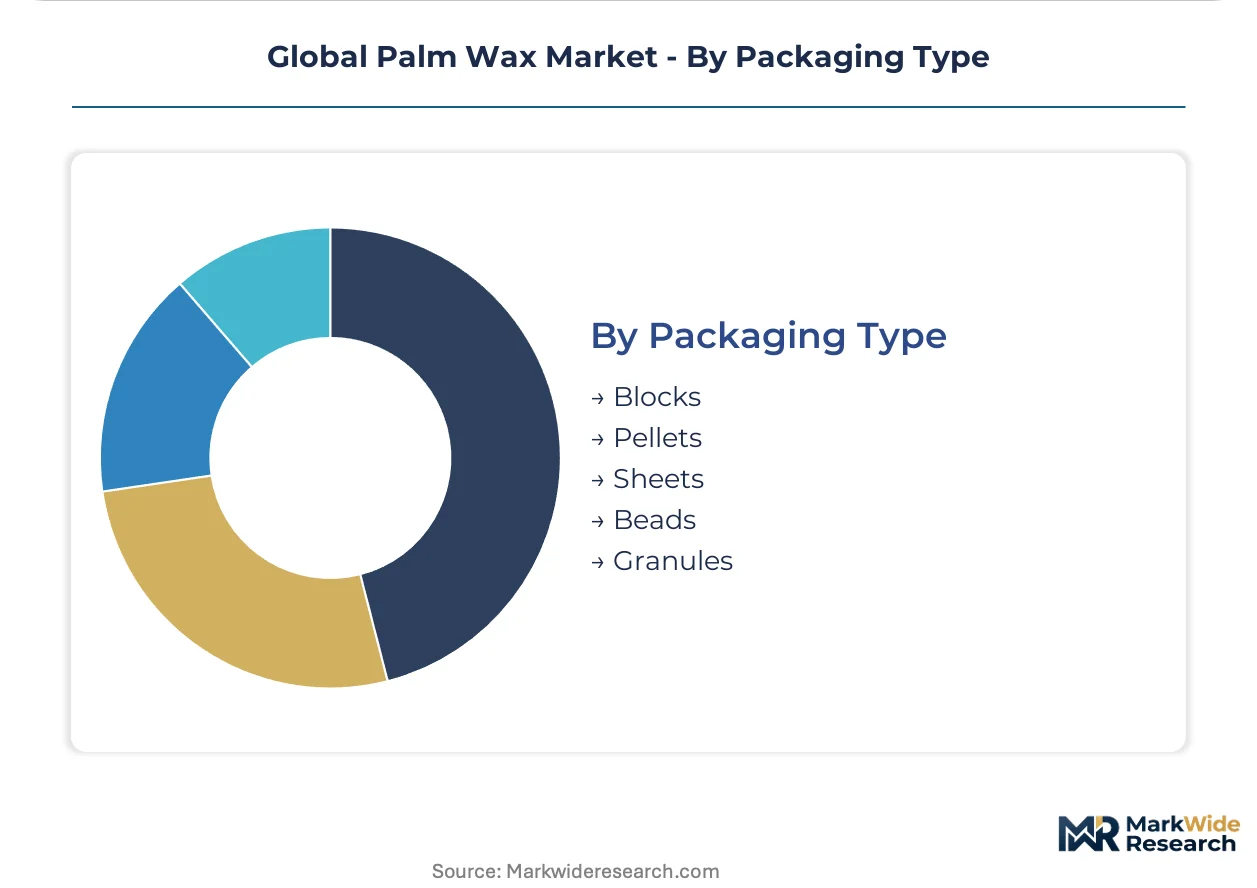
- Blocks:Standard bulk format for large-scale candle manufacturing. Malaysian refiners export predominantly in block form for North American industrial formulation facilities.
- Pellets:Metered-feed compatibility for automated cosmetic compounding lines. Guangdong Zhongke Hongtai's South China base distributes pelletized grades to regional personal care manufacturers.
- Sheets:Specialized applications requiring planar deposition.
- Beads:Rapid-melt formulations for small-batch processing.
- Granules:Intermediate handling format for blending operations.
Blocks dominate export volumes while pellets capture expanding share in automated cosmetic production.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
ECHA's REACH registration framework anchors European import compliance, while Indonesian and Malaysian export corridors face geolocation traceability mandates under EU Deforestation Regulation enforcement timelines.
Indonesia
Crude palm oil extraction and fractionation capacity concentrates in Sumatran and Kalimantan plantation belts. The national export levy adjustment mechanism creates feedstock cost volatility that refiners must hedge through long-term supply contracts. Batam and Belawan port clusters are deploying satellite monitoring systems to satisfy Rotterdam-bound shipment documentation requirements.
Malaysia
Peninsular Malaysian oleochemical corridors expand hydrogenation and crystallization capacity to serve European cosmetic formulators. The Malaysian Palm Oil Board certification schemes align with RSPO segregation standards demanded by German and Dutch procurement tenders. Klang Valley refiners are integrating blockchain traceability platforms to capture certified supply premiums.
Germany
REACH dossier maintenance costs escalate for importers of novel fractionated grades entering Hamburg and Rotterdam ports. The EU Green Deal deforestation-free mandates require satellite-verified geolocation data from Southeast Asian suppliers. BASF's integrated oleochemicals network supplies domestic cosmetic producers with compliant documentation packages.
United States
California and Texas candle manufacturing facilities drive RSPO-certified offtake through direct Malaysian refiner contracts. EPA industrial chemical reporting governs imported wax derivative classifications. Los Angeles and Houston formulation clusters are bypassing spot market volatility through multi-year segregation-standard agreements.
China
Guangdong province anchors South China distribution through pelletized grade manufacturing for regional personal care producers. SAMR food contact material regulations govern barrier coating applications in packaging segments. The Pearl River Delta oleochemical base is expanding fractionation capabilities to serve domestic luxury candle demand.
Global Palm Wax Market Competitive Landscape
Integrated oleochemical majors and specialized wax refiners split the market into consolidation-resistant tiers. Malaysian and Indonesian upstream operators control feedstock access, while European and North American downstream formulators capture specification premiums. Three archetypes dominate: plantation-integrated refiners with captive crude supply, independent processors leveraging tolling arrangements, and specialty chemical divisions serving cosmetic certification requirements. Competitive dynamics center on backward integration into plantation traceability systems and technology licensing for enzymatic interesterification pathways.
Among Asia-Pacific-based processors, Guangdong Zhongke Hongtai New Materials and Jiangsu Haian Petrochemical Plant exemplify the regional manufacturing base serving domestic and export demand. BASF occupies a position representing the integrated multinational archetype with European REACH compliance infrastructure. These three entities anchor the competitive structure without exhaustive market coverage.
| Leading Market Players |
|---|
| Jiangsu Haian Petrochemical Plant |
| Guangdong Zhongke Hongtai New Materials |
| BASF |
| Weihai Huaen Rubber & Plastic New Material |
| Guangdong Nanhui New Material |
| Clariant |
| Shanghai Greening Chemical Technology |
| HaiAn GuoLi Chemical |
| Michelman |
| Others |
Supply & Pricing Matrix
Klang Valley refiners in Malaysia are expanding hydrogenation capacity faster than Indonesian competitors, concentrating pricing power for RSPO-segregated grades in Peninsular Malaysian corridors. This capacity asymmetry lets certified processors command premiums from European cosmetic producers while spot-market crude palm oil volatility compresses margins for unintegrated Indonesian fractionators serving price-sensitive packaging segments.
Pricing Analysis
Rotterdam-Hamburg spreads for hydrogenated palm wax run 12-18% above Peninsular Malaysian export parity, reflecting EU Deforestation Regulation compliance cost layering. Contract-based long-term offtake dominates procurement between North American candle manufacturers and Malaysian refiners, with price differentiation driven by RSPO certification tier and volume scale commitments. Cost compression in standard refined grades is intensifying because Indonesian export levy adjustments feed directly into feedstock pricing. Artisan candle makers exhibit highest price sensitivity, while European cosmetic multinationals absorb premiums for REACH-documented hydrogenated grades.
Supply Chain Analysis
Toll refiners in Malaysia's Port Klang Free Zone and independent processors in Indonesia's Belawan-Batam corridor hold the bulk of contract-manufacturing capacity for fractionated and hydrogenated derivatives. Geographic supply concentrates in Indonesia, Malaysia, and China, with the Pearl River Delta adding crystallization capacity for domestic luxury candle demand. Raw material dependencies rest on crude palm oil from Sumatran and Kalimantan plantation belts, hydrogenation catalysts from European specialty chemical suppliers, and bleaching earth from Indonesian bentonite deposits. Single-source vulnerability runs through Indonesian export levy policy shifts that redirect crude supply toward biodiesel mandates. Distribution feeds from refiner direct contracts to North American formulation facilities, displacing traditional trader mediation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of integrated traceability infrastructure separates sustainable supply leaders from compliance laggards. The gap between satellite-verified plantation data capabilities and spot-market procurement systems defines competitive endurance as EU enforcement timelines harden.
For Market Incumbents: Insulate margin pools by locking multi-year RSPO-segregated offtake with California and Texas candle manufacturers before spot-market volatility widens. Backward integration into blockchain-enabled plantation monitoring in Peninsular Malaysia captures certified supply premiums that unintegrated Indonesian competitors cannot match. Capacity addition in Klang Valley hydrogenation corridors reinforces supply security for European REACH-compliant cosmetic grades. For New Entrants and Emerging Players: Build out ANVISA registration capabilities for Brazilian cosmetic formulators, where plant-derived rheology modifier pathways remain underpenetrated relative to saturated European markets. Direct contracting with artisan candle makers in North America bypasses trader intermediation while capturing clean-label retail channel growth. Specialty fractionation for luxury candle specifications offers the most penetrable tier given narrow-cut crystallization capability scarcity. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among Malaysian refiners with locked RSPO-segregated supply agreements and integrated oleochemical networks. Long-term viability across the analysis window favors plantation-integrated processors with captive crude and digital traceability infrastructure. Acquisition targets should display blockchain-verified geolocation capabilities and multi-year North American offtake coverage. The signal to watch is Indonesian export levy diversion toward biodiesel mandates, which would compress fractionation feedstock availability and accelerate consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Plantation Traceability | Blockchain-verified geolocation data satisfies Rotterdam port entry under EU Deforestation Regulation mandates. |
| Capacity Expansion in Hydrogenation Corridors | Peninsular Malaysian oleochemical clusters capture European cosmetic formulator demand for REACH-documented grades. |
| Long-term Supply Agreement with North American Buyers | Direct contracting with California and Texas facilities locks out spot-market volatility for RSPO-segregated output. |
| Green Certification Program | RSPO segregation standards command measurable premiums in German and Dutch procurement tenders under CSRD expansion. |
| Joint Venture for Brazilian Market Entry | ANVISA registration partnerships open underpenetrated cosmetic rheology modifier demand relative to saturated European channels. |
Research Methodology
Operator-level perspectives from refinery operations managers, cosmetic formulator procurement leads, candle manufacturing supply chain directors, and RSPO certification auditors anchored the qualitative base. Primary interviews with Malaysian Palm Oil Board officials and European oleochemical import compliance officers combined with secondary validation from customs trade databases, ECHA REACH registration filings, and SEC 10-K disclosures from listed oleochemical groups. Bottom-up capacity modeling across Indonesian and Malaysian processing facilities triangulated against top-down demand estimates from end-use industry associations.
Scenario-bracketing around EU Deforestation Regulation enforcement timelines and El Niño weather pattern probabilities shaped the analytical framework across the projection horizon. Segmentation dimensions modeled include product grade tier, end-use application intensity, certification standard, and regional production hub concentration. CAGRs derived from installed capacity utilization trajectories and substitution elasticity estimates for paraffin displacement in candle formulations. Forecast inputs incorporated hydrogenation technology diffusion rates and blockchain traceability adoption curves among Southeast Asian exporters.
The forecast holds incumbent behavior within observed patterns; aggressive moves by plantation-integrated majors with captive crude supply would shift outcomes beyond modeled ranges. Forecasts assume Indonesian export levy mechanisms and Malaysian biodiesel diversion policies follow historical adjustment patterns. Quarterly review of RSPO certification uptake rates, Rotterdam port detention incidents for geolocation documentation failures, and North American clean-label retail channel expansion is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Sodium Lauroyl Isethionate Market
Oleochemicals
2-Hexyldecanol Market
Oleochemicals
Oleochemicals Market
Oleochemicals
Glycerol Esters of Wood Rosins Market
Oleochemicals
Fatty Acid Amides Market
Oleochemicals
Camphor Oil Market
Oleochemicals
Partially Hydrogenated Oil Market
Oleochemicals
Tallow Amine Market
Oleochemicals
Global Fatty Amides Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Isodecyl Pelargonate Market
Oleochemicals
Octylphenol Ethoxylate Market
Oleochemicals
US Esters Market
Oleochemicals
1-Decene Market
Oleochemicals
Global White Oil Market
Oleochemicals
Global Methyl Ester Ethoxylate Market