
 Lipid Rich Powder Market | 2026-2036
Lipid Rich Powder Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid Rich Powder Market Foresight
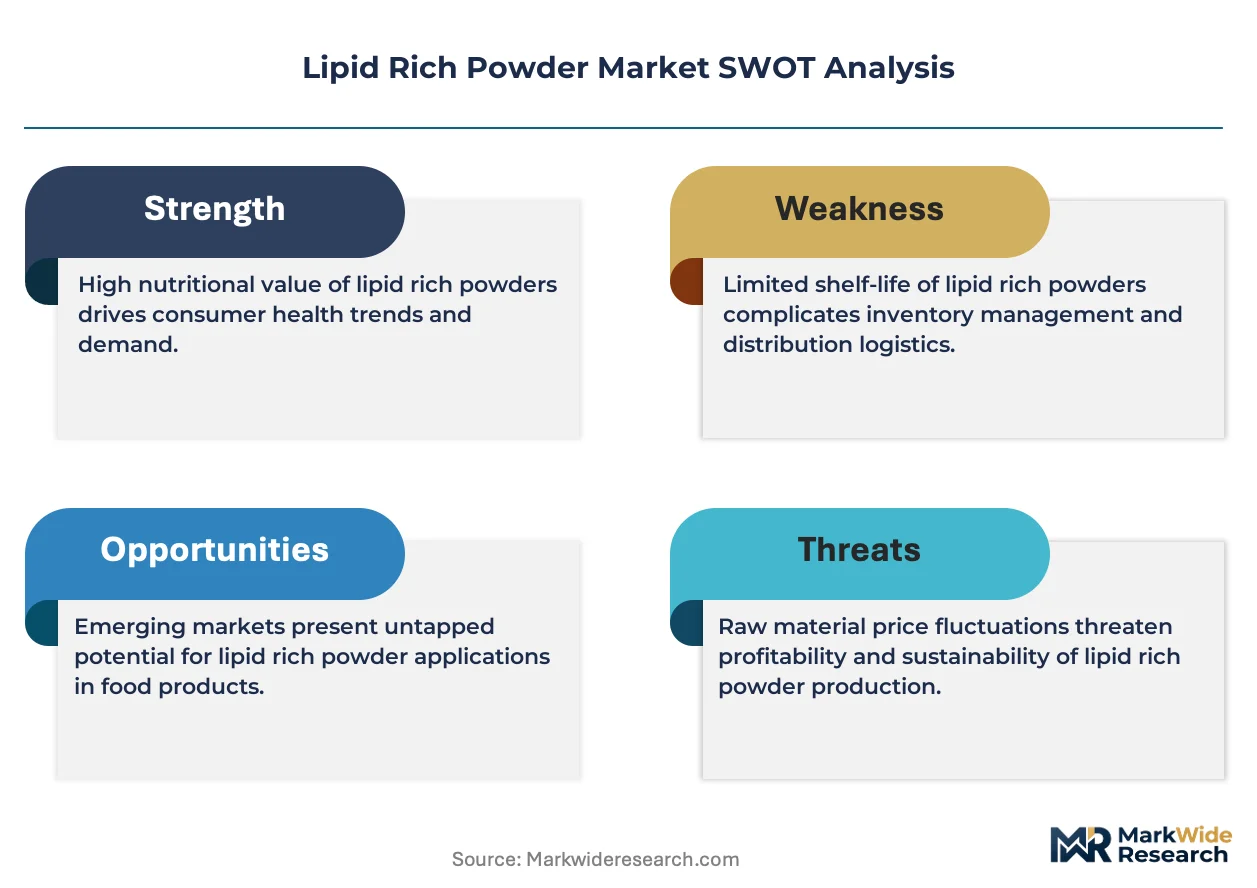
A shortage of lipid formulation chemists is unwinding capacity expansion plans across European nutraceutical manufacturers. Cargill leverages its integrated oilseed processing network to secure raw material streams for powder production. BASF SE anchors its position through advanced emulsification technologies that improve bioavailability in finished formulations. Kerry Group plc differentiates by controlling flavor-masked lipid systems for functional beverage applications.
Lipid rich powder consists of concentrated triglycerides, phospholipids, or structured lipids processed into free-flowing particulate form, typically achieving 50-80% fat content with particle sizes between 50-200 microns for uniform dispersion in food matrices. Spray-dried formulations dominate commercial output due to their superior shelf stability and reconstitution properties, while microencapsulated powder commands premium positioning in pharmaceutical applications where oxidative protection determines efficacy. Plant-based sources are expanding fastest within the source type dimension, though animal-based lipids still occupy the majority share in infant nutrition segments where dairy lipid profiles remain specified.
The FDA's GRAS notification framework and EFSA's novel food assessment pathway jointly determine market access timelines for new lipid ingredients in their respective jurisdictions. EFSA's evolving guidance on sustainability claims is forcing reformulation documentation that traces lipid sourcing through supply chains. Stakeholders must monitor how REACH chemical registration requirements apply to synthetic lipid intermediates, as classification shifts could trigger costly substance evaluations. The convergence of pharmaceutical-grade specifications with food-sector scale economics will determine which suppliers can bridge both compliance regimes without margin erosion.
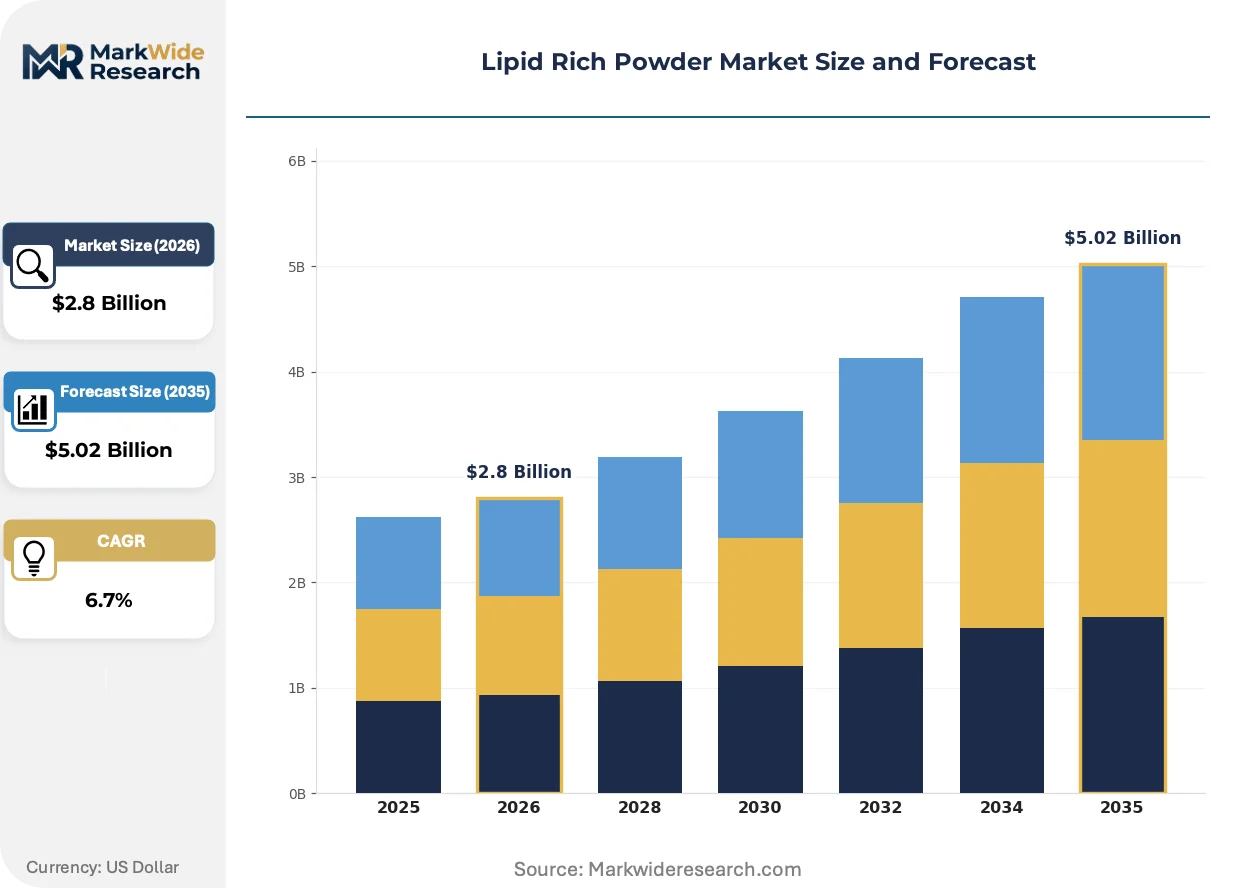
Market Dynamics
The lipid rich powder market is restructuring around supply-side consolidation in raw material sourcing and EFSA's tightening novel food assessment timelines, which together compress formulation-to-market cycles for new entrants.
Growth Catalysts
- Precision nutrition protocols:Clinical dietetics programs in Germany are integrating lipid microencapsulation for targeted metabolic interventions, expanding pharmaceutical-grade demand.
- EU Green Deal procurement mandates:Public health institutions across member states now require documented sustainable sourcing credentials for lipid ingredients in institutional nutrition contracts.
- Spray-drying equipment advances:Continuous processing systems are reducing oxidative degradation during powder formation, improving shelf stability for plant-derived formulations.
Market Restraints
- Phospholipid feedstock volatility:Sunflower lecithin supply from Black Sea origins faces recurring disruption, forcing reformulation cycles.
- Formulation chemist scarcity:European universities produce insufficient lipid specialization graduates to match capacity expansion timelines at contract manufacturers.
- REACH registration burden:Synthetic lipid intermediates trigger substance evaluation protocols that extend commercialization timelines by months.
Strategic Opportunities
- India functional food penetration:FSSAI's streamlined novel food approval pathway is opening access for structured lipid powders in mass-market dairy fortification.
- Cell-culture media applications:Biopharmaceutical serum replacement protocols are adopting lipid-rich powder formulations as animal-free alternatives.
- Direct-to-clinician distribution:Specialized lipid systems are bypassing traditional ingredient distributors through partnerships with metabolic health platforms.
Industry Challenges
- Emulsification expertise gaps:Scale-up from pilot to production volumes requires rare combinations of food engineering and pharmaceutical compliance knowledge.
- Dual certification complexity:Suppliers bridging food-grade and pharma-grade specifications face redundant audit cycles from separate accreditation bodies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid Rich Powder Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $5.02 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Whole Powder, Concentrated Powder, Emulsified Powder, Microencapsulated Powder End Use Industry: Food & Beverage, Nutraceuticals, Pharmaceuticals, Cosmetics Formulation Type: Liquid Formulations, Dry Formulations, Semi-Solid Formulations, Spray-Dried Formulations Source Type: Animal-Based, Plant-Based, Synthetic, Others |
| Companies Covered | Cargill, BASF SE, Archer Daniels Midland Company, DSM-Firmenich, Croda International Plc, Kerry Group plc, Royal FrieslandCampina, FMC, Algavia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid Rich Powder Market Shifts & Advancements
Formulation science is pivoting toward bioavailability enhancement as the primary competitive axis, with emulsification technologies and encapsulation architectures converging to redefine performance benchmarks across nutraceutical and pharmaceutical applications.
Structured lipid assemblies combining medium-chain triglycerides with phospholipid shells are decomposing the traditional separation between food-grade and pharma-grade supply chains. Nutraceutical formulators in the Netherlands and Denmark are adopting these hybrid systems at accelerated procurement cycles. The technology is decomposing legacy pricing tiers that previously segregated markets by certification grade rather than functional performance.
EFSA's evolving guidance on sustainability substantiation is forcing ingredient suppliers to deploy blockchain-traceable documentation for lipid sourcing claims. Manufacturers must now verify deforestation-free credentials through supply chain audits that extend to third-country origin farms. Infant nutrition specialists face the steepest compliance burden, as their formulations rely on dairy lipid fractions with complex international sourcing profiles.
Metabolic health platforms are consolidating procurement decisions for lipid ingredients through centralized formulary committees that bypass traditional distributor relationships. Specialized contract manufacturers in Bavaria and North Rhine-Westphalia are responding with direct technical service models. This channel compression is most pronounced in Germany, where precision nutrition startups cluster and demand rapid formulation iteration cycles.
Lipid Rich Powder Market Segmentation
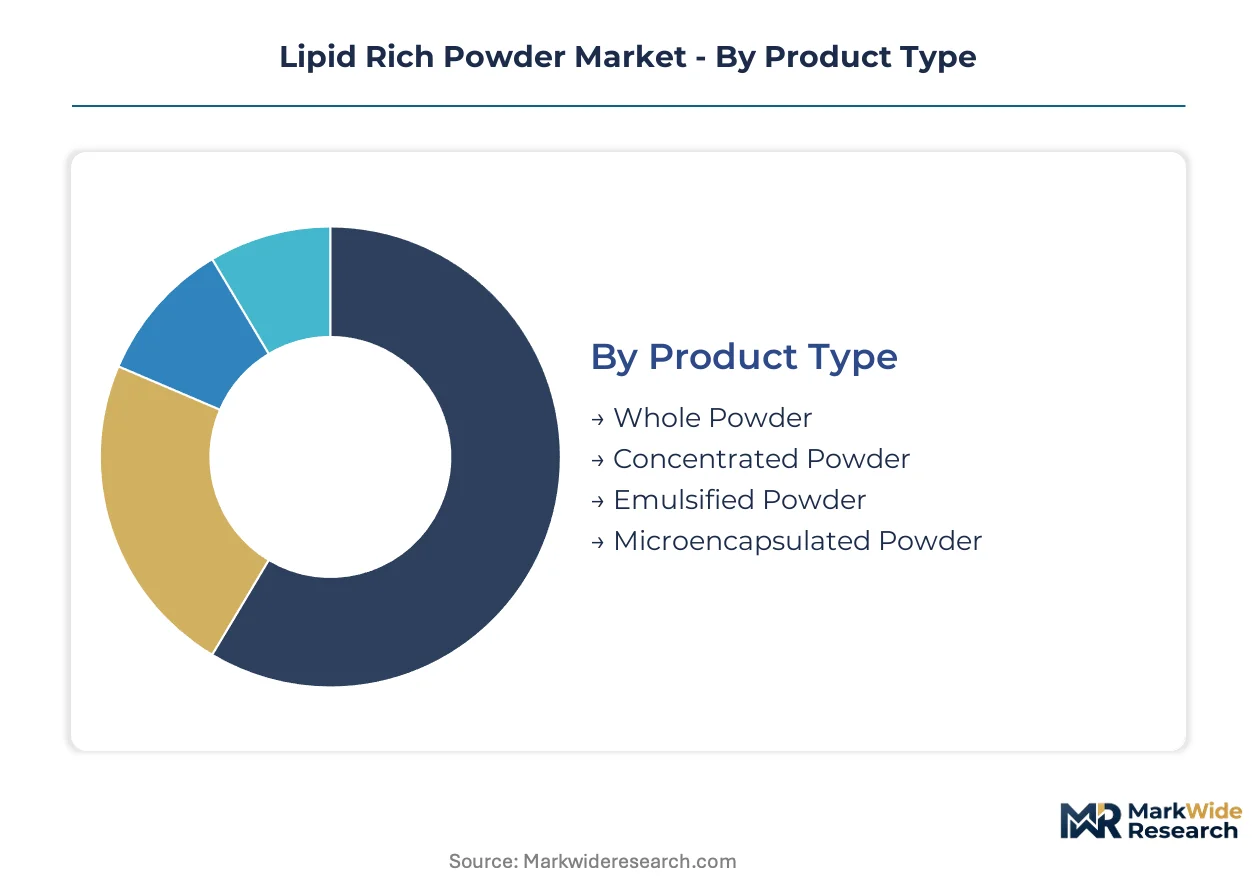
Segmentation in lipid rich powder markets reveals how technical specifications determine pricing power and customer lock-in. Formulation architecture and sourcing provenance create distinct competitive battlegrounds that separate commodity suppliers from premium-positioned players.
Product Type:
Margin pools concentrate in microencapsulated and emulsified formats where proprietary processing technology creates defendable differentiation.
- Microencapsulated Powder:Phospholipid or protein-based shell structures encasing lipid cores achieve 80-95% encapsulation efficiency for oxidative protection. Pharmaceutical applications in Germany and the Netherlands command premium positioning due to EFSA's stringent stability documentation requirements for novel food transitions.
- Emulsified Powder:Pre-formed oil-in-water emulsions stabilized by modified starches or gums enable direct reconstitution without high-shear mixing. Functional beverage manufacturers in Bavaria are standardizing procurement around these systems to eliminate downstream processing steps.
- Concentrated Powder:High-fat fractions (70-85% lipid content) serve infant nutrition specifications where dairy lipid profiles remain mandatory.
- Whole Powder:Full-fat compositions preserve native lipid structures for clean-label positioning in artisanal food applications.
The dominant share belongs to concentrated powder, while microencapsulated powder is closing the gap fastest.
End Use Industry:
Application requirements split the market between pharmaceutical-grade compliance burdens and food-sector scale economics.
- Nutraceuticals:Precision nutrition protocols in Munich and Hamburg are integrating lipid microencapsulation for targeted metabolic interventions, expanding demand for pharmaceutical-grade specifications at food-sector volumes.
- Pharmaceuticals:Cell-culture media applications are adopting lipid-rich powder formulations as animal-free serum replacements, with biopharmaceutical manufacturers requiring dual certification for GMP and food-grade traceability.
- Food & Beverage:Clean-label dairy fortification in mass-market applications drives procurement of spray-dried whole milk powders and structured lipid systems.
- Cosmetics:Ceramide-rich powders for topical delivery systems occupy niche positioning with limited supplier concentration.
Nutraceuticals capture the steepest expansion trajectory, though pharmaceuticals maintain the highest margin per kilogram.
Formulation Type:
Processing methodology determines oxidative degradation profiles and shelf stability, with spray-drying economics dominating commercial output.
- Spray-Dried Formulations:Continuous atomization and hot-air dehydration produce free-flowing particles with 50-200 micron uniformity. Equipment advances in continuous processing systems are reducing thermal degradation for plant-derived formulations.
- Dry Formulations:Physical blending of lipid fractions with carriers enables cost-competitive positioning in commodity nutrition applications.
- Liquid Formulations:Pre-dispersed lipid concentrates serve industrial-scale food manufacturing with minimal handling requirements.
- Semi-Solid Formulations:Paste concentrates occupy intermediate positioning for bakery and confectionery fat replacement applications.
Spray-dried formulations hold the volume majority, yet dry formulations are expanding most quickly in emerging market dairy fortification.
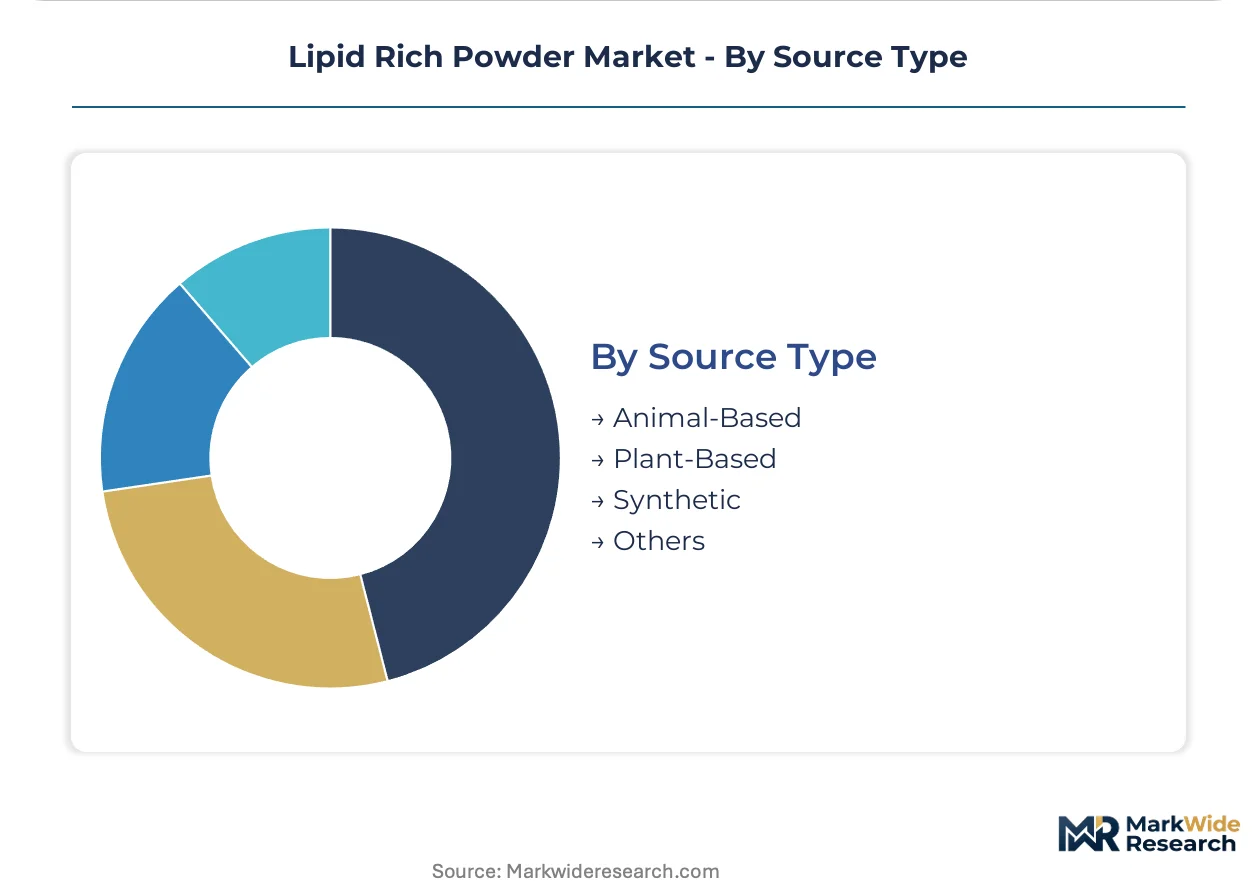
Source Type:
Sustainability credentialing and supply security are restructuring procurement priorities across origin categories.
- Plant-Based:Sunflower lecithin and algal lipid fractions are expanding fastest within novel food approval pathways, though Black Sea supply disruptions create recurring feedstock volatility forcing reformulation cycles.
- Animal-Based:Dairy lipid fractions maintain majority share in infant nutrition where specified fatty acid profiles remain non-negotiable, with complex international sourcing triggering EFSA's steepest blockchain-traceability compliance burden.
- Synthetic:Structured lipids with tailored medium-chain triglyceride compositions serve pharmaceutical applications requiring precise metabolic targeting.
- Others:Fermentation-derived and cell-culture lipids occupy pre-commercial positioning with limited current procurement scale.
Animal-based sources retain the dominant revenue position, while plant-based sources are gaining share fastest on EU Green Deal procurement mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EFSA's novel food assessment pathways anchor European market access timelines, while procurement mandates under the EU Green Deal reshape sourcing documentation requirements across member states. Germany concentrates precision nutrition demand, with clinical dietetics programs driving pharmaceutical-grade specifications at food-sector volumes.
Germany
Precision nutrition startups cluster around Munich and Hamburg, integrating lipid microencapsulation for targeted metabolic interventions. The EU Green Deal procurement mandates require documented sustainable sourcing credentials for institutional nutrition contracts. Bavarian contract manufacturers respond with direct technical service models that bypass traditional distributor relationships.
Netherlands
Nutraceutical formulators adopt structured lipid assemblies combining medium-chain triglycerides with phospholipid shells at accelerated procurement cycles. EFSA's tightening novel food assessment timelines compress formulation-to-market cycles for new entrants. Rotterdam and Amsterdam harbor logistics support plant-based lipid import streams from Black Sea origins.
United States
The FDA's GRAS notification framework determines market access timelines for new lipid ingredients entering functional food applications. Metabolic health platforms consolidate procurement decisions through centralized formulary committees. California and Massachusetts biopharmaceutical manufacturers require dual certification for GMP and food-grade traceability in cell-culture media applications.
India
FSSAI's streamlined novel food approval pathway opens access for structured lipid powders in mass-market dairy fortification. Dairy cooperatives in Gujarat and Maharashtra expand procurement of spray-dried whole milk powders for clean-label positioning. Mumbai and Delhi-NCR functional food processors drive dry formulation demand for cost-competitive nutrition applications.
China
SAMR's evolving food safety standards shape import requirements for lipid-rich powder formulations entering infant nutrition segments. Yangtze River Delta processors invest in continuous spray-drying equipment to reduce oxidative degradation during powder formation. Shanghai and Hangzhou precision nutrition ventures experiment with algal lipid fractions within novel food approval pathways.
Lipid Rich Powder Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, creating a tiered structure where proprietary emulsification capabilities separate premium-positioned suppliers from commodity processors. The market consolidates around integrated oilseed processors, advanced emulsification technology providers, and flavor-masked lipid system specialists. Dominant competitive moves include backward integration into raw material sourcing and strategic partnerships with metabolic health platforms for direct-to-clinician distribution channels.
Among integrated agribusiness operators, Cargill exemplifies the archetype of captive supply control over oilseed processing networks. BASF SE and Kerry Group plc occupy positions within the technology-driven tier, representing differentiated approaches to formulation science. These three anchors illustrate how scale economics, advanced emulsification capabilities, and flavor-system integration define distinct competitive vectors without overlapping positioning.
| Leading Market Players |
|---|
| Cargill |
| BASF SE |
| Archer Daniels Midland Company |
| DSM-Firmenich |
| Croda International Plc |
| Kerry Group plc |
| Royal FrieslandCampina |
| FMC |
| Algavia |
| Others |
Supply & Pricing Matrix
REACH chemical registration requirements for synthetic lipid intermediates gate both supplier qualification and price differentiation simultaneously, forcing ingredient manufacturers to absorb compliance costs or exit premium certification tiers entirely. EFSA's novel food assessment timelines compound this dynamic by extending commercialization cycles and concentrating pricing power among incumbent suppliers with established dossiers.
Pricing Analysis
German precision nutrition startups pay 15-25% premiums over standard food-grade lipid powders for pharmaceutical-grade specifications, while Indian dairy fortification buyers negotiate aggressively on dry formulation commodities. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and encapsulation efficiency, with microencapsulated formats commanding the highest positioning. Cost compression in spray-dried plant-based segments intensifies because Black Sea sunflower lecithin supply disruptions force emergency sourcing at elevated spot rates. Functional beverage manufacturers in Bavaria demonstrate least price sensitivity due to elimination of downstream processing steps, whereas mass-market dairy processors in Gujarat exhibit highest sensitivity to per-kilogram input costs.
Supply Chain Analysis
Black Sea sunflower lecithin transit through Rotterdam and Amsterdam harbor logistics underwrites European plant-based lipid powder availability, creating systemic vulnerability to regional conflict and weather disruptions. Raw material sourcing concentrates in Germany, the Netherlands, and India, with formulation processing anchored in Bavarian contract manufacturing clusters. Phospholipid feedstock, modified starch carriers, and spray-drying equipment components constitute critical input dependencies. Single-source vulnerability runs through Ukrainian-origin sunflower lecithin, where substitution requires 6-12 month reformulation cycles. Distribution runs through direct technical service models that bypass traditional ingredient distributors for metabolic health platforms, while commodity volumes flow through established food ingredient distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Procurement consolidation among metabolic health platforms and precision nutrition startups is shifting bargaining power toward buyers, compressing distributor margins and forcing suppliers into direct technical service relationships.
For Market Incumbents: Shield margin pools in microencapsulated formats by deepening captive supply of phospholipid feedstocks through backward integration into Black Sea alternative sourcing networks. Accelerate EFSA novel food dossier submissions for algal lipid fractions before assessment timelines tighten further. Prioritize certification investment in dual GMP-food-grade traceability to capture cell-culture media applications from biopharmaceutical manufacturers. For New Entrants and Emerging Players: Direct-to-clinician distribution capabilities represent the service-layer gap where incumbents under-serve, offering rapid formulation iteration cycles that bypass traditional distributor relationships. Target metabolic health platforms in Munich and Hamburg with specialized lipid microencapsulation for targeted metabolic interventions. Enter through partnership-based go-to-market angles with Bavarian contract manufacturers rather than building captive production capacity. For Investors and Strategic Acquirers: EFSA's evolving sustainability substantiation guidance reshapes the acquisition landscape by elevating blockchain-traceable supply chain documentation from competitive advantage to compliance necessity. Long-term viability across the 5-10 year window favors suppliers with integrated oilseed processing networks and established novel food approval pathways. Monitor FSSAI's streamlined approval pathway in India as the signal to watch for mass-market dairy fortification inflection.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alternative Phospholipid Sourcing | Reduces Black Sea supply disruption exposure for European manufacturers. |
| Dual GMP-Food-Grade Certification Investment | Captures biopharmaceutical cell-culture media applications requiring traceability. |
| Direct Technical Service Model Deployment | Bypasses traditional distributors for metabolic health platform partnerships. |
| Blockchain-Traceable Supply Chain Documentation | Satisfies EFSA sustainability substantiation requirements for EU Green Deal procurement. |
| FSSAI Novel Food Dossier Preparation | Opens access to India's mass-market dairy fortification growth trajectory. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with lipid formulation chemists, nutraceutical procurement managers, contract manufacturing executives, and EFSA regulatory affairs specialists; and secondary validation through REACH registration databases, EFSA novel food approval records, FSSAI regulatory circulars, and customs trade data for oilseed and lecithin imports. Bottom-up triangulation across ingredient supplier revenue disclosures and top-down demand modeling from end-use industry consumption patterns ensured cross-verification of market sizing estimates.
Across the analysis window, the forecasting framework modeled volume and value outputs through segmentation by product type, formulation architecture, source origin, and end-use industry compliance tier. CAGRs were derived from regression analysis against historical approval timeline data and procurement volume trends. Industry-specific forecast inputs included EFSA novel food assessment queue lengths and FSSAI approval pathway efficiency metrics.
Underlying assumptions cover sustained EU Green Deal procurement mandate enforcement and stable novel food regulatory frameworks, with deviation risk concentrated in Black Sea geopolitical disruptions and REACH classification shifts for synthetic lipid intermediates. Practitioners should keep alternative scenarios live as phospholipid feedstock sourcing patterns and EFSA sustainability guidance evolve.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oleochemicals
Tall Oil Rosin Market
Oleochemicals
Europe Wax Market
Oleochemicals
US Esters Market
Oleochemicals
Propane-1,2-Diol Esters Of Fatty Acid Market
Oleochemicals
Asia-Pacific Wax Market
Oleochemicals
Candelilla Wax Market
Oleochemicals
Decanoyl Chloride Market
Oleochemicals
Esters Market
Oleochemicals
Disodium Oleamido MIPA Sulfosuccinate Market
Oleochemicals
Enzymatically Interesterified Oils Market
Oleochemicals
Oxo-Octyl Acetate Market
Oleochemicals
Asia-Pacific Algae Omega-3 Ingredient Market
Oleochemicals
Fatty Acid Ester Market
Oleochemicals
Rice Bran Wax Market
Oleochemicals
Petrolatum Market
Oleochemicals
Ethoxylates Market