
 Canada Big Data Analytics in Energy Market | 2026-2036
Canada Big Data Analytics in Energy Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Big Data Analytics in Energy Market Insights
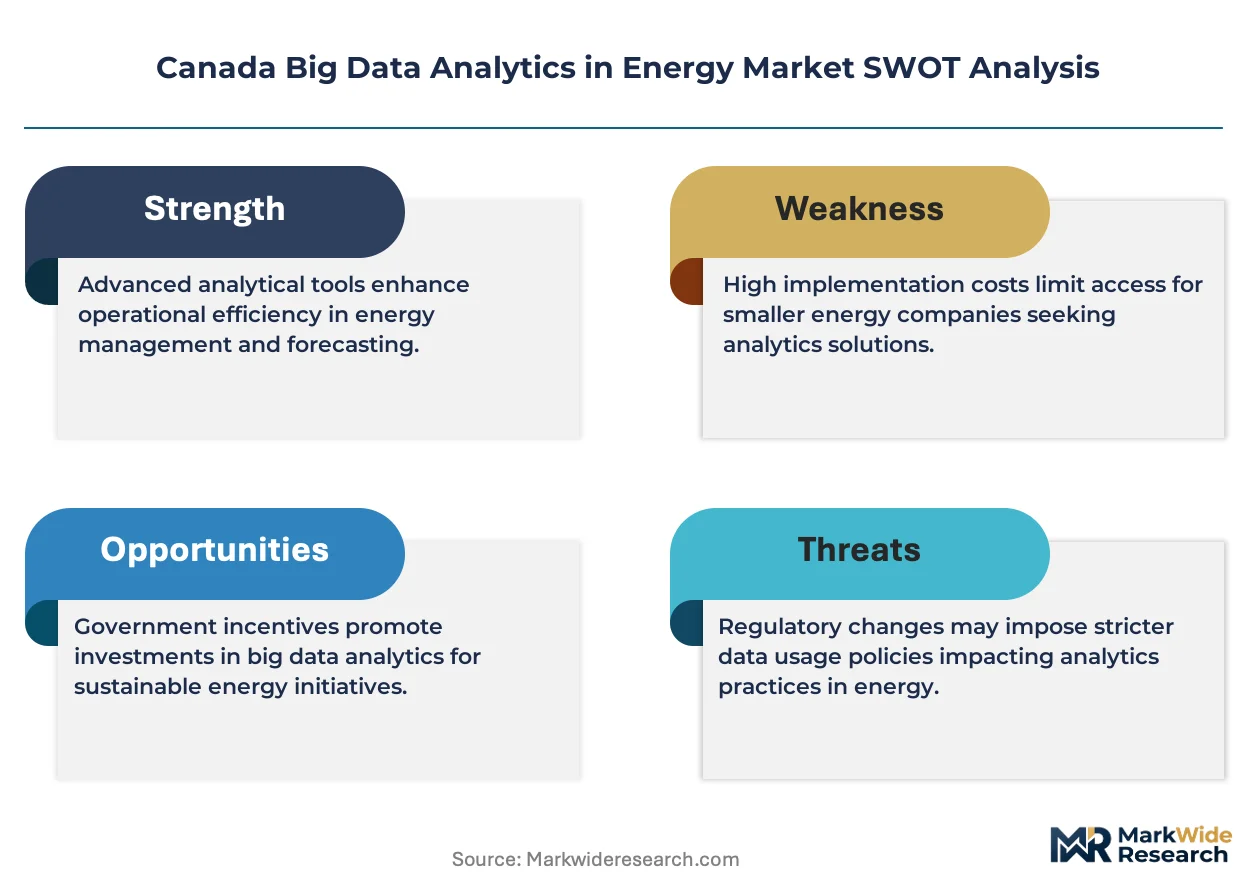
Asset-light SaaS financing is fragmenting competitive barriers across the Canada Big Data Analytics in Energy Market, allowing mid-tier consultancies to challenge legacy vendors without heavy infrastructure commitments. IBM leverages its Watson platform to anchor enterprise-scale deployments at major Canadian utilities, while Microsoft competes through Azure cloud integrations tailored to provincial grid operators. Schneider Electric specializes in edge-to-cloud architectures that sustain long-term service contracts with hydroelectric generators.
Big data analytics in energy encompasses the collection, processing, and algorithmic analysis of high-velocity operational datasets from generation, transmission, and distribution systems, typically involving time-series ingestion rates exceeding one million data points per second from SCADA and AMI networks. The technology enables predictive maintenance, load balancing, and carbon intensity optimization across multi-source power portfolios. Predictive analytics leads current product adoption as utilities confront aging transformer fleets and extreme weather vulnerability, while machine learning platforms represent the fastest-expanding segment as operators train models on decade-long equipment degradation records. Among end users, renewable energy providers command expanding budget share for forecasting tools that synchronize intermittent wind and solar output with provincial dispatch schedules.
Health Canada and PMRA oversee environmental compliance data standards affecting how energy firms report emissions, while provincial regulators like the Alberta Utilities Commission and Ontario Energy Board mandate grid transparency protocols that directly stimulate analytics procurement. The federal Clean Electricity Regulations impose escalating data verification requirements that operators cannot satisfy without upgraded telemetry and analytics stacks. Stakeholders must weigh whether to build proprietary data science teams or outsource to platform vendors as regulatory reporting granularity tightens.
Market Dynamics
The Clean Electricity Regulations are compressing utility infrastructure replacement cycles, forcing asset operators to overlay real-time telemetry onto decades-old SCADA architectures. This regulatory pressure is virtualizing procurement priorities across provincial grids.
Growth Catalysts
- Clean Electricity Regulations:Federal mandates for net-zero grids by 2035 compel utilities to deploy predictive analytics for emissions verification and carbon intensity tracking. Hydroelectric operators in Quebec face binding data transparency requirements.
- AMI network saturation:Advanced metering infrastructure across Ontario and Alberta generates time-series data streams exceeding one million points per second, creating native demand for edge-processing platforms.
- Extreme weather vulnerability:Aging transformer fleets in British Columbia require predictive maintenance algorithms trained on decade-long degradation records to prevent cascade failures during winter demand spikes.
Market Restraints
- Legacy system entrenchment:Provincial utilities operate proprietary SCADA protocols from the 1990s that resist API standardization, fragmenting data lake architectures.
- Specialized talent scarcity:The intersection of power systems engineering and machine learning expertise concentrates in Toronto and Vancouver, creating recruitment bottlenecks for Prairie operators.
- Capital intensity of edge infrastructure:Rural distribution networks in northern Alberta and Saskatchewan require fiber and 5G backhaul investments that strain municipal utility budgets.
Strategic Opportunities
- Indigenous community microgrids:Remote First Nations reserves in northern Ontario and British Columbia lack grid connectivity, creating white space for distributed analytics platforms managing solar-battery hybrid systems.
- Carbon credit verification services:Federal offset protocols create demand for blockchain-anchored analytics that document renewable generation with tamper-evident telemetry.
- Convergence of digital twins and meteorological forecasting:Wind farm operators in Alberta and Nova Scotia seek unified platforms that correlate turbine vibration data with Environment Canada weather models.
Industry Challenges
- Interprovincial data sovereignty friction:Quebec's hydroelectric data residency requirements conflict with cloud architectures hosted in Ontario or US border regions, complicating multi-provincial utility consolidation.
- Cybersecurity certification timelines:Critical infrastructure protection standards from the Canadian Centre for Cyber Security impose 18-24 month approval cycles for foreign-sourced analytics platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Big Data Analytics in Energy Market |
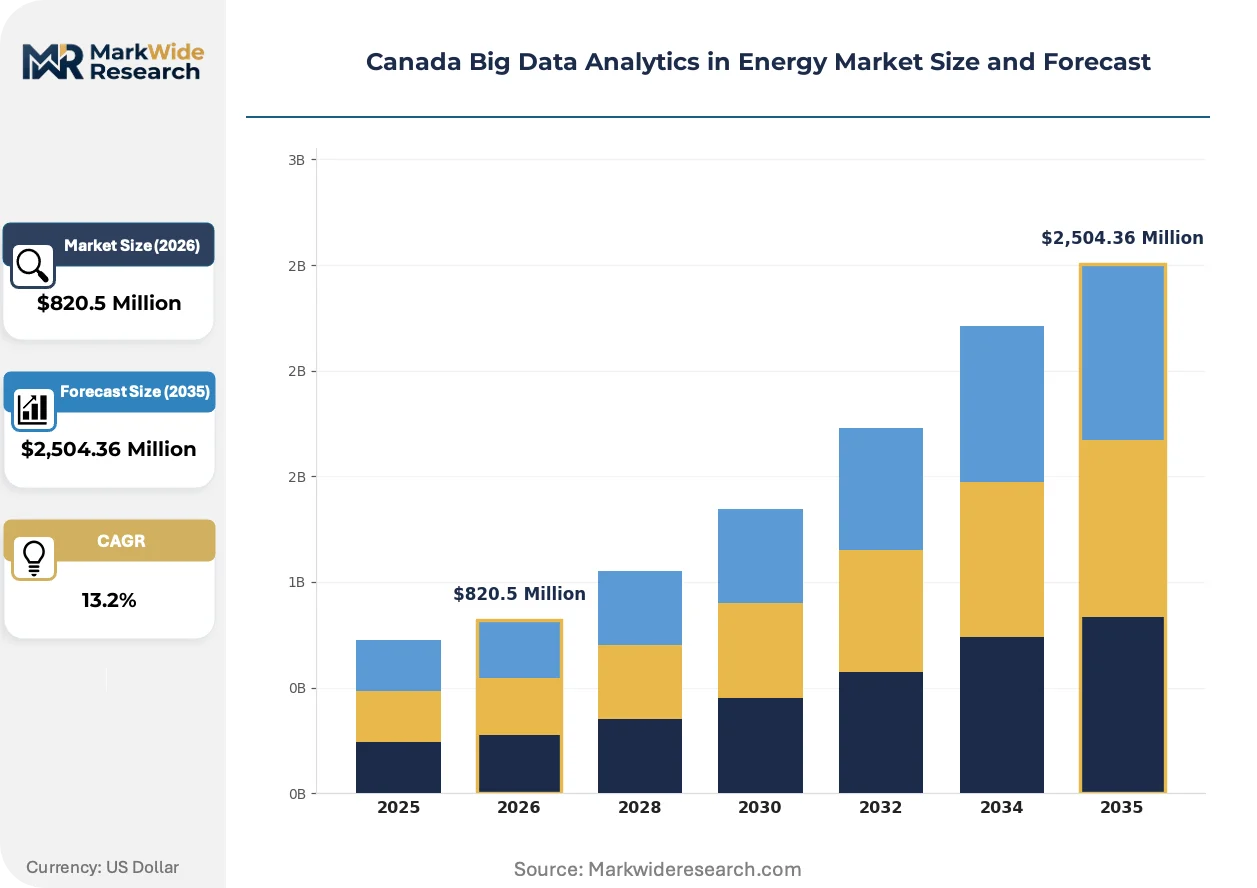
| Market Size in 2026 | $820.5 Million |
| Market Size in 2035 | $2,504.36 Million |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Data Processing, Predictive Analytics, Visualization Tools, Machine Learning Platforms End User: Utilities, Oil & Gas Companies, Renewable Energy Providers, Energy Consultants Application: Demand Forecasting, Asset Management, Risk Assessment, Performance Optimization Technology: Cloud Computing, IoT Integration, AI Algorithms, Data Warehousing |
| Companies Covered | IBM, SAP, Microsoft, Oracle, Schneider Electric, Siemens, GE Vernova, Hydro Quebec, Environics Analytics, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Big Data Analytics in Energy Market Trends and Innovations
Algorithmic forecasting is displacing deterministic dispatch models across Canadian provincial grids. This shift compresses planning horizons and reconfigures how utilities procure software capabilities.
Digital twin platforms are virtualizing asset management workflows for hydroelectric generators in Quebec and British Columbia. BC Hydro and Hydro-Québec deploy these systems to simulate dam structural degradation under varying seasonal flow conditions. The technology is virtualizing traditional preventive maintenance schedules into condition-based interventions that reduce forced outage rates.
Health Canada and PMRA oversight of environmental compliance data standards is tightening granularity requirements for emissions reporting. Energy firms must now submit verified telemetry rather than estimated inventories. Oil sands operators in Alberta face the steepest compliance burden as they retrofit fugitive methane monitoring with continuous analytics feeds.
Subscription-based SaaS procurement is displacing perpetual license models among mid-sized municipal utilities. Ontario's local distribution companies now favor consumption-priced forecasting tools over capital-intensive on-premise deployments. This shift concentrates vendor selection authority within procurement functions rather than IT departments, shortening sales cycles but compressing contract values.
Canada Big Data Analytics in Energy Market Segmentation
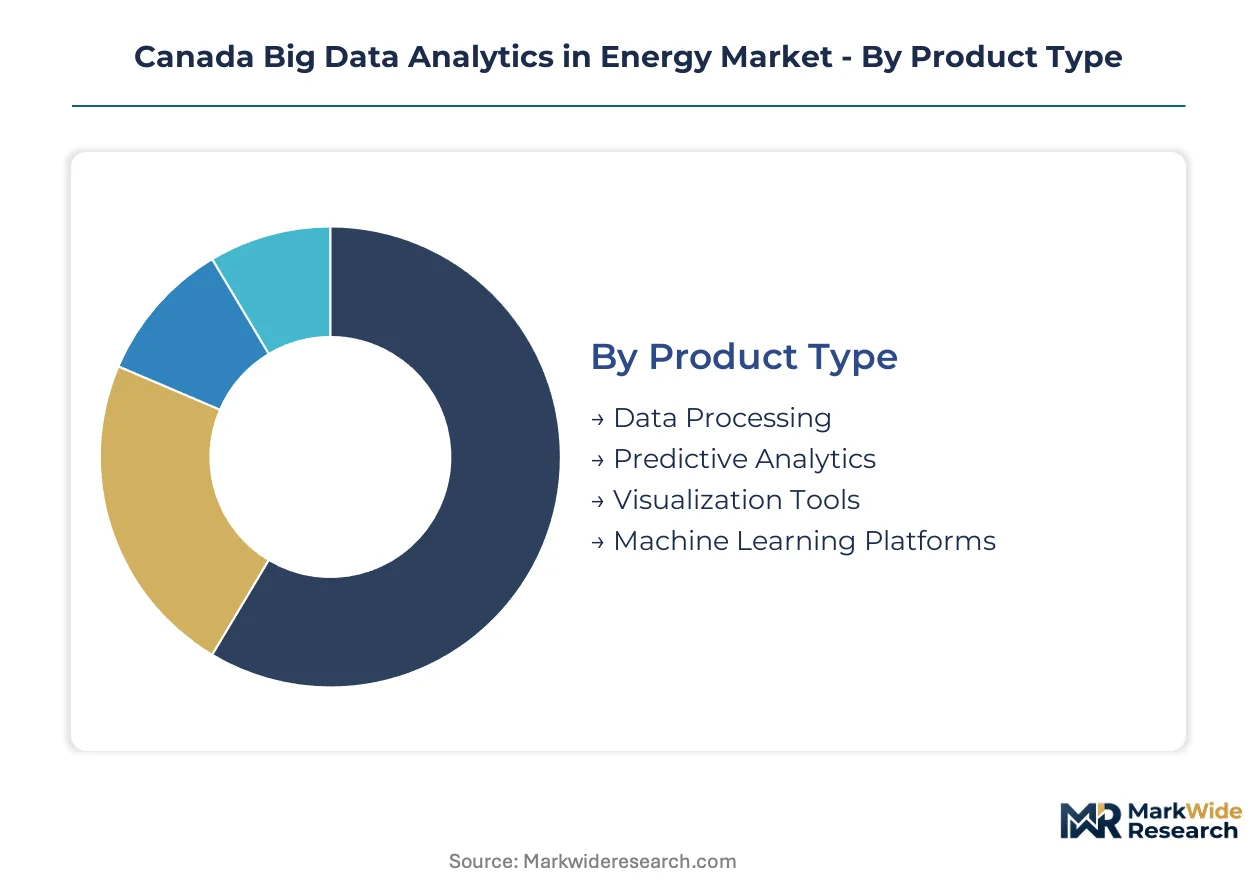
Segmentation in the Canada Big Data Analytics in Energy Market reveals how procurement priorities diverge between legacy grid operators and emerging renewable developers. Each dimension exposes distinct capability requirements that vendors must address through specialized platform architectures.
Product Type:
Mature data processing infrastructure dominates current utility budgets, while machine learning platforms represent the emerging frontier for next-generation grid intelligence.
- Data Processing:High-throughput ingestion engines handle time-series streams exceeding one million points per second from SCADA and AMI networks. Hydroelectric operators in Quebec and British Columbia rely on these systems for real-time reservoir level monitoring and generation dispatch coordination.
- Predictive Analytics:Algorithmic models trained on decade-long equipment degradation records enable condition-based maintenance for aging transformer fleets. Alberta utilities deploy these tools to prevent cascade failures during extreme winter demand spikes.
- Visualization Tools:Dashboard platforms translate complex operational telemetry into dispatch-ready interfaces for control room operators.
- Machine Learning Platforms:Self-optimizing neural architectures are gaining traction among wind farm operators seeking to correlate turbine vibration data with Environment Canada meteorological feeds.
Predictive analytics handles the majority of throughput; machine learning platforms are climbing the fastest on share.
End User:
Customer type segmentation tracks procurement authority shifting from centralized IT departments toward operational line managers with direct asset accountability.
- Utilities:Provincial grid operators across Ontario and Alberta mandate enterprise-scale deployments with stringent Health Canada and provincial regulator compliance protocols. These buyers prioritize edge-to-cloud architectures that sustain long-term service contracts.
- Renewable Energy Providers:Wind and solar developers in Alberta and Nova Scotia command expanding budget share for forecasting tools that synchronize intermittent output with provincial dispatch schedules.
- Oil & Gas Companies:Oil sands operators face steep retrofit burdens as federal offset protocols demand blockchain-anchored emissions verification.
- Energy Consultants:Mid-tier advisory firms leverage asset-light SaaS financing to challenge legacy vendors without heavy infrastructure commitments.
Utilities absorb the dominant procurement volume; renewable energy providers are expanding most quickly as Clean Electricity Regulations tighten.
Application:
Application segmentation exposes how regulatory pressure is virtualizing traditional preventive maintenance schedules into condition-based interventions.
- Asset Management:Digital twin platforms virtualize dam structural degradation under varying seasonal flow conditions for BC Hydro and Hydro-Québec. These systems reduce forced outage rates through simulation-driven maintenance scheduling.
- Demand Forecasting:Algorithmic models displace deterministic dispatch approaches across provincial grids, compressing planning horizons from seasonal to hourly intervals.
- Risk Assessment:Cyber-physical security analytics address Critical Infrastructure Protection standards from the Canadian Centre for Cyber Security with 18-24 month certification timelines.
- Performance Optimization:Carbon intensity tracking tools enable real-time emissions verification mandated by federal Clean Electricity Regulations.
Asset management commands the largest installed base; demand forecasting is gaining share fastest as AMI saturation accelerates.
Technology:
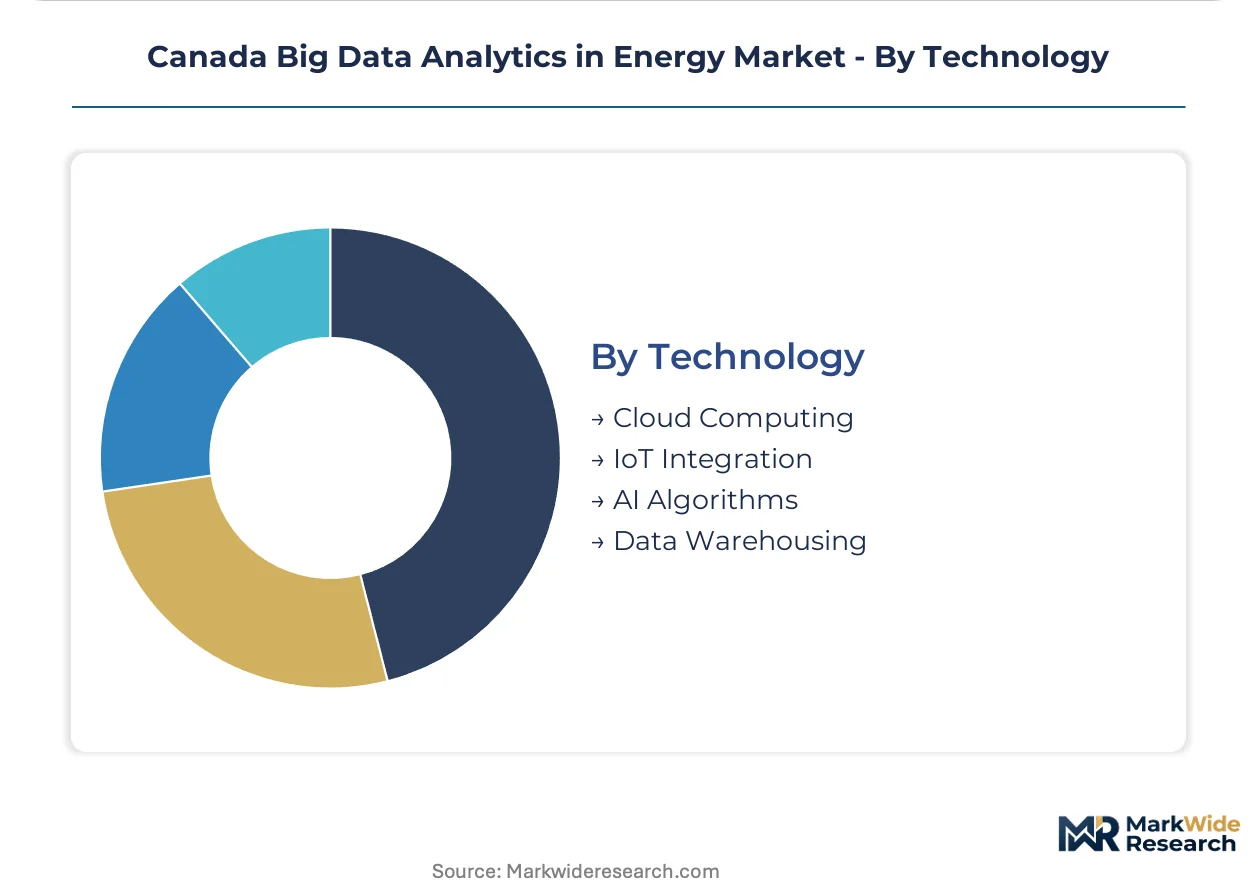
Technology segmentation reveals infrastructure choices constrained by Quebec's data residency requirements and rural connectivity gaps in Prairie provinces.
- Cloud Computing:Azure and Watson deployments anchor enterprise-scale utility contracts, though provincial data sovereignty rules complicate multi-jurisdictional architectures.
- IoT Integration:Edge-processing platforms manage sensor networks across remote First Nations microgrids in northern Ontario and British Columbia.
- AI Algorithms:Neural architectures optimize load balancing across multi-source power portfolios with distributed renewable assets.
- Data Warehousing:Lakehouse architectures consolidate decade-long equipment records for model training and regulatory submission.
Cloud computing underpins the majority of new deployments; IoT integration is expanding most quickly at the distribution edge.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Ontario commands premium pricing for grid analytics contracts compared to Prairie provinces, where municipal utility budgets constrain procurement scope. Quebec's data sovereignty requirements fragment multi-provincial vendor architectures.
Ontario
Advanced metering infrastructure saturation across Toronto and Ottawa generates time-series data streams exceeding one million points per second. The Ontario Energy Board mandates grid transparency protocols that directly stimulate analytics procurement. Hydro One and local distribution companies in the Golden Horseshoe favor consumption-priced SaaS forecasting tools over capital-intensive deployments.
Quebec
Hydro-Québec's dam infrastructure requires digital twin platforms for structural degradation simulation under varying seasonal flow conditions. The province's data residency requirements conflict with cloud architectures hosted in Ontario or US border regions. Montreal-based analytics clusters serve condition-based maintenance contracts for provincial hydroelectric generators.
Alberta
Wind farm operators in southern Alberta seek unified platforms correlating turbine vibration data with Environment Canada meteorological feeds. The Alberta Utilities Commission enforces emissions verification standards that oil sands operators cannot satisfy without upgraded telemetry stacks. Calgary anchors enterprise-scale deployments for predictive maintenance of aging transformer fleets facing extreme winter demand spikes.
British Columbia
BC Hydro deploys edge-to-cloud architectures for real-time reservoir level monitoring across mountainous terrain. Health Canada and PMRA oversight tightens environmental compliance data standards for hydroelectric operators. Vancouver concentrates machine learning expertise for training models on decade-long equipment degradation records.
Atlantic Canada
Wind and tidal energy developers in Nova Scotia command expanding budget share for forecasting tools synchronizing intermittent output with provincial dispatch schedules. Federal Clean Electricity Regulations impose escalating data verification requirements on maritime grid operators. Halifax hosts emerging analytics consultancies serving distributed renewable asset integration.
Canada Big Data Analytics in Energy Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream supplying ingestion engines and visualization modules. The vendor base concentrates around three strategic tiers: cloud hyperscalers anchoring enterprise utility contracts, industrial automation firms with edge-to-cloud service capabilities, and asset-light SaaS consultancies challenging legacy vendors without infrastructure commitments. Dominant competitive moves include strategic partnerships between provincial utilities and platform vendors, plus portfolio diversification into Indigenous community microgrid deployments.
Within the cloud hyperscaler tier, Microsoft and IBM occupy positions anchoring enterprise-scale deployments at major Canadian utilities. Schneider Electric exemplifies the industrial automation archetype with long-term service contracts sustaining hydroelectric generator relationships. These three companies represent distinct competitive vectors: consumption-priced Azure integrations, Watson-platform enterprise anchoring, and edge-to-cloud architecture specialization respectively.
| Leading Market Players |
|---|
| IBM |
| SAP |
| Microsoft |
| Oracle |
| Schneider Electric |
| Siemens |
| GE Vernova |
| Hydro Quebec |
| Environics Analytics |
| Others |
Pricing and Supply Chain Analysis
The Trans-Canada Highway logistics corridor carries edge computing hardware from Vancouver port terminals to Prairie utility depots, with freight cost volatility compressing margins for remote deployment contracts while concentrating procurement authority among Ontario-based aggregators who command volume-based price discounts unavailable to northern Alberta municipal operators.
Pricing Analysis
Industrial OEM buyers anchor subscription-based SaaS pricing across provincial utility markets. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade under Health Canada data residency protocols and customization depth for legacy SCADA integration. Cost compression in the economy tier is intensifying because asset-light consultancies bypass infrastructure commitments. Municipal utilities in Saskatchewan exhibit highest price sensitivity; Hydro-Québec demonstrates lowest sensitivity due to captive data center investments.
Supply Chain Analysis
Tariff exposure between the United States and Canada dominates hardware sourcing decisions for edge infrastructure components. Supply concentrates in the United States, Taiwan, and South Korea for GPU accelerators and fiber optic transmission gear. Raw material dependencies include rare earth elements for sensor magnets, high-purity silicon for chip fabrication, and copper for grid connectivity hardware. Single-source vulnerability persists for quantum-encrypted telemetry modules. Distribution runs through Toronto-based systems integrators who bundle provincial compliance certification with hardware procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Open-source machine learning frameworks threaten incumbent platform vendors with commoditization, forcing proprietary analytics providers to defend subscription renewal rates through regulatory compliance lock-in rather than algorithmic differentiation alone.
For Market Incumbents: Insulate enterprise utility relationships by embedding Clean Electricity Regulations reporting workflows into long-term service contracts. Acquire Indigenous community microgrid specialists to capture federal infrastructure grants. Deepen backward integration into edge hardware manufacturing to reduce exposure to US-China semiconductor tariff volatility.
For New Entrants and Emerging Players: Northern Ontario First Nations reserves lack grid connectivity and represent the most penetrable geography for distributed analytics platforms. Target carbon credit verification services as a wedge application with blockchain-anchored telemetry. Pursue consumption-priced SaaS procurement channels through Ontario Energy Board-mandated transparency protocols.
For Investors and Strategic Acquirers: Asset-light SaaS consultancies with Health Canada compliance certification represent priority acquisition targets. Long-term viability hinges on regulatory reporting granularity tightening rather than technology performance breakthroughs. Monitor Alberta Utilities Commission procurement database for early signals of predictive analytics contract acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Azure and Watson deployments anchor enterprise-scale utility contracts across Ontario and Alberta. |
| Backward Integration | In-house production of edge computing hardware reduces tariff exposure for Prairie network operators. |
| Strategic Partnership | Schneider Electric sustains long-term service contracts with Hydro-Québec through edge-to-cloud architectures. |
| Geographic Expansion | Indigenous community microgrids in northern British Columbia create white space for distributed analytics vendors. |
| Acquisition of Specialist Firm | Carbon credit verification boutiques with blockchain capabilities command premium valuations from oil sands operators. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with utility planning officers, grid operators, IPP project developers, and EPC contractors; and secondary validation against EIA data, IEA reports, provincial regulator filings, and project development databases. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators.
Forecast inputs across the analysis window incorporated deployment model, generation capacity tier, regulatory framework, regional grid type, and provincial data residency requirements. CAGRs derived from algorithmic curve-fitting against historical procurement cycles and policy implementation timelines. Clean Electricity Regulations compliance deadlines and AMI network saturation curves served as primary demand drivers.
Practitioners should monitor federal offset protocol revisions and cybersecurity certification timeline extensions for early signals of demand acceleration. Forecasts reflect documented assumptions about regulatory enforcement intensity and utility capital allocation priorities. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Asia-Pacific Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Power System Analysis Software Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Oil and Gas Data Management Software Market
Energy Analytics and Software
US Big Data Analytics in Energy Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Big Data in Oil and Gas Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market