
 Big Data Analytics in Power Sector Market | 2026-2036
Big Data Analytics in Power Sector Market Size, Share, and Industry Trends Forecast 2026-2036
Big Data Analytics in Power Sector Market Insights
The gap between premium enterprise-grade analytics suites and commodity cloud tools is realigning procurement patterns across power sector buyers. IBM Corporation leverages its hybrid cloud architecture to sustain long-term contracts with regulated utilities requiring on-premise data sovereignty. Siemens AG anchors its position through deep integration with industrial automation hardware, while Palantir Technologies Inc. competes on specialized government and critical infrastructure security clearances.
Big Data Analytics in Power Sector encompasses the collection, processing, and algorithmic interpretation of high-velocity operational data from generation, transmission, and distribution systems to optimize asset performance and grid stability. The discipline applies machine learning models to time-series sensor feeds exceeding terabyte-scale daily volumes, enabling automated fault prediction and dynamic load balancing across heterogeneous generation portfolios. Predictive Maintenance applications command the deepest margin pools due to quantifiable ROI from avoided downtime, while Cloud Analytics deployments are expanding fastest as utilities retire legacy data warehouses. Machine Learning technology leads absolute spending but IoT Analytics is gaining share at the grid edge where latency constraints favor distributed processing.
FERC Order 2222 in the United States enables distributed energy resource aggregation, creating compliance-driven demand for real-time analytics platforms that utilities must deploy to participate in emerging markets. The EU Green Deal and CSRD reporting requirements in Europe mandate granular emissions tracking and grid transparency, forcing asset operators to upgrade data infrastructure. Stakeholders must weigh capital allocation between retrofitting existing SCADA integrations against greenfield cloud-native architectures as regulatory deadlines tighten and cyber insurance underwriters impose stricter data governance conditions.
Market Dynamics
Real-time grid monitoring mandates are compressing procurement cycles for analytics platforms as transmission operators race to comply with hard deadlines for sensor deployment and data interoperability.
Growth Catalysts
- FERC Order 2222:Distributed energy resource aggregation rules in the United States compel utilities to deploy real-time platforms for market participation, creating compliance-driven procurement pipelines.
- IoT edge processing:Latency-sensitive applications at distribution feeders favor distributed analytics architectures, expanding addressable infrastructure beyond centralized data centers.
- German TSO mandates:Transmission system operators face compulsory real-time monitoring requirements, concentrating near-term demand in Europe's largest power market.
Market Restraints
- SCADA integration costs:Retrofitting decades-old supervisory control systems with modern analytics APIs demands specialized engineering talent and extended commissioning timelines.
- Data sovereignty requirements:Regulated utilities in jurisdictions with strict localization rules cannot migrate workloads to hyperscale cloud regions, limiting vendor flexibility.
- Cyber insurance conditions:Underwriters now mandate granular data governance frameworks as prerequisites for coverage, adding compliance overhead to deployments.
Strategic Opportunities
- EU CSRD alignment:Corporate Sustainability Reporting Directive requirements for granular emissions tracking create demand for carbon-accounting modules integrated with operational analytics.
- Digital twin convergence:Physics-based modeling combined with machine learning enables predictive simulation of asset degradation, opening premium service tiers.
- India smart grid programs:Central Electricity Authority directives for urban distribution automation present greenfield deployment opportunities without legacy system drag.
Industry Challenges
- OT-IT security bridging:Analytics platforms must traverse operational technology and information technology domains with diverging security protocols, complicating architecture design.
- Time-series data engineering:Utilities lack sufficient personnel skilled in high-velocity sensor data pipeline construction, constraining platform utilization rates.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Big Data Analytics in Power Sector Market |
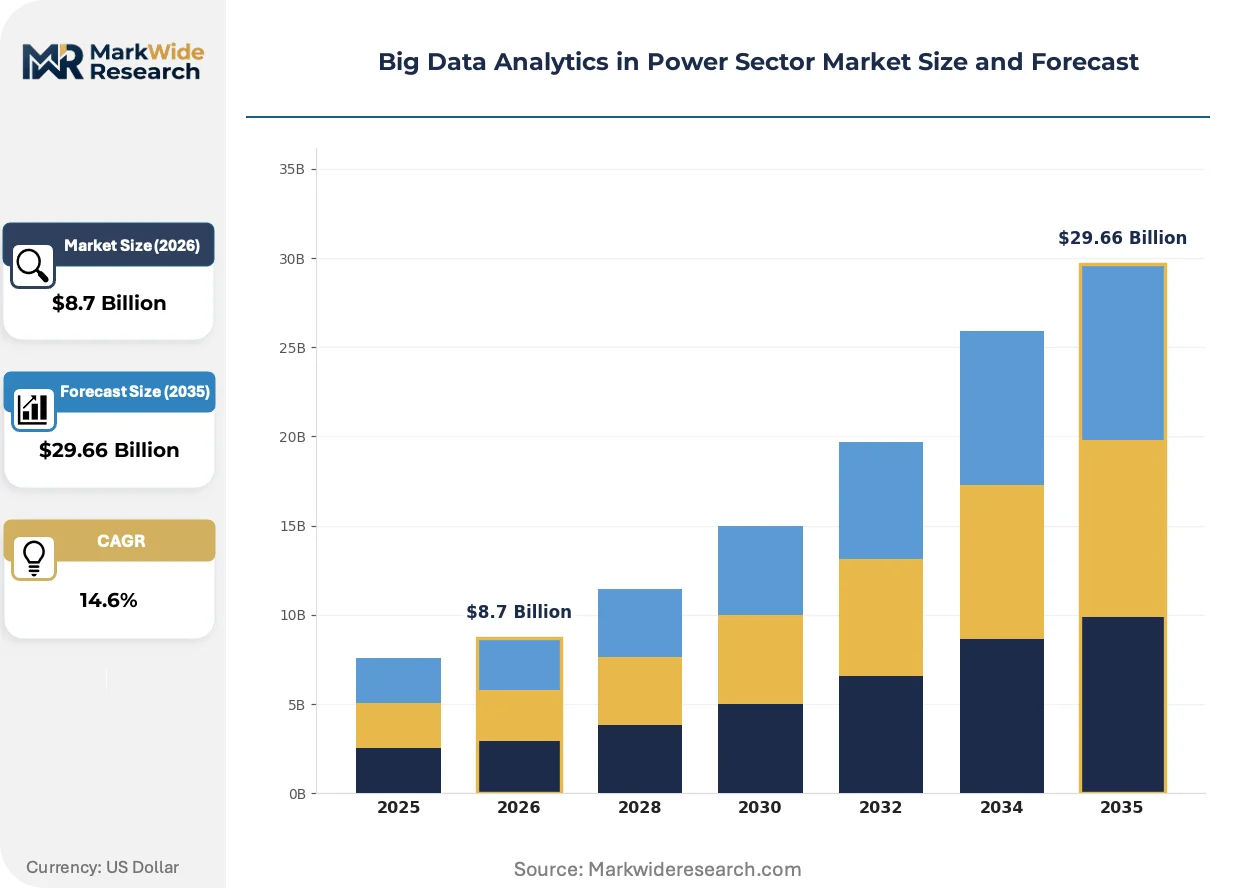
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $29.66 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Application: Predictive Maintenance, Load Forecasting, Asset Management, Demand Response Technology: Machine Learning, Data Warehousing, Cloud Analytics, IoT Analytics End User: Utilities, Independent Power Producers, Industrial Plants, Government Agencies Deployment: On-Premise, Cloud-Based, Hybrid, Edge Computing |
| Companies Covered | IBM Corporation, SAP SE, Microsoft Corporation, Teradata Corporation, Palantir Technologies Inc., Oracle Corporation, Accenture PLC, C3.ai, Inc., Siemens AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Big Data Analytics in Power Sector Market Trends and Innovations
Algorithmic interpretation of grid-edge data streams is restructuring competitive advantage around latency performance and predictive accuracy rather than historical data warehouse scale.
Stream processing architectures are overtaking batch analytics for fault detection applications. These platforms ingest sub-second phasor measurement unit feeds to identify instability precursors before cascading failures propagate. Mid-sized municipal utilities in Texas and California are adopting these systems fastest, compressing the traditional SCADA upgrade cycle from seven years to eighteen months.
The EU Green Deal's digitalization mandates for grid operators are accelerating software procurement cycles. Asset operators must demonstrate real-time transparency to regulators, forcing upgrades to data infrastructure that predates modern API standards. German and French transmission system operators now embed analytics procurement into mandatory network development plans.
Subscription-based platform access is displacing perpetual license models among European distribution utilities. Buyers prefer operational expenditure treatment for analytics capabilities given regulatory uncertainty around cost recovery mechanisms. This shift is most pronounced in Scandinavia where state-owned grid operators face strict public procurement rules favoring service-based contracts.
Big Data Analytics in Power Sector Market Segmentation
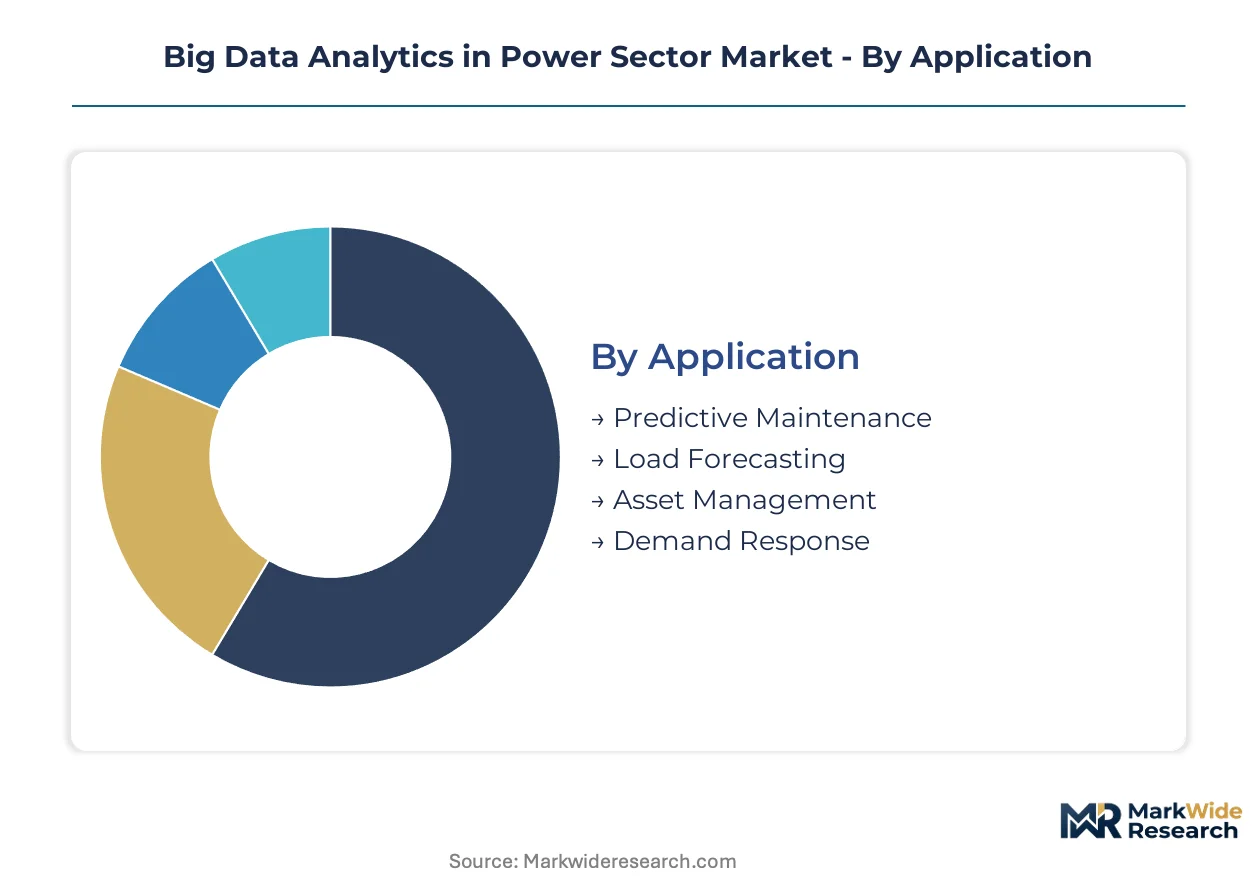
Segmentation in power sector analytics reveals divergent investment priorities between regulated utilities seeking compliance certainty and competitive generators chasing operational alpha. Understanding these fault lines clarifies where vendors must architect for latency, sovereignty, or scale.
Application:
Predictive Maintenance commands premium pricing while Load Forecasting drives volume deployment across rate-regulated territories.
- Predictive Maintenance:Algorithms process vibration, thermal, and dissolved gas analysis signals to forecast transformer and turbine failures before operational impact. German transmission system operators mandate these capabilities under real-time monitoring rules, with procurement concentrated among TenneT and 50Hertz. The quantifiable ROI from avoided outage penalties sustains margin pools above other applications.
- Load Forecasting:Time-series models ingest weather, economic, and behavioral data to optimize dispatch schedules and procurement hedges. Texas municipal utilities deploy these fastest after Winter Storm Uri exposed forecasting gaps, compressing upgrade cycles from seven years to eighteen months. Volume deployment dominates where regulatory cost recovery mechanisms exist.
- Asset Management:Lifecycle optimization platforms integrate condition monitoring with capital planning workflows for generation portfolios.
- Demand Response:Real-time aggregation analytics enable distributed energy resource participation under FERC Order 2222 compliance frameworks.
Today's leader: Predictive Maintenance. Tomorrow's challenger: Demand Response.
Technology:
Machine Learning absorbs the largest absolute spending while IoT Analytics gains share fastest at the grid edge where latency constraints favor distributed processing.
- Machine Learning:Supervised and unsupervised models train on terabyte-scale historical operational datasets for pattern recognition in asset degradation. Palantir Technologies and IBM compete here through specialized security clearances and hybrid cloud architectures respectively. Demand concentrates among US utilities with FERC compliance deadlines and EU operators facing CSRD emissions tracking mandates.
- IoT Analytics:Stream processing architectures ingest sub-second phasor measurement unit feeds for instability precursor detection. Siemens anchors this segment through deep integration with industrial automation hardware at distribution feeders. California and Texas municipal utilities adopt these systems fastest where wildfire and storm resilience priorities override legacy upgrade cycles.
- Data Warehousing:Centralized storage systems for batch analytics and regulatory reporting workloads.
- Cloud Analytics:Hyperscale platforms expanding where data sovereignty rules permit workload migration.
Machine Learning currently dominates vendor R&D allocation. IoT Analytics shows the steepest expansion trajectory as edge deployment economics improve.
End User:
Utilities represent the mature core market while Independent Power Producers exhibit the most elastic demand response to wholesale price volatility.
- Utilities:Regulated grid operators with mandatory compliance deadlines and cost-recovery mechanisms for infrastructure investments. German TSOs embed analytics procurement into network development plans under EU Green Deal digitalization mandates.
- Independent Power Producers:Competitive generators optimizing dispatch and maintenance scheduling against merchant power prices. Texas and California IPPs show fastest adoption where market participation rules reward real-time operational agility.
- Industrial Plants:Cogeneration and captive power facilities seeking demand charge optimization and reliability improvements.
- Government Agencies:Research laboratories and policy bodies requiring grid transparency for market design and security assessment.
Deployment concentration tilts toward Utilities. Independent Power Producers represent the highest-beta expansion opportunity as wholesale market complexity increases.
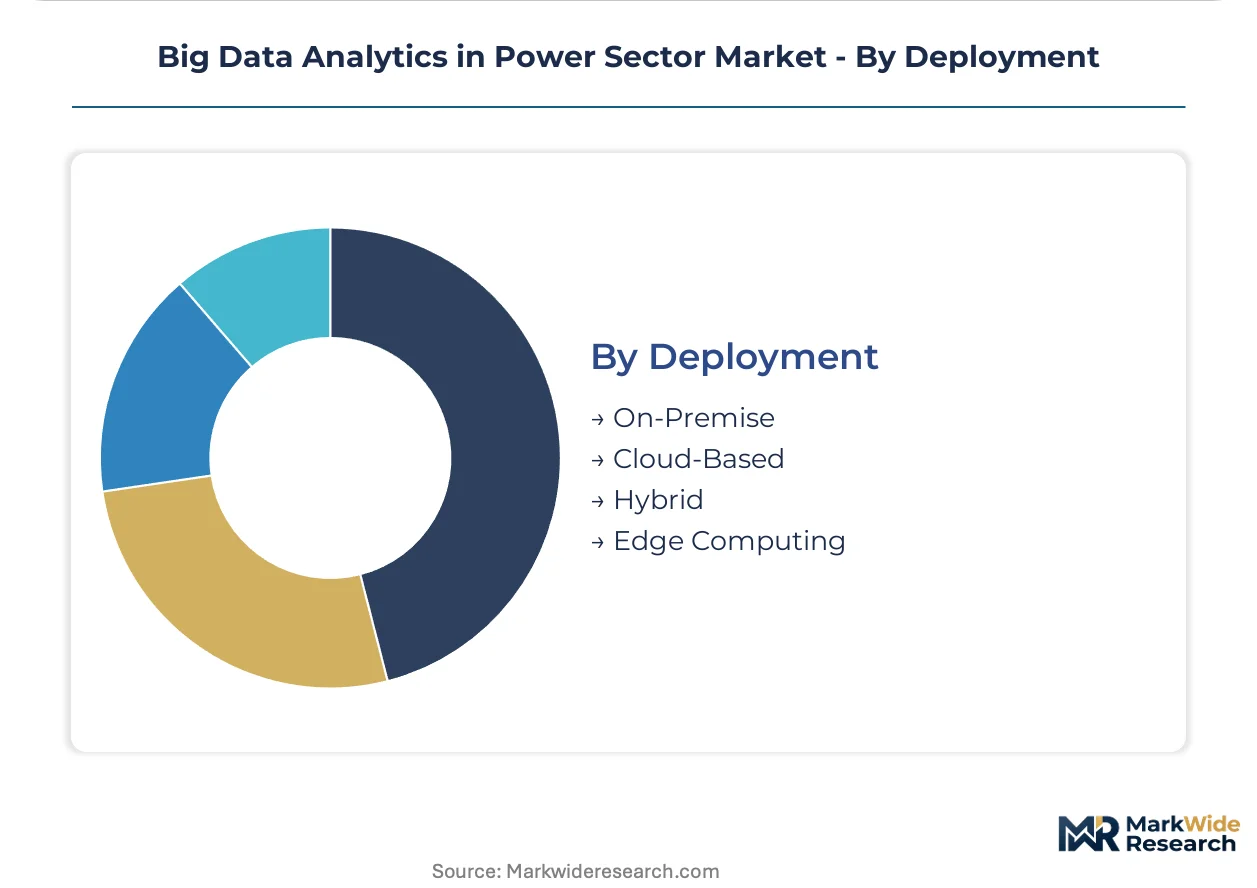
Deployment:
On-Premise retains dominance in jurisdictions with strict data localization while Hybrid architectures emerge as the practical compromise for multi-jurisdictional operators.
- On-Premise:Sovereignty-compliant installations for regulated utilities in Germany, France, and US states with sector-specific privacy rules. Cyber insurance underwriters increasingly mandate granular data governance frameworks as coverage prerequisites, reinforcing preference for controlled environments.
- Hybrid:Workload-splitting between edge, private data center, and selective cloud burst capacity. Scandinavian state-owned grid operators favor this model under strict public procurement rules that prefer operational expenditure treatment.
- Cloud-Based:Full hyperscale deployment where regulatory frameworks permit and latency requirements allow.
- Edge Computing:Distributed processing at substations and distribution feeders for sub-100ms response applications.
Hybrid deployments are gaining share fastest as utilities navigate between sovereignty constraints and cloud economics. Edge Computing represents the next architectural frontier as grid-edge sensor density increases.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data engineering talent clusters in Germany's industrial regions anchor European demand for power sector analytics platforms. Transmission system operators in TenneT and 50Hertz territories face mandatory real-time monitoring deadlines. Procurement velocity concentrates where regulatory compliance intersects with technical workforce availability.
United States
Texas municipal utilities and California wildfire mitigation programs drive fastest adoption of grid-edge analytics. FERC Order 2222 compels distributed energy resource aggregation platforms for market participation. Houston and Austin clusters compress SCADA upgrade cycles from seven years to eighteen months as storm resilience priorities override legacy timelines.
Germany
TenneT and 50Hertz transmission operators embed analytics procurement into mandatory network development plans under EU Green Deal digitalization mandates. The country's national energy regulator enforces real-time transparency requirements for grid stability monitoring. Bavarian and North Rhine-Westphalian industrial zones concentrate predictive maintenance deployments for transformer and turbine fleets.
India
Central Electricity Authority directives for urban distribution automation create greenfield deployment opportunities without legacy system constraints. The country's national power sector regulator mandates smart metering rollout timelines for state distribution companies. Maharashtra and Gujarat industrial corridors attract analytics vendors targeting captive power optimization for manufacturing clusters.
United Kingdom
Ofgem's RIIO-2 price control framework incentivizes network operators to demonstrate digitalization outcomes for cost recovery. The country's national energy regulator embeds data transparency requirements into distribution network operator licenses. London and Southeast England transmission hubs concentrate spending on cloud-native architectures where sovereignty rules permit workload migration.
Japan
METI's carbon neutrality roadmap accelerates grid modernization investments for renewable integration analytics. The country's ministry of economy, trade and industry funds demonstration projects for AI-enabled demand forecasting. Tokyo and Kansai metropolitan area utilities deploy machine learning platforms for load balancing across heterogeneous generation portfolios.
Big Data Analytics in Power Sector Market Competitive Landscape
Capital-heavy producers compete with asset-light designers across the power sector analytics market. The vendor base stratifies between integrated industrial conglomerates with captive hardware ecosystems and specialized software pure-plays selling modular subscriptions. Three archetypes dominate: hybrid cloud architects serving sovereignty-constrained utilities, edge analytics specialists bundling sensor hardware with stream processing, and government-cleared platforms targeting critical infrastructure security mandates. Competitive moves concentrate on strategic partnerships bridging OT-IT security domains and portfolio diversification into carbon accounting modules.
Within the hybrid cloud tier, IBM Corporation and Microsoft Corporation occupy positions anchored by data sovereignty compliance architectures for regulated utilities. Siemens AG exemplifies the integrated hardware-software archetype through deep industrial automation linkages at distribution feeders. Palantir Technologies Inc. sits within the security-cleared specialist tier, representing platforms competing on specialized government and critical infrastructure access credentials.
| Leading Market Players |
|---|
| IBM Corporation |
| SAP SE |
| Microsoft Corporation |
| Teradata Corporation |
| Palantir Technologies Inc. |
| Oracle Corporation |
| Accenture PLC |
| C3.ai, Inc. |
| Siemens AG |
| Others |
Pricing and Supply Chain Analysis
EU Green Deal digitalization mandates gate qualified supply and premium-tier pricing access for power sector analytics vendors, as transmission system operators in Germany and France embed software procurement into mandatory network development plans with hard compliance deadlines. Sovereignty-compliant on-premise deployments command margin premiums over commodity cloud alternatives where data localization rules apply.
Pricing Analysis
Bundled hardware-software service splits from Siemens AG and unbundled SaaS tiers from IBM Corporation define the competitive pricing landscape. Three-tier pricing structure across enterprise-grade, mid-market, and entry-level deployments separates regulated utilities with cost-recovery mechanisms from municipal operators facing budget constraints. Cost compression in entry-level tiers is intensifying because hyperscalers are pushing consumption-based models into distribution utility segments. Independent power producers in Texas and California exhibit highest price sensitivity due to merchant power margin volatility, while German transmission system operators show lowest sensitivity given mandatory procurement timelines.
Supply Chain Analysis
Single-source vulnerability sits with Taiwan-based semiconductor fabrication for industrial-grade edge processors deployed at distribution feeders. Hardware component sourcing draws from Germany, Japan, and the United States for precision sensor manufacturing, while cloud infrastructure rests on hyperscale data center concentration in Ireland, the Netherlands, and Virginia. Tariff exposure on industrial automation hardware imported from China complicates total cost of ownership calculations for European utilities. Distribution runs through systems integrators with OT-IT security bridging capabilities, extending sales cycles but ensuring deployment compliance with cyber insurance underwriter mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a stable compounder where regulatory compliance deadlines across multiple jurisdictions create non-discretionary procurement pipelines with predictable renewal characteristics.
For Market Incumbents: Extend predictive maintenance platform capabilities into carbon-accounting modules aligned with EU CSRD reporting requirements, defending against specialized pure-plays entering from adjacent sustainability software markets. Deepen edge analytics hardware integration to capture IoT deployment growth at distribution feeders where latency constraints favor bundled offerings. Vertical integration into OT-IT security certification services creates switching costs against modular competitors. For New Entrants and Emerging Players: Cloud-native deployment routes targeting Indian state distribution companies under Central Electricity Authority smart grid directives offer greenfield penetration without legacy SCADA integration drag. Municipal utilities in Texas and California represent the most penetrable buyer segment given compressed eighteen-month upgrade cycles and wildfire resilience procurement urgency. Partner with regional systems integrators possessing FERC compliance expertise to accelerate sales velocity. For Investors and Strategic Acquirers: Roll-up economics work for mid-sized IoT analytics specialists because buyer preference for subscription-based operational expenditure treatment favors recurring revenue consolidation plays. Five-to-ten year viability hinges on platform differentiation around sub-100ms latency performance rather than historical data warehouse scale. Watch German TSO procurement acceleration as the inflection indicator for European demand expansion.| Strategic Initiative | Industry Significance |
|---|---|
| Platform Integration | Combining predictive maintenance with CSRD carbon-accounting modules addresses EU Green Deal compliance bundling. |
| Strategic Partnership | OT-IT security bridging alliances with cyber insurance underwriters reduce deployment friction for regulated utilities. |
| Geographic Expansion | India smart grid programs offer greenfield deployment without legacy SCADA retrofit constraints. |
| Acquisition of Specialist Firm | Edge analytics hardware targets latency-sensitive applications at California wildfire mitigation programs. |
| Product Launch | Stream processing architectures for sub-second phasor measurement unit feeds target Texas storm resilience priorities. |
Research Methodology
Bottom-up utility procurement modeling reconciled against top-down vendor shipment tracking forms the analytical core of this study. Primary interviews with utility planning officers, IPP project developers, grid operators, and EPC contractors combined with secondary validation from FERC filings, EIA data, IEA reports, and EU network development plan disclosures. Triangulation across bottom-up segment builds and top-down macro constraints ensures internal consistency.
Historical trendline analysis of software procurement cycles and sensor deployment velocities anchors the projection framework. Segmentation dimensions modeled include deployment architecture, application type, technology stack, and end-user regulatory framework across the analysis window. CAGRs derive from regression-adjusted adoption curves incorporating FERC Order 2222 compliance deadlines and EU Green Deal digitalization mandates as structural demand drivers.
Regulatory deadline slippage, cyber insurance condition tightening, and OT-IT security talent scarcity are the dominant revision risks that could compress or extend forecast outcomes. Forecasts reflect documented assumptions about compliance enforcement intensity and cloud sovereignty rule evolution. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Italy Big Data Analytics in Energy Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
France Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Oil Condition Monitoring Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Energy As a Service (Eaas) Market
Energy Analytics and Software
Solar Analyzer Market
Energy Analytics and Software
Carbon and Energy Software Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Predictive Maintenance in the Energy Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market
Energy Analytics and Software
Energy Intelligence Solutions Market