
 Energy As a Service (Eaas) Market | 2026-2036
Energy As a Service (Eaas) Market Size, Share, and Industry Trends Forecast 2026-2036
Energy As a Service (Eaas) Market Intelligence
Demand within the Energy as a Service model is rotating from single-site manufacturing plants toward multi-location commercial facilities and data center operators. Schneider Electric leverages its digital twin and microgrid expertise to serve these complex portfolios. Siemens differentiates through its comprehensive energy management platforms for smart buildings and critical infrastructure. Engie competes by offering integrated solutions that combine renewable energy supply with long-term efficiency guarantees for large corporate clients.
Energy as a Service (EaaS) is a delivery model that bundles hardware, software, and operational services into a subscription-based contract. Its primary function is to deliver specified energy outcomes, such as kilowatt-hour savings or power reliability, backed by performance guarantees. Within service types, efficiency optimization and energy management form the foundational offerings for most contracts. Renewable integration and energy storage services represent the fastest-growing segments, driven by corporate sustainability goals and grid resilience needs.
Regulatory frameworks like the EU's Corporate Sustainability Reporting Directive (CSRD) and the US Inflation Reduction Act (IRA) create direct incentives for adopting EaaS models. These policies, along with China's dual carbon goals, compel organizations to improve energy efficiency and document their carbon footprint, which EaaS providers facilitate. The critical decision for end-users now involves selecting EaaS partners based on their ability to navigate complex regulatory landscapes and guarantee long-term performance outcomes.
Market Dynamics
The convergence of corporate decarbonization goals with the rising need for energy resilience is the central force shaping the Energy as a Service market. Regulatory frameworks like the EU Green Deal and the US IRA are compelling large energy users to seek guaranteed outcomes through outsourced service models.
Growth Catalysts
- Regulatory Mandates:The EU's Corporate Sustainability Reporting Directive (CSRD) and China's dual carbon goals require rigorous documentation of energy use and emissions, driving demand for EaaS providers who can deliver and verify efficiency improvements.
- Data Center Expansion:Hyperscale data center operators, for whom power reliability and cooling efficiency are paramount, are primary adopters of EaaS contracts that guarantee uptime and Power Usage Effectiveness (PUE) targets.
- Microgrid Proliferation:Decreasing costs of distributed energy resources (DERs), including solar PV and battery storage, make on-site generation economically attractive, with EaaS models managing the complexity of these assets for commercial clients.
Market Restraints
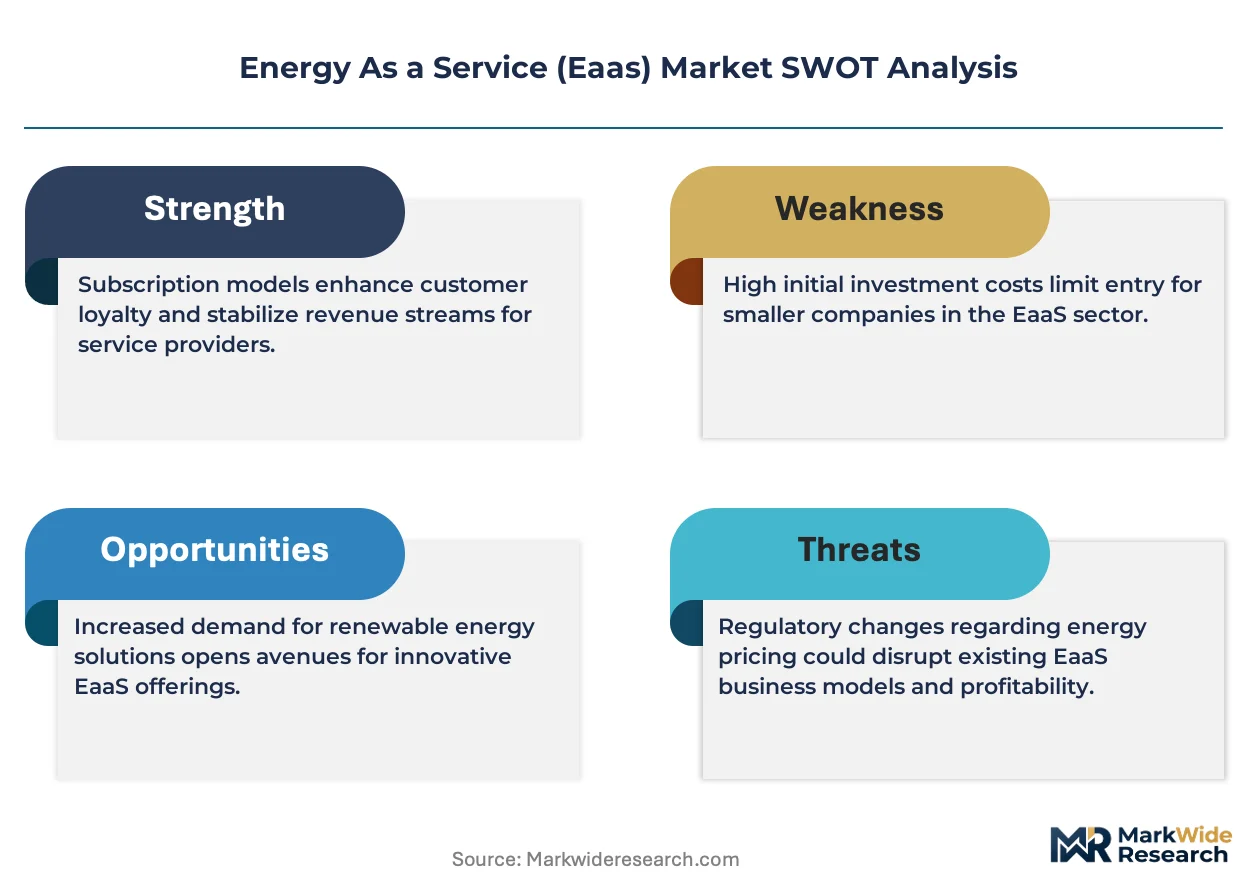
- High Upfront Capital:The significant initial investment required for energy hardware, such as new chillers or combined heat and power units, remains a financial hurdle for EaaS providers, complicating contract pricing and access for smaller clients.
- Contractual Complexity:Negotiating long-term, performance-based contracts with detailed service level agreements is a time-consuming and legally intensive process, creating friction and extending sales cycles for both providers and customers.
- Legacy System Integration:Interfacing modern EaaS platforms with clients' existing, often outdated, building management systems and operational technology infrastructure poses significant technical, security, and interoperability challenges.
Strategic Opportunities
- EV Fleet Electrification:The corporate and municipal shift to electric vehicle fleets opens a new service frontier for "Charging as a Service," bundling infrastructure deployment, energy management software, and electricity procurement.
- Southeast Asian Industrial Hubs:Rapidly industrializing economies in Vietnam, Thailand, and Indonesia face growing energy demand and grid constraints, creating a strong business case for EaaS solutions focused on resilience and efficiency.
- AI-Powered Optimization:The integration of artificial intelligence and machine learning into energy management platforms enables predictive analytics for load forecasting and autonomous control, creating opportunities for premium, high-performance service tiers.
Industry Challenges
- Skilled Workforce Scarcity:A persistent shortage of professionals with combined expertise in energy engineering, data science, and complex financial modeling constrains the ability of providers to scale the design and execution of sophisticated EaaS projects.
- Performance Verification Standards:The lack of a single, universally accepted standard for Measurement and Verification (M&V) of energy savings can lead to disputes over contract fulfillment and complicates performance comparisons between different EaaS vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Energy As a Service (Eaas) Market |
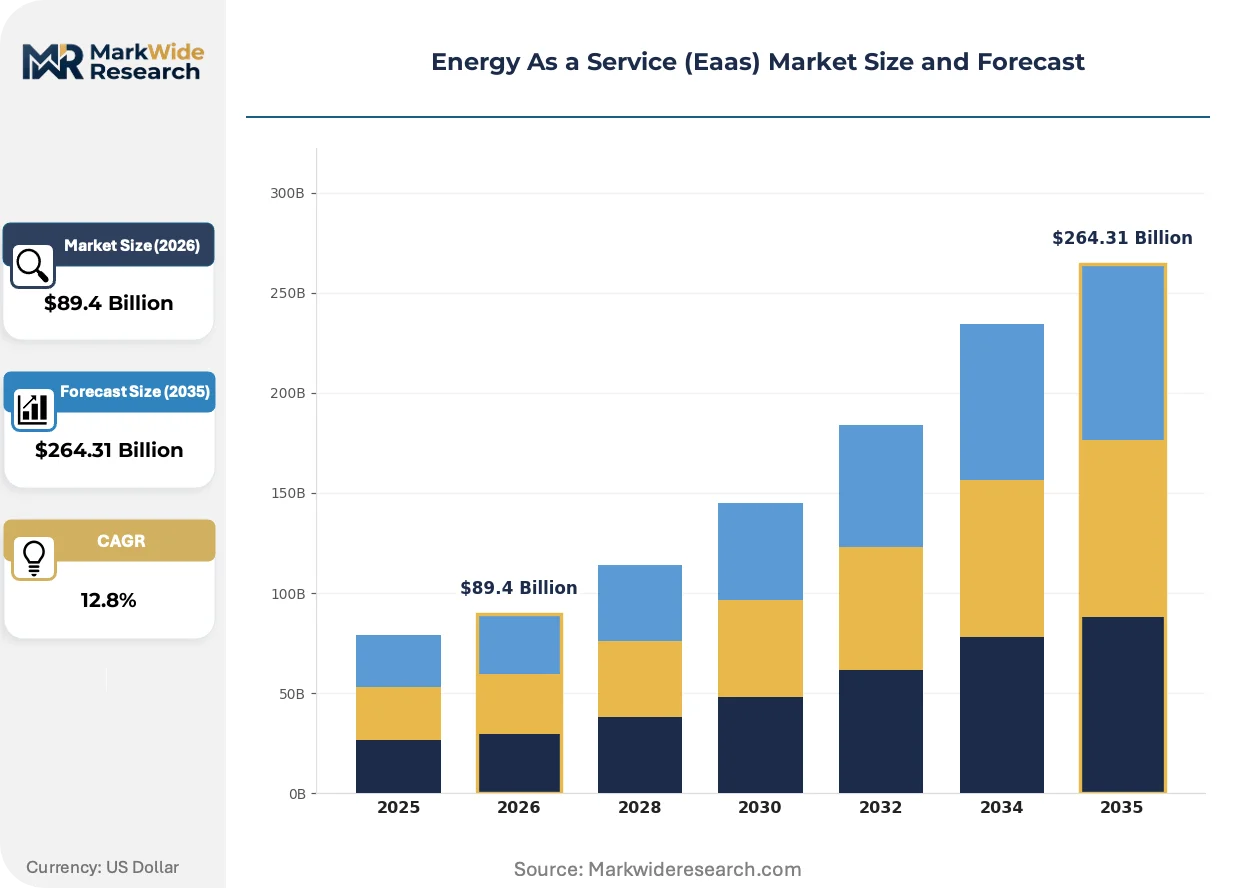
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $264.31 Billion |
| CAGR (2026 – 2036) | 12.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Energy Management, Demand Response, Energy Storage, Renewable Integration, Microgrid Operations, Efficiency Optimization Application: Commercial Facilities, Data Centers, Educational Institutions, Government Buildings, Hospitality, Residential Complexes Deployment Model: On-Premises, Cloud-Based, Hybrid, Edge Computing, Virtual Power Plants, Distributed Energy Resources End User: Manufacturing Plants, Telecommunications, Transportation Hubs, Mining Operations, Agriculture, Public Sector Entities |
| Companies Covered | Schneider Electric, Siemens, Engie, Johnson Controls, Veolia, Honeywell International, General Electric, Ameresco, EDF Energy, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Energy As a Service (Eaas) Market Strategic Shifts & Innovations
The EaaS model is evolving from discrete efficiency projects toward integrated, portfolio-wide energy management partnerships. This transformation is driven by the maturation of digital platforms and mounting regulatory pressure, turning EaaS into a core strategic instrument for large enterprises seeking to manage costs and carbon exposure.
Digital twin technology creates a virtual replica of a physical asset, like a data center or a manufacturing plant, to simulate energy flows and test optimization strategies without physical intervention. Data center operators and industrial facility managers are the primary adopters, using these models to improve cooling efficiency and power reliability. The adoption of digital twins is bifurcating the market between basic efficiency providers and advanced partners offering predictive, simulation-based energy management services.
The US Inflation Reduction Act (IRA) offers substantial tax credits and direct incentives for deploying renewable energy, battery storage, and energy-efficient technologies. This federal policy directly lowers the capital cost for EaaS providers to install these assets as part of a service offering. The commercial and industrial sector is most affected, as providers now actively structure contracts to monetize these credits and pass savings to clients, accelerating clean energy adoption.
A significant demand-side shift is underway from single-asset, single-measure contracts toward enterprise-wide energy management agreements covering entire facility portfolios. Large retail chains, hospital systems, and real estate investment trusts (REITs) are consolidating their energy management with single EaaS partners to achieve standardized reporting and centralized control. This trend is most prominent in North America and Europe, where corporations with extensive geographic footprints prioritize consistent carbon accounting and unified energy strategies.
Energy As a Service (Eaas) Market Segmentation
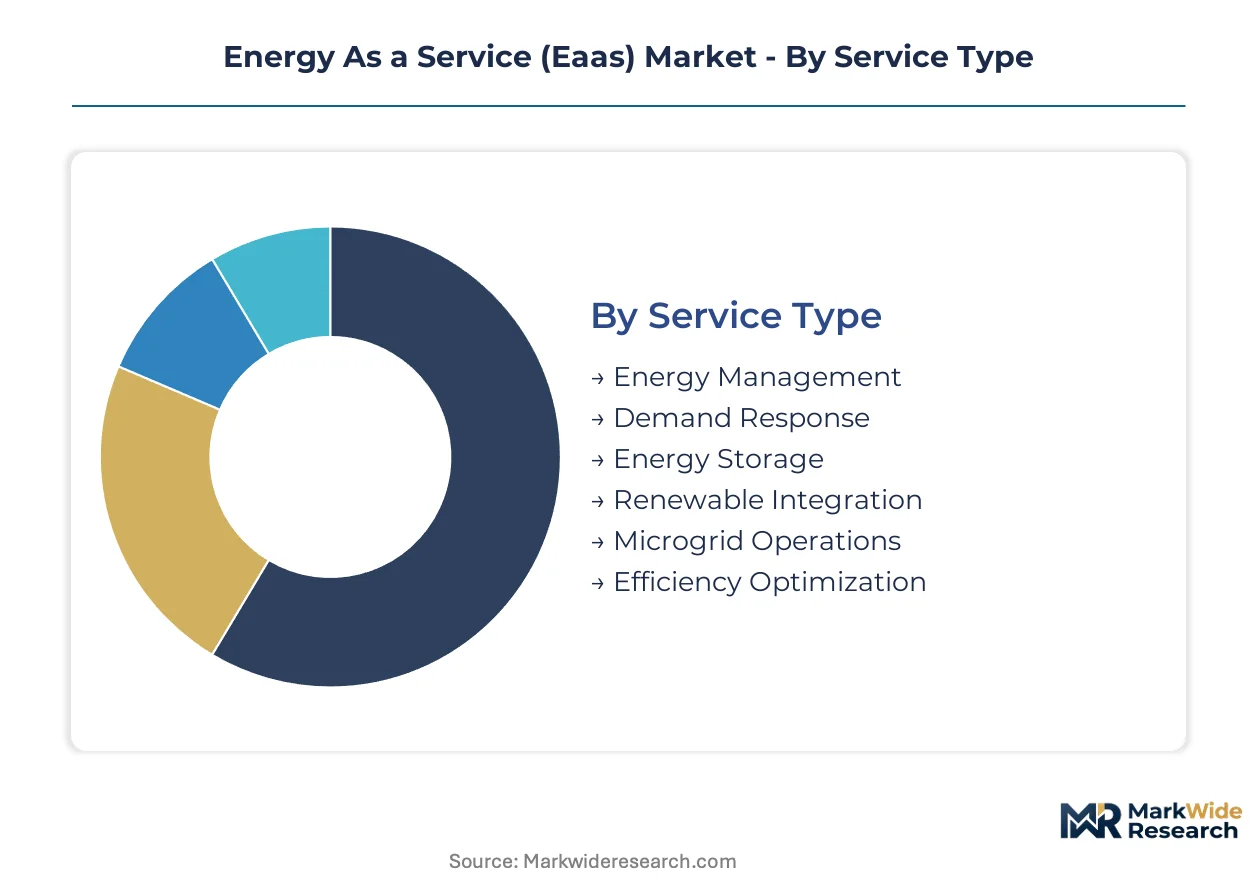
Segmentation within the Energy as a Service market provides critical insight into the diverse needs and operational models driving adoption. Understanding these distinct categories helps providers tailor solutions to specific client requirements, from optimizing existing infrastructure to integrating advanced renewable technologies. Each segment represents a unique demand profile influencing contract structures and service delivery.
Service Type:
The Energy as a Service market channels solutions through distinct service types, each addressing specific client needs for energy efficiency and reliability.
- Renewable Integration:This service incorporates on-site or off-site renewable energy sources, such as solar PV and wind, into a client's energy portfolio. Corporate sustainability goals and grid decarbonization efforts are significantly driving demand in European and North American markets.
- Energy Storage:These services deploy battery storage systems to manage peak demand, provide grid stabilization, and enhance energy resilience for commercial and industrial users. The decreasing cost of lithium-ion batteries makes these solutions increasingly attractive for data centers.
- Energy Management:Providers offer comprehensive platforms and services for monitoring, analyzing, and controlling energy consumption across client facilities.
- Demand Response:This service allows clients to adjust energy consumption during peak periods in exchange for financial incentives, supporting grid stability.
- Microgrid Operations:EaaS providers design, build, and operate localized energy grids that can function independently or connected to the main grid.
- Efficiency Optimization:These services focus on improving the energy performance of existing systems through upgrades, retrofits, and operational adjustments.
Efficiency Optimization dominates the installed base. Renewable Integration is where expansion concentrates.
Application:
Application segments delineate where EaaS solutions find their primary end-user focus and operational impact across various facility types.
- Data Centers:These facilities require highly reliable and efficient power delivery, making EaaS contracts critical for guaranteeing uptime and optimizing Power Usage Effectiveness (PUE) metrics. Hyperscale operators in the United States and Ireland are primary adopters.
- Commercial Facilities:This segment includes multi-location retail, office buildings, and corporate campuses seeking standardized energy management and decarbonization pathways. The EU Green Deal compels many European commercial entities to pursue these outsourced models.
- Educational Institutions:Universities and school districts leverage EaaS for energy cost reduction, infrastructure upgrades, and sustainability reporting.
- Government Buildings:Public sector entities utilize EaaS to meet energy efficiency mandates and reduce operational expenditures across their diverse portfolios.
- Hospitality:Hotels and resorts adopt EaaS to manage energy costs, enhance guest comfort, and improve their environmental footprint.
- Residential Complexes:Multi-family dwellings and planned communities use EaaS for centralized energy management and renewable energy integration.
The market exhibits strong demand from Data Centers while Commercial Facilities represent a significant growth vector.
Deployment Model:
Deployment models reflect the technological sophistication and infrastructural approach for delivering EaaS capabilities to clients.
- Cloud-Based:These models leverage remote servers and internet connectivity for data analytics, energy monitoring, and predictive control of client assets. Digital twin technology often underpins these advanced platforms.
- Distributed Energy Resources:This model integrates on-site generation, such as solar PV, and storage systems directly at the client's location, managed through EaaS contracts. Tax credits from the US Inflation Reduction Act accelerate deployment for commercial clients.
- On-Premises:Energy management hardware and software are installed and operated directly within the client's physical infrastructure.
- Hybrid:This approach combines elements of both on-premises and cloud-based solutions, offering flexibility and enhanced data security.
- Edge Computing:Data processing occurs closer to the energy assets, enabling faster response times for critical control and optimization tasks.
- Virtual Power Plants:Aggregated distributed energy resources are centrally managed to provide grid services, acting as a single, dispatchable power plant.
While On-Premises solutions remain prevalent, Distributed Energy Resources technologies are rapidly gaining traction.
End User:
End-user categories are defined by their operational scale and specific industry requirements for energy management and resilience.
- Manufacturing Plants:Industrial facilities, particularly in Germany and China, seek EaaS to improve energy efficiency, reduce operational costs, and meet stringent decarbonization targets. Their complex processes benefit from guaranteed outcomes.
- Public Sector Entities:Government agencies and municipal operations in Europe and North America adopt EaaS to modernize aging infrastructure, ensure energy security, and comply with public sustainability mandates like CSRD.
- Telecommunications:EaaS solutions ensure continuous power for critical network infrastructure, reducing downtime and operational expenses.
- Transportation Hubs:Airports, ports, and railway stations utilize EaaS for efficient energy management and to support the electrification of their operations.
- Mining Operations:Remote mining sites benefit from EaaS to secure reliable power, often integrating microgrids and renewable energy sources.
- Agriculture:Farms and agricultural facilities deploy EaaS for optimizing irrigation systems, climate control, and cold storage energy use.
Enterprises with complex operational profiles prioritize EaaS solutions for resilience and efficiency gains.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Energy as a Service market sees significant demand originating from developed economies, particularly as European industrial firms seek decarbonization solutions. This demand drives technology and service exports from providers with advanced energy management capabilities. North American entities also contribute substantially, leveraging new federal incentives.
Germany
Germany's industrial and commercial firms actively pursue decarbonization and energy independence through EaaS models. The EU Green Deal and Corporate Sustainability Reporting Directive (CSRD) compel these entities to adopt outsourced energy management. Bavaria's manufacturing sector, in particular, implements EaaS for complex process optimization.
United States
United States demand for EaaS solutions stems from hyperscale data centers and corporate sustainability initiatives. The US Inflation Reduction Act (IRA) provides substantial tax credits, accelerating clean energy deployment for commercial clients. Hyperscale data center operators in Northern Virginia leverage EaaS for guaranteed uptime.
China
China's manufacturing plants seek EaaS for improved energy efficiency and rigorous carbon footprint documentation. The nation's dual carbon goals drive organizations to integrate advanced energy management platforms. Industrial zones within the Yangtze River Delta utilize EaaS to meet stringent environmental targets.
United Kingdom
Across the United Kingdom, multi-location commercial facilities require standardized energy management and decarbonization pathways. Corporate sustainability mandates, influenced by European directives, compel outsourced energy solutions. London's extensive commercial real estate sector adopts EaaS for consistent carbon accounting.
Vietnam
Vietnam's rapidly industrializing economy faces growing energy demand and grid constraints, creating strong EaaS business cases. National energy efficiency policies encourage the adoption of service-based models for resilience. Industrial parks near Ho Chi Minh City increasingly deploy EaaS for on-site generation.
Energy As a Service (Eaas) Market Key Industry Players
Player mix skews toward large industrial technology conglomerates and specialized energy service companies. The market structure exhibits a consolidating trend as established players acquire smaller innovators to expand their digital and technical capabilities. Three strategic archetypes emerge: technology-driven integrators leveraging digital twins, comprehensive platform providers for smart infrastructure, and renewable-focused solution deliverers. Geographic expansion across North America and Europe, alongside portfolio diversification into new service offerings, represents dominant competitive moves for these entities.
Specialists in advanced digital energy management platforms include Schneider Electric, a French multinational company. Schneider Electric exemplifies the technology-driven integrator archetype, leveraging its digital twin and microgrid expertise for complex portfolios. Siemens AG, a German industrial manufacturing giant, occupies a position as a comprehensive platform provider, offering extensive energy management for smart buildings and critical infrastructure. Engie SA, a French utility company, anchors the integrated solution deliverer segment, providing renewable energy supply with long-term efficiency guarantees for large corporate clients across Europe.
| Leading Market Players |
|---|
| Schneider Electric |
| Siemens |
| Engie |
| Johnson Controls |
| Veolia |
| Honeywell International |
| General Electric |
| Ameresco |
| EDF Energy |
| Others |
Cost & Logistics Intelligence
Renewable energy integration, replacing fossil-fuel reliance, reshapes the Energy as a Service supply chain by shifting procurement toward specialized hardware and influencing long-term contract pricing.
Pricing Analysis
Next-generation digital twin platforms command premium pricing compared to legacy efficiency optimization tools. EaaS contracts typically employ a subscription-based model, often incorporating performance-based incentives for specified energy outcomes. Price differentiation stems from the complexity of integrated solutions and the level of performance guarantees provided. Hyperscale data centers exhibit lower price sensitivity for guaranteed uptime, while smaller commercial clients remain highly cost-conscious.
Supply Chain Analysis
Container availability and port congestion on key Asian-European trade lanes impact hardware costs for EaaS providers. The supply of critical components like lithium-ion batteries and solar PV modules concentrates in China, while specialized sensors often originate from Southeast Asia. Geopolitical tensions create single-source vulnerability for advanced microgrid controllers. Downstream distribution primarily runs through direct sales teams and specialized system integrators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Energy as a Service market offers a defensive moat, primarily due to regulatory entrenchment from mandates like the EU Green Deal.
For Market Incumbents: Secure long-term performance-based contracts with multi-location commercial facilities to counter emerging software-only providers. Invest in advanced digital twin capabilities and microgrid integration to deepen customer switching costs. The threat of commoditization for basic efficiency services necessitates continuous innovation. Expand geographic footprint in high-growth regions like Southeast Asia to leverage regulatory incentives.
For New Entrants and Emerging Players: Certification fast-tracks for renewable energy components offer new entrants a path into the EaaS market. Target underserved small and medium-sized industrial clients in Germany seeking decarbonization solutions. Offer AI-powered optimization for existing building management systems, focusing on rapid, verifiable efficiency gains. The most penetrable segment remains efficiency optimization for legacy infrastructure, leveraging a direct-to-customer sales approach.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with private equity-backed energy management software providers, presenting attractive long-term viability. The market offers sustained growth over the next decade, driven by decarbonization mandates and energy resilience needs. Acquisition targets should be specialized microgrid developers or digital twin technology firms with proven implementation records. The signal to watch is the standardization of Measurement and Verification protocols, which will streamline contract fulfillment.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout in DERs | Expands on-site generation capabilities for commercial clients, leveraging US Inflation Reduction Act incentives. |
| Power Purchase Agreement (PPA) Structuring | Secures long-term renewable energy supply for large corporate clients, supporting EU Green Deal compliance. |
| Digital Twin Technology Integration | Enhances predictive optimization for data centers, improving Power Usage Effectiveness (PUE) metrics. |
| Microgrid Solutions Development | Provides energy resilience for industrial hubs in Vietnam, addressing grid constraints. |
| AI-Powered Load Forecasting | Optimizes energy consumption for multi-location commercial facilities, reducing operational costs. |
Research Approach
A standing panel of utility planning officers, data center architects, energy engineers, and corporate sustainability leads provided ongoing calibration for market insights. Primary interviews with these industry stakeholders were triangulated with extensive secondary validation. Secondary sources included EIA data, IEA reports, corporate financial filings, and regulatory body publications like the EU CSRD. This approach ensured robust bottom-up validation and top-down market sizing.
Forecast outputs were consistently checked against external benchmarks, including national energy consumption trends and distributed energy resource deployment rates. The analytical framework integrated segmentation across service type, application, deployment model, and end-user, alongside regional regulatory landscapes. Compound Annual Growth Rates were derived from historical data analysis and projected technological adoption curves, with key inputs like projected renewable energy costs.
Underlying assumptions cover stable geopolitical conditions and consistent regulatory enforcement, with deviation risk concentrated in rapid policy shifts or unforeseen supply chain disruptions. Forecasts reflect these foundational assumptions. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Analytics and Software
Big Data Analytics in Energy Market
Energy Analytics and Software
Building Energy Simulation Software Market
Energy Analytics and Software
Global Geophysical Services and Equipment Market
Energy Analytics and Software
Industrial Energy Monitoring Market
Energy Analytics and Software
Smart Grid Data Analytics Market
Energy Analytics and Software
Europe Big Data Analytics in Energy Market
Energy Analytics and Software
Germany Big Data Analytics in Energy Market
Energy Analytics and Software
Australia Big Data Analytics in Energy Market
Energy Analytics and Software
AI in Energy Market
Energy Analytics and Software
Spain Big Data Analytics in Energy Market
Energy Analytics and Software
Africa Big Data Analytics in Energy Market
Energy Analytics and Software
Energy and Utilities Analytics Market
Energy Analytics and Software
India Big Data Analytics in Energy Market
Energy Analytics and Software
Digital Energy Platform Market
Energy Analytics and Software
Smart Grid Software Market
Energy Analytics and Software
Utility Analytics and Energy Analytics Market