
 Office Furniture Market | 2026-2036
Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Office Furniture Market Intelligence
The EU Green Deal is restructuring procurement criteria across European corporate buyers, forcing suppliers to certify recycled content thresholds and carbon footprints. Steelcase Inc. leverages its global manufacturing footprint to pre-certify entire product lines against evolving environmental standards. Haworth Inc. sustains competitive advantage through deep vertical integration into textile and seating component production.
Office furniture encompasses workstations, seating, storage, and ancillary surfaces engineered for commercial interior environments, typically specified to ANSI/BIFMA standards for durability, safety, and ergonomics in sustained-use settings. The product category serves to optimize worker productivity, spatial density, and organizational flexibility across leased and owned real estate. Seating and desks anchor the majority of revenue volume, while storage solutions and collaborative tables capture expanding share as open-plan and hybrid layouts displace traditional cellular offices. Metal and wood materials dominate bill-of-materials costs, though fabric innovation around antimicrobial and recycled polymer content is shifting specification patterns in healthcare-adjacent and co-working segments.
EPA guidelines on indoor air quality, OSHA ergonomic requirements, and BIFMA's e3 sustainability standard collectively constrain product design and market access for non-compliant manufacturers. REACH chemical restrictions in Europe and California's Proposition 65 disclosure mandates add further compliance layers to material sourcing decisions. Stakeholders must monitor evolving building certification schemes and municipal green procurement ordinances to anticipate specification shifts before they harden into contract requirements.
Market Dynamics
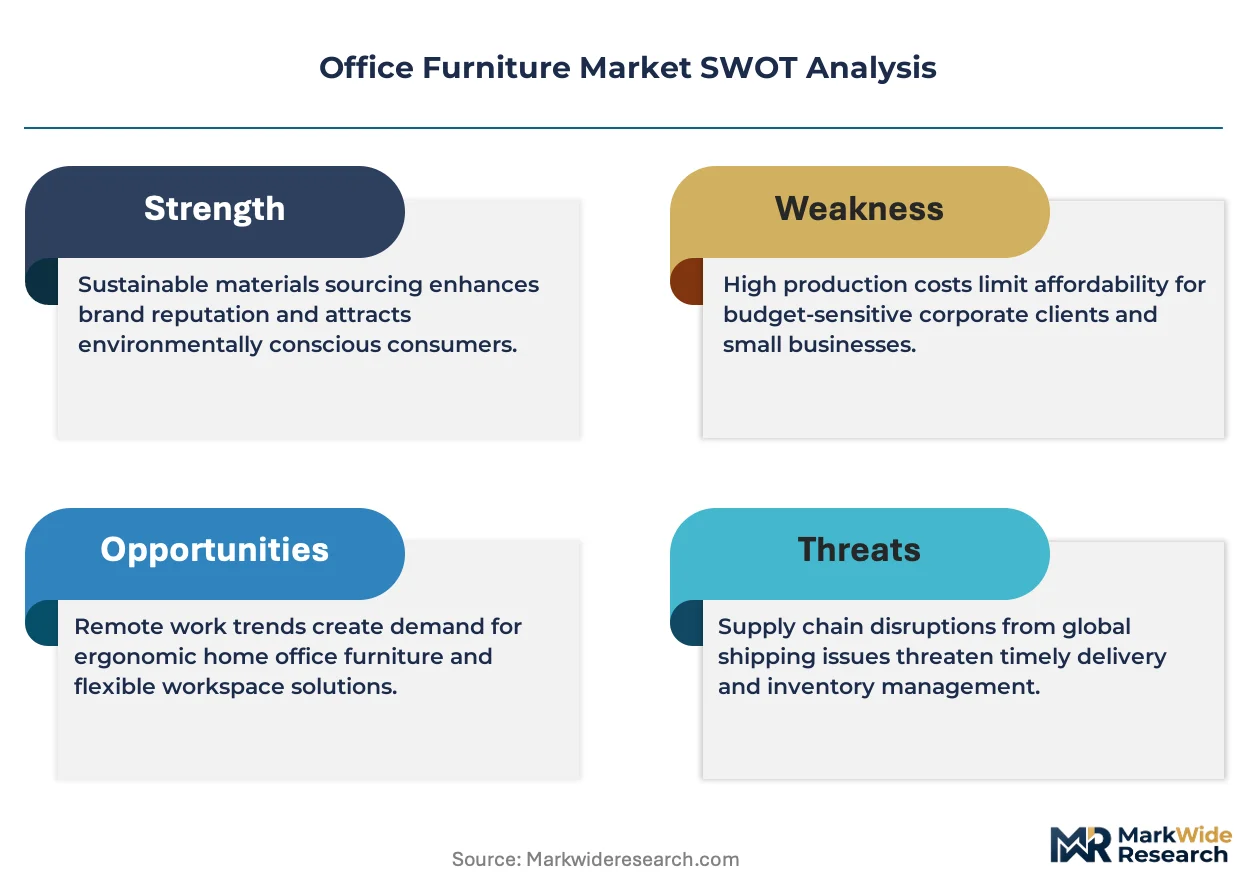
Hybrid work mandates from corporate headquarters are compressing furniture replacement cycles and forcing manufacturers to engineer reconfigurable systems that adapt to fluctuating occupancy rates.
Growth Catalysts
- LEED v4.1 certification thresholds:North American facility managers now require embodied carbon disclosures for interior fit-outs, accelerating specification of low-emission workstation systems.
- Biophilic design integration:Live-edge timber and moss wall installations in German financial services headquarters are expanding the addressable market for ancillary furniture categories.
- China:Municipal green procurement ordinances in Shenzhen and Shanghai mandate recycled content minimums for government office renovations.
Market Restraints
- Steel price volatility:Cold-rolled steel accounts for 35-40% of seating frame costs, exposing manufacturers to commodity swings without pass-through pricing power.
- Concentrated textile supply:Performance fabric mills cluster in North Carolina and northern Italy, creating single-source vulnerability for antimicrobial upholstery programs.
- REACH SVHC restrictions:ECHA's expanding candidate list of substances of very high concern forces reformulation of flame-retardant foam chemistry ahead of compliance deadlines.
Strategic Opportunities
- Healthcare-adjacent co-working:Medical office buildings in Texas and Florida are installing HIPAA-compliant workstation pods with acoustic privacy screening.
- EU Taxonomy alignment:Manufacturers certifying products against the EU's sustainable finance classification gain preferential access to ESG-mandated institutional real estate portfolios.
- Direct-to-tenant platforms:WeWork competitors and flexible space operators are bypassing traditional dealer networks to source modular benching systems through proprietary digital procurement portals.
Industry Challenges
- BIFMA e3 auditor scarcity:Limited third-party certification capacity creates 12-16 week bottlenecks for manufacturers launching sustainable product lines.
- Legacy CAD integration:Specifiers using Autodesk Revit require native BIM objects with embedded carbon data, forcing costly digital asset redevelopment.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Furniture Market |
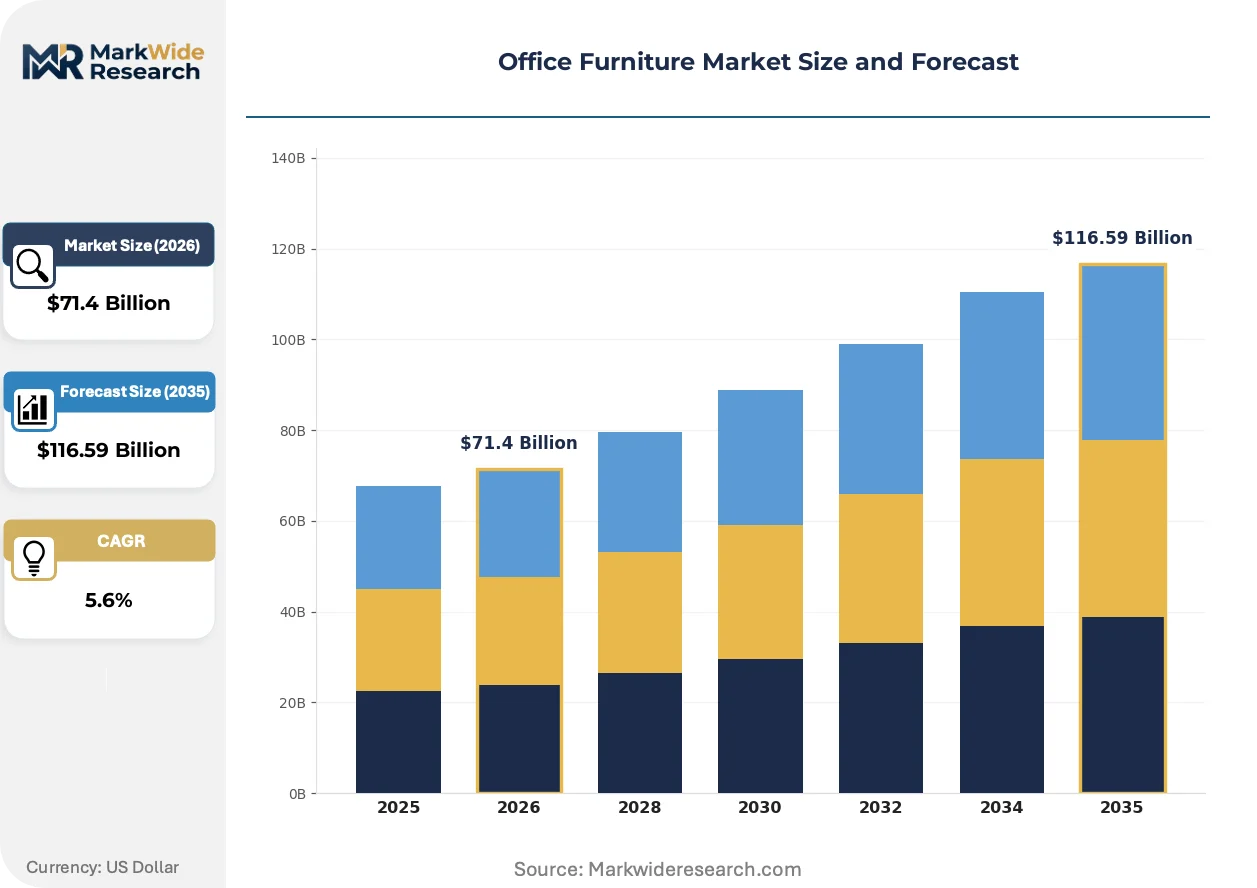
| Market Size in 2026 | $71.4 Billion |
| Market Size in 2035 | $116.59 Billion |
| CAGR (2026 – 2036) | 5.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Solutions Material: Wood, Metal, Glass, Fabric Use Case: Home Office, Co-working Spaces, Corporate Offices, Educational Institutions Distribution Channel: Online Retail, Showrooms, Wholesale, Direct Sales |
| Companies Covered | MillerKnoll, Inc., Steelcase Inc., Haworth Inc., HNI Corporation, Herman Miller, Inc., KI (Krueger International), Teknion Corporation, Okamura Corporation, Humanscale, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Furniture Market Strategic Shifts & Innovations
Material science breakthroughs and embedded sensor platforms are redefining how furniture manufacturers capture value beyond physical product sales.
Smart seating platforms incorporating pressure-mapping sensors and posture-feedback haptics are absorbing functionality previously delivered by standalone ergonomic consulting services. Enterprise buyers in the technology and professional services sectors are deploying these systems at 200-400 seat pilots before campus-wide rollout. The technology is absorbing service revenue into hardware margins while generating continuous utilization data for real estate optimization teams.
California's Proposition 65 enforcement actions against formaldehyde-emitting composite wood products are tightening supply chains for casegoods manufacturers serving the western United States. Litigation risk has prompted several mills to accelerate conversion to ultra-low emitting phenolic resin systems ahead of federal TSCA Title VI standards. Upholstered seating and storage systems containing particleboard substrates face the steepest compliance cost increases.
Subscription-based furniture-as-a-service contracts are displacing capital expenditure procurement in London and New York flexible workplace deployments. Operators of sub-10,000 square foot satellite offices are replacing three-year depreciation schedules with monthly per-seat fees covering delivery, reconfiguration, and end-of-life recovery. Financial services and legal sector tenants in Manhattan and the City of London represent the densest adoption clusters for this model.
Office Furniture Market Segmentation
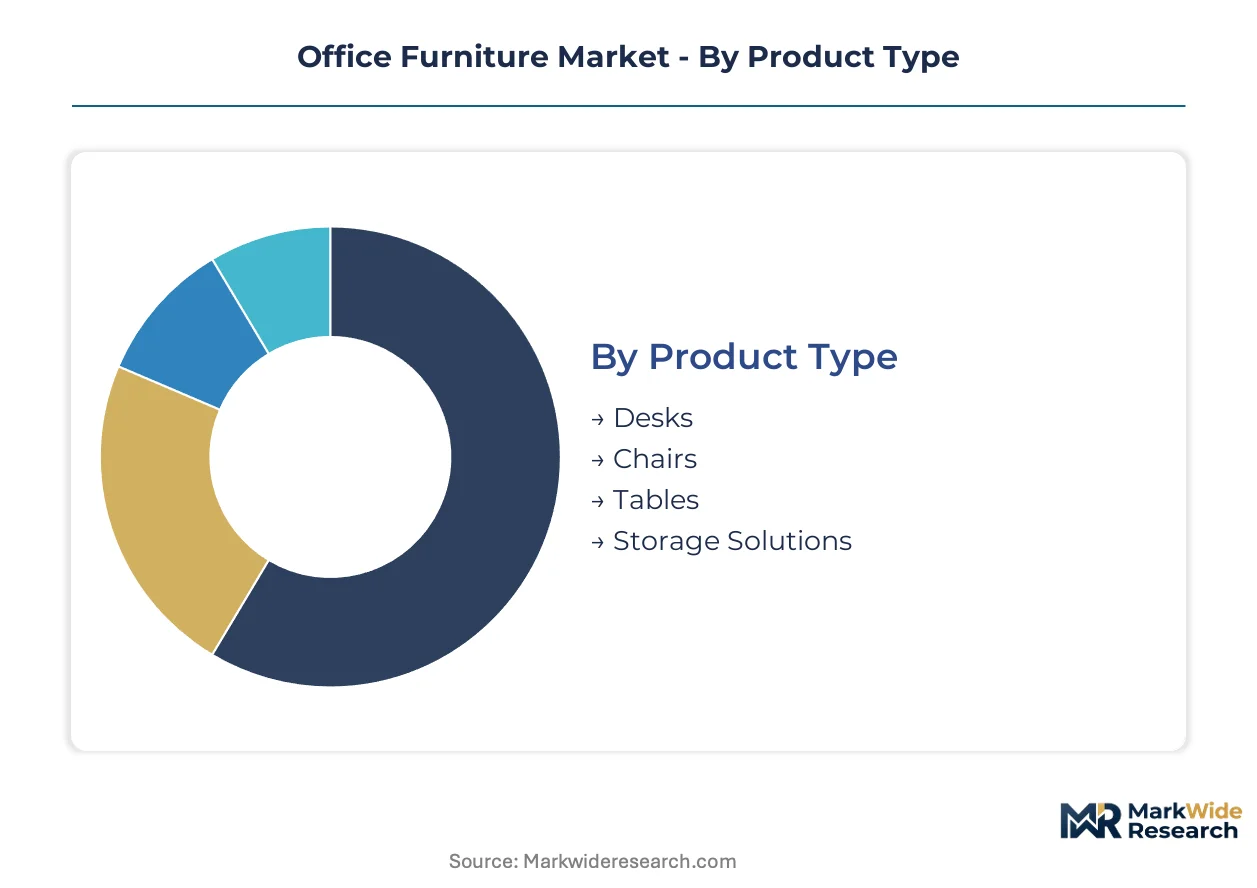
Office furniture procurement follows distinct specification pathways depending on interior environment, durability requirements, and procurement authority. Each segmentation axis reveals divergent margin structures and compliance burdens that reshape competitive positioning across manufacturer portfolios.
Product Type:
Engineering complexity and ergonomic certification intensity separate premium seating from commodity surfaces.
- Desks:Height-adjustable electric bases with ANSI/BIFMA load ratings now dominate corporate specifications. Demand concentrates in German technology headquarters and Shenzhen financial services towers where hybrid occupancy rates fluctuate weekly.
- Chairs:Mesh-back synchronous mechanisms with pressure-mapped lumbar support absorb the highest R&D investment per unit. North American technology campuses and London legal sector tenants require 12-hour continuous-use certification for task seating procurement.
- Tables:Modular benching systems with integrated cable management serve open-plan reconfigurations. Co-working operators in Manhattan and Singapore specify quick-release connection hardware for rapid floor-plate changes.
- Storage Solutions:Low-VOC laminate lockers and mobile pedestals face tightening California Proposition 65 composite wood enforcement. Healthcare-adjacent installations in Texas medical office buildings drive antimicrobial surface specifications.
Mature deployment sits with Desks. Newer deployment is concentrated in Storage Solutions.
Material:
Raw material selection determines carbon disclosure burden and REACH compliance exposure across manufacturing footprints.
- Wood:FSC-certified timber and live-edge slabs command specification premiums in German financial services biophilic installations. EU Green Deal embodied carbon thresholds favor mass-plywood and cross-laminated timber over steel-intensive alternatives.
- Metal:Cold-rolled steel frames anchor seating durability ratings but expose manufacturers to commodity price volatility without pass-through pricing power. Recycled content minimums in Shanghai and Shenzhen municipal procurement favor domestic secondary steel sourcing.
- Glass:Tempered surface materials serve executive conferencing and reception applications. Italian and North Carolina specification communities drive demand for ultra-clear low-iron variants in premium interiors.
- Fabric:Antimicrobial polymer blends with recycled ocean plastic content reshape healthcare and co-working upholstery. REACH SVHC restrictions on flame-retardant chemistry force reformulation ahead of ECHA compliance deadlines.
Mature deployment sits with Metal. Newer deployment is concentrated in Fabric.
Use Case:
Occupancy patterns and lease structures dictate replacement cycles and reconfiguration frequency.
- Home Office:Compact task seating and folding desk systems serve distributed work arrangements. Suburban residential clusters in the United States and United Kingdom sustain direct-to-consumer shipment volumes.
- Co-working Spaces:Furniture-as-a-service subscription contracts displace capital expenditure procurement in London and New York flexible workplace deployments. Per-seat monthly fees cover delivery, reconfiguration, and end-of-life recovery.
- Corporate Offices:LEED v4.1 certification thresholds require embodied carbon disclosures for interior fit-outs. Facility managers in the United States and Germany specify low-emission workstation systems with native Revit BIM objects.
- Educational Institutions:Durability specifications prioritize 15-year lifecycle ratings over ergonomic adjustability. Municipal procurement in China and state university systems in the United States favor standardized benching over customized configurations.
Mature deployment sits with Corporate Offices. Newer deployment is concentrated in Co-working Spaces.
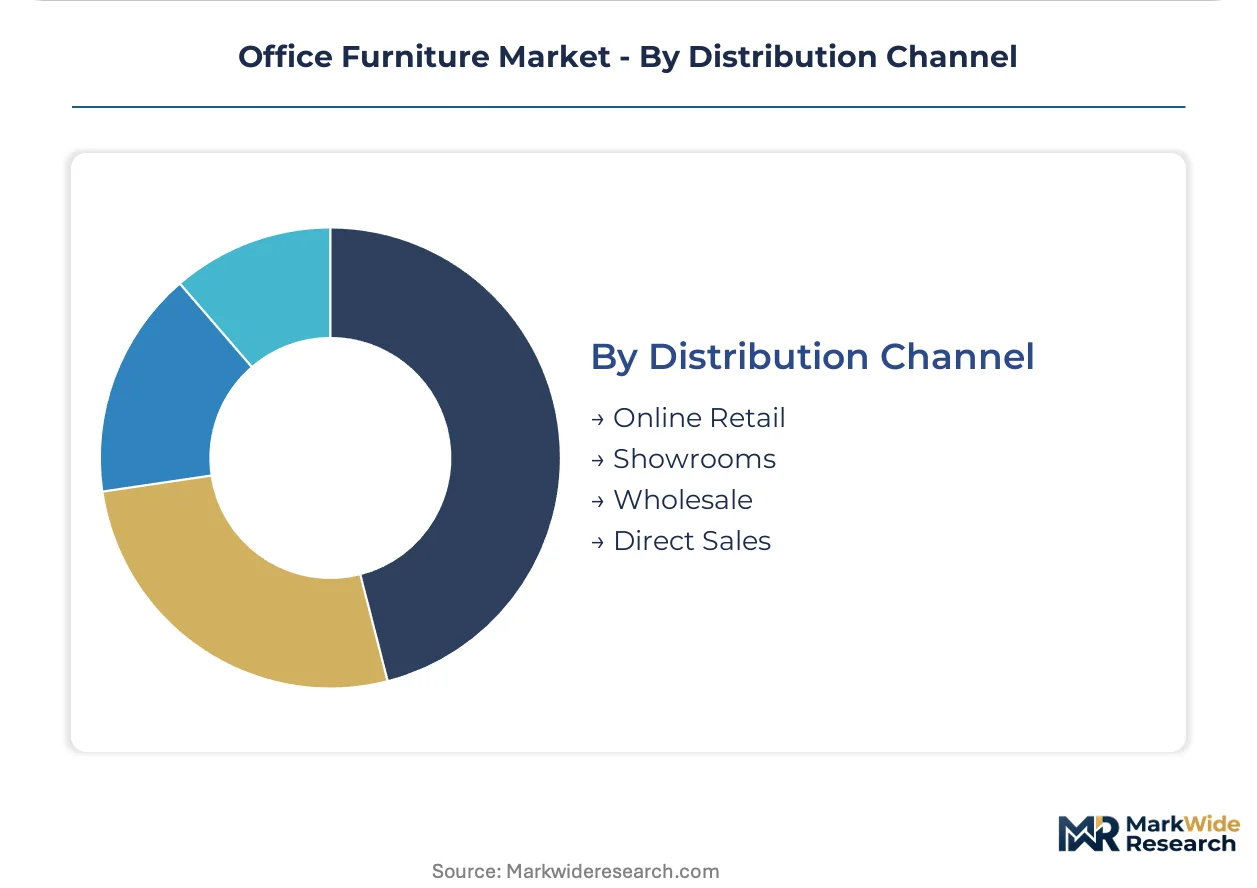
Distribution Channel:
Channel selection determines specification influence and margin capture relative to dealer network investment.
- Online Retail:Direct-to-tenant platforms bypass traditional dealer networks for modular benching procurement. WeWork competitors source through proprietary digital portals with embedded carbon data for ESG reporting.
- Showrooms:Physical specification environments sustain high-consideration seating decisions in Manhattan and the City of London. Financial services and legal sector tenants require tactile evaluation before campus-wide rollout.
- Wholesale:Dealer networks retain influence in institutional and government procurement where competitive bidding rules apply. Multi-year maintenance contracts attach to volume seating purchases.
- Direct Sales:Manufacturer-owned specification teams serve Fortune 500 headquarters with customized program development. Steelcase and Haworth deploy dedicated account executives for global real estate portfolio standardization.
Mature deployment sits with Wholesale. Newer deployment is concentrated in Online Retail.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Manhattan and the City of London concentrate premium specification activity for task seating and executive conferencing systems. Corporate headquarters in these financial centers drive embodied carbon disclosure requirements and native BIM object demands. Facility managers in both metros now require 12-hour continuous-use certification for campus-wide seating procurement.
United States
LEED v4.1 certification thresholds compel facility managers to demand embodied carbon disclosures for interior fit-outs. EPA guidelines on indoor air quality and OSHA ergonomic requirements constrain product design for domestic manufacturers. California's Proposition 65 enforcement actions against formaldehyde-emitting composite wood products tighten supply chains for casegoods serving the western United States.
Germany
EU Green Deal procurement criteria force suppliers to certify recycled content thresholds and carbon footprints for federal and corporate buyers. ECHA's REACH SVHC restrictions compel reformulation of flame-retardant foam chemistry ahead of compliance deadlines. Frankfurt and Munich financial services headquarters drive biophilic design integration with live-edge timber and moss wall installations expanding ancillary furniture categories.
China
Municipal green procurement ordinances in Shenzhen and Shanghai mandate recycled content minimums for government office renovations. MIIT and MEE standards on indoor environmental quality shape domestic manufacturer compliance strategies. Yangtze River Delta manufacturing clusters supply height-adjustable electric desk bases to technology headquarters and financial services towers.
United Kingdom
Corporate hybrid work mandates compress furniture replacement cycles and force reconfigurable system engineering. London flexible workplace operators displace capital expenditure procurement with subscription-based furniture-as-a-service contracts. City of London legal and financial sector tenants represent the densest adoption clusters for monthly per-seat fee structures covering delivery and end-of-life recovery.
Japan
METI energy efficiency standards and JIS durability ratings govern workstation system specifications for corporate buyers. Tokyo technology campuses deploy smart seating platforms with pressure-mapping sensors at pilot scales before broader rollout. Osaka manufacturing clusters supply precision-engineered synchronous mechanisms for 12-hour continuous-use task seating certification.
Office Furniture Market Key Industry Players
The competitive structure tilts toward integrated manufacturers with captive supply of steel frames and textile components. Scale advantages concentrate among North American and European firms with pre-certified product lines against evolving environmental standards. Three archetypes dominate: full-system integrators with global manufacturing footprints, regional specialists with deep vertical integration into component production, and digital-native platforms bypassing traditional dealer networks. Consolidation through strategic acquisitions and portfolio diversification into healthcare-adjacent segments represent the dominant competitive moves.
Within the full-system integrator tier, Steelcase Inc. and MillerKnoll, Inc. exemplify global manufacturing footprint strategies with pre-certification against multiple regulatory regimes. Haworth Inc. occupies a position emphasizing upstream control over textile and seating component production. Okamura Corporation represents Japanese precision-engineering specialization in ergonomic mechanism design. These three anchors illustrate how geographic origin and corporate structure shape competitive positioning without determining specific strategic outcomes.
| Leading Market Players |
|---|
| MillerKnoll, Inc. |
| Steelcase Inc. |
| Haworth Inc. |
| HNI Corporation |
| Herman Miller, Inc. |
| KI (Krueger International) |
| Teknion Corporation |
| Okamura Corporation |
| Humanscale |
| Others |
Cost & Logistics Intelligence
Cold-rolled steel frame costs cascade through three distinct pricing tiers as manufacturers absorb commodity volatility without pass-through power. Fabric specification premiums for antimicrobial and recycled polymer content separate healthcare-adjacent procurement from standard corporate seating, while FSC-certified timber and low-VOC finishes command specification premiums in German and North American LEED-driven markets.
Pricing Analysis
Certification-grade pricing anchors value capture in the Office Furniture Market, with BIFMA e3 and LEED v4.1 compliance tiers separating premium specification from commodity procurement. Price differentiation stratifies across certification intensity, ergonomic adjustability range, and embodied carbon disclosure depth, with North American facility managers and German federal buyers least sensitive to base unit costs. Pricing pressure stems from steel commodity swings concentrated in cold-rolled frame production, compressing margins in mid-tier seating without recycled content certification. Sub-10,000 square foot co-working operators in Manhattan and London exhibit highest price sensitivity, driving subscription-based furniture-as-a-service displacement of capital expenditure procurement.
Supply Chain Analysis
Performance fabric supply rests on North Carolina and northern Italian specialty mills, creating single-source vulnerability for antimicrobial upholstery programs serving healthcare-adjacent and co-working segments. Raw material dependencies center on cold-rolled steel from domestic secondary sources in China, FSC-certified timber from Nordic and Baltic suppliers, and flame-retardant foam chemistry subject to REACH SVHC reformulation deadlines. Supply chain risk concentrates in concentrated textile geography exposure, with limited alternative sourcing for ocean-recycled polymer blends. Distribution runs through traditional dealer networks for institutional and government procurement, while direct-to-tenant digital portals capture flexible workplace operators in London, New York, and Singapore.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Office Furniture Market is consolidating as EU Green Deal procurement criteria and LEED v4.1 certification thresholds force sub-scale manufacturers to absorb compliance costs without volume leverage to defray investment.
For Market Incumbents: Anchor competitive position through captive supply of seating frames and textile components, eliminating margin leakage to external component suppliers. Steelcase and Haworth demonstrate how upstream control over synchronous mechanisms and performance fabrics sustains specification influence against digital-native entrants. Defend against furniture-as-a-service platforms by embedding carbon data and Revit BIM objects into proprietary digital specification tools for Fortune 500 real estate portfolios. For New Entrants and Emerging Players: Launch via direct-to-tenant digital procurement portals targeting sub-10,000 square foot satellite offices in Texas and Florida medical office buildings, where HIPAA-compliant workstation pods face limited incumbent penetration. Healthcare-adjacent co-working in Sun Belt metros represents the most penetrable white-space, with acoustic privacy screening and antimicrobial surfaces driving specification decisions outside traditional dealer relationships. Pursue subscription-based per-seat monthly fee structures to bypass capital expenditure procurement cycles. For Investors and Strategic Acquirers: BIFMA e3 auditor scarcity creating 12-16 week certification bottlenecks is the leading indicator that pre-certified product portfolios command acquisition premiums as compliance deadlines harden. The five-to-ten year viability window favors targets with established recycled content supply chains and native BIM object libraries. Monitor ECHA REACH SVHC list expansion as the inflection signal for flame-retardant chemistry reformulation costs that will strain sub-scale foam suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Component Production | Captive supply of steel frames and textiles eliminates margin leakage to external suppliers. |
| Certification Pre-Investment Against BIFMA e3 | Early compliance with evolving sustainability standards secures specification access before bottlenecks harden. |
| Native Revit BIM Object Development | Embedded carbon data objects meet facility manager demands for LEED v4.1 disclosure compliance. |
| Furniture-as-a-Service Platform Launch | Subscription per-seat fees capture co-working operators displacing capital expenditure procurement. |
| Healthcare-Adjacent Segment Diversification | HIPAA-compliant pods with antimicrobial surfaces open Texas and Florida medical office building demand. |
Research Approach
Independent corroboration across facility manager interviews, dealer network consultations, and manufacturer specification team discussions underwrites the qualitative findings in this study. Primary fieldwork engaged corporate real estate directors, furniture procurement leads at Fortune 500 headquarters, co-working space operators, and healthcare facility planners across the United States, Germany, China, and the United Kingdom. Secondary validation drew from EPA indoor air quality guidelines, BIFMA technical standards documentation, ECHA REACH substance registrations, and municipal green procurement ordinances in Shenzhen and Shanghai. Bottom-up shipment data triangulated against top-down real estate absorption metrics and construction pipeline tracking.
Historical reference periods spanning pre-pandemic, pandemic disruption, and hybrid work normalization phases anchored the forecast window. The analytical framework modeled volume and value across product type, material composition, use case environment, and distribution channel dimensions, with additional segmentation for certification tier and geographic regulatory cluster. CAGRs derived from curve-fitting observed replacement cycle compression and embodied carbon disclosure adoption rates, with smart seating sensor deployment and furniture-as-a-service contract penetration as industry-specific demand modifiers.
The model assumes a particular technology adoption path for pressure-mapping sensor platforms and posture-feedback haptics; alternative pathways for embedded ergonomic consulting functionality would alter the outlook. Forecasts reflect assumptions around hybrid work policy persistence, steel commodity price stabilization, and REACH SVHC compliance timeline adherence. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Home Office Spending Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Rental Furniture Market