
 Standing Desk Market | 2026-2036
Standing Desk Market Size, Share, and Industry Trends Forecast 2026-2036
Standing Desk Market Outlook
Subscription-based furniture leasing and asset-light office provisioning are reshaping competitive dynamics in the standing desk sector. Branch leverages direct-to-consumer logistics to compete against legacy contract furniture channels. Steelcase sustains institutional relationships through specification-grade ergonomic programs. Flexispot anchors e-commerce volume with manufacturing scale across Asia-Pacific supply networks.
A standing desk is a height-adjustable workstation engineered with electric motors, manual cranks, or fixed elevated platforms to enable alternating seated and upright postures during computer-based tasks. Electric variants incorporate dual-motor lifting columns with load capacities exceeding 150 kilograms and programmable memory presets for precise height calibration between 60 and 125 centimeters. Electric models lead revenue contribution due to enterprise procurement preferences for programmable ergonomics, while manual units occupy the entry-level residential segment where price sensitivity dominates. Co-working spaces represent the fastest-growing application channel as flexible lease operators standardize on adjustable furniture to attract tenant rotations.
OSHA workplace ergonomic guidelines in the United States mandate employer assessment of workstation fit, directly stimulating corporate standing desk procurement. The EU Display Screen Equipment Directive requires member states to ensure adjustable furniture availability for screen-based workers, creating compliance-driven demand across Germany, France, and the Netherlands. ISO 9241-410 ergonomic standards further shape product design benchmarks for international market access. Stakeholders must monitor evolving building certification schemes such as WELL and Fitwel, which increasingly credit active workstation deployment as indoor environmental quality metrics tighten.
Market Dynamics
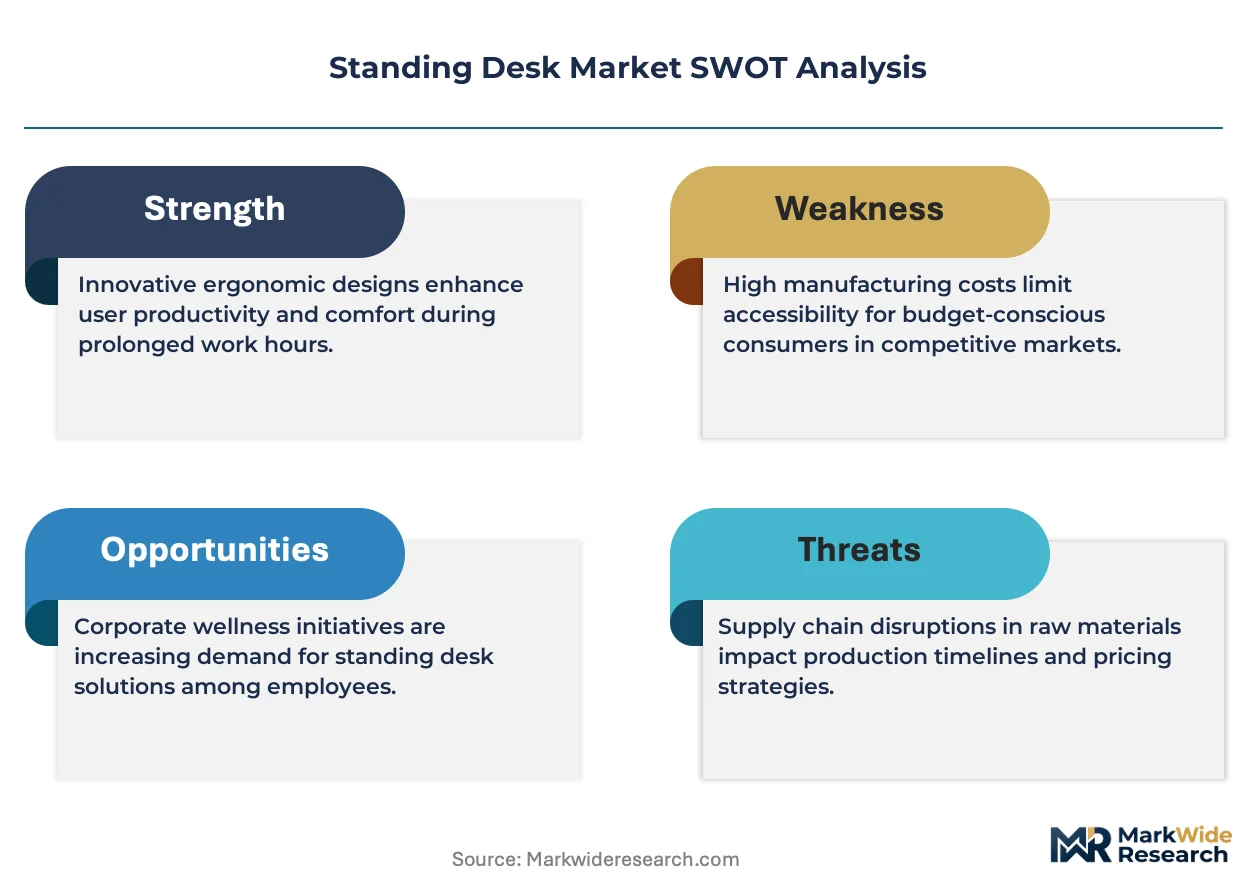
Hybrid work permanence is bifurcating demand into enterprise specification-grade procurement and direct-to-consumer residential purchases, forcing manufacturers to maintain dual distribution architectures without scale economies.
Growth Catalysts
- OSHA Ergonomic Mandates:United States employers must assess workstation fit for computer-based employees, triggering bulk standing desk orders across Fortune 500 corporate campuses and government agencies.
- EU Display Screen Equipment Directive:Member states enforce adjustable furniture availability for screen workers, creating compliance-driven procurement waves across German automotive headquarters and Dutch financial services firms.
- Biometric Sensor Integration:Posture-tracking modules embedded in desk surfaces feed wellness platforms, attracting technology sector employers seeking measurable productivity metrics.
Market Restraints
- Steel and Aluminum Input Volatility:Lifting column raw material costs swing with commodity indexes, compressing margins for mid-tier manufacturers without long-term supplier contracts.
- Motor Drive Supply Concentration:Precision linear actuator production clusters in Zhejiang province, exposing brands to single-source disruption risk during regional lockdowns or trade friction.
- Fixed-Height Substitutes:Converter platforms and stackable monitor risers satisfy price-sensitive residential buyers unwilling to invest in full motorization.
Strategic Opportunities
- Subscription Leasing Models:Asset-light office operators in United Kingdom and Germany seek furniture-as-a-service contracts bundling installation, maintenance, and refresh cycles.
- Healthcare Facility Deployment:Hospitals and clinics adopt height-adjustable nursing stations and physician documentation areas to reduce musculoskeletal injury claims among clinical staff.
- WELL Building Certification Credits:Active workstation deployment earns points under indoor environmental quality metrics, motivating commercial real estate developers to specify adjustable furniture in new construction.
Industry Challenges
- Cross-Border Certification Timelines:UL listing for United States electrical safety and CE marking for European electromagnetic compatibility require parallel testing tracks, delaying product launches by 6-12 months.
- Legacy Office Integration Complexity:Cable management, power routing, and space planning for adjustable desks conflict with fixed-height cubicle infrastructure in 1990s-era commercial buildings.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Standing Desk Market |
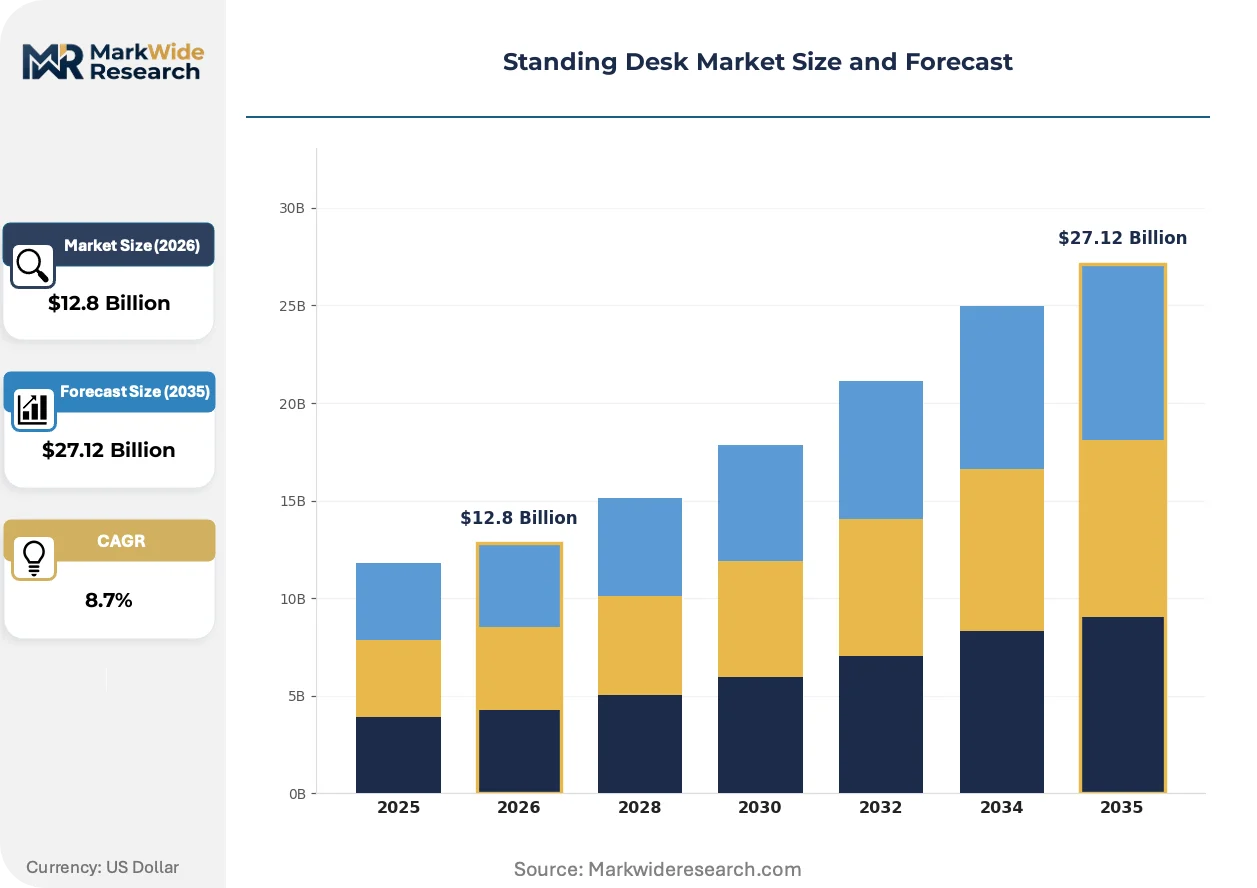
| Market Size in 2026 | $12.8 Billion |
| Market Size in 2035 | $27.12 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Electric, Manual, Height-Adjustable, Fixed Material: Wood, Metal, Glass, Laminated Particleboard Application: Home Office, Commercial Office, Educational Institutions, Co-Working Spaces End User: Freelancers, Corporate Employees, Students, Remote Workers |
| Companies Covered | Branch, Burrow, Uplift, IKEA, Steelcase, Flexispot, Secretlab, Oakywood, Vivo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Standing Desk Market Strategic Shifts
Digital wellness platforms are merging hardware telemetry with employer health initiatives, transforming standing desks from passive furniture into active data collection nodes.
Dual-motor synchronized lifting columns with anti-collision sensors are collapsing the performance gap between entry-level and premium electric variants. Small and medium enterprises previously constrained to manual crank models now access programmable height memory at mid-market price points. This compression is eroding the premium tier's historical justification purely on motor reliability.
REACH substance restrictions on phthalates and flame retardants in polymer components are forcing reformulation of cable jackets and control housing materials. Manufacturers serving European Union markets must validate alternative compounds through extended thermal cycling tests. German and French contract furniture specifiers now require full material disclosure documentation as standard bid prerequisites.
Direct-to-consumer brands are capturing residential buyers through augmented reality room visualization tools that eliminate showroom dependence. Traditional contract furniture dealers respond with white-glove installation and same-day repair services for enterprise accounts. This channel tension is most acute in United States metropolitan markets where hybrid workers maintain dual home-office setups.
Standing Desk Market Segmentation
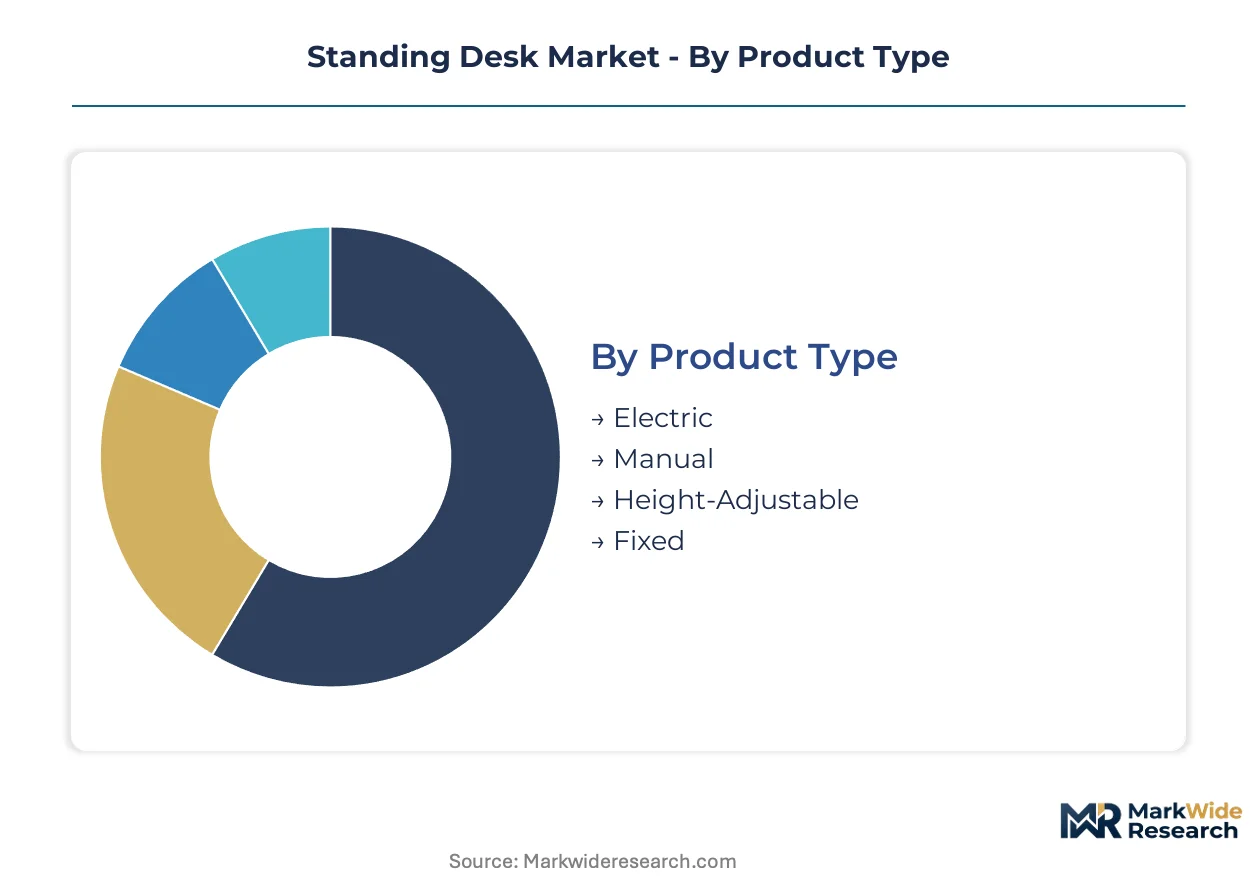
Standing desk segmentation reflects divergent procurement logic across residential impulse purchases and enterprise specification cycles. Manufacturers must engineer product architectures that satisfy OSHA compliance mandates for Fortune 500 campuses while maintaining price accessibility for home office upgraders.
Product Type:
Height-adjustment mechanisms span motorized precision systems to fixed elevated platforms, each occupying distinct use-case spectrums from clinical documentation stations to residential craft workspaces.
- Electric:Dual-motor lifting columns with programmable memory presets enable precise height calibration between 60 and 125 centimeters. Enterprise procurement in Germany and the Netherlands concentrates here due to EU Display Screen Equipment Directive compliance requirements and bulk installation contracts.
- Manual:Crank-operated or pneumatic counterbalance systems eliminate electrical dependency and reduce unit cost. Demand clusters in price-sensitive residential segments across United States suburban markets where hybrid workers seek ergonomic upgrades without premium expenditure.
- Height-Adjustable:Converter platforms and riser attachments retrofit existing fixed desks. These units serve United Kingdom co-working operators seeking furniture flexibility across short-term lease rotations without capital-intensive full-desk replacement.
- Fixed:Non-adjustable elevated workstations occupy permanent standing configurations. Healthcare documentation areas in United States hospital systems specify these for nursing stations with dedicated upright posture protocols.
Established volume favors Electric; emerging adoption favors Height-Adjustable.
Material:
Surface composition determines durability certification, aesthetic specification, and REACH compliance burden across European and North American procurement channels.
- Metal:Steel and aluminum framing systems deliver structural load capacity exceeding 150 kilograms for dual-monitor enterprise deployments. German automotive headquarters and Dutch financial services firms specify powder-coated metal bases for contract furniture longevity.
- Wood:Solid hardwood and veneer surfaces satisfy residential aesthetic preferences and WELL Building certification biophilia credits. United States metropolitan residential buyers in Seattle and Austin prioritize FSC-certified timber for home office installations.
- Glass:Tempered glass surfaces enable modern minimalist specifications in executive suites and design-forward co-working lounges. French contract furniture specifiers require additional edge treatment certification for safety compliance.
- Laminated Particleboard:Cost-optimized composite surfaces dominate entry-level e-commerce volume. REACH substance restrictions on formaldehyde emissions and phthalate plasticizers force reformulation for European Union market access.
Metal commands the premium tier; particleboard captures volume scale.
Application:
Deployment environment dictates installation complexity, warranty terms, and refresh cycle velocity across asset-light and asset-heavy operational models.
- Co-Working Spaces:Flexible lease operators standardize on adjustable furniture to attract tenant rotations and justify membership premiums. United Kingdom and German operators lead procurement velocity as commercial real estate adapts to hybrid permanence.
- Commercial Office:Corporate campuses and government agencies execute bulk standing desk orders triggered by OSHA ergonomic assessment mandates. United States Fortune 500 headquarters and federal facilities represent concentrated specification-grade demand.
- Home Office:Direct-to-consumer residential purchases sustain e-commerce channel growth. Hybrid work policies in United States metropolitan markets sustain dual-setup procurement where workers maintain equivalent stations at employer and residence locations.
- Educational Institutions:Universities and K-12 districts deploy adjustable workstations for computer labs and faculty offices. Procurement concentrates in United States public school systems with ergonomic injury prevention budgets.
Commercial Office anchors revenue; Co-Working Spaces climb the fastest.
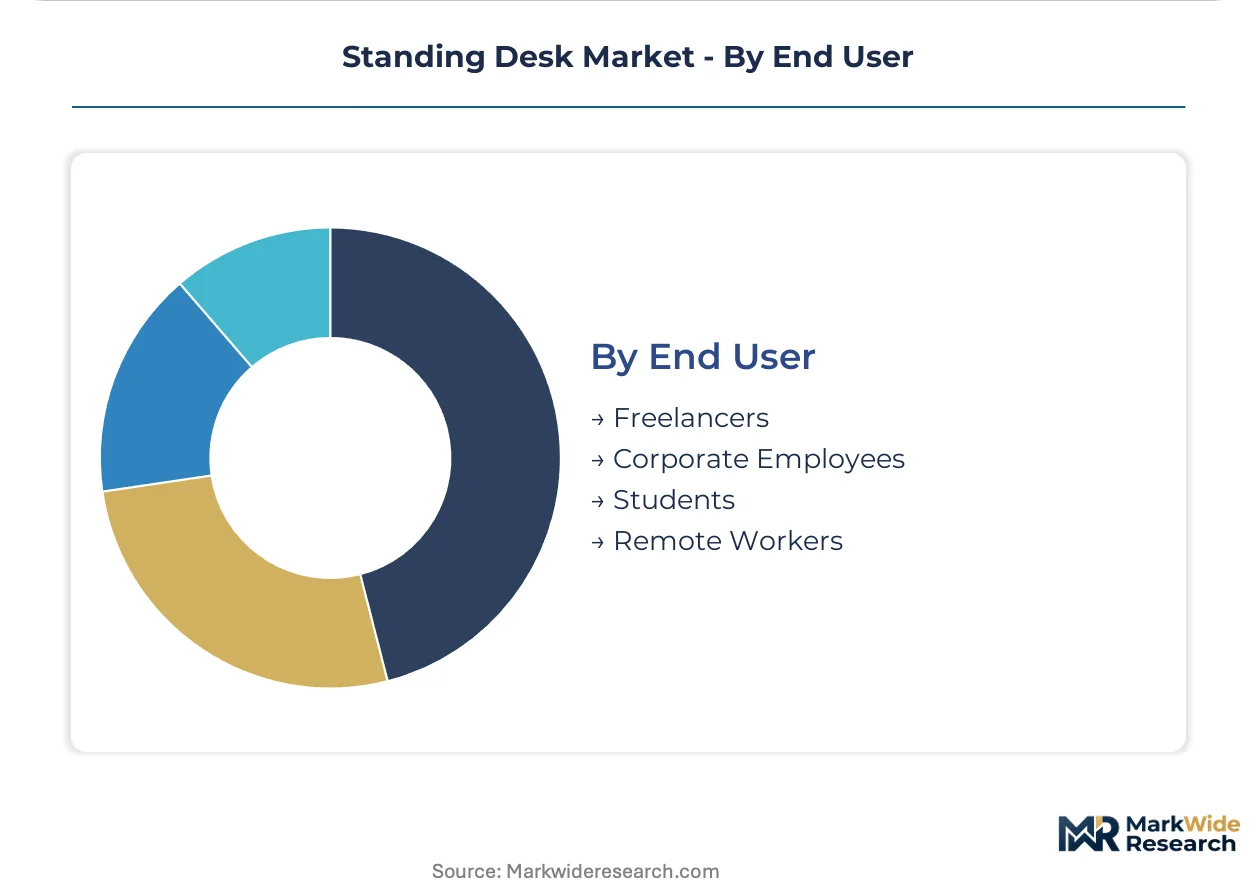
End User:
User category determines price sensitivity, feature complexity requirements, and channel preference between direct-to-consumer logistics and contract furniture dealer networks.
- Corporate Employees:Enterprise-provisioned workstations follow occupational health and safety procurement protocols. United States employers under OSHA jurisdiction must assess workstation fit, triggering specification-grade electric desk deployment.
- Remote Workers:Self-funded residential purchasers prioritize mid-market electric variants with programmable features. This segment expands across United States suburban markets as hybrid policies stabilize.
- Freelancers:Independent professionals balance ergonomic investment against income variability. Manual and converter platforms satisfy price-conscious procurement in United Kingdom and German metropolitan gig economy clusters.
- Students:Educational pricing and institutional procurement dominate this segment. United States university technology fee structures increasingly include adjustable furniture for dormitory and library computing facilities.
Corporate Employees drive specification value; Remote Workers expand addressable market breadth.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Import flows of electric lifting columns and precision linear actuators concentrate from Zhejiang province manufacturers toward North American and European assembly operations, while finished desk exports from Vietnam and Malaysia gain share as contract furniture brands diversify sourcing beyond China.
United States
Fortune 500 corporate campuses in Texas and California execute bulk procurement triggered by OSHA ergonomic assessment mandates for computer-based employees. Federal facilities and government agencies maintain specification-grade standing desk deployment protocols. The Greater Boston metropolitan cluster hosts technology sector employers integrating biometric sensor modules into wellness platform architectures.
Germany
Automotive headquarters in Stuttgart and Munich specify powder-coated metal frame systems for contract furniture longevity under EU Display Screen Equipment Directive compliance. REACH substance restrictions on phthalates force reformulation of polymer cable jackets and control housings. The Rhine-Ruhr industrial corridor concentrates distribution logistics for adjustable furniture serving Dutch and Belgian cross-border procurement.
Netherlands
Financial services firms in Amsterdam standardize on programmable electric variants with dual-motor synchronized lifting columns. Dutch building certification schemes credit active workstation deployment under tightening indoor environmental quality metrics. The Eindhoven Region harbors flexible lease operators seeking furniture-as-a-service contracts bundling installation and refresh cycles.
United Kingdom
London co-working operators lead procurement velocity as commercial real estate adapts to hybrid work permanence. Asset-light office providers in Manchester and Birmingham seek subscription leasing models with maintenance-inclusive terms. UK contract furniture specifiers increasingly require full material disclosure documentation as standard bid prerequisites.
China
Zhejiang province manufacturers dominate precision linear actuator production, exposing supply chains to single-source disruption risk during regional lockdowns. Domestic demand concentrates in Shanghai and Beijing technology sector employers deploying posture-tracking modules. Yangtze River Delta assembly operations export finished electric desk systems to North American direct-to-consumer brands.
Standing Desk Market Competitive Environment
On the supply side, the industry is bifurcated between specification-grade contract furniture channels and direct-to-consumer e-commerce logistics, with mid-tier manufacturers caught between dual distribution architectures without scale economies. Three strategic archetypes dominate: legacy institutional dealers maintaining white-glove installation services, Asia-Pacific manufacturing scale players capturing volume through online marketplaces, and digitally-native brands leveraging augmented reality visualization tools. Competitive moves concentrate on strategic partnerships with commercial real estate developers and portfolio diversification into healthcare facility deployment.
Among North American direct-to-consumer specialists, Branch and Uplift exemplify digitally-native distribution models, while Steelcase anchors the institutional specification tier through ergonomic program relationships with Fortune 500 campuses. Flexispot represents Asia-Pacific manufacturing scale players competing on e-commerce volume across global online marketplaces.
| Leading Market Players |
|---|
| Branch |
| Burrow |
| Uplift |
| IKEA |
| Steelcase |
| Flexispot |
| Secretlab |
| Oakywood |
| Vivo |
| Others |
Value Chain & Pricing Dynamics
Yangtze River Delta port freight corridors transmit cost volatility from Zhejiang actuator manufacturers to North American assembly plants, amplifying price differentiation between enterprise specification-grade procurement and residential direct-to-consumer channels. This logistics concentration rewards contract furniture dealers with volume leverage while squeezing mid-tier brands lacking long-term supplier commitments.
Pricing Analysis
Enterprise procurement teams anchor pricing structures around three-tier certification-grade differentiation across UL-listed, CE-marked, and uncertified variants. Price differentiation stems from motor load capacity ratings and REACH-compliant material disclosure documentation. Cost compression in entry-level electric segments intensifies as dual-motor reliability gaps narrow. Remote workers exhibit highest price sensitivity, while Fortune 500 facilities accept premium positioning for OSHA compliance bundling.
Supply Chain Analysis
Extended payment terms from Zhejiang precision actuator suppliers now stretch to 90-120 days, straining working capital for mid-tier assemblers. Manufacturing gravity centers on China, Vietnam, and Malaysia for finished desk systems, with steel and aluminum framing sourced from Shandong and Guangdong provinces. Single-source vulnerability concentrates in linear actuator production clusters. Distribution runs through contract furniture dealer networks for enterprise accounts and direct-to-consumer logistics for residential buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among asset-light office operators and Fortune 500 procurement consortiums, fragmenting price-setting authority away from manufacturers. This shift rewards scale players with balance-sheet depth to absorb inventory financing pressure.
For Market Incumbents: Harden specification-grade relationships through WELL Building certification consulting services that embed desks into broader indoor environmental quality contracts. Deepen backward integration into precision actuator sourcing to offset Zhejiang supply concentration risk. Defend against direct-to-consumer brands by white-glove installation networks with same-day repair SLAs.
For New Entrants and Emerging Players: Build out healthcare facility deployment capabilities targeting nursing station retrofits with fixed-height elevated configurations. The United States hospital systems segment remains underpenetrated by ergonomic furniture specialists. Pursue group purchasing organization contracts to bypass entrenched dealer relationships.
For Investors and Strategic Acquirers: Mid-cycle technology positioning favors manufacturers with captive sensor integration capabilities for wellness platform partnerships. Long-term viability hinges on software-enabled recurring revenue streams rather than hardware margins. Monitor biometric data privacy regulatory developments as inflection indicators for platform-based valuation premiums.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor Integration Partnership | Posture-tracking modules feed employer wellness platforms, creating switching costs. |
| Healthcare Facility Certification | Hospital system GPO contracts unlock recurring procurement beyond commercial office cycles. |
| Subscription Leasing Launch | Asset-light operators in Germany and United Kingdom seek furniture-as-a-service bundling. |
| REACH Compliance Investment | Alternative compound validation secures European Union market access against restricted rivals. |
| Augmented Reality Visualization | Room-planning tools reduce showroom dependence for residential direct-to-consumer conversion. |
Study Parameters
Desk research of customs trade databases, OSHA enforcement records, and EU Display Screen Equipment Directive implementation reports preceded structured interviews with contract furniture procurement directors, facilities managers at Fortune 500 campuses, co-working space operators, and precision actuator manufacturing executives. Bottom-up volume estimates triangulated against top-down addressable market calculations derived from commercial office construction permits and hybrid work policy adoption surveys.
Assumptions held OSHA ergonomic assessment mandate enforcement rates and EU member state compliance timelines fixed at current trajectories, while varying steel and aluminum commodity price scenarios across the projection horizon. Segmentation modeling incorporated height-adjustment mechanism type, surface material certification tier, deployment environment, and end-user procurement authority. CAGRs were derived from fitted trend analysis of historical procurement velocity correlated with regulatory implementation phases.
Practitioners should monitor REACH substance restriction expansion and biometric data privacy regulatory developments for early signals of compliance cost escalation or platform partnership viability shifts. Macroeconomic deviation in commercial real estate construction, regulatory enforcement intensity variation, or sensor technology standardization disruption would prompt forecast revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
India Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Europe Home Office Furniture Market