
 Canada Office Furniture Market | 2026-2036
Canada Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Canada Office Furniture Market Outlook
The Canada office furniture sector is rebalancing as premium ergonomic systems pull away from commodity-grade catalog products on specification intensity and project engineering depth. Haworth Inc. leverages its Western Michigan manufacturing base to serve Canadian corporate headquarters with integrated workplace systems. Groupe Lacasse anchors Quebec's commercial furniture cluster through specialized government and institutional contracts. Teknion differentiates via advanced height-adjustable desk platforms and clean-air certified workstations.
Canada office furniture encompasses desks, chairs, conference tables, filing cabinets, and associated workplace systems engineered to commercial-grade durability standards with load ratings, VOC emissions compliance, and modular reconfiguration capability. Manufacturing employs steel tube forming, high-pressure laminate bonding, and powder-coat finishing to produce products rated for ten-plus year institutional lifecycles. The ergonomic design style commands expanding specification share as employers address musculoskeletal injury prevention and hybrid-work flexibility requirements. Direct sales channels dominate large corporate and government transactions where contract negotiation and installation services add value, while online platforms capture growing small-business and home-office volume with faster fulfillment.
Health Canada sets mandatory upholstered furniture flammability standards under the Hazardous Products Act, while provincial regulators enforce green building codes that specify recycled content thresholds and indoor air quality certification. The Canadian General Standards Board publishes performance specifications for federal procurement that filter into broader commercial buying criteria. Stakeholders must monitor evolving carbon disclosure requirements and circular economy mandates that will reshape supplier qualification and material sourcing decisions.
Market Dynamics
Corporate office renovations across Ontario's Greater Toronto Area commercial corridor are accelerating procurement of ergonomic workstations, creating a demand surge that outpaces commodity-grade catalog supply capacity and reshaping supplier qualification requirements.
Growth Catalysts
- Health Canada Flammability Standards:Mandatory upholstered furniture compliance under the Hazardous Products Act is elevating specification intensity for certified domestic manufacturers serving federal and institutional contracts.
- Provincial Green Building Codes:Recycled content thresholds and indoor air quality certification in Ontario and Quebec are filtering into broader commercial buying criteria and expanding addressable market for clean-air certified product lines.
- Hybrid-Work Flexibility Requirements:Musculoskeletal injury prevention mandates from employers are pulling height-adjustable desk platforms into standard corporate fit-out specifications.
Market Restraints
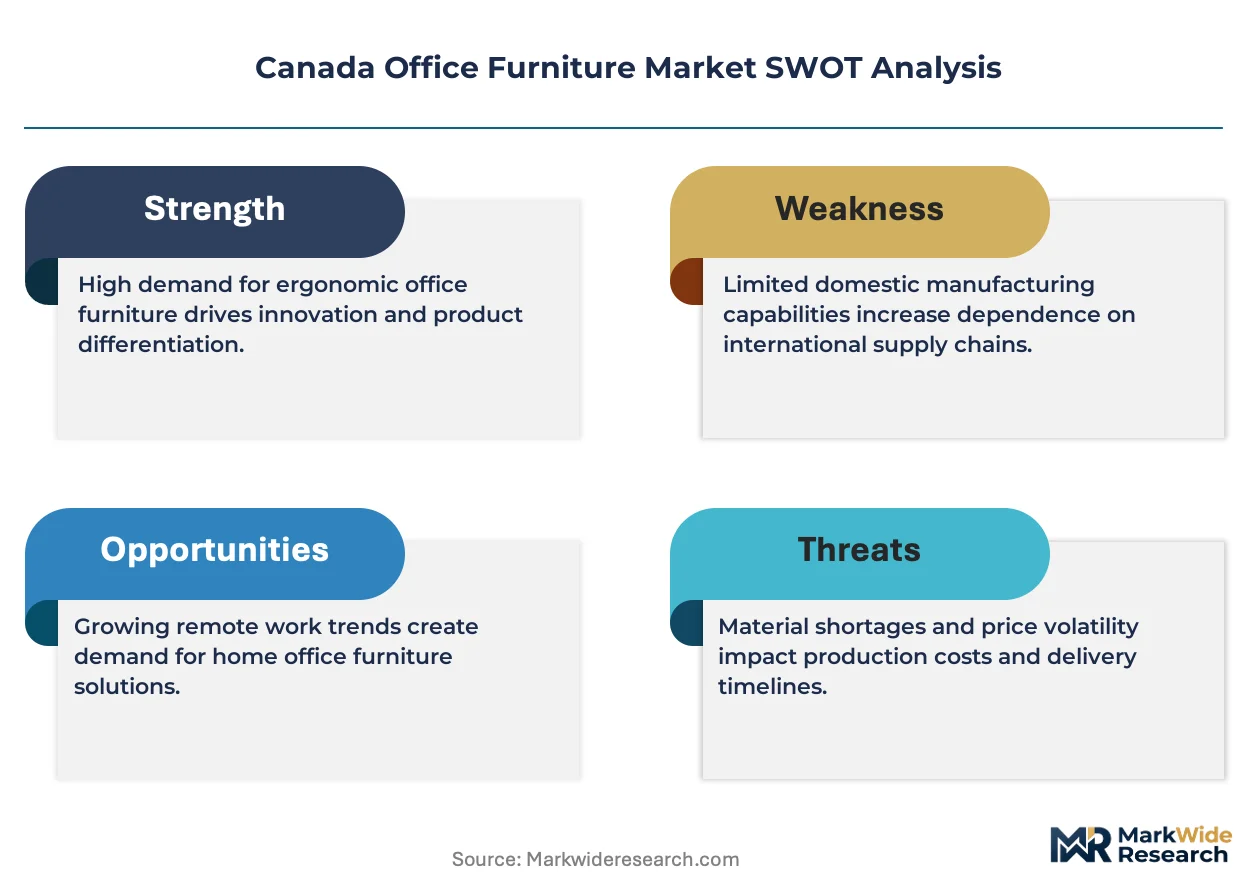
- Steel and Laminate Input Volatility:High-pressure laminate bonding and powder-coat finishing operations face margin compression from commodity steel tube and resin price swings.
- Western Michigan Supply Concentration:Cross-border manufacturing dependence for integrated workplace systems creates tariff exposure and logistics coordination complexity for Canadian corporate headquarters projects.
- Modular Reconfiguration Technical Limits:Load-rated structural connections for ten-plus year institutional lifecycles constrain rapid reconfiguration flexibility demanded by agile workspace programs.
Strategic Opportunities
- Quebec Government Contract Expansion:Specialized institutional procurement channels outside Ontario's dominant corridor offer underpenetrated volume for certified manufacturers with bilingual service capabilities.
- Circular Economy Mandates:Evolving carbon disclosure requirements from federal and provincial regulators will reshape supplier qualification and create first-mover advantage for take-back program operators.
- Online Platform Channel Development:Direct-to-small-business fulfillment infrastructure captures growing home-office and SME volume with faster lead times than traditional contract negotiation channels.
Industry Challenges
- CGSB Certification Timeline Compression:Canadian General Standards Board performance specification updates require accelerated testing and documentation cycles that strain product development bandwidth.
- Legacy Installation Service Integration:Contract negotiation and project engineering capabilities must mesh with automated quoting platforms without degrading large-transaction relationship management.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Canada Office Furniture Market |
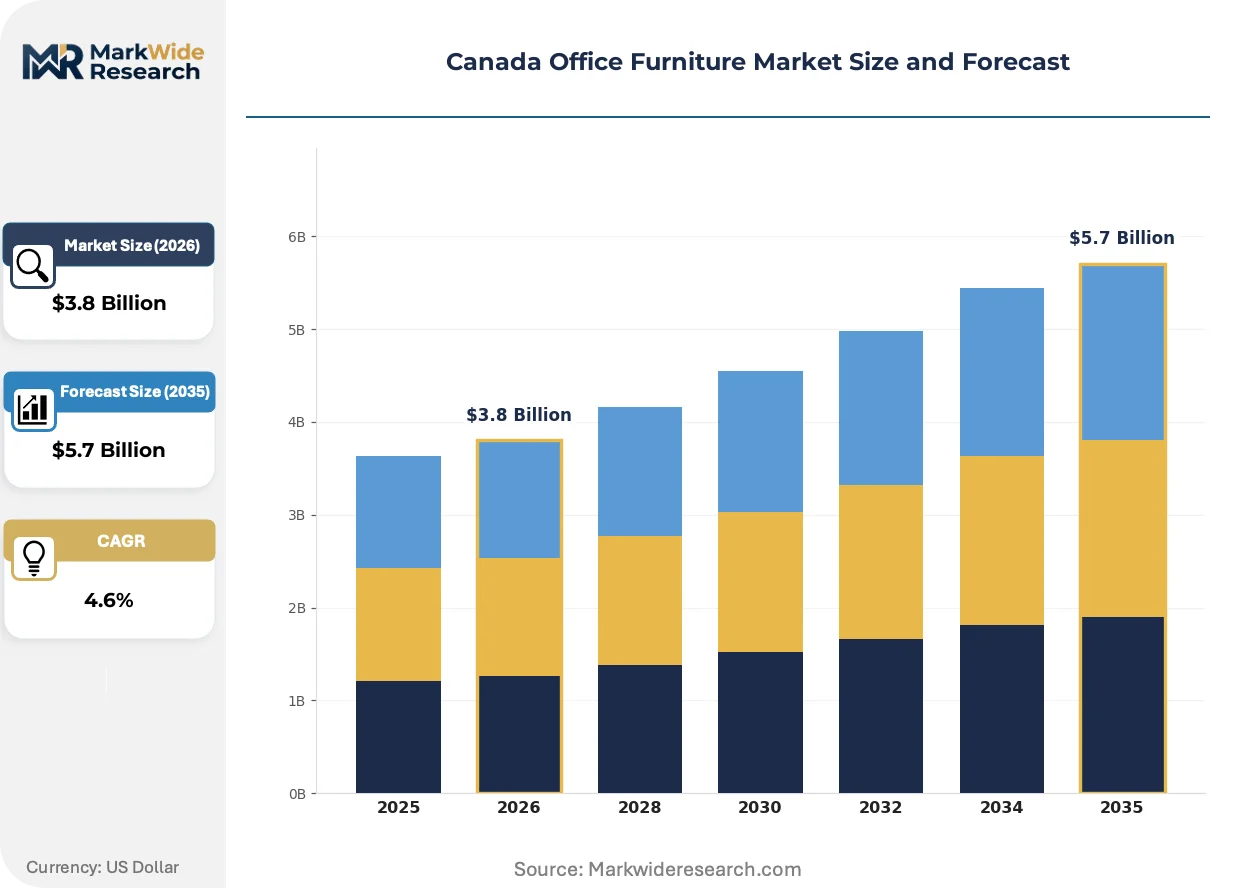
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Conference Tables, Filing Cabinets Distribution Channel: Direct Sales, Retail Stores, Online Platforms, Wholesalers End User: Corporates, Educational Institutions, Healthcare Facilities, Government Offices Design Style: Modern, Traditional, Ergonomic, Modular |
| Companies Covered | Haworth Inc., Groupe Lacasse, Global Furniture Group, MillerKnoll, Artopex, Teknion, Herman Miller Inc., Keilhauer, Steelcase Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Canada Office Furniture Market Strategic Shifts
Workplace technology convergence and regulatory tightening are compressing traditional product lifecycles while elevating service-content expectations in contract furniture procurement.
Sensor-integrated height-adjustable desk platforms are unifying occupancy analytics with ergonomic intervention, allowing facility managers to correlate workstation usage patterns with employee wellness program outcomes. Large corporate headquarters in Toronto and Vancouver are specifying these systems for new-build and renovation projects. This convergence is compressing the traditional separation between furniture procurement and building management system integration.
Health Canada's proposed updates to upholstered furniture flammability testing protocols under the Hazardous Products Act will expand chemical disclosure requirements and testing documentation burdens. Domestic manufacturers serving federal contracts face reformulation and certification renewal costs. Quebec-based suppliers with established government relationships are pre-positioning compliance documentation to defend institutional contract positions.
Corporate real estate teams are consolidating vendor relationships around single-source workplace system providers capable of delivering integrated design, installation, and post-occupancy reconfiguration services. This behavior compresses the addressable market for standalone catalog product distributors. The shift is most visible in Ontario's Greater Toronto Area, where consolidated procurement mandates from financial services and technology sector occupiers are reducing supplier counts per project.
Canada Office Furniture Market Segmentation
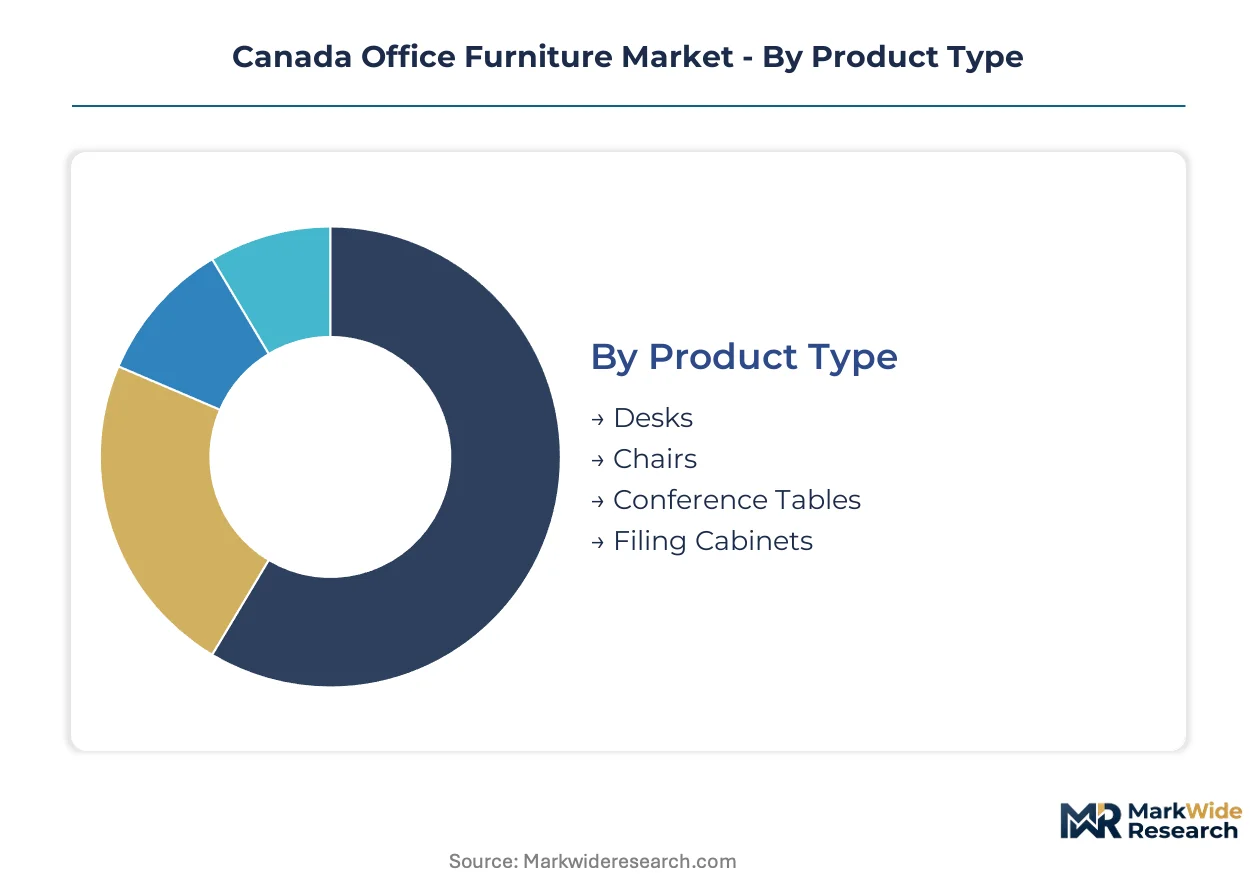
Segmentation in the Canada office furniture market reveals how procurement patterns split across compliance intensity, channel economics, and workplace transformation priorities. Understanding these divides exposes where specification power concentrates and where margin compression threatens.
Product Type:
Health Canada flammability certification under the Hazardous Products Act applies unevenly across product categories, with upholstered seating facing the heaviest testing burden while hard-surface workstations navigate simpler material disclosure requirements.
- Desks:Height-adjustable platforms with steel tube frames and high-pressure laminate surfaces dominate corporate fit-outs in Toronto and Vancouver. Financial services occupiers in Ontario's Greater Toronto Area commercial corridor are standardizing sit-stand specifications for new-build projects to address musculoskeletal injury prevention mandates.
- Chairs:Upholstered task seating with mesh or fabric suspension systems requires the most intensive CGSB performance documentation and Health Canada flammability compliance. Quebec-based manufacturers with established federal contract relationships are pre-positioning reformulated foam and textile certifications to defend institutional positions.
- Conference Tables:Modular power-integrated surfaces with cable management systems serve boardroom and huddle-space applications. Demand concentrates in technology sector headquarters seeking reconfigurable collaboration infrastructure.
- Filing Cabinets:Steel storage with powder-coat finishing and modular reconfiguration capability retains steady government and healthcare procurement volume despite digital document migration trends.
Desks sit at the top of the volume ranking, with chairs climbing the fastest as ergonomic specification intensity accelerates across corporate renovation cycles.
Distribution Channel:
Channel economics in Canada fragment sharply between high-touch contract negotiation for large transactions and automated fulfillment for smaller accounts, with margin structures reflecting service-content differentiation rather than product markup alone.
- Direct Sales:Contract negotiation and project engineering capabilities dominate corporate headquarters and government transactions where installation coordination and post-occupancy reconfiguration services add measurable value. This channel captures the highest per-project revenue but requires sustained relationship management infrastructure.
- Online Platforms:Direct-to-small-business fulfillment with accelerated lead times is displacing traditional catalog distributors for home-office and SME volume. Platform operators are investing in automated quoting systems that mesh with legacy installation service networks without degrading large-transaction capabilities.
- Retail Stores:Immediate-need fulfillment for individual consumers and micro-businesses operates on thinner margins and limited ergonomic product depth. Foot traffic dependence constrains expansion in secondary markets.
- Wholesalers:Inventory aggregation for independent dealers and regional contract furniture providers serves markets outside Ontario's dominant commercial corridor. Bilingual service capabilities unlock Quebec government contract access for certified manufacturers.
Direct sales retains the highest absolute revenue contribution, though online platforms are expanding most quickly as hybrid-work normalization sustains home-office equipment procurement.
End User:
End-user procurement behavior splits between consolidated vendor relationships for large corporate real estate teams and fragmented purchasing for institutional segments with specialized compliance requirements.
- Corporates:Single-source workplace system consolidation is compressing supplier counts per project, particularly among financial services and technology sector occupiers in Toronto. Integrated design, installation, and reconfiguration service expectations elevate qualification barriers for standalone product distributors.
- Government Offices:Canadian General Standards Board performance specifications and Health Canada flammability mandates filter into federal and provincial procurement criteria. Quebec-based suppliers with bilingual capabilities and established institutional relationships defend entrenched contract positions.
- Healthcare Facilities:Infection-control surface specifications and clean-air certification requirements drive specialized product selection for hospitals and clinics. Provincial green building codes with recycled content thresholds expand addressable market for certified product lines.
- Educational Institutions:Durability-rated furniture for K-12 and post-secondary applications emphasizes ten-plus year institutional lifecycles over ergonomic flexibility. Budget constraints favor commodity-grade catalog products with established supply relationships.
Corporates command the largest procurement volume, with healthcare facilities gaining share fastest as infection-control and indoor air quality specifications tighten.
Design Style:
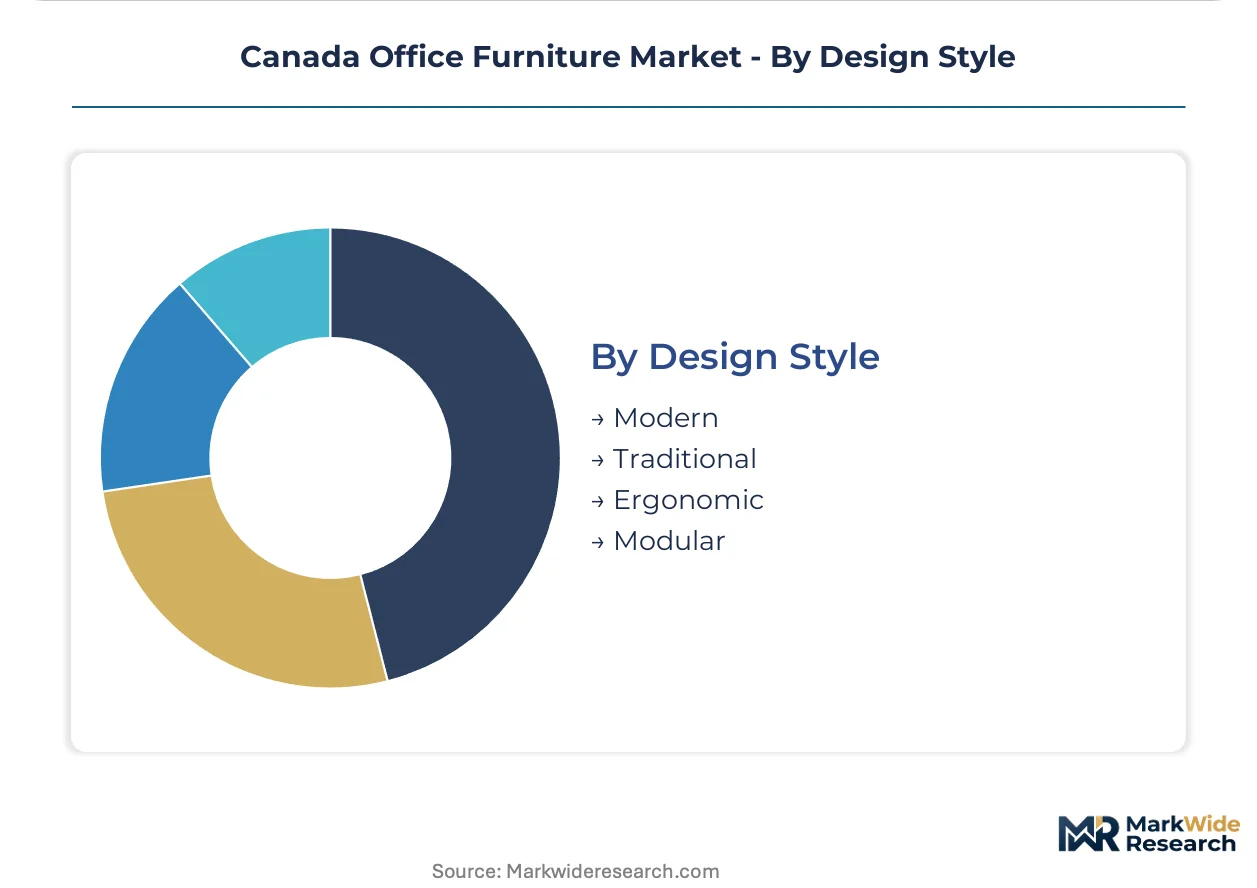
Design style specification reflects workplace transformation priorities, with ergonomic and modular systems pulling away from traditional aesthetics on engineering depth and reconfiguration flexibility.
- Ergonomic:Height-adjustable desk platforms and task seating with anthropometric adjustment ranges are standardizing in corporate fit-outs. Sensor-integrated workstations unifying occupancy analytics with wellness program outcomes command premium specification in Vancouver and Toronto headquarters.
- Modular:Load-rated structural connections enabling rapid reconfiguration serve agile workspace programs, though technical limits on institutional lifecycle ratings constrain pure flexibility claims. Demand concentrates in technology sector occupiers with frequent team restructuring.
- Modern:Minimalist aesthetic with clean lines and neutral palettes dominates financial services and professional services environments. Specification intensity varies with project budget tier rather than functional requirement.
- Traditional:Hardwood veneer and classic proportioning retains government and legal sector preference where aesthetic continuity signals institutional stability. Volume is contracting as renovation cycles favor contemporary workplace signaling.
Ergonomic design sits at the top of the volume ranking, with modular systems climbing the fastest as agile workspace programming spreads beyond technology sector early adopters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate real estate teams and government procurement officers anchor furniture demand across Canada's provincial economies, with concentration patterns tracking commercial construction cycles and institutional spending programs.
Ontario
Financial services and technology sector occupiers in Toronto drive specification intensity for ergonomic workstations and integrated workplace systems. Health Canada flammability standards under the Hazardous Products Act filter into federal procurement criteria for Ottawa-based government offices. The Greater Toronto Area commercial corridor concentrates renovation activity that is accelerating demand for height-adjustable platforms and sensor-integrated desks.
Quebec
Institutional procurement channels for government and healthcare facilities sustain specialized contract volumes with bilingual service requirements. Provincial green building codes specifying recycled content thresholds and indoor air quality certification expand addressable market for clean-air certified product lines. Montreal and Quebec City anchor a commercial furniture cluster where established suppliers defend entrenched positions through pre-positioned compliance documentation.
British Columbia
Technology sector headquarters in Vancouver command premium specifications for reconfigurable collaboration infrastructure and wellness-program-integrated workstations. The province's carbon disclosure requirements for public sector procurement are reshaping supplier qualification criteria. Vancouver's commercial real estate market is consolidating vendor relationships around single-source workplace system providers capable of delivering post-occupancy reconfiguration services.
Alberta
Energy sector corporate headquarters in Calgary generate cyclical demand for boardroom and executive office furniture tied to commodity price recovery phases. Provincial procurement policies emphasize durability-rated products for ten-plus year institutional lifecycles in government and healthcare applications. Edmonton serves as a distribution node for Prairie Provinces markets outside the dominant Ontario-Quebec corridor.
Atlantic Canada
Educational institutions and regional government offices sustain steady procurement volume for commodity-grade catalog products with established supply relationships. Federal infrastructure programs and post-secondary expansion projects intermittently stimulate demand for modular conference and collaboration spaces. Halifax anchors the region's limited commercial furniture specification activity.
Canada Office Furniture Market Competitive Environment
Capital-heavy domestic manufacturers compete with asset-light cross-border suppliers for corporate and institutional contracts, creating a tiered structure where integrated workplace system capabilities separate premium-tier competitors from catalog distributors. The market consolidates around single-source providers capable of delivering design, installation, and reconfiguration services, compressing addressable market for standalone product vendors. Three archetypes dominate: Western Michigan-based integrated system suppliers, Quebec-centered institutional specialists, and platform-driven direct-to-business operators. Competitive moves center on geographic service expansion and compliance certification pre-positioning.
Among cross-border integrated system suppliers, Haworth Inc. and Steelcase Inc. represent the capital-intensive archetype with manufacturing proximity to Canadian corporate headquarters. Groupe Lacasse exemplifies the Quebec-based institutional specialist archetype with entrenched government contract relationships. Teknion occupies a position bridging integrated system capabilities with advanced ergonomic platform specialization. These three anchors illustrate how service-content differentiation and compliance documentation capabilities determine competitive positioning across Ontario's dominant commercial corridor and Quebec's institutional procurement channels.
| Leading Market Players |
|---|
| Haworth Inc. |
| Groupe Lacasse |
| Global Furniture Group |
| MillerKnoll |
| Artopex |
| Teknion |
| Herman Miller Inc. |
| Keilhauer |
| Steelcase Inc. |
| Others |
Value Chain & Pricing Dynamics
Sensor-integrated workstation manufacturing is compressing cost economics for domestic assembly while amplifying cross-border component dependence, reshaping how Canadian buyers negotiate bundled service contracts against catalog-only suppliers.
Pricing Analysis
Bundled project engineering and installation services command substantial premiums over unbundled catalog transactions. Three-tier pricing structure across premium, standard, and economy levels separates sensor-integrated ergonomic systems from height-adjustable platforms and commodity-grade fixed desks. Price differentiation hinges on Health Canada flammability certification tier and CGSB performance documentation depth. Pricing pressure stems from steel tube and high-pressure laminate input volatility, with small-business buyers through online platforms exhibiting highest price sensitivity versus corporate real estate teams prioritizing specification compliance.
Supply Chain Analysis
Workforce availability constraints in Western Michigan furniture manufacturing clusters and Quebec's specialized upholstery operations limit domestic production scaling. Supply draws from the United States, Canada, and Mexico under USMCA trade provisions. Raw material dependencies center on commodity steel tube, thermosetting resins for high-pressure laminate bonding, and certified fire-retardant foam formulations. Tariff exposure on cross-border finished goods creates structural vulnerability for integrated workplace system procurement. Distribution runs through direct sales channels for large corporate headquarters, online platforms for small-business volume, and regional wholesalers serving Atlantic Canada and Prairie Provinces markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Canada office furniture market represents a late-cycle quality story where ergonomic specification intensity and regulatory compliance premiums are displacing price-driven procurement, particularly among Toronto and Vancouver corporate occupiers consolidating vendor relationships.
For Market Incumbents: Anchor contract positions through accelerated CGSB certification pre-positioning and bilingual service infrastructure expansion into Quebec institutional channels. Threats from platform-driven direct-to-business operators and commodity-grade import competition require defensive investment in post-occupancy reconfiguration service capabilities. Vertical integration into sensor-integrated workstation assembly within Ontario manufacturing footprints provides margin protection against cross-border logistics disruption. For New Entrants and Emerging Players: Health Canada's proposed Hazardous Products Act flammability protocol updates in Canada open a window for specialized compliance documentation services and reformulated foam supply partnerships. White-space targets include Atlantic Canada educational institution procurement and Alberta energy sector cyclical recovery phases. Go-to-market execution through automated quoting platforms meshing with legacy installation networks captures small-business volume without replicating incumbent relationship infrastructure. For Investors and Strategic Acquirers: Valuations sit cheapest among Quebec-based institutional specialists with entrenched government contract relationships and underutilized clean-air certified product line capacity. Long-term viability framing favors operators with demonstrated compliance documentation capabilities and circular economy program development. The signal to watch is consolidation velocity among Ontario corporate real estate teams reducing supplier counts per project below critical relationship-sustainability thresholds.| Strategic Initiative | Industry Significance |
|---|---|
| CGSB Certification Pre-Positioning | Accelerated compliance documentation defends federal and institutional contract positions against regulatory timeline compression. |
| Sensor-Integrated Platform Launch | Occupancy analytics integration captures premium specification share in Toronto and Vancouver corporate headquarters. |
| Quebec Service Infrastructure Expansion | Bilingual capabilities unlock underpenetrated government and healthcare procurement channels outside Ontario's corridor. |
| Circular Economy Program Development | Take-back and carbon disclosure capabilities create first-mover advantage as provincial mandates reshape supplier qualification. |
| Online Platform Channel Integration | Automated quoting systems capture small-business and home-office volume with faster fulfillment than traditional contract channels. |
Study Parameters
Coverage spans Ontario, Quebec, British Columbia, Alberta, and Atlantic Canada, with primary inputs from each provincial market. Primary interviews with corporate real estate directors, government procurement officers, furniture manufacturing plant managers, and installation service providers combined with secondary validation from Health Canada regulatory filings, Canadian General Standards Board performance specifications, provincial green building code documentation, and customs trade data. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Rate-of-change decomposition across product type, distribution channel, end user, and design style segmentation dimensions informed the analytical framework. CAGRs were derived from volume and value trajectory modeling incorporating renovation cycle timing, regulatory compliance cost pass-through assumptions, and hybrid-work normalization patterns. Industry-specific forecast inputs included steel and laminate commodity price sensitivity analysis and cross-border logistics coordination efficiency indices.
Revisions become necessary when Health Canada flammability protocol finalization timelines, provincial carbon disclosure mandate enforcement dates, or USMCA tariff renegotiation outcomes materialize differently than modeled assumptions. Forecasts reflect documented assumptions regarding specification intensity progression and channel migration velocity. Material deviation in named triggers warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Office Chairs Market
Office Furniture
Rental Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Europe Office Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Home Office Spending Market