
 Germany Office Furniture Market | 2026-2036
Germany Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Germany Office Furniture Market Foresight
Ergonomic certification tiers is collapsing the gap between mid-market and premium seating as buyers demand adjustable lumbar support and sit-stand compatibility at lower price points. Sedus leverages its vertical integration in Baden-Württemberg to control component quality from frame welding to final upholstery. König + Neurath AG anchors its position through system furniture platforms that integrate desking, storage, and partitioning into modular workplace ecosystems. Steelcase Inc. competes by extending its research partnerships with German ergonomics institutes to validate biomechanical performance claims.
Germany office furniture encompasses workstations, seating, storage, and collaborative fixtures engineered to DIN and EN dimensional standards with load ratings typically between 100 and 150 kilograms for task chairs and fire-retardant foam densities specified for commercial occupancy codes. Its primary purpose is to support knowledge-worker productivity while complying with workplace safety directives under the German Occupational Safety Act. Seating commands the deepest margin pools as replacement cycles compress and buyers prioritize 24-hour-use certifications for shift-work environments. Wood and metal hybrid constructions lead material preferences as procurement teams balance sustainability credentials with structural durability for high-traffic installations. Co-working spaces represent the fastest-growing application channel as operators in Hamburg and Frankfurt seek flexible lease terms and rapid reconfiguration capabilities.
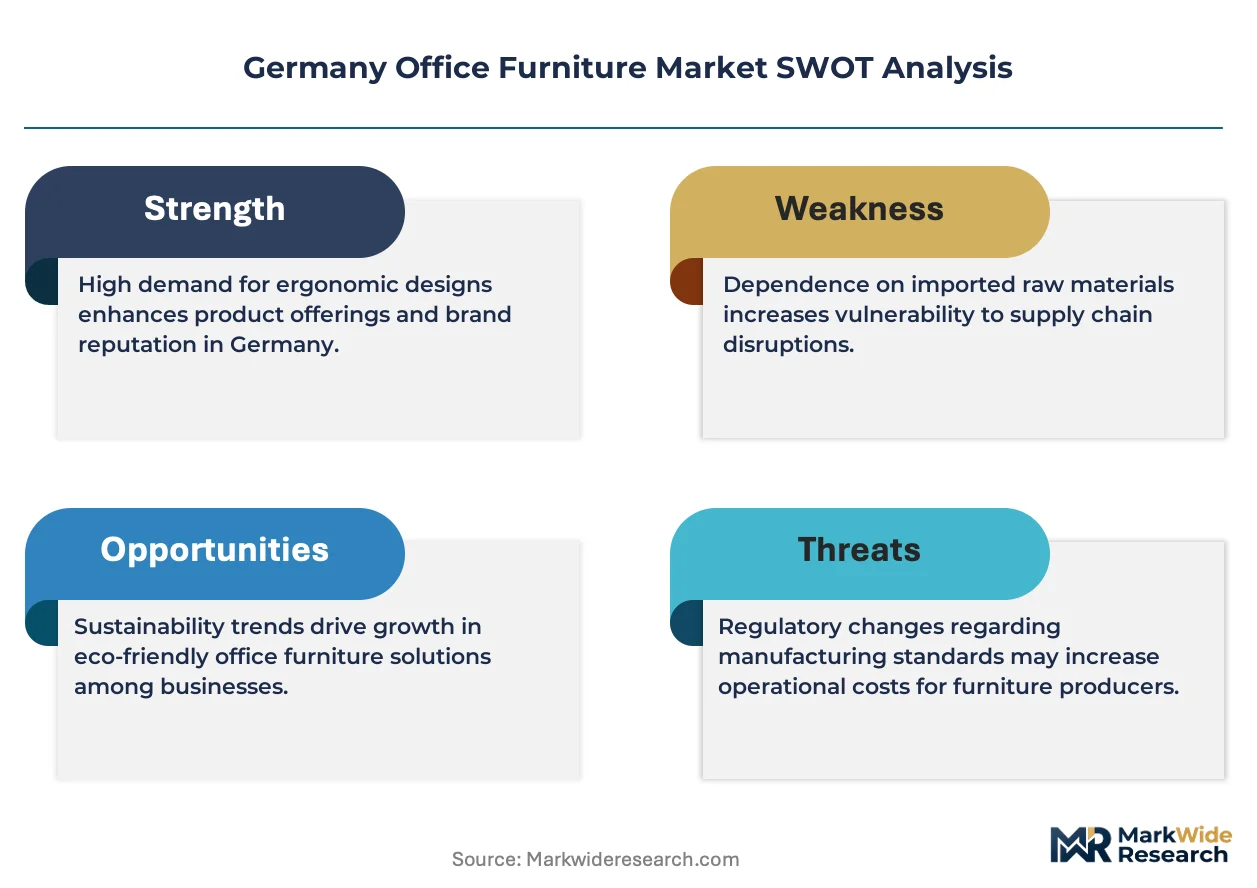
The German Social Accident Insurance DGUV mandates workstation assessments that directly shape employer purchasing criteria for adjustable furniture. REACH and the EU Green Deal's embodied carbon reporting requirements are forcing reformulation of adhesives, finishes, and upholstery substrates to eliminate restricted substances and document lifecycle impacts. Manufacturers must also navigate CE marking under the Construction Products Regulation for fixed storage and partition systems used in commercial builds. Stakeholders should monitor how the EU AI Act's emerging workplace surveillance provisions intersect with sensor-embedded smart furniture deployments in corporate retrofit programs.
Market Dynamics
The EU Green Deal's embodied carbon reporting mandate is restructuring procurement criteria across German commercial construction, forcing manufacturers to reengineer supply chains for documented lifecycle transparency from raw material extraction to end-of-life recovery.
Growth Catalysts
- REACH chemical reformulation deadlines:Manufacturers accelerating substitution of restricted flame retardants and adhesives ahead of sunset dates, opening certified product lines to public-sector tender pools.
- Co-working space proliferation:Operators in Hamburg and Frankfurt prioritizing rapid-reconfiguration furniture systems with lease-flexibility clauses driving replacement velocity.
- Baden-Württemberg manufacturing cluster density:Concentrated supplier networks around Waldshut-Tiengen and Nagold compressing component lead times and enabling just-in-sequence delivery to Berlin and Munich fit-out projects.
Market Restraints
- Steel and aluminum input volatility:Frame and base component costs fluctuating with energy-intensive metal production curtailments across European smelters.
- Polyurethane foam supply concentration:Three specialized chemical producers controlling fire-retardant upholstery substrate supply creating single-source vulnerability for mid-tier manufacturers.
- DIN certification timeline friction:Extended test-protocol durations for 24-hour-use task chair ratings delaying product launches by eight to fourteen months.
Strategic Opportunities
- Eastern German state retrofit wave:Saxony and Thuringia commercial building stock modernization programs creating demand for workstation assessments and compliant furniture replacement.
- Sensor-embedded furniture convergence:Integration of occupancy analytics with height-adjustable desking enabling usage-based facility management contracts.
- EU AI Act workplace surveillance provisions:Emerging compliance requirements for data-collecting furniture creating advisory service revenue streams around privacy-impact documentation.
Industry Challenges
- Ergonomic assessor talent scarcity:DGUV-mandated workstation evaluation backlog exceeding qualified occupational health specialist capacity in Bavaria and North Rhine-Westphalia.
- CE marking complexity under CPR:Fixed storage and partition systems requiring construction-product regulation compliance creating documentation bottlenecks for integrated system furniture platforms.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Germany Office Furniture Market |
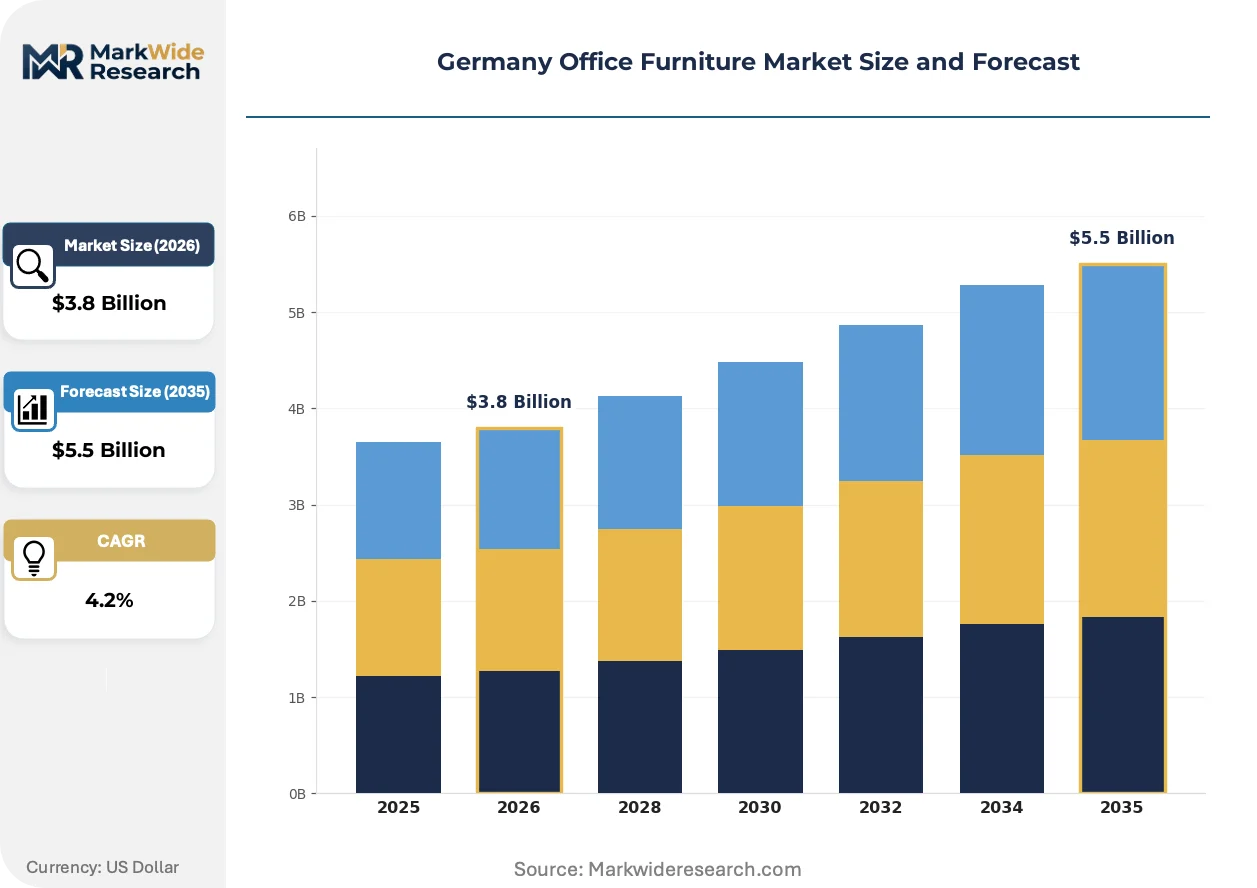
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.5 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Storage Cabinets, Cubicles, Conference Tables, Reception Furniture Material: Wood, Metal, Plastic, Laminate, Glass, Upholstery Application: Corporate Offices, Government Establishments, Educational Institutes, Co-working Spaces, Startups Customer Type: Small Enterprises, Medium Enterprises, Large Corporations, Freelancers, Consultants |
| Companies Covered | Sedus, Steelcase Inc., Haworth Inc., MillerKnoll Inc., König + Neurath AG, Vitra AG, Wilkhahn Wilkening + Hahne GmbH & Co. KG, Interstuhl Büromöbel GmbH & Co. KG, Dauphin HumanDesign Group, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Germany Office Furniture Market Shifts & Advancements
Biomechanical validation protocols and material traceability systems are converging to redefine competitive differentiation, compressing the traditional premium-mid-economy tier structure into certification-grade segmentation.
Recycled ocean-bound polypropylene is supplanting virgin petroleum-based plastics in task chair bases and armrest housings. Corporate procurement teams in Munich and Düsseldorf are mandating minimum recycled content thresholds in RFP specifications. This material transition is compressing margin structures for manufacturers lacking captive recycling partnerships or vertical control over polymer reprocessing.
The EU Green Deal's embodied carbon reporting requirements for building products are forcing reformulation of finishes, substrates, and adhesives to eliminate restricted substances and document lifecycle impacts. Manufacturers must now maintain chain-of-custody certification from timber sourcing through upholstery assembly. Fixed storage and partition systems face heightened scrutiny under CE marking obligations within the Construction Products Regulation.
Leasing and furniture-as-a-service contracts are displacing outright purchase for co-working operators and corporate real estate teams managing hybrid work transitions. Berlin and Frankfurt facility managers prioritize total-cost-of-occupancy metrics over capital expenditure minimization. This procurement evolution favors manufacturers with reverse-logistics capabilities and refurbishment infrastructure in the Baden-Württemberg cluster.
Germany Office Furniture Market Segmentation
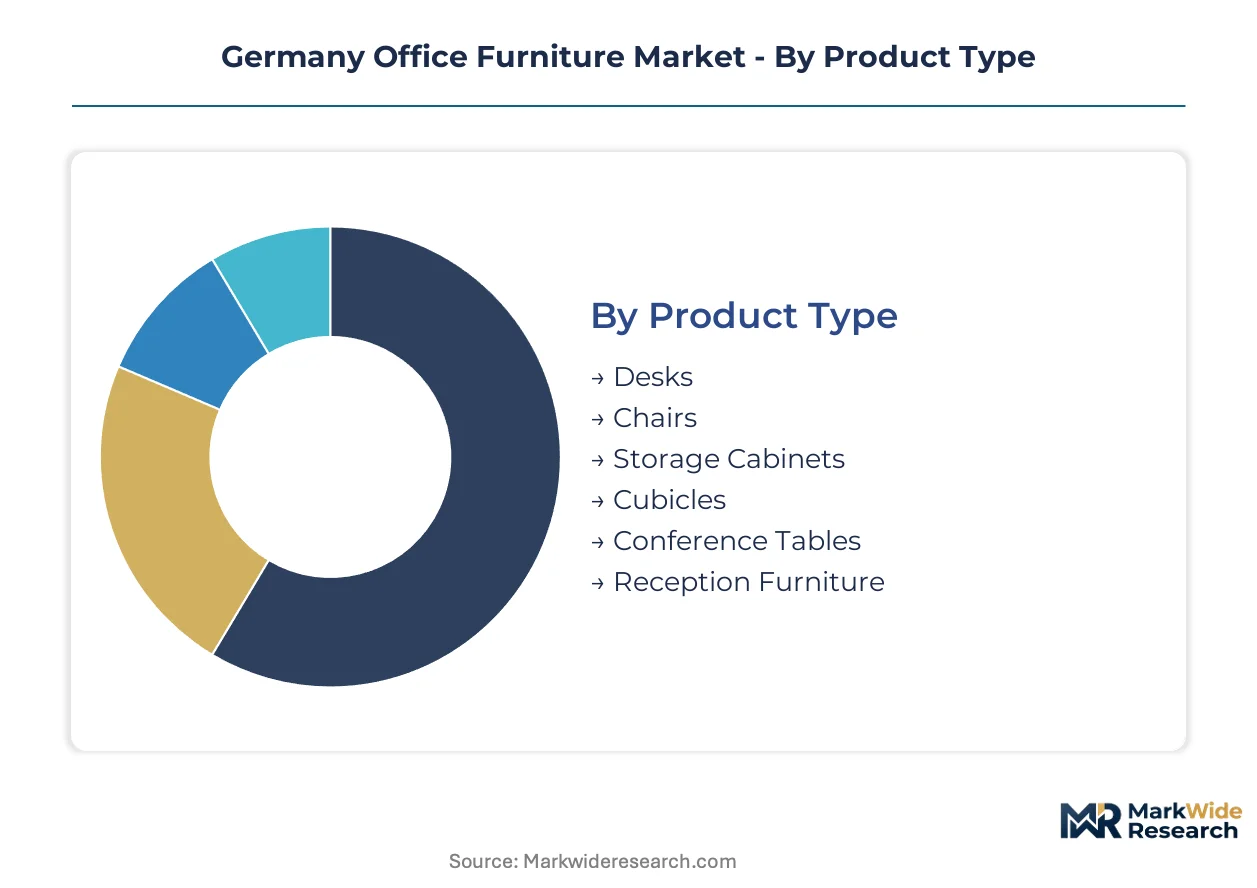
German office furniture procurement operates through four distinct classification systems that shape compliance pathways and margin structures. Each segmentation axis intersects with REACH chemical mandates, DGUV workstation assessments, and the EU Green Deal's embodied carbon reporting requirements.
Product Type:
REACH chemical restrictions and DGUV ergonomic mandates create divergent compliance burdens across furniture categories, with seating and desking facing the most intensive certification protocols.
- Desks:Height-adjustable workstations with electric or manual lift mechanisms dominate corporate fit-outs in Berlin and Munich. Employers prioritize sit-stand compatibility to satisfy DGUV-mandated workstation assessments and reduce musculoskeletal injury claims.
- Chairs:Task seating with adjustable lumbar support and 24-hour-use certifications commands premium positioning. Baden-Württemberg manufacturers leverage vertical control over frame welding and upholstery to meet compressed replacement cycles in shift-work environments.
- Storage Cabinets:Fixed and mobile units engineered to DIN dimensional standards with fire-retardant specifications.
- Cubicles:Modular partition systems requiring CE marking under the Construction Products Regulation for commercial builds.
- Conference Tables:Collaborative fixtures integrating cable management and power distribution for hybrid meeting spaces.
- Reception Furniture:First-impression seating and counter systems balancing aesthetic specification with commercial durability ratings.
Chairs handle the majority of throughput; co-working space proliferation is making desks the fastest mover on share.
Material:
Cost tiers stratify sharply around sustainability credentialing, with certified chain-of-custody timber and recycled content polymers commanding measurable premiums over conventional inputs.
- Wood:Engineered timber and solid hardwood constructions dominate premium corporate installations. Waldshut-Tiengen manufacturers maintain FSC and PEFC certification to satisfy Munich and Düsseldorf procurement teams mandating documented lifecycle impacts.
- Metal:Steel and aluminum frame components face input volatility from European smelter energy curtailments. Nagold fabricators hedge through just-in-sequence delivery contracts with regional steel processors.
- Plastic:Recycled ocean-bound polypropylene is supplanting virgin petroleum-based grades in task chair bases.
- Laminate:High-pressure surfacing materials undergoing reformulation to eliminate restricted formaldehyde emissions under REACH.
- Glass:Tempered glazing for executive desking and conference applications with specified load ratings.
- Upholstery:Fire-retardant foam substrates sourced from a concentrated supplier base creating single-source vulnerability.
Wood and metal hybrid constructions dominate value capture; recycled-content plastics are climbing the fastest as RFP thresholds harden.
Application:
Customer procurement maturity varies dramatically, with government and educational channels bound by public tender regulations while co-working operators prioritize lease-flexibility economics.
- Corporate Offices:Large-scale fit-out projects in Frankfurt and Hamburg specifying system furniture platforms. Procurement teams prioritize total-cost-of-occupancy metrics over capital expenditure minimization.
- Government Establishments:Federal and state-level tenders requiring certified sustainable materials and documented supply chain transparency.
- Educational Institutes:Universities and technical colleges in Saxony and Thuringia modernizing commercial building stock.
- Co-working Spaces:Operators seeking rapid-reconfiguration systems with refurbishment clauses.
- Startups:Early-stage companies favoring furniture-as-a-service contracts over outright purchase.
Corporate offices handle the majority of throughput; co-working spaces are expanding most quickly as hybrid work transitions mature.
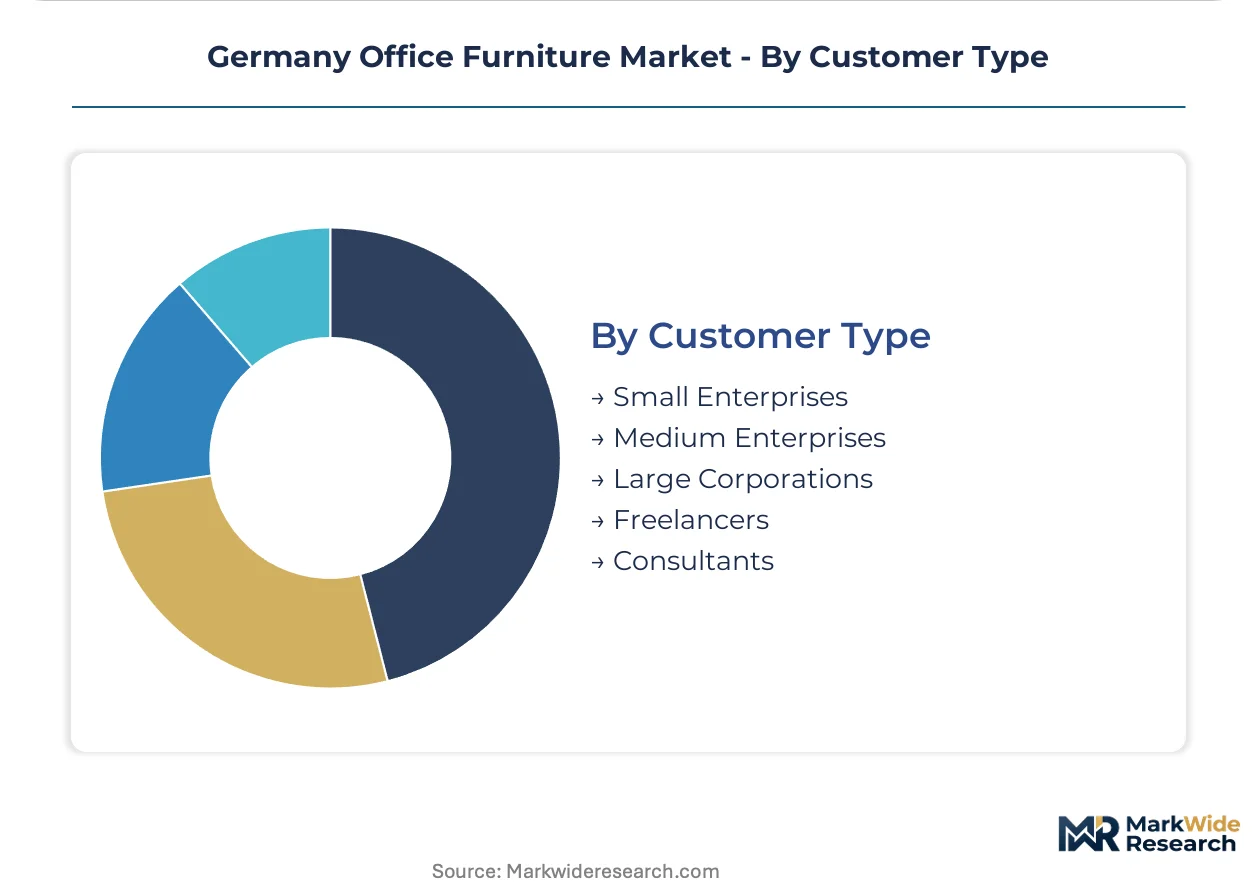
Customer Type:
Enterprise scale determines access to specialized ergonomic assessment services and volume pricing leverage, creating distinct service tier expectations.
- Large Corporations:Dedicated facility management teams with DGUV compliance officers conducting workstation evaluations. These buyers negotiate enterprise frameworks with Baden-Württemberg manufacturers for standardized deployments across Berlin and Munich locations.
- Medium Enterprises:Growing procurement sophistication seeking modular systems that scale with headcount fluctuations.
- Small Enterprises:Price-sensitive buyers dependent on reseller channels for compliance guidance.
- Freelancers:Individual purchasers prioritizing compact residential-office solutions.
- Consultants:Project-based buyers specifying temporary installations for client sites.
Large corporations handle the majority of throughput; medium enterprises are gaining share fastest as ergonomic assessor capacity constraints ease.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany's office furniture trade balance tilts toward net exports, with Baden-Württemberg manufacturers shipping system furniture to neighboring EU markets while importing specialized upholstery substrates from concentrated chemical suppliers in Belgium and the Netherlands.
Baden-Württemberg
Waldshut-Tiengen and Nagold anchor the densest manufacturing cluster, where frame welding and final upholstery operations compress lead times for Berlin and Munich fit-out projects. REACH chemical reformulation deadlines push local producers toward certified adhesive substitutes ahead of sunset dates. Vertical control from timber sourcing through assembly enables just-in-sequence delivery contracts.
Bavaria
Munich corporate headquarters drive premium workstation specifications with DGUV-mandated ergonomic assessments shaping procurement criteria. The state's occupational health specialist shortage creates evaluation backlogs that delay furniture deployment timelines. Nuremberg logistics hubs facilitate distribution to Saxony and Thuringia retrofit programs.
North Rhine-Westphalia
Düsseldorf procurement teams mandate minimum recycled content thresholds in RFP specifications, pressuring suppliers to document chain-of-custody certification. Cologne and Düsseldorf co-working operators prioritize furniture-as-a-service contracts with refurbishment clauses. The region's steel processor relationships hedge against energy-intensive metal production curtailments.
Berlin-Brandenburg
Capital region fit-out budgets expand for ergonomic workstations as government tenants modernize under federal sustainability directives. The EU AI Act's emerging workplace surveillance provisions intersect with sensor-embedded smart furniture trials in ministry retrofit programs. Potsdam technical colleges train assessors to address DGUV evaluation capacity constraints.
Hesse
Frankfurt financial services tenants prioritize total-cost-of-occupancy metrics over capital expenditure minimization in hybrid work transitions. The state's central location enables rapid-reconfiguration furniture distribution to Hamburg and Stuttgart co-working networks. CE marking complexity under the Construction Products Regulation creates documentation bottlenecks for partition system deployments.
Germany Office Furniture Market Competitive Landscape
Listed leaders compete with private specialists across capital structure and investment horizon dimensions, creating tiered competitive dynamics where publicly traded firms pursue scale economies while family-owned entities prioritize margin protection through captive manufacturing control. The vendor base organizes around three strategic archetypes: integrated system furniture platforms, ergonomic seating specialists, and regional contract manufacturers serving public-sector tender pools. Consolidation pressure concentrates among mid-tier producers lacking backward integration into frame fabrication or polymer reprocessing. Dominant competitive moves include M&A activity targeting distribution networks and strategic partnerships with ergonomics institutes for biomechanical validation protocols.
Among Baden-Württemberg-based fabricators, Sedus exemplifies vertical manufacturing control from component production through final assembly, while König + Neurath AG occupies a position within the system furniture platform tier integrating desking, storage, and partitioning into modular workplace ecosystems. Steelcase Inc. represents the multinational research-driven archetype extending validation partnerships with German ergonomics institutes to support performance claims in corporate procurement evaluations.
| Leading Market Players |
|---|
| Sedus |
| Steelcase Inc. |
| Haworth Inc. |
| MillerKnoll Inc. |
| König + Neurath AG |
| Vitra AG |
| Wilkhahn Wilkening + Hahne GmbH & Co. KG |
| Interstuhl Büromöbel GmbH & Co. KG |
| Dauphin HumanDesign Group |
| Others |
Supply & Pricing Matrix
Fourteen-to-eighteen-week component lead times for fire-retardant upholstery substrates concentrate pricing power with Belgium and Netherlands chemical suppliers, compressing margin flexibility for mid-tier German manufacturers while rewarding Baden-Württemberg fabricators with captive polymer reprocessing capabilities.
Pricing Analysis
Large corporate facility management teams anchor contract-based long-term procurement frameworks that stratify across certification-grade tiers rather than legacy premium-mid-economy segments. Price differentiation hinges on DGUV ergonomic certification level and documented chain-of-custody sustainability credentials. Cost compression in mid-market seating intensifies as recycled-content thresholds harden in Munich and Düsseldorf RFP specifications. Small enterprises exhibit highest price sensitivity due to reseller channel dependency, while government tenders show lowest sensitivity given compliance-driven procurement mandates.
Supply Chain Analysis
Inventory cycles for steel frame components stretch to twelve weeks during European smelter energy curtailments, exposing just-in-sequence delivery contracts to input volatility. Manufacturing concentrates in Germany, Belgium, and the Netherlands, with Baden-Württemberg anchoring final assembly and the Low Countries controlling specialized chemical substrates. The supply chain rests on polyurethane foam from three concentrated producers, steel and aluminum frame materials, and FSC-certified timber from regional forestry operations. Single-source vulnerability in fire-retardant upholstery substrates creates structural risk. Distribution runs through manufacturer-direct enterprise contracts, regional dealer networks, and furniture-as-a-service platform operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
System furniture platforms are displacing point-product vendors as corporate buyers prioritize modular workplace ecosystems with unified desking-storage-partition interoperability, creating winner-take-most dynamics around integrated specification control.
For Market Incumbents: Consolidate backward integration into polymer reprocessing and frame fabrication to defend margin position against REACH reformulation cost pressures. Acquire certified adhesive specialists ahead of sunset dates to lock public-sector tender access. Prioritize captive refurbishment infrastructure in the Baden-Württemberg cluster to capture furniture-as-a-service contract economics from Hamburg and Frankfurt co-working operators. For New Entrants and Emerging Players: Differentiate on rapid-reconfiguration lease-flexibility terms targeting Saxony and Thuringia commercial building modernization programs, where DGUV assessor scarcity delays incumbent deployment timelines. Penetrate the medium enterprise segment through modular scaling systems that align with headcount fluctuation needs. Pursue direct-to-lessee go-to-market models bypassing traditional dealer markups. For Investors and Strategic Acquirers: Carve-out targets emerge from family-owned Baden-Württemberg fabricators lacking succession liquidity but holding vertical manufacturing control and established DIN certification protocols. Long-term viability favors assets with demonstrated reverse-logistics capabilities and sensor-embedded furniture development pipelines. Monitor EU AI Act workplace surveillance rulemaking as inflection signal for privacy-impact advisory service valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Polymer Reprocessing | Captures margin from recycled ocean-bound polypropylene mandates in Düsseldorf procurement specifications. |
| Sensor-Embedded Furniture Development | Enables usage-based facility management contracts aligned with Frankfurt total-cost-of-occupancy metrics. |
| CE Marking Compliance Investment | Accelerates partition system deployment timelines constrained by Construction Products Regulation documentation bottlenecks. |
| Furniture-as-a-Service Platform Launch | Captures recurring revenue from Berlin and Hamburg co-working operators prioritizing lease flexibility. |
| Ergonomic Assessor Training Partnership | Addresses Bavaria and North Rhine-Westphalia evaluation backlogs delaying corporate fit-out completions. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with corporate facility managers, DGUV compliance officers, co-working space operators, Baden-Württemberg manufacturing executives, and public-sector procurement leads. Secondary validation drew from EU Green Deal implementation documents, REACH substance restriction timelines, DIN certification protocol specifications, and trade data from German federal statistics. Bottom-up segment sizing triangulated against top-down macroeconomic indicators.
Across the analysis window, the forecasting framework modeled product type, material composition, application channel, and customer scale dimensions alongside interoperability complexity tiers for system furniture platforms. CAGRs were derived from segment-level growth trajectory synthesis. Key inputs included co-working space lease velocity in Hamburg and Frankfurt, DGUV assessment backlog resolution rates, and embodied carbon reporting compliance cost curves.
The analysis sits within stated boundaries; outcomes outside sustained REACH reformulation timelines or EU AI Act surveillance rule finalization would require recalibration. Forecasts reflect assumptions regarding assessor capacity expansion and polymer recycling infrastructure buildout. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Office Seat Cushion Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Rental Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Institutional Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Japan Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Home Office Furniture Market