
 United Kingdom Office Furniture Market | 2026-2036
United Kingdom Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Office Furniture Market Analytics
Premium ergonomic seating and height-adjustable desking is decoupling from commodity panel-based systems on specification criteria and procurement channels. The Senator Group leverages domestic manufacturing scale to anchor public-sector contracts across Whitehall departments. Bisley Office Furniture sustains metal-storage specialization that differentiates its offer from laminated competitors. Tangent Office Furniture navigates mid-market project business through direct-sales relationships with regional fit-out contractors.
United Kingdom office furniture encompasses workstations, seating, storage, and meeting-room products engineered to BS EN 527 and BS EN 1335 dimensional standards for task performance and user safety. Manufacturers fabricate through steel tube bending, MFC panel pressing, foam-in-place upholstery, and powder-coat finishing to serve commercial workplace fit-out, refurbishment, and replacement cycles. Wood and metal materials dominate structural value, with fabric upholstery commanding margin concentration in executive and collaborative seating. Co-working spaces represent the fastest-growing end-user channel, while corporations retain volume leadership through framework agreements. Online retail is displacing showroom-dependent specification in small-business procurement.
The UK's Furniture and Furnishings (Fire) (Safety) Regulations and BS 5852 ignition-source standards mandate foam and fabric testing that filters import competition from non-compliant suppliers. BSI Kitemark certification and FSC chain-of-custody documentation shape tender eligibility for central government and NHS estates. Stakeholders must monitor how Building Regulations Part L efficiency targets and WELL certification criteria redirect specification toward low-emission materials and biophilic design integration.
Market Dynamics
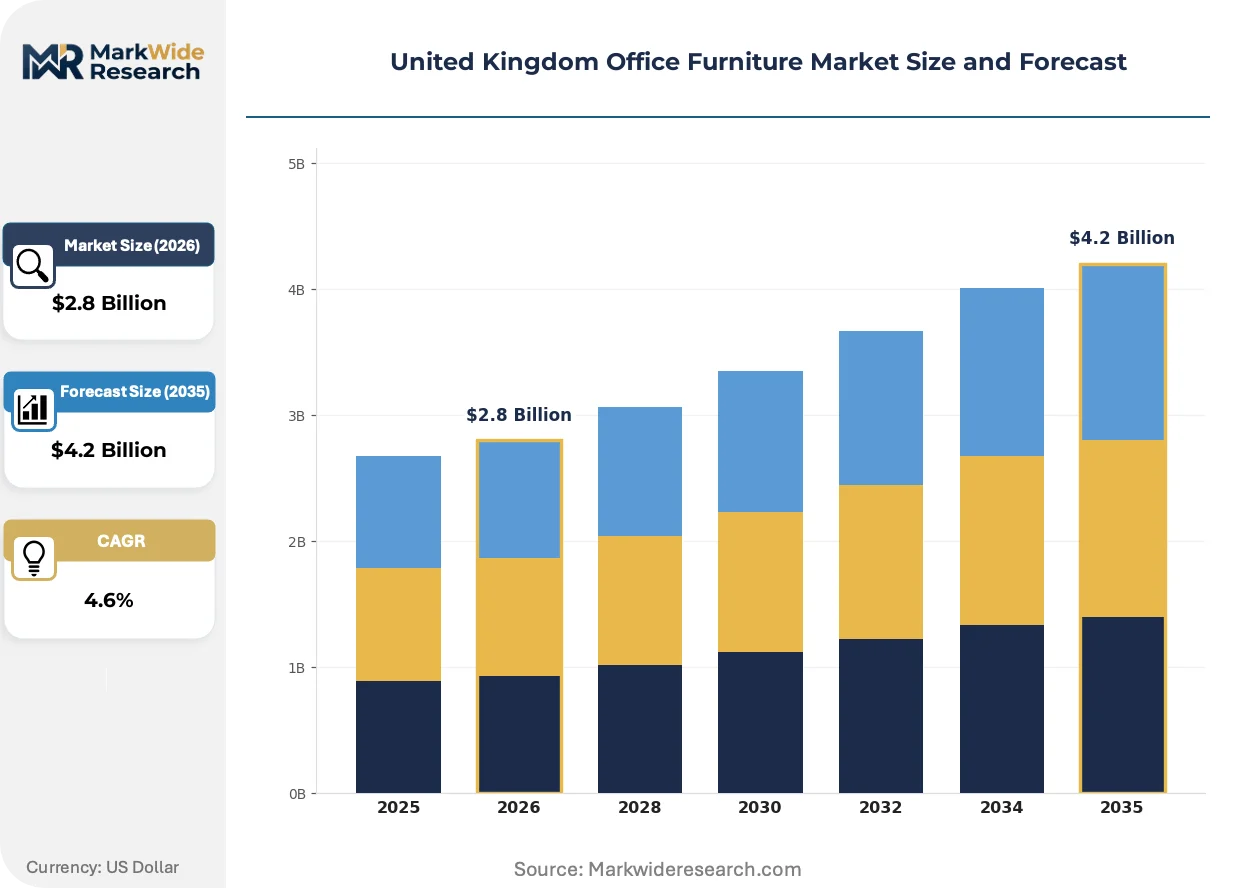
The United Kingdom office furniture market is restructuring around hybrid workplace mandates that compress replacement cycles and elevate ergonomic specification priority above cost minimization. This demand recalibration is fragmenting procurement authority between corporate real estate teams and distributed facilities managers.
Growth Catalysts
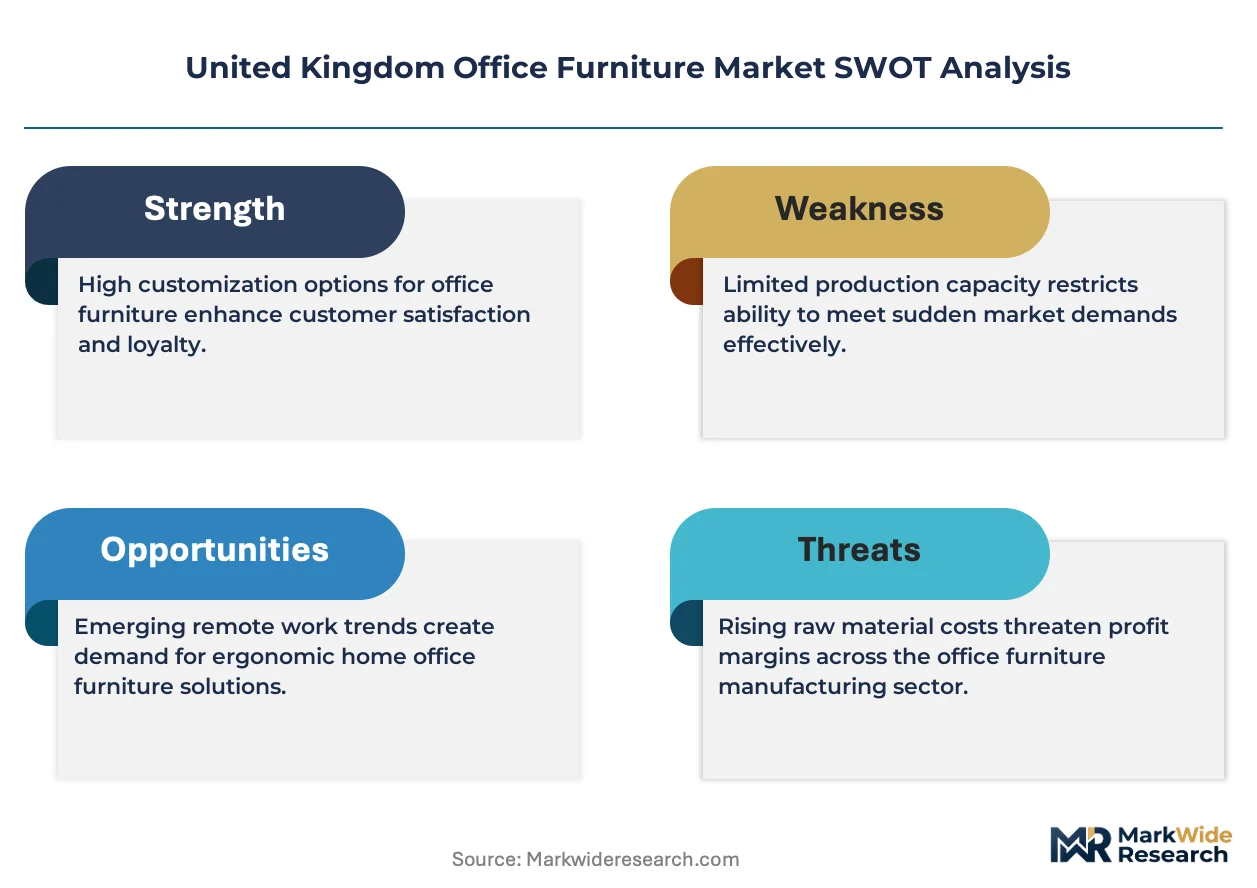
- BS 5852 ignition-source compliance:Mandatory foam and fabric testing under the Furniture and Furnishings (Fire) (Safety) Regulations filters low-cost import competition and sustains domestic manufacturer margin structures.
- Technology sector fit-outs:London and Manchester technology occupiers anchor premium demand for height-adjustable desking and acoustic meeting pods through accelerated refresh programs.
- WELL certification adoption:Biophilic design integration and low-emission material specifications in commercial developments redirect procurement toward certified product portfolios.
Market Restraints
- Steel and MFC panel input volatility:Structural steel tube and melamine-faced chipboard pricing fluctuations compress manufacturer margin predictability on fixed-price public sector frameworks.
- Greater London procurement concentration:Co-working space operators and corporate headquarters concentrate demand in the capital, leaving regional manufacturers with fragmented project pipelines and elevated logistics costs.
- BS EN 527 dimensional rigidity:Prescriptive workstation height and depth standards constrain modular system innovation and limit differentiation in task furniture categories.
Strategic Opportunities
- NHS estates modernization:BSI Kitemark-certified clinical and administrative furniture procurement under central government framework agreements offers volume stability distinct from cyclical commercial fit-out demand.
- Scotland and Northern England regional hubs:Underpenetrated corporate relocation activity outside Greater London creates whitespace for direct-sales relationships with regional fit-out contractors.
- Building Regulations Part L efficiency targets:Thermal performance and embodied carbon mandates in commercial refurbishment projects favor domestic manufacturers with FSC chain-of-custody documentation and short-haul supply chains.
Industry Challenges
- Upholstery craft skills shortage:Foam-in-place and fabric specification expertise attrition constrains seating production scaling and quality consistency across mid-tier manufacturers.
- powder-coat finishing capacity constraints:Environmental compliance investments for metal finishing operations require capital deployment that smaller fabricators struggle to access.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Office Furniture Market |
| Market Size in 2026 | $2.8 Billion |
| Market Size in 2035 | $4.2 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Cubicles, Conference Tables Material: Wood, Metal, Plastic, Fabric End User: Corporations, Government, Small Businesses, Co-working Spaces Distribution Channel: Online Retail, Direct Sales, Distributors, Showrooms |
| Companies Covered | The Senator Group, Bisley Office Furniture, Tangent Office Furniture, Verco Office Furniture, Flexiform Office Furniture, Verve Workspace, The Frem Group, Margolis Furniture, Lee & Plumpton, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Office Furniture Market Evolving Landscape
Sensor-integrated furniture and circular material flows are redefining product value propositions beyond static workstation functionality. These developments compress traditional replacement cycles while elevating service and certification components in buyer evaluation criteria.
Smart desking with occupancy sensing and usage analytics is expanding into corporate headquarters and co-working portfolios. Facility managers in London's technology and professional services occupiers deploy these systems to optimize space utilization and justify real estate expenditure. The technology is expanding into mid-market specifications as hardware costs decline and software integration standardizes.
The UK's Furniture and Furnishings (Fire) (Safety) Regulations enforcement tightening is reshaping import sourcing patterns. Non-compliant overseas suppliers face accelerated market exit as trading standards inspections intensify. Upholstery and foam-intensive seating categories experience the most pronounced supplier base contraction.
Small-business procurement behavior is fragmenting specification authority away from traditional dealer showrooms. Online retail platforms with configurators and direct delivery are capturing replacement and expansion orders below framework agreement thresholds. This channel rotation is most visible in home county commuter belt markets where distributed work patterns sustain residential office furniture demand.
United Kingdom Office Furniture Market Segmentation
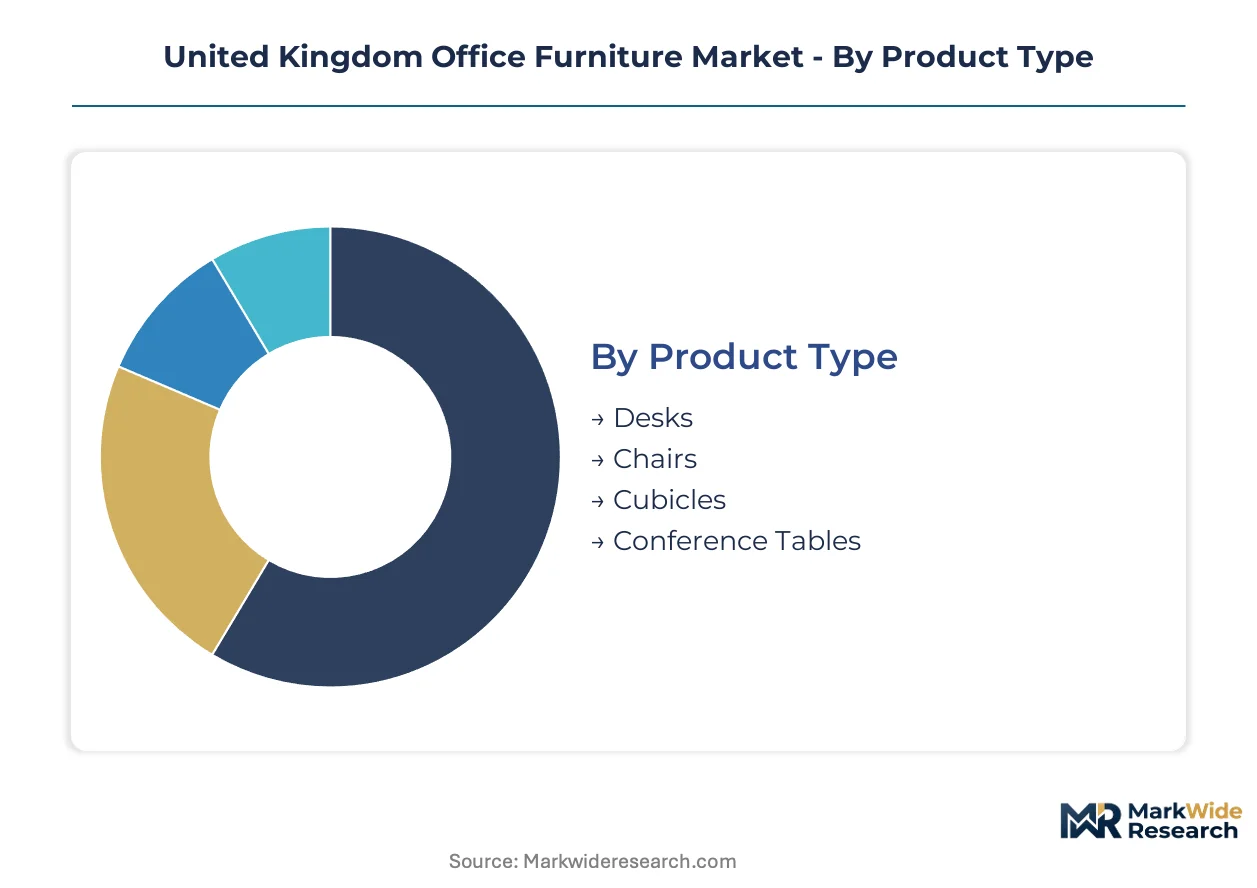
Office furniture procurement in the United Kingdom fragments across specification hierarchies that separate commodity replacement cycles from premium fit-out projects. Understanding these segment boundaries clarifies why height-adjustable desking commands margin structures unavailable to panel-based systems, and why co-working operators source through channels distinct from NHS estates teams.
Product Type:
Standalone workstation products operate independently within fit-out specifications, while integrated systems require synchronized procurement with power, data, and acoustic infrastructure.
- Desks:Height-adjustable frames with MFC tops dominate technology sector fit-outs in London and Manchester. Fixed-height panel systems retain volume leadership through public sector framework agreements where BS EN 527 dimensional compliance simplifies tender evaluation.
- Chairs:Foam-in-place upholstery with synchronous mechanisms commands the widest specification variance between executive suites and task seating. Ergonomic certification under BS EN 1335 filters import competition and sustains domestic manufacturer margin concentration in premium tiers.
- Cubicles:Acoustic screening systems integrate with open-plan desking to create semi-private work zones. Demand concentrates in financial services occupiers refreshing legacy footprint.
- Conference Tables:Cable-managed tops with integrated power modules serve meeting room refurbishment cycles. Video-conferencing hardware compatibility shapes specification criteria in corporate headquarters.
Chairs lead volumes today; height-adjustable desks are gaining share fastest.
Material:
Cost tier stratification separates structural materials commanding framework agreement eligibility from surface finishes driving specification differentiation.
- Wood:MFC panels with FSC chain-of-custody documentation anchor central government and NHS tender eligibility. Melamine-faced chipboard pricing volatility compresses manufacturer margin predictability on fixed-price contracts.
- Metal:Steel tube framing with powder-coat finishing dominates storage and desking structural elements. Environmental compliance investments for finishing operations constrain smaller fabricator participation.
- Plastic:Polypropylene shells and base components serve mid-market seating price points. Recycled content specifications are expanding in WELL-certified developments.
- Fabric:Upholstery textiles face mandatory BS 5852 ignition-source testing that filters non-compliant import supply. Fabric specification expertise attrition constrains seating production scaling across mid-tier manufacturers.
Metal and wood dominate structural value; fabric commands the steepest margin concentration.
End User:
Procurement authority fragmentation separates centralized real estate teams from distributed facilities managers with divergent specification priorities.
- Corporations:Framework agreements with national dealers govern headquarters refresh programs. Technology occupiers in London and Manchester accelerate replacement cycles through WELL certification mandates.
- Government:BSI Kitemark certification and FSC documentation shape Whitehall department tender eligibility. NHS estates modernization offers volume stability distinct from cyclical commercial fit-out demand.
- Small Businesses:Online retail platforms with configurators capture replacement orders below framework thresholds. Home county commuter belt markets sustain residential office furniture demand from distributed work patterns.
- Co-working Spaces:Operators concentrate procurement in Greater London with accelerated refresh programs. Acoustic meeting pods and sensor-integrated desking anchor premium specification in this channel.
Corporations retain volume leadership; co-working spaces are expanding most quickly.
Distribution Channel:
Customer type determines channel selection, with specification complexity dictating whether showroom consultation or direct digital procurement prevails.
- Online Retail:Configurator-driven platforms with direct delivery capture small-business and home office replacement demand. This channel is displacing showroom-dependent specification in orders below framework agreement thresholds.
- Direct Sales:Manufacturer relationships with regional fit-out contractors serve mid-market project business outside Greater London concentration. Tangent Office Furniture navigates this channel through established contractor networks.
- Distributors:National dealer networks hold framework agreement relationships with corporate real estate teams. Inventory holding and installation capability differentiate distributor value from pure digital channels.
- Showrooms:Physical specification consultation retains importance for executive seating and boardroom furniture where tactile evaluation shapes procurement decisions. London concentration elevates showroom relevance for premium segments.
Distributors lead transaction volumes today; online retail is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
London's financial services and technology workforce concentration anchors national demand, with regional distribution networks extending procurement authority across England, Scotland, Wales, and Northern Ireland.
Greater London and the Southeast
Technology sector occupiers in Canary Wharf and Shoreditch accelerate refresh cycles for height-adjustable desking and acoustic meeting pods. The Greater London Authority's planning frameworks mandate WELL certification for major commercial developments. Co-working operators concentrate procurement decisions in this corridor, with WeWork and IWG maintaining flagship locations in the Square Mile.
Midlands Manufacturing Belt
Automotive and logistics headquarters in Birmingham and Coventry sustain demand for panel-based systems through framework agreements. The West Midlands Combined Authority's industrial strategy prioritizes commercial property refurbishment. Wolverhampton and Telford host steel-tube bending and powder-coat finishing clusters serving national distribution networks.
North England
Corporate relocation activity in Manchester and Leeds generates premium fit-out demand distinct from London specifications. The Northern Powerhouse Partnership's infrastructure commitments elevate regional office stock quality. MediaCityUK in Salford anchors technology sector clustering that rivals Thames Valley concentrations.
Scotland
Financial services and public sector estates in Edinburgh and Glasgow sustain volume procurement through NHS Scotland and Scottish Government frameworks. The Scottish Futures Trust's property investment programs standardize BSI Kitemark-certified specifications. Aberdeen's energy sector contraction redirects demand toward administrative refurbishment cycles.
Wales and Northern Ireland
Public sector procurement concentration in Cardiff and Belfast offers volume stability distinct from cyclical commercial demand. The Welsh Government's procurement frameworks emphasize FSC chain-of-custody documentation. Belfast's Titanic Quarter regeneration attracts corporate service centers with accelerated fit-out timelines.
United Kingdom Office Furniture Market Competitive Landscape
Top-tier vendors anchor public sector frameworks and national corporate accounts, while mid-scale fabricators compete through regional fit-out contractor relationships and specialization in metal storage or ergonomic seating. The vendor base stratifies across domestic manufacturing scale, import-dependent distribution, and direct-to-business digital channels. Three archetypes dominate: integrated manufacturers with captive steel and upholstery operations, storage specialists leveraging powder-coat metal finishing differentiation, and project-focused mid-market players navigating contractor-direct sales. Competitive moves center on NHS estates framework positioning and co-working operator volume capture.
Within the domestic manufacturing tier, The Senator Group and Bisley Office Furniture exemplify scale-driven positioning through public sector anchoring and metal-storage specialization respectively. Tangent Office Furniture occupies the mid-market project segment through established regional contractor networks. These three entities represent distinct competitive vectors: framework-dependent volume, product-category focus, and relationship-driven project execution.
| Leading Market Players |
|---|
| The Senator Group |
| Bisley Office Furniture |
| Tangent Office Furniture |
| Verco Office Furniture |
| Flexiform Office Furniture |
| Verve Workspace |
| The Frem Group |
| Margolis Furniture |
| Lee & Plumpton |
| Others |
Value Network & Pricing Analysis
Building Regulations Part L efficiency targets and WELL certification criteria gate both qualified supply and premium-tier pricing access in the United Kingdom office furniture market. Domestic manufacturers with FSC chain-of-custody documentation and short-haul supply chains command pricing power over import-dependent competitors facing compliance filtration.
Pricing Analysis
Bundled installation and after-sales service separates framework-agreement pricing from stripped-back online retail quotations. Three-tier pricing structure across premium, standard, and economy levels stratifies by certification grade and volume scale, with BSI Kitemark-certified products commanding substantial premiums over non-certified alternatives. Price differentiation stems from ergonomic certification tier and geographic delivery cost, with steel and MFC panel input volatility compressing margins on fixed-price public sector contracts. Small businesses exhibit highest price sensitivity through configurator-driven platforms, while technology sector occupiers in London and Manchester demonstrate lowest sensitivity due to WELL certification mandates.
Supply Chain Analysis
Reverse-logistics flows for refurbishment and remanufacturing are expanding as circular material commitments reshape procurement evaluation criteria. Manufacturing concentration rests on domestic steel-tube bending clusters in the West Midlands and powder-coat finishing operations in Wolverhampton and Telford, with MFC panel pressing drawing from continental European suppliers. Raw material dependencies center on structural steel tube, melamine-faced chipboard, and foam-in-place upholstery chemicals. Single-source vulnerability in MFC panel supply creates exposure to commodity price volatility. Distribution runs through national dealer networks holding framework agreement relationships with corporate real estate teams.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United Kingdom office furniture market functions as a stable compounder anchored by NHS estates modernization and public sector framework renewal cycles that insulate domestic manufacturers from cyclical commercial fit-out volatility.
For Market Incumbents: To counter upholstery craft skills shortage constraining seating production scaling, incumbents should anchor capacity addition in West Midlands manufacturing clusters and deepen certification investment for BSI Kitemark clinical furniture eligibility. Captive steel-tube bending operations and foam-in-place upholstery expertise defend margin structures against import competition filtered by BS 5852 ignition-source compliance. For New Entrants and Emerging Players: Sensor-integrated desking with occupancy analytics offers a technology-first wedge into mid-market corporate specifications as hardware costs decline and software integration standardizes. White-space targets include Scotland and Northern England regional hubs where underpenetrated corporate relocation activity creates whitespace for direct-sales relationships with regional fit-out contractors. Go-to-market execution should prioritize WELL-certified developments requiring low-emission material specifications and biophilic design integration. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-scale fabricators with regional contractor networks and metal-storage specialization distinct from laminated competitors. Long-term viability framing centers on 5-10 year public sector framework anchoring and co-working operator volume capture. Acquisition target archetype: domestic manufacturers with captive powder-coat finishing capacity and FSC chain-of-custody documentation. The signal to watch is tightening enforcement of the Furniture and Furnishings (Fire) (Safety) Regulations accelerating non-compliant supplier exit.| Strategic Initiative | Industry Significance |
|---|---|
| BSI Kitemark Certification Investment | Opens NHS estates and Whitehall framework eligibility distinct from cyclical commercial demand. |
| Sensor-Integrated Product Development | Captures corporate headquarters and co-working operator specifications as hardware costs decline. |
| West Midlands Capacity Expansion | Consolidates steel-tube bending and powder-coat finishing clusters serving national distribution networks. |
| FSC Chain-of-Custody Documentation | Satisfies central government and NHS tender eligibility requirements filtering import competition. |
| Regional Fit-Out Contractor Partnerships | Builds direct-sales presence in Scotland and Northern England outside Greater London procurement concentration. |
Research Methodology
Coverage spans Greater London, the Midlands Manufacturing Belt, North England, Scotland, Wales, and Northern Ireland, with primary inputs from each region combined with secondary validation. Primary interviews engaged facilities managers at technology sector occupiers, procurement leads at co-working operators, framework agreement officers at NHS estates, regional fit-out contractors, and upholstery craft specialists. Secondary sources included BSI certification databases, FSC chain-of-custody registries, Furniture and Furnishings (Fire) (Safety) Regulations enforcement records, and central government procurement frameworks. Bottom-up and top-down triangulation cross-validated manufacturer shipment data against end-user procurement disclosures.
Rate-of-change decomposition anchored the analytical framework across the analysis window, segmenting by product type, material, end user, and distribution channel with additional dimensioning for certification tier and geographic procurement cluster. CAGRs derived from historical trajectory analysis adjusted for regulatory inflection points and input cost volatility assumptions. Industry-specific forecast inputs incorporated WELL certification adoption curves and BS 5852 compliance enforcement intensity.
The model holds under stable regulatory enforcement and continued public sector framework renewal; deviation in steel and MFC panel input volatility or accelerated non-compliant supplier exit would shift volume and value trajectories. Practitioners should monitor Building Regulations Part L efficiency target tightening and WELL certification mandate expansion for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
United States Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Europe Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
India Office Furniture Market
Office Furniture
Indonesia Office Furniture Market