
 Rental Furniture Market | 2026-2036
Rental Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Rental Furniture Market Outlook
Corporate buyer concentration is consolidating around multinationals seeking standardized housing solutions for rotating talent. Rent-A-Center anchors North American distribution through its brick-and-mortar network and lease-to-own infrastructure. Furlenco dominates Indian metro markets with full-home subscription models designed for mobile professionals. Feather differentiates in coastal U.S. cities through curated, design-forward packages targeting technology sector relocations.
Rental furniture encompasses durable goods leased under short-to-medium term contracts, typically constructed with commercial-grade fabrics, reinforced joinery, and modular frames engineered for repeated installation cycles. The category serves cost-conscious consumers, transient workforces, and event operators requiring flexible asset deployment without ownership burden. Sofas and desks lead volume across residential and corporate channels, while dining sets capture premium margins among event planners seeking statement pieces for temporary installations. Online platforms now compete aggressively with legacy showrooms, though rental agencies retain pricing power in luxury tiers where white-glove delivery and installation justify higher rates.
The U.S. Consumer Financial Protection Bureau oversees lease disclosure rules, while the EU Green Deal and REACH frameworks govern chemical content and end-of-life recovery obligations for cross-border operators. California's SB 54 extended producer responsibility mandates are forcing rental fleet operators to document recycling pathways and reduce single-use packaging in logistics. Stakeholders must monitor how municipal zoning in dense cities restricts warehouse expansion, as last-mile inventory positioning becomes the decisive cost variable.
Market Dynamics
The rental furniture market is being fundamentally restructured by circular economy mandates that force asset-light business models to internalize end-of-life recovery costs and redesign logistics for repeated refurbishment cycles.
Growth Catalysts
- EU Green Deal implementation:Extended producer responsibility frameworks in member states now require rental fleet operators to document material recovery pathways, accelerating standardization of modular furniture designs that simplify disassembly and component reuse.
- Hybrid workforce normalization:Corporate housing providers now contract for furnished apartments on 3-12 month cycles rather than purchasing depreciating assets, converting capital expenditure into predictable operational spending.
- Urban density premiums:Young professionals in Bengaluru, Mumbai, and São Paulo face space constraints and job mobility that make ownership impractical, driving subscription uptake for living room and bedroom packages.
Market Restraints
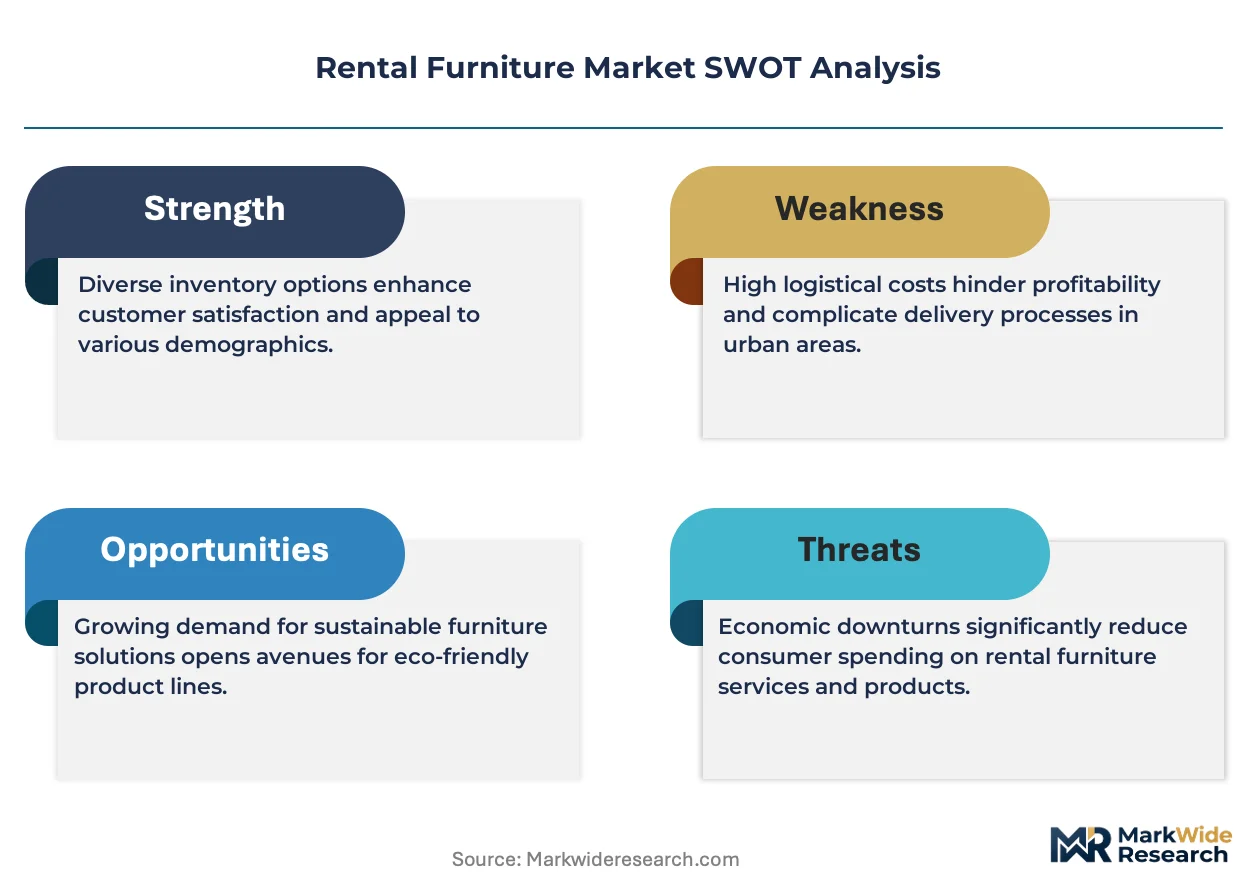
- Freight cost volatility:Container shipping rates and last-mile fuel costs compress margins on bulky items like sofas and dining sets, particularly for operators without owned warehouse networks in tier-one cities.
- Supplier concentration in textile inputs:Commercial-grade upholstery fabrics depend on concentrated petrochemical supply chains in East Asia, exposing rental fleets to input cost spikes and dye chemistry compliance gaps under REACH.
- Residual value uncertainty:Depreciation schedules for refurbished furniture lack standardized benchmarks, complicating balance sheet treatment and investor due diligence for fleet expansion financing.
Strategic Opportunities
- Secondary city penetration in India:Hyderabad, Pune, and Chennai exhibit rising IT sector employment with minimal rental furniture presence, offering first-mover positioning before local competitors establish depot infrastructure.
- Event and exhibition verticals:Trade show organizers and temporary hospitality installations represent underserved demand for statement dining sets and lounge configurations on sub-30-day cycles.
- Integration of RFID tracking with predictive maintenance:Combining embedded sensors with fleet management software enables condition-based refurbishment scheduling, reducing premature retirement and improving asset utilization rates.
Industry Challenges
- Certification fragmentation:Operators must navigate overlapping BIFMA durability standards, California TB 117 flammability requirements, and emerging EU digital product passports, extending compliance timelines for cross-border fleet deployment.
- Warehouse zoning restrictions:Municipal land-use policies in dense metropolitan areas limit expansion of refurbishment depots and buffer inventory staging, forcing reliance on expensive third-party logistics partnerships.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rental Furniture Market |
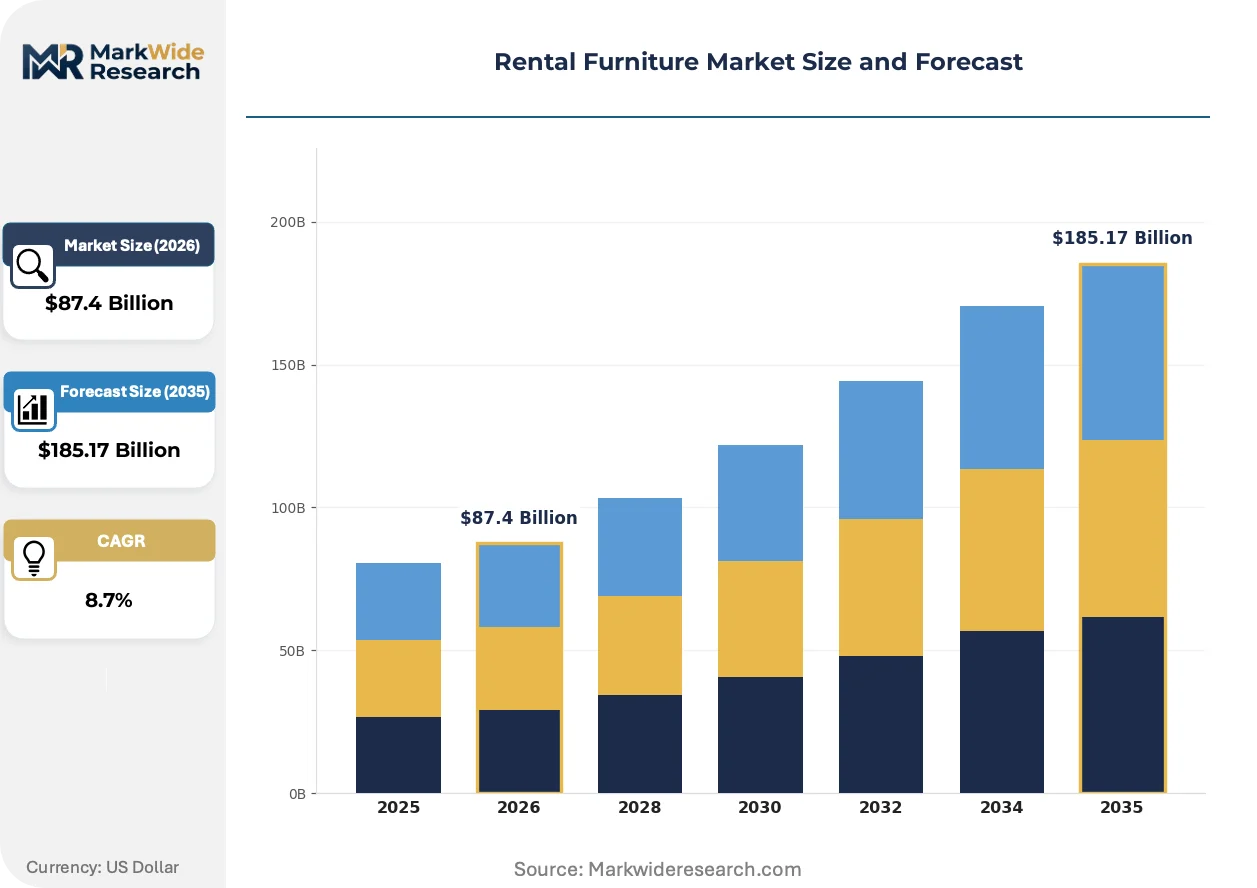
| Market Size in 2026 | $87.4 Billion |
| Market Size in 2035 | $185.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Sofas, Beds, Dining Sets, Desks Customer Type: Residential, Corporate, Event Planners, Students Distribution Channel: Online, Showrooms, Rental Agencies, Third-Party Platforms Price Tier: Economy, Mid-Range, Premium, Luxury |
| Companies Covered | Rent-A-Center, Furlenco, The Everset, Fernished Inc., Aaron's LLC, Feather, Luxe Modern Rentals, RentoMojo, Fashion Furniture Rental, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rental Furniture Market Strategic Shifts
Asset tracking and predictive analytics are converging with circular design principles to transform how rental furniture fleets are managed, financed, and recovered across their operational lifecycles.
RFID and IoT-enabled inventory systems are consolidating control over dispersed furniture assets. Rental operators now embed durable tags in sofa frames and table legs to monitor location, usage intensity, and condition remotely. Corporate housing providers and event rental agencies are adopting these systems fastest, using real-time visibility to optimize redistribution and reduce idle inventory. This consolidation of data streams is compressing working capital requirements and enabling dynamic pricing based on actual utilization rather than static depreciation schedules.
REACH chemical restrictions are forcing material substitutions across upholstered furniture supply chains. The European Chemicals Agency has expanded restricted substance lists to cover flame retardants and stain-resistant coatings commonly used in commercial fabrics. Fleet operators serving EU markets must now validate alternative chemistries through third-party testing, adding 8-14 weeks to procurement cycles. Upholstery suppliers with pre-certified low-VOC fabric lines are capturing preference share from rental companies seeking to avoid compliance delays.
Subscription bundling is displacing single-item rental contracts in residential channels. Young professionals now expect living room, bedroom, and home office packages with unified billing and swap flexibility rather than negotiating separate agreements per category. Online platforms are responding with tiered service levels—basic delivery, white-glove installation, or full room styling—extracting premium pricing in coastal U.S. cities where technology sector relocations concentrate. This behavioral shift is visible most acutely in Seattle, Austin, and Denver, where job mobility and housing turnover sustain demand for turnkey furnishing solutions.
Rental Furniture Market Segmentation
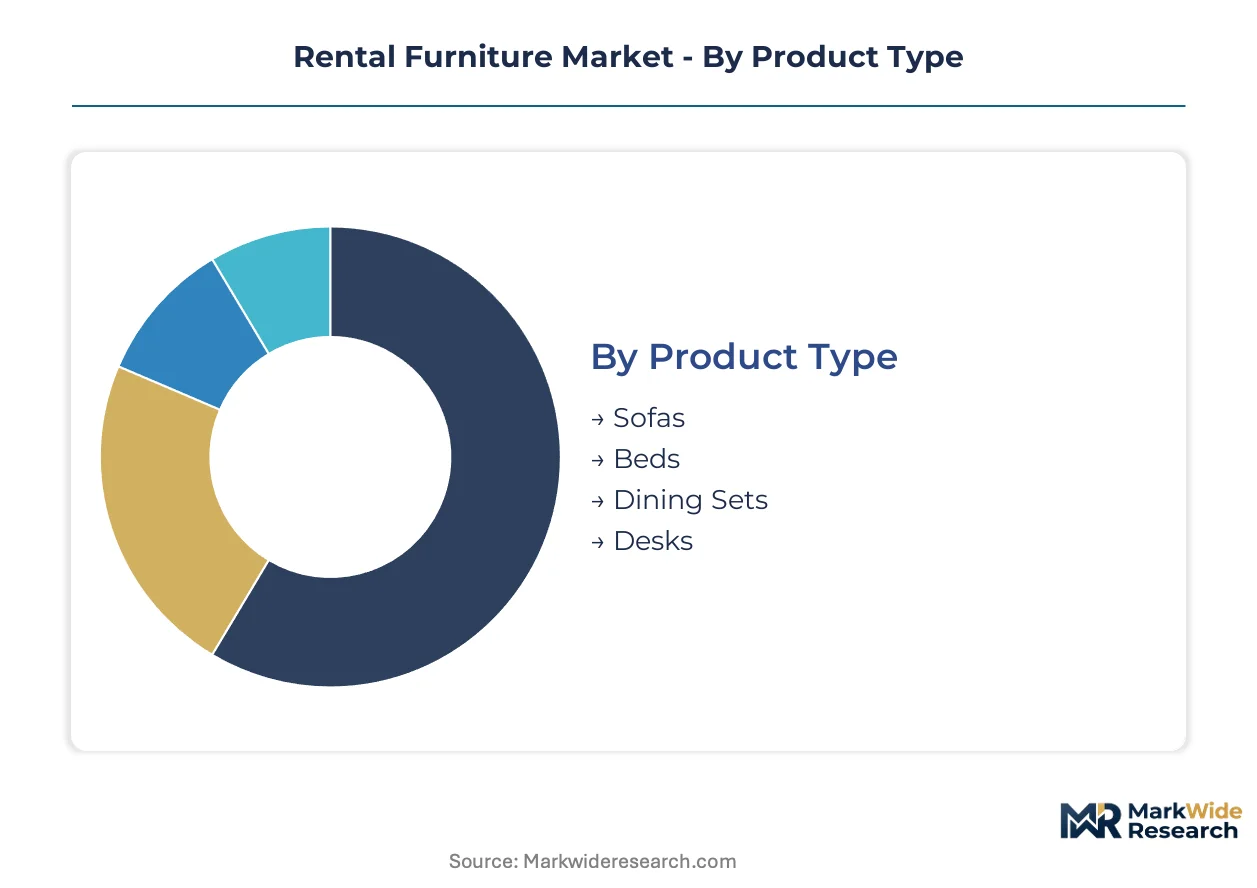
Rental furniture segmentation reveals how asset utilization patterns diverge across customer lifecycles and procurement channels. Understanding these splits enables operators to configure fleet composition, refurbishment cycles, and pricing architectures that match actual deployment economics.
Product Type:
Sofas and beds dominate volume throughput, while desks and dining sets command divergent margin profiles based on wear tolerance and replacement frequency.
- Sofas:Constructed with commercial-grade upholstery fabrics and reinforced hardwood frames engineered for repeated installation cycles. Demand concentrates in corporate housing contracts across Bengaluru and Mumbai, where rotating technology sector talent requires turnkey living room solutions on 3-12 month cycles.
- Beds:Modular platform designs with standardized mattress dimensions simplify inventory pooling across dispersed depot networks. Young professionals in São Paulo and Mexico City drive subscription uptake for bedroom packages, converting capital expenditure into operational spending amid housing turnover.
- Dining Sets:Event planners seeking statement pieces for temporary installations.
- Desks:Home office configurations surging with hybrid workforce normalization.
Mature deployment sits with sofas. Newer deployment is concentrated in desks.
Customer Type:
Corporate contracts deliver predictable utilization rates, while residential subscriptions exhibit higher churn but expand total addressable market penetration.
- Residential:Young professionals in dense urban clusters seeking flexibility without ownership burden. Subscription bundling now displaces single-item contracts in Seattle, Austin, and Denver.
- Corporate:Multinationals standardizing housing solutions for rotating talent across North America and Europe. These buyers consolidate procurement around furniture-as-a-service contracts that convert depreciating assets into predictable operational expenditure.
- Event Planners:Trade show organizers requiring lounge configurations on sub-30-day cycles.
- Students:Semester-based demand concentrated near university clusters with high turnover.
Corporate procurement anchors fleet utilization economics. Residential subscriptions are expanding most quickly.
Distribution Channel:
Online platforms compete aggressively on convenience, while legacy showrooms retain pricing power where white-glove service justifies premium positioning.
- Online:Tiered service levels spanning basic delivery to full room styling extract premium pricing in coastal U.S. cities. Real-time inventory visibility enables dynamic pricing based on actual utilization rather than static depreciation schedules.
- Showrooms:Brick-and-mortar networks anchor North American distribution through lease-to-own infrastructure. Physical inspection remains decisive for luxury tier purchases where tactile evaluation of fabric grades and joinery quality influences selection.
- Rental Agencies:Specialized operators managing end-to-end logistics and refurbishment.
- Third-Party Platforms:Aggregators connecting dispersed inventory with fragmented demand.
Showroom infrastructure represents mature channel deployment. Online platforms are gaining share fastest.
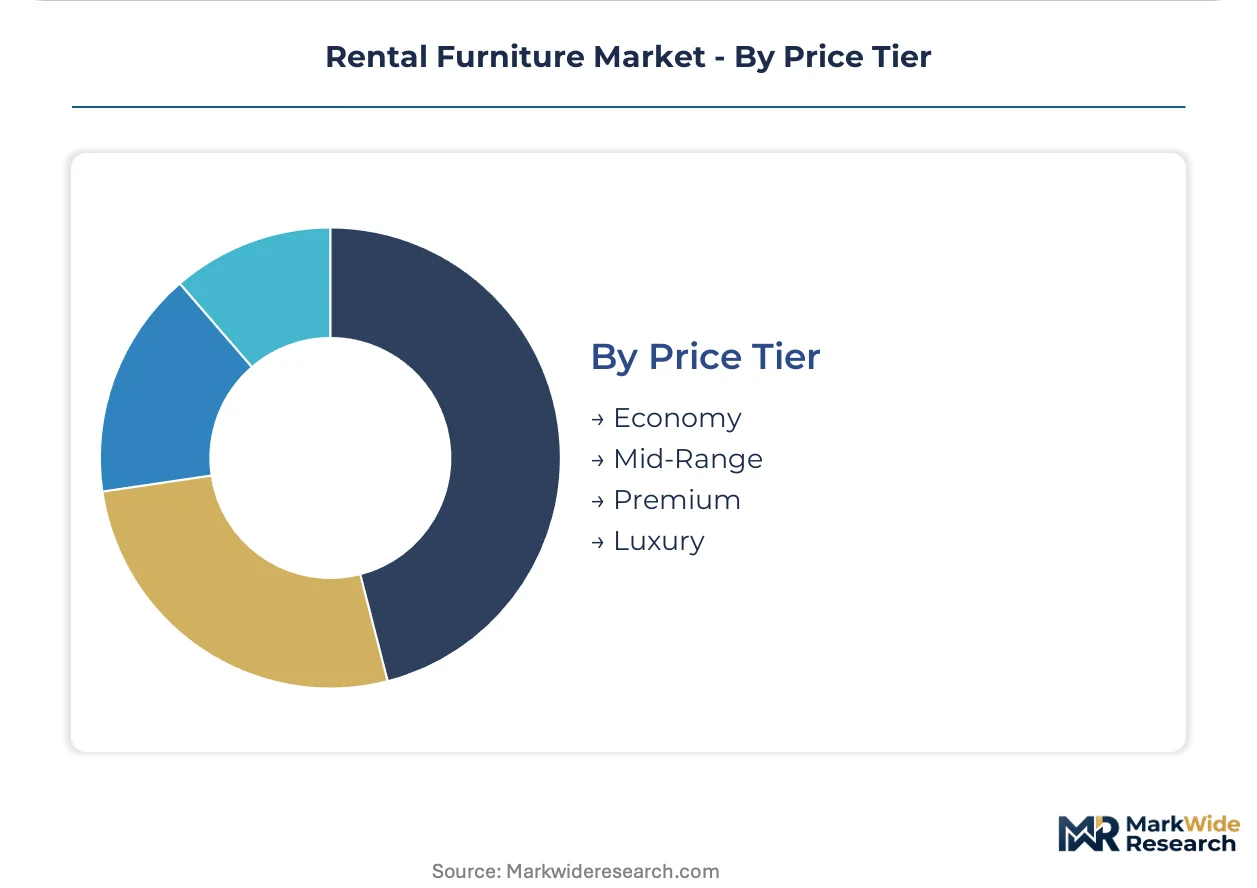
Price Tier:
Economy and mid-range segments drive volume throughput, while premium and luxury tiers capture margin through service differentiation and extended contract terms.
- Economy:Standardized designs with simplified joinery and synthetic fabric covers prioritize replacement over refurbishment. Student housing and entry-level corporate apartments in Hyderabad and Pune concentrate demand for this tier.
- Mid-Range:Balanced durability and design flexibility targeting young professionals with subscription-based living room packages. RentoMojo and Furlenco dominate Indian metro markets with full-home configurations at this price point.
- Premium:Curated packages with white-glove delivery and installation services.
- Luxury:Statement pieces for event installations and executive housing with bespoke styling.
Economy tier represents mature market penetration. Premium positioning is climbing the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Corporate housing demand concentrates in the United States, where rotating technology talent drives furniture-as-a-service procurement. Subscription uptake accelerates in India among mobile professionals seeking turnkey living solutions. European operators navigate circular economy mandates while expanding refurbishment depot networks.
United States
Hybrid workforce normalization sustains corporate housing contracts across Seattle, Austin, and Denver. The Consumer Financial Protection Bureau enforces lease disclosure rules that standardize contract transparency. Feather and Fernished Inc. anchor coastal city operations with design-forward packages targeting technology sector relocations.
India
Young professionals in Bengaluru and Mumbai convert capital expenditure into operational spending through full-home subscriptions. Bureau of Indian Standards certification requirements shape product safety benchmarks for upholstered furniture. Hyderabad and Pune exhibit rising IT employment with minimal rental furniture presence, offering first-mover positioning.
Germany
Corporate relocation services standardize housing solutions for multinational talent rotation across Frankfurt and Munich. EU Green Deal extended producer responsibility frameworks mandate material recovery documentation. Berlin's refurbishment depot networks expand to meet REACH chemical compliance and modular disassembly requirements.
United Kingdom
Financial services and technology sector mobility sustains demand for flexible furnishing solutions in London and Manchester. UK REACH adoption post-Brexit maintains chemical content standards aligned with EU frameworks. Corporate housing providers in the Southeast consolidate procurement around furniture-as-a-service contracts.
Brazil
Urban density premiums in São Paulo drive subscription uptake for bedroom and living room packages among mobile professionals. ANVISA regulates product safety standards for imported furniture components. Rio de Janeiro's event rental agencies seek statement dining sets for temporary hospitality installations on sub-30-day cycles.
Rental Furniture Market Competitive Environment
North American operators anchor the lease-to-own infrastructure tier; Indian specialists hold the subscription bundling segment. The vendor base splits between legacy showroom networks and online platforms competing on convenience versus white-glove service. Three archetypes dominate: brick-and-mortar lease-to-own incumbents, full-home subscription platforms, and curated design-forward specialists. Competitive moves center on geographic expansion into secondary cities and technology integration for fleet tracking.
Among North American incumbents, Rent-A-Center anchors the lease-to-own infrastructure with physical showroom networks. Feather and The Everset occupy positions within the curated specialist tier, targeting coastal technology sector relocations with design-forward positioning. Furlenco and RentoMojo exemplify the full-home subscription model, serving Indian metro markets with bundled living room and bedroom packages. These named entities represent strategic archetypes rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Rent-A-Center |
| Furlenco |
| The Everset |
| Fernished Inc. |
| Aaron's LLC |
| Feather |
| Luxe Modern Rentals |
| RentoMojo |
| Fashion Furniture Rental |
| Others |
Value Chain & Pricing Dynamics
Commercial-grade upholstery fabric costs cascade from concentrated petrochemical supply chains in East Asia through three distinct pricing tiers, with REACH-compliant chemistries commanding premiums that compress margins on economy-tier sofa deployments while subsidizing refurbishment economics for premium fleet operators.
Pricing Analysis
Volume throughput concentrates in economy and mid-range tiers where standardized synthetic fabrics and simplified joinery prioritize replacement cycles, while premium and luxury segments capture margin through white-glove installation and extended contract terms. Price differentiation hinges on certification grade—California TB 117 flammability compliance and EU REACH chemical validation—and geographic delivery density, with urban depot proximity reducing last-mile surcharges. Pricing pressure stems from freight cost volatility on bulky items, compressing returns for operators without owned warehouse networks. Residential subscribers exhibit highest price sensitivity, while corporate housing providers prioritize predictable operational expenditure over per-unit cost optimization.
Supply Chain Analysis
Reverse-logistics flows dominate operational complexity, with returned sofas and beds routing through refurbishment depots for disassembly, component reuse, and redeployment rather than disposal. Manufacturing concentrates in China, Vietnam, and India for frame production and upholstery assembly, while commercial-grade fabric mills cluster in Taiwan and South Korea. Raw material dependencies include petrochemical-based synthetic fibers, hardwood lumber for structural frames, and fire-retardant chemical treatments. Tariff exposure on finished furniture imports from Southeast Asia presents structural risk. Distribution runs through hybrid networks combining owned urban depots with third-party logistics partnerships for last-mile staging.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU Green Deal extended producer responsibility mandates function as a compliance moat, forcing asset-light entrants to internalize end-of-life recovery costs that incumbents with established refurbishment infrastructure absorb more efficiently.
For Market Incumbents: Deploy RFID-enabled fleet tracking to optimize redistribution and reduce idle inventory carrying costs. Expand depot infrastructure in secondary Indian cities before local competitors establish buffer inventory staging. Consolidate procurement relationships with pre-certified low-VOC upholstery suppliers to compress compliance timelines and defend margin position against emerging subscription platforms. For New Entrants and Emerging Players: Launch via event and exhibition verticals in São Paulo and Rio de Janeiro, where sub-30-day rental cycles for statement dining sets remain underserved by incumbent residential specialists. Target corporate housing providers in Hyderabad and Pune with modular bedroom packages designed for IT sector rotation. Penetrate through third-party platform aggregation rather than owned depot capital expenditure. For Investors and Strategic Acquirers: First-mover establishment of refurbishment depot networks in Indian secondary cities is the leading indicator that subscription economics will sustain competitive positioning. Long-term viability favors operators with backward integration into upholstery supply chains and captive logistics infrastructure. Monitor municipal zoning approvals for warehouse expansion in dense metropolitan areas as the decisive capacity constraint signal.| Strategic Initiative | Industry Significance |
|---|---|
| Refurbishment Depot Network Expansion | EU Green Deal compliance in Berlin and Frankfurt mandates material recovery documentation. |
| RFID Fleet Tracking Integration | Predictive maintenance scheduling reduces premature retirement for corporate housing contracts. |
| Low-VOC Upholstery Certification | REACH chemical restrictions force 8-14 week procurement cycle compression. |
| Secondary City Penetration | Hyderabad and Pune IT employment clusters lack established subscription competitors. |
| Event Rental Vertical Entry | Temporary hospitality installations in São Paulo seek statement pieces on sub-30-day cycles. |
Study Parameters
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with fleet operations directors, upholstery procurement leads, corporate housing procurement managers, and municipal zoning officials. Secondary sources encompassed EU ECHA substance restriction updates, California SB 54 implementation guidance, Bureau of Indian Standards certification databases, and container shipping rate indices. Bottom-up modeling of depot-level utilization rates triangulated against top-down market sizing from furniture-as-a-service contract disclosures.
Product-level granularity modeled sofa, bed, desk, and dining set categories separately across residential, corporate, event, and student customer segments, with distribution channel splits for online platforms, showrooms, rental agencies, and third-party aggregators. CAGRs derived from fitted trend analysis of subscription uptake rates and corporate housing contract growth, incorporating hybrid workforce normalization assumptions and circular economy regulatory phase-in schedules across the projection horizon.
Freight cost volatility, REACH chemical restriction expansion, and municipal warehouse zoning denials are the dominant revision risks to modeled refurbishment economics and fleet expansion timelines. Forecasts reflect documented assumptions regarding subscription churn rates and corporate contract renewal patterns. Practitioners should monitor EU digital product passport implementation timelines and Indian secondary city IT employment data for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
India Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
South Korea Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Home Office Spending Market