
 Home Office Spending Market | 2026-2036
Home Office Spending Market Size, Share, and Industry Trends Forecast 2026-2036
Home Office Spending Market Outlook
ISO 9241-410 ergonomic certification for home office equipment is unwinding competitive barriers as smaller vendors struggle to meet validated human-interface standards. Microsoft Corporation leverages its cloud productivity stack to anchor enterprise procurement decisions for distributed teams. Dell Technologies differentiates through direct-to-consumer configuration tools that sustain margin capture in premium workstation tiers.
Home office spending encompasses the acquisition, deployment, and maintenance of physical infrastructure, digital tools, and consumable resources that enable productive work outside traditional employer premises, spanning ergonomic furniture with adjustable height specifications, computing hardware meeting minimum processing thresholds, and SaaS collaboration platforms. Technology and furniture segments dominate current revenue pools, while accessories and supplies categories represent faster-growing margin opportunities as workers personalize multi-year setups. The budget tier dimension shows premium and mid-range equipment capturing disproportionate share as employers issue standardized stipends rather than bulk-purchasing commodity hardware.
FCC equipment authorization requirements govern wireless peripherals and networking gear sold into US home offices, while OSHA general duty clause interpretations increasingly extend to employer-funded ergonomic assessments for remote staff. The EU Green Deal and associated Ecodesign for Sustainable Products Regulation will tighten material disclosure and recyclability mandates for furniture and electronics shipped to European remote workers. Stakeholders must monitor whether national labor regulators reclassify home office equipment as taxable benefits-in-kind, a shift that would restructure procurement channels and budget tier distribution.
Market Dynamics
Permanent hybrid work policies are restructuring employer-employee equipment ownership boundaries, with stipend-based procurement displacing direct corporate purchasing and fragmenting volume concentration across millions of individual decision-makers.
Growth Catalysts
- EU AI Act workplace surveillance provisions:Employers must deploy compliant monitoring tools for distributed teams, mandating certified hardware-software bundles that refresh procurement cycles.
- Suburban technology corridor expansion:Austin, Raleigh-Durham, and Denver metro areas concentrate remote-worker density, creating localized demand spikes for ergonomic furniture and high-bandwidth networking gear.
- Biometric authentication integration:Fingerprint and facial-recognition sensors are becoming standard in keyboards, webcams, and docking stations for zero-trust security architectures.
Market Restraints
- Memory and display panel volatility:DDR5 RAM and OLED panel spot prices swing 15-40 percent quarterly, compressing margins for system integrators and furniture-electronics bundles.
- Single-source ergonomic component dependence:Precision gas-lift cylinders for sit-stand desks concentrate production in Zhejiang province, exposing supply chains to port congestion and energy-rationing disruptions.
- OSHA general duty clause uncertainty:Ambiguous employer liability for home-office injury claims creates legal friction that delays enterprise stipend program rollouts.
Strategic Opportunities
- India's PLI scheme for electronics manufacturing:Component and finished-goods production incentives attract contract manufacturers serving European and North American remote-worker demand.
- Refurbished and circular equipment channels:Certified pre-owned workstations and remanufactured ergonomic furniture capture sustainability-conscious buyers in Germany and the Netherlands.
- Spatial computing convergence:Mixed-reality headsets and haptic peripherals are creating new hardware categories for immersive virtual collaboration environments.
Industry Challenges
- ISO 9241-410 ergonomic certification backlog:Testing laboratory capacity constraints delay product launches by 4-8 months for furniture vendors seeking validated human-interface credentials.
- Legacy enterprise software integration:Home-office hardware must maintain compatibility with on-premise security clients and VPN architectures that predate cloud-native endpoints.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Office Spending Market |
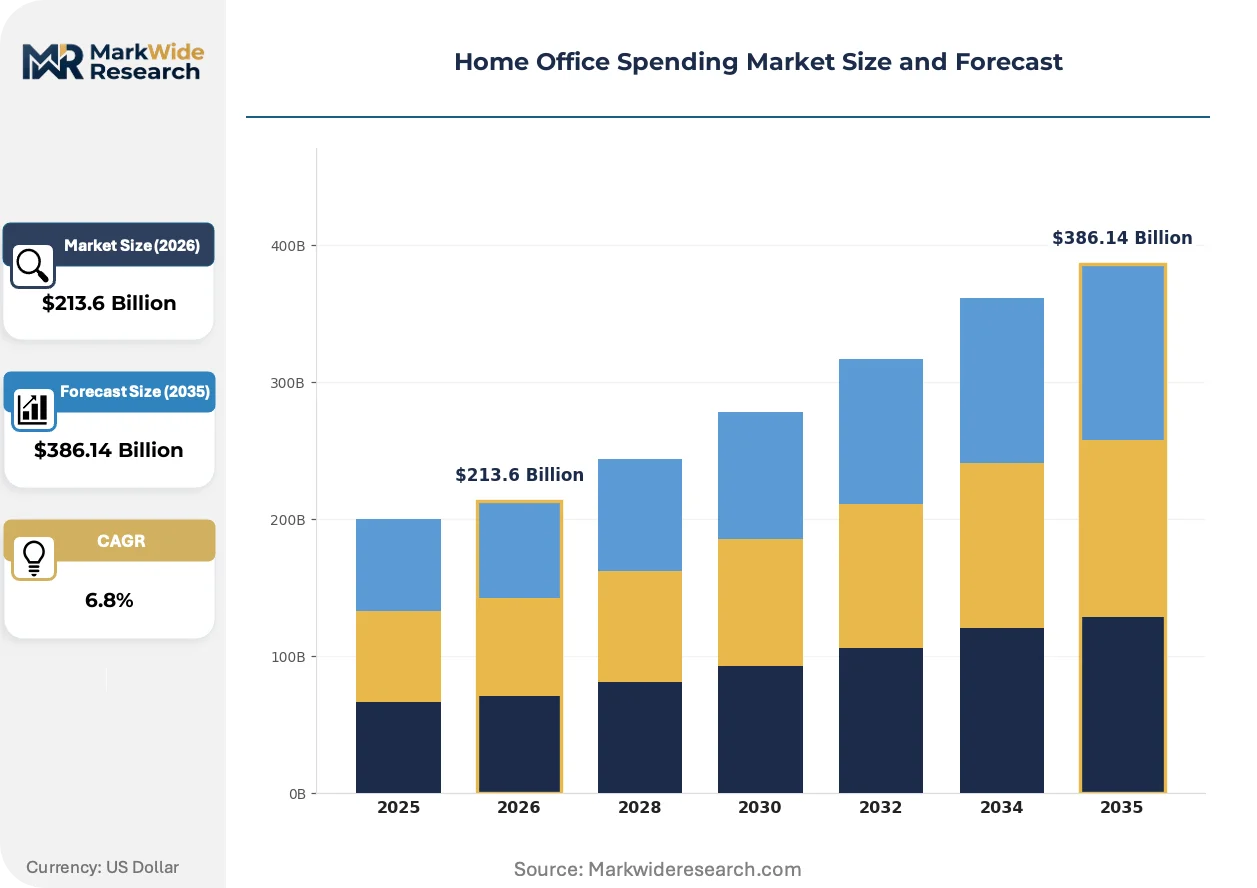
| Market Size in 2026 | $213.6 Billion |
| Market Size in 2035 | $386.14 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Furniture, Technology, Accessories, Supplies End User: Freelancers, SMEs, Large Enterprises, Remote Workers Sales Channel: Online Retailers, Brick-and-Mortar Stores, B2B Wholesale, Direct Sales Budget Tier: Low-Cost, Mid-Range, Premium, Luxury |
| Companies Covered | Microsoft Corporation, Google, Zoom Video Communications, Cisco Systems, Dell Technologies, HP Inc., Lenovo Group, Amazon Web Services, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Office Spending Market Strategic Shifts
Workstation hardware is compressing physical footprints while expanding functional density, with thermal management and modularity engineering enabling new form factors that relocate computing power away from desk surfaces.
Thunderbolt and USB4 docking architectures are miniaturizing. These single-cable connectivity hubs consolidate power delivery, display output, and peripheral expansion for laptop-centric remote workers. Enterprise IT departments are standardizing on these compact units to simplify support tickets and reduce cable clutter complaints. The technology is miniaturizing traditional tower workstations into palm-sized enclosures that mount behind monitors, freeing premium square footage in home offices.
EU Ecodesign for Sustainable Products Regulation is mandating material passports and recyclability disclosures for electronics and furniture shipped to European remote workers. Manufacturers must document full substance inventories and end-of-life disassembly protocols by 2027. Premium workstation and ergonomic furniture vendors are responding by redesigning adhesive-free assemblies and modular component architectures that satisfy French and German enforcement timelines.
Employer stipend programs are fragmenting procurement authority to individual employees who optimize for aesthetic integration with residential interiors rather than pure technical specifications. Direct-to-consumer brands and interior-design-aligned retailers are capturing share from traditional B2B channels. This behavioral pivot is most pronounced in United States suburban markets where remote workers treat home offices as permanent residential investments rather than temporary workplace extensions.
Home Office Spending Market Segmentation
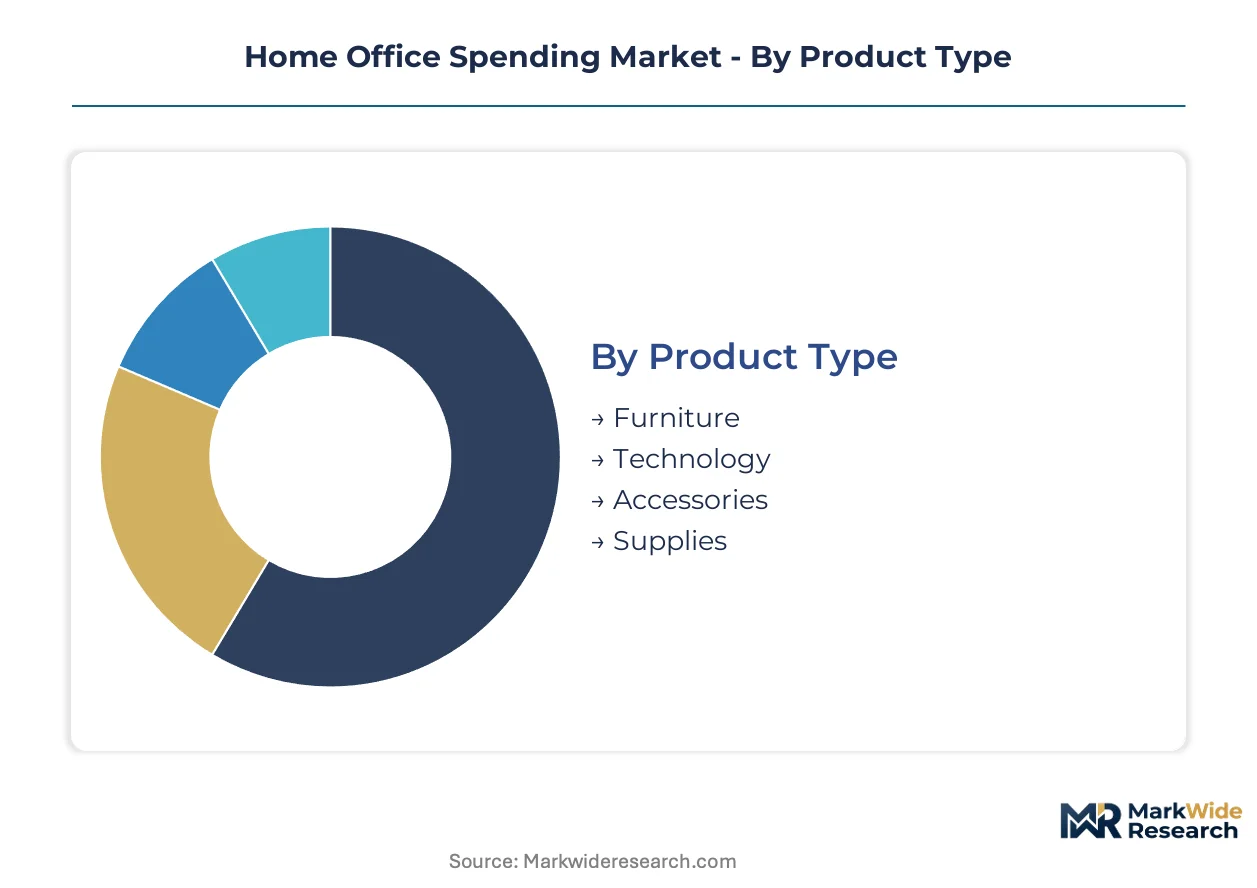
Home office spending fragments across four distinct category axes, each commanding different margin structures and procurement authority. Technology and furniture capture the bulk of current revenue, while accessories and supplies categories deliver faster margin expansion as workers personalize multi-year setups.
Product Type:
Margin pools concentrate in technology hardware and ergonomic furniture, where certification requirements and performance specifications sustain pricing power against commoditization pressures.
- Furniture:Ergonomic workstations with adjustable height specifications and validated human-interface credentials command sustained premiums. Demand concentrates in United States suburban technology corridors—Austin, Raleigh-Durham, and Denver metro areas—where remote workers treat home offices as permanent residential investments rather than temporary workplace extensions.
- Technology:Computing hardware meeting minimum processing thresholds for professional workloads, including compact docking architectures and biometric-integrated peripherals. Enterprise IT departments standardize on Thunderbolt and USB4 connectivity hubs to simplify support tickets, while FCC equipment authorization requirements govern wireless peripherals sold into US home offices.
- Accessories:Cable management systems, monitor arms, and acoustic panels that complete workstation ecosystems.
- Supplies:Consumable resources including printing materials, desk organizers, and maintenance products for sustained productivity.
Furniture holds installed capacity. Accessories is rotating up the share rankings.
End User:
Procurement authority distributes unevenly across buyer types, with employer-funded stipends displacing direct corporate purchasing and fragmenting volume concentration across millions of individual decision-makers.
- Remote Workers:Individual employees receiving standardized stipends rather than bulk-purchased hardware, optimizing for aesthetic integration with residential interiors. This behavioral pivot is most pronounced in United States suburban markets where hybrid work policies have become permanent.
- Large Enterprises:Distributed teams requiring certified hardware-software bundles compliant with EU AI Act workplace surveillance provisions, mandating procurement refresh cycles for monitoring tools.
- SMEs:Small and medium enterprises balancing cost constraints with professional-grade requirements for competitive talent retention.
- Freelancers:Independent contractors self-funding workstation investments without employer subsidy, driving demand in refurbished and circular equipment channels.
Large Enterprises holds installed capacity. Remote Workers is rotating up the share rankings.
Sales Channel:
Channel mix reflects the fundamental shift from B2B bulk purchasing to individual stipend-based procurement, rewarding direct-to-consumer configuration capabilities and interior-design-aligned retail experiences.
- Online Retailers:E-commerce platforms capturing share from traditional B2B channels as individual employees exercise procurement autonomy. Direct-to-consumer brands leverage digital configurators to sustain margin capture in premium workstation tiers.
- Direct Sales:Manufacturer-owned channels enabling customized specification and post-purchase support relationships with distributed teams.
- B2B Wholesale:Legacy corporate procurement channels experiencing volume displacement as stipend programs fragment purchasing authority.
- Brick-and-Mortar Stores:Physical retail locations retaining relevance for ergonomic furniture requiring tactile evaluation and immediate fulfillment.
B2B Wholesale holds installed capacity. Online Retailers is rotating up the share rankings.
Budget Tier:
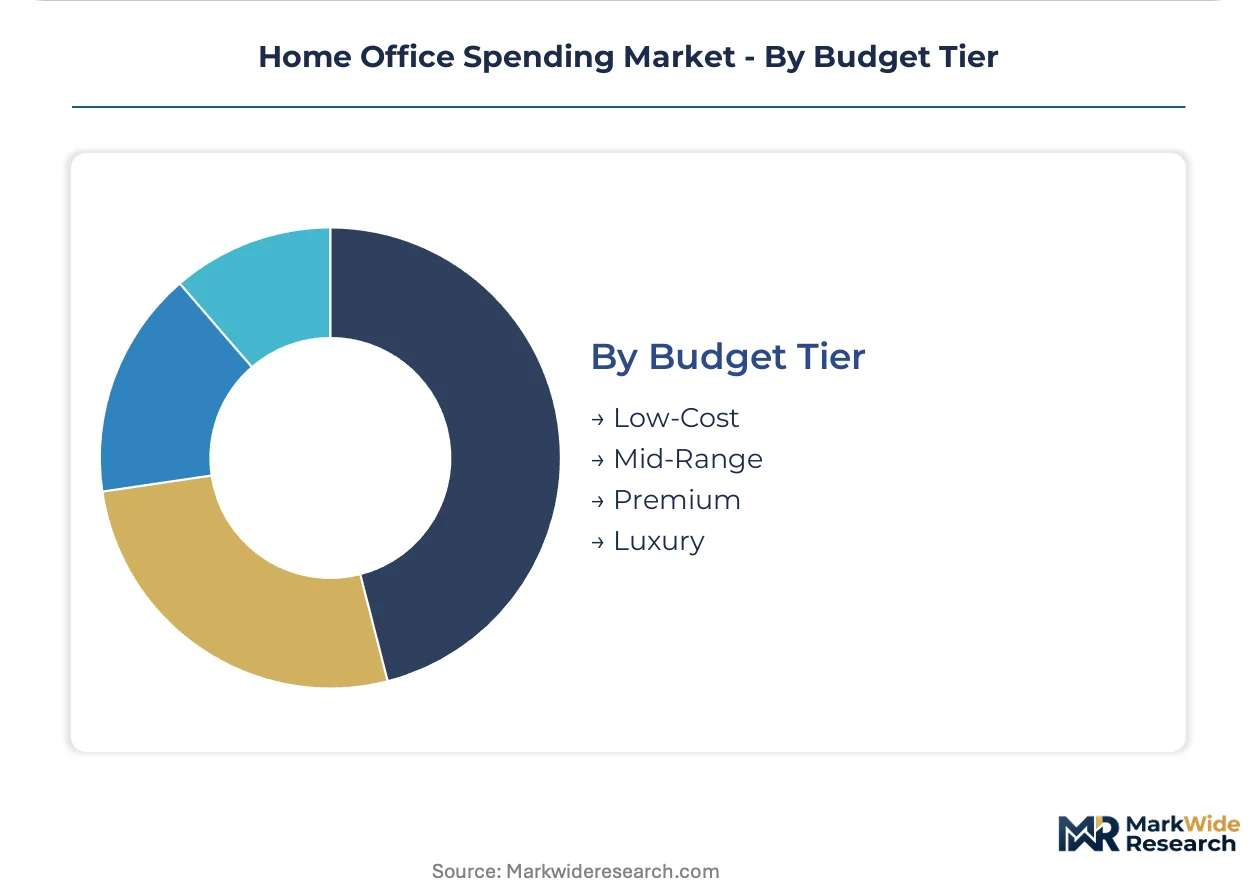
Price stratification across premium, standard, and economy tiers reflects certification grade differentiation and volume scale economics, with premium and mid-range equipment capturing disproportionate share under employer stipend programs.
- Premium:Workstations and peripherals meeting ISO 9241-410 ergonomic certification and enterprise security specifications. OSHA general duty clause interpretations increasingly extend to employer-funded ergonomic assessments for remote staff, validating investment in validated human-interface standards.
- Mid-Range:Professional-grade equipment balancing performance requirements with cost constraints, representing the standard stipend allocation tier for most employer programs.
- Luxury:Aesthetic-forward designs integrating with high-end residential interiors, commanding margins through interior-design alignment rather than pure technical specifications.
- Low-Cost:Commodity hardware facing margin compression from memory and display panel volatility, with DDR5 RAM and OLED panel spot prices swinging quarterly.
Mid-Range holds installed capacity. Premium is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Government stipend programs and workplace safety regulations are redrawing procurement patterns across major economies. Fiscal incentives for remote work infrastructure now operate in at least a dozen national jurisdictions.
United States
Employer-funded equipment stipends have become standard in technology and professional services sectors. OSHA general duty clause interpretations increasingly extend to home office ergonomic assessments for distributed staff. Austin, Raleigh-Durham, and Denver metro areas concentrate remote-worker density, creating localized demand spikes for adjustable-height workstations and high-bandwidth networking gear.
Germany
The EU Green Deal and Ecodesign for Sustainable Products Regulation mandate material passports and recyclability disclosures for electronics and furniture. German enforcement timelines for documented substance inventories and end-of-life disassembly protocols accelerate vendor redesign cycles. Berlin and Munich anchor certified pre-owned workstation channels that capture sustainability-conscious buyers.
United Kingdom
HMRC guidance on home office equipment tax treatment shapes employer procurement channel decisions. The country's national workplace regulator continues clarifying duty-of-care obligations for remote staff. London's financial services sector and Manchester's media clusters drive premium-tier demand for enterprise-grade collaboration hardware.
India
The PLI scheme for electronics manufacturing attracts contract manufacturers serving North American and European remote-worker demand. BIS certification requirements for IT and networking equipment tighten quality benchmarks for export-oriented production. Bangalore and Hyderabad technology corridors concentrate distributed team infrastructure spending among multinational captive centers.
Japan
METI guidelines on telework infrastructure standardization influence enterprise procurement specifications. JIS ergonomic standards for display equipment and input devices create compliance baselines for vendor market entry. Tokyo and Osaka metropolitan areas sustain concentrated demand for space-efficient workstation designs optimized for compact residential floor plans.
Home Office Spending Market Competitive Environment
Player mix skews toward diversified technology conglomerates with cloud productivity and hardware manufacturing capabilities. The competitive structure concentrates around three strategic tiers: enterprise software platforms anchoring collaboration ecosystems, direct-to-consumer hardware configurators capturing stipend-based procurement, and cloud infrastructure providers enabling distributed team architectures. Dominant competitive moves include portfolio diversification into adjacent ergonomic categories and strategic partnerships certifying hardware-software bundles for regulatory compliance.
Among the technology platforms identified in this study, Microsoft Corporation exemplifies the productivity-stack anchor archetype, Dell Technologies occupies a position within the direct-configuration hardware tier, and Amazon Web Services represents the cloud infrastructure vector. These entities illustrate how competitive positioning now depends on cross-category integration rather than single-product dominance. Each sits within a broader vendor ecosystem where certification credentials and channel relationships determine stipend capture rates.
| Leading Market Players |
|---|
| Microsoft Corporation |
| Zoom Video Communications |
| Cisco Systems |
| Dell Technologies |
| HP Inc. |
| Lenovo Group |
| Amazon Web Services |
| Oracle Corporation |
| Others |
Value Chain & Pricing Dynamics
ISO 9241-410 ergonomic certification gates both supply qualification and price differentiation simultaneously, forcing vendors to absorb testing laboratory delays while commanding premiums for validated human-interface credentials that employers now mandate for remote-worker stipend programs.
Pricing Analysis
Certification level creates the primary spread between premium and commodity tiers in home office equipment. Three-tier pricing structure across premium, standard, and economy levels reflects ISO 9241-410 validation status, brand equity in enterprise IT procurement, and bundled after-sales support. Cost compression in the economy tier is intensifying because DDR5 RAM and OLED panel spot prices swing quarterly, eroding assembler margins. Freelancers and self-funded remote workers exhibit highest price sensitivity, while large enterprises issuing standardized stipends prioritize certification grade over unit cost.
Supply Chain Analysis
Inventory lead times for precision gas-lift cylinders extend 4-8 months due to testing laboratory capacity constraints, delaying furniture launches for vendors seeking ergonomic credentials. Component manufacturing concentrates in China, Taiwan, and Vietnam, with Zhejiang province hosting critical sit-stand desk mechanism production. Supply chains draw from aluminum extrusions, memory semiconductors, and display panels as primary inputs. Single-source vulnerability in ergonomic component sourcing exposes vendors to port congestion and energy-rationing disruptions. Distribution runs through direct-to-consumer configurators and interior-design-aligned retailers that capture stipend-based procurement authority.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Home office spending represents a defensive-moat market where regulatory entrenchment through certification requirements creates sticky vendor relationships that resist price-based displacement.
For Market Incumbents: Shield market position by deepening backward integration into ergonomic component manufacturing to circumvent Zhejiang supply bottlenecks, while accelerating ISO 9241-410 certification investments to extend testing laboratory relationships that new entrants cannot replicate. Biometric authentication integration and EU AI Act compliance bundling create additional switching cost layers. For New Entrants and Emerging Players: Refurbished workstation certification gaps in Germany and the Netherlands offer immediate white-space capture, as sustainability-conscious buyers face limited certified pre-owned supply. India's PLI scheme electronics manufacturing incentives enable contract manufacturing partnerships serving North American stipend demand without legacy channel conflicts. Direct-to-consumer configurators targeting suburban technology corridor aesthetics bypass entrenched B2B procurement relationships. For Investors and Strategic Acquirers: Capital-intensity ratios are inflecting upward across premium ergonomic furniture manufacturing due to adhesive-free assembly redesigns and modular component architectures required by EU Ecodesign mandates. Acquisition targets should demonstrate established testing laboratory relationships and validated certification backlogs rather than pure production capacity. Monitor OSHA general duty clause interpretation clarity as inflection signal for enterprise stipend program acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Ergonomic Certification Fast-Track | ISO 9241-410 validation compresses 4-8 month laboratory queues into preferred vendor status. |
| Biometric Peripheral Integration | Fingerprint and facial-recognition sensors align hardware with zero-trust security architectures. |
| EU AI Act Compliance Bundling | Certified hardware-software bundles mandate procurement refresh cycles for surveillance tools. |
| Refurbished Channel Certification | Certified pre-owned workstations capture sustainability-conscious buyers in German and Dutch markets. |
| Suburban Technology Corridor Expansion | Austin, Raleigh-Durham, and Denver density spikes localize demand for high-bandwidth networking gear. |
Study Parameters
Findings reconcile primary fieldwork against secondary review of SEC 10-K filings, hyperscaler capex disclosures, and customs import records, combining structured interviews with IT procurement officers, ergonomic furniture product managers, enterprise facilities directors, and channel sales heads with bottom-up and top-down triangulation across vendor shipment data and employer stipend program disclosures.
Segmentation dimensions modeled include product type, end-user archetype, sales channel, and budget tier across the projection horizon, with CAGRs derived from trend extrapolation anchored in employer hybrid work policy permanence and regulatory compliance refresh cycles. Forecast inputs incorporate EU AI Act implementation timelines and OSHA general duty clause interpretation trajectories.
Underlying assumptions cover employer stipend program standardization and certification requirement enforcement, with deviation risk concentrated in memory and display panel spot price volatility and single-source ergonomic component supply disruptions. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
United States Home Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
France Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
India Office Furniture Market