
 France Office Furniture Market | 2026-2036
France Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
France Office Furniture Market Foresight
A widening capital-intensity gap between integrated manufacturers and assembly-dependent competitors is redrawing competitive boundaries in the France office furniture sector. Steelcase leverages its captive North American supply chain to sustain margin resilience on large corporate rollouts. Buronomic anchors its position through deep manufacturing presence in western France, where it controls regional distribution networks for public-sector tenders.
France office furniture encompasses movable equipment designed for administrative, collaborative, and executive workspaces, typically constructed from engineered wood substrates, tubular steel frames, or thermoplastic polymers with surface finishes rated for commercial abrasion resistance. The primary purpose is to support ergonomic productivity while accommodating spatial reconfiguration demands in leased commercial real estate. Seating and desks dominate product-type revenue pools, though workstations are capturing accelerated interest from coworking operators seeking lease-term flexibility. Wood and metal materials command premium positioning in enterprise and legal-firm end-user segments, where durability specifications and aesthetic signaling carry procurement weight.
France's RE2020 building regulation, the EU Ecodesign Directive, and ANSM/CNIL data-privacy frameworks for connected workplace devices collectively shape product compliance burdens and market access conditions. CE marking under the Construction Products Regulation governs structural and fire-safety performance for installed furniture systems. Stakeholders must monitor how evolving circular-economy mandates from Brussels alter material sourcing requirements and end-of-life take-back obligations for domestic producers.
Market Dynamics
France's RE2020 building regulation is compressing demand timelines for low-carbon furniture systems while coworking operators accelerate workstation replacement cycles across Paris and Lyon. This regulatory-demand tension is restructuring procurement priorities for domestic manufacturers and importers alike.
Growth Catalysts
- Coworking space expansion:Flexible workspace operators in Paris, Lyon, and Marseille are scaling modular workstation procurement to match lease-term agility requirements.
- RE2020 environmental mandate:France's building regulation mandates lower carbon footprints in commercial fit-outs, pulling manufacturers toward certified wood and recycled metal inputs.
- Île-de-France concentration:Corporate headquarters and government agencies in this region sustain premium demand for ergonomic seating and executive desk configurations.
Market Restraints
- Input cost volatility:Steel and engineered wood substrate prices fluctuate with energy costs, compressing margin predictability for assembly-dependent producers.
- Supply concentration risk:North American captive supply chains dominate premium component sourcing, exposing French assemblers to transatlantic logistics friction.
- Technical limitation:Connected workplace devices face ANSM/CNIL data-privacy compliance burdens that delay product launch timelines.
Strategic Opportunities
- Western France manufacturing base:Deep production presence in this region offers control over public-sector tender distribution networks.
- Circular-economy mandate alignment:Evolving Brussels directives on material sourcing and end-of-life take-back create first-mover advantages for certified producers.
- Modular system convergence:Integration of IoT-enabled occupancy sensors with reconfigurable furniture systems opens premium pricing in smart building deployments.
Industry Challenges
- Certification timeline compression:CE marking under the Construction Products Regulation requires fire-safety and structural performance testing that extends product development cycles.
- Skills gap in sustainable materials:Shortage of technicians trained in certified wood processing and recycled metal fabrication limits production scaling.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | France Office Furniture Market |
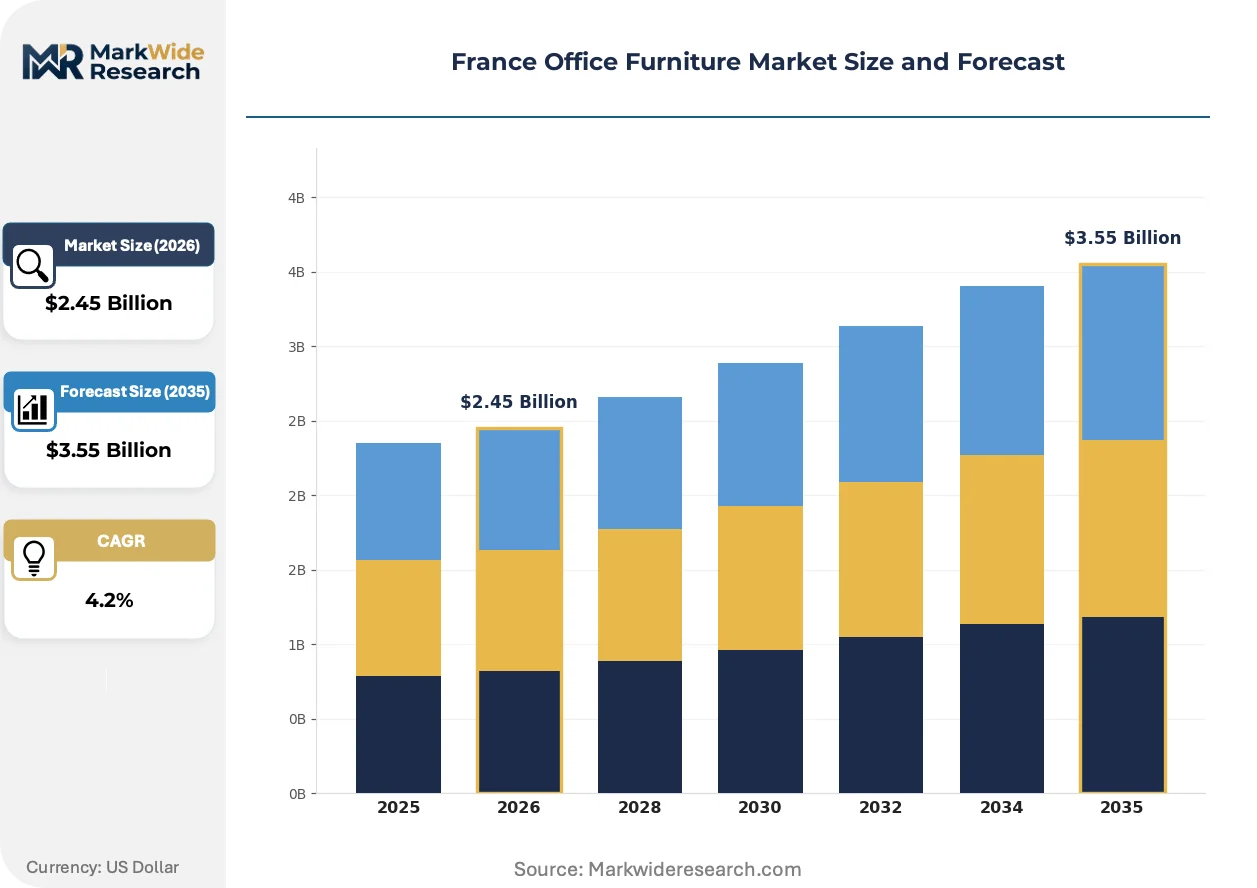
| Market Size in 2026 | $2.45 Billion |
| Market Size in 2035 | $3.55 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Filing Cabinets, Workstations, Bookcases, Conference Tables Material: Wood, Metal, Plastic, Glass, Laminates, Fabric Application: Corporate Offices, Coworking Spaces, Government Agencies, Educational Institutions, Banks, Startups End User: Enterprises, IT Firms, Financial Organizations, Legal Firms, Creative Agencies, Consulting Companies |
| Companies Covered | IKEA, Buronomic, Steelcase, Kinnarps, Gautier, Herman Miller, Majencia, Vitra, Haworth, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
France Office Furniture Market Shifts & Advancements
Workplace technology integration and regulatory carbon accounting are converging to redefine furniture system specifications. These forces are compressing traditional product lifecycles while opening premium segments for compliant, connected solutions.
Modular workstation architecture is decomposing fixed-floorplan conventions in French commercial real estate. Coworking operators in Paris and Marseille are adopting plug-and-play desk configurations at accelerated replacement cadences. This flexibility is decomposing the traditional five-to-seven-year furniture depreciation cycle into shorter, lease-matched refresh intervals.
France's RE2020 regulation is tightening embodied carbon thresholds for building fit-out materials. Manufacturers must now document lifecycle emissions for wood substrates and metal frames to qualify for public and corporate procurement. Enterprise and legal-firm segments are responding by demanding Environmental Product Declaration certifications as standard bid requirements.
Buyer concentration among flexible workspace providers is fragmenting traditional dealer-channel relationships. Direct manufacturer-to-operator contracts are displacing furniture dealership intermediaries in Lyon and Marseille markets. This disintermediation is most visible in mid-market coworking chains seeking volume pricing transparency and faster installation turnaround.
France Office Furniture Market Segmentation
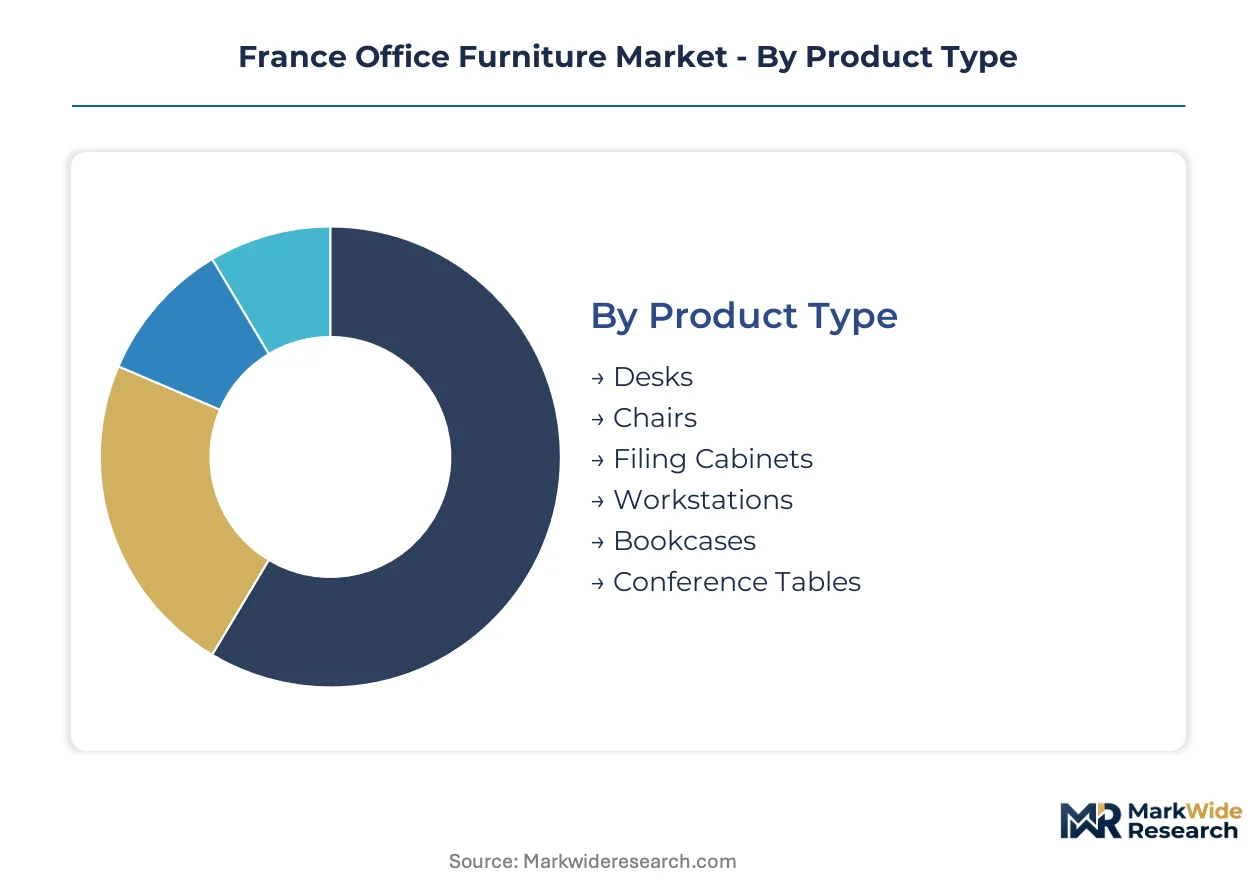
Segmentation in the France office furniture market reveals distinct margin architectures across product categories and buyer profiles. Understanding these divisions exposes where procurement budgets concentrate and how regulatory pressures differentially affect material and application segments.
Product Type:
Margin pools concentrate in seating and workstation categories where ergonomic specifications and modular flexibility command pricing premiums.
- Chairs:Ergonomic seating systems incorporate adjustable lumbar support, synchronous tilt mechanisms, and breathable mesh fabrics rated for commercial abrasion. Demand clusters in Île-de-France corporate headquarters and government agencies where ANSM workplace safety guidelines elevate specification thresholds.
- Workstations:Modular desk configurations feature reconfigurable frame systems, integrated cable management, and tool-free assembly for lease-term flexibility. Coworking operators in Paris and Lyon are compressing replacement cycles to match shorter tenancy agreements, accelerating volume throughput.
- Desks:Executive and height-adjustable configurations dominate enterprise procurement in legal and financial sectors.
- Filing Cabinets:Steel and fire-rated variants sustain steady public-sector demand under RE2020 durability mandates.
- Bookcases:Storage systems face substitution pressure from digital document workflows in corporate environments.
- Conference Tables:Large-format meeting furniture encounters elongated decision cycles as hybrid work patterns reduce dedicated collaboration space requirements.
Chairs hold installed capacity. Workstations are rotating up the share rankings.
Material:
Cost tier stratification separates certified sustainable inputs from commodity alternatives, with RE2020 carbon accounting reshaping procurement weightings.
- Wood:Engineered substrates and solid timber frames carry FSC or PEFC certification for public-sector eligibility. Legal firms and enterprise headquarters in Paris specify hardwood veneers for aesthetic signaling in client-facing environments.
- Metal:Tubular steel and recycled aluminum frames deliver structural durability for high-traffic coworking installations. RE2020 embodied carbon thresholds push manufacturers toward verified recycled content documentation.
- Plastic:Thermoplastic polymers and polypropylene shells dominate mid-market seating through injection-molded production economies.
- Glass:Tempered surface applications concentrate in executive desk and conference table segments for premium positioning.
- Laminates:High-pressure surface finishes balance abrasion resistance with cost control in volume deployments.
- Fabric:Upholstery textiles face evolving fire-safety testing under CE marking Construction Products Regulation requirements.
Wood maintains margin leadership. Metal is climbing the fastest as carbon certification hardens bid requirements.
Application:
Customer type fragmentation separates long-cycle enterprise procurement from velocity-driven flexible workspace operators.
- Corporate Offices:Traditional headquarters demand ergonomic seating suites and executive desk configurations with extended depreciation horizons. Île-de-France concentration sustains premium pricing for certified wood and metal combinations.
- Coworking Spaces:Flexible workspace operators prioritize modular workstation architectures with rapid-install capabilities and lease-matched refresh intervals. Direct manufacturer contracts in Lyon and Marseille are displacing traditional dealer intermediaries.
- Government Agencies:Public-sector tenders mandate RE2020 compliance and certified material documentation, favoring western France manufacturing presence.
- Educational Institutions:Universities and training centers balance durability specifications with constrained capital budgets.
- Banks:Financial institutions combine security-rated storage with client-facing aesthetic requirements in branch fit-outs.
- Startups:Early-stage companies prioritize cost-efficient plastic and laminate configurations with short lead times.
Corporate Offices anchor volume commitments. Coworking Spaces are gaining share fastest as lease structures fragment.
End User:
Volume concentration among professional services segments creates procurement pattern predictability for qualified vendors.
- Enterprises:Large organizations deploy standardized furniture programs across multi-site footprints with centralized procurement governance. Ergonomic certification and lifecycle cost modeling dominate evaluation criteria.
- Legal Firms:Paris-based practices specify premium wood and leather combinations for partner office signaling and client reception aesthetics.
- IT Firms:Technology companies favor open-plan benching systems and height-adjustable surfaces for engineering team density.
- Financial Organizations:Banks and insurers balance regulatory compliance documentation with executive floor prestige requirements.
- Creative Agencies:Design studios prioritize aesthetic differentiation through custom material combinations and non-standard configurations.
- Consulting Companies:Professional services firms align furniture specifications with client impression management and consultant mobility patterns.
Enterprises dominate contract scale. Legal Firms are rotating up the share rankings as premium positioning intensifies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
France's office furniture consumption concentrates in Île-de-France, where corporate headquarters demand premium ergonomic configurations, while coworking operators in Lyon and Marseille prioritize modular workstation agility over durability cycles.
Île-de-France
Corporate headquarters and government agencies in Paris drive premium seating and executive desk procurement with extended depreciation horizons. RE2020 environmental regulation mandates lower carbon footprints in commercial fit-outs, pulling manufacturers toward certified wood inputs. La Défense and central Paris business districts sustain demand for hardwood veneer configurations in client-facing legal and financial environments.
Auvergne-Rhône-Alpes
Coworking operators in Lyon compress workstation replacement cycles to match shorter lease agreements, accelerating modular system throughput. ANSM workplace safety guidelines elevate ergonomic specification thresholds for regional technology and consulting firms. Lyon Part-Dieu and Confluence districts host expanding flexible workspace providers sourcing rapid-install desk configurations.
Provence-Alpes-Côte d'Azur
Marseille's flexible workspace market fragments traditional dealer-channel relationships through direct manufacturer contracts. CE marking under the Construction Products Regulation governs fire-safety performance for installed furniture systems in renovated port district commercial buildings. Aix-Marseille-Provence metropolitan area attracts mid-market coworking chains seeking volume pricing transparency.
Hauts-de-France
Public-sector tenders in Lille mandate RE2020 compliance and certified material documentation, favoring western France manufacturing presence. The country's national environmental regulator enforces embodied carbon thresholds for building fit-out materials in regional administrative buildings. Euralille business district sustains steady demand for steel filing cabinets under durability mandates.
Nouvelle-Aquitaine
Educational institutions and regional startups in Bordeaux balance constrained capital budgets with durability specifications. CNIL data-privacy frameworks for connected workplace devices delay product launch timelines for IoT-enabled furniture deployments. Bordeaux Métropole hosts emerging technology companies prioritizing cost-efficient plastic and laminate configurations.
France Office Furniture Market Competitive Landscape
A small set of integrated leaders sits above a broader specialist tier in France's office furniture sector. Steelcase leverages captive North American supply chains to sustain margin resilience on large corporate rollouts, while Buronomic anchors position through deep manufacturing presence in western France controlling regional distribution networks. The competitive terrain separates three archetypes: multinational integrated manufacturers, regional production specialists, and modular system innovators. Dominant competitive moves include direct manufacturer-to-operator contract formation and circular-economy certification alignment.
Within the integrated multinational tier, Steelcase Inc. and Herman Miller Inc. exemplify scale-driven positioning through captive supply chain control and corporate rollout execution. Among regional production specialists, Buronomic S.A.S. occupies a position representing western France manufacturing depth and public-sector tender access. These three companies sit within distinct competitive vectors—multinational scale, regional manufacturing control, and premium ergonomic specialization—each responding differently to RE2020 carbon mandates and coworking procurement fragmentation.
| Leading Market Players |
|---|
| IKEA |
| Buronomic |
| Steelcase |
| Kinnarps |
| Gautier |
| Herman Miller |
| Majencia |
| Vitra |
| Haworth |
| Others |
Supply & Pricing Matrix
Long-term offtake contracts between integrated manufacturers and Île-de-France corporate buyers lock in steel and certified wood supply access while anchoring price visibility against RE2020 compliance cost fluctuations. This contract-structure pattern insulates premium-tier procurement from spot-market volatility while compressing margins for assembly-dependent competitors exposed to raw material swings.
Pricing Analysis
After-sales service contracts and extended warranty tiers drive lifetime value capture in the France office furniture sector. Three-tier pricing structure across premium, standard, and economy levels segments buyers by certification grade and ergonomic specification depth. Price differentiation hinges on FSC/PEFC certification status and volume scale, with enterprise procurement commanding transparency discounts. Cost compression in the mid-market plastic seating tier is intensifying because coworking operators prioritize lease-matched refresh cycles over durability premiums. Startups and educational institutions exhibit highest price sensitivity, while legal firms and government agencies demonstrate lowest sensitivity due to aesthetic signaling and compliance mandates.
Supply Chain Analysis
Strategic stockpiling of engineered wood substrates and tubular steel frames dominates inventory strategy among western France manufacturers serving public-sector tenders. Supply concentrates in France, Germany, and Poland for finished furniture systems, with raw material dependencies on Swedish and Baltic certified timber plus recycled aluminum from European smelters. Single-source vulnerability in North American captive supply chains for premium ergonomic components exposes French assemblers to transatlantic logistics friction. Distribution runs through regional dealer networks in Paris and Lyon, though direct manufacturer-to-operator contracts are displacing intermediaries in Marseille coworking markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
France office furniture incumbents face substitution defense imperatives as flexible workspace operators increasingly lease rather than purchase furniture assets, threatening traditional ownership-based revenue models.
For Market Incumbents: Compound manufacturing depth in western France with RE2020 certification investment to defend against modular-system innovators capturing coworking procurement. Anchor public-sector tender access through certified wood processing capabilities while building direct-contract muscle to offset dealer-channel displacement. Vertical integration into recycled metal fabrication mitigates input cost volatility from energy-linked steel pricing. For New Entrants and Emerging Players: PEFC fast-track certification opens public-sector eligibility in Hauts-de-France and Nouvelle-Aquitaine where western France incumbents maintain weaker distribution presence. Target mid-market coworking chains in Marseille and Lyon seeking volume pricing transparency and rapid-install capabilities. Go-to-market through direct manufacturer-to-operator contracts bypasses entrenched dealer relationships. For Investors and Strategic Acquirers: Capital is best deployed toward regional production specialists with circular-economy certification alignment and captive distribution networks in underserved French sub-regions. Long-term viability over the next decade rests on compliance-advantaged manufacturing footprints rather than brand equity alone. Watch for inflection when Brussels circular-economy mandates harden end-of-life take-back obligations, advantaging certified producers.| Strategic Initiative | Industry Significance |
|---|---|
| RE2020 Certification Investment | Secures public-sector tender eligibility under France's national environmental regulator mandates. |
| Direct-to-Operator Contracting | Bypasses dealer intermediaries in Lyon and Marseille coworking markets for pricing transparency. |
| Recycled Metal Integration | Aligns with embodied carbon thresholds in RE2020 building fit-out regulations. |
| Modular System Convergence | Captures premium positioning through IoT-enabled occupancy sensor integration. |
| Western France Capacity Expansion | Controls regional distribution networks for government agency procurement clusters. |
Research Methodology
A standing panel of furniture procurement directors, coworking space operators, public-sector tender managers, and certified wood processing technicians provided ongoing calibration across primary interview cycles. Secondary validation drew from ANSM workplace safety guidelines, RE2020 regulatory filings, CE marking Construction Products Regulation documentation, and customs records of engineered wood substrate imports. Bottom-up segmentation modeling triangulated against top-down macroeconomic indicators to ensure consistency.
Consistency checks against external benchmarks validated volume and value outputs across the projection horizon. The analytical framework modeled product type, material certification tier, application segment, and end-user professional services category throughout the forecast period. CAGRs were derived from installed base depreciation patterns, replacement cycle compression in flexible workspaces, and regulatory compliance cost pass-through assumptions. Coworking operator expansion rates and RE2020 enforcement timelines served as industry-specific forecast inputs.
Decision-makers should treat outputs as directional under assumptions of stable RE2020 enforcement intensity and continued coworking market fragmentation; material deviation would warrant model refresh. Forecasts reflect assumptions of sustained Île-de-France corporate headquarters demand and unimpeded western France manufacturing access to public-sector networks. Revision becomes warranted when Brussels circular-economy mandates cross implementation thresholds or when transatlantic logistics friction escalates beyond current baselines.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
Russia Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
Rental Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Indonesia Office Furniture Market