
 Office Furniture Edgebands Market | 2026-2036
Office Furniture Edgebands Market Size, Share, and Industry Trends Forecast 2026-2036
Office Furniture Edgebands Market Insights
Corporate office fit-outs are rotating toward modular workstation systems as hybrid work policies reshape floor plans. REHAU AG + Co leverages its polymer compounding expertise to supply color-matched edgebanding for European panel processors. Egger Group anchors its position through captive demand from its own particleboard and laminate operations. Wilsonart LLC differentiates via textured and high-gloss finishes targeting premium commercial interiors.
Office furniture edgebands are narrow strips applied to the exposed edges of particleboard, MDF, and plywood panels to seal substrates against moisture, impact, and abrasion while providing aesthetic continuity with surface laminates. These strips typically measure 0.4 mm to 3.0 mm in thickness and are applied via hot-melt adhesive or laser bonding systems calibrated to panel line speeds. PVC edgebands continue to dominate volume due to cost efficiency and color stability, though ABS and polypropylene segments are gaining specification share as architects prioritize halogen-free, recyclable alternatives for LEED and BREEAM-certified projects. Wood veneer edgebands retain premium positioning in executive furniture and design studio applications where natural grain authenticity commands margin premiums.
EMA and REACH frameworks in Europe restrict phthalate plasticizers and heavy metal pigments in PVC formulations, pushing compounders toward calcium-zinc stabilizer systems. EPA and OSHA standards in the United States govern formaldehyde emissions from substrate panels and volatile organic compound thresholds in adhesive systems, directly influencing edgeband bonding technology selection. Stakeholders must monitor evolving Ecodesign requirements and state-level extended producer responsibility laws to align product portfolios with compliance timelines and recycling infrastructure investments.
Market Dynamics
REACH and RoHS compliance in Europe is redirecting specification sheets toward low-emission ABS and polypropylene alternatives, forcing compounders to reformulate stabilizer systems and panel processors to recalibrate bonding equipment.
Growth Catalysts
- Modular workstation demand:Hybrid work policies are compressing floor-plan refresh cycles across corporate real estate portfolios, accelerating panel consumption for reconfigurable systems.
- REACH phthalate restrictions:ECHA's substance restrictions on plasticizer chemistry are compelling PVC compounders toward calcium-zinc stabilizer platforms that command specification premiums.
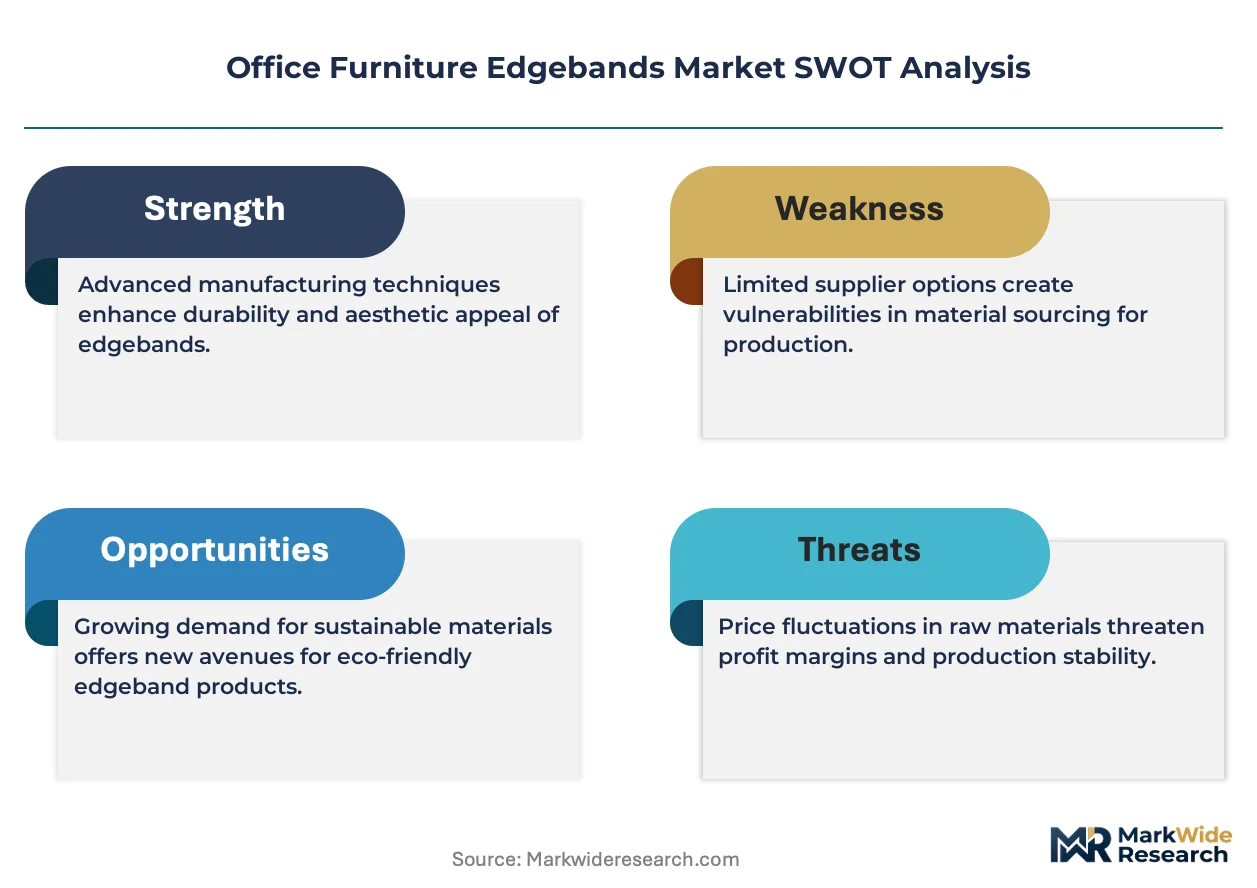
- LEED certification pipelines:Commercial interior projects pursuing BREEAM and LEED accreditation are specifying halogen-free edgebanding to secure material health credits.
Market Restraints
- Petrochemical input volatility:ABS and polypropylene resin prices track naphtha and propylene feedstock swings, compressing compounder margins during upstream shocks.
- German supply concentration:Captive edgebanding operations at major particleboard producers limit independent supplier access to specification channels in Europe's largest panel processing cluster.
- Laser bonding capex barriers:Zero-joint edgebanding systems require panel line retrofits exceeding standard hot-melt equipment replacement cycles, slowing technology diffusion among mid-scale processors.
Strategic Opportunities
- China's green building mandates:Provincial dual carbon enforcement is creating specification windows for low-VOC edgebanding in commercial fit-outs across Shanghai and Shenzhen.
- Take-back infrastructure:Extended producer responsibility frameworks in Germany and France are creating closed-loop material recovery partnerships between furniture OEMs and compounders.
- Digital color matching:Spectrophotometry integration with extrusion lines is enabling batch-size-one production for custom laminate matching without inventory carry.
Industry Challenges
- Adhesive formulation expertise:Hot-melt chemistry optimization for high-speed laser bonding requires polymer science capabilities scarce among traditional edgebanding distributors.
- Multi-certification coordination:Simultaneous compliance with EPA formaldehyde emissions, OSHA VOC thresholds, and REACH substance restrictions demands dedicated regulatory affairs staffing.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Office Furniture Edgebands Market |
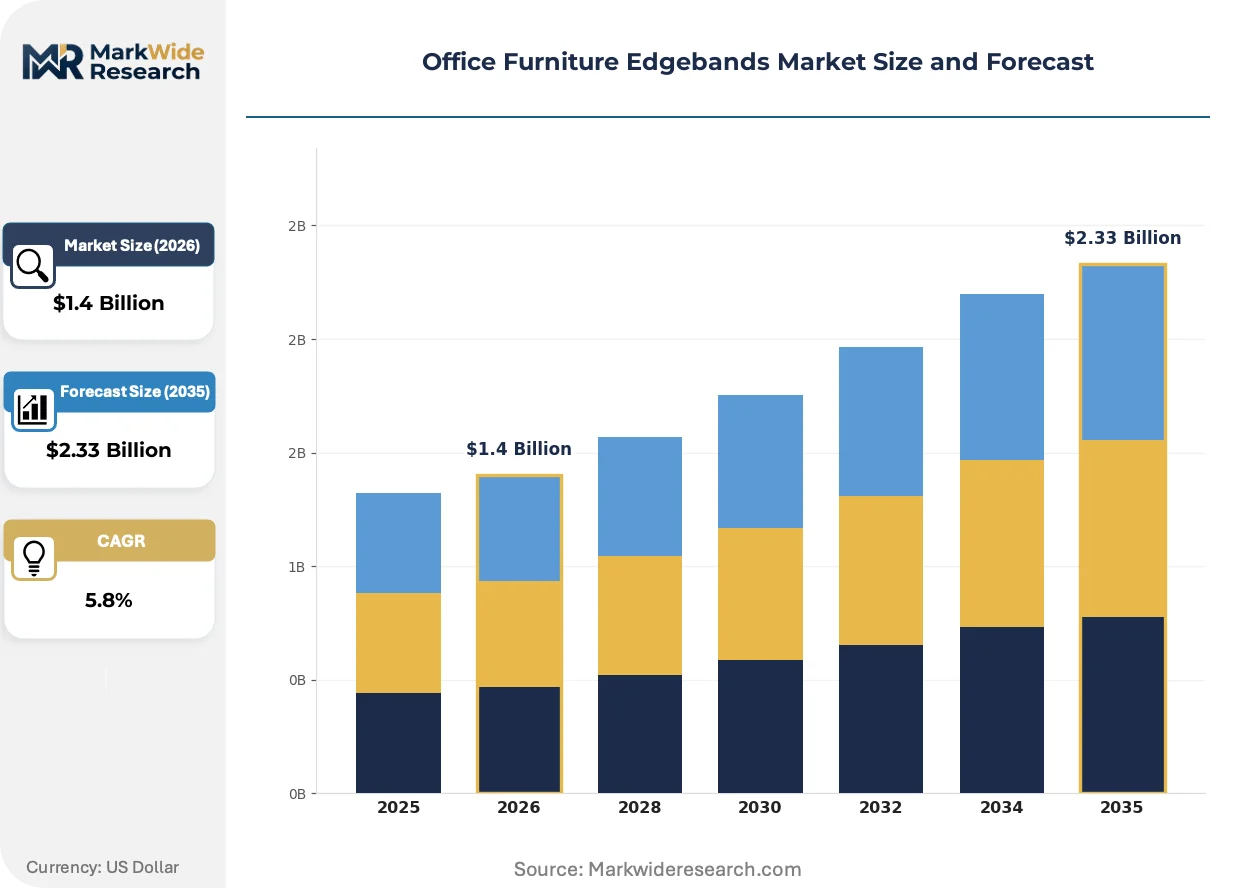
| Market Size in 2026 | $1.4 Billion |
| Market Size in 2035 | $2.33 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Material Type: PVC, ABS, Melamine, Wood Veneer, Polypropylene, Acrylic Application: Desks, Cabinets, Shelving, Conference Tables, Reception Counters, Workstations Finish Type: Matt, Glossy, Textured, Satin, Embossed, Metallic End User: Corporate Offices, Coworking Spaces, Government Agencies, Educational Institutions, Design Studios, Call Centers |
| Companies Covered | REHAU AG + Co, Egger Group, Wilsonart LLC, Hranipex, s.r.o., Ostermann GmbH, Teknaform, Inc., Doellken-Woodtape, Frama-Tech, Inc., MKT GmbH & Co. KG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Office Furniture Edgebands Market Trends and Innovations
Active reformulation of polymer compounds, regulatory chemistry restrictions, and procurement centralization are converging to reshape specification authority and bonding technology selection across commercial furniture supply chains.
Laser-activated edgebanding with functional layers is displacing conventional hot-melt adhesive systems in premium panel processing lines. German and Austrian cabinet manufacturers are adopting zero-joint technology at line speeds exceeding 25 meters per minute. This bonding method is displacing mechanical edge scrapers and enabling seamless surface continuity that commands margin premiums in executive furniture segments.
REACH Annex XVII restrictions on cadmium and lead compounds in PVC stabilizers are forcing compounders toward organic-based and calcium-zinc alternatives. The industrial consequence is elevated raw material cost structures and reformulation validation cycles extending 18-24 months. Furniture manufacturers serving EU public procurement are responding by pre-qualifying ABS and polypropylene alternatives to de-risk specification compliance.
Consolidated procurement desks at multinational furniture OEMs are compressing supplier panels and demanding bonded inventory programs. Distributor networks that previously stocked generic color ranges are being displaced by direct mill relationships with color-matched production slots. This concentration is most visible in North American commercial interiors, where three national furniture systems houses now specify 60% of edgebanding volume through approved vendor lists.
Office Furniture Edgebands Market Segmentation
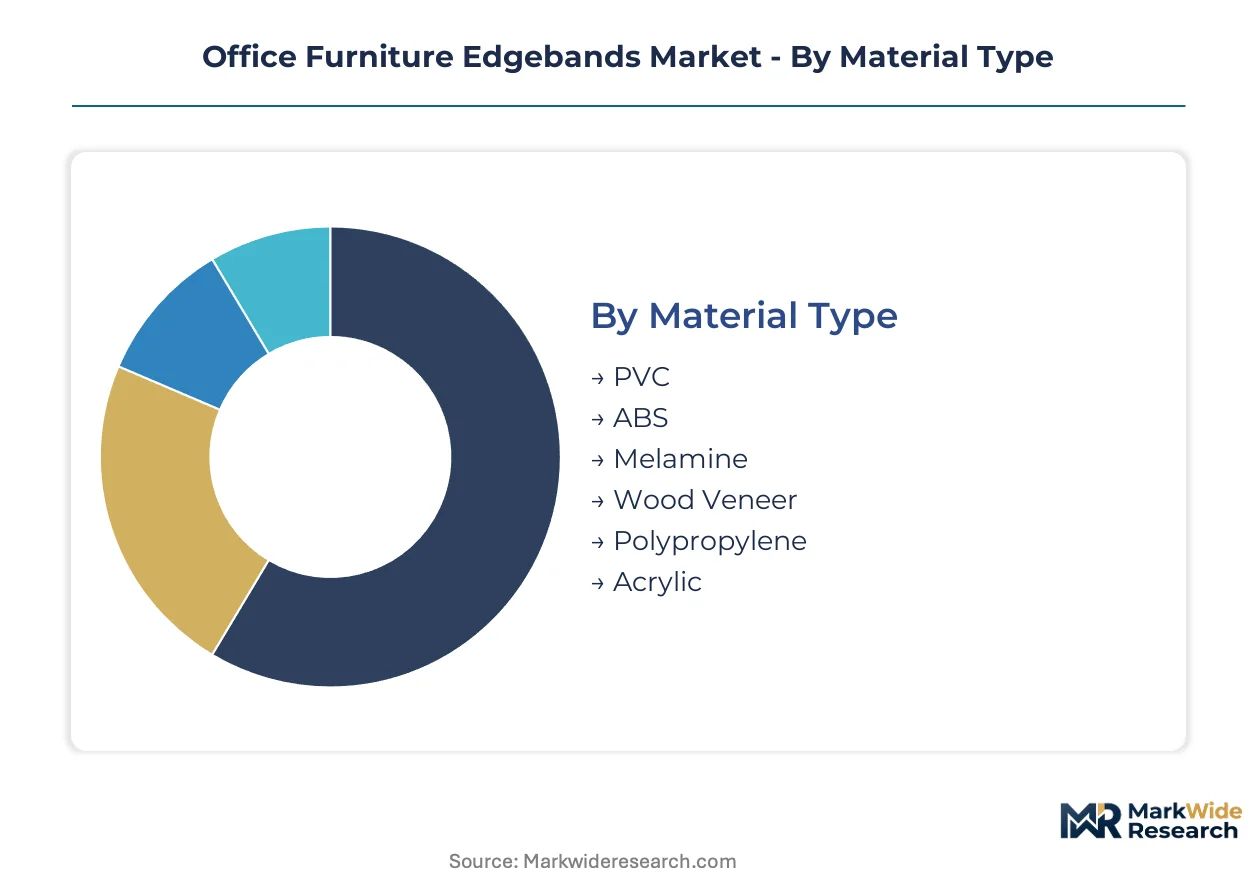
Edgebanding specification flows through distinct procurement channels depending on material chemistry and finish complexity. Panel processors serving furniture OEMs route orders through distributor networks or direct mill relationships based on color-matching requirements and volume commitments.
Material Type:
Channel mix varies sharply by polymer chemistry, with commodity resins moving through distribution and specialty compounds requiring direct technical support.
- PVC:Cost-optimized formulations with calcium-zinc stabilizer systems now dominate high-volume panel lines in Germany and China. REACH phthalate restrictions are compressing specification windows for legacy plasticizer chemistries across European public procurement.
- ABS:Halogen-free polymer structures command premium positioning in LEED-certified commercial interiors. Specifiers in the United States are pre-qualifying ABS alternatives to de-risk multi-certification compliance for corporate fit-out portfolios.
- Melamine:Pre-glued paper-based edgebanding serves budget furniture tiers through mass-market distribution channels.
- Wood Veneer:Natural grain authenticity supports margin premiums in executive furniture segments served by specialty distributors.
- Polypropylene:Recyclable thermoplastic structures align with Ecodesign requirements in French and German closed-loop recovery programs.
- Acrylic:High-gloss surfaces target premium reception and conference applications through specification-focused direct sales.
PVC dominates installed base. ABS is where expansion concentrates.
Application:
End-use geometry dictates thickness specifications and bonding equipment selection across panel processing lines.
- Desks:Rectilinear surfaces consume standard 0.4 mm to 2.0 mm edgebanding at high line speeds. Modular workstation demand in the United States is accelerating refresh cycles for reconfigurable desk systems.
- Cabinets:Vertical panel edges require impact-resistant formulations for storage applications in high-traffic environments.
- Shelving:Open edge exposure drives specification toward durable PVC and ABS grades in retail and library fit-outs.
- Conference Tables:Large surface areas demand seamless color matching across multiple laminate suppliers.
- Reception Counters:Curved edge profiles require flexible thermoplastic formulations with post-forming capability.
- Workstations:Privacy panel edges specify thin-gauge edgebanding for acoustic partition systems in open-plan offices.
Desks and workstations absorb the highest panel volumes. Reception counters deliver the steepest expansion trajectory as experience-driven commercial interiors proliferate.
Finish Type:
Surface aesthetics separate commodity supply from specification-grade relationships with laminate OEMs.
- Matt:Low-sheen surfaces minimize glare in monitor-intensive workstation environments.
- Glossy:High-reflectance acrylic and lacquered finishes command premium positioning in executive and reception applications.
- Textured:Embossed patterns replicate wood grain and stone surfaces for design continuity with premium laminates.
- Satin:Intermediate sheen levels balance aesthetic refinement with fingerprint resistance in high-touch areas.
- Embossed:Deep-relief surface structures enhance tactile authenticity in hospitality-influenced office designs.
- Metallic:Specialty pigment systems target statement furniture pieces in branded corporate environments.
Textured and matt finishes dominate specification volume. Glossy and metallic variants are climbing the fastest as premium commercial interiors emphasize visual differentiation.
End User:
Procurement authority concentrates differently across customer types, with consolidated furniture OEMs driving approved vendor list concentration.
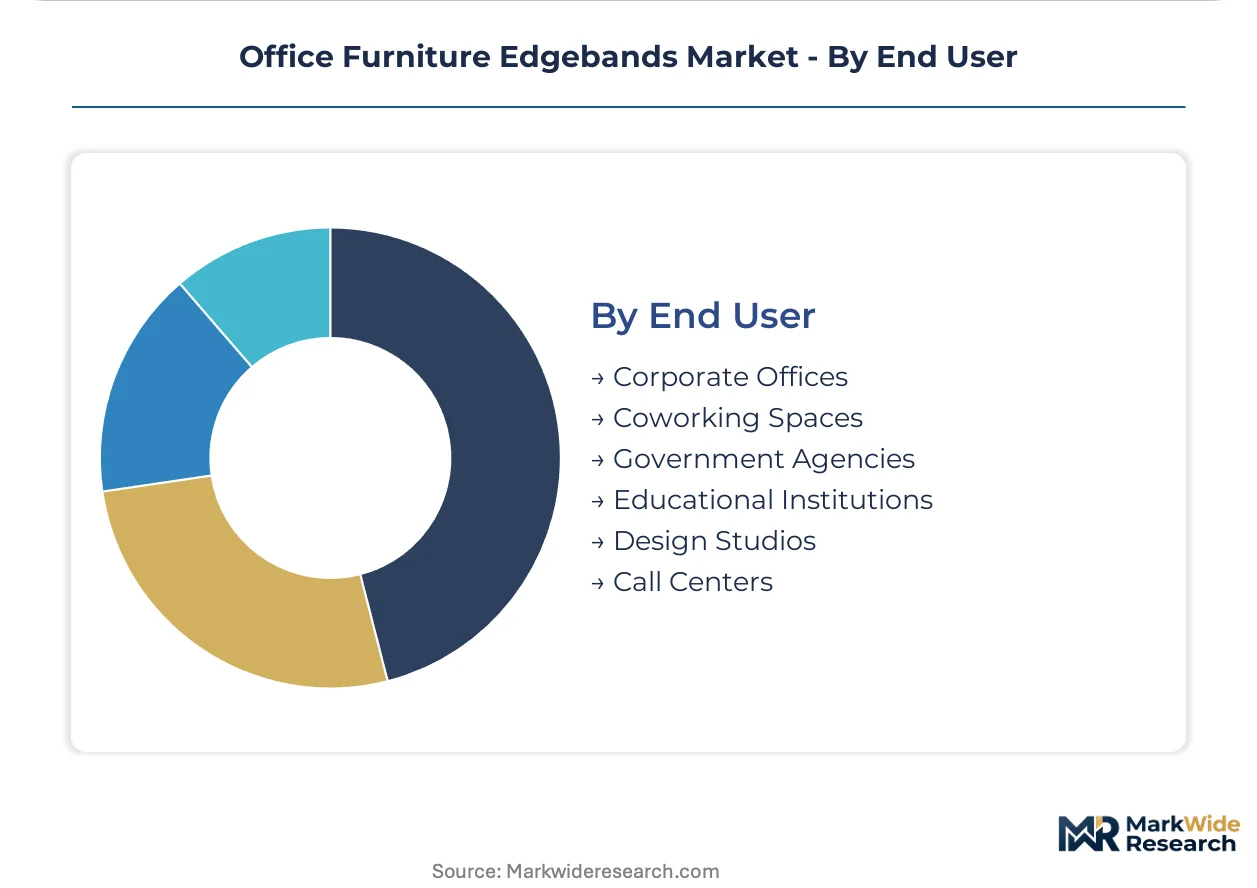
- Corporate Offices:Multinational real estate portfolios standardize edgebanding specifications through national furniture systems houses. Three United States-based OEMs now control the majority of commercial interiors volume through bonded inventory programs.
- Coworking Spaces:Rapid fit-out cycles prioritize cost-optimized PVC and melamine solutions through distributor channels.
- Government Agencies:EU public procurement mandates REACH and Ecodesign compliance, favoring pre-qualified ABS and polypropylene alternatives.
- Educational Institutions:Durability requirements for high-abuse environments specify impact-resistant thermoplastic grades.
- Design Studios:Custom color matching and small-batch production serve bespoke furniture commissions.
- Call Centers:High-density seating configurations drive volume demand for standardized workstation components.
Corporate offices anchor revenue concentration. Coworking spaces are gaining share fastest as flexible lease structures multiply fit-out velocity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German compounders export color-matched edgebanding to panel processors across Poland and the Czech Republic. Chinese manufacturers supply PVC and ABS grades to Southeast Asian furniture assembly hubs. This trade-flow pattern concentrates specification authority in manufacturing clusters with captive resin compounding capabilities.
Germany
Modular workstation demand from corporate real estate refreshes drives panel consumption in the Rhine-Ruhr and Bavarian manufacturing belts. REACH Annex XVII restrictions on cadmium stabilizers force compounders toward calcium-zinc and organic-based alternatives. The Ostwestfalen-Lippe region hosts dense clusters of particleboard producers with captive edgebanding operations.
China
Provincial dual carbon enforcement in Shanghai and Shenzhen creates specification windows for low-VOC ABS and polypropylene alternatives. MIIT guidelines on green building materials accelerate substitution away from high-emission PVC formulations. The Yangtze River Delta panel processing corridor feeds furniture export manufacturing in Zhejiang and Jiangsu provinces.
United States
Three national furniture systems houses now control specification authority for the majority of commercial interiors volume. EPA formaldehyde emission standards and OSHA VOC thresholds govern adhesive system selection across panel processing lines. The Carolina Piedmont furniture manufacturing belt concentrates demand for impact-resistant thermoplastic grades.
France
Extended producer responsibility frameworks create closed-loop material recovery partnerships between furniture OEMs and compounders. Ecodesign requirements under the EU Green Deal redirect public procurement toward recyclable polypropylene structures. The Auvergne-Rhône-Alpes region hosts specialty distributors serving design studio and premium reception applications.
Poland
Panel processors serving Western European export markets import German-compounded edgebanding through cross-border supply chains. CE marking requirements align local production with EU-wide substance restrictions. The Greater Poland Voivodeship furniture cluster absorbs volume for standardized workstation components.
Office Furniture Edgebands Market Competitive Landscape
Player mix skews toward polymer compounders with captive resin operations and laminate-integrated panel processors. Market structure concentrates around vertically integrated particleboard producers and independent distributors serving color-matched specification channels. Strategic archetypes include stabilizer-system compounders, zero-joint technology licensors, and direct-mill color matching specialists. Competitive moves center on laser bonding equipment partnerships and bonded inventory programs with multinational furniture OEMs.
Within the compounder tier, REHAU AG + Co and Egger Group exemplify divergent structural positions. REHAU represents the independent polymer specialist archetype with extrusion capabilities decoupled from substrate manufacturing. Egger occupies a position as the captive supply archetype, anchoring edgebanding demand through internal particleboard and laminate operations. Wilsonart LLC sits within the surface-integrated fabricator tier, leveraging decorative laminate expertise to command specification authority in premium commercial interiors.
| Leading Market Players |
|---|
| REHAU AG + Co |
| Egger Group |
| Wilsonart LLC |
| Hranipex, s.r.o. |
| Ostermann GmbH |
| Teknaform, Inc. |
| Doellken-Woodtape |
| Frama-Tech, Inc. |
| MKT GmbH & Co. KG |
| Others |
Pricing and Supply Chain Analysis
REACH Annex XVII substance restrictions gate both supplier qualification and price differentiation simultaneously, forcing compounders toward calcium-zinc stabilizer platforms that command specification premiums while excluding legacy PVC formulations from EU public procurement channels. Panel processors face dual certification burdens that stratify vendor tiers by compliance investment depth.
Pricing Analysis
Zero-joint laser bonding systems carry 40-60% equipment premiums over standard hot-melt lines, translating to higher edgebanding unit costs for processors serving premium commercial interiors. Pricing stratifies across premium, standard, and economy tiers based on certification grade and color-matching complexity. Cost compression in commodity PVC grades intensifies as naphtha feedstock volatility squeezes compounder margins. Coworking space operators exhibit highest price sensitivity, while design studios and executive furniture OEMs prioritize specification-grade ABS and acrylic finishes with limited elasticity.
Supply Chain Analysis
Germany, China, and the United States anchor resin compounding and panel processing capacity across the value chain. ABS and polypropylene formulations draw from propylene and styrene monomer streams vulnerable to petrochemical price swings. Single-source vulnerability concentrates in German particleboard producers with captive edgebanding operations that limit independent supplier access. Distribution runs through direct mill relationships for color-matched specifications and distributor networks for generic inventory.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as hybrid work policies compress corporate real estate refresh cycles and accelerate modular workstation adoption across commercial fit-out portfolios.
For Market Incumbents: Secure bonded inventory partnerships with multinational furniture OEMs before procurement centralization hardens approved vendor lists. Deepen upstream control over calcium-zinc stabilizer supply chains to defend margin position against REACH-driven reformulation costs. Pre-qualify ABS and polypropylene alternatives to de-risk specification compliance as Ecodesign requirements tighten. For New Entrants and Emerging Players: Lead with digital color-matching capabilities targeting design studios and bespoke furniture commissions underserved by high-volume compounders. China's provincial dual carbon enforcement creates specification windows for low-VOC alternatives in Shanghai and Shenzhen commercial fit-outs. Pursue direct technical sales relationships with panel processors lacking in-house spectrophotometry integration. For Investors and Strategic Acquirers: Carve-out targets emerge from diversified chemical conglomerates with underoptimized edgebanding divisions lacking laser bonding equipment partnerships. Long-term viability hinges on regulatory chemistry adaptation capacity and closed-loop material recovery infrastructure. Watch for inflection signals in extended producer responsibility framework implementation across France and Germany.| Strategic Initiative | Industry Significance |
|---|---|
| Laser Bonding Equipment Partnership | Zero-joint technology adoption at 25+ meters per minute displaces conventional hot-melt systems in German and Austrian cabinet manufacturing. |
| Calcium-Zinc Stabilizer Platform Transition | REACH Annex XVII compliance investment separates qualified EU suppliers from excluded legacy PVC compounders. |
| Direct Mill Color Matching Integration | Spectrophotometry-enabled batch-size-one production eliminates inventory carry for custom laminate specifications. |
| Closed-Loop Material Recovery Partnership | French and German extended producer responsibility frameworks create captive supply agreements with furniture OEMs. |
| Green Building Certification Pre-Qualification | LEED and BREEAM material health credits drive specification share toward halogen-free ABS and polypropylene alternatives. |
Research Methodology
A spread of perspectives from polymer compounding executives, panel processing plant managers, furniture OEM procurement leads, and distributor channel partners converged on the working assumptions underlying demand forecasts. Primary fieldwork combined structured interviews with secondary validation through customs trade data, SEC filings from listed laminate and particleboard producers, and REACH regulatory submission databases. Bottom-up volume estimates triangulated against top-down market sizing derived from panel processing line capacity and edgebanding consumption rates per square meter of finished furniture.
Segmentation dimensions modeled include material chemistry, finish complexity, application geometry, and end-user procurement authority across the projection horizon. CAGRs were derived from regression analysis of historical panel consumption against corporate real estate refresh cycle data and green building certification pipeline growth. Industry-specific forecast inputs incorporated Ecodesign requirement implementation timelines and laser bonding equipment diffusion curves among mid-scale processors.
The analysis sits within stated boundaries; outcomes outside sustained hybrid work policy adoption or accelerated REACH substance restriction timelines would require recalibration. Forecasts reflect assumptions about petrochemical feedstock price stability and bonding technology capital expenditure cycles. Recalibration cycles align with material shifts in regulatory chemistry mandates and corporate real estate portfolio restructuring velocity.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Luxury Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
China Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Asia-Pacific Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Office Chairs Market
Office Furniture
Home Office Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Europe Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
France Office Furniture Market