
 Asia-Pacific Office Furniture Market | 2026-2036
Asia-Pacific Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Office Furniture Market Outlook
China's GB standards for indoor air quality and formaldehyde emissions is pivoting the cost-of-entry calculus for domestic and imported furniture alike. Sunon Group leverages its manufacturing scale to meet these certification thresholds across multiple product lines. Okamura Corporation anchors its premium positioning through R&D intensity in ergonomic seating systems. Godrej Interio dominates the Indian institutional segment with channel control that extends into tier-two cities.
Asia-Pacific office furniture encompasses workstations, seating, storage, and spatial division systems engineered for commercial interior environments, typically fabricated from engineered wood substrates, steel framing, and thermoplastic components with surface finishes rated for abrasion resistance and VOC compliance. The primary purpose is to organize human activity within workplaces while supporting musculoskeletal health and acoustic privacy. The ergonomic design style commands margin pools as enterprises prioritize employee retention through wellness-oriented interiors, while the co-working spaces end-user segment represents the fastest-growing demand channel as flexible lease models proliferate across Southeast Asian business districts. Metal as a material category sustains share in high-traffic corporate installations where durability specifications outweigh first-cost considerations.
Japan's METI enforces JIS standards that govern product safety and sustainability labeling, while Australia's TGA-equivalent building product regulator mandates compliance with fire-resistance and structural integrity benchmarks for commercial fit-outs. India's BIS certification requirements for furniture create non-tariff barriers that favor localized production over direct import. Stakeholders must monitor how ASEAN harmonization of technical standards alters cross-border manufacturing footprints and procurement rules of origin.
Market Dynamics
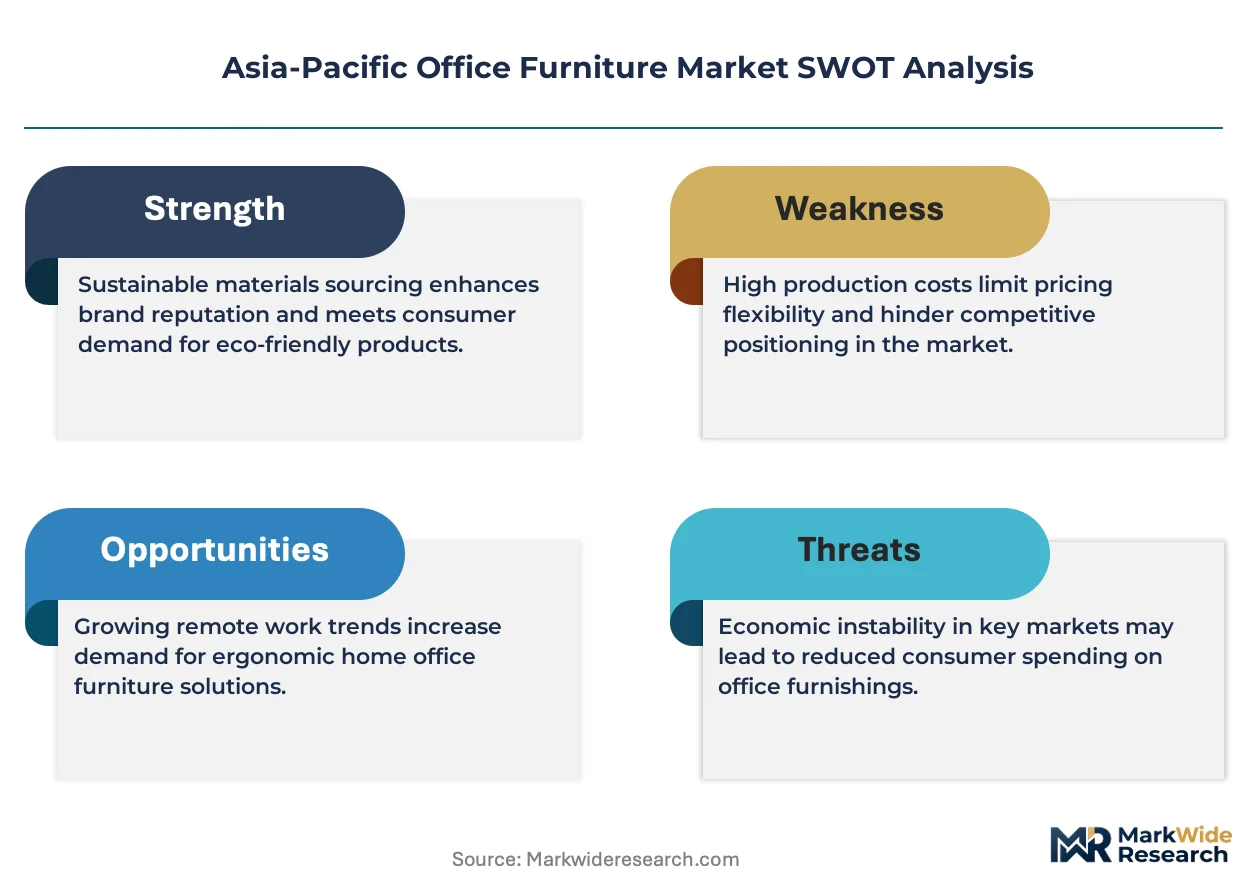
China's GB standards for indoor air quality and formaldehyde emissions are recalibrating manufacturing cost structures across the Asia-Pacific office furniture supply base. Compliance investments now determine market access for both domestic producers and cross-border suppliers.
Growth Catalysts
- India's PLI scheme for furniture manufacturing:Production-linked incentives are lowering import dependence and attracting capital into Gujarat and Tamil Nadu manufacturing clusters.
- Technology campus expansion:Bulk procurement from IT and BPO sectors across Bangalore and Hyderabad is driving workstation volume contracts.
- Ergonomic wellness mandates:Enterprise HR policies prioritizing musculoskeletal health are accelerating specification of adjustable-height desks and task seating.
Market Restraints
- Engineered wood price volatility:MDF and particleboard input costs fluctuate with pulp fiber availability and regional resin supply constraints.
- China supply concentration:Component and hardware sourcing dependence on Zhejiang and Guangdong provinces creates geographic risk exposure.
- BIS certification timelines:India's Bureau of Indian Standards testing protocols extend product launch cycles by four to six months for imported furniture.
Strategic Opportunities
- Vietnam manufacturing migration:Labor cost arbitrage and EU trade agreement access are drawing assembly capacity from China into Hai Phong industrial zones.
- Circular material flows:Take-back programs and certified recycled content are opening specification pathways with ESG-mandated corporate buyers.
- Co-working channel development:Flexible lease operators across Singapore and Jakarta represent high-velocity, design-forward procurement relationships.
Industry Challenges
- Ergonomic design talent scarcity:Industrial designers with biomechanics training remain concentrated in Japan and South Korea, limiting regional R&D scaling.
- Multi-standard compliance burden:Simultaneous GB, JIS, and BIS certification requirements fragment product development resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Office Furniture Market |
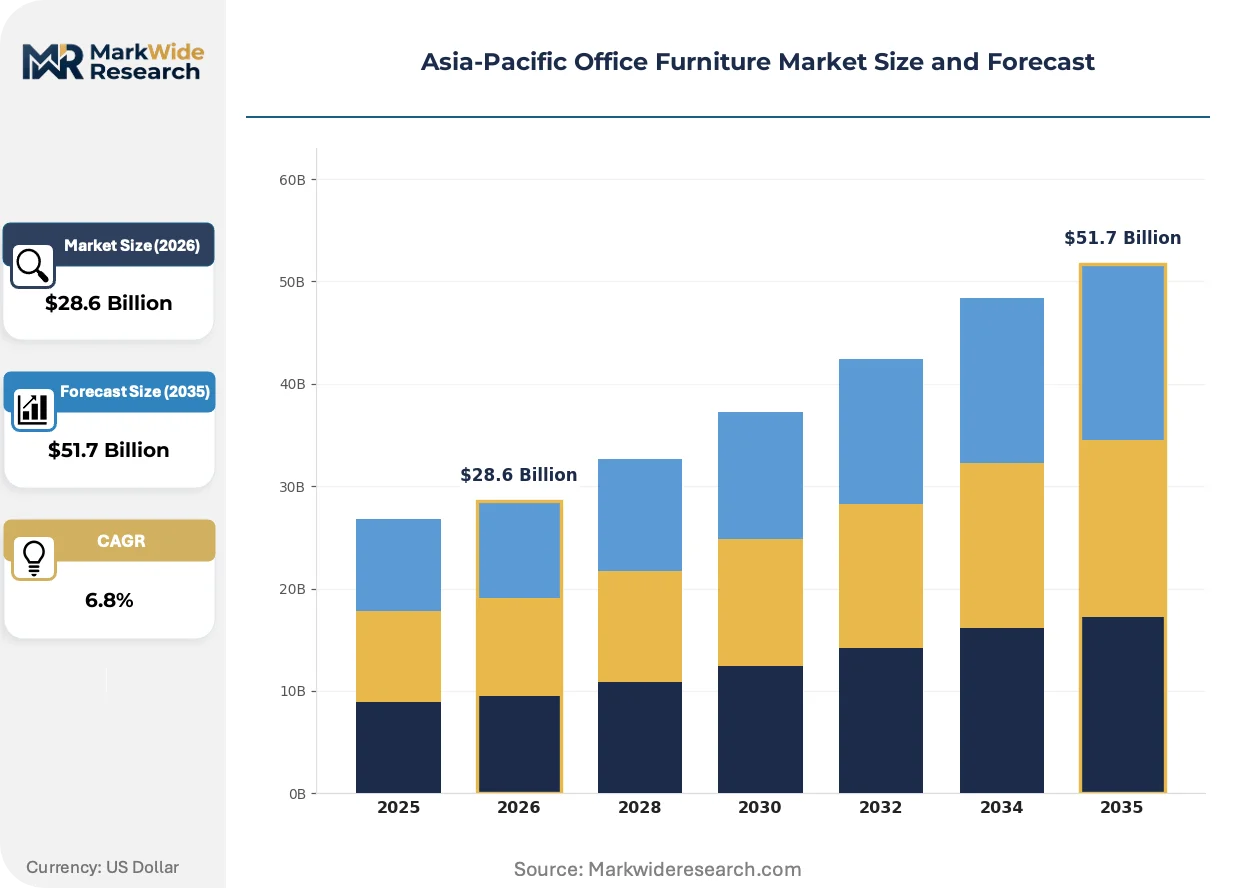
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $51.7 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Cabinets, Partitions End User: Corporate Offices, Co-working Spaces, Government Offices, Educational Institutions Material: Wood, Metal, Plastic, Glass Design Style: Modern, Traditional, Ergonomic, Minimalist |
| Companies Covered | MillerKnoll, Sunon Group, Okamura Corporation, HNI Corporation, Godrej Interio, KOKUYO Co., Ltd., Haworth Inc., Itoki Corporation, Steelcase Inc., Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Office Furniture Market Strategic Shifts
Sensor-embedded furniture and material traceability systems are redefining how workplace assets are specified, monitored, and retired across Asia-Pacific commercial interiors.
Smart workstation systems integrating occupancy sensors and environmental monitors are electrifying the traditional furniture category. Multinational headquarters in Shanghai and Singapore are specifying these connected assets for space utilization analytics. The technology is compressing replacement cycles as IT refresh timelines override physical durability ratings.
Japan's METI enforcement of JIS sustainability labeling requirements is tightening disclosure obligations for product lifecycle data. Manufacturers must now document carbon intensity and material provenance to maintain market access. Premium seating and systems furniture categories face the steepest compliance cost escalations.
Enterprise buyers are consolidating vendor relationships around full-service workspace partners. Single-source contracts covering design, installation, and ongoing refresh are displacing transactional furniture procurement. This pattern is most pronounced among financial services and professional services firms in Sydney and Hong Kong.
Asia-Pacific Office Furniture Market Segmentation
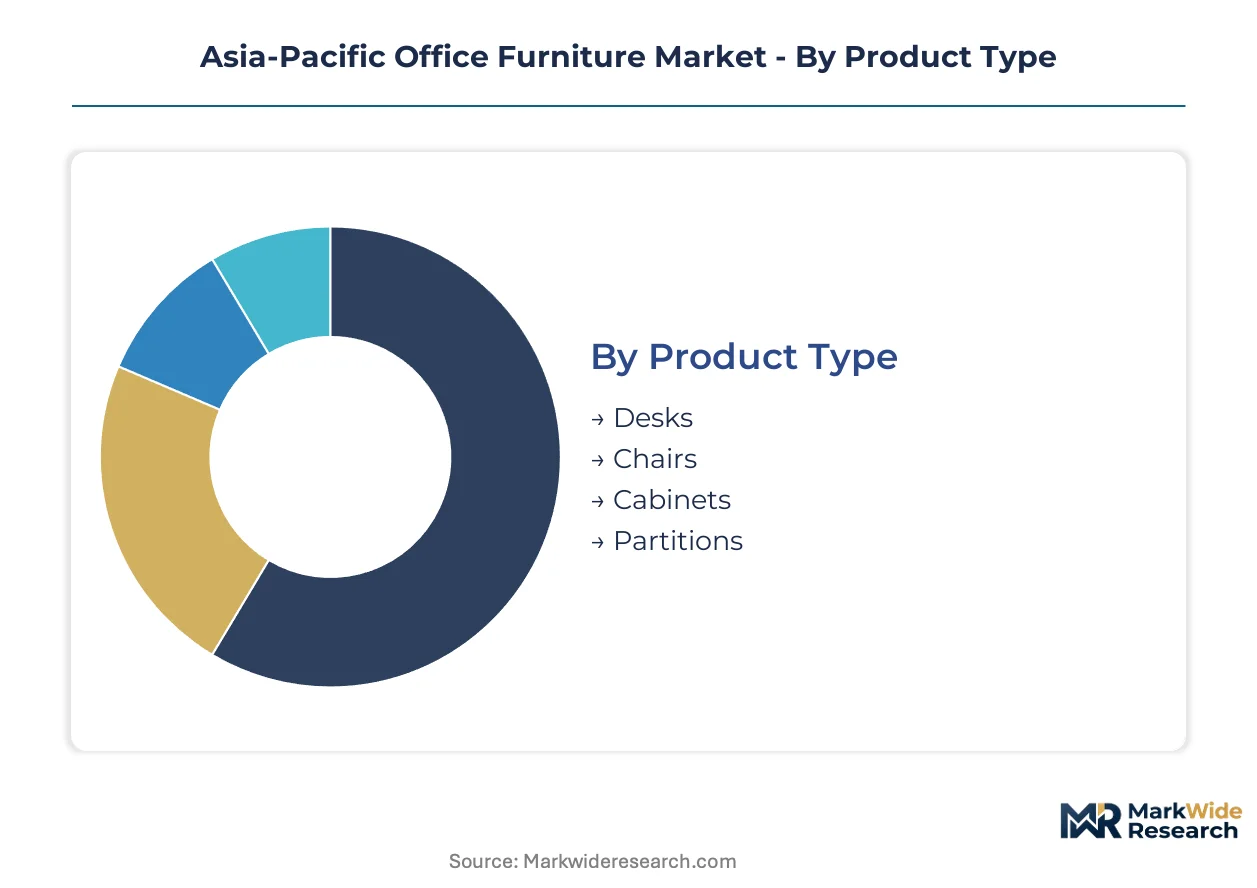
Segmentation reveals how procurement priorities diverge across buyer types and material specifications in Asia-Pacific office furniture. Each dimension exposes distinct margin structures and compliance requirements that shape competitive positioning.
Product Type:
Standalone furniture systems operate independently of building infrastructure, while integrated systems require coordination with electrical and data networks during installation.
- Desks:Height-adjustable workstations with electric lift mechanisms and cable management channels dominate technology sector procurement in Bangalore and Hyderabad. IT campus expansions specify these for ergonomic compliance and space density optimization.
- Chairs:Task seating incorporates synchro-tilt mechanisms, lumbar support adjustability, and breathable mesh upholstery rated for extended use cycles. Multinational headquarters in Singapore and Shanghai prioritize these for employee retention metrics.
- Cabinets:Storage systems with modular drawer configurations and locking protocols serve institutional buyers across Indian government offices.
- Partitions:Acoustic panel systems and glass-divided workstations enable spatial reconfiguration in flexible lease environments across Jakarta co-working operators.
Chairs lead volumes today; desks are gaining share fastest.
End User:
Cost tiers separate specification authority between centralized procurement teams and distributed facility managers.
- Corporate Offices:Enterprise buyers with ESG mandates specify certified sustainable materials and full-service vendor partnerships covering design through refresh cycles. Financial services firms in Sydney and Hong Kong consolidate spend around single-source contracts.
- Co-working Spaces:Flexible lease operators prioritize rapid-install, design-forward furniture with shorter depreciation schedules. Singapore and Jakarta operators drive high-velocity procurement relationships.
- Government Offices:Public sector buyers in India face BIS certification requirements that extend launch timelines and favor localized production.
- Educational Institutions:Universities and training centers across China specify durability-rated furniture for high-traffic lecture halls and library environments.
Corporate offices command premium pricing; co-working spaces are expanding most quickly.
Material:
Supply concentration for engineered substrates and metal framing creates geographic risk exposure across the value chain.
- Wood:Engineered wood substrates including MDF and particleboard face price volatility from pulp fiber availability and regional resin constraints. GB standards for formaldehyde emissions in China recalibrate manufacturing cost structures.
- Metal:Steel framing systems sustain specification share in high-traffic corporate installations where durability ratings outweigh first-cost considerations.
- Plastic:Thermoplastic components for seating shells and edge banding offer weight reduction and color consistency across large deployments.
- Glass:Tempered glass surfaces and partition panels serve premium aesthetic requirements in headquarters and client-facing environments.
Wood dominates volume; metal holds pricing power in premium segments.
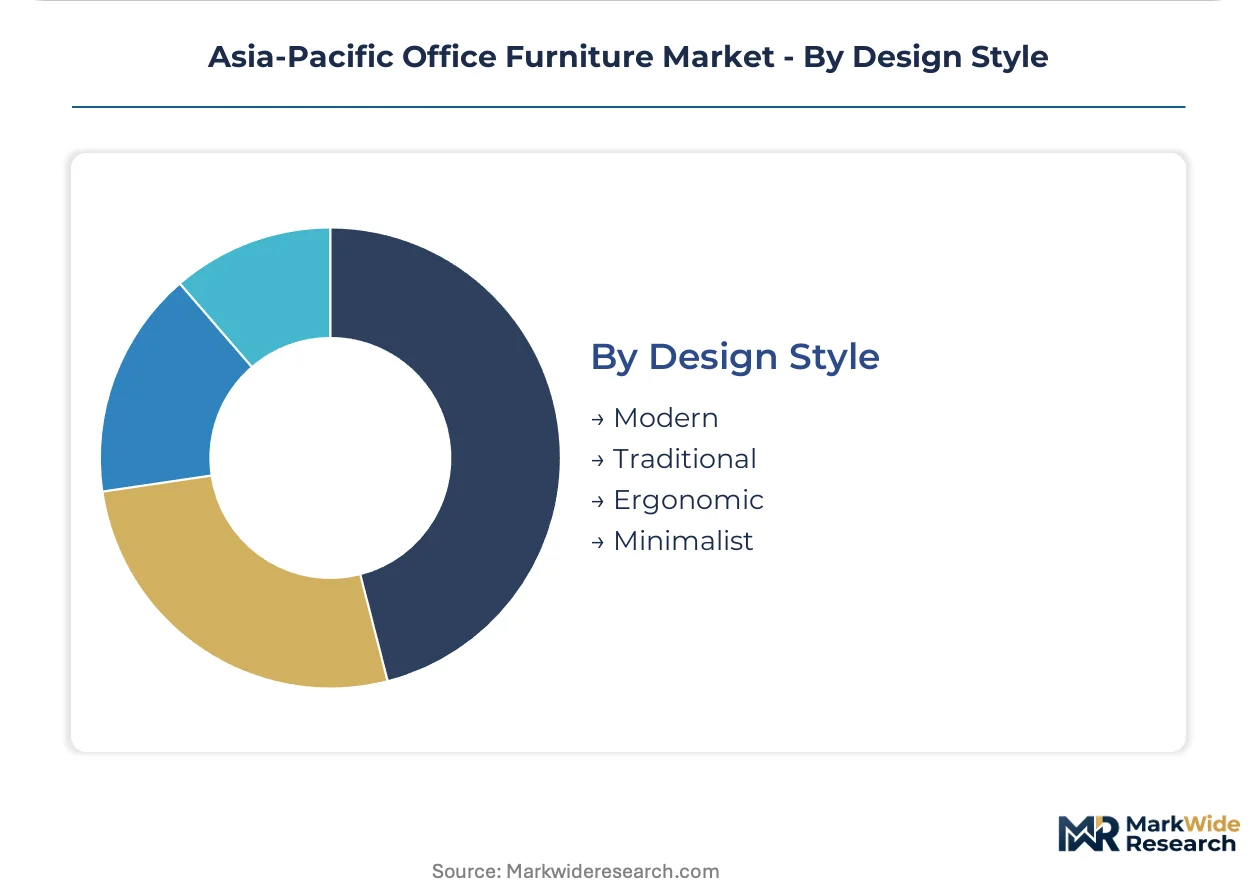
Design Style:
Maturity curves separate established aesthetic categories from emerging wellness-oriented specifications.
- Modern:Clean-lined furniture with neutral palettes and concealed hardware aligns with multinational brand standards across Asia-Pacific headquarters.
- Traditional:Ornate wood finishes and classical proportions serve institutional and heritage building requirements in select government and legal sector applications.
- Ergonomic:Biomechanically optimized workstations and seating systems command margin pools as enterprise HR policies prioritize musculoskeletal health and employee retention through wellness-oriented interiors.
- Minimalist:Reduced-material designs with visible structural elements appeal to design-forward co-working operators and creative sector tenants.
Modern styling leads specification frequency; ergonomic design climbs the fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
India's technology workforce concentration across Bangalore and Hyderabad anchors procurement volume in the region. China's manufacturing scale and domestic corporate expansion sustain dual demand for production inputs and finished goods. Japan's aging office stock and METI sustainability mandates drive replacement cycles for premium systems furniture.
China
Corporate campus expansions by domestic technology conglomerates in Shenzhen and Hangzhou drive bulk workstation procurement. GB standards for formaldehyde emissions and indoor air quality recalibrate manufacturing cost structures for domestic and imported suppliers alike. Zhejiang and Guangdong provinces concentrate component and hardware sourcing, creating geographic risk exposure for regional supply chains.
India
IT and BPO sector growth across the Mumbai-Bangalore metropolitan corridor generates high-volume contracts for ergonomic workstations. The PLI scheme for furniture manufacturing lowers import dependence and attracts capital into Gujarat and Tamil Nadu production clusters. BIS certification requirements create non-tariff barriers that favor localized production over direct import channels.
Japan
Enterprise headquarters in Tokyo and Osaka prioritize premium seating and systems furniture for employee retention metrics. METI enforces JIS standards governing product safety and sustainability labeling with tightened disclosure obligations for lifecycle data. Industrial designers with biomechanics training concentrate in Kanto and Kansai regions, limiting regional R&D scaling elsewhere.
Singapore
Multinational financial services and professional services firms consolidate vendor relationships around full-service workspace partnerships. Flexible lease operators across the central business district drive high-velocity procurement for design-forward furniture with shorter depreciation schedules. The city-state functions as a specification gateway influencing procurement standards across Southeast Asian markets.
Australia
Commercial fit-out activity in Sydney and Melbourne sustains demand for durability-rated metal framing systems in high-traffic corporate installations. Building product regulators mandate compliance with fire-resistance and structural integrity benchmarks. Enterprise buyers with ESG mandates specify certified sustainable materials and circular material flows through take-back programs.
Asia-Pacific Office Furniture Market Competitive Environment
The competitive structure tilts toward diversified conglomerates with captive manufacturing capacity. Domestic champions in China and India leverage scale and regulatory familiarity to defend position against multinational entrants. Three archetypes dominate: integrated manufacturers controlling substrate-to-assembly value chains, design-forward specialists commanding premium positioning through R&D intensity, and full-service workspace partners consolidating procurement relationships around single-source contracts. Capacity expansion and portfolio diversification represent the dominant competitive moves as players respond to co-working channel growth and ergonomic wellness mandates.
Within the integrated manufacturing tier, Sunon Group and Godrej Interio exemplify scale-driven positioning. Sunon leverages manufacturing breadth across multiple product lines to meet certification thresholds efficiently. Godrej Interio anchors institutional segment presence through channel control extending into tier-two Indian cities. Among design-intensive specialists, Okamura Corporation occupies a position defined by R&D concentration in ergonomic seating systems. These three companies collectively represent how geographic origin and structural form shape competitive archetype alignment in the region.
| Leading Market Players |
|---|
| MillerKnoll |
| Sunon Group |
| Okamura Corporation |
| HNI Corporation |
| Godrej Interio |
| KOKUYO Co., Ltd. |
| Haworth Inc. |
| Itoki Corporation |
| Steelcase Inc. |
| Others |
Value Chain & Pricing Dynamics
Bulk procurement contracts from technology campuses across Bangalore and Hyderabad are compressing margins on standardized workstations and forcing suppliers to absorb certification costs or cede volume to integrated manufacturers with captive substrate production.
Pricing Analysis
Full-service workspace partnerships versus transactional component sales define the dominant pricing split. Three-tier pricing structure across premium, standard, and economy levels separates ergonomic-certified systems from basic compliance-grade furniture and import-dependent budget lines. Cost compression in the economy tier intensifies because BIS certification timelines extend launch cycles for cross-border suppliers. Co-working operators exhibit highest price sensitivity due to rapid depreciation schedules, while financial services headquarters in Singapore and Sydney accept premium positioning for single-source vendor consolidation.
Supply Chain Analysis
Container freight rates from Zhejiang and Guangdong provinces to Indian west coast ports directly input into landed cost calculations for component-dependent assemblers. Engineered wood substrates and steel framing systems draw from manufacturing clusters in China, Vietnam, and India. Pulp fiber availability and regional resin supply constraints create raw material volatility. Single-source vulnerability concentrates in Zhejiang hardware sourcing. Distribution runs through project-based dealer networks for corporate fit-outs and direct vendor relationships for co-working channel procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where China's GB standards for formaldehyde emissions and India's BIS certification requirements continuously elevate compliance investment thresholds and favor capitalized domestic manufacturers.
For Market Incumbents: Extend channel control into tier-two Indian cities before PLI scheme subsidies attract new manufacturing entrants. Deepen backward integration into engineered wood substrate production to buffer pulp fiber price volatility. Certify multiple product lines simultaneously against GB, JIS, and BIS standards to amortize compliance costs across volume.
For New Entrants and Emerging Players: Launch via design-forward co-working channel partnerships in Jakarta and Singapore where specification authority decentralizes to flexible lease operators. Target acoustic partition systems for Southeast Asian co-working expansion where rapid-install requirements outpace incumbent response times. Prioritize ergonomic designer recruitment from Japan's Kanto region to differentiate on biomechanical R&D.
For Investors and Strategic Acquirers: Asymmetric upside sits with Vietnam-based assembly specialists with EU trade agreement access and Hai Phong industrial zone operational presence. Five-to-ten year viability hinges on circular material flow capabilities and take-back program infrastructure. Monitor ASEAN harmonization of technical standards as inflection indicator for cross-border manufacturing footprint rationalization.
| Strategic Initiative | Industry Significance |
|---|---|
| Certification Multi-Standard Stacking | Simultaneous GB, JIS, and BIS compliance amortizes testing costs across product portfolios. |
| Backward Integration into Substrates | Captive MDF and particleboard production buffers pulp fiber price volatility for margin stability. |
| Co-Working Channel Direct Partnerships | Design-forward procurement relationships in Singapore and Jakarta bypass traditional dealer networks. |
| Vietnam Manufacturing Migration | Hai Phong assembly capacity leverages EU trade agreement access for tariff-advantaged export positioning. |
| Circular Material Flow Investment | Take-back programs and certified recycled content unlock ESG-mandated corporate buyer specifications. |
Study Parameters
Direct dialogue with furniture manufacturing executives, corporate procurement officers at technology campuses, co-working space operators, ergonomic design specialists, and BIS certification consultants grounded qualitative findings. Secondary validation drew from customs trade databases, Bureau of Indian Standards filing records, METI sustainability disclosure registries, and SEC 10-K filings of listed furniture manufacturers. Bottom-up and top-down triangulation cross-checked volume assumptions against production capacity announcements and import-export flow data.
Bottom-up modeling aggregated segment-level demand across product type, end-user category, material specification, and design style dimensions. Top-down validation referenced macroeconomic indicators for commercial real estate absorption and technology sector employment growth across the analysis window. CAGRs derived from regression analysis of historical procurement patterns and projected workspace expansion timelines. Specific forecast inputs included IT campus build-out schedules, PLI scheme subsidy disbursement trajectories, and co-working lease velocity indices.
Forecast precision tightens around the base case; tail outcomes carry wider variance under ASEAN regulatory harmonization delays or engineered wood supply disruptions. Projections reflect assumptions about certification timeline stability and technology sector capital expenditure continuity. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
Japan Office Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
France Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Rental Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Ergonomic Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Desk Chairs Market
Office Furniture
Office Seat Cushion Market