
 Japan Office Furniture Market | 2026-2036
Japan Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Japan Office Furniture Market Foresight
Technology sector workspace upgrades are hardening demand for ergonomic seating and collaborative workstations across Japan. Okamura Corporation leverages its domestic manufacturing scale to anchor supply for premium task chairs and height-adjustable desks. Kokuyo Co., Ltd. sustains R&D intensity in smart office systems that integrate sensor-enabled furniture. Itoki Corporation specializes in modular workspace configurations that compete on flexibility for hybrid office layouts.
Japan office furniture comprises desks, chairs, tables, and storage units engineered to JIS standards for load-bearing capacity, fire resistance, and formaldehyde emission limits, serving commercial workspaces where employee productivity and spatial efficiency determine procurement value. Chairs and desks dominate current revenue pools as corporates replace aging inventories, while storage units represent the fastest-growing category as densification drives vertical filing demand. Wood and metal materials lead specification sheets, though metal frames with recycled content are gaining share as METI circular economy guidelines tighten.
METI enforces JIS standards for structural safety and chemical emissions, while the Ministry of Health, Labour and Welfare regulates workplace ergonomics under Industrial Safety and Health Act provisions that mandate adjustable seating for prolonged computer use. These frameworks elevate compliance costs for imported products while creating preferential market access for domestic manufacturers certifying to JIS Z 2801 antimicrobial standards. Stakeholders must monitor whether forthcoming revisions to building energy codes accelerate demand for furniture-integrated power and data systems.
Market Dynamics
Hybrid work normalization is fragmenting procurement authority across Japanese enterprises, as facility managers lose centralized control over furniture specifications to departmental IT and HR buyers prioritizing plug-and-play modularity over traditional durability metrics.
Growth Catalysts
- Technology sector workspace upgrades:Persistent hybrid models at Tokyo-based software firms are accelerating replacement cycles for ergonomic seating and collaborative workstations.
- METI sustainability guidelines:Circular economy mandates for building materials are redirecting public and corporate procurement toward furniture with verified recycled metal content and lower formaldehyde emissions.
- Greater Tokyo commercial corridor concentration:Headquarters refurbishment waves in Minato and Chiyoda wards are sustaining premium demand for modular desk systems and executive seating.
Market Restraints
- Steel and aluminum input volatility:Price swings in ferrous metals are compressing margin buffers for domestic frame manufacturers locked into fixed-price municipal contracts.
- Import compliance friction:JIS Z 2801 antimicrobial certification requirements create timeline and testing cost barriers for Southeast Asian suppliers seeking market entry.
- Space-efficient digital storage substitution:Cloud-based document management is eroding demand for vertical filing cabinets in administrative departments, the traditional volume anchor for storage unit producers.
Strategic Opportunities
- Osaka-Kobe manufacturing belt penetration:Underdeveloped refurbishment activity at machinery and pharmaceutical headquarters in western Japan offers whitespace for modular system vendors.
- Sensor-embedded furniture convergence:Integration of occupancy sensors with height-adjustable desks is opening premium pricing tiers for workplace analytics contracts.
- Fukuoka startup ecosystem channel innovation:Direct-to-tenant leasing models through flexible office operators are bypassing traditional general contractor intermediaries.
Industry Challenges
- Ergonomic assessment skill scarcity:Certified industrial health consultants capable of workstation compliance audits under Ministry of Health, Labour and Welfare guidelines remain concentrated in Tokyo and Osaka.
- Legacy system integration complexity:Smart furniture IoT platforms face interoperability friction with incumbent building management systems at aging central Tokyo office stock.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Japan Office Furniture Market |
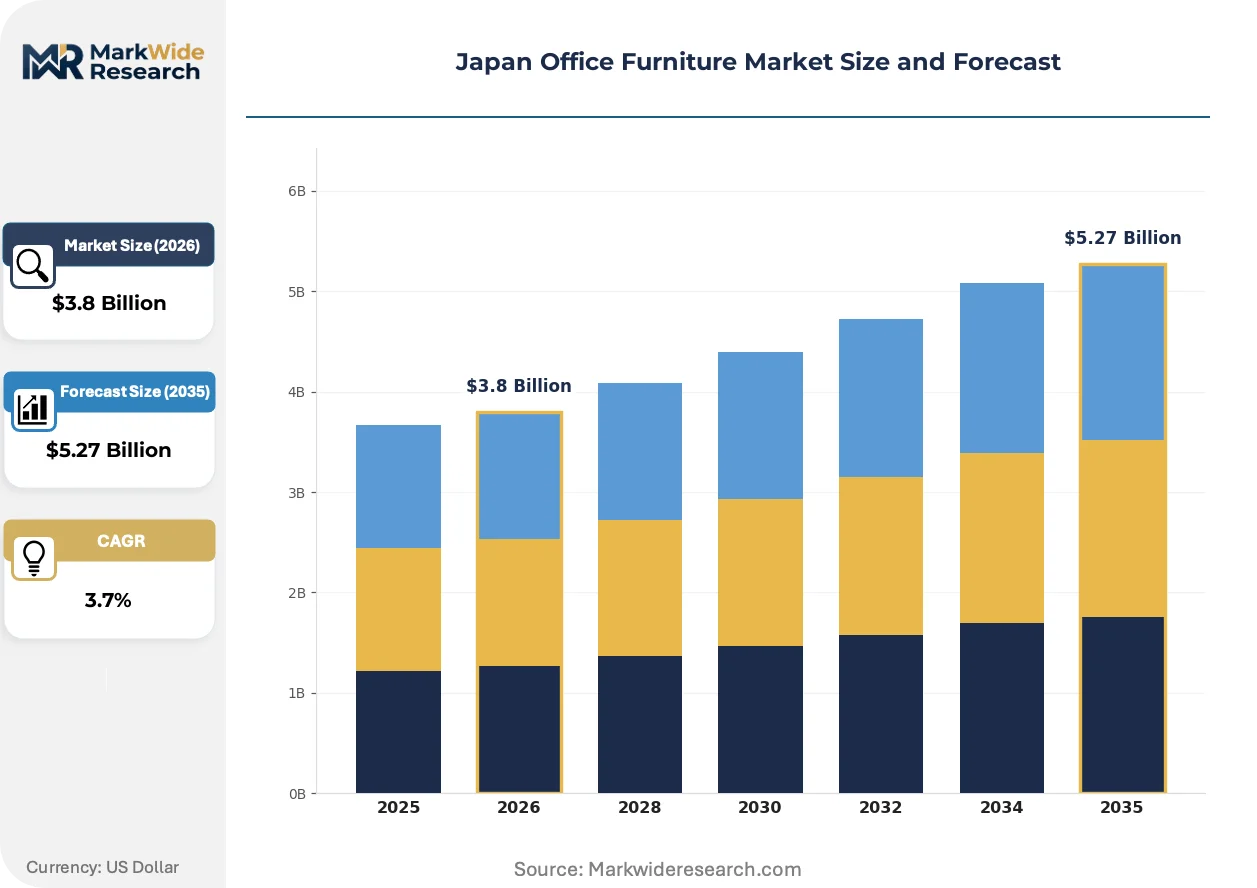
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.27 Billion |
| CAGR (2026 – 2036) | 3.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Tables, Storage Units End User: Corporates, SMEs, Educational Institutions, Government Offices Material: Wood, Metal, Plastic, Glass Distribution Channel: Online Retail, Offline Retail, Direct Sales, Wholesalers |
| Companies Covered | Okamura Corporation, Kokuyo Co., Ltd., Itoki Corporation, Uchida Yoko Co., Ltd., Plus Corporation, Kurogane, Askul Corporation, Steelcase Inc., Herman Miller Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Japan Office Furniture Market Shifts & Advancements
Workplace technology integration is redefining furniture from passive infrastructure to active data collection nodes, while regulatory pressure on material transparency and buyer fragmentation are simultaneously reshaping competitive requirements.
Sensor-enabled desks and chairs are absorbing real-time occupancy and posture data streams, transmitting analytics to facility management software. Corporate real estate teams at financial services firms are piloting these systems fastest, treating furniture as distributed sensor networks rather than depreciating assets. This capability expansion is absorbing budget share from traditional IT infrastructure categories as workplace analytics contracts bundle hardware and software procurement.
METI's building material circularity guidelines are tightening disclosure requirements for recycled content ratios and end-of-life recyclability. Domestic manufacturers with in-house metal recycling streams are securing preferential access to public sector tenders. Premium seating and modular systems face the steepest compliance ramps as corporate sustainability officers demand third-party verified lifecycle documentation.
Fragmented buying authority is compressing sales cycles and elevating direct-to-occupant digital channels. Departmental managers at technology firms are sourcing task chairs through e-procurement platforms with 48-hour delivery guarantees, bypassing traditional six-month capital expenditure approvals. This pattern is most pronounced in Fukuoka and Sapporo satellite offices where centralized facilities oversight has weakened.
Japan Office Furniture Market Segmentation
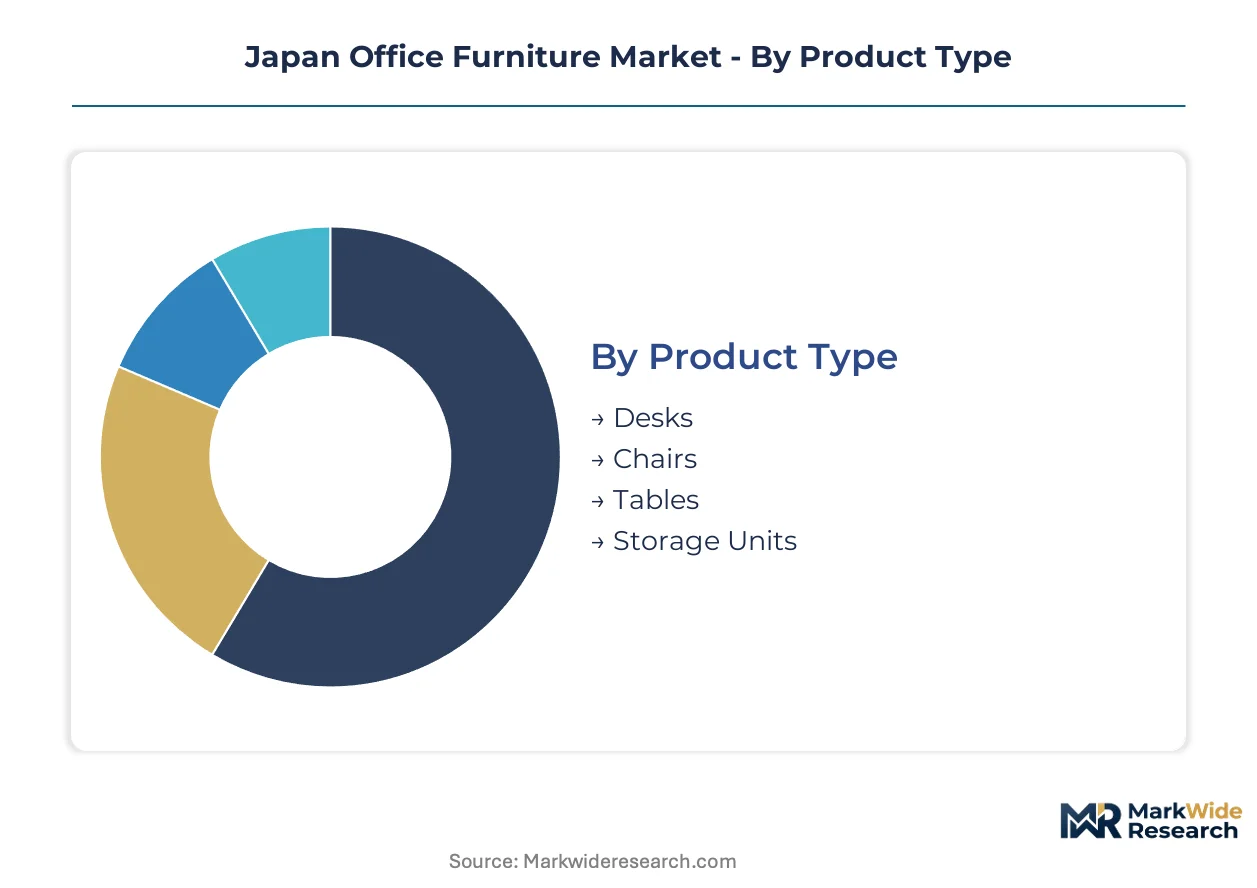
Segmentation in Japan's office furniture market exposes divergent procurement rhythms across buyer types and material specifications. Understanding these fault lines reveals where METI compliance costs bite deepest and where hybrid work models are fragmenting traditional purchasing authority.
Product Type:
Supply concentration in seating and desk manufacturing dominates the revenue landscape, with domestic producers anchoring premium tier availability through JIS-certified production lines.
- Chairs:Ergonomic task seating with adjustable lumbar support and pneumatic height mechanisms absorbs the largest procurement budgets. Tokyo technology firms and financial services headquarters in Minato Ward are accelerating replacement cycles as hybrid schedules demand home-office quality at corporate desks.
- Desks:Height-adjustable workstations and modular benching systems command premium positioning. Corporate real estate teams at headquarters refurbishment projects in Chiyoda Ward specify these for densification and flexibility compliance.
- Tables:Conference and collaborative surfaces with integrated power and data modules serve meeting room renovations. Demand concentrates in co-working operator fit-outs across Fukuoka's startup corridor.
- Storage Units:Vertical filing cabinets and mobile pedestals face compression from cloud-based document management. However, densification in legacy Tokyo office stock sustains demand for space-efficient personal storage at workstations.
Today's leader: Chairs. Tomorrow's challenger: Desks.
End User:
Cost tier stratification separates capital-rich headquarters buyers from price-sensitive institutional purchasers, with compliance requirements widening the gap.
- Corporates:Large enterprises with dedicated facility management functions procure through multi-year framework agreements. Premium ergonomic specifications and smart furniture pilots dominate spending at technology and financial services headquarters in Greater Tokyo.
- SMEs:Small and medium enterprises purchase through direct-to-tenant digital channels with compressed lead times. Fukuoka and Sapporo satellite offices source task chairs through e-procurement platforms bypassing traditional contractor intermediaries.
- Educational Institutions:Universities and vocational schools face constrained capital budgets. Procurement prioritizes durability metrics over ergonomic adjustability, with bulk purchases concentrated in municipal tender cycles.
- Government Offices:Public sector buyers enforce METI circular economy guidelines through mandatory recycled content verification. Domestic manufacturers with in-house metal recycling streams secure preferential tender access.
Corporate buyers set specification standards. Government procurement is rewriting compliance rules.
Material:
Volume distribution favors metal and wood specifications, with sustainability disclosure requirements reshaping supplier qualification.
- Metal:Steel and aluminum frames dominate task chair bases and desk leg assemblies. Recycled content ratios are becoming gatekeeping criteria under METI building material circularity guidelines.
- Wood:Engineered wood panels and solid timber surfaces lead executive desk and conference table specifications. Formaldehyde emission limits under JIS standards elevate compliance costs for imported veneer products.
- Plastic:Polypropylene and nylon components serve seating shells and castor housings. Cost positioning supports SME and educational price tiers.
- Glass:Tempered glass surfaces occupy niche premium positioning for executive workstations and reception furniture. Limited volume reflects fragility concerns in high-traffic commercial environments.
Metal and wood anchor current procurement. Recycled metal content is climbing the fastest.
Distribution Channel:
Customer type fragmentation is compressing traditional sales cycles and elevating channel diversification imperatives for incumbent suppliers.
- Direct Sales:Manufacturer-led specification and installation services capture premium corporate and government contracts. JIS certification support and lifecycle documentation provision create switching costs.
- Offline Retail:Specialty furniture showrooms and general contractor partnerships serve refurbishment project channels. Concentrated in Osaka-Kobe manufacturing belt proximity for western Japan penetration.
- Online Retail:E-procurement platforms with rapid fulfillment guarantees are gaining share among departmental managers at technology firms. Forty-eight-hour delivery promises bypass capital expenditure approval bottlenecks.
- Wholesalers:Intermediary networks distribute standardized products to regional SME and educational buyers. Margin pressure from direct digital channels is eroding traditional volume roles.
Direct sales still command premium value. Online retail is forcing channel restructuring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory-arbitrage dynamics are minimal in Japan's office furniture sector given METI's stringent JIS standards and domestic manufacturing heritage, yet sub-regional demand patterns reveal distinct procurement rhythms across the archipelago's commercial centers.
Kanto/Tokyo
Corporate headquarters refurbishment in Minato and Chiyoda wards drives premium seating and modular desk procurement at technology and financial services firms. METI's circular economy guidelines for building materials reshape public sector tender specifications toward verified recycled metal content. Greater Tokyo's commercial corridor concentrates demand for ergonomic task chairs and height-adjustable workstations as hybrid work models persist.
Kansai/Osaka
Machinery and pharmaceutical headquarters in the Osaka-Kobe manufacturing belt generate underdeveloped refurbishment activity relative to capital investment scale. Industrial Safety and Health Act provisions enforced by the Ministry of Health, Labour and Welfare mandate adjustable seating compliance for prolonged computer use. Modular system vendors face whitespace opportunity as western Japan corporate real estate teams lag Tokyo in workspace densification adoption.
Chubu/Nagoya
Automotive supplier offices and industrial equipment headquarters sustain mid-tier procurement volumes for durable task seating and standardized desk systems. JIS Z 2801 antimicrobial certification requirements elevate compliance costs for imported products while securing preferential access for domestic manufacturers. Nagoya's automotive engineering culture prioritizes durability metrics over smart furniture pilot programs prevalent in Tokyo technology firms.
Kyushu
Fukuoka's startup ecosystem fragments procurement authority through direct-to-tenant leasing models at flexible office operators. Departmental managers source task chairs through e-procurement platforms with compressed delivery timelines, bypassing traditional general contractor intermediaries. Satellite office expansion at technology firms accelerates demand for plug-and-play modularity over capital-intensive built-in systems.
Hokkaido
Sapporo's regional corporate functions and government administrative offices maintain conservative replacement cycles for aging furniture inventories. Municipal tender processes prioritize durability specifications and JIS structural safety compliance over ergonomic adjustability innovations. Limited certified industrial health consultant availability constrains workstation compliance audit penetration outside major metropolitan corridors.
Japan Office Furniture Market Competitive Landscape
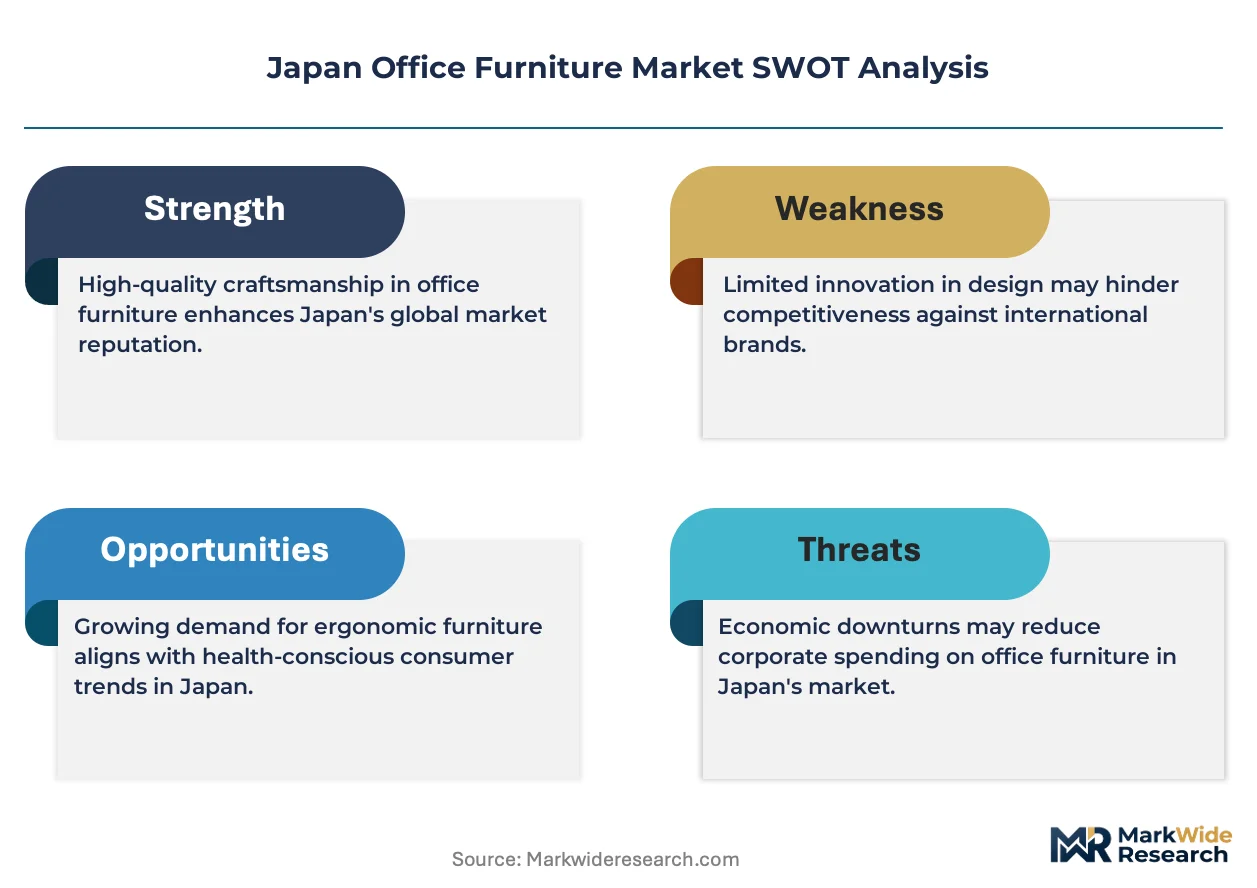
Portfolio diversification dominates the current landscape as incumbent manufacturers extend from core seating and desk production into sensor-enabled furniture and workplace analytics software. The vendor base clusters around three strategic archetypes: integrated domestic manufacturers with in-house metal recycling streams, specialized modular system fabricators, and global ergonomic brands navigating JIS certification barriers. M&A activity remains subdued relative to organic capacity expansion in premium task chair segments. Strategic partnerships between furniture producers and building management system vendors accelerate smart furniture interoperability development.
Among domestic integrated manufacturers, Okamura Corporation and Kokuyo Co., Ltd. exemplify scale-driven archetypes with captive supply chain control over JIS-certified production lines. Itoki Corporation occupies a position within the specialized modular system tier, representing flexibility-focused competitive positioning for hybrid office layouts. These three entities anchor the premium-tier supply structure while global participants Steelcase Inc. and Herman Miller Inc. navigate antimicrobial certification timelines to access public sector procurement channels.
| Leading Market Players |
|---|
| Okamura Corporation |
| Kokuyo Co., Ltd. |
| Itoki Corporation |
| Uchida Yoko Co., Ltd. |
| Plus Corporation |
| Kurogane |
| Askul Corporation |
| Steelcase Inc. |
| Herman Miller Inc. |
| Others |
Supply & Pricing Matrix
Government procurement concentration under METI circular economy guidelines anchors Japan's office furniture pricing around certification-tiered structures. Corporate buyers in Greater Tokyo absorb premium markups for JIS Z 2801 antimicrobial compliance while municipal contracts enforce fixed-price durability benchmarks.
Pricing Analysis
Distributor margins on standardized task chairs compress as direct-to-tenant digital channels gain share among Fukuoka technology firms. Pricing stratifies across premium certified, standard domestic, and economy import tiers, with JIS emission-grade verification and recycled metal content ratios as primary differentiation drivers. Cost compression in steel-frame seating intensifies as ferrous input volatility erodes manufacturer buffers. SMEs and educational institutions exhibit highest price sensitivity, while government offices accept certified-premium positioning for lifecycle documentation compliance.
Supply Chain Analysis
Single-source vulnerability sits with Chinese steel coil and Southeast Asian polypropylene resin suppliers serving domestic frame and seating shell production. Manufacturing draws from Japan, China, and South Korea for precision metal components, engineered wood panels, and sensor module assembly. Tariff exposure on aluminum extrusions from regional trade agreement renegotiations threatens margin structures at Osaka-Kobe fabricators. Distribution runs through manufacturer-direct specification teams for premium corporate contracts, general contractor partnerships for refurbishment projects, and emergent e-procurement platforms for compressed-cycle departmental purchases.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Japan's office furniture market functions as a stable compounder, with METI regulatory tightening on material circularity creating sustained replacement demand across public and corporate procurement channels.
For Market Incumbents: Deepen captive metal recycling capabilities to secure preferential government tender access as recycled content verification becomes mandatory. Expand certified industrial health consultant networks beyond Tokyo-Osaka corridors to capture workstation compliance audit demand in Nagoya and Sapporo satellite offices. Sensor-enabled furniture R&D partnerships with building management system vendors address interoperability friction threatening smart furniture adoption at aging central Tokyo stock. For New Entrants and Emerging Players: Enter via modular workspace system specialization targeting the underdeveloped Osaka-Kobe pharmaceutical and machinery headquarters refurbishment market. Fukuoka's startup ecosystem offers whitespace through direct-to-tenant leasing partnerships with flexible office operators bypassing traditional general contractor channels. Position on 48-hour fulfillment guarantees through e-procurement platform integration rather than capital-intensive JIS certification infrastructure. For Investors and Strategic Acquirers: Domestic building materials conglomerates seeking workplace technology diversification are the most active acquirer in this space. Target mid-cap modular system fabricators with established western Japan distribution and in-house metal recycling streams for five-to-ten year holding windows. Monitor METI building energy code revision timelines as inflection indicators for furniture-integrated power and data system demand acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Product Launch | Occupancy analytics integration opens premium pricing tiers at Tokyo financial services headquarters. |
| Backward Integration into Metal Recycling | In-house recycled content streams secure preferential METI circular economy tender access. |
| Osaka-Kobe Distribution Partnership | Western Japan machinery and pharmaceutical refurbishment whitespace awaits modular system penetration. |
| JIS Z 2801 Certification Investment | Antimicrobial compliance creates timeline barriers for Southeast Asian import competition. |
| Workplace Analytics Software Development | Sensor data platform bundling absorbs budget share from traditional IT infrastructure categories. |
Research Methodology
Coverage spans Kanto, Kansai, Chubu, Kyushu, and Hokkaido, with primary inputs from each. Facility management directors at technology and financial services headquarters, procurement officers at municipal government offices, industrial health consultants certified under Ministry of Health, Labour and Welfare guidelines, and modular system vendor sales executives provided structured interview data. Secondary validation drew from METI building material circularity guideline publications, JIS standard revision documentation, municipal tender award databases, and corporate real estate trade association reports. Bottom-up shipment estimates triangulated against top-down construction permit and office refurbishment expenditure flows.
Granularity-level modeling addressed product type, end user category, material specification, and distribution channel dimensions across the projection horizon. Deployment scale differentiated headquarters refurbishment from satellite office fit-out patterns. CAGRs were derived from segment-level volume trajectories calibrated to construction cycle timing and regulatory compliance deadline clustering. Hybrid work normalization persistence and METI guideline implementation pace served as scenario-weighted forecast inputs.
Inputs from government procurement databases and corporate sustainability disclosure filings were available through the study window; gaps in real-time e-procurement platform transaction data introduce uncertainty bands around SME and departmental direct-buy estimates. Forecasts reflect documented assumptions regarding regulatory timeline adherence and steel input price stabilization. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Standing Desk Market
Office Furniture
Office Furniture Edgebands Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Standing Desk Balance Boards Market
Office Furniture
Russia Office Furniture Market
Office Furniture
Home Office Desk Market
Office Furniture
Office Chairs Market
Office Furniture
Institutional Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
Europe Home Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Home Office Furniture Market
Office Furniture
France Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Desk Chairs Market