
 Europe Home Office Furniture Market | 2026-2036
Europe Home Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Home Office Furniture Market Foresight
Market Context
Ergonomic digital integration is rewriting how European home office furniture is engineered, with sensor-enabled desks and app-connected seating now embedded in premium product lines. Vitra International AG leverages its Basel design heritage to dominate high-end ergonomic seating across German and Swiss metropolitan markets. Steelcase sustains R&D intensity in adaptive workstation systems that respond to biometric feedback. Sedus Stoll AG anchors its position through captive manufacturing of height-adjustable frames at its Dogern facility.
Technical Definition and Segment Structure
Europe home office furniture encompasses self-contained workstations, seating, and storage systems engineered for residential deployment, typically featuring load-rated desk surfaces of 80-120 kg, gas-lift cylinder mechanisms rated to 150,000 cycles, and footprint optimization below 2.5 square meters for urban apartment compatibility. Wood material grades command durable margin pools in Nordic markets where FSC-certified oak and birch carry buyer premiums, while metal frames represent the fastest-growing structural category as consumers prioritize longevity over first-cost savings. Modern style segments lead volume in Netherlands and Denmark, though minimalist aesthetics are displacing traditional forms among freelancer end users in Portugal and Spain.
Regulatory Frame and Outlook
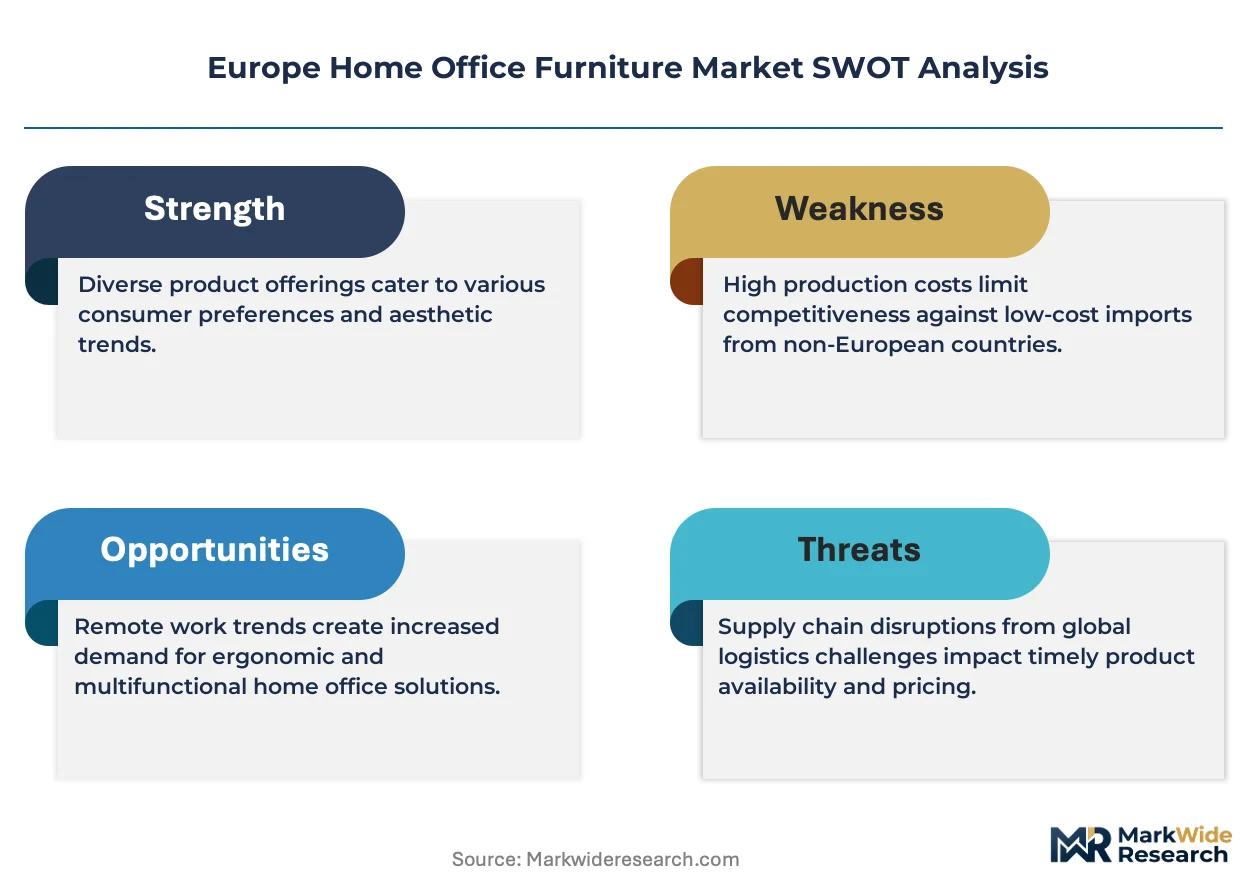
ECHA REACH restrictions on formaldehyde emissions and flame retardants directly shape upholstery chemistry and composite board specifications across EU manufacturing bases. The EU Green Deal's Ecodesign for Sustainable Products Regulation forces modular construction and end-of-life recyclability into product development roadmaps. CE marking requirements under the Construction Products Regulation govern structural stability claims for wall-mounted storage and shelving units. Stakeholders must monitor how CSRD disclosure mandates will expose supply chain carbon intensity to institutional procurement departments.
Market Dynamics
Hybrid work permanence has compressed furniture replacement cycles across European metropolitan areas, with technology sector employees demanding ergonomic upgrades that mirror corporate office specifications. The EU Green Deal's Ecodesign for Sustainable Products Regulation is forcing manufacturers to reengineer supply chains toward circular material flows and modular end-of-life disassembly.
Growth Catalysts
- REACH compliance upgrades:ECHA restrictions on formaldehyde emissions and flame retardants are accelerating upholstery chemistry innovation, creating competitive advantage for early reformulators.
- Sensor-enabled workstations:Biometric-responsive desks and app-connected seating are penetrating premium residential segments as remote-first employers subsidize home office stipends.
- Berlin-Munich corridor density:German startup and creative agency clusters are generating concentrated demand for space-optimized furniture below 2.5 square meter footprints.
Market Restraints
- FSC-certified timber scarcity:Nordic oak and birch supply constraints are inflating input costs for manufacturers targeting sustainability premiums.
- Gas-lift cylinder import dependence:Asian component sourcing creates vulnerability in height-adjustable frame production, particularly at Dogern-scale captive facilities.
- Wall-mounted storage CE marking:Construction Products Regulation structural stability claims require extended testing timelines, delaying product launches.
Strategic Opportunities
- Portuguese freelancer adoption:Minimalist aesthetic preference displacement in Iberian markets offers entry points for modern-style specialists.
- CSRD disclosure readiness:Supply chain carbon intensity transparency mandates are creating procurement advantages for manufacturers with verified Scope 3 data.
- Biometric-AI convergence:Adaptive workstation systems integrating posture sensors with predictive health analytics are opening wellness-positioned product tiers.
Industry Challenges
- Circular design engineering capacity:Modular construction and recyclability expertise shortages are constraining product development velocity under Ecodesign deadlines.
- Legacy inventory obsolescence:Traditional form factor stockpiles face accelerated value erosion as minimalist aesthetics displace conventional designs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Home Office Furniture Market |
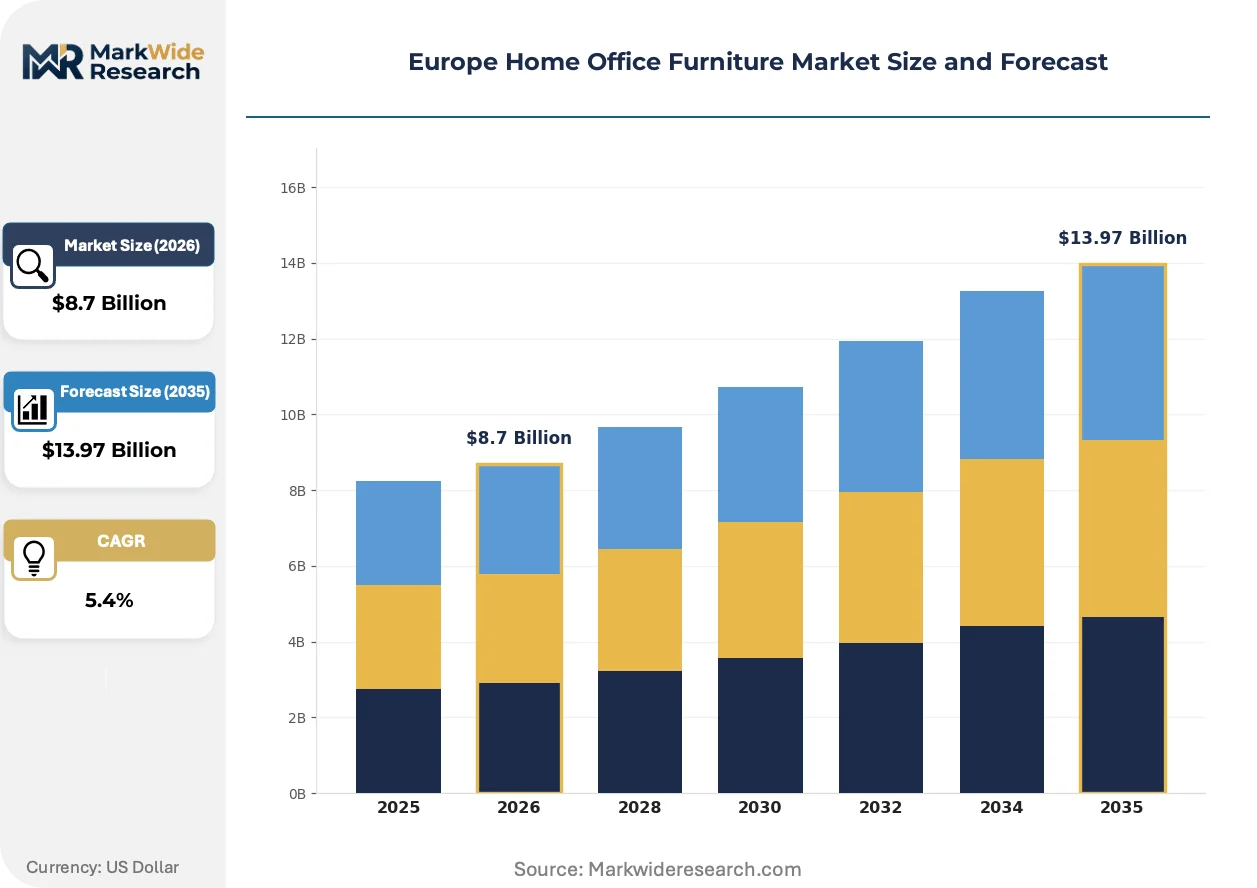
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $13.97 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Storage Units, Bookshelves Material: Wood, Metal, Glass, Plastic Style: Modern, Traditional, Minimalist, Industrial End User: Freelancers, Remote Workers, Students, Small Businesses |
| Companies Covered | Vitra International AG, Steelcase, Sedus Stoll AG, BoConcept, Koninklijke Ahrend BV, Kinnarps AB, Herman Miller Europe, Poltrona Frau, Nowy Styl, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Home Office Furniture Market Shifts & Advancements
Sensor-embedded furniture and circular material mandates are converging to redefine how European manufacturers engineer for residential deployment. Product development cycles are compressing as sustainability certification requirements and digital integration demands simultaneously intensify.
Biometric-responsive workstation systems are collapsing the functional boundary between residential and corporate office environments. Remote-first technology employers in Germany and the Netherlands are subsidizing these upgrades at accelerating rates. The result is collapsing price premiums that previously separated enterprise contract furniture from consumer retail tiers.
Ecodesign for Sustainable Products Regulation mandates are forcing modular construction and end-of-life recyclability into every product roadmap. Manufacturers must now certify disassembly pathways and material recovery rates before market entry. German and Swiss producers with captive component manufacturing are responding fastest, while import-dependent competitors face compliance timeline disadvantages.
Employer-subsidized home office stipends are fragmenting traditional retail channels across European metropolitan markets. Direct-to-employee platforms and B2B procurement portals are displacing conventional furniture retail for ergonomic seating and height-adjustable desks. This channel rotation is most visible in Denmark and the Netherlands, where freelancer density and corporate remote-work policies overlap most densely.
Europe Home Office Furniture Market Segmentation
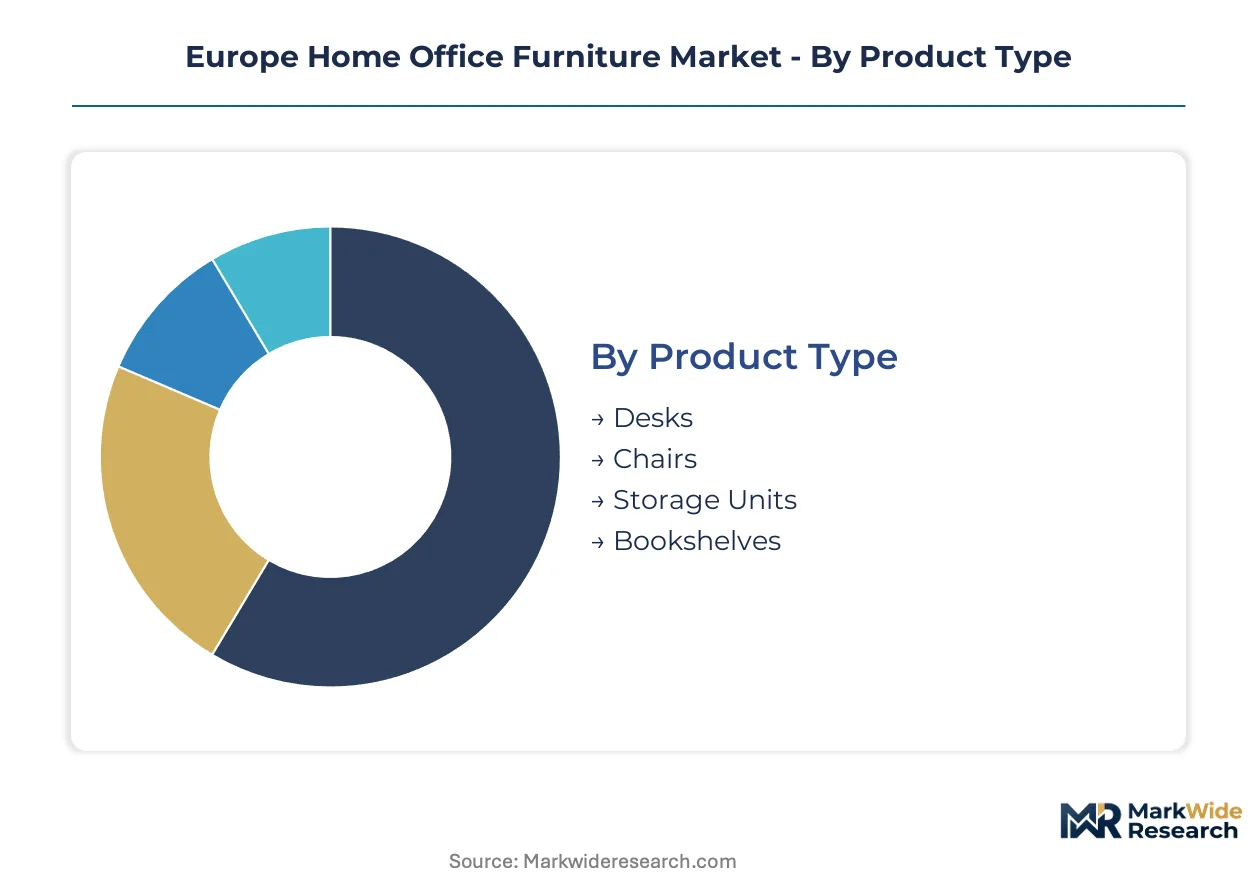
European home office furniture segmentation reveals distinct replacement rhythms across product categories, with hybrid work permanence compressing refresh cycles for seating and workstations while storage solutions turn over more slowly. Material and style preferences diverge sharply across national markets, creating tiered opportunity structures for specialized manufacturers.
Product Type:
Chairs and desks exhibit the shortest replacement cycles as ergonomic awareness intensifies, while storage units and bookshelves demonstrate extended lifespans tied to residential tenancy patterns rather than workplace policy shifts.
- Desks:Height-adjustable frames with gas-lift mechanisms rated to 150,000 cycles dominate specification sheets. Demand concentrates in the Berlin-Munich corridor where remote-first startups subsidize workstation upgrades through employee stipends.
- Chairs:Biometric-responsive seating with posture sensors and app connectivity commands premium positioning. Dutch and Danish freelancer clusters are driving fastest adoption of adaptive lumbar support systems.
- Storage Units:Modular wall-mounted systems face extended CE marking timelines under Construction Products Regulation stability requirements. German captive manufacturers at Dogern-scale facilities maintain compliance advantages.
- Bookshelves:Traditional form factors face accelerated obsolescence as minimalist aesthetics displace conventional designs in Iberian markets.
Chairs anchor the volume base while desks gain share at the steepest rate.
Material:
Cost tier stratification separates premium certified timber from commodity metal and plastic alternatives, with glass occupying a narrow aesthetic niche.
- Wood:FSC-certified oak and birch from Nordic sources carry buyer premiums in sustainability-positioned segments. Supply constraints are inflating input costs for manufacturers targeting Ecodesign compliance.
- Metal:Structural frames represent the fastest-expanding category as consumers prioritize longevity over first-cost savings. German and Swiss producers with captive component manufacturing capture margin expansion.
- Glass:Tempered surface panels occupy premium aesthetic tiers with limited volume penetration.
- Plastic:Recycled-content polymers face REACH formaldehyde and flame-retardant reformulation pressures.
Metal frames anchor the volume base while wood gains share at the steepest rate.
Style:
Application context determines style selection, with corporate-remote aesthetics diverging from residential-native preferences.
- Modern:Clean lines and integrated cable management dominate Netherlands and Denmark volume. Freelancer adoption in Portugal and Spain is accelerating displacement of traditional forms.
- Minimalist:Space-optimized footprints below 2.5 square meters address urban apartment constraints. Berlin and Munich startup density generates concentrated demand for this aesthetic tier.
- Traditional:Ornate detailing and hardwood finishes face inventory obsolescence as hybrid work policies reshape residential office specifications.
- Industrial:Exposed metal framing and reclaimed materials occupy narrow specialist niches with limited scaling potential.
Modern style anchors the volume base while minimalist gains share at the steepest rate.
End User:
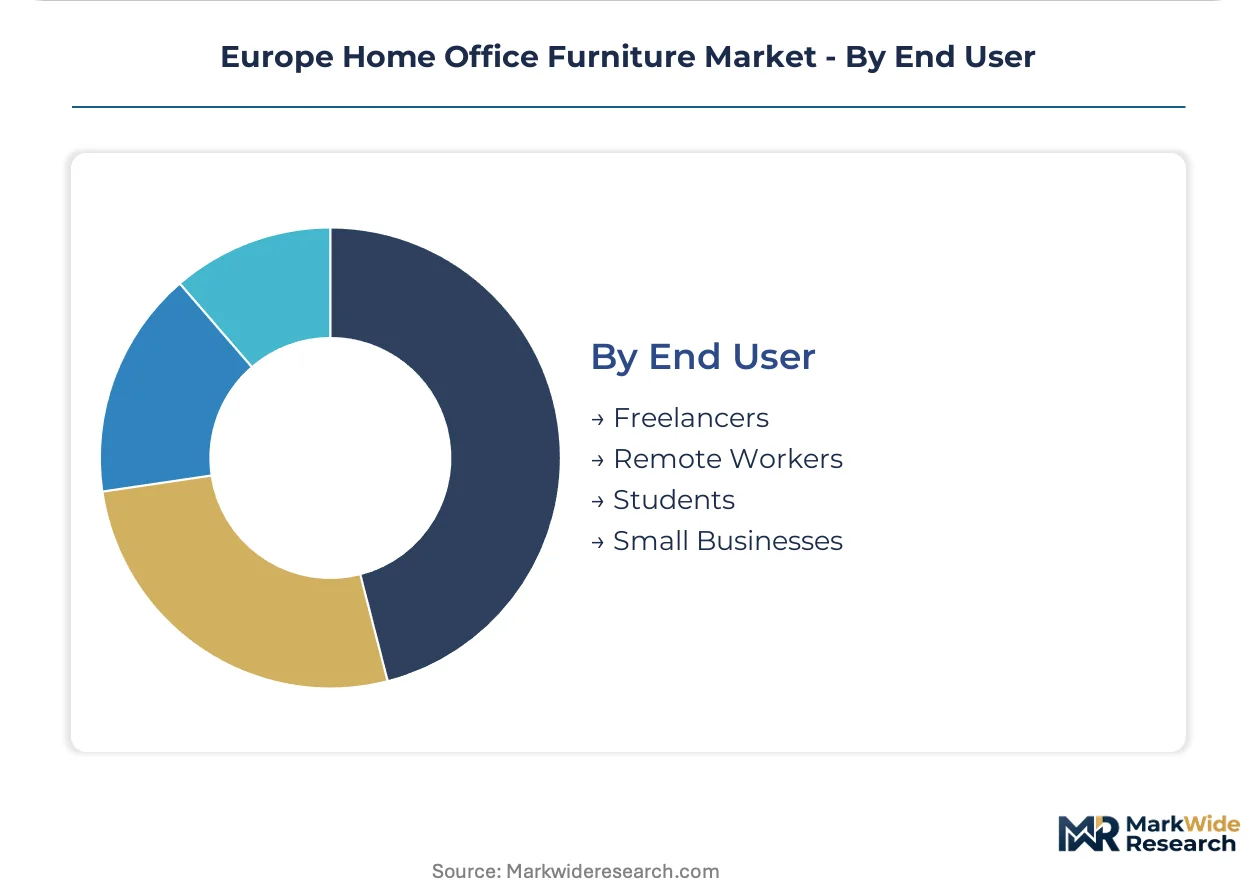
Customer type segmentation maps directly to subsidy eligibility and procurement channel preferences.
- Remote Workers:Employer-subsidized stipends enable premium ergonomic specifications matching corporate office standards. Direct-to-employee platforms are displacing conventional retail in Denmark and the Netherlands.
- Freelancers:Self-funded purchases prioritize space-optimized solutions for urban apartments. Portuguese and Spanish freelancer clusters are driving minimalist aesthetic displacement fastest.
- Students:Price-sensitive segment with compressed specification requirements and extended replacement cycles.
- Small Businesses:B2B procurement portal adoption is fragmenting traditional channel structures across metropolitan markets.
Remote workers anchor the volume base while freelancers gain share at the steepest rate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Export-import dynamics across European home office furniture reveal German and Swiss producers commanding premium positioning through captive manufacturing, while import-dependent markets in Southern Europe absorb cost pressures from Asian component sourcing.
Germany
Berlin and Munich startup density drives concentrated demand for space-optimized workstations below 2.5 square meter footprints. Ecodesign for Sustainable Products Regulation mandates force modular construction into product roadmaps. The Dogern manufacturing cluster anchors height-adjustable frame production with gas-lift cylinder integration.
Netherlands
Amsterdam and Rotterdam freelancer clusters accelerate adoption of biometric-responsive seating with app connectivity. CSRD disclosure mandates push procurement departments toward suppliers with verified Scope 3 carbon data. Eindhoven's design heritage supports modern aesthetic dominance in clean-line furniture specifications.
Denmark
Copenhagen's remote-first employer policies subsidize premium ergonomic upgrades through direct-to-employee platforms. REACH restrictions on formaldehyde emissions reshape upholstery chemistry requirements across Nordic sourcing. Aarhus manufacturing maintains FSC-certified timber advantages despite Nordic oak supply constraints.
Spain
Barcelona and Madrid freelancer adoption displaces traditional furniture forms with minimalist aesthetics. CE marking under Construction Products Regulation delays wall-mounted storage launches. Valencia's import-dependent assembly faces vulnerability from Asian gas-lift cylinder sourcing disruptions.
United Kingdom
London's hybrid work permanence compresses ergonomic seating replacement cycles among technology sector employees. Post-Brexit regulatory divergence from EU Ecodesign timelines creates compliance complexity for cross-border suppliers. Manchester distribution hubs fragment traditional retail channels through B2B procurement portal growth.
Europe Home Office Furniture Market Competitive Landscape
On the supply side, the industry is consolidating around design heritage specialists with captive manufacturing capabilities and modular engineering expertise. Three archetypes dominate: Basel-design heritage houses with ergonomic seating specialization, Scandinavian modernist fabricators with sustainability certification depth, and Central European metal-frame producers with vertical component control. Competitive moves center on circular design engineering capacity acquisition and biometric-AI workstation integration partnerships.
Among Swiss and German heritage manufacturers, Vitra International AG exemplifies design-origin positioning anchored in Basel metropolitan influence. Steelcase represents the adaptive workstation systems tier with biometric feedback integration. Sedus Stoll AG occupies the captive manufacturing archetype through its Dogern-scale facility control over height-adjustable frame production. These three entities collectively illustrate how supply-side concentration around circular material expertise and sensor-enabled engineering is reshaping competitive positioning across premium residential segments.
| Leading Market Players |
|---|
| Vitra International AG |
| Steelcase |
| Sedus Stoll AG |
| BoConcept |
| Koninklijke Ahrend BV |
| Kinnarps AB |
| Herman Miller Europe |
| Poltrona Frau |
| Nowy Styl |
| Others |
Supply & Pricing Matrix
The Dogern manufacturing cluster anchors height-adjustable frame production for the European market, with captive gas-lift cylinder integration conferring pricing power that import-dependent competitors cannot match. This supply concentration enables German and Swiss producers to command premium positioning while Southern European assemblers absorb cost volatility from Asian component sourcing.
Pricing Analysis
Sensor-enabled workstation pricing gaps separate biometric-responsive premium tiers from basic height-adjustable frames and legacy fixed-height alternatives. Three-tier pricing structure across premium, standard, and economy levels reflects differentiation by certification grade and ergonomic feature depth. Cost compression in the standard tier is intensifying because REACH compliance upgrades force upholstery chemistry reformulation. Freelancer segments in Iberian markets exhibit highest price sensitivity, while employer-subsidized remote workers in Germany and the Netherlands show lowest sensitivity to premium positioning.
Supply Chain Analysis
Tariff exposure between Asian component suppliers and European assembly facilities dominates supply chain risk planning for height-adjustable frame producers. Manufacturing concentrates in Germany, Switzerland, and Poland, with final assembly drawing from Chinese and Vietnamese gas-lift cylinder sources. Raw material dependencies center on Nordic FSC-certified timber, steel structural tubing, and polymer upholstery components. Single-source vulnerability in gas-lift mechanism supply creates production continuity exposure. Distribution runs through direct-to-employee platforms and B2B procurement portals that displace conventional retail channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Europe home office furniture sits in early-cycle expansion as employer-subsidized stipends accelerate ergonomic upgrade adoption beyond traditional replacement rhythms. Hybrid work permanence sustains this tailwind by collapsing the boundary between residential and corporate office specifications.
For Market Incumbents: Pre-empt circular design engineering shortages by acquiring modular construction expertise ahead of Ecodesign for Sustainable Products Regulation deadlines. Defend margin position through backward integration into FSC-certified timber sourcing as Nordic oak supply constraints deepen. Channel control through direct-to-employee platform investments protects against retail fragmentation. For New Entrants and Emerging Players: Establish a beachhead in Portuguese and Spanish freelancer segments where minimalist aesthetic displacement creates white-space opportunity. Target biometric-AI convergence partnerships with wellness technology developers to bypass capital-intensive manufacturing scale requirements. Go-to-market through design-forward digital native channels that bypass incumbent retail relationships. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors captive manufacturing specialists with sensor-integration partnerships over pure design houses. Five-to-ten year viability hinges on circular material certification depth and Scope 3 carbon data transparency. Acquisition target archetype: Central European metal-frame producers with vertical component control and Ecodesign compliance readiness. The signal to watch is CSRD disclosure mandate acceleration driving procurement department supplier consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Enabled Product Line Launch | Biometric-responsive workstations capture employer-subsidized stipend flows in German startup clusters. |
| Backward Integration into Certified Timber | FSC-certified oak sourcing secures margin pools as Nordic supply constraints intensify input cost volatility. |
| Direct-to-Employee Platform Expansion | Bypassing conventional retail channels captures procurement portal growth in Denmark and Netherlands markets. |
| Circular Design Engineering Acquisition | Modular construction expertise addresses Ecodesign for Sustainable Products Regulation compliance timelines. |
| CSRD-Ready Supply Chain Certification | Verified Scope 3 carbon data creates procurement advantages with institutional buyers under disclosure mandates. |
Research Methodology
A standing panel of furniture manufacturing executives, ergonomic product designers, procurement officers at remote-first technology employers, and sustainability certification specialists provided ongoing calibration throughout the study. Primary interviews with these stakeholders combined with secondary validation against EU ECHA regulatory filings, FSC supply chain databases, and customs trade records. Bottom-up demand modeling across end-user segments triangulated with top-down market sizing from production capacity assessments.
Scenario-bracketing framed the analytical approach across the projection horizon, with optimistic, baseline, and conservative paths reflecting hybrid work policy durability and Ecodesign implementation pace. Segmentation dimensions modeled encompassed product type, material grade, style aesthetic, and end-user funding mechanism. CAGRs were derived from replacement cycle compression rates and employer stipend penetration curves. Industry-specific inputs included gas-lift cylinder import dependency ratios and REACH compliance cost pass-through elasticity.
Stress conditions across Nordic timber supply disruption, Asian component tariff escalation, and Ecodesign deadline acceleration were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding hybrid work permanence and regulatory implementation timelines. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
United States Home Office Furniture Market
Office Furniture
Office Seat Cushion Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
Indonesia Office Furniture Market
Office Furniture
Home Office Spending Market
Office Furniture
Home Office Furniture Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Desk Chairs Market
Office Furniture
Home Office Desk Market
Office Furniture
Australia Office Furniture Market
Office Furniture
Standing Desk Market
Office Furniture
Rental Furniture Market
Office Furniture
US Office Furniture Market
Office Furniture
Canada Office Furniture Market
Office Furniture
UAE Office Furniture Market