
 Ergonomic Office Furniture Market | 2026-2036
Ergonomic Office Furniture Market Size, Share, and Industry Trends Forecast 2026-2036
Ergonomic Office Furniture Market Insights
China is reshaping supply dynamics through expanded manufacturing clusters for adjustable desk frames and precision-machined bases. Steelcase leverages vertical integration across North American component fabrication to sustain delivery reliability for large corporate rollouts. Herman Miller differentiates through design-led R&D intensity in task seating biomechanics. Haworth competes on channel control, occupying direct specification relationships with architecture firms that influence enterprise procurement decisions.
Ergonomic office furniture encompasses workstation systems engineered to reduce musculoskeletal strain through adjustable anthropometric parameters such as seat pan depth, lumbar support positioning, and desktop height modulation ranges. These products serve commercial environments where prolonged computer use necessitates configurable interfaces between users and their equipment. The chair segment anchors volume, while sit-stand desks represent the fastest-growing structural category as employers address sedentary behavior liability. Fabric and mesh materials dominate premium seating specifications, whereas metal frames standardize across mid-market modular installations where margin pools concentrate in assembly logistics rather than raw materials.
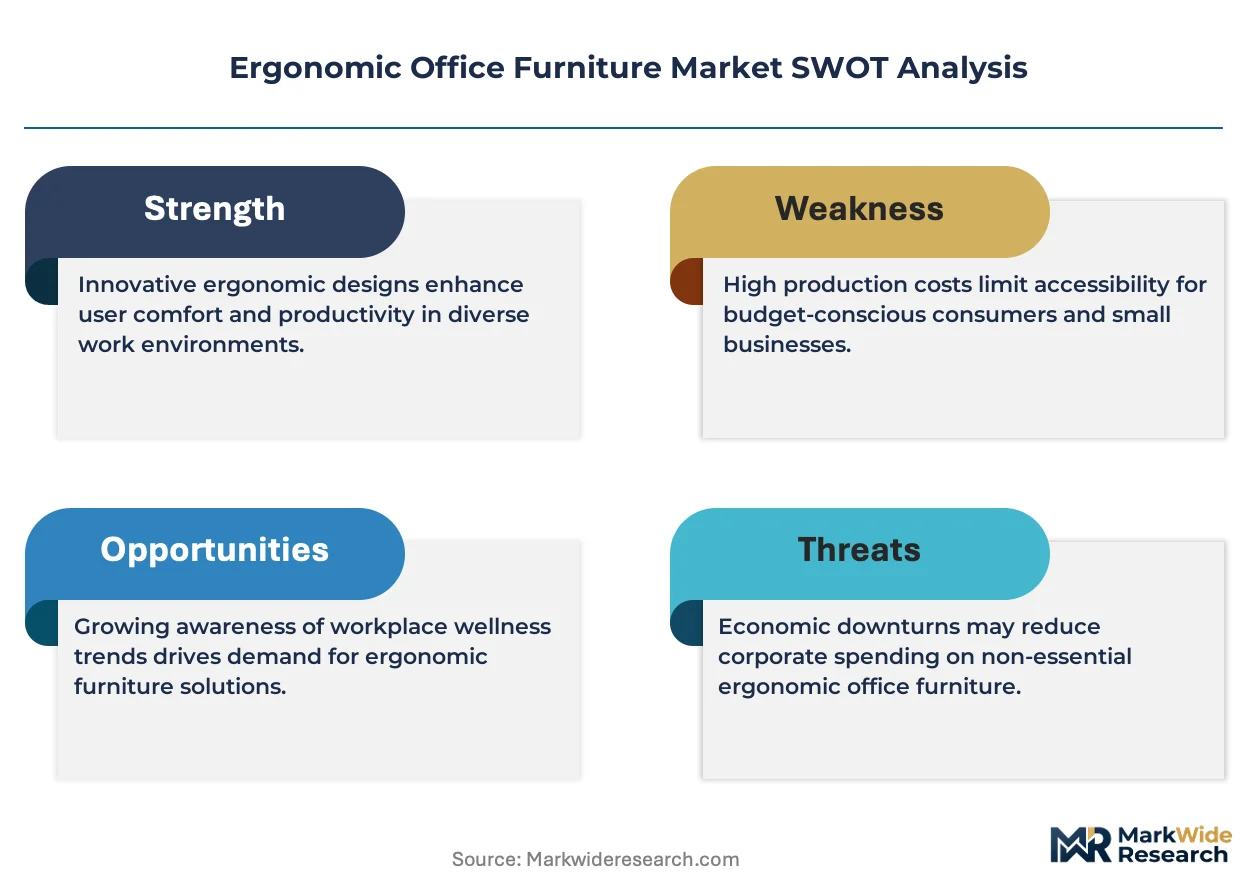
OSHA workplace ergonomics guidelines and the EU F-Gas Regulation on foam blowing agents shape product compliance pathways across the two largest demand blocs. BIFMA level certification and EPA procurement standards further filter market access for seating and desking suppliers targeting government and institutional contracts. Stakeholders must monitor evolving state-level building codes in California and New York that increasingly mandate sit-stand capability in new commercial construction, as these jurisdictions often prefigure broader regulatory diffusion.
Market Dynamics
Workstation upgrade programs across technology sector employers are compressing replacement cycles from ten-year intervals to five-year refresh mandates, forcing manufacturers to reconfigure supply chains for volume surges.
Growth Catalysts
- EU Green Deal compliance mandates:Facility managers in Germany now specify certified ergonomic configurations in new commercial builds, creating specification pull-through for BIFMA level and EPA procurement standard products.
- Sedentary behavior liability frameworks:Employers facing workers compensation exposure for musculoskeletal disorders are accelerating sit-stand desk deployments across computer-intensive departments.
- Precision-machined base manufacturing:Expanded production clusters in China for adjustable desk frames are reducing lead times and enabling faster corporate rollout fulfillment.
Market Restraints
- REACH chemical compliance costs:Upholstered seating manufacturers face reformulation expenses for foam blowing agents under tightened EU F-Gas Regulation standards, compressing margin pools in mid-market segments.
- Steel and aluminum input volatility:Metal frame standardization across modular installations exposes assemblers to commodity price swings that concentrate risk in logistics-dependent operations.
- Biomechanical R&D capability scarcity:Task seating innovation requiring anthropometric parameter engineering sits with a limited pool of design-led specialists, constraining new entrant viability.
Strategic Opportunities
- California and New York building code prefiguration:State-level mandates for sit-stand capability in new commercial construction are establishing regulatory templates likely to diffuse to additional jurisdictions.
- Direct specification channel development:Architecture firm relationships that influence enterprise procurement decisions represent underdeveloped pathways for seating and desking suppliers outside incumbent networks.
- Fabric-to-mesh material convergence:Premium seating specifications are converging on advanced mesh technologies that reduce chemical compliance burdens while improving thermal comfort metrics.
Industry Challenges
- Certification timeline compression:BIFMA level and EPA procurement standard validation processes create bottlenecks for suppliers targeting government and institutional contract windows.
- Legacy workstation integration complexity:Adjustable desk frame retrofits must accommodate existing cable management and power distribution infrastructure, complicating field installation protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Ergonomic Office Furniture Market |
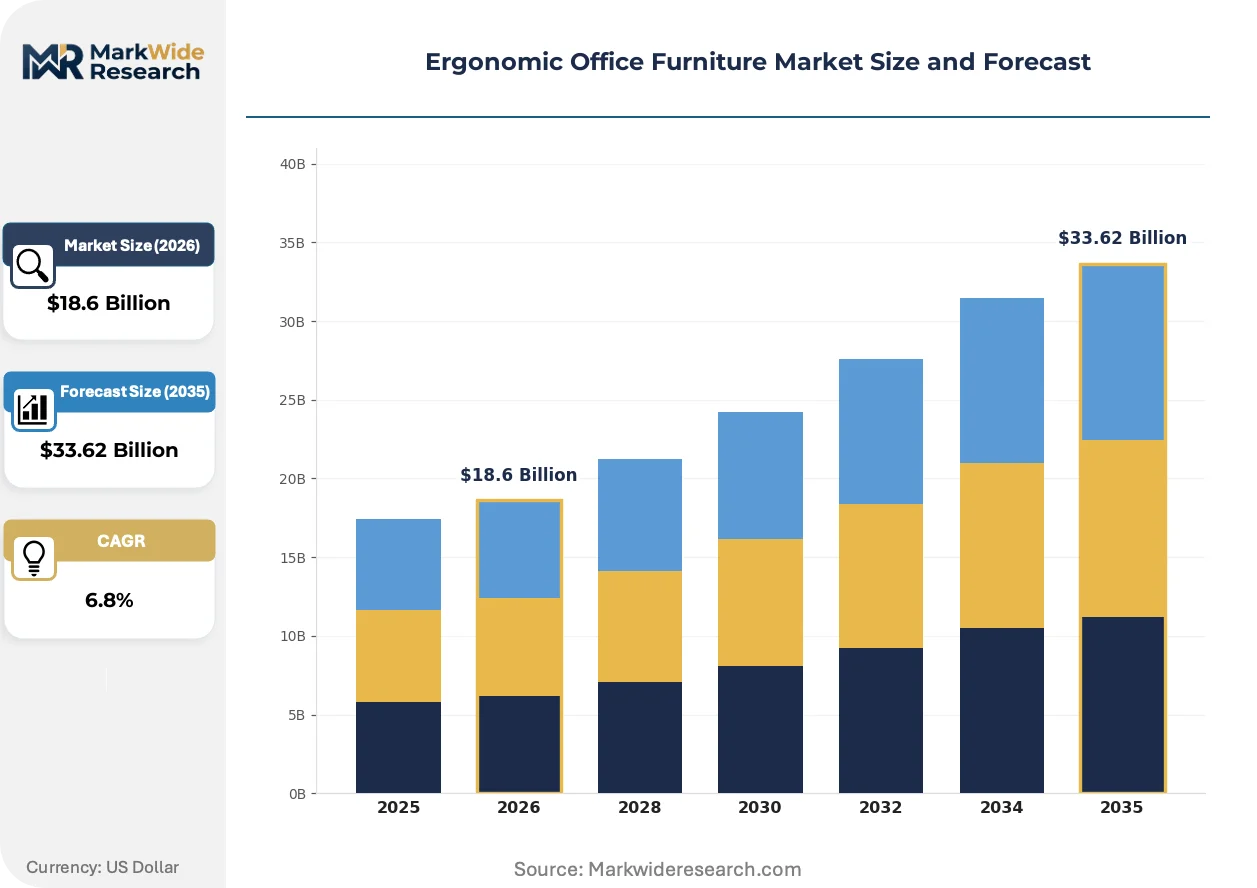
| Market Size in 2026 | $18.6 Billion |
| Market Size in 2035 | $33.62 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Desks, Chairs, Sit-Stand Desks, Accessories End User: Corporates, Small Businesses, Home Offices, Educational Institutions Material: Wood, Metal, Plastic, Fabric Installation Type: Pre-assembled, Modular, Custom, DIY |
| Companies Covered | Okamura, Knoll, Steelcase, Kokuyo, Teknion, Herman Miller, Humanscale, Vitra, Haworth, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Ergonomic Office Furniture Market Trends and Innovations
Biomechanical sensing and automated adjustment mechanisms are collapsing traditional boundaries between passive furniture and active health monitoring systems.
Sensor-embedded task seating is collapsing the distinction between furniture and wellness hardware. Technology sector employers with aggressive workstation upgrade programs are piloting chairs that automatically modulate lumbar support based on real-time posture detection. This convergence is compressing R&D timelines as seating manufacturers recruit software engineering talent previously outside their hiring profiles.
REACH chemical standards and the EU F-Gas Regulation are forcing foam reformulation across upholstered seating supply chains. Manufacturers serving European demand blocs must substitute blowing agents and flame retardants while maintaining density and durability specifications. German facility managers are now requiring material safety data documentation as a standard specification element, filtering supplier pools before design review stages.
Enterprise buyers are consolidating vendor relationships around full-workstation solution providers rather than discrete chair or desk transactions. Architecture firms and facility management consultancies are displacing traditional dealer networks as the primary influence point in procurement decisions. This concentration is most visible in North American corporate rollouts where Steelcase and Herman Miller compete for sole-source contracts spanning multiple building locations.
Ergonomic Office Furniture Market Segmentation
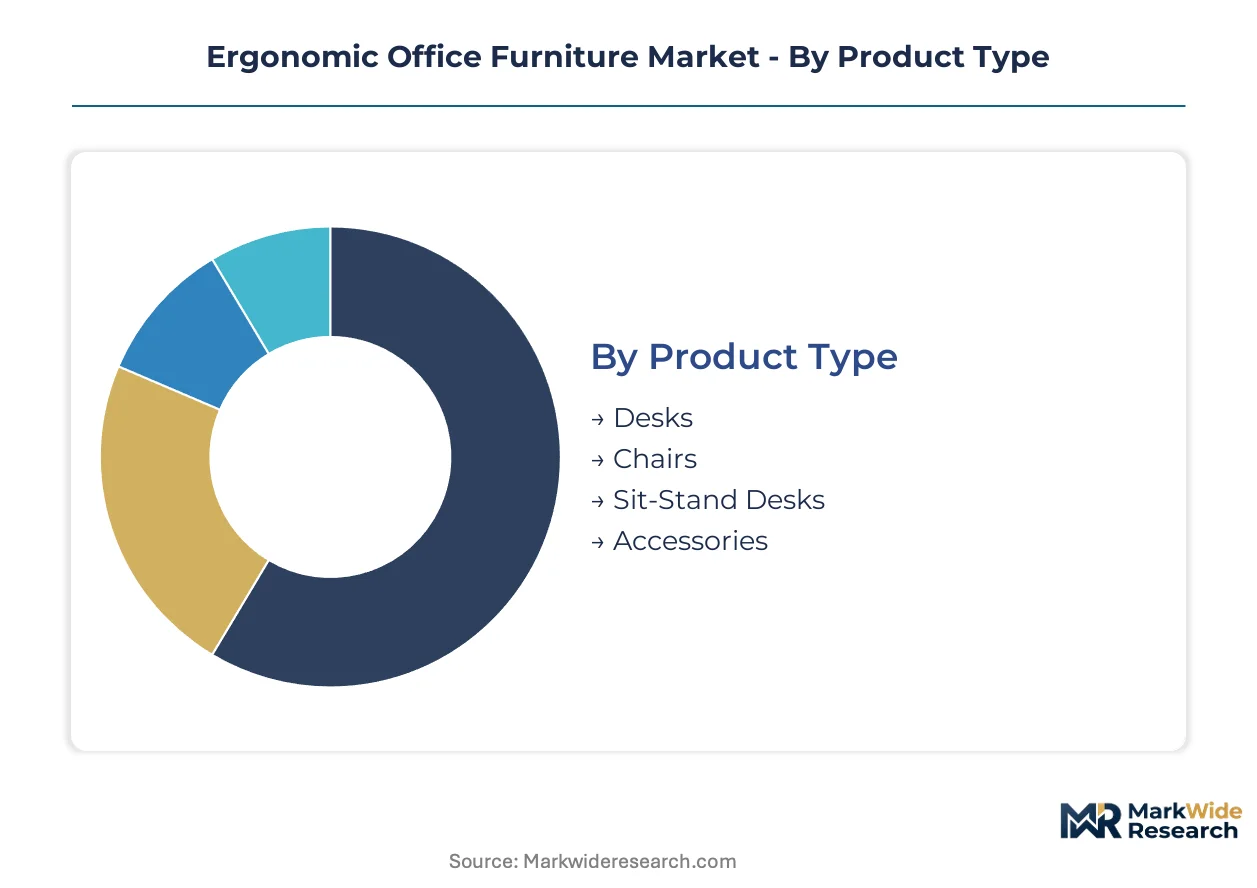
Segmentation in ergonomic office furniture reveals how procurement authority, material compliance burdens, and installation complexity reshape competitive positioning across customer tiers. Manufacturers must align R&D intensity and channel strategy to the specific constraints governing each segment cluster.
Product Type:
Cost tier differentiation separates commodity-grade metal frames from premium biomechanical seating systems with embedded sensor arrays.
- Desks:Workstation surfaces engineered for cable management integration and height modulation compatibility. Demand concentrates in German commercial builds where facility managers require BIFMA level certification as a baseline specification filter.
- Chairs:Task seating with adjustable anthropometric parameters including seat pan depth, lumbar positioning, and armrest modulation. Corporate technology employers in California and New York are compressing replacement cycles from ten-year intervals to five-year refresh mandates, forcing manufacturers to reconfigure supply chains for volume surges.
- Sit-Stand Desks:Adjustable frames with precision-machined bases enabling desktop height transitions. Expanded manufacturing clusters in China are reducing lead times for corporate rollouts.
- Accessories:Monitor arms, keyboard trays, and footrests completing ergonomic workstation configurations. Home office demand drives modular attachment specifications.
Chairs command the established base. The steepest expansion runs through sit-stand desks.
End User:
Application context determines whether procurement flows through architecture firm specification, dealer networks, or direct-to-consumer channels.
- Corporates:Enterprise buyers consolidating vendor relationships around full-workstation solution providers rather than discrete transactions. OSHA workplace ergonomics guidelines and EPA procurement standards filter supplier access for government-adjacent contracts.
- Small Businesses:Price-sensitive purchasers prioritizing modular assembly over custom configuration. Metal frame standardization dominates this tier where margin pools concentrate in logistics rather than raw materials.
- Home Offices:Individual consumers selecting pre-assembled or DIY options through e-commerce channels. Post-pandemic remote work normalization sustains demand for compact ergonomic configurations.
- Educational Institutions:Bulk procurement of durable seating and desking for computer labs and library installations. Institutional buyers emphasize warranty terms and replacement part availability over design innovation.
Corporates anchor volume concentration. Home offices are climbing the fastest as distributed work arrangements persist.
Material:
Supply concentration and regulatory exposure vary sharply across input categories, with chemical compliance costs reshaping competitive economics.
- Wood:Engineered substrates and solid timber frames for premium executive and residential applications. REACH chemical standards and the EU F-Gas Regulation impose reformulation requirements on finishes and adhesives.
- Metal:Steel and aluminum structural components standardizing across mid-market modular installations. Commodity price volatility exposes assemblers to margin compression in logistics-dependent operations.
- Plastic:Polymer components for cost-optimized seating shells and base elements. Injection molding scale economies favor high-volume producers serving small business and institutional segments.
- Fabric:Upholstery materials facing tightened EU foam blowing agent regulations. German facility managers now require material safety data documentation as a standard specification element.
Metal frames dominate unit economics. Advanced mesh technologies are gaining share fastest as premium specifications converge on reduced chemical compliance burdens.
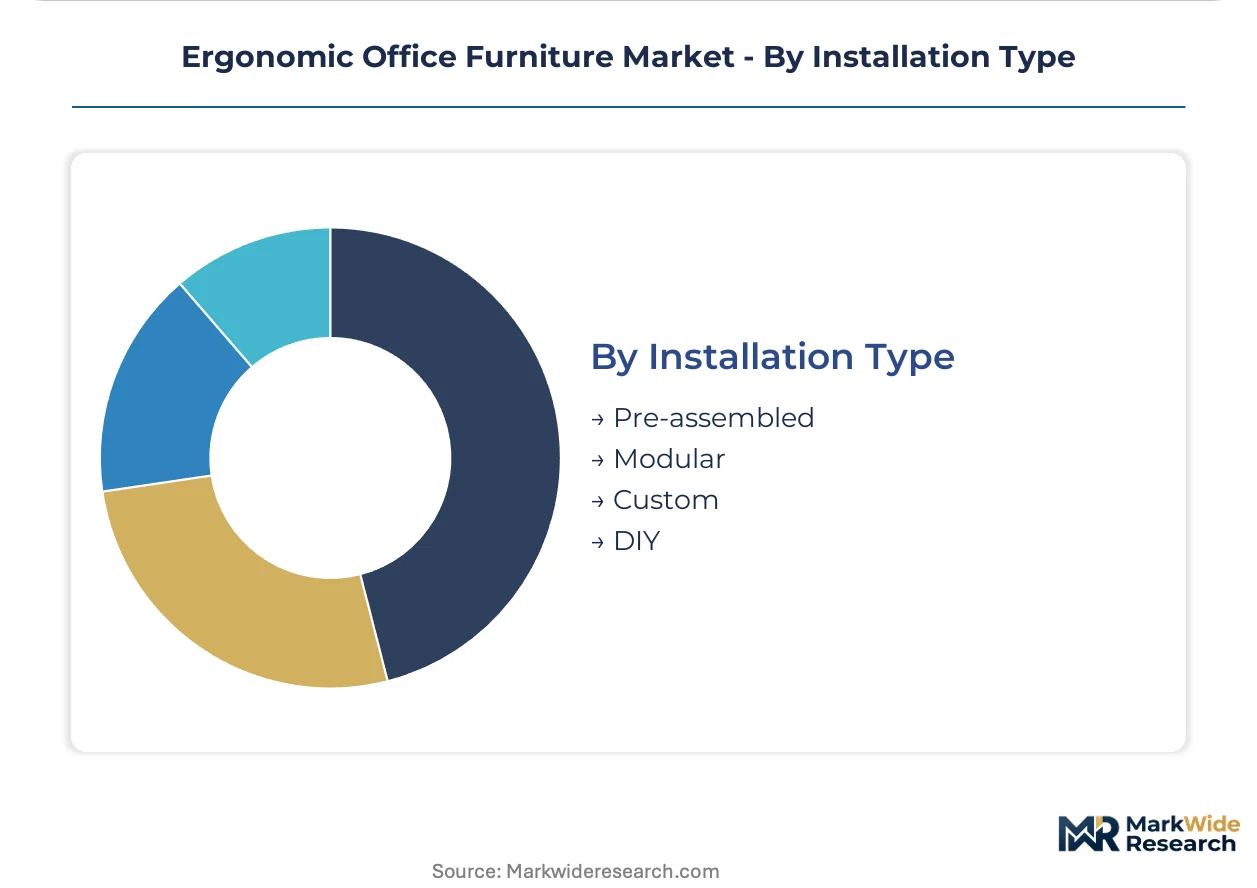
Installation Type:
Customer capability and field service infrastructure requirements segment the fulfillment model between manufacturer-controlled and buyer-executed assembly.
- Pre-assembled:Factory-completed workstations delivered for immediate deployment. Corporate rollouts in technology sector employers favor this model to minimize facility disruption.
- Modular:Component-based systems enabling reconfiguration and expansion. Architecture firms specify these for enterprise clients anticipating spatial adaptation needs.
- Custom:Bespoke dimensions and finishes tailored to specific building constraints. High-end commercial builds in Germany and California drive specification for certified ergonomic configurations.
- DIY:Self-assembly kits targeting home office and small business price sensitivity. E-commerce channel control determines competitive positioning in this segment.
Modular systems command the established base. Pre-assembled delivery is expanding most quickly as employers prioritize deployment speed over reconfiguration flexibility.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Port of Hamburg anchors European distribution for precision-machined desk frames arriving from Asian manufacturing clusters. German facility managers leverage this infrastructure to compress lead times for certified ergonomic configurations specified under EU Green Deal mandates.
Germany
Facility managers in Bavaria and North Rhine-Westphalia specify BIFMA level certification as a baseline for new commercial builds. The EU F-Gas Regulation imposes reformulation requirements on foam blowing agents for upholstered seating. Manufacturing clusters around Stuttgart concentrate precision-engineered base production for adjustable workstations.
United States
Technology sector employers in California and New York compress replacement cycles from ten-year intervals to five-year refresh mandates. OSHA workplace ergonomics guidelines and state-level building codes increasingly mandate sit-stand capability in new construction. Corporate rollout volumes concentrate in the Pacific Northwest and Northeast Corridor logistics hubs.
China
Expanded manufacturing clusters in the Yangtze River Delta and Pearl River Delta reshape supply dynamics for adjustable desk frames. The country's dual carbon goals pressure exporters toward cleaner production credentials. Zhengzhou and Dongguan anchor precision-machined base fabrication serving European and North American demand.
Japan
METI industrial standards shape domestic ergonomic specifications for task seating biomechanics. Corporate buyers in Tokyo and Osaka prioritize sensor-embedded seating systems for workstation upgrade programs. Manufacturing in the Chubu region around Nagoya concentrates high-precision component fabrication.
United Kingdom
Architecture firms in London influence enterprise procurement decisions through direct specification relationships. The country's building regulations increasingly reference ergonomic workstation standards for new commercial developments. Midlands-based assemblers serve mid-market modular installations where metal frame standardization dominates.
Ergonomic Office Furniture Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between full-workstation solution providers and discrete product fabricators. Three archetypes dominate: design-led R&D houses, scale-driven assemblers, and channel-controlling specification players. Competitive moves concentrate on sole-source contract pursuit and backward integration into precision-machined component supply.
Among Japanese manufacturers, Okamura and Kokuyo occupy positions within the precision-engineering archetype. Steelcase represents North American platform integration, anchoring supply chain control across component fabrication. These three exemplify how geographic manufacturing clusters align with distinct competitive positioning in enterprise procurement channels.
| Leading Market Players |
|---|
| Okamura |
| Knoll |
| Steelcase |
| Kokuyo |
| Teknion |
| Herman Miller |
| Humanscale |
| Vitra |
| Haworth |
| Others |
Pricing and Supply Chain Analysis
Chinese manufacturing clusters for precision-machined desk frames concentrate upstream supply leverage, driving margin pools toward assembly logistics and certification compliance rather than raw material capture in downstream tiers.
Pricing Analysis
REACH and the EU F-Gas Regulation dictate the pricing tier structure across European demand blocs. Three-tier pricing structure across premium, standard, and economy levels separates BIFMA level-certified seating from uncertified alternatives and commodity metal-frame configurations. Cost compression in mid-market upholstered segments is intensifying because foam reformulation expenses under tightened chemical standards erode producer margins. Small business buyers exhibit highest price sensitivity, while corporate technology employers prioritize certified ergonomic specifications regardless of premium positioning.
Supply Chain Analysis
Extended payment terms from large corporate buyers strain working capital for component suppliers serving adjustable workstation programs. Supply concentrates in China for precision-machined bases, Germany for certified ergonomic assembly, and Vietnam for cost-optimized metal frame fabrication. Raw material dependencies span steel and aluminum structural inputs, polymer components for seating shells, and advanced mesh textiles for premium specifications. Single-source vulnerability sits with Chinese manufacturing clusters for electric height-adjustment mechanisms. Distribution runs through architecture firm specification channels for corporate accounts and e-commerce platforms for home office segments.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Biomechanical sensing integration is disrupting traditional furniture categories, creating acceleration windows for stakeholders who capture specification authority before sensor-embedded seating becomes standard enterprise procurement.
For Market Incumbents: Entrench specification control through direct architecture firm relationships that influence enterprise procurement decisions ahead of sensor-embedded seating commoditization. Deepen backward integration into precision-machined component supply to defend margin position against Chinese manufacturing cluster expansion. Prioritize BIFMA level and EPA procurement standard certification investment to filter competitor access in government-adjacent contract windows.
For New Entrants and Emerging Players: Establish a beachhead in home office e-commerce channels where brand building costs remain manageable and specification authority is underdeveloped. Target DIY assembly segments with compact ergonomic configurations serving distributed work arrangements. Pursue white-label partnerships with established logistics platforms to bypass dealer network barriers that incumbent channel control erects.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed ergonomic seating specialists possessing established architecture firm specification relationships but limited sensor-embedded R&D capabilities. Five-to-ten year viability hinges on biomechanical engineering talent acquisition and software integration competency. Monitor California and New York building code diffusion patterns as the signal indicating regulatory template adoption across additional state jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Sensor-Embedded Seating Development | Collapses furniture-wellness hardware boundaries for technology sector employers. |
| Backward Integration into Precision Machining | Captures margin pools concentrated in Chinese manufacturing clusters. |
| Architecture Firm Specification Partnership | Displaces traditional dealer networks in enterprise procurement influence. |
| Foam Reformulation Compliance Program | Addresses REACH and EU F-Gas Regulation requirements for European market access. |
| Modular System Platform Expansion | Enables reconfiguration flexibility that corporate buyers prioritize over fixed installations. |
Research Methodology
Two parallel data streams informed the analysis: primary field engagement with industry stakeholders and secondary validation across published sources. Facility managers, architecture firm specification leads, corporate procurement officers, and ergonomic product R&D directors contributed qualitative perspective. Secondary sources encompassed BIFMA certification databases, EPA procurement standard documentation, EU regulatory filings, and customs trade records for precision-machined component flows. Bottom-up segment sizing and top-down market triangulation were cross-validated for consistency.
Forecast inputs incorporated product type segmentation across chairs, desks, sit-stand configurations, and accessories; end-user tiers spanning corporates, small businesses, home offices, and educational institutions; material categories including metal, wood, plastic, and fabric; and installation types from pre-assembled to DIY. CAGRs were derived through trend extrapolation adjusted for regulatory inflection points and technology adoption curves. Biomechanical sensing penetration rates and EU Green Deal compliance timelines served as industry-specific demand modifiers across the projection horizon.
Stress conditions across steel and aluminum commodity volatility, REACH chemical reformulation cost trajectories, and California building code diffusion velocity were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about replacement cycle compression and sensor-embedded seating adoption. Macroeconomic contraction, regulatory reversal, or technological disruption in posture-sensing accuracy would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Office Furniture
Office Seat Cushion Market
Office Furniture
Russia Office Furniture Market
Office Furniture
Germany Office Furniture Market
Office Furniture
Institutional Furniture Market
Office Furniture
UAE Office Furniture Market
Office Furniture
United States Home Office Furniture Market
Office Furniture
United States Furniture Market
Office Furniture
Office Furniture Market
Office Furniture
India Office Furniture Market
Office Furniture
Europe Office Furniture Market
Office Furniture
Brazil Office Furniture Market
Office Furniture
Australia Office Furniture Market
Office Furniture
United Kingdom Office Furniture Market
Office Furniture
Furniture and Home Furnishings Market
Office Furniture
Home Office Furniture Market
Office Furniture
Rental Furniture Market