
 Truck and Bus Tires Market | 2026-2036
Truck and Bus Tires Market Size, Share, and Industry Trends Forecast 2026-2036
Truck and Bus Tires Market Insights
Wholesale distribution networks is reconfiguring as direct-to-fleet digital platforms capture procurement volume from traditional dealer tiers. Bridgestone Corporation leverages its Bandag retreading subsidiary to sustain service revenue streams alongside new tire sales. Michelin Group anchors its position through fleet management solutions that integrate tire monitoring with predictive maintenance contracts. Continental AG competes on embedded sensor technology, differentiating its commercial tire portfolio through connected vehicle data layers.
Truck and bus tires are engineered pneumatic structures designed to support heavy commercial vehicle loads, typically incorporating steel-belted radial carcasses, specialized tread compounds, and reinforced sidewalls to withstand sustained highway speeds and irregular terrain. Their primary purpose is to ensure vehicle stability, cargo safety, and operational uptime across freight and passenger transport duty cycles. Radial tires dominate installed base volumes due to superior heat dissipation and tread life, while smart tires embedding pressure and temperature sensors represent the fastest-expanding technology category as telematics adoption spreads through logistics fleets. Retreaded tires retain significant share in cost-sensitive segments, though margin pools increasingly concentrate in premium eco-friendly compounds that command higher replacement prices.
EPA SmartWay verification programs and NHTSA greenhouse gas standards for medium- and heavy-duty vehicles shape tire design requirements, pushing manufacturers toward reduced rolling resistance formulations. The European Union's F-Gas Regulation and ECE R117 labeling standards further constrain compound chemistry and noise performance for cross-border fleet operators. Stakeholders must monitor how California's Advanced Clean Trucks rule and pending federal tire efficiency benchmarks will reshape specification requirements and supplier qualification criteria across North American procurement channels.
Market Dynamics
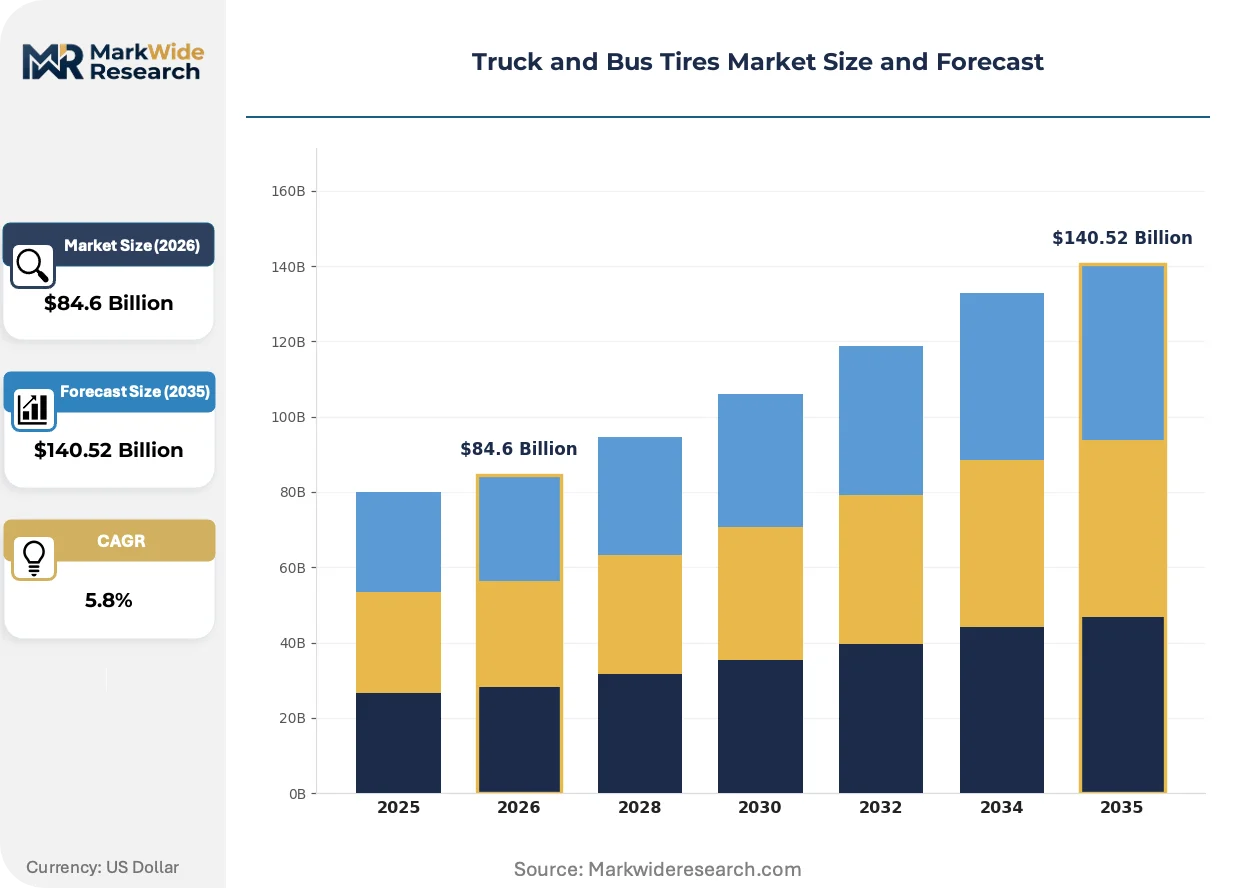
Fleet digitization and EPA SmartWay verification requirements are compressing replacement cycles while elevating specification complexity for commercial tire procurement across North American logistics corridors.
Growth Catalysts
- EPA SmartWay Verification:Federal emissions benchmarking for medium- and heavy-duty vehicles mandates low rolling resistance compounds, pulling fleet operators toward certified tire specifications that reduce fuel consumption and greenhouse gas output.
- Telematics Integration:Embedded pressure and temperature sensors in smart tires enable predictive maintenance contracts, creating recurring revenue streams for tire manufacturers and reducing unplanned downtime for freight operators.
- Retread Economics:Cost-sensitive regional carriers and municipal bus fleets sustain demand for Bandag-style retreading programs, preserving casing value and extending service life across multiple tread cycles.
Market Restraints
- Natural Rubber Volatility:Southeast Asian supply disruptions and futures market speculation create input cost instability that compresses manufacturer margins and complicates long-term contract pricing.
- Steel Belt Concentration:Dependence on integrated steel producers in China and India for radial tire reinforcement creates geopolitical exposure and tariff-related cost escalations for North American manufacturers.
- Technical Limitation:Current silica-silane coupling chemistry in green tire formulations sacrifices wet traction performance, creating specification trade-offs that delay full fleet conversion.
Strategic Opportunities
- California ACT Rule:The state's Advanced Clean Trucks mandate accelerates zero-emission vehicle deployment, creating demand for specialized tire constructions optimized for electric drivetrain torque characteristics and weight distribution.
- Direct-to-Fleet Platforms:Digital procurement channels bypass traditional dealer tiers, enabling manufacturers to capture margin pools previously allocated to wholesale distribution networks.
- Sensor-Telematics Convergence:Integration of tire-mounted IoT devices with fleet management software creates data monetization opportunities and sticky customer relationships through subscription-based monitoring services.
Industry Challenges
- Compound Formulation Expertise:Shortage of polymer chemists capable of balancing rolling resistance, tread wear, and wet grip in sustainable rubber formulations delays product development timelines.
- Smart Tire Certification:NHTSA validation protocols for sensor-embedded commercial tires extend regulatory approval cycles, compressing launch windows for connected product portfolios.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Truck and Bus Tires Market |
| Market Size in 2026 | $84.6 Billion |
| Market Size in 2035 | $140.52 Billion |
| CAGR (2026 – 2036) | 5.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Radial Tires, Bias Tires, Tubeless Tires, Retreaded Tires End User: Logistics Companies, Public Transport Operators, Freight Carriers, OEMs Application: On-Road, Off-Road, Emergency Services, Urban Transport Technology: Smart Tires, Eco-Friendly Tires, Performance Tires, Standard Tires |
| Companies Covered | Bridgestone Corporation, Michelin Group, Continental AG, Goodyear Tire & Rubber Company, Sumitomo Rubber Industries Ltd., Hankook Tire & Technology, Pirelli & Co SPA, Yokohama Tire Corporation, Zhongce Rubber Group Company Limited, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Truck and Bus Tires Market Trends and Innovations
Material science breakthroughs and regulatory tightening are converging to transform tire construction priorities, with sustainability metrics now embedded in procurement specifications alongside traditional performance benchmarks.
Silica-reinforced tread compounds are migrating from premium passenger segments into heavy-duty commercial applications as fleet operators demand fuel efficiency gains without sacrificing load-bearing capacity. Long-haul carriers operating EPA SmartWay-certified tractors adopt these formulations at accelerating rates, particularly on drive axle positions where rolling resistance impacts compound most directly. The shift is compressing demand for conventional carbon-black-heavy constructions and elevating compound chemistry to a primary competitive differentiator.
NHTSA greenhouse gas standards for medium- and heavy-duty vehicles mandate phase-in efficiency improvements that cascade directly into tire design requirements. The regulation forces manufacturers to validate reduced rolling resistance coefficients through standardized test protocols, creating compliance costs that favor scaled producers with captive R&D facilities. California's complementary Advanced Clean Trucks rule amplifies this pressure, with fleet operators in the state now specifying tires against combined federal-state efficiency benchmarks.
Fleet procurement departments now unbundle tire acquisition from maintenance service contracts, reversing decades of bundled dealer relationships. Large logistics operators with centralized procurement functions negotiate direct supply agreements with manufacturers, capturing volume discounts and standardizing specifications across dispersed vehicle populations. The disintermediation is most visible among for-hire trucking fleets operating more than five hundred power units, where procurement centralization justifies dedicated account management resources.
Truck and Bus Tires Market Segmentation
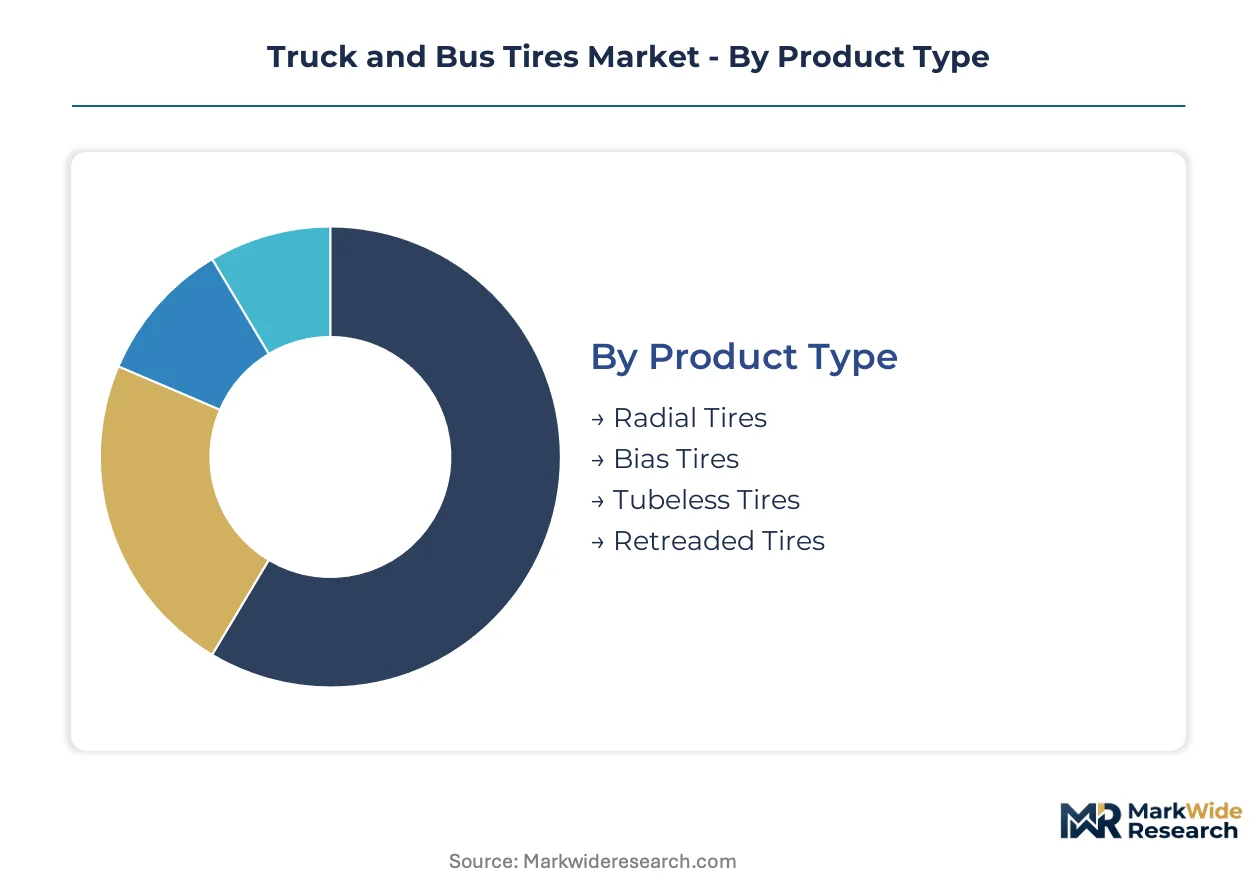
Segmentation in the truck and bus tires market reveals divergent procurement patterns across fleet types, duty cycles, and regulatory exposure zones. Tire manufacturers calibrate product portfolios against these divisions to optimize manufacturing capacity and distribution investments.
Product Type:
Mature radial constructions dominate installed base volumes, while emerging technologies reshape replacement cycle economics and margin structures.
- Radial Tires:Steel-belted radial carcasses with multi-layer tread compounds deliver superior heat dissipation and extended tread life under sustained highway loads. Long-haul freight corridors in the United States concentrate replacement demand as EPA SmartWay verification mandates pull fleets toward low rolling resistance specifications.
- Bias Tires:Cross-ply nylon or polyester cord constructions retain niche positions in severe-duty mining and construction applications where sidewall puncture resistance outweighs fuel efficiency priorities. Demand concentrates in off-road segments across developing economies with limited highway infrastructure.
- Tubeless Tires:Eliminate inner tube failure modes through direct rim-sealing bead designs, reducing roadside service incidents for high-utilization fleets.
- Retreaded Tires:Bandag-style cold-process retreading preserves casing value across multiple tread cycles, sustaining cost-sensitive regional carrier procurement.
Radial tires retain volume leadership; smart tire-enabled retreading holds the steepest expansion curve.
End User:
Customer type segmentation exposes divergent specification authority, with centralized procurement functions displacing decentralized dealer relationships among large fleet operators.
- Logistics Companies:Asset-light and asset-heavy third-party logistics operators with centralized procurement functions negotiate direct manufacturer supply agreements, standardizing specifications across dispersed power unit populations. Telematics integration requirements from United States-based e-commerce fulfillment networks accelerate smart tire specification.
- Public Transport Operators:Municipal bus fleets and regional transit authorities prioritize total cost of ownership metrics over acquisition price, sustaining retreading program participation.
- Freight Carriers:For-hire trucking fleets balance fuel efficiency mandates against casing durability for irregular route operations.
- OEMs:Original equipment manufacturers specify tires against vehicle platform efficiency targets, with California ACT rule compliance cascading into factory-fit requirements.
Logistics companies capture the fastest volume growth; public transport operators maintain the most stable replacement cycles.
Application:
Duty cycle intensity and surface condition variability create distinct performance envelopes that constrain compound formulation choices.
- On-Road:Highway freight and intercity bus operations subject tires to sustained speed-induced heat buildup and uniform abrasion patterns. United States interstate corridors concentrate demand for EPA SmartWay-certified compounds that reduce rolling resistance coefficients.
- Off-Road:Mining, logging, and construction applications impose irregular terrain loading with high cut-and-chip exposure.
- Emergency Services:Fire apparatus and ambulance fleets require rapid acceleration response and stable high-speed handling under full load.
- Urban Transport:Stop-and-go duty cycles with frequent curb contact prioritize sidewall durability and regressive tread wear resistance.
On-road applications command the largest revenue pool; urban transport segments climb fastest on electrification-driven specification changes.
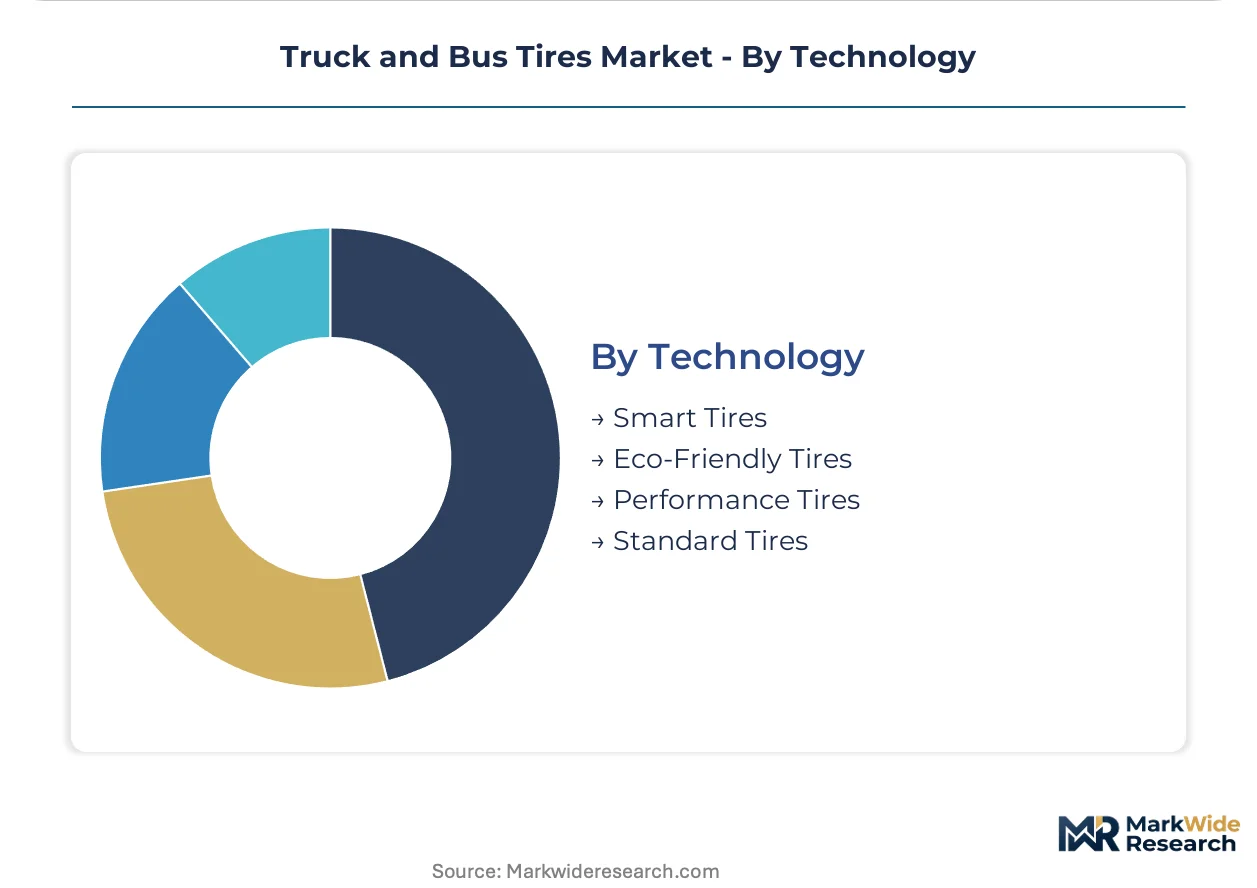
Technology:
Technology tiering separates premium data-enabled products from commodity replacements, with regulatory pressure compressing the middle tier.
- Smart Tires:Embedded pressure, temperature, and tread depth sensors transmit real-time condition data through fleet telematics platforms. United States long-haul operators adopt these systems fastest where unplanned downtime costs exceed sensor hardware premiums.
- Eco-Friendly Tires:Silica-reinforced tread compounds and renewable content formulations satisfy EPA and NHTSA efficiency benchmarks.
- Performance Tires:Optimized for specific handling characteristics in emergency vehicle and premium coach applications.
- Standard Tires:Conventional carbon-black constructions serve price-sensitive replacement segments with minimal regulatory exposure.
Standard tires retain volume leadership; smart tires gain share fastest on predictive maintenance contract penetration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
EPA SmartWay verification and NHTSA fuel efficiency mandates in the United States are compressing replacement cycles and elevating specification complexity for commercial tire procurement. Freight tonnage growth across interstate corridors pulls demand toward low rolling resistance compounds. Fleet digitization and direct-to-fleet procurement platforms are reconfiguring distribution networks in mature markets.
United States
Long-haul logistics operators expand replacement tire procurement as freight volumes rise across interstate corridors. EPA SmartWay verification programs mandate certified tire specifications that reduce fuel consumption and greenhouse gas output. The Dallas-Fort Worth metroplex anchors fleet management technology adoption, with telematics-integrated tire monitoring spreading through regional carrier operations.
Germany
Commercial vehicle manufacturers specify tires against EU CO2 performance standards for heavy-duty vehicles. The ECE R117 labeling standards constrain compound chemistry and noise performance for cross-border fleet operators. The Stuttgart industrial cluster concentrates OEM procurement authority, with factory-fit specifications cascading into replacement market demand patterns.
China
Domestic freight volume expansion and export manufacturing sustain radial tire production scale. MIIT fuel consumption standards for commercial vehicles push domestic manufacturers toward reduced rolling resistance formulations. The Shandong Peninsula hosts concentrated tire manufacturing capacity, with Qingdao-based producers serving both domestic replacement and export OEM channels.
India
Highway infrastructure expansion and logistics fleet modernization drive commercial tire replacement demand. BIS certification requirements and axle load norms shape product specifications for domestic heavy vehicle operators. The Chennai-Bangalore industrial corridor concentrates bus and truck OEM assembly, pulling tire supply agreements toward southern manufacturing zones.
Brazil
Agricultural commodity transport and long-distance freight corridors sustain heavy-duty tire consumption. ANVISA and national environmental agency regulations on tire disposal and recycling shape aftermarket service requirements. The São Paulo state industrial belt anchors distribution infrastructure, with Campinas-based logistics hubs channeling replacement volume to regional carrier fleets.
Truck and Bus Tires Market Competitive Landscape
On the supply side, the industry is consolidating around integrated manufacturers with captive R&D facilities and retreading service networks. Scale advantages concentrate in producers with vertical control over compound formulation and sensor-embedded product development. Two strategic archetypes dominate: diversified rubber conglomerates with fleet management solution portfolios, and specialized commercial tire manufacturers with regional retreading partnerships. Competitive moves center on direct-to-fleet digital platform deployment and predictive maintenance contract bundling.
Among Japanese rubber conglomerates, Bridgestone Corporation and Sumitomo Rubber Industries Ltd. exemplify the integrated service archetype, combining new tire manufacturing with retreading program ownership. Continental AG anchors the European sensor-technology vector, while Michelin Group and Goodyear Tire & Rubber Company occupy positions spanning premium compound development and fleet solution integration. Zhongce Rubber Group Company Limited represents the scale-driven Asian manufacturer archetype.
| Leading Market Players |
|---|
| Bridgestone Corporation |
| Michelin Group |
| Continental AG |
| Goodyear Tire & Rubber Company |
| Sumitomo Rubber Industries Ltd. |
| Hankook Tire & Technology |
| Pirelli & Co SPA |
| Yokohama Tire Corporation |
| Zhongce Rubber Group Company Limited |
| Others |
Pricing and Supply Chain Analysis
Interstate 80 freight corridors between Chicago and San Francisco concentrate cost pressure from fuel efficiency mandates, with supply concentration in Southeast Asian natural rubber markets and tiered certification requirements creating three distinct price bands for fleet procurement managers.
Pricing Analysis
Certification level creates the primary spread across procurement tiers, with EPA SmartWay-verified compounds commanding premiums over baseline radials and unverified imports occupying the economy segment. Price differentiation rests on rolling resistance coefficients and telematics integration depth, with embedded sensor packages adding service-contract value. Cost compression in standard-tier products is intensifying as Chinese manufacturers expand North American distribution. Regional for-hire fleets exhibit highest price sensitivity, while dedicated contract carriers with centralized procurement show lowest.
Supply Chain Analysis
Natural rubber feedstock draws from Thailand, Indonesia, and Vietnam, with steel belt reinforcement anchored in Chinese and Indian integrated mills. Synthetic rubber and silica fillers hinge on petrochemical complexes in South Korea and Japan. Tariff exposure on radial tire components creates margin volatility for North American assemblers. Distribution runs through manufacturer-owned wholesale networks and direct-to-fleet digital platforms, bypassing traditional dealer tiers at accelerating rates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Telematics-embedded smart tires and predictive maintenance contracts represent a structural inflection, with EPA SmartWay phase-ins and California ACT rules compressing replacement cycles while elevating specification complexity beyond commodity competition.
For Market Incumbents: Harden retreading service networks against digital-native entrants by integrating Bandag-style cold-process operations with real-time casing tracking. Deepen backward integration into silica-silane compound formulation to defend margin position against raw material volatility. Prioritize NHTSA certification pathways for sensor-embedded portfolios before regulatory windows narrow.
For New Entrants and Emerging Players: Mid-market regional carriers operating 50-200 power units represent the most penetrable entry point, with fragmented procurement functions and limited telematics legacy creating lower switching costs. Specialized tire constructions for electric drivetrain torque characteristics offer white-space differentiation as California ACT compliance cascades into specification requirements. Direct-to-fleet platform partnerships with logistics software providers enable bypass of entrenched dealer relationships.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified rubber conglomerates seeking to monetize non-core commercial tire divisions. Long-term viability over the next decade hinges on compound chemistry IP and telematics data infrastructure rather than manufacturing scale alone. Watch NHTSA smart tire validation protocol timelines as the signal for competitive consolidation velocity.
| Strategic Initiative | Industry Significance |
|---|---|
| Retreading Network Integration | Bandag-style cold-process operations preserve casing value across multiple tread cycles for cost-sensitive fleets. |
| Smart Tire Certification | NHTSA validation protocols for sensor-embedded commercial tires compress launch windows for connected portfolios. |
| Direct-to-Fleet Platform Deployment | Digital procurement channels capture margin pools previously allocated to wholesale distribution networks. |
| Silica-Silane Compound Investment | Specialized formulations balance rolling resistance reduction with wet traction performance for EPA compliance. |
| Predictive Maintenance Contract Bundling | Telematics integration creates recurring revenue streams and sticky relationships with logistics operators. |
Research Methodology
Desk research of customs trade databases, SEC manufacturing disclosures, and EPA SmartWay certification registries preceded structured interviews with fleet procurement directors, tire manufacturer R&D leads, and aftermarket service operators. Primary fieldwork across North American logistics corridors combined with secondary validation against NHTSA regulatory filings and commercial vehicle registration data. Bottom-up volume estimates from replacement cycle modeling were triangulated against top-down market sizing from trade flow analysis.
Assumptions regarding freight tonnage growth, regulatory phase-in schedules, and telematics adoption curves were held fixed across baseline scenarios while commodity price volatility and tariff trajectories were stress-tested. The analytical framework segmented volume and value across product construction, end-user type, duty cycle application, and technology tier throughout the forecast period. CAGRs were derived from regression analysis against historical replacement patterns and fleet expansion trajectories, with silica compound penetration and smart tire attach rates as key industry-specific inputs.
Stress conditions across natural rubber futures volatility, steel tariff schedules, and NHTSA certification timeline delays were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding regulatory compliance deadlines and fleet digitization investment cycles. Cross-checking against American Trucking Associations freight volume benchmarks and commercial vehicle production data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Tires and Wheels
Automotive Retread Tires Market
Tires and Wheels
Asia Pacific Two Wheeler Tire Market
Tires and Wheels
Intelligent Tire Market
Tires and Wheels
Trailer Wheel Market
Tires and Wheels
Automotive Wheel Spindle Market
Tires and Wheels
Industrial Tire Market
Tires and Wheels
Solid Tire Market
Tires and Wheels
Rolling Stock Wheel Market
Tires and Wheels
Global Automotive Tire Inflator Market
Tires and Wheels
Off-The-Road (OTR) Tire Market
Tires and Wheels
Global Aircraft Tire Market
Tires and Wheels
Bias Tire Market
Tires and Wheels
Automotive Automatic Tire Inflation System (ATIS) Market
Tires and Wheels
Magnesium Wheel Market
Tires and Wheels
Asia-Pacific Alloy Wheels Market
Tires and Wheels
Steel Cord for Tire Reinforcement Market