
 Global Reishi Mushroom Extracts Market | 2026-2036
Global Reishi Mushroom Extracts Market Size, Share, and Industry Trends Forecast 2026-2036
Global Reishi Mushroom Extracts Market Foresight
Asset-light contract cultivation and third-party extraction tolling is fragmenting competitive barriers in Reishi supply chains. Nammex leverages wild-simulated growing protocols in British Columbia to sustain premium positioning for North American nutraceutical buyers. Hokkaido Reishi Co. Ltd. anchors traditional Japanese cultivation expertise, while DXN Holdings Bhd competes through integrated direct-selling networks spanning Southeast Asia.
Reishi mushroom extracts comprise bioactive concentrates derived from Ganoderma lucidum fruiting bodies or mycelium, standardized for polysaccharide and triterpenoid content through hot-water or ethanol extraction processes, serving primarily as functional ingredients for immune modulation and adaptogenic applications. Powdered extracts dominate bulk ingredient procurement due to formulation flexibility across dietary supplements and functional beverages, while liquid extracts command premium placement in herbal medicine and cosmetic ingredient channels where rapid bioavailability claims differentiate positioning. Capsule formats occupy the largest finished-product margin pool through pharmacy and online retail distribution.
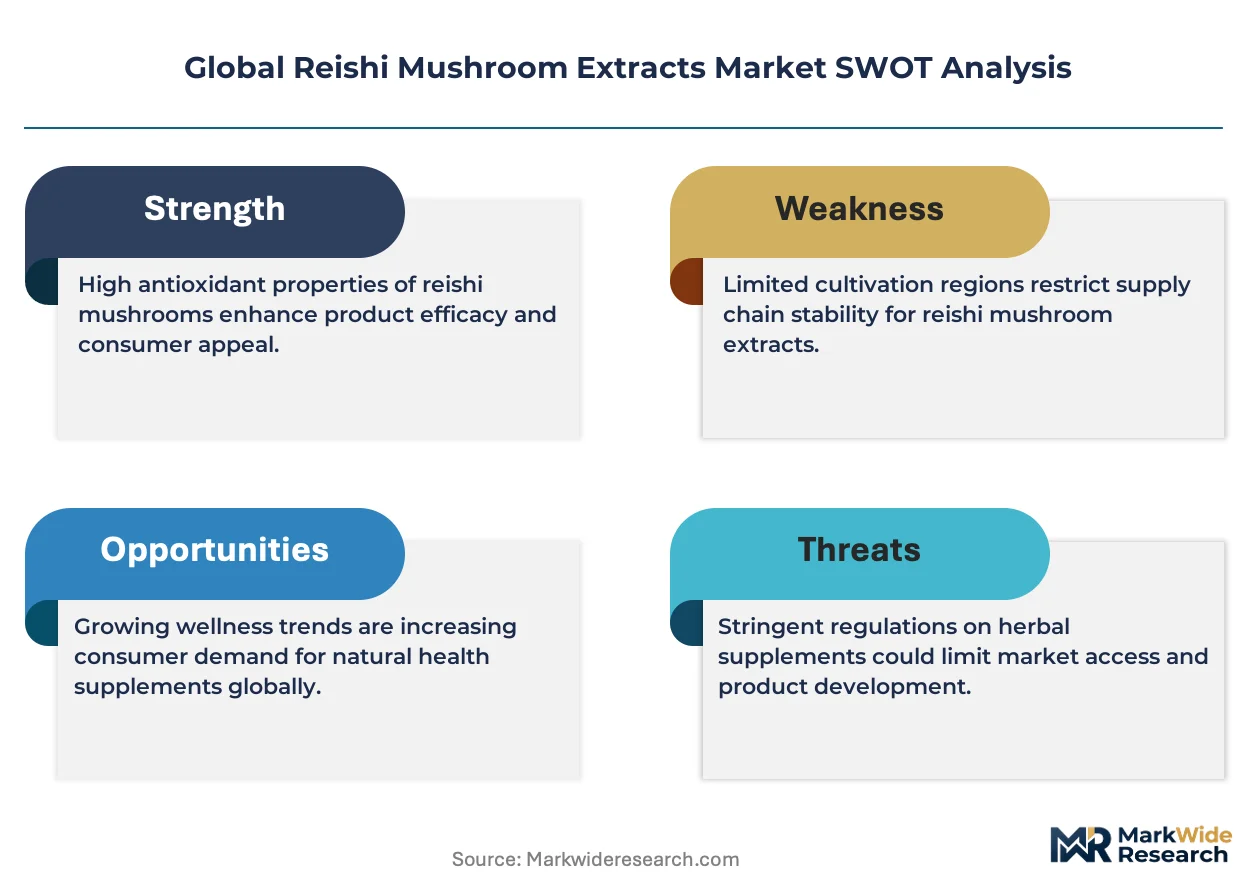
FDA dietary supplement GMPs, EFSA Novel Food assessments, and China's NMPA traditional medicine registration pathways collectively determine market access timelines and label claim permissibility across major demand zones. Compliance divergence between these frameworks forces extract suppliers to maintain parallel certification portfolios, elevating fixed costs for smaller cultivators. Stakeholders must monitor evolving botanical drug pathways in the US and EU, as regulatory reclassification would redirect R&D investment and reshape competitive moats around clinical validation capabilities.
Market Dynamics
Asset-light contract cultivation is fragmenting competitive barriers across Reishi supply chains, enabling new entrants to bypass capital-intensive growing infrastructure while forcing established players to defend premium positioning through proprietary extraction protocols and certification depth.
Growth Catalysts
- EU Novel Food Regulation pathway clarity:EFSA's evolving assessment framework for mushroom-derived ingredients is accelerating compliant product launches across Germany, France, and Italy.
- Traditional medicine integration in East Asia:China's NMPA registration pathways for botanical drug candidates are channeling R&D investment toward clinical validation of triterpenoid standardization.
- Hot-water extraction technology maturation:Advanced polysaccharide concentration methods are improving batch consistency for North American dietary supplement contract manufacturers.
Market Restraints
- Wild-simulated substrate cost volatility:Hardwood log and sawdust input prices fluctuate with British Columbia and Hokkaido forestry cycles, compressing margin predictability for premium cultivators.
- Extraction capacity concentration:Third-party tolling networks cluster in Zhejiang and Shandong provinces, creating geographic single-point vulnerabilities for international buyers.
- Dual carbon compliance in China:MEE energy-intensity targets for agricultural processing are elevating fixed costs for steam-dependent hot-water extraction facilities.
Strategic Opportunities
- Underpenetrated Brazilian and Mexican pharmacy channels:ANVISA's expanding functional food ingredient registry is opening formal retail pathways for capsule-format Reishi products.
- Cosmetic ingredient convergence:Adaptogenic skincare formulations are absorbing ethanol-extracted triterpenoid fractions previously channeled exclusively into nutraceuticals.
- Direct-to-practitioner distribution innovation:Licensed herbalist networks in Australia and Canada are bypassing traditional retail markup structures for liquid extract procurement.
Industry Challenges
- Analytical chemist scarcity:Polysaccharide and triterpenoid quantification expertise concentrates in university labs and contract research organizations, not cultivator quality departments.
- Parallel certification portfolio burden:Smaller suppliers struggle to maintain simultaneous FDA dietary supplement GMPs, ISO 22000, and organic handling certifications required by multinational buyers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Reishi Mushroom Extracts Market |
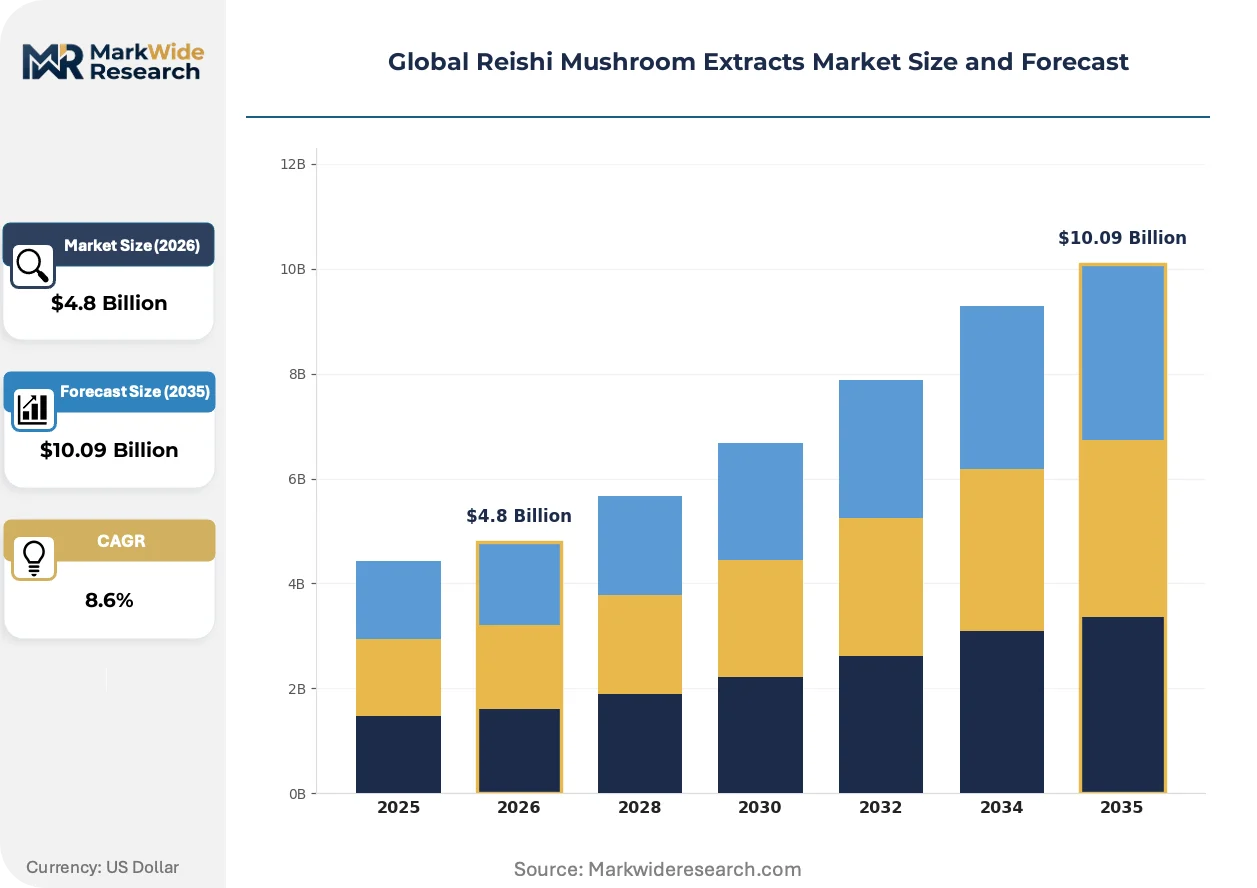
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powdered Extract, Liquid Extract, Capsule, Tablet, Tea Blend Application: Dietary Supplements, Functional Beverages, Cosmetic Ingredients, Herbal Medicines, Nutraceuticals End User: Pharmaceutical Companies, Personal Care Brands, Herbal Clinics, Dietary Supplement Manufacturers, Wellness Centers Distribution Channel: Online Retail, Health Stores, Pharmacies, Direct Sales, Specialty Stores |
| Companies Covered | Bio-Botanica Inc., Hokkaido Reishi Co. Ltd., Nammex, Bristol Botanicals Limited, Qingdao Dacon Trading Co., Ltd., Xian Yuensun Biological Technology Co., Ltd., DXN Holdings Bhd, Xi'an Greena Biotech Co., Ltd., Aloha Medicinals, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Reishi Mushroom Extracts Market Shifts & Advancements
Digital traceability infrastructure and precision fermentation alternatives are compressing traditional cultivation-to-extraction timelines while regulatory divergence between pharmacopeial and food-grade pathways is forcing suppliers to place divergent bets on standardization protocols.
Submerged liquid fermentation of Reishi mycelium is virtualizing the traditional 6-12 month fruiting body cultivation cycle, enabling year-round biomass production in controlled bioreactor environments. North American and European nutraceutical contract manufacturers are accelerating mycelium-derived extract procurement to hedge against climate-dependent wild-simulated supply volatility. This technology is virtualizing geographic production advantages previously anchored to specific growing regions, compressing the premium pricing power of terroir-based suppliers.
REACH-compliant solvent recovery mandates are reshaping ethanol extraction economics across EU member states, particularly affecting mid-scale toll processors in Poland and the Netherlands. ECHA's tightening volatile organic compound thresholds are forcing capital deployment into closed-loop recovery systems that smaller operators cannot finance. Premium-positioned extractors in Germany and Switzerland are absorbing compliance costs through pharmacy-channel pricing power, while commodity suppliers face margin compression or exit.
Hospital and clinic procurement committees are consolidating botanical ingredient purchasing through group purchasing organizations, displacing fragmented herbalist-direct relationships that historically dominated Reishi distribution. This concentration is compressing supplier negotiation leverage and elevating documentation requirements for clinical trial backing and pharmacovigilance data. The shift is most visible in South Korean and Taiwanese healthcare systems, where MFDS and TFDA institutional procurement frameworks now dominate volume allocation.
Global Reishi Mushroom Extracts Market Segmentation
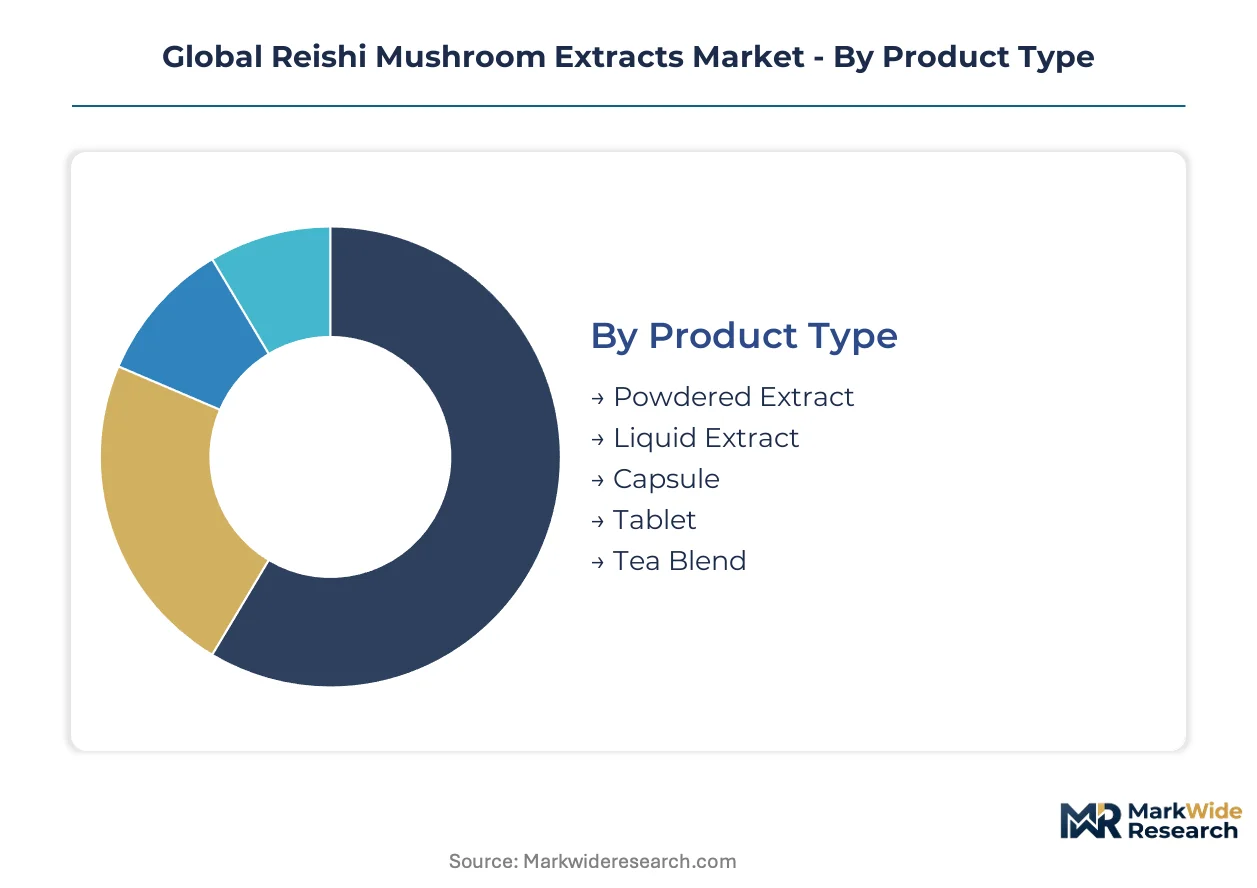
Segmentation in Reishi extracts reveals divergent margin profiles and regulatory pathways. Powdered bulk ingredients cycle through inventory faster than finished capsules, while cosmetic and pharmaceutical channels impose distinct certification burdens on suppliers.
Product Type:
Cycle times range from six-month fruiting body cultivation for premium powdered extracts to 48-hour liquid extract batch processing, with finished dosage forms sitting in distribution channels longest.
- Powdered Extract:Hot-water or ethanol-concentrated polysaccharide and triterpenoid matrices standardized to 10-30% beta-glucan content. Dietary supplement contract manufacturers in the US and Germany absorb bulk volumes for capsule and tablet formulation, though hardwood substrate cost volatility compresses margin predictability for wild-simulated cultivators.
- Liquid Extract:Hydroethanolic tinctures and glycerites offering rapid dissolution claims for functional beverage and herbal medicine applications. Australian licensed herbalist networks and Canadian naturopathic clinics are expanding procurement of alcohol-preserved formats for practitioner-dispensed protocols.
- Capsule:Hard-shell gelatin and vegetable cellulose formats dominating pharmacy and online retail margin pools.
- Tablet:Compressed formulations with excipient blends for extended-release claims in nutraceutical channels.
- Tea Blend:Whole fruiting body granules and instant soluble powders targeting traditional medicine consumers in China and Japan.
Powdered extract dominates installed base. Liquid extract is where expansion concentrates.
Application:
Cost tiers separate commodity bulk ingredients from premium finished goods, with clinical validation investments creating divergent entry barriers.
- Dietary Supplements:Standardized polysaccharide concentrates for immune-modulation label claims, subject to FDA GMP and EFSA Novel Food compliance. North American private-label manufacturers are consolidating procurement through fewer suppliers demanding parallel organic and ISO certifications.
- Cosmetic Ingredients:Ethanol-extracted triterpenoid fractions for adaptogenic skincare formulations. South Korean and French beauty brands are absorbing supply previously channeled exclusively into nutraceuticals, with triterpene standardization now required for anti-aging positioning.
- Functional Beverages:Instant-dissolve powders and flavor-masked extracts for ready-to-drink immune support products.
- Herbal Medicines:Pharmacopeial-grade extracts for traditional Chinese medicine and Kampo formulations in Japan.
- Nutraceuticals:Clinical-trial-backed ingredients for condition-specific health positioning.
Dietary supplements anchor volume absorption. Cosmetic ingredients are climbing the fastest.
End User:
Customer type determines documentation depth, with pharmaceutical and personal care buyers imposing the most stringent analytical and traceability requirements.
- Dietary Supplement Manufacturers:Contract and branded marketers sourcing bulk extracts for immune and adaptogenic formulations. US and German buyers are consolidating vendor lists to reduce audit burden, favoring suppliers with captive cultivation and in-house extraction.
- Pharmaceutical Companies:Botanical drug developers pursuing NMPA and FDA IND pathways for triterpenoid-standardized Reishi fractions. China's hospital procurement consolidation through group purchasing organizations is elevating clinical trial and pharmacovigilance documentation requirements.
- Personal Care Brands:Formulators integrating Reishi extracts into adaptogenic skincare and hair care products.
- Herbal Clinics:Practitioner-direct procurement of liquid extracts and traditional preparations.
- Wellness Centers:Integrative health facilities dispensing Reishi as part of functional medicine protocols.
Dietary supplement manufacturers represent the broadest installed base. Pharmaceutical companies are where strategic investment concentrates.
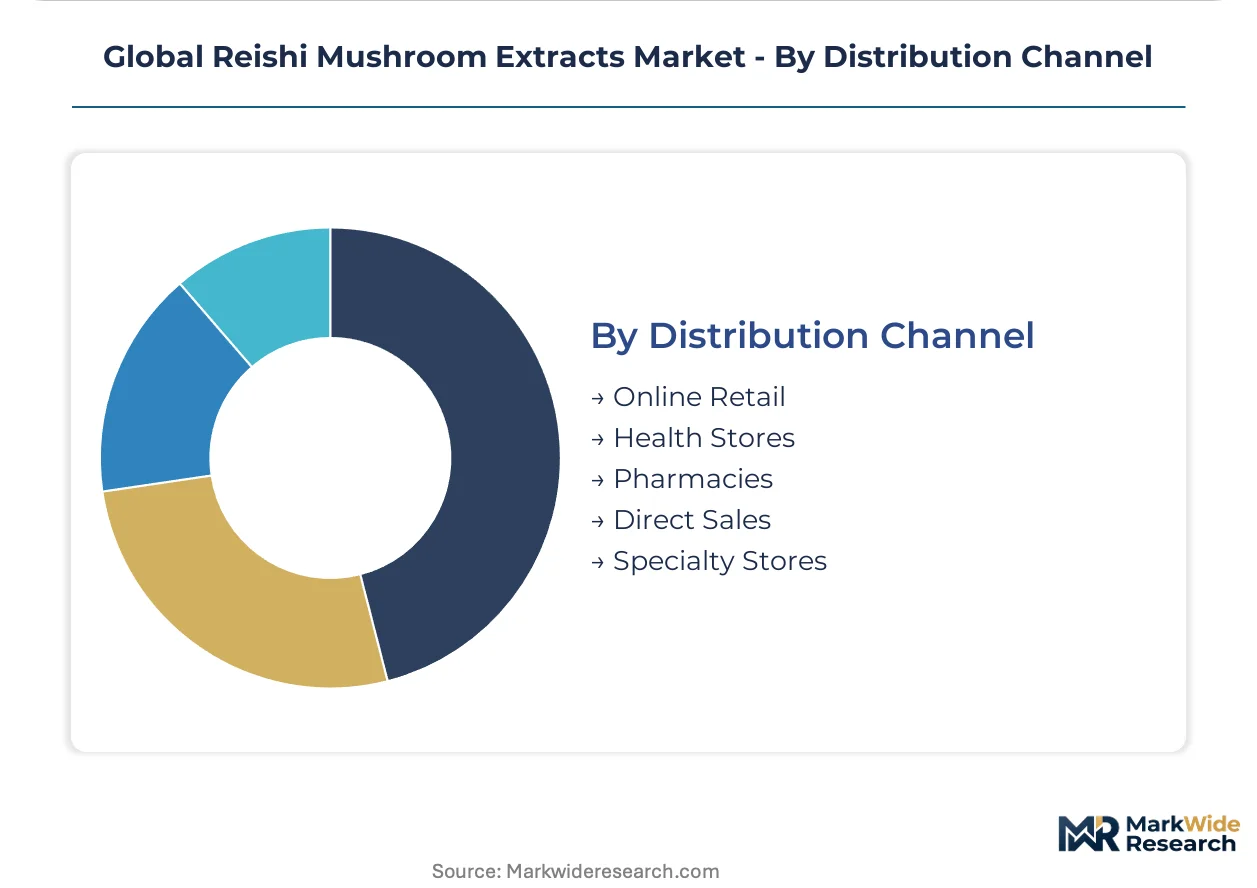
Distribution Channel:
Geographic concentration of procurement behavior shapes channel strategy, with Asia-Pacific favoring direct selling and North America shifting toward consolidated online retail.
- Online Retail:Amazon, Tmall, and direct-to-consumer platforms capturing increasing finished-product share. US and Chinese e-commerce consolidation is compressing smaller brand visibility, favoring suppliers with marketing co-investment capabilities.
- Direct Sales:Person-to-person networks dominating Southeast Asian volume, particularly Malaysia and Indonesia. DXN Holdings and comparable integrated operators leverage cultivation-to-consumer control for margin capture.
- Health Stores:Specialty retailers in Germany, Australia, and Canada serving educated supplement consumers.
- Pharmacies:Formal retail channels expanding in Brazil and Mexico through ANVISA regulatory pathway maturation.
- Specialty Stores:Traditional Chinese medicine dispensaries and herbal apothecaries in China, Taiwan, and Hong Kong.
Online retail dominates transaction velocity. Direct sales is where margin expansion concentrates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China commands extraction-scale pricing power through concentrated toll-processing capacity, while Japan sustains premium positioning through pharmacopeial-grade cultivation protocols. This asymmetry shapes procurement patterns across North American and European nutraceutical channels.
China
Provincial extraction clusters in Zhejiang and Shandong process bulk volumes for international dietary supplement contract manufacturers. NMPA traditional medicine registration pathways channel domestic demand toward standardized triterpenoid fractions. The Yangtze River Delta concentration of third-party tolling facilities creates geographic single-point vulnerabilities for buyers dependent on steam-dependent hot-water extraction.
Japan
Kampo formulation demand and aging-population immune-modulation consumption sustain premium absorption for fruiting body-derived extracts. PMDA pharmacopeial standards enforce batch-level triterpenoid quantification that elevates compliance costs for import suppliers. Hokkaido cultivation zones leverage hardwood substrate protocols to differentiate terroir-based positioning in North Asian markets.
United States
FDA dietary supplement GMP enforcement and DSHEA label claim constraints shape procurement toward certified-organic bulk extract suppliers. Private-label manufacturers in California and Utah consolidate vendor lists to reduce audit burden, favoring cultivators with captive British Columbia growing operations. Amazon and direct-to-consumer platforms compress smaller brand visibility, elevating marketing co-investment requirements.
Germany
EFSA Novel Food assessments and pharmacy-channel regulatory compliance elevate documentation depth for extract suppliers targeting immunological positioning. REACH-compliant solvent recovery mandates reshape ethanol extraction economics, forcing capital deployment into closed-loop recovery systems. Bavarian and Baden-Württemberg toll processors absorb compliance costs through pharmacy-channel pricing power unavailable to commodity suppliers.
Canada
Health Canada Natural Health Product regulations and licensed herbalist network procurement sustain demand for liquid extract formats in practitioner-dispensed protocols. British Columbia wild-simulated cultivation operations leverage forestry substrate access to supply North American premium positioning. Vancouver and Toronto distribution hubs consolidate botanical ingredient purchasing through group purchasing organization frameworks.
Global Reishi Mushroom Extracts Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream. The vendor base stratifies between asset-light contract cultivators bypassing capital-intensive growing infrastructure and integrated operators controlling cultivation-to-extraction workflows. Three archetypes dominate: wild-simulated terroir-based suppliers defending premium positioning through substrate protocols; third-party toll processors aggregating biomass from fragmented cultivator networks; and direct-selling integrated operators capturing margin through person-to-person distribution. Competitive moves concentrate on geographic expansion into underpenetrated pharmacy channels and backward integration into captive cultivation to reduce supply volatility exposure.
Among Asia-Pacific integrated operators, Hokkaido Reishi Co. Ltd. and DXN Holdings Bhd occupy positions reflecting divergent geographic and channel strategies. North American supply anchors through Nammex exemplify wild-simulated protocol differentiation. Chinese extraction specialists including Xian Yuensun Biological Technology Co., Ltd. and Xi'an Greena Biotech Co., Ltd. represent scale-driven toll-processing concentration. European positioning flows through Bristol Botanicals Limited as a compliance-heavy pharmacy-channel supplier. These named entities serve as archetype anchors rather than exhaustive market coverage.
| Leading Market Players |
|---|
| Bio-Botanica Inc. |
| Hokkaido Reishi Co. Ltd. |
| Nammex |
| Bristol Botanicals Limited |
| Qingdao Dacon Trading Co., Ltd. |
| Xian Yuensun Biological Technology Co., Ltd. |
| DXN Holdings Bhd |
| Xi'an Greena Biotech Co., Ltd. |
| Aloha Medicinals |
| Others |
Supply & Pricing Matrix
Zhejiang and Shandong extraction clusters command downstream pricing power through concentrated hot-water and ethanol processing capacity, enabling toll processors to capture margin premiums during peak procurement cycles from North American and European dietary supplement contract manufacturers.
Pricing Analysis
Configured-to-order pricing for pharmacopeial-grade triterpenoid-standardized extracts commands a substantial premium over standard polysaccharide concentrates. Three-tier pricing structure across premium, standard, and economy levels reflects divergence in certification depth, with organic and ISO 22000 tiers extracting buyer premiums. Cost compression in commodity powdered extracts is intensifying because hardwood substrate volatility compresses wild-simulated cultivator margins. Dietary supplement contract manufacturers exhibit highest price sensitivity, while pharmaceutical companies pursuing NMPA botanical drug pathways demonstrate lowest sensitivity due to clinical validation requirements.
Supply Chain Analysis
Tariff exposure between the United States and China dominates supply chain risk calculations for North American nutraceutical buyers dependent on Zhejiang toll processing. Geographic supply concentrates in China, Japan, and Canada, with British Columbia wild-simulated operations and Hokkaido cultivation zones anchoring premium tier sourcing. Raw material dependencies center on hardwood logs, sawdust substrates, and ethanol solvents for extraction. Single-source vulnerability persists in third-party tolling networks clustered in specific Chinese provinces. Distribution runs through consolidated group purchasing organizations and direct-to-practitioner channels in parallel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market sits in early-cycle expansion as precision fermentation alternatives and cosmetic ingredient convergence open absorption channels beyond traditional nutraceutical applications.
For Market Incumbents: Pre-empt precision fermentation entrants by securing exclusive mycelium-derived supply agreements with North American bioreactor operators before substrate-agnostic alternatives erode terroir-based pricing power. Defend position through captive British Columbia cultivation expansion and simultaneous EFSA Novel Food dossier investment to lock pharmacy-channel access. Certification depth serves as the primary defensive moat against asset-light contract cultivators. For New Entrants and Emerging Players: Brazilian pharmacy channels offer the most penetrable white-space opportunity as ANVISA's functional food ingredient registry matures and formal retail pathways consolidate. Mexican pharmacy expansion and Australian licensed herbalist networks present secondary entry vectors with lower incumbent saturation. A direct-to-practitioner liquid extract positioning bypasses Amazon-driven brand visibility compression and captures premium pricing through practitioner-dispensed protocols. For Investors and Strategic Acquirers: Long-term, this sits as a platform consolidation play because regulatory divergence between pharmacopeial and food-grade pathways forces supplier specialization, creating roll-up opportunities for compliance-heavy operators with parallel certification portfolios. Acquisition targets should demonstrate captive cultivation, in-house extraction, and existing EFSA or NMPA dossier progress. The signal to watch is hospital procurement committee consolidation through group purchasing organizations, which will elevate clinical trial backing requirements and separate investable operators from commodity suppliers.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Captive Cultivation | Reduces hardwood substrate volatility exposure for British Columbia and Hokkaido operators. |
| EFSA Novel Food Dossier Investment | Unlocks pharmacy-channel pricing power in Germany and France ahead of commodity competitors. |
| Precision Fermentation Partnership | Virtualizes geographic production advantages and hedges climate-dependent supply risk. |
| Direct-to-Practitioner Channel Development | Bypasses Amazon consolidation and captures margin through Australian and Canadian herbalist networks. |
| Cosmetic Ingredient Certification | Positions ethanol-extracted triterpenoid fractions for South Korean and French beauty brand absorption. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with extraction facility operators, dietary supplement contract manufacturing procurement leads, regulatory affairs specialists at NMPA and EFSA, and licensed herbalist network coordinators; alongside secondary validation through FDA dietary supplement GMP inspection records, EFSA Novel Food assessment databases, Chinese customs trade data for mushroom extract exports, and Health Canada Natural Health Product licensing registries. Bottom-up cultivation and extraction capacity modeling triangulated against top-down finished product demand estimation.
Forecast inputs considered product type segmentation across powdered extract, liquid extract, and finished dosage forms; application segmentation spanning dietary supplements, cosmetic ingredients, and herbal medicines; and end-user segmentation distinguishing contract manufacturers from pharmaceutical developers and personal care formulators. CAGRs derived from volume absorption trajectories across these dimensions, incorporating hardwood substrate cost cycle assumptions, regulatory pathway maturation timelines, and channel consolidation patterns specific to Reishi extract procurement.
Practitioners should monitor EFSA Novel Food assessment throughput rates, NMPA botanical drug registration velocity, and precision fermentation scale-up announcements for early signals of supply structure transformation. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Chia-Based Protein Market
Nutritional Supplements
Europe Nutritional Beverages Market
Nutritional Supplements
Canada Protein Market
Nutritional Supplements
Global Liver Health Supplements Market
Nutritional Supplements
High-Concentrated Protein Market
Nutritional Supplements
Apo-8 Carotenal Market
Nutritional Supplements
Vitamins and Minerals Market
Nutritional Supplements
Global Algal DHA and ARA Market
Nutritional Supplements
Horehound Supplement Market
Nutritional Supplements
Australia Collagen Peptides Market
Nutritional Supplements
Spain Whey Protein Market
Nutritional Supplements
Calcium Supplements Market
Nutritional Supplements
Coral Calcium Market
Nutritional Supplements
Vegetable Capsules Market
Nutritional Supplements
Native Whey Protein Market
Nutritional Supplements
Bone Supplements Market