

Cordless Wood Planer Market Size, Share, and Industry Trends Forecast 2026-2036
Cordless Wood Planer Market Insights
Lithium-ion battery cell chemistry is shifting from traditional cobalt-heavy formulations toward nickel-manganese alternatives that cut pack costs for cordless wood planers. Bosch leverages its established battery platform to anchor professional loyalty across European woodworking trades. Makita competes through dense distribution networks in Japanese construction supply channels. Milwaukee Tool differentiates via brushless motor thermal management systems engineered for sustained load conditions.
A cordless wood planer is a handheld surfacing tool driven by a battery-powered motor, typically spinning a cylindrical cutter head at speeds between 10,000 and 16,000 RPM to remove material in increments measured in sixty-fourths of an inch; its primary purpose is to dimension lumber, smooth rough stock, and create uniform thickness across boards in field or shop environments. Compact planers occupy the fastest-expanding tier as mobile contractors prioritize reduced tool bag weight and single-hand operation. Heavy-duty units sustain the deepest margin pools where professional carpenters pay premiums for chip ejection efficiency and extended runtime on hardwood species. Brushless motor technology leads all technology segments for replacement velocity as users trade up from brushed units seeking longer service intervals.
FCC equipment authorization governs electromagnetic emissions from cordless tool electronics sold in the United States, while EPA hazardous waste rules shape end-of-life battery collection obligations for manufacturers and retailers. REACH chemical restrictions in Europe limit certain substances in tool housings and battery contacts, redirecting material choices toward compliant polymer formulations. Stakeholders must monitor how evolving battery transport regulations and extended producer responsibility frameworks reshape supply chain costs and regional product availability.
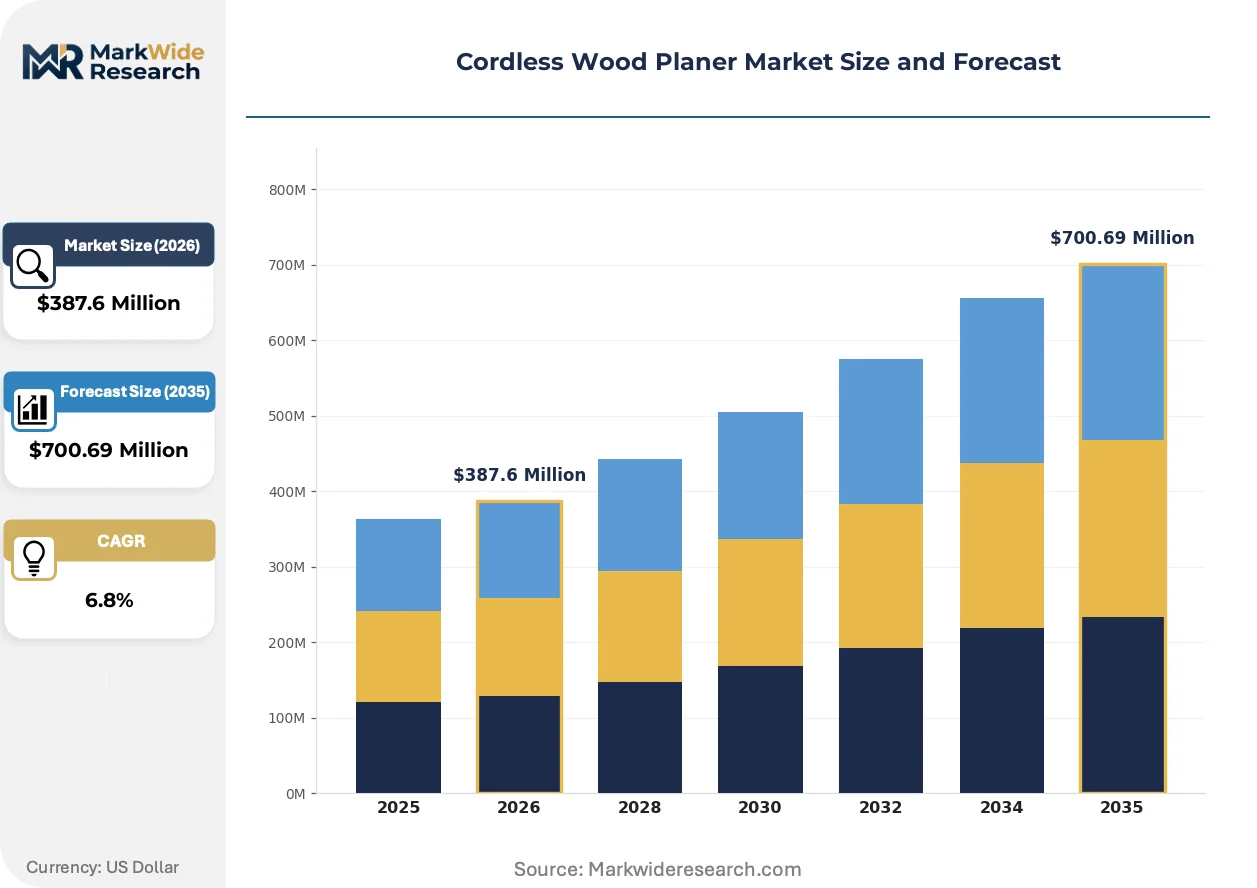
Market Dynamics
Brushless motor replacement cycles are compressing product lifespans across professional woodworking fleets as thermal efficiency gains justify premature trade-ins of functional brushed units.
Growth Catalysts
- Brushless motor thermal management:Extended runtime under sustained hardwood loads reduces jobsite downtime for professional carpenters in Japan and Germany.
- REACH chemical compliance:European polymer reformulation mandates accelerate housing material upgrades that improve tool durability and user safety ratings.
- Mobile contractor density:Single-hand operation demand from renovation specialists in the United States drives compact planer SKU expansion.
Market Restraints
- Lithium cell cost volatility:Nickel-manganese cathode price swings compress margin pools for battery pack suppliers serving mid-tier tool OEMs.
- Platform lock-in effects:Major power tool ecosystems create switching costs that fragment addressable demand for standalone planer entrants.
- Chip ejection physics:Compact form factors face hard limits on debris clearance velocity, constraining cut depth in dense hardwood applications.
Strategic Opportunities
- Japanese construction supply channels:Dense distribution networks in prefectural hardware cooperatives remain underpenetrated by European battery platform competitors.
- EPA hazardous waste frameworks:Extended producer responsibility rules create first-mover advantages for OEMs building closed-loop battery collection infrastructure.
- Smart torque sensing convergence:Integration of load-responsive electronics with brushless controllers enables premium pricing for hardwood-specific auto-feed calibration.
Industry Challenges
- Brushless controller firmware certification:FCC equipment authorization timelines for electromagnetic compliance delay product launches by 4-6 months.
- Cross-platform battery interoperability:Voltage architecture standardization conflicts with proprietary connector designs complicate third-party accessory development.
Report Scope
MarkWide ResearchGet the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cordless Wood Planer Market Trends and Innovations
Tool intelligence is migrating from the workshop to the jobsite as embedded electronics enable real-time performance adjustment without operator intervention.
Brushless motor controllers with integrated thermal feedback loops are absorbing operator judgment functions previously handled through manual feed pressure. Professional carpenters in Germany adopt these systems fastest, replacing tactile skill with automated load compensation. The technology is absorbing margin from premium hand-tool categories while compressing training requirements for apprentice tradespeople.
REACH substance restrictions on cobalt and cadmium in battery contacts force European manufacturers toward nickel-plated copper alternatives with higher contact resistance tolerances. Tool housing polymer suppliers reformulate flame-retardant compounds to meet evolving ECHA thresholds. German professional channels show strongest compliance-driven preference shifts toward certified sustainable product lines.
Hardware cooperative procurement in Japan consolidates purchasing authority from individual contractors toward prefectural-level buying consortia. These aggregators negotiate battery platform exclusivity in exchange for volume commitments, displacing traditional distributor markups. The behavioral shift concentrates demand planning power with construction supply intermediaries rather than end-user jobsite crews.
Cordless Wood Planer Market Segmentation
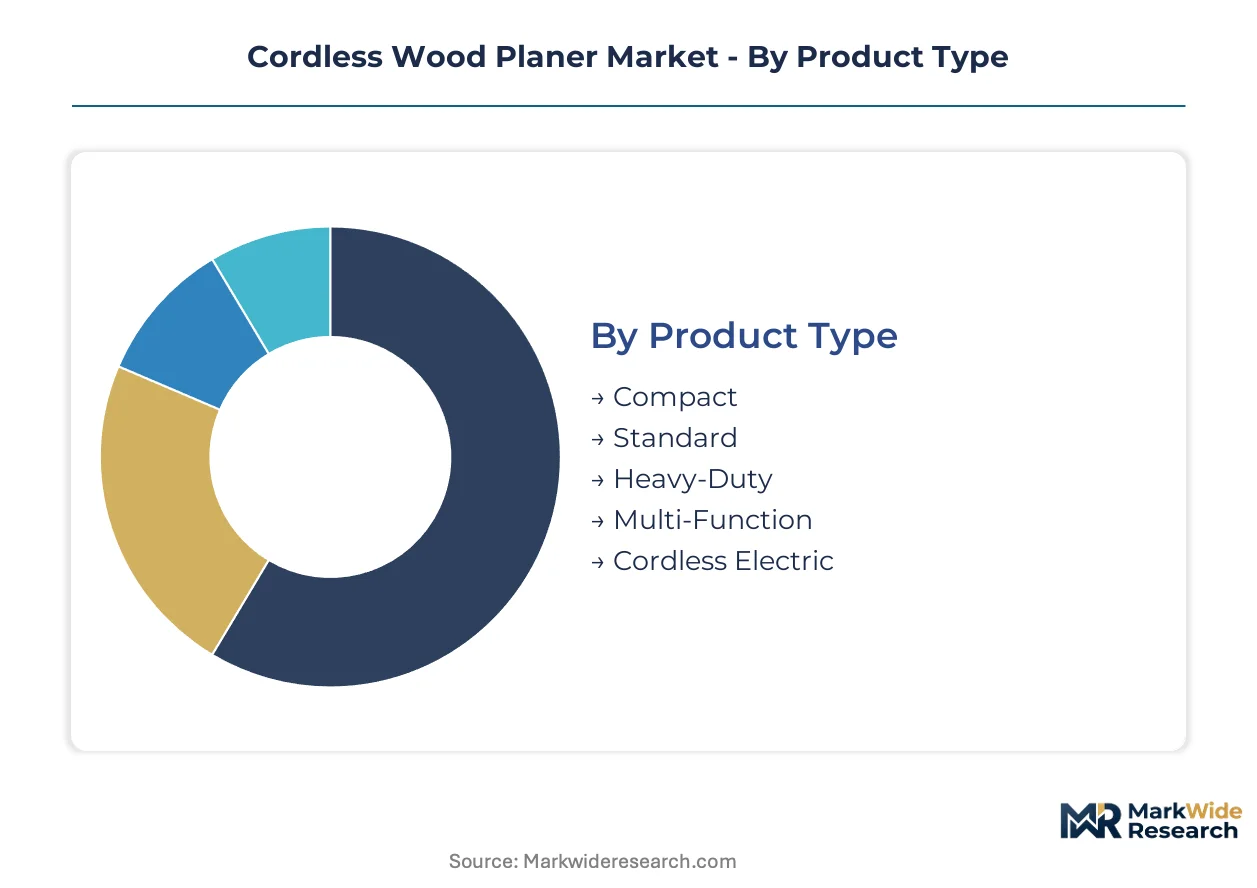
Cordless wood planer segmentation reflects divergent performance requirements across jobsite mobility and workshop precision. Product architecture choices cascade through motor technology, battery chemistry, and end-use durability specifications.
Product Type:
Customization intensity spans from standardized compact units to engineered heavy-duty platforms with thermal management systems.
- Compact:Single-hand operation design reduces tool bag weight below 2.5 kg for renovation specialists traversing multi-story residential sites. Demand concentrates in United States metropolitan construction corridors where elevator access constraints favor reduced bulk.
- Heavy-Duty:Reinforced cutter head bearings and extended chip ejection chutes sustain 3 mm depth-of-cut capacity in dense hardwood species. German professional carpenters pay premiums for runtime continuity on oak and beech dimensioning tasks.
- Standard:Balanced weight-to-power ratio serves mixed-material workshops with intermittent surfacing needs.
- Multi-Function:Interchangeable base plates extend utility to chamfering and rabbeting operations.
- Cordless Electric:Battery-native architecture eliminates cord management for field fabrication.
Most installed capacity flows through Standard units. Expansion is steepest in Compact.
Technology:
Cost tier stratification separates premium brushless thermal management from value-oriented brushed alternatives.
- Brushless Motor:Electronic commutation eliminates brush wear while enabling real-time thermal feedback loops for sustained hardwood loads. Japanese construction supply channels show fastest replacement velocity as contractors trade functional brushed units prematurely.
- Lithium-Ion Battery:Nickel-manganese cathode formulations from major power tool ecosystems standardize voltage architectures across professional fleets. REACH chemical compliance redirects European suppliers toward cobalt-reduced cell chemistries.
- Nickel-Cadmium Battery:Legacy platform retention in price-sensitive hobbyist segments.
- Brush Motor:Simpler controller requirements suit entry-tier SKUs with shorter duty cycle expectations.
- Variable Speed:Load-responsive RPM adjustment prevents tear-out in figured grain patterns.
Volume concentrates in Lithium-Ion Battery configurations. Margin expansion is most pronounced in Brushless Motor.
Application:
Customer type determines durability specifications across stationary workshop and mobile field environments.
- Construction Sites:Dust-sealed electronics and impact-resistant housings withstand uncontrolled outdoor conditions. United States general contractors prioritize rapid blade change systems minimizing downtime between rough lumber batches.
- Furniture Manufacturing:Precision thickness tolerance requirements demand rigid bed construction and minimal vibration transmission. German mid-size workshops specify planers with sub-0.1 mm repeatability for table top glue-up preparation.
- Woodworking Shops:Mixed-use environments balancing portability with bench-mounted stability.
- Cabinet Making:Narrow stock processing favors shorter bed lengths with enhanced chip clearance.
- DIY Projects:Occasional-use tolerance for reduced runtime and slower material removal rates.
Revenue concentration sits with Furniture Manufacturing. Volume growth is strongest in Construction Sites.
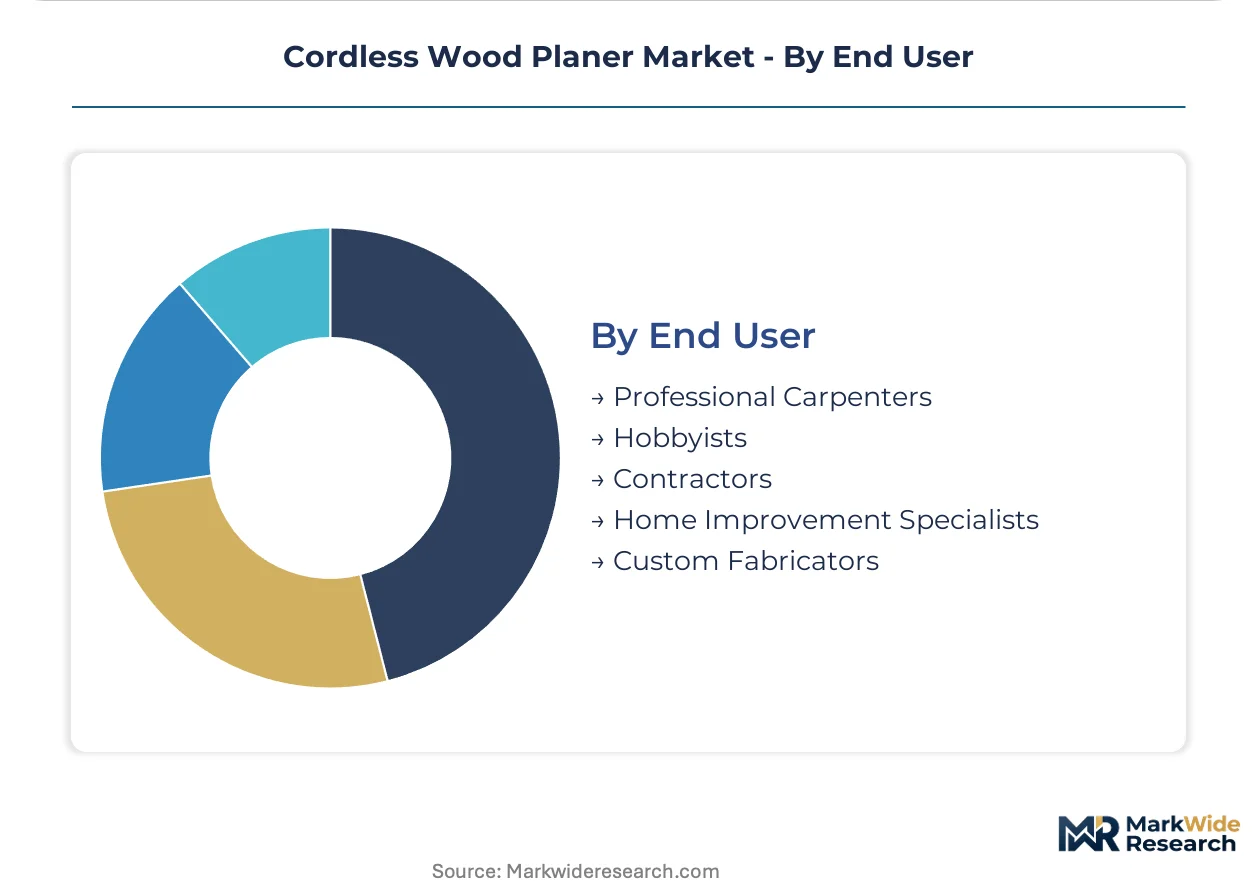
End User:
Procurement authority separates individual purchasing decisions from fleet-standardized corporate buying.
- Professional Carpenters:Tool fleet standardization on single battery platforms reduces charger redundancy across circular saws, routers, and planers. Japanese prefectural hardware cooperatives negotiate platform exclusivity consolidating demand planning power.
- Contractors:Durability specifications prioritize survival in multi-trade jobsite conditions with abrasive dust exposure.
- Custom Fabricators:Specialized surfacing requirements for reclaimed lumber with embedded fasteners demand enhanced cutter head protection systems.
- Home Improvement Specialists:Balanced performance-to-weight ratios for residential trim and finish carpentry.
- Hobbyists:Price sensitivity favors brushed motor configurations with shorter warranty terms.
Replacement cycle velocity peaks among Professional Carpenters. New entrant acquisition concentrates in Hobbyists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German professional woodworking clusters anchor cordless wood planer demand through dense networks of mid-size workshops and mobile carpentry contractors. Battery platform standardization across construction supply channels accelerates replacement cycles in mature tool markets. Regulatory frameworks in three major economies reshape material specifications and distribution economics.
United States
Metropolitan renovation corridors drive compact planer demand where elevator access constraints favor reduced tool bag weight. FCC equipment authorization timelines for electromagnetic compliance delay product launches by four to six months. Dallas-Fort Worth construction supply hubs concentrate procurement authority among general contractors prioritizing rapid blade change systems.
Germany
REACH chemical restrictions on cobalt and cadmium redirect battery contact materials toward nickel-plated copper alternatives with higher resistance tolerances. ECHA threshold evolution forces housing polymer reformulation toward flame-retardant compounds with improved durability ratings. Stuttgart industrial zones host precision woodworking equipment distributors negotiating battery platform exclusivity with prefectural cooperatives.
Japan
Prefectural hardware cooperative procurement consolidates individual contractor purchasing toward volume-driven battery platform commitments. METI industrial standards govern power tool electromagnetic emissions and thermal safety certification requirements. Osaka-Kobe construction supply channels concentrate demand planning authority with intermediaries rather than end-user jobsite crews.
China
Domestic lithium-ion cell manufacturing expansion reduces pack cost volatility for tool OEMs serving mid-tier market segments. GB standards and MIIT regulations shape cordless tool electromagnetic compatibility and battery transport safety protocols. Yangtze River Delta industrial clusters integrate brushless motor controller production with downstream power tool assembly operations.
Cordless Wood Planer Market Competitive Landscape
Platform lock-in effects dominate the current landscape as major power tool ecosystems create switching costs that fragment addressable demand for standalone entrants. The vendor base organizes around three strategic tiers: integrated battery platform operators controlling charger and cell architecture, motor-technology specialists differentiating through thermal management firmware, and regional fabricators competing on price-adjusted portability metrics. M&A activity concentrates battery cell supply agreements while geographic expansion targets underpenetrated prefectural distribution networks.
Among diversified industrial equipment manufacturers, Bosch and Makita occupy positions exemplifying platform-centric competitive strategy, while Milwaukee Tool represents the thermal-management specialization archetype. Bosch leverages established battery architecture to anchor professional loyalty across European woodworking trades. Makita competes through dense presence in Japanese construction supply channels. Milwaukee Tool differentiates via brushless motor systems engineered for sustained load conditions in hardwood applications.
| Leading Market Players |
|---|
| Bosch |
| DeWalt |
| Makita |
| Milwaukee Tool |
| Metabo HPT |
| Einhell |
| Hitachi Koki |
| Ryobi |
| WEN Products |
| Others |
Pricing and Supply Chain Analysis
REACH chemical compliance gates qualified supply and premium-tier pricing access for cordless wood planer manufacturers serving European professional channels. ECHA-mandated cobalt and cadmium restrictions in battery contacts and housing polymers disqualify legacy suppliers while concentrating certified material sourcing among reformulation-capable compounders.
Pricing Analysis
Input-cost pass-through from nickel-manganese cathode volatility compresses margin pools for battery pack suppliers serving mid-tier tool OEMs. Three-tier pricing structure across premium, standard, and economy levels separates brushless thermal management systems from brushed motor alternatives and entry hobbyist units. Price differentiation hinges on certification grade and runtime specification under sustained hardwood loads. Cost compression in mid-tier configurations is intensifying because lithium cell chemistry shifts redirect R&D expenditure toward compliance rather than performance gains. Hobbyist segments exhibit highest price sensitivity; German professional carpenters demonstrate lowest sensitivity, paying premiums for runtime continuity.
Supply Chain Analysis
Warehouse-distribution layer consolidation in Japanese prefectural hardware cooperatives concentrates inventory positioning near Osaka-Kobe construction supply channels. Brushless motor controller production centers on China, Japan, and Germany, with Yangtze River Delta clusters integrating upstream semiconductor fabrication with downstream power tool assembly. Raw material dependencies include rare earth magnets for rotor assemblies, nickel-manganese cathode active materials, and flame-retardant polymer compounds for housings. Single-source vulnerability concentrates in advanced thermal management firmware licensing. Distribution runs through construction supply intermediaries rather than direct-to-contractor models in Japan and Germany.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Professional carpenters in Germany and Japan are trading functional brushed units prematurely for brushless thermal management systems, concentrating replacement demand on premium specifications.
For Market Incumbents: To counter platform lock-in effects from rival battery ecosystems, anchor professional loyalty through backward integration into nickel-manganese cell supply agreements and exclusive distribution partnerships with prefectural hardware cooperatives. Prioritize REACH-compliant polymer certification to maintain European channel access. For New Entrants and Emerging Players: Launch via direct-to-contractor digital channels targeting underpenetrated Japanese prefectural cooperatives outside Osaka-Kobe and Tokyo corridors. White-space concentrates in compact planer SKUs for United States metropolitan renovation specialists prioritizing single-hand operation. Differentiate through cross-platform battery adapter systems that reduce switching costs for locked-in users. For Investors and Strategic Acquirers: Roll-up economics work for brushless motor controller specialists because thermal management firmware IP is consolidating among three dominant ecosystems. Five-to-ten year viability favors targets with captive semiconductor sourcing relationships and METI certification track records. Signal to monitor: EPA hazardous waste framework implementation timelines affecting closed-loop battery collection infrastructure valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cell Chemistry | Nickel-manganese cathode captive supply secures margin pools against raw material volatility. |
| Prefectural Cooperative Exclusivity Agreements | Japanese construction supply channel concentration rewards volume-commitment negotiating leverage. |
| REACH-Compliant Polymer Certification | ECHA threshold adherence gates European professional distribution and premium pricing tiers. |
| Cross-Platform Battery Adapter Development | Proprietary connector circumvention reduces switching costs for locked-in contractor fleets. |
| Closed-Loop Battery Collection Infrastructure | EPA extended producer responsibility rules create first-mover service differentiation advantages. |
Research Methodology
Direct dialogue with brushless motor R&D directors, professional carpentry fleet managers, construction supply procurement leads, and power tool platform engineers grounded qualitative findings in operational reality. Secondary validation drew from FCC equipment authorization databases, ECHA substance restriction updates, METI industrial standard filings, and customs trade records for lithium-ion cell imports. Bottom-up unit economics triangulated against top-down construction spending correlations.
Segment-level outputs across product type, motor technology, battery chemistry, end-use application, and customer procurement authority fed into the analytical framework over the projection horizon. CAGRs derived from replacement cycle velocity modeling in professional versus hobbyist segments, with brushless motor trade-in rates and REACH compliance cost pass-through as industry-specific forecast inputs.
Forecast precision tightens around the base case; tail outcomes carry wider variance under lithium cell cost volatility and extended producer responsibility framework acceleration. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.