
 Global 5G Enterprise Market | 2026-2036
Global 5G Enterprise Market Size, Share, and Industry Trends Forecast 2026-2036
Global 5G Enterprise Market Foresight
Single-source infrastructure procurement is decoupling from legacy telecom vendor relationships as enterprises pursue multi-vendor interoperability. Cisco Systems leverages its software-defined networking portfolio to anchor campus deployments across North American manufacturing sites. Nokia competes through specialized private networking solutions that sustain its position in European industrial automation corridors.
Global 5G Enterprise encompasses dedicated cellular networks operating in sub-6 GHz and mmWave spectrum bands with latency thresholds below 10 milliseconds, engineered to replace or augment Wi-Fi in mission-critical operational environments. Network Slicing generates the deepest margin pools by enabling virtualized quality-of-service guarantees across shared physical infrastructure. Edge Computing represents the fastest-expanding segment as enterprises push inference workloads closer to robotic control systems and automated quality inspection stations.
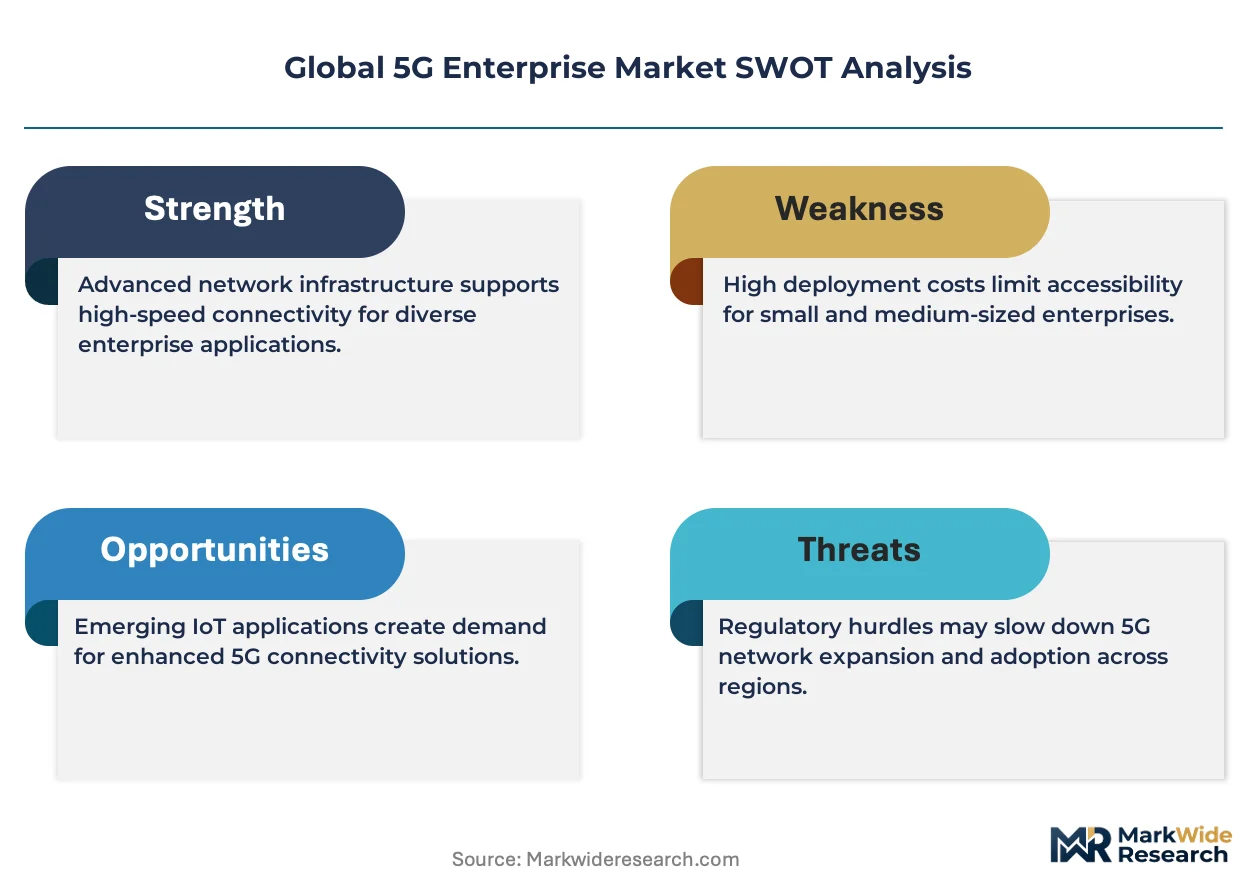
The FCC's CBRS spectrum framework in the United States and the EU's 5G PPP funding instruments collectively shape enterprise deployment economics by lowering barriers to private network ownership. Germany's BNetzA enforces strict local spectrum licensing conditions that direct infrastructure investment toward industrial parks rather than metropolitan consumer zones. Stakeholders must monitor evolving national spectrum auction designs that determine whether enterprises obtain direct licensing authority or remain dependent on operator intermediation.
Market Dynamics
Private spectrum licensing frameworks are fragmenting procurement authority away from traditional mobile network operators toward industrial end-users, forcing infrastructure vendors to rearchitect go-to-market channels and service delivery models.
Growth Catalysts
- CBRS Spectrum Framework:The FCC's three-tiered access model in the United States grants enterprises direct control over 3.5 GHz bands, bypassing carrier intermediation for campus and factory deployments.
- Industrial Automation Demand:Automotive assembly lines in Germany's Baden-Württemberg region are mandating sub-10 millisecond latency for robotic coordination, pulling private 5G infrastructure into brownfield manufacturing sites.
- Network Slicing Maturation:Virtualized quality-of-service partitioning now enables shared infrastructure to host both mission-critical operational technology and administrative traffic on identical radio hardware.
Market Restraints
- Radio Unit Cost Concentration:Specialized massive MIMO antenna arrays and baseband units remain concentrated among a handful of semiconductor foundries, exposing deployment budgets to silicon supply volatility.
- Spectrum Coordination Complexity:Germany's BNetzA local licensing conditions impose geographic exclusion zones that complicate multi-site enterprise rollouts across adjacent industrial parks.
- Wi-Fi 6E Substitution:Unlicensed 6 GHz wireless systems offer sufficient throughput for non-latency-sensitive applications, compressing addressable market scope for lighter-use enterprise segments.
Strategic Opportunities
- Indian Manufacturing Corridors:The country's PLI scheme for electronics and automotive sectors is channeling capital toward Tamil Nadu and Gujarat industrial zones where private cellular infrastructure remains nascent.
- Edge-Cloud Convergence:Integration of containerized compute nodes with radio access networks creates bundled offerings for predictive maintenance and computer vision quality inspection.
- Open RAN Policy Mandates:Japan's METI interoperability requirements for public networks are spilling into enterprise procurement specifications, opening vendor selection to specialized radio software providers.
Industry Challenges
- RF Engineering Talent Scarcity:Enterprise IT departments lack personnel trained in propagation modeling, interference mitigation, and spectrum analysis for industrial radio deployments.
- Legacy OT Integration Friction:Brownfield facilities running Modbus and PROFINET fieldbus protocols require protocol translation gateways that introduce latency and single points of failure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global 5G Enterprise Market |
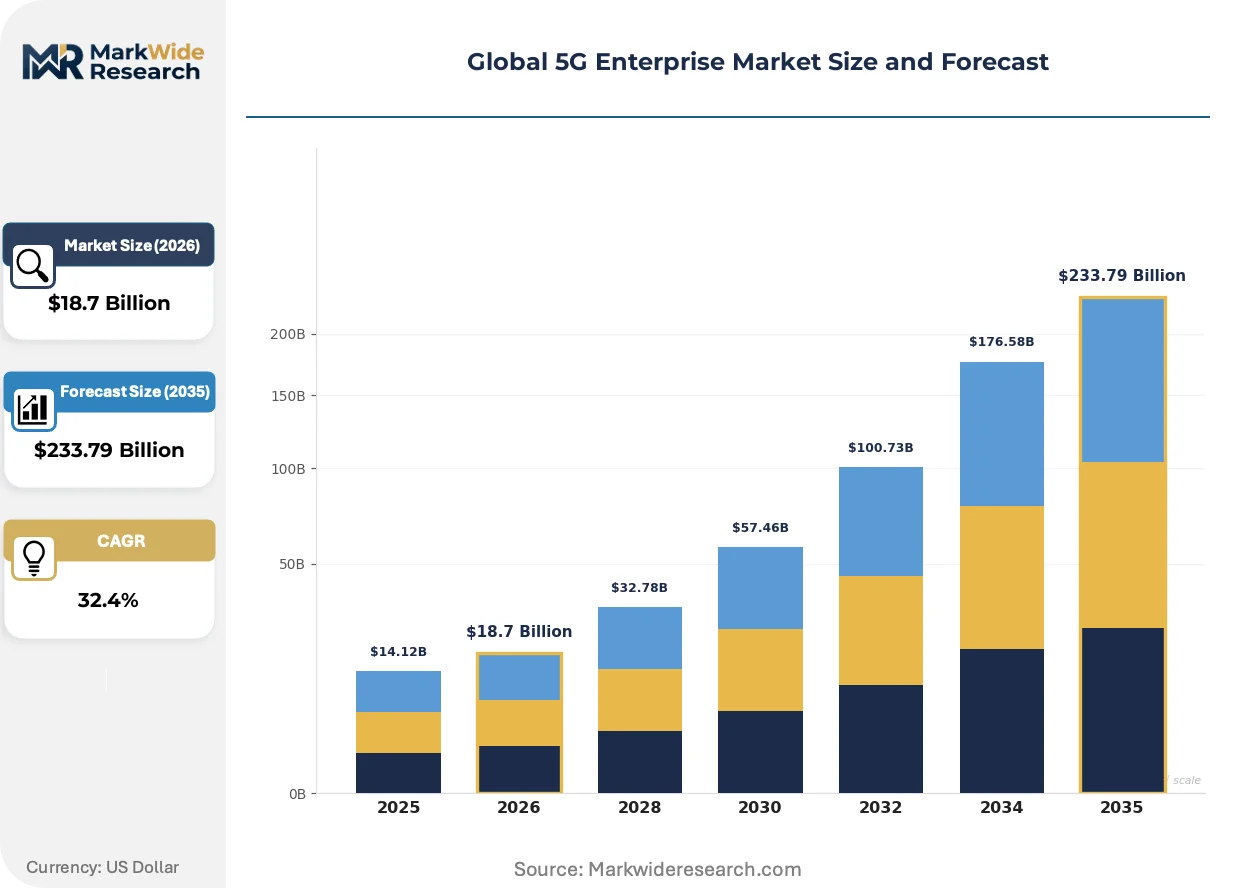
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $233.79 Billion |
| CAGR (2026 – 2036) | 32.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Solution Type: Network Slicing, Edge Computing, Massive MIMO, Enhanced Mobile Broadband, Ultra-Reliable Low Latency Communication, Private Networking Industry Vertical: Manufacturing, Logistics, Smart Cities, Energy & Utilities, Media & Entertainment, Government Agencies Deployment Model: On-Premises, Cloud-Based, Hybrid, Managed Services End User Type: Enterprises, System Integrators, Telecom Operators, Technology Providers |
| Companies Covered | Cisco Systems, Inc., Telefonaktiebolaget LM Ericsson, Nokia, Huawei Technologies Co., Ltd., Samsung, ZTE Corporation, Qualcomm Technologies, Inc., NEC Corporation, Juniper Networks, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global 5G Enterprise Market Shifts & Advancements
Open radio access network architectures are dissolving vendor lock-in across enterprise deployments, enabling mixing of radio units, baseband software, and management platforms from disparate suppliers.
Virtualized distributed unit and centralized unit functions are decentralizing hardware requirements at cell sites, allowing enterprises to deploy lightweight radio heads while hosting signal processing in on-premise edge data centers. Mining operations in Western Australia's Pilbara region are adopting this architecture to cover vast pit-to-port haulage routes without maintaining full base stations at each access point. The shift is compressing total cost of ownership for wide-area private networks spanning multiple square kilometers.
The EU's Cyber Resilience Act imposes mandatory security update obligations and vulnerability disclosure timelines on radio equipment manufacturers selling into European enterprise markets. Industrial automation vendors must now maintain software support lifecycles extending beyond traditional hardware refresh cycles. German chemical producers in the BASF Ludwigshafen complex are rewriting procurement specifications to mandate attestation of twenty-year security patch commitments.
Enterprise buyers are consolidating vendor relationships around systems integrators capable of delivering radio, transport, core, and application layers as unified operational outcomes. This displaces the historical pattern of separate procurement for connectivity and software platforms. South Korean shipbuilders at DSME's Okpo yard are contracting single-source responsibility for private 5G coverage, edge computing infrastructure, and digital twin visualization tools.
Global 5G Enterprise Market Segmentation
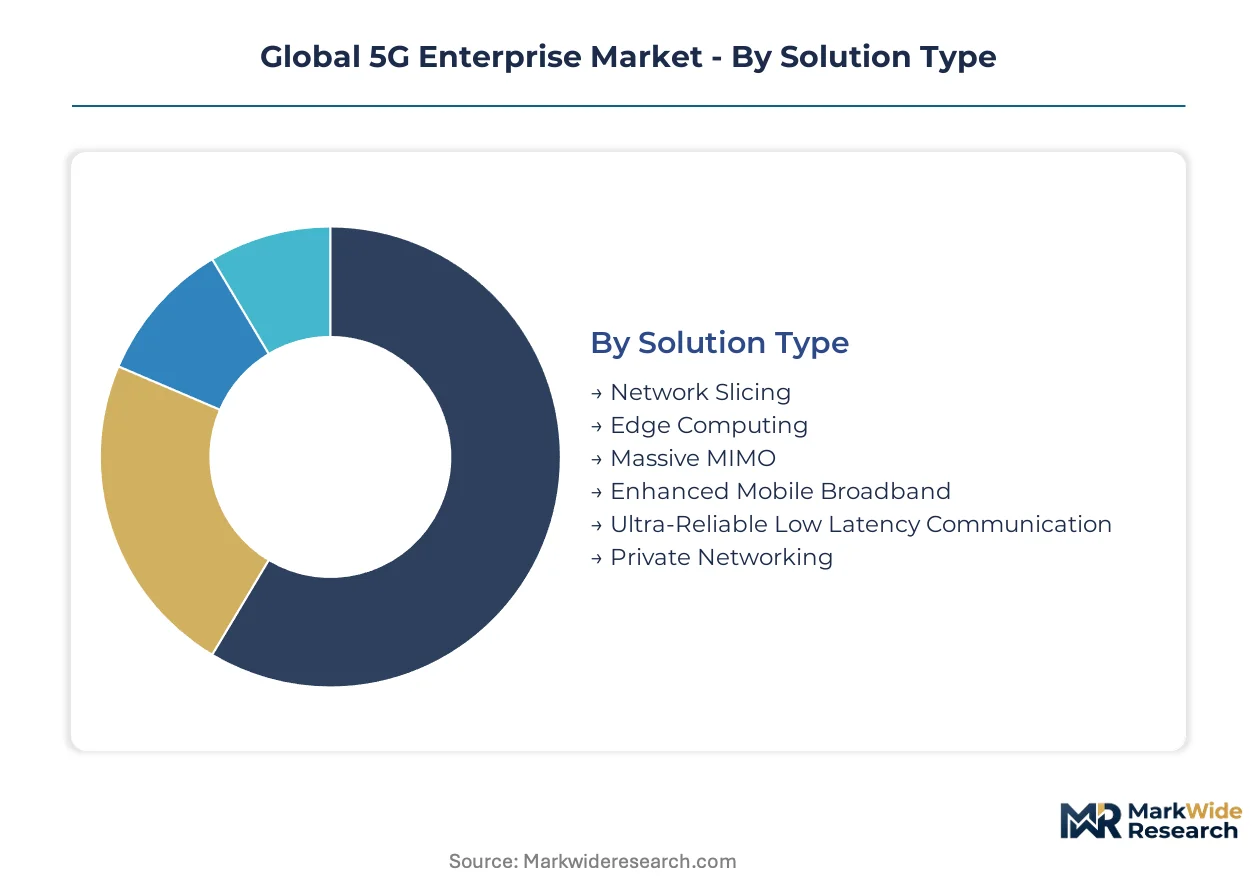
Enterprise 5G procurement patterns diverge sharply across technical architectures and operational contexts. Solution type determines integration complexity and margin structure. Industry vertical shapes latency requirements and spectrum licensing strategies.
Solution Type:
Spectrum utilization and virtualization depth define the technical axis for enterprise cellular infrastructure.
- Network Slicing:Virtualized quality-of-service partitioning enables simultaneous operation of mission-critical OT traffic and administrative data on shared radio hardware. Demand concentrates in German automotive complexes where BMW and Volkswagen mandate guaranteed bandwidth for robotic coordination. FCC spectrum frameworks in the United States accelerate slicing adoption by granting enterprises direct licensing authority.
- Edge Computing:Containerized compute nodes collocated with radio access networks host inference workloads for predictive maintenance and automated quality inspection. South Korean shipbuilders at DSME's Okpo yard deploy edge-integrated private 5G for digital twin visualization of vessel assembly. BNetzA licensing conditions in Germany channel investment toward industrial parks with edge-ready infrastructure.
- Massive MIMO:Antenna arrays with 64+ elements deliver spectral efficiency in dense factory environments.
- Enhanced Mobile Broadband:High-throughput connectivity serves non-latency-sensitive enterprise applications including video surveillance and campus Wi-Fi offloading.
- Ultra-Reliable Low Latency Communication:Sub-10 millisecond transmission intervals enable closed-loop robotic control and autonomous guided vehicle coordination.
- Private Networking:Dedicated cellular infrastructure operating on licensed, unlicensed, or shared spectrum bands replaces or augments Wi-Fi in security-sensitive operational zones.
Mature deployment sits with Enhanced Mobile Broadband. Newer deployment is concentrated in Edge Computing.
Industry Vertical:
Operational technology maturity and automation intensity shape vertical adoption curves.
- Manufacturing:Brownfield assembly lines in Germany's Baden-Württemberg region mandate sub-10 millisecond latency for robotic coordination, pulling private 5G into legacy facilities. India's PLI scheme for electronics and automotive sectors channels capital toward Tamil Nadu and Gujarat industrial zones where cellular infrastructure remains nascent. Modbus and PROFINET fieldbus protocol translation requirements complicate OT integration.
- Logistics:Automated warehouse management and yard operations drive demand for wide-area coverage with deterministic handoff performance. Mining operations in Western Australia's Pilbara region adopt virtualized distributed unit architectures to cover vast pit-to-port haulage routes without full base stations at each access point.
- Smart Cities:Municipal infrastructure deployments prioritize cost efficiency over latency guarantees.
- Energy & Utilities:Grid modernization and remote asset monitoring applications favor ruggedized radio equipment with extended temperature tolerances.
- Media & Entertainment:Live production and venue connectivity exploit high-throughput capabilities for broadcast contribution and fan engagement.
- Government Agencies:Security-cleared deployments emphasize supply chain attestation and domestic vendor preferences.
Deployment volume concentrates in Manufacturing. Steepest expansion trajectory appears in Logistics.
Deployment Model:
Capital structure and operational control preferences segment procurement approaches.
- On-Premises:Enterprises retain full ownership of radio, transport, and core network elements. German chemical producers at BASF's Ludwigshafen complex rewrite procurement specifications to mandate twenty-year security patch commitments under EU Cyber Resilience Act obligations.
- Cloud-Based:Network functions virtualization shifts baseband processing to hyperscaler facilities. South Korean industrial zones anchor testbed ecosystems where Samsung and SK Telecom deliver cloud-native 5G cores.
- Hybrid:Split architectures host latency-sensitive functions on-premise while backhauling administrative traffic to cloud facilities.
- Managed Services:System integrators assume operational responsibility for radio planning, optimization, and lifecycle maintenance.
Procurement authority is fragmenting toward On-Premises ownership. Managed Services capture mid-market entrants lacking RF engineering capacity.
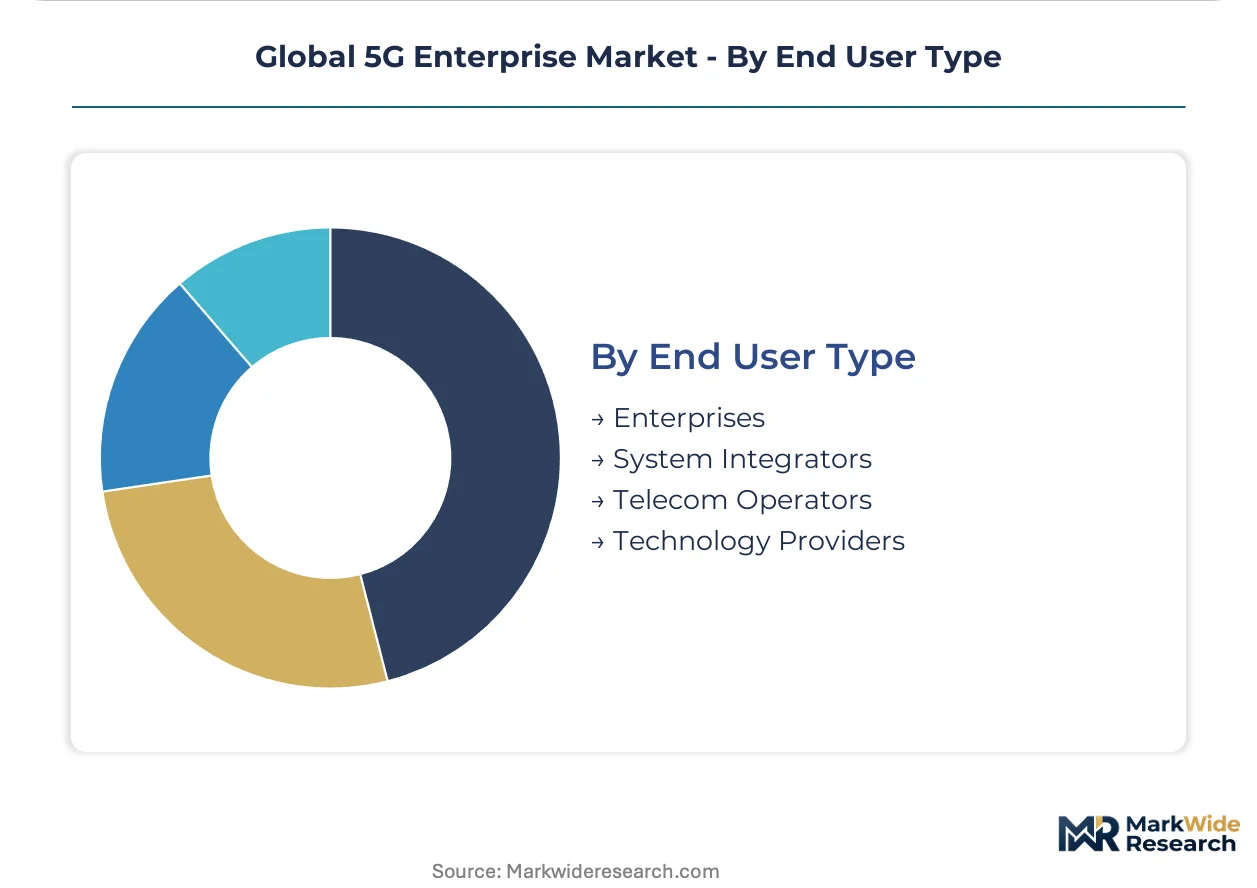
End User Type:
Value chain position determines technical specification authority and budget control.
- Enterprises:Industrial end-users in Germany's automotive corridor and India's manufacturing belts drive direct spectrum licensing demand. BNetzA local licensing conditions and FCC CBRS frameworks enable bypass of traditional carrier intermediation.
- System Integrators:Consolidated vendor relationships around unified radio, transport, core, and application delivery displace separate connectivity and software procurement.
- Telecom Operators:Traditional mobile network operators defend position through managed private network offerings and spectrum lease arrangements.
- Technology Providers:Specialized radio software vendors gain access through Japan's METI interoperability requirements spilling into enterprise procurement specifications.
Specification control concentrates with Enterprises. Fastest-growing influence belongs to System Integrators.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon design expertise in the United States and radio frequency component fabrication in Germany anchor geographic deployment patterns for enterprise cellular infrastructure. Spectrum allocation reforms and industrial automation mandates are fragmenting procurement authority toward end-users across multiple regulatory jurisdictions.
United States
Automotive assembly plants in Michigan and Tennessee are mandating deterministic wireless for robotic coordination, pulling private cellular into brownfield facilities. The FCC's CBRS three-tiered access model grants enterprises direct control over 3.5 GHz bands without carrier intermediation. Dallas-Fort Worth corridor hosts concentrated testbed activity where system integrators bundle radio infrastructure with edge computing deployments.
Germany
Chemical producers at BASF's Ludwigshafen complex and automotive OEMs in Baden-Württemberg are rewriting procurement specifications to mandate sub-10 millisecond latency guarantees. BNetzA enforces strict local spectrum licensing conditions that direct infrastructure investment toward industrial parks rather than metropolitan zones. Munich and Stuttgart anchor Europe's densest concentration of private 5G manufacturing deployments.
South Korea
Shipbuilders at DSME's Okpo yard and electronics manufacturers in Gyeonggi Province are contracting single-source responsibility for private cellular coverage and digital twin infrastructure. Samsung and SK Telecom anchor testbed ecosystems that channel vendor selection toward domestic equipment preferences. Busan-Ulsan industrial corridor represents the fastest-expanding addressable base for integrated edge-radio offerings.
India
Electronics and automotive sectors under the PLI scheme are channeling capital toward Tamil Nadu and Gujarat industrial zones where private cellular infrastructure remains nascent. TRAI consultations on enterprise spectrum direct licensing are creating regulatory momentum for bypassing traditional carrier intermediation. Sriperumbudur and Sanand manufacturing belts are emerging as early deployment clusters for automotive OEMs.
Japan
Machine tool builders in Nagoya's Chubu region and semiconductor fabricators in Kyushu are adopting open radio access architectures to dissolve vendor lock-in. METI interoperability requirements for public networks are spilling into enterprise procurement specifications. Yokohama and Osaka host concentrated systems integrator activity capable of delivering unified radio, transport, and application layers.
Global 5G Enterprise Market Competitive Landscape
Global majors compete with regional champions across spectrum access frameworks and integration depth, producing a tiered structure where scale-driven infrastructure vendors coexist with specialized radio software providers. The vendor base fragments across three strategic archetypes: integrated systems houses with end-to-end portfolios, component specialists focusing on semiconductors or antenna systems, and open-architecture enablers supplying disaggregated radio software. Dominant competitive moves include strategic partnerships with systems integrators and geographic expansion through spectrum licensing advisory services.
Within the integrated systems tier, Cisco Systems, Inc. and Nokia occupy positions that exemplify divergent geographic anchoring—San Jose-based Cisco leveraging software-defined networking portfolios across North American manufacturing sites, while Espoo-headquartered Nokia competes through specialized private networking solutions in European industrial automation corridors. Telefonaktiebolaget LM Ericsson represents the scale-driven archetype with Stockholm origins, sitting within the tier of vendors capable of delivering radio, transport, core, and managed service layers as unified operational outcomes.
| Leading Market Players |
|---|
| Cisco Systems, Inc. |
| Telefonaktiebolaget LM Ericsson |
| Nokia |
| Huawei Technologies Co., Ltd. |
| Samsung |
| ZTE Corporation |
| Qualcomm Technologies, Inc. |
| NEC Corporation |
| Juniper Networks, Inc. |
| Others |
Supply & Pricing Matrix
Private-equity-rolled-up infrastructure specialists anchor supply-side consolidation across radio unit manufacturing, compressing procurement leverage for enterprise buyers while enforcing disciplined margin structures on systems integrators. Their ownership patterns concentrate baseband semiconductor sourcing among Taiwanese foundries and German precision-component houses, tethering pricing power to silicon allocation cycles and BNetzA licensing timelines.
Pricing Analysis
Warranty and lifecycle service bundling separates premium-tier Nokia and Ericsson offerings from unbundled hardware-only procurement favored by mid-market manufacturing entrants. Three-tier pricing structure across premium, standard, and economy levels reflects certification depth under EU Cyber Resilience Act obligations and FCC CBRS compliance tiers. Price differentiation hinges on software-defined core inclusion versus radio-only supply, with German automotive OEMs demonstrating lowest price sensitivity due to latency guarantees for robotic coordination. Cost compression in economy-tier massive MIMO arrays is intensifying because Qualcomm and ZTE are flooding Indian PLI corridors with volume-scale supply.
Supply Chain Analysis
RF engineering talent scarcity across Shenzhen, Munich, and Dallas-Fort Worth manufacturing corridors constrains baseband unit production scaling and extends fulfillment timelines for brownfield deployments. Supply concentration rests on Taiwanese semiconductor foundries for 5G NR chipsets, German precision antenna fabricators for massive MIMO arrays, and South Korean memory suppliers for edge computing nodes. Raw material dependencies span gallium nitride substrates, high-purity copper for RF cabling, and advanced ceramics for thermal management. Single-source vulnerability in 7nm baseband silicon exposes deployment budgets to foundry allocation decisions. Distribution runs through systems integrators capable of unified radio, transport, and core delivery rather than discrete component channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a consolidation play where Open RAN interoperability mandates and sovereign spectrum licensing reforms are forcing sub-scale radio software vendors into distressed exits or strategic absorption.
For Market Incumbents: Anticipate Japanese METI interoperability requirements spilling into enterprise procurement specifications across Nagoya machine-tool corridors and Kyushu semiconductor clusters. Defensive consolidation moves center on acquiring specialized radio software providers before they gain METI certification traction, and deepening backward integration into gallium nitride substrate supply through captive offtake arrangements with Taiwanese foundries. Threat substitution from Wi-Fi 6E unlicensed systems compresses addressable scope in non-latency-sensitive campus segments.
For New Entrants and Emerging Players: The price-point gap between premium integrated systems and economy-tier hardware-only supply creates white-space opportunity in Indian Tamil Nadu and Gujarat manufacturing belts where PLI capital inflows outpace domestic systems integrator capacity. Target mid-market logistics operators in Western Australia's Pilbara region requiring virtualized distributed unit architectures without full managed service overlays. Go-to-market angle emphasizes rapid deployment kits bypassing traditional RF engineering bottlenecks through automated propagation modeling tools.
For Investors and Strategic Acquirers: Distressed-cycle entries favor Open RAN software specialists with METI certification progress and established channel relationships with Japanese systems integrators in Yokohama and Osaka. Long-term viability across the projection horizon rests on spectrum licensing advisory capabilities and twenty-year security patch infrastructure under EU Cyber Resilience Act obligations. Acquisition target archetype combines radio software intellectual property with existing BNetzA local license holdings in German industrial parks. Signal to watch is TRAI enterprise direct-licensing rule finalization triggering capital deployment into Sriperumbudur and Sanand manufacturing clusters.
| Strategic Initiative | Industry Significance |
|---|---|
| Spectrum Licensing Advisory Expansion | FCC CBRS and BNetzA local license expertise unlocks German and US industrial park deployments. |
| Open RAN Software Certification | METI interoperability compliance opens Japanese machine-tool and semiconductor procurement channels. |
| Edge-Cloud Convergence Partnership | Integration with Samsung and SK Telecom testbed ecosystems captures South Korean shipbuilder demand. |
| Twenty-Year Security Patch Infrastructure | EU Cyber Resilience Act attestation capability satisfies BASF Ludwigshafen procurement specifications. |
| Automated RF Engineering Tool Development | Propagation modeling automation addresses talent scarcity constraining mid-market deployment velocity. |
Research Methodology
Independent corroboration across primary interviews with private network deployment leads, spectrum licensing consultants, and industrial automation procurement officers, combined with secondary validation through FCC docket filings, BNetzA license registry extracts, and EU 5G PPP funding disbursement records, underwrites the qualitative findings. Bottom-up triangulation aggregates deployment counts across German Baden-Württemberg automotive complexes, US Dallas-Fort Worth testbeds, and South Korean Busan-Ulsan industrial corridors. Top-down reconciliation cross-references vendor revenue disclosures against PLI scheme capital flow data from India's Tamil Nadu and Gujarat industrial development authorities.
Comparable-period anchoring to historical private LTE deployment cycles and early 5G NR enterprise pilot phases established baseline adoption velocity assumptions across the projection horizon. Segmentation dimensions modeled span solution type, industry vertical, deployment model, and end-user specification authority, with cross-cutting analysis of spectrum licensing framework maturity by national jurisdiction. CAGRs derive from fitted adoption curves incorporating industrial automation intensity indices and OT integration friction coefficients. Industry-specific forecast inputs include brownfield protocol translation gateway penetration rates and edge computing node density per square kilometer in mining and logistics applications.
Inputs from regulatory filing databases and vendor disclosure documents were available through the study window; gaps in real-time private network activation data introduce uncertainty bands around near-term deployment velocity estimates. Forecasts reflect documented assumptions regarding CBRS priority access license allocation timelines and TRAI consultation outcomes. Material deviation in BNetzA local licensing fee structures or METI interoperability certification deadlines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Telecommunications
Spain ICT Market
Telecommunications
Optical Network Terminal (ONT) Equipment Market
Telecommunications
Cloud PBX Market
Telecommunications
Middle East and Africa Telecom Market
Telecommunications
Voice Over Internet Protocol (Voip) Over WLAN (Vowlan) Market
Telecommunications
Argentina Telecom Market
Telecommunications
Call Control (PBX-IP PBX) Market
Telecommunications
Voice Communication Control System Market
Telecommunications
DWDM System Market
Telecommunications
Fixed Voice Market
Telecommunications
Russia Telecom Market
Telecommunications
Hong Kong Telecom Market
Telecommunications
Saudi Arabia Telecom Market
Telecommunications
Rich Communication Services (RCS) Messaging Market
Telecommunications
Telecom API Platform Market
Telecommunications
ASEAN Mobile Virtual Network Operator (MVNO) Market