
 Industrial Gas Stove Market | 2026-2036
Industrial Gas Stove Market Size, Share, and Industry Trends Forecast 2026-2036
Industrial Gas Stove Market Foresight
Shortages of certified combustion technicians and commercial kitchen equipment installers is unwinding capacity expansion plans across multiple manufacturing hubs. Hurst leverages its vertical integration in burner assembly to sustain delivery timelines against these labor constraints. Faber anchors its competitive stance through specialized stainless-steel fabrication capabilities that command premium positioning in European markets. Oilon competes on R&D intensity in low-NOx burner technology, a segment where regulatory thresholds continue tightening.
An industrial gas stove is a heavy-duty cooking appliance engineered with cast-iron or stainless-steel grates, multiple high-BTU burners typically rated between 25,000 and 150,000 BTU per burner, and modular configurations designed for continuous operation in high-throughput food service environments. Its primary purpose is to deliver rapid, controllable thermal output for batch and continuous cooking processes where electric alternatives cannot match recovery speed or operating cost profiles. Commercial range configurations dominate current revenue pools due to their versatility across protein, sauce, and starch preparation workflows in full-service restaurants. Four-burner units represent the fastest-expanding product type as ghost kitchens and delivery-optimized facilities prioritize compact footprint with maximum burner density. Griddle attachments are capturing margin concentration where operators seek single-appliance flexibility for breakfast and sandwich menus without dedicated equipment outlays.
EPA emissions standards for commercial cooking equipment and OSHA ventilation requirements shape product design mandates and installation compliance costs across the United States. CE marking under the EU Gas Appliances Regulation and Ecodesign directives govern burner efficiency thresholds and material safety specifications for European market access. China's GB standards for commercial gas appliances enforce thermal efficiency minimums that foreign manufacturers must certify through the country's national quality regulator. Stakeholders must monitor evolving municipal natural gas bans and electrification mandates in major urban centers, as these local policy shifts could abruptly reconfigure fuel type demand and retrofit investment timelines.
Market Dynamics
Natural gas efficiency mandates across North America and Europe are compressing product lifecycles while China's centralized food processing procurement concentrates demand around four-burner configurations.
Growth Catalysts
- EPA Commercial Cooking Emissions Standards:Tightening NOx thresholds in the United States force equipment replacement cycles, creating pull for certified low-emission burner assemblies in full-service restaurant chains.
- Ghost Kitchen Proliferation:Delivery-optimized facilities prioritize compact footprint with maximum burner density, accelerating specification of four-burner units over traditional six-burner ranges.
- Stainless-Steel Fabrication Advances:Specialized welding and surface treatment capabilities enable thinner-gauge commercial construction without thermal deformation, supporting lighter equipment designs for high-turnover installations.
Market Restraints
- Certified Combustion Technician Scarcity:Installation and maintenance labor shortages in manufacturing hubs unwind capacity expansion timelines and extend delivery windows for complex burner configurations.
- Municipal Natural Gas Bans:Electrification mandates in major urban centers abruptly reconfigure fuel type demand and compress retrofit investment timelines for gas-dependent operators.
- Cast-Iron Grate Supply Concentration:Foundry capacity constraints in specific manufacturing regions create input bottlenecks for heavy-duty grate assemblies rated above 100,000 BTU.
Strategic Opportunities
- India Commercial Kitchen Infrastructure:Underpenetrated food service equipment markets in tier-two cities present white space for four-burner and griddle-attachment configurations as organized retail expands.
- EU Ecodesign Directive Alignment:Burner efficiency threshold upgrades create regulatory tailwind for manufacturers with pre-certified thermal performance testing protocols.
- Cloud Kitchen Equipment Leasing:Asset-light operating models for delivery-only brands open channel innovation through rental and managed service arrangements rather than outright purchase.
Industry Challenges
- Cross-Border Certification Timelines:GB standards compliance for China's national quality regulator requires extended product testing cycles that delay market entry for foreign manufacturers.
- Ventilation System Integration Complexity:OSHA requirements for commercial kitchen airflow management create execution friction when retrofitting gas stoves into existing building infrastructure with dated hood configurations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Industrial Gas Stove Market |
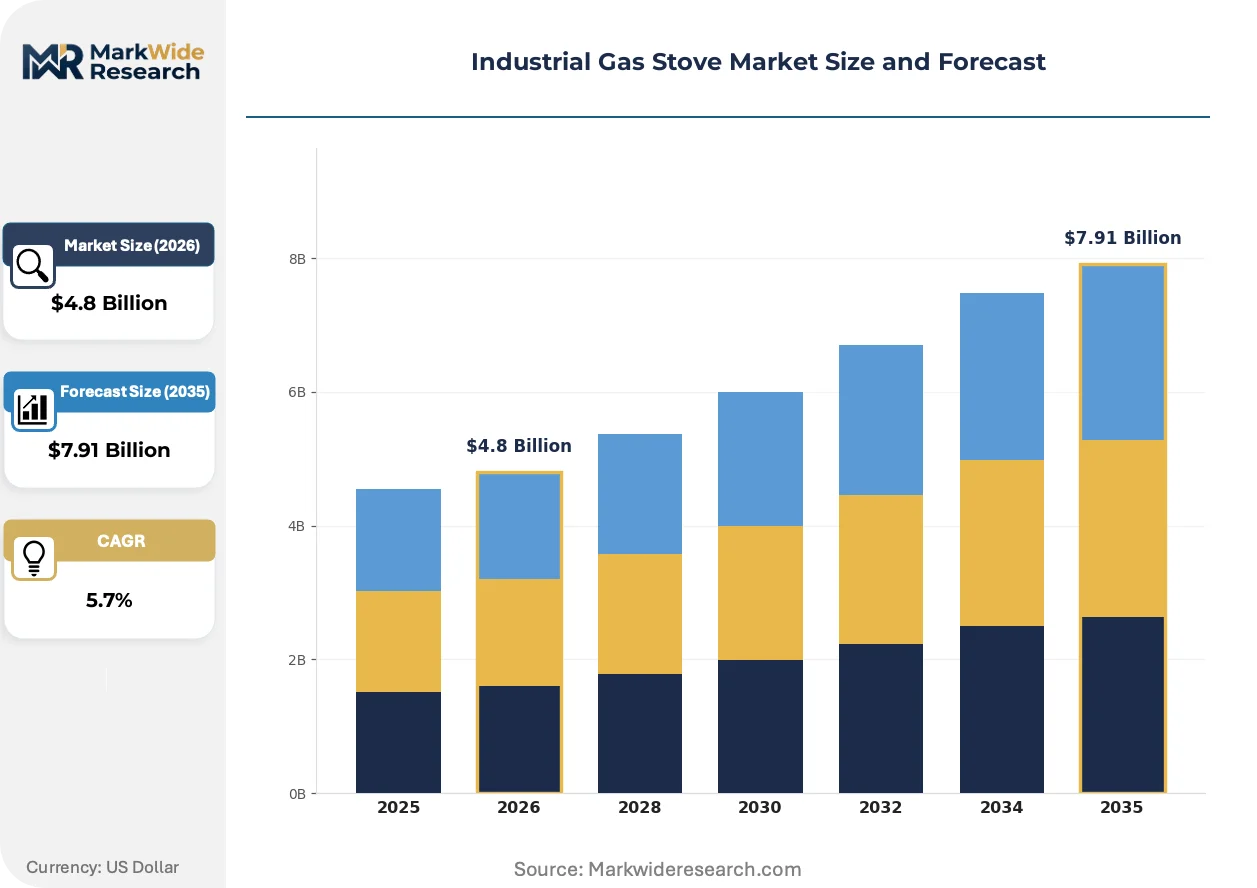
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Two-Burner, Four-Burner, Commercial Range, Griddle Application: Restaurants, Catering Services, Food Processing, Industrial Kitchens Fuel Type: Natural Gas, Propane, Butane, LPG End User: Food Industry, Hotels, Cafés, Catering Enterprises |
| Companies Covered | Hurst, Faber, Honeywell Thermal Solutions, Limpsfield, EBICO, Oilon, Miura America, Vulcan, Power Flame, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Industrial Gas Stove Market Shifts & Advancements
Equipment miniaturization and modular attachment systems are compressing kitchen footprints while regulatory pressure on combustion emissions accelerates burner technology substitution cycles.
Compact four-burner configurations with integrated griddle attachments are miniaturizing traditional range footprints without sacrificing thermal output. Ghost kitchen operators and delivery-optimized facilities specify these units to maximize linear feet of cooking surface within constrained real estate. The technology is miniaturizing equipment procurement decisions, collapsing what previously required two dedicated appliances into single-source capital outlays.
EU Gas Appliances Regulation updates under Ecodesign directives are tightening burner efficiency thresholds and material safety specifications for CE marking compliance. Manufacturers must redesign combustion chambers and flame supervision systems to meet revised thermal performance minimums. European full-service restaurant chains face compressed replacement timelines as grandfathered equipment loses certification validity.
Centralized procurement by multi-unit food service operators is consolidating vendor relationships and unbundling after-sales service from equipment purchase. Large restaurant groups negotiate direct burner assembly supply contracts, bypassing traditional distribution channels. This concentration is most visible in China where state-affiliated food processing facilities drive bulk tender processes for standardized four-burner configurations.
Industrial Gas Stove Market Segmentation
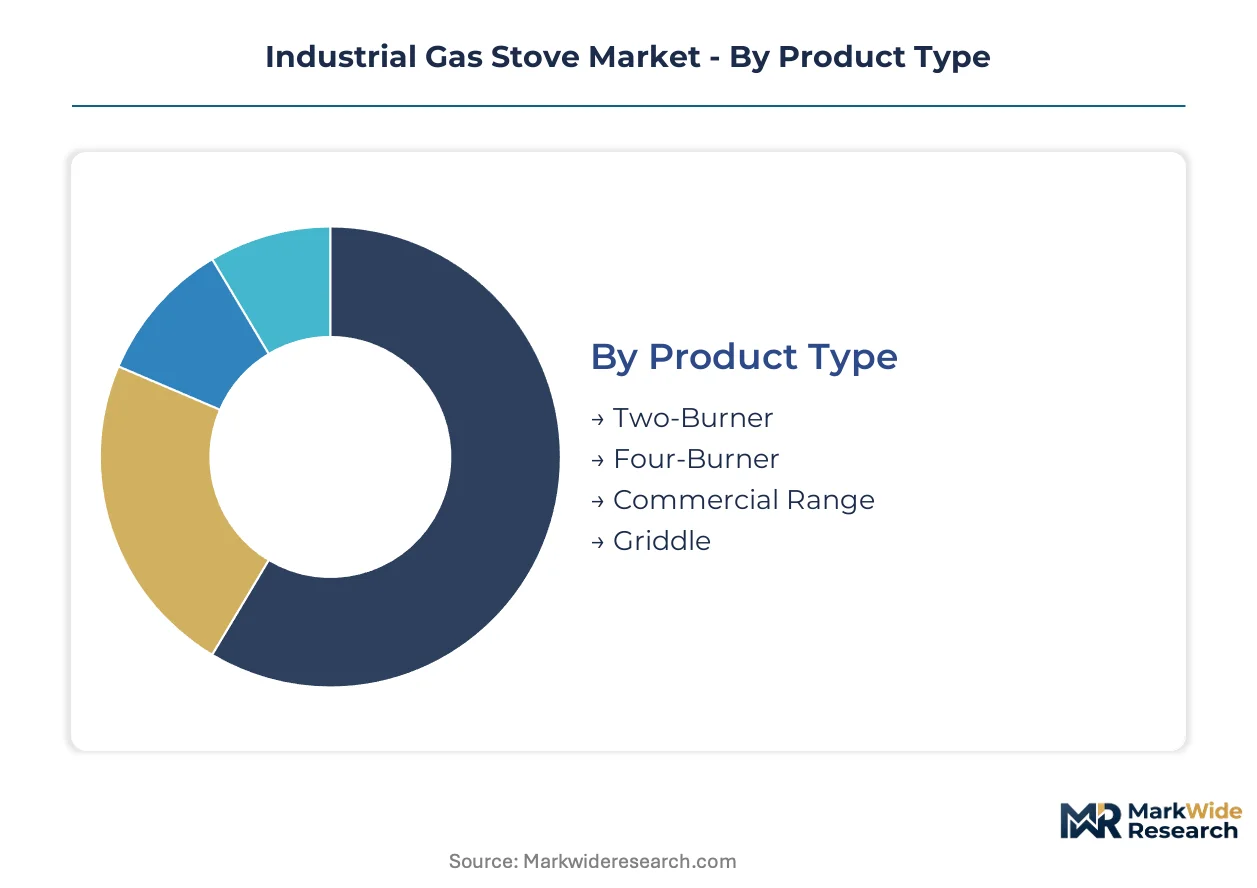
Industrial gas stove segmentation reveals how procurement decisions split between throughput requirements and fuel infrastructure constraints. Equipment specification varies sharply across end-use environments, from high-turnover restaurant chains to centralized food processing facilities with dedicated utility feeds.
Product Type:
Margin pools concentrate in configurations that balance burner density with footprint efficiency, particularly where real estate costs dominate operating economics.
- Four-Burner:Compact configurations pack maximum thermal output into minimal linear footage, serving ghost kitchens and delivery-optimized facilities where space constraints override range versatility. China's centralized food processing procurement drives bulk tender processes for standardized four-burner units with cast-iron grate assemblies.
- Commercial Range:Modular six-burner and eight-burner systems dominate full-service restaurant chains requiring simultaneous protein, sauce, and starch preparation workflows. Foundry capacity constraints for heavy-duty grate assemblies rated above 100,000 BTU create supply bottlenecks for premium range configurations.
- Two-Burner:Entry-level units serve small cafés and limited-menu operators with restricted capital budgets and lower throughput requirements.
- Griddle:Flat-top attachments capture operators seeking single-appliance flexibility for breakfast and sandwich menus without dedicated equipment outlays.
Commercial range configurations hold installed capacity. Four-burner units are rotating up the share rankings.
Application:
Volume concentrates where batch cooking demands intersect with continuous operation requirements, creating divergent equipment durability specifications.
- Restaurants:Full-service chains specify modular range configurations with integrated ventilation compatibility, driven by EPA commercial cooking emissions standards that force replacement cycles for legacy burner assemblies.
- Food Processing:Centralized facilities in China deploy standardized four-burner configurations across protein and prepared meal production lines, with procurement consolidated through state-affiliated tender processes.
- Catering Services:Mobile and event-based operators prioritize propane compatibility and rapid deployment capabilities for off-grid service environments.
- Industrial Kitchens:Institutional food service operations in hospitals and universities require certified low-NOx burner technology to meet municipal air quality mandates.
Restaurants anchor current procurement volume. Food processing is climbing the fastest.
Fuel Type:
Supply concentration and infrastructure availability dictate fuel specification across geographies with divergent utility regulation.
- Natural Gas:Pipeline-fed systems dominate North American and European commercial installations where efficiency standards under EPA and EU Ecodesign directives compress product lifecycles. Municipal natural gas bans in major urban centers abruptly reconfigure demand toward alternatives.
- Propane:Tank-stored fuel serves off-grid catering operations and facilities in regions without pipeline infrastructure, particularly in tier-two Indian cities where organized retail expansion outpaces utility buildout.
- LPG:Cylinder-based distribution supports small-scale food service operators across Southeast Asian markets with fragmented natural gas coverage.
- Butane:Portable canister configurations address mobile catering and temporary kitchen installations requiring minimal fixed infrastructure.
Natural gas retains dominant share. Propane is gaining share fastest.
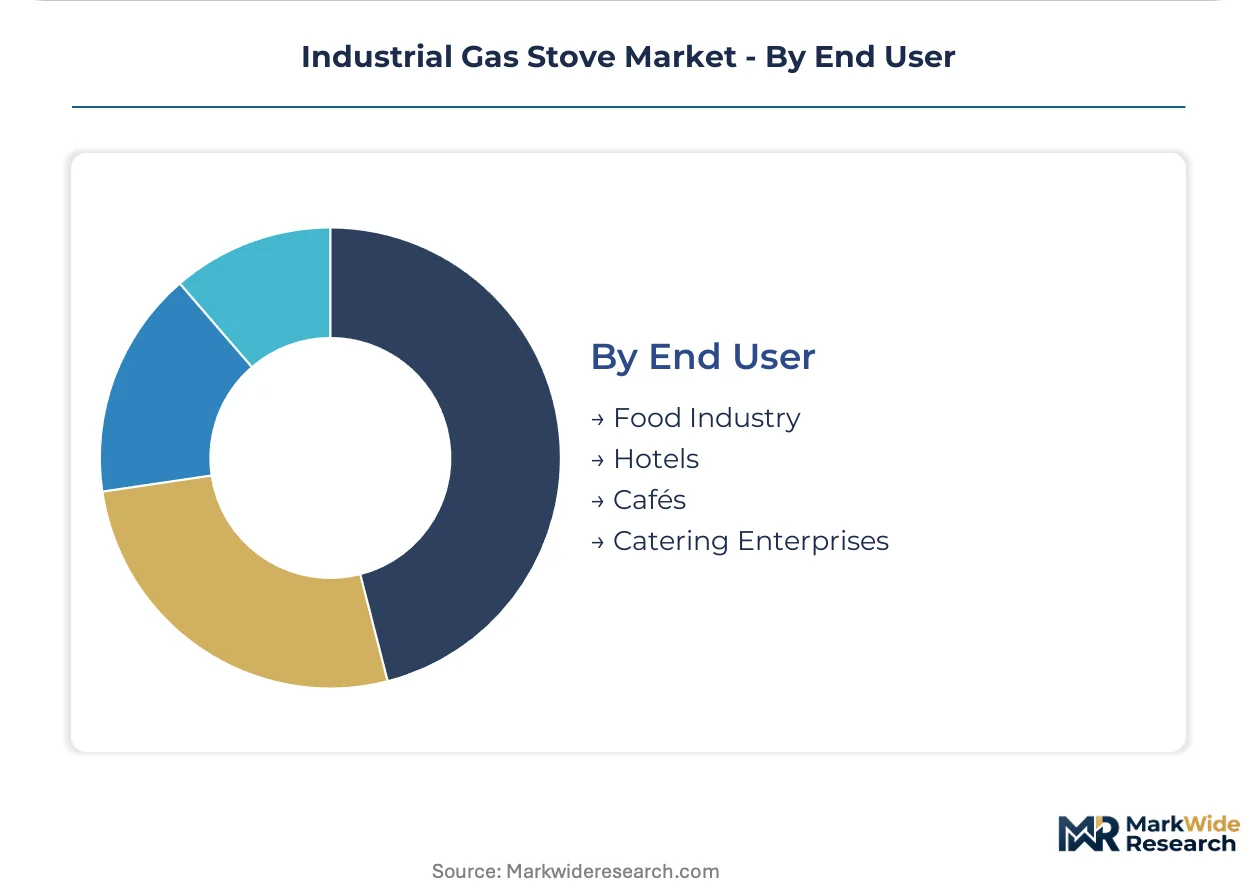
End User:
Customer type determines service bundling expectations and financing structure preferences across the procurement cycle.
- Food Industry:Multi-unit chains negotiate direct burner assembly supply contracts, unbundling after-sales service from equipment purchase through centralized procurement functions.
- Hotels:Full-service properties require integrated ventilation system compatibility and 24-hour operational support contracts for high-occupancy banquet service.
- Cafés:Limited-menu operators prioritize compact two-burner and four-burner configurations with rapid heat recovery for beverage-accompanying food preparation.
- Catering Enterprises:Asset-light operators increasingly specify equipment leasing arrangements rather than outright purchase, opening channel innovation through rental and managed service models.
Food industry chains command procurement volume. Catering enterprises are rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China deploys industrial gas stoves primarily in centralized food processing facilities with bulk procurement, while the United States concentrates demand in fragmented full-service restaurant chains facing emissions-driven replacement cycles.
United States
Full-service restaurant chains drive equipment turnover as EPA commercial cooking emissions standards tighten NOx thresholds. OSHA ventilation requirements shape retrofit complexity in older urban buildings. Kitchen equipment clusters in Chicago, Dallas, and Los Angeles absorb premium range configurations with integrated hood compatibility.
Germany
CE marking under EU Gas Appliances Regulation and Ecodesign directives compress product lifecycles for stainless-steel fabricators. Full-service hotels and banquet facilities anchor procurement volume in Frankfurt-Rhine-Main and Munich industrial corridors. Foundry-linked manufacturers in North Rhine-Westphalia manage grate assembly supply for high-BTU configurations.
China
State-affiliated food processing facilities concentrate demand through standardized tender processes for four-burner units. GB standards enforcement through SAMR requires extended certification cycles for foreign entrants. Yangtze River Delta manufacturing hubs in Jiangsu and Zhejiang provinces dominate burner assembly production for domestic and export markets.
India
Tier-two city organized retail expansion outpaces natural gas utility buildout, tilting specification toward propane-compatible configurations. FSSAI food safety protocols and state-level pollution control mandates shape commercial kitchen equipment standards. Maharashtra and Gujarat industrial zones host emerging fabrication capacity for entry-level two-burner and four-burner units.
United Kingdom
London metropolitan electrification mandates and municipal natural gas bans abruptly reconfigure fuel-type demand for ghost kitchen operators. CE marking alignment post-Brexit maintains EU Ecodesign threshold compliance for cross-border equipment flows. Southeast England logistics corridors concentrate delivery-optimized facility buildouts specifying compact burner-density configurations.
Industrial Gas Stove Market Competitive Landscape
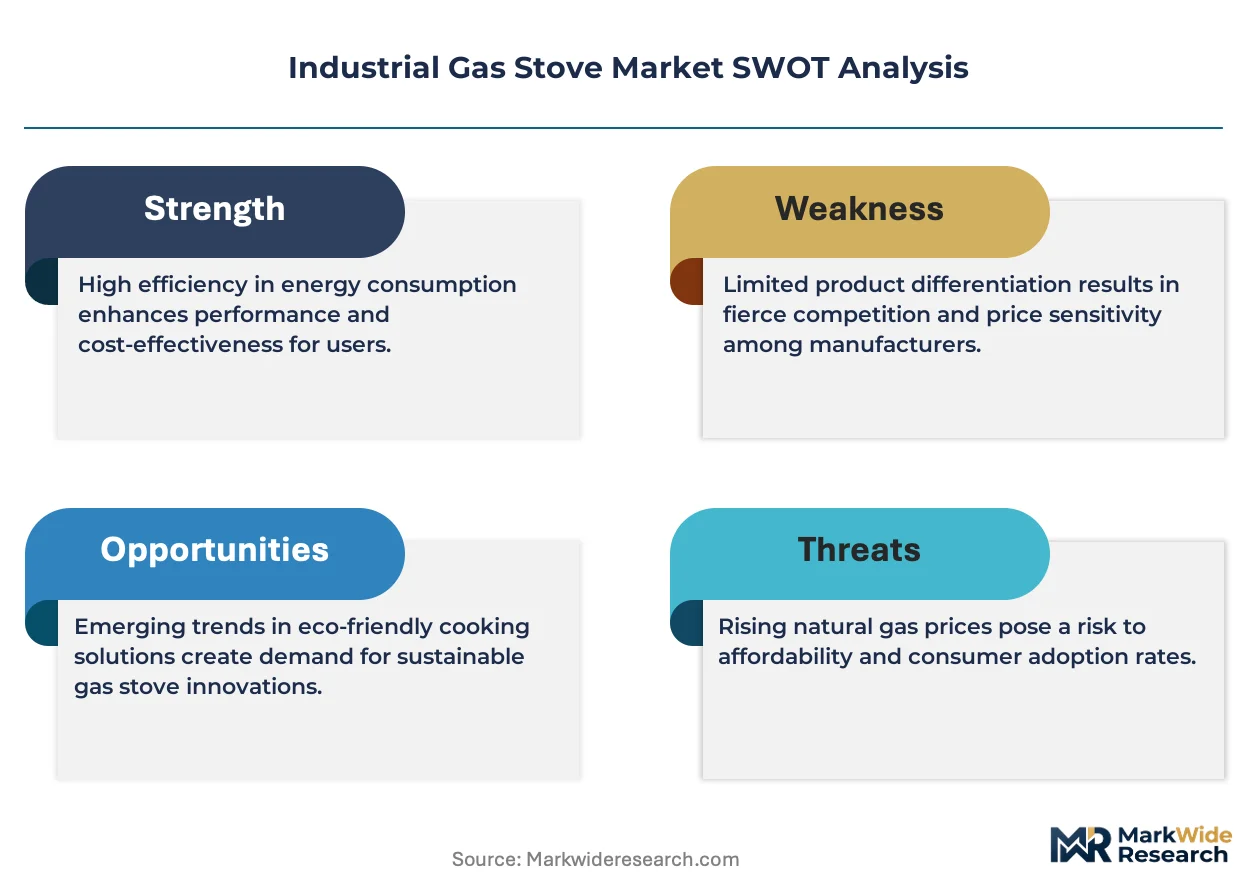
A small set of integrated leaders sits above a broader specialist tier, with backward integration into burner assembly and captive stainless-steel fabrication creating delivery reliability advantages against labor-constrained installation markets. The structure rewards vertical control over combustion component supply and specialized welding capabilities for thinner-gauge commercial construction. Three archetypes dominate: integrated burner-and-range fabricators, stainless-steel surface treatment specialists, and low-NOx combustion technology developers. Competitive moves concentrate on capacity expansion in tier-two manufacturing hubs and technology licensing arrangements for emissions-certified burner platforms.
Within the integrated fabrication tier, Hurst and Faber exemplify divergent positioning archetypes, with the former representing North American vertical integration models and the latter embodying European premium-surface specialization. Oilon occupies a position among combustion technology developers targeting regulatory threshold tightening. Honeywell Thermal Solutions anchors the diversified industrial conglomerate vector with cross-sector thermal systems capabilities.
| Leading Market Players |
|---|
| Hurst |
| Faber |
| Honeywell Thermal Solutions |
| Limpsfield |
| EBICO |
| Oilon |
| Miura America |
| Vulcan |
| Power Flame |
| Others |
Supply & Pricing Matrix
Foundry scale economies in Jiangsu and Zhejiang provinces anchor burner assembly cost floors, with captive grate production compressing unit economics for integrated fabricators while fragmenting pricing power among non-integrated assemblers. China's SAMR certification timelines and EPA emissions thresholds in the United States create divergent compliance cost burdens that stratify price bands across export and domestic market configurations.
Pricing Analysis
Long-term offtake contracts dominate procurement between multi-unit restaurant chains and integrated burner fabricators, locking in volume commitments against foundry capacity allocation. Price differentiation hinges on CE marking tier and UL certification grade, with premium stainless-surface treatment commanding spreads above standard cast-iron configurations. Cost compression in entry-level two-burner segments is intensifying because of propane-compatible specification proliferation in India's tier-two markets. Ghost kitchen operators exhibit highest price sensitivity, while full-service hotel chains absorb premium positioning for integrated ventilation compatibility.
Supply Chain Analysis
China and India anchor global burner assembly and grate fabrication, with North Rhine-Westphalia in Germany retaining specialized stainless-steel surface treatment capacity. Raw material flows draw from foundry-grade pig iron, nickel-alloy stainless feedstock, and ceramic burner component supply. Single-source vulnerability concentrates in heavy-duty cast-iron grate production above 100,000 BTU rating. Distribution runs through OEM direct channels for large chains and specialized kitchen equipment distributors for independent operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Industrial gas stove demand is accelerating through ghost kitchen proliferation and low-NOx burner substitution cycles, with EPA and EU Ecodesign regulatory inflections compressing replacement timelines across installed bases.
For Market Incumbents: Consolidate burner assembly capacity in Yangtze River Delta hubs to offset certified combustion technician scarcity, while pre-certifying thermal performance protocols under revised EU Ecodesign thresholds. Electrification mandates in London and other metropolitan centers threaten gas-dependent revenue pools; backward integration into stainless fabrication preserves margin against surface-treatment bottlenecks. For New Entrants and Emerging Players: CE marking fast-track through notified body partnerships in Germany unlocks European hotel and banquet procurement channels without extended SAMR cycles. India's tier-two organized retail expansion presents the most penetrable white space, with propane-compatible four-burner configurations addressing utility buildout gaps. Cloud kitchen equipment leasing models bypass capital-constrained operator entry barriers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among burner technology licensors with emissions-certified platforms, as regulatory tightening forces continuous upgrade cycles across fragmented restaurant bases. Acquisition targets should demonstrate captive foundry relationships or specialized welding capabilities for thinner-gauge commercial construction. Watch municipal natural gas ban announcements in major urban centers as demand-inflection signals.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Burner Assembly | Hurst's captive production sustains delivery timelines against combustion technician shortages. |
| CE Marking Pre-Certification | Faber's specialized stainless fabrication commands premium positioning under EU Ecodesign thresholds. |
| Low-NOx R&D Intensification | Oilon's combustion technology development targets tightening EPA NOx thresholds in restaurant chains. |
| Cloud Kitchen Leasing Models | Asset-light rental arrangements bypass capital constraints for delivery-only brand proliferation. |
| India Tier-Two Capacity Expansion | Maharashtra and Gujarat fabrication buildout addresses propane-compatible demand in organized retail expansion. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted across primary interview programs, incorporating commercial kitchen equipment procurement managers, ghost kitchen facility operators, foundry production heads, and aftermarket service technicians. Secondary validation drew from EPA emissions filings, EU Ecodesign directive documentation, SAMR certification registries, and trade flow data through kitchen equipment distribution channels. Bottom-up unit economics triangulated against top-down market sizing across product type, application, fuel type, and end user segmentation dimensions.
Across the analysis window, volume and value outputs reflect segmentation modeling by burner configuration, thermal output tier, regional regulatory cluster, and customer procurement scale. CAGRs were derived from installed base turnover rates and replacement cycle compression under evolving emissions standards. Forecast inputs incorporated foundry capacity utilization rates, certified technician labor availability, and municipal electrification policy trajectories.
Decision-makers should treat outputs as directional under base assumptions of continued natural gas infrastructure availability and stable foundry input costs; material deviation in electrification mandate pace or cast-iron supply disruption would warrant model refresh. Specific risk factors include abrupt municipal fuel bans, extended SAMR certification delays, and combustion technician labor pool contraction. Recalibration cycles align with material shifts in EPA rulemaking, EU Ecodesign threshold revisions, and China procurement tender patterns.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Appliances
Fully Integrated Dishwasher Market
Appliances
Asia-Pacific Tumble Dryers Market
Appliances
Microwave Market
Appliances
Europe Household Electric Grills Market
Appliances
AI Washing Machine Market
Appliances
Built-In Large Cooking Appliance Market
Appliances
Asia-Pacific Electric Rice Cooker Market
Appliances
Asia-Pacific Washing Machine Market
Appliances
Electric Dryers Market
Appliances
Small Electric Kettles Market
Appliances
North America Microwave Oven Market
Appliances
Automatic Dishwasher Market
Appliances
Digital Showers Market
Appliances
Global Massage Chairs Market
Appliances
Oman Dishwashers Market
Appliances
Asia Pacific Compact Dishwasher Market