
 Asia Pacific Nutritional Supplements Market | 2026-2036
Asia Pacific Nutritional Supplements Market Size, Share, and Industry Trends Forecast 2026-2036
Asia Pacific Nutritional Supplements Market Analytics
Fragmentation among millennial and Gen-Z buyers across Southeast Asian cities is repositioning brand loyalty dynamics throughout the region. Amway leverages its direct-selling infrastructure to sustain channel control across tier-two Indian and Indonesian markets. Abbott Laboratories anchors its portfolio in clinical nutrition segments where healthcare practitioner endorsement commands premium positioning. Herbalife Nutrition competes through localized flavor development and community-based distributor networks in Philippines and Vietnam.
Nutritional supplements encompass biologically active compounds including vitamins, minerals, herbal extracts, and amino acids formulated in pills, powders, gummies, or liquid vehicles to augment dietary intake and support physiological function. Manufacturing employs granulation, encapsulation, and cold-press tableting to preserve thermolabile actives such as probiotics and certain B-vitamin complexes. Vitamins and minerals occupy mature volume positions with established supply chains and price transparency, while herbal extracts capture expanding margin pools as Ayurvedic and Traditional Chinese Medicine formulations gain clinical validation. Gummies represent the fastest-growing form segment as palatability drives compliance among children and younger adults who reject conventional tablet regimens.
China's NMPA maintains stringent blue-hat registration requirements for health food claims, while India's FSSAI enforces progressively tighter label disclosure and adulteration testing protocols that elevate compliance costs for imported formulations. TGA-equivalent standards in Australia and MFDS regulations in South Korea create divergent specification requirements that fragment regional product standardization. Stakeholders must monitor evolving probiotic and novel ingredient approval pathways as regulators balance innovation access against post-market surveillance capacity across the region.
Market Dynamics
China's NMPA blue-hat registration requirements are forcing reformulation investments across the Asia Pacific Nutritional Supplements Market, compressing product development timelines while elevating quality thresholds for market entry.
Growth Catalysts
- Athlete segment expansion:Professional and amateur sports participation across Australia, South Korea, and Thailand is accelerating demand for protein isolates and branched-chain amino acid formulations. This end-use vertical now commands dedicated R&D budgets from regional manufacturers.
- FSSAI label modernization:India's tightened disclosure mandates are building consumer trust in imported formulations, reducing information asymmetry that previously suppressed premium product uptake. Urban middle-class buyers respond to verified ingredient sourcing claims.
- Herbal extract validation:Clinical trials supporting Ayurvedic and Traditional Chinese Medicine compounds are unlocking practitioner endorsement channels. This scientific legitimization is absorbing margin expansion previously captured by synthetic vitamin suppliers.
Market Restraints
- Raw material concentration:Gelatin capsule supply depends on Pakistani and Brazilian bovine hide processors, exposing manufacturers to livestock disease quarantine disruptions and halal certification complexity.
- Probiotic thermostability limits:Cold-chain requirements for viable colony-forming units restrict distribution reach into Indonesian archipelago markets and rural Indian tier-three cities without refrigerated logistics infrastructure.
- MFDS novel ingredient friction:South Korea's extended safety assessment timelines for postbiotic and phytosome complexes delay product launches by 18-24 months versus conventional vitamin registrations.
Strategic Opportunities
- Vietnamese pharmacy channel penetration:Modern trade format expansion in Ho Chi Minh City and Hanoi creates shelf access for gummy and liquid supplement formats previously confined to direct-selling networks.
- PLI scheme alignment:India's production-linked incentive framework for active pharmaceutical ingredients extends to nutraceutical intermediates, reducing effective manufacturing costs for domestic encapsulation facilities.
- Digital health convergence:Wearable biomarker integration with personalized supplement subscription models is capturing micronutrient deficiency data from South Korean and Japanese consumer cohorts.
Industry Challenges
- Formulation scientist scarcity:Cross-disciplinary expertise combining food chemistry with regulatory affairs commands premium compensation in Singapore and Sydney, constraining mid-tier manufacturer technical staffing.
- Multi-jurisdiction label compliance:Simultaneous NMPA, FSSAI, and TGA registration requires parallel dossier preparation, fragmenting quality assurance team capacity and extending time-to-revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia Pacific Nutritional Supplements Market |
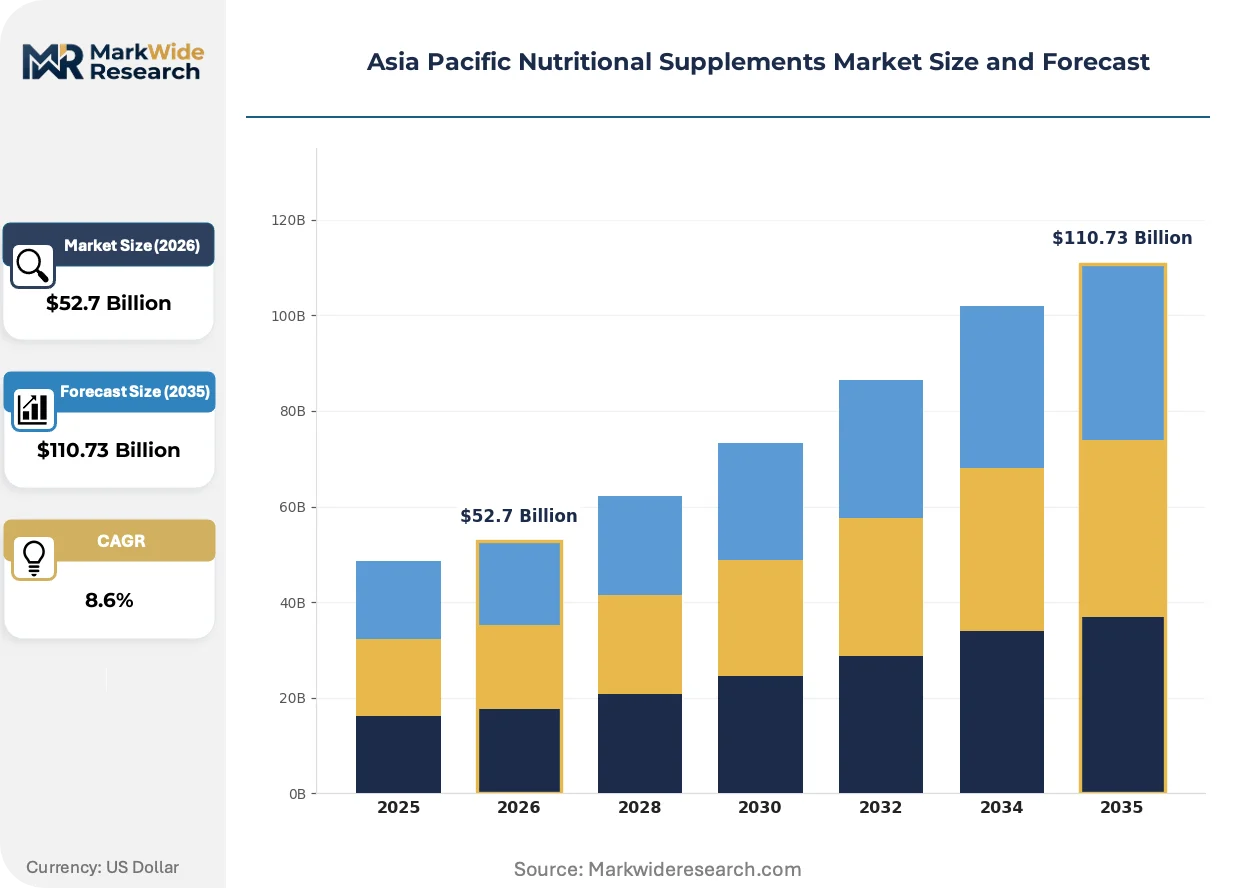
| Market Size in 2026 | $52.7 Billion |
| Market Size in 2035 | $110.73 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Herbal Extracts, Amino Acids End User: Adults, Children, Pregnant Women, Athletes Form: Pills, Powders, Gummies, Liquid Distribution Channel: Health Stores, Online Retail, Pharmacies, Supermarkets |
| Companies Covered | Amway, Abbott Laboratories, BY-HEALTH Co., Bayer AG, Nestlé, Kalbe Farma, Herbalife Nutrition, Blackmores, H&H Group, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia Pacific Nutritional Supplements Market Evolving Landscape
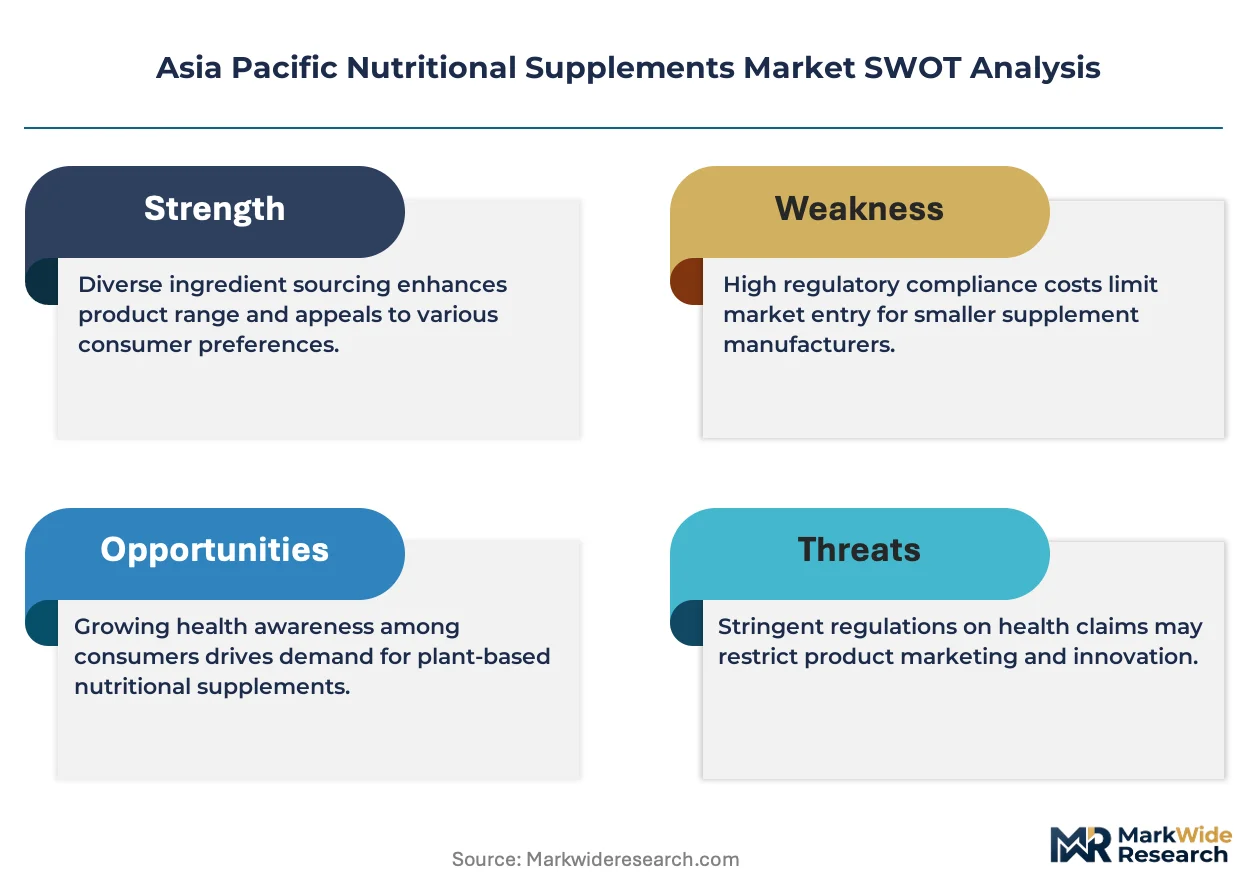
Functional format innovation and regulatory data requirements are compressing traditional competitive advantages in ingredient sourcing, while digital traceability systems reshape quality assurance investments across manufacturing networks.
Microencapsulation technology is absorbing thermolabile active protection requirements across probiotic and omega-3 fatty acid formulations. Pediatric and geriatric supplement manufacturers in Japan and Australia adopt this process at accelerated rates to replace enteric coating methods. The shift is compressing spoilage loss rates while enabling ambient distribution channels previously inaccessible to live culture products.
China's NMPA health food claim substantiation rules now mandate human intervention trials for blue-hat registration of immune function and bone density assertions. This evidentiary burden is eliminating legacy dossier submissions reliant on literature reviews or animal model data. Domestic Chinese manufacturers with captive clinical research organizations are absorbing compliance costs more efficiently than import-dependent competitors.
Subscription-based replenishment models are displacing traditional pharmacy and supermarket replenishment cycles among urban millennial cohorts in Bangalore, Jakarta, and Manila. Direct-to-consumer platforms capture recurring revenue through personalized dosage algorithms while eroding distributor margin pools. This channel rotation is most visible in protein powder and nootropic segments where brand switching costs remain minimal.
Asia Pacific Nutritional Supplements Market Segmentation
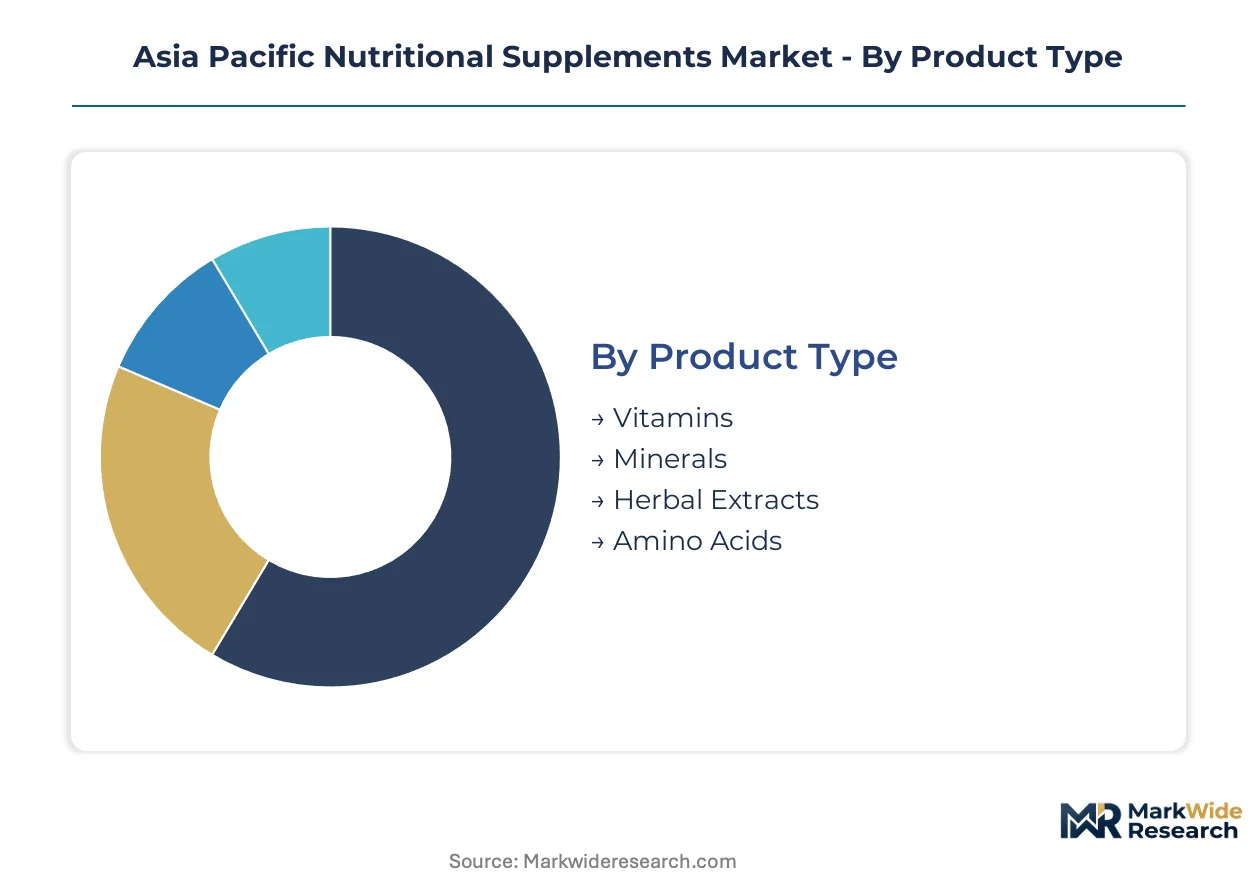
Segmentation in Asia Pacific Nutritional Supplements Market reveals how formulation specifications, user physiology, and channel infrastructure create divergent margin profiles. Manufacturers configure supply chains differently across each axis, from cold-chain probiotics for pediatric gummies to bulk powder logistics serving Australian gym networks.
Product Type:
Thermostability and bioavailability specifications differentiate manufacturing investment intensity across compound categories.
- Vitamins:Synthetic and natural isolates including B-complex, C, D, and E formulations dominate volume throughput in established encapsulation facilities. Indian urban middle-class consumers drive sustained demand for D3 and B12 combinations as deficiency awareness spreads through diagnostic clinic partnerships.
- Herbal Extracts:Ayurvedic and Traditional Chinese Medicine compounds require standardized marker compound verification and heavy metal screening. Clinical validation investments by domestic Chinese manufacturers with captive CROs are compressing approval timelines for NMPA blue-hat registrations versus import-dependent competitors.
- Minerals:Chelated forms and colloidal suspensions address absorption efficiency concerns in geriatric populations. FSSAI-mandated label disclosure on elemental content is elevating transparency premiums for verified sourcing claims.
- Amino Acids:Branched-chain and essential amino acid isolates serve sports nutrition formulations with specified leucine ratios. Protein isolate demand from Australian and South Korean amateur sports participation is accelerating dedicated R&D budget allocation.
Vitamins lead on scale; herbal extracts lead on momentum.
End User:
Physiological state determines dosage precision requirements and compliance format preferences.
- Adults:General wellness and condition-specific formulations target working-age populations with preventive health orientation. Subscription-based replenishment models capture recurring revenue through personalized algorithms among urban millennial cohorts in Bangalore and Manila.
- Athletes:Professional and amateur sports participants require batch-tested formulations with banned substance certification. Thailand's expanding marathon and triathlon participation is creating dedicated protein isolate demand previously served by generic fitness products.
- Children:Palatability-driven formats with micronutrient density specifications address growth-phase nutritional gaps. Gummy formats displace conventional tablets as compliance drivers among parents rejecting pill regimens.
- Pregnant Women:Folate, iron, and DHA combinations require teratogenic safety profiling and trimester-specific dosing protocols. Practitioner endorsement channels command premium positioning through clinic-based sampling programs.
Adults lead on scale; athletes lead on momentum.
Form:
Manufacturing process selection—granulation, encapsulation, cold-press tableting, or liquid filling—locks in thermolabile active protection capabilities.
- Gummies:Gelatin and pectin-based matrices with flavor masking systems deliver pediatric and young adult compliance. Palatability is displacing conventional tablet regimens across Southeast Asian millennial and Gen-Z fragmentation.
- Pills:Compressed tablets and two-piece hard capsules dominate cost-efficient adult dosing with established supply chains. Enteric coating and microencapsulation upgrades are absorbing thermolabile protection requirements from legacy methods.
- Powders:Bulk protein and prebiotic formulations enable flexible dosing and flavor customization. Cold-chain bypass for ambient-stable concentrates expands distribution reach into Indonesian archipelago markets.
- Liquid:Emulsion and suspension vehicles address swallowing difficulty in geriatric and pediatric populations. Vietnamese pharmacy channel expansion in Ho Chi Minh City and Hanoi creates shelf access previously confined to direct-selling networks.
Pills lead on scale; gummies lead on momentum.
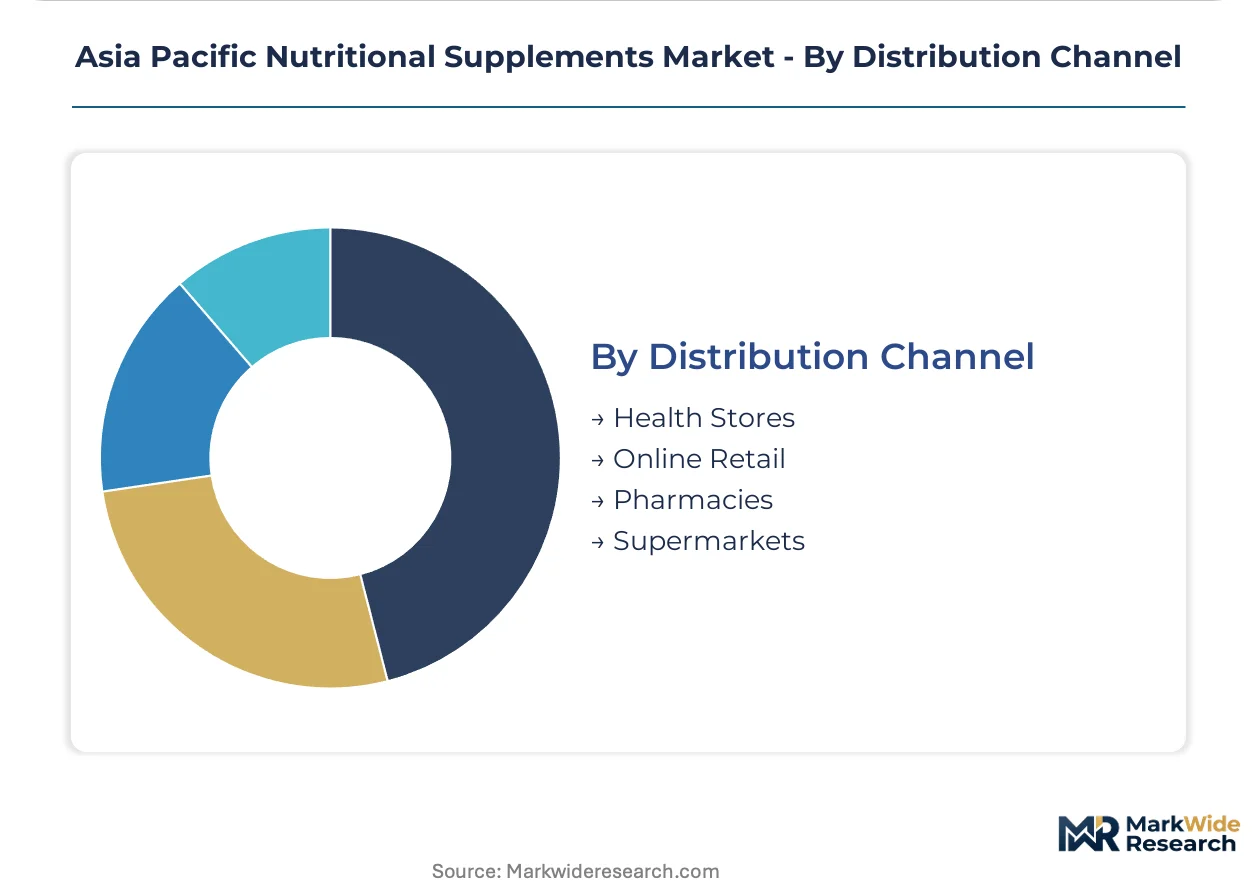
Distribution Channel:
Channel selection determines margin capture, regulatory scrutiny intensity, and consumer education burden.
- Online Retail:Direct-to-consumer platforms with subscription algorithms erode traditional distributor margin pools. Personalized dosage recommendations based on wearable biomarker integration capture micronutrient deficiency data from South Korean and Japanese cohorts.
- Pharmacies:Healthcare practitioner endorsement channels command premium positioning through clinical credibility transfer. Modern trade format expansion creates shelf access for liquid and gummy formats with professional recommendation protocols.
- Health Stores:Specialized retail with trained staff supports complex herbal formulation education and stacking guidance. Direct-selling infrastructure sustains channel control across tier-two Indian and Indonesian markets through community-based distributor networks.
- Supermarkets:Mass-market penetration for standardized vitamin and mineral combinations with price transparency. Established supply chains and volume throughput dominate mature product categories with minimal differentiation.
Pharmacies lead on scale; online retail leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Formulation scientists and regulatory affairs specialists concentrate in Singapore and Sydney, commanding premium compensation that constrains mid-tier manufacturer technical staffing across the region.
China
Urban middle-class consumers in Shanghai and Beijing drive sustained demand for protein and herbal formulations. NMPA blue-hat registration requirements mandate human intervention trials for immune function claims, eliminating legacy dossier submissions reliant on literature reviews. Zhejiang and Jiangsu provinces host domestic manufacturers with captive clinical research organizations absorbing compliance costs more efficiently than import-dependent competitors.
India
FSSAI-mandated label disclosure on elemental content elevates transparency premiums for verified sourcing claims among urban middle-class buyers. The production-linked incentive framework for active pharmaceutical ingredients extends to nutraceutical intermediates, reducing effective manufacturing costs for domestic encapsulation facilities. Maharashtra and Gujarat cluster pharmaceutical-grade manufacturing infrastructure serving both export and domestic markets.
Australia
Amateur sports participation accelerates demand for batch-tested formulations with banned substance certification. TGA-equivalent standards create specification requirements that diverge from regional product standardization efforts. Victoria and New South Wales concentrate pediatric and geriatric supplement manufacturing adopting microencapsulation technology at accelerated rates.
South Korea
Wearable biomarker integration captures micronutrient deficiency data from consumer cohorts enabling personalized supplement subscription models. MFDS extended safety assessment timelines for postbiotic and phytosome complexes delay product launches by 18-24 months versus conventional vitamin registrations. Seoul Capital Area anchors digital health convergence with subscription-based replenishment platforms.
Vietnam
Modern trade format expansion in Ho Chi Minh City and Hanoi creates shelf access for gummy and liquid supplement formats previously confined to direct-selling networks. Pharmacy channel penetration absorbs professional recommendation protocols for complex herbal formulation education. Southern provinces concentrate manufacturing infrastructure serving domestic consumption and export to neighboring ASEAN markets.
Asia Pacific Nutritional Supplements Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across channel and formulation dimensions. The vendor base organizes into three tiers: multinational pharmaceutical-hybrid firms with clinical nutrition portfolios, direct-selling infrastructure operators with community-based distributor networks, and domestic Chinese manufacturers with captive clinical research capabilities. Consolidation pressures concentrate among mid-tier encapsulation facilities facing formulation scientist scarcity. Dominant competitive moves include geographic expansion into Vietnamese pharmacy channels and portfolio diversification toward gummy and liquid formats.
Within the direct-selling infrastructure tier, Amway and Herbalife Nutrition occupy positions sustained by community-based distributor networks across tier-two Indian and Indonesian markets. Among diversified pharmaceutical-hybrid operators, Abbott Laboratories exemplifies clinical nutrition segment anchoring where healthcare practitioner endorsement commands premium positioning. BY-HEALTH Co. represents the domestic Chinese manufacturer archetype with integrated clinical research capabilities compressing NMPA approval timelines versus import-dependent competitors.
| Leading Market Players |
|---|
| Amway |
| Abbott Laboratories |
| BY-HEALTH Co. |
| Bayer AG |
| Nestlé |
| Kalbe Farma |
| Herbalife Nutrition |
| Blackmores |
| H&H Group |
| Others |
Value Network & Pricing Analysis
Family-owned mid-cap encapsulation specialists across India and Vietnam anchor regional supply, translating fragmented ownership into pricing discipline that resists the margin compression seen in private-equity-rolled-up vitamin distributors. Their retained earnings finance cold-chain infrastructure without external capital discipline, insulating NMPA-compliant manufacturers from the cost-pass-through pressures affecting import-dependent competitors.
Pricing Analysis
Bundled practitioner-endorsed formulations with clinic-based sampling programs command premium positioning against unbundled direct-to-consumer subscription models. Three-tier pricing structure across premium, standard, and economy levels separates NMPA blue-hat certified immune function claims from FSSAI-mandated label disclosure tiers and unverified mass-market vitamin combinations. Pricing pressure stems from gelatin capsule input volatility tied to Pakistani bovine hide quarantine disruptions. Urban millennial subscribers in Bangalore and Manila exhibit lowest price sensitivity; rural Indian tier-three buyers in generic tablet segments face highest elasticity.
Supply Chain Analysis
Gelatin capsule supply rests on Pakistani and Brazilian bovine hide processors, with gelatin and pectin gummy matrices drawing from Chinese pectin refiners and Indonesian seaweed extractors. Raw material dependencies span bovine-derived gelatin, probiotic culture banks, and standardized herbal marker compounds. Single-source vulnerability concentrates in halal-certified gelatin supply chains facing livestock disease quarantine protocols. Distribution runs through direct-selling community networks across tier-two Indian and Indonesian markets, with pharmacy modern trade expansion absorbing liquid and gummy formats in Vietnamese urban centers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where India's PLI scheme for nutraceutical intermediates creates manufacturing cost advantages against China's NMPA clinical trial requirements for blue-hat registrations.
For Market Incumbents: Deploy captive clinical research capabilities to compress NMPA approval timelines versus import-dependent rivals facing 18-24 month delays. Anchor capacity addition in Maharashtra and Gujarat pharmaceutical clusters to capture PLI scheme benefits. Defend against direct-to-consumer subscription erosion by reinforcing pharmacy channel control through practitioner endorsement protocols. For New Entrants and Emerging Players: Launch via Vietnamese pharmacy modern trade expansion in Ho Chi Minh City and Hanoi, where gummy and liquid formats remain underrepresented versus direct-selling saturation. Target Indonesian archipelago markets with ambient-stable probiotic powders bypassing cold-chain gaps. White-space exists in wearable biomarker-integrated subscription models for South Korean and Japanese cohorts. For Investors and Strategic Acquirers: Valuations sit cheapest among mid-tier encapsulation facilities facing formulation scientist scarcity in Singapore and Sydney. Long-term viability centers on domestic Chinese manufacturers with integrated CROs capturing NMPA compliance efficiency. Watch MFDS postbiotic approval timeline acceleration as inflection signal for novel ingredient pipeline viability.| Strategic Initiative | Industry Significance |
|---|---|
| Microencapsulation Technology Adoption | Japanese and Australian pediatric manufacturers replace enteric coating to enable ambient probiotic distribution. |
| NMPA Blue-Hat Registration Investment | Zhejiang and Jiangsu captive CROs absorb human intervention trial costs that eliminate literature-based dossiers. |
| Direct-to-Consumer Subscription Launch | Bangalore and Manila platforms capture recurring revenue through personalized dosage algorithms eroding distributor pools. |
| Vietnamese Pharmacy Channel Expansion | Ho Chi Minh City and Hanoi modern trade creates shelf access for liquid formats previously confined to direct-selling. |
| PLI Scheme Alignment for API Intermediates | Maharashtra and Gujarat facilities reduce effective manufacturing costs against import-dependent encapsulation competitors. |
Research Methodology
Coverage spans China, India, Australia, South Korea, and Vietnam, with primary inputs from each market combining interviews with formulation scientists, regulatory affairs leads, health food brand managers, pharmacy chain procurement officers, and direct-selling distributor network heads. Secondary validation draws from NMPA blue-hat registration databases, FSSAI label disclosure mandates, TGA therapeutic goods listings, MFDS novel ingredient safety assessments, and customs trade data on gelatin and pectin imports. Bottom-up segment sizing triangulates against top-down macroeconomic health expenditure trends.
Granularity-level modeling disaggregates volume and value across product type, end user physiology, form factor, and distribution channel dimensions, with additional segmentation by regional regulatory cluster and cold-chain infrastructure maturity. CAGRs derive from trend extrapolation calibrated to historical approval timeline data and sports nutrition participation rates. Forecast inputs incorporate NMPA clinical trial completion rates, FSSAI enforcement intensity indices, and ambient-stable formulation adoption curves.
Forecast precision tightens around the base case; tail outcomes carry wider variance under MFDS novel ingredient approval acceleration or Indonesian archipelago cold-chain infrastructure investment. Forecasts reflect documented assumptions on regulatory enforcement continuity and raw material trade flow stability. A small set of triggers—NMPA blue-hat registration backlog clearance, PLI scheme extension to finished dosage forms, and wearable biomarker data interoperability standards—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Pregnenolone Supplements Market
Nutritional Supplements
Nutritional Lipids Market
Nutritional Supplements
Japan Protein Market
Nutritional Supplements
Curcumin Market
Nutritional Supplements
Complete Nutrition Products Market
Nutritional Supplements
Germany Whey Protein Market
Nutritional Supplements
Lactoferrin Products Market
Nutritional Supplements
Nutrition Powder Market
Nutritional Supplements
Garlic Supplements Market
Nutritional Supplements
Postbiotic Supplements Market
Nutritional Supplements
Global Nutraceutical Market
Nutritional Supplements
Vegan Protein Market
Nutritional Supplements
Andro Supplements Market
Nutritional Supplements
Meal Replacement Products OEM Market
Nutritional Supplements
Green Food Supplements Market
Nutritional Supplements
Phytoceramide Supplement Market