
 Global Nutraceutical Market | 2026-2036
Global Nutraceutical Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nutraceutical Market Outlook
Asset-light contract manufacturing and white-label financing is reshaping competitive entry in nutraceuticals. Nestlé S.A. leverages its vertically integrated nutrition science platform to sustain R&D intensity across functional food categories. Danone S.A. anchors its position through specialized probiotic fermentation capabilities and geographic dominance in European dairy-based nutraceuticals.
Nutraceuticals comprise bioactive compounds, vitamins, minerals, probiotics, and botanical extracts formulated to deliver physiological benefits beyond basic nutrition, typically manufactured through controlled fermentation, extraction, or microencapsulation processes to preserve bioavailability. Probiotics leads product type segments due to established gut-health science and repeat-purchase loyalty, while online retailers represent the fastest-growing distribution channel as direct-to-consumer subscription models capture margin pools previously held by supermarkets. Capsule and tablet forms remain mature volume drivers, though powder formats are gaining share among athlete end users seeking dose flexibility.
FDA's Current Good Manufacturing Practice regulations and EFSA's health claims authorization framework enforce stringent substantiation standards that filter out unsubstantiated entrants. India's FSSAI and China's SAMR impose additional layer testing and import registration requirements that shape market access timelines. Stakeholders must monitor evolving NDI notification enforcement and adapt formulation pipelines to jurisdiction-specific premarket approval pathways.
Market Dynamics
The nutraceutical sector faces intensifying pressure from EFSA's health claims substantiation requirements and FDA's New Dietary Ingredient notification pathway, which are compressing product development timelines and elevating R&D thresholds for functional ingredient suppliers.
Growth Catalysts
- Sports nutrition demand:Athlete-targeted formulations incorporating bioactive peptides and adaptogenic botanicals are commanding premium positioning through direct-to-consumer channels.
- EFSA authorization framework:Validated gut-health and immunity claims for probiotics are creating regulatory moats that reward science-backed entrants with repeat-purchase loyalty.
- Microencapsulation advances:Lipid-shell and spray-drying technologies are extending shelf stability for heat-sensitive bioactives in functional beverages.
Market Restraints
- Botanical supply concentration:Ashwagandha, curcumin, and ginseng raw material sourcing clusters in India and China expose formulators to climate-driven harvest volatility.
- FDA NDI enforcement:Pre-market notification requirements for novel synthetic bioactives extend commercialization timelines by 18-24 months.
- Probiotic strain commoditization:Generic Lactobacillus and Bifidobacterium offerings are compressing margins for non-differentiated suppliers.
Strategic Opportunities
- Personalized nutrition services:Microbiome testing and genotype-informed supplement regimens in the United States are capturing margin pools from mass-market multivitamins.
- India PLI scheme:Production-linked incentives for active pharmaceutical ingredient and nutraceutical manufacturing are attracting contract fermentation capacity.
- Online subscription models:Direct-to-consumer platforms bypassing supermarket intermediaries are enabling higher-frequency replenishment and customer lifetime value expansion.
Industry Challenges
- Clinical substantiation capacity:Double-blind trial design and biostatistics expertise shortages delay EFSA and FDA claim authorization submissions.
- Cross-jurisdiction registration complexity:China's SAMR import registration and India's FSSAI layer testing create redundant compliance burdens for multi-market launches.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nutraceutical Market |
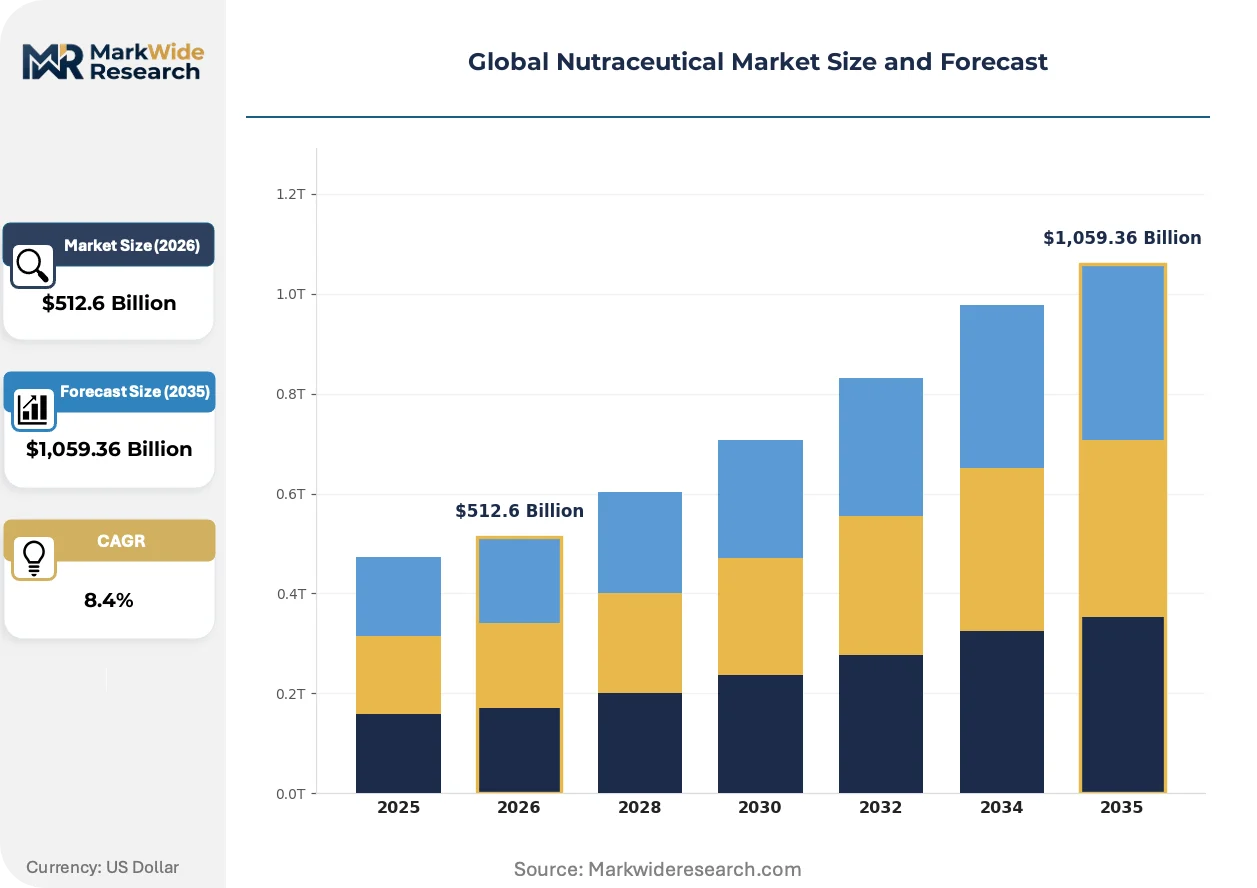
| Market Size in 2026 | $512.6 Billion |
| Market Size in 2035 | $1,059.36 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Vitamins, Minerals, Probiotics, Herbal Supplements Distribution Channel: Supermarkets, Health Stores, Pharmacies, Online Retailers End User: Adults, Athletes, Seniors, Children Form: Capsules, Tablets, Powders, Liquids |
| Companies Covered | Nestlé S.A., Abbott Laboratories, Danone S.A., Herbalife Nutrition Ltd., Amway Corporation, Glanbia plc, Archer Daniels Midland Company, PepsiCo Inc., General Mills Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nutraceutical Market Strategic Shifts
Bioprocessing advances and regulatory science maturation are compressing development cycles while reshaping how bioactive compounds reach end consumers.
Precision fermentation of recombinant proteins and rare botanical actives is rendering obsolete extraction-dependent supply chains vulnerable to agricultural volatility. Specialty ingredient houses in Denmark and the Netherlands are scaling mammalian and microbial cell platforms to produce high-purity omega-3 fatty acids and antioxidant compounds. This biotechnology shift is collapsing cost curves for previously scarce actives while decoupling production from geographic cultivation constraints.
EFSA's 2023 updated guidance on beneficial physiological effects demands randomized controlled trial evidence for immunity and cognitive function claims. European probiotic and nootropic suppliers are restructuring clinical programs to meet evidentiary thresholds. German and French functional food manufacturers are prioritizing strain-specific dossiers over generic positioning to secure authorized health claims.
Athlete and fitness enthusiast segments are abandoning fixed-dose tablets for scoopable powders and effervescent formats enabling session-specific customization. Sports nutrition brands are reformulating around instantized branched-chain amino acids and cluster-dextrin carbohydrates. This consumption pattern shift concentrates fastest in United States CrossFit and endurance cycling communities where dosing precision confers perceived performance advantages.
Global Nutraceutical Market Segmentation
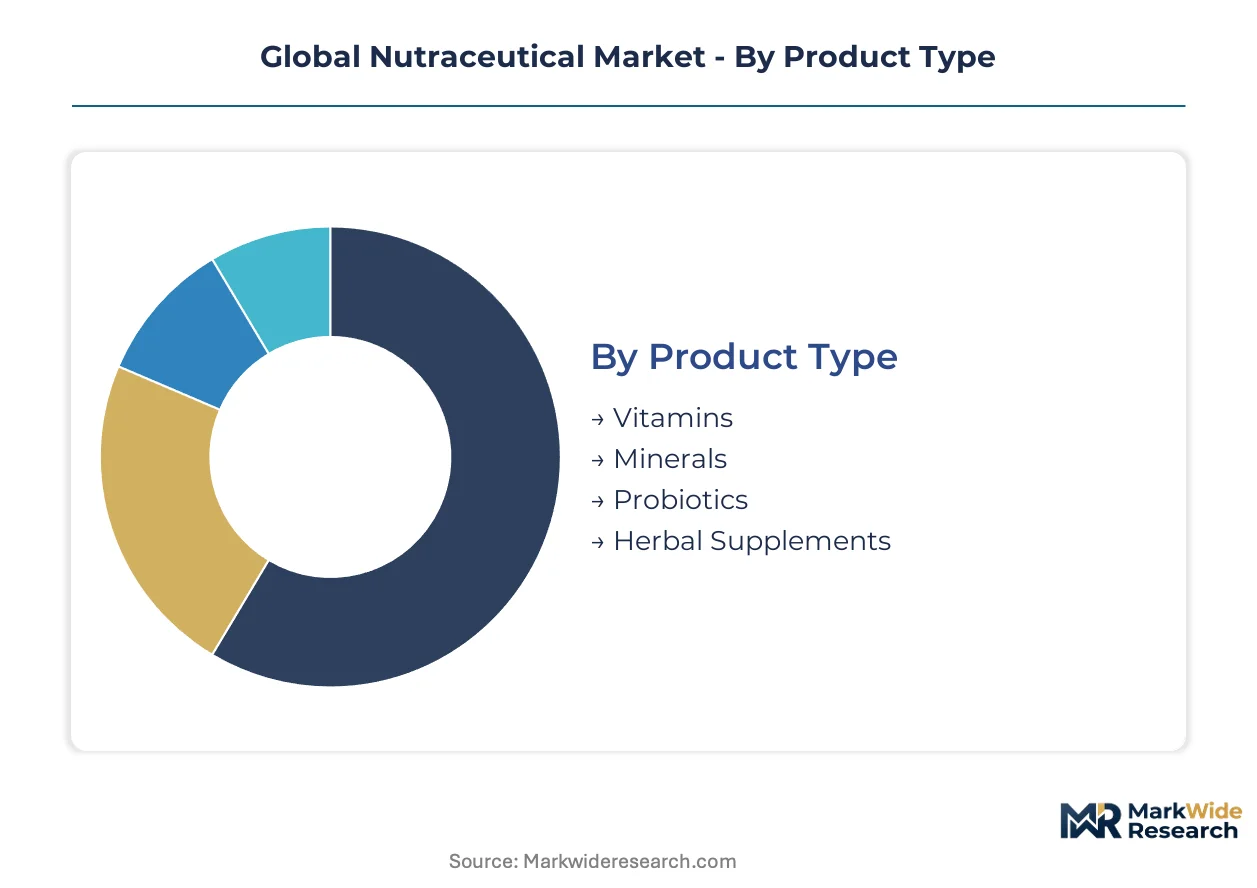
Nutraceutical segmentation reveals distinct formulation, channel, and demographic strategies that separate mass-market commodity suppliers from premium-positioned players. Each dimension carries specific regulatory, bioavailability, and margin implications that shape competitive entry and R&D allocation.
Product Type:
Cost tier stratification separates commodity vitamins from high-margin biologics requiring fermentation infrastructure and clinical substantiation investment.
- Probiotics:Live microbial strains formulated for gut microbiome modulation, typically requiring cryoprotection and acid-resistant encapsulation. Demand concentrates among repeat-purchase consumers in Germany and France where EFSA-authorized health claims command shelf price premiums. Strain-specific dossiers now filter out generic Lactobacillus suppliers lacking clinical trial backing.
- Vitamins:Synthetic or nature-identical compounds spanning fat-soluble and water-soluble categories, manufactured through chemical synthesis or fermentation. Volume leadership in United States mass-market channels faces compression from personalized nutrition services offering genotype-informed regimens.
- Minerals:Chelated and inorganic forms addressing deficiency correction, with bioavailability differentiating premium from standard positioning.
- Herbal Supplements:Botanical extracts including ashwagandha, curcumin, and ginseng, vulnerable to climate-driven harvest volatility in India and China sourcing clusters.
Probiotics commands the established base. The steepest expansion runs through herbal supplements as adaptogenic positioning gains athlete segment traction.
Distribution Channel:
Channel selection determines margin capture, customer data ownership, and regulatory compliance burden intensity across jurisdictions.
- Online Retailers:Direct-to-consumer platforms enabling subscription replenishment and microbiome test integration. United States-based fitness enthusiasts drive fastest growth through athlete-targeted formulation brands bypassing supermarket intermediaries.
- Supermarkets:Mass-market shelf space commanding volume but compressing margins through private-label competition and slotting fee structures.
- Pharmacies:Professional recommendation channel concentrated in European markets where pharmacist consultation influences probiotic and mineral selection.
- Health Stores:Specialty retail emphasizing organic certification and clean-label positioning, with geographic concentration in urban United States and Australian markets.
Supermarkets retain volume leadership. Online retailers are gaining share fastest through subscription model customer lifetime value expansion.
End User:
Customer type segmentation aligns formulation complexity, dosing precision, and clinical substantiation requirements with physiological life-stage needs.
- Athletes:Performance-optimized formulations incorporating bioactive peptides, branched-chain amino acids, and cluster-dextrin carbohydrates. United States CrossFit and endurance cycling communities drive powder format preference for session-specific customization.
- Adults:General wellness maintenance segment spanning multivitamin and single-nutrient supplementation, facing displacement from personalized nutrition services.
- Seniors:Bone density, cognitive function, and muscle preservation targeting, with EFSA and FDA claim authorization requirements elevating R&D thresholds.
- Children:Palatability-driven formats including gummies and liquids, with stringent safety testing and pediatric dosing regulation in United States and European markets.
Adults represent the installed base. Athletes show the steepest trajectory through premium sports nutrition positioning.
Form:
Physical delivery format selection trades manufacturing capital intensity, shelf stability, and consumer convenience against bioavailability preservation.
- Powders:Scoopable formats enabling dose titration and beverage integration, preferred by athlete segments seeking pre-workout and recovery customization. Instantization technology investments separate premium from clumping commodity offerings.
- Capsules:Gelatin and vegetable-based shells protecting acid-sensitive actives, with enteric coating options for probiotic and enzyme delivery.
- Tablets:Mature high-volume format facing compression from powder and liquid alternatives, with direct compression and wet granulation process differentiation.
- Liquids:Pediatric and geriatric accessibility format requiring preservative systems and stability testing, with higher shipping cost profiles constraining e-commerce economics.
Capsules anchor current volume. Powders are climbing the fastest through athlete segment format migration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
United States functional food brands command shelf price premiums that German probiotic manufacturers struggle to match, revealing a stark pricing-power asymmetry between North American direct-to-consumer channels and European pharmacy-dependent distribution.
United States
Personalized nutrition services and athlete-targeted sports nutrition brands drive fastest growth through subscription-based replenishment models. FDA's Current Good Manufacturing Practice regulations enforce stringent quality standards that filter out undercapitalized entrants. California's Bay Area and Austin, Texas host clusters of microbiome testing startups integrating genotype-informed supplement regimens.
Germany
EFSA-authorized health claims for probiotics create regulatory moats rewarding science-backed suppliers with repeat-purchase loyalty in pharmacy channels. Germany's Federal Office of Consumer Protection and Food Safety enforces strict strain-specific dossier requirements for gut-health positioning. Bavaria and North Rhine-Westphalia concentrate precision fermentation facilities producing high-purity bioactive compounds.
China
SAMR's import registration and layer testing requirements shape market access timelines for foreign functional food brands seeking entry. China's dual carbon goals accelerate domestic biotechnology investment in recombinant protein production. Yangtze River Delta cities including Shanghai and Suzhou host contract manufacturing capacity serving both domestic and export markets.
India
FSSAI's layer testing and import registration create compliance burdens that domestic ashwagandha and curcumin extractors navigate more efficiently than foreign competitors. India's PLI scheme for active pharmaceutical ingredient and nutraceutical manufacturing attracts fermentation capacity expansion. Maharashtra and Gujarat host raw material processing clusters vulnerable to climate-driven harvest volatility.
Japan
Aging demographics sustain demand for cognitive function and bone density formulations requiring clinical substantiation investment. Japan's Ministry of Health, Labour and Welfare maintains strict functional food labeling standards that elevate R&D thresholds. Tokyo-Osaka corridor manufacturers specialize in palatability-driven formats including gummies and liquids for senior consumption.
Global Nutraceutical Market Competitive Environment
Platform integrators command the system tier; component specialists sit upstream supplying bioactive extracts and fermentation-derived actives. The vendor base stratifies between multinational nutrition science platforms with captive R&D infrastructure and asset-light contract manufacturers serving white-label demand. Three archetypes dominate: vertically integrated food conglomerates with functional food divisions, specialized probiotic fermentation houses, and direct-to-consumer sports nutrition brands. Competitive moves concentrate on precision fermentation capacity expansion and microbiome testing platform acquisitions.
Among Swiss-domiciled nutrition conglomerates, Nestlé S.A. occupies a position exemplifying vertically integrated platform strategy, while France-based Danone S.A. represents specialized probiotic fermentation capabilities. Irish nutritionals supplier Glanbia plc anchors the sports nutrition ingredient tier, supplying bioactive peptides and dairy-derived proteins to athlete-targeted formulation brands.
| Leading Market Players |
|---|
| Nestlé S.A. |
| Abbott Laboratories |
| Danone S.A. |
| Herbalife Nutrition Ltd. |
| Amway Corporation |
| Glanbia plc |
| Archer Daniels Midland Company |
| PepsiCo Inc. |
| General Mills Inc. |
| Others |
Value Chain & Pricing Dynamics
Undercapacity in precision fermentation facilities across Denmark and the Netherlands is driving supplier discipline and sustaining premium pricing for bioactive peptides and omega-3 fatty acids. Capacity constraints in these biotechnology hubs force buyers into longer contract commitments while elevating spot-market premiums for uncontracted volumes.
Pricing Analysis
The customization-premium spread between athlete-targeted powder formulations and standard multivitamin tablets spans three distinct pricing tiers. Subscription-based direct-to-consumer models command the highest premiums through personalized microbiome integration, while mass-market supermarket channels face compression from private-label competition. Price differentiation rests on strain-specific clinical substantiation and EFSA authorization status. Cost compression in generic probiotic segments is intensifying because of Lactobacillus commoditization. Athlete segments show the least price sensitivity, prioritizing dosing precision over per-unit cost.
Supply Chain Analysis
Climate-driven harvest volatility in Indian ashwagandha and Chinese curcumin sourcing clusters dominates supply chain risk for botanical extract formulators. Raw material dependencies center on fermentation-derived actives from European biotechnology hubs, marine-sourced omega-3 from Peruvian anchovy fisheries, and adaptogenic botanicals from South Asian cultivation zones. Single-source vulnerability in heat-sensitive probiotic cryoprotection logistics creates spoilage exposure during transoceanic shipment. Distribution runs through direct-to-consumer platforms bypassing supermarket intermediaries, with contract manufacturers in India and China serving white-label demand.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating through direct-to-consumer platform consolidation, as subscription-based replenishment models capture customer data and displace pharmacy-dependent intermediaries. This fragmentation among downstream channels is compressing margins for non-differentiated suppliers.
For Market Incumbents: Entrench proprietary strain dossiers through expanded clinical trial investment targeting EFSA immunity and cognitive function claims. Acquire precision fermentation capacity in Denmark and the Netherlands to secure captive supply of heat-sensitive bioactives. This defensive posture counters emerging biotechnology entrants with recombinant protein platforms.
For New Entrants and Emerging Players: Personalized nutrition services in the United States represent the most penetrable entry point, specifically microbiome testing integration with genotype-informed supplement regimens. India's PLI scheme for active pharmaceutical ingredient manufacturing offers contract fermentation white-space for export-oriented production. A direct-to-consumer subscription go-to-market model bypasses supermarket slotting fees and captures recurring revenue.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among direct-to-consumer sports nutrition brands with athlete segment loyalty. Long-term viability across the analysis window favors precision fermentation specialists with mammalian cell platform capabilities. The signal to watch is FDA NDI notification enforcement intensity for novel synthetic bioactives.
| Strategic Initiative | Industry Significance |
|---|---|
| Precision Fermentation Capacity Expansion | Denmark and Netherlands facilities decouple high-purity omega-3 production from marine sourcing volatility. |
| EFSA Health Claims Dossier Investment | Strain-specific clinical substantiation creates regulatory moats against generic probiotic competitors in Germany. |
| Direct-to-Consumer Platform Launch | Subscription replenishment models bypass supermarket intermediaries and capture customer lifetime value in United States. |
| Microbiome Testing Integration | Genotype-informed regimens displace mass-market multivitamins through personalization in California and Texas clusters. |
| India PLI Scheme Participation | Production-linked incentives attract contract manufacturing capacity for ashwagandha and curcumin extraction. |
Study Parameters
A spread of perspectives from brand managers at functional food manufacturers, category buyers at online retailers, fermentation facility operations directors, and regulatory affairs specialists converged on the working assumptions. Primary interviews with these stakeholders combined with secondary validation from FDA NDI notification databases, EFSA health claims authorization registers, FSSAI layer testing protocols, and customs trade data for botanical raw materials. Bottom-up demand modeling across product types and top-down market sizing triangulated volume and value estimates.
Demand-supply balance dynamics anchored the analytical framework across the projection horizon. Segmentation dimensions modeled include product type tier, distribution channel structure, end-user physiological life-stage, and physical delivery format. CAGRs derived from category-level growth trajectories incorporated precision fermentation technology diffusion rates, EFSA authorization pipeline velocity, and athlete segment format migration patterns.
Macroeconomic conditions sit as an overlay; deviation in consumer discretionary spending and freight logistics costs would shift the trajectory. Forecasts reflect assumptions on regulatory enforcement continuity and biotechnology cost curve collapse. Material shifts in FDA NDI notification timelines or climate-driven botanical harvest failures would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nutritional Supplements
Effervescent Product Market
Nutritional Supplements
Personalized Nutrition Market
Nutritional Supplements
Skin-Booster Beverages Market
Nutritional Supplements
Phytonutrients Market
Nutritional Supplements
Health Supplements Market
Nutritional Supplements
Africa Nutraceutical Market
Nutritional Supplements
Gummy Vitamins Market
Nutritional Supplements
Lactates Market
Nutritional Supplements
Nutritional Supplements Market
Nutritional Supplements
Bypass Fat Supplement Market
Nutritional Supplements
Global Ashwagandha Extract Market
Nutritional Supplements
GLP-1 Meal Replacement Market
Nutritional Supplements
Human Nutrition Market
Nutritional Supplements
Low-Carb Fat Loss Market
Nutritional Supplements
Nutritional Yeast Market
Nutritional Supplements
Cod Liver Oil Market