
 Europe Commercial Drones Market | 2026-2036
Europe Commercial Drones Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Commercial Drones Market Insights
A capital-intensity divergence between sensor-integrated platforms and basic imaging units is bifurcating competitive dynamics in the European commercial drone sector. Parrot Drones leverages its French R&D base to anchor premium positioning in civilian surveillance payloads. Quantum-Systems GmbH sustains manufacturing scale for fixed-wing platforms serving German energy infrastructure clients. Flyability SA differentiates through collision-tolerant designs purpose-built for confined industrial inspections.
Europe commercial drones are unmanned aerial vehicles with maximum takeoff weights typically below 25 kilograms, equipped with stabilized gimbals, real-time kinematic GPS, and modular payload bays for sensors or cargo delivery. These systems perform aerial data capture, asset monitoring, and last-mile logistics across European industrial and agricultural operations. Multi-rotor configurations dominate short-range photography and surveillance deployments due to vertical takeoff flexibility and lower operator certification thresholds. Fixed-wing platforms lead energy corridor mapping and large-scale agriculture across France and Spain where endurance requirements exceed 45 minutes per sortie. Hybrid architectures represent the fastest-growing product category as logistics operators seek combined vertical launch with efficient cruise performance for inter-urban delivery routes.
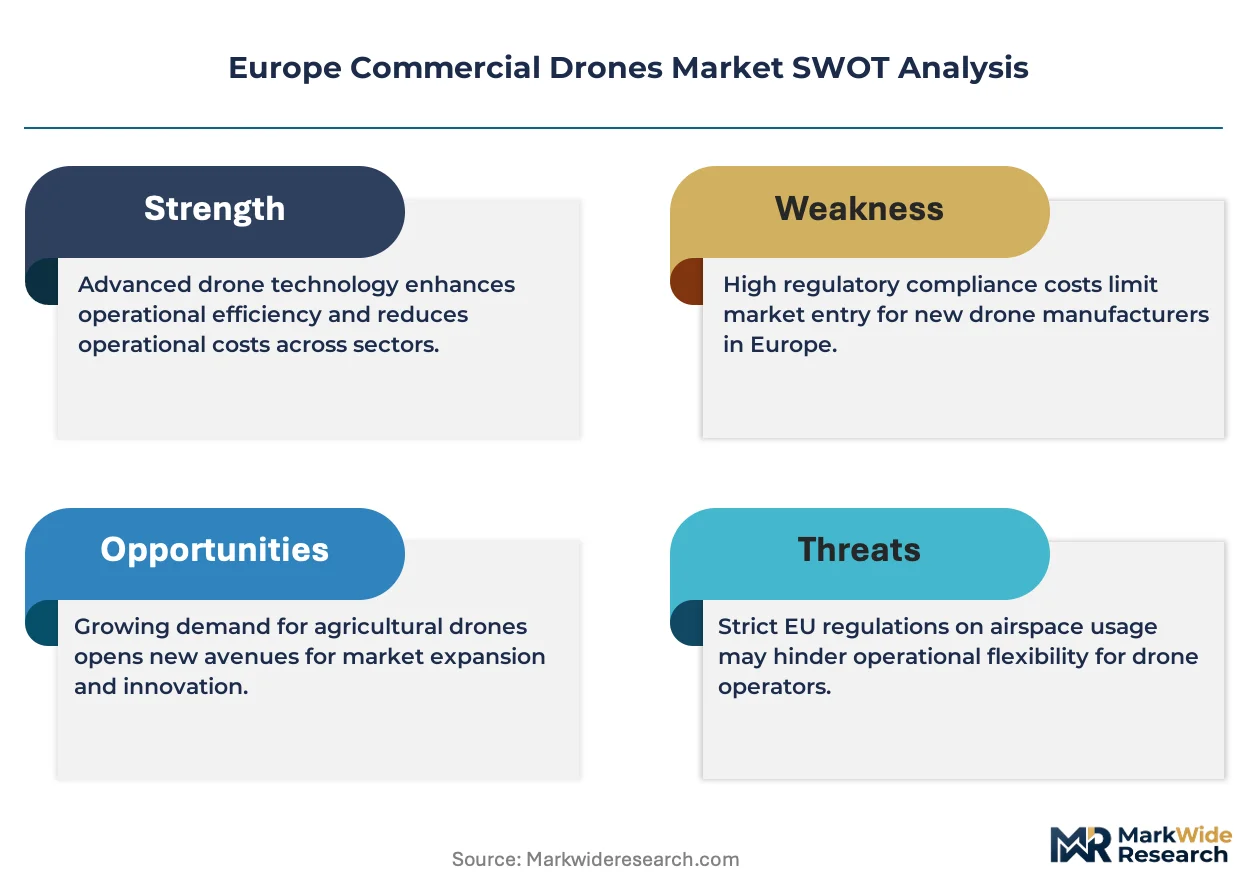
EASA's EU 2019/947 framework and CE marking requirements under the EU Drone Regulation shape product certification timelines and operator training obligations across member states. REACH compliance and RoHS directives constrain battery chemistry selections and electronics sourcing for manufacturers targeting European distribution. National aviation authorities in Italy and Poland impose supplementary no-fly zone databases that fragment route planning software requirements. Stakeholders must monitor EASA's forthcoming U-space regulatory package for automated traffic management integration decisions.
Market Dynamics
EASA's EU 2019/947 framework is compressing certification timelines while fragmenting national implementation, creating a dual-speed market where harmonized operators scale faster than those navigating member-state overlays.
Growth Catalysts
- Precision Agriculture:German and French farming cooperatives deploy RTK-GPS equipped multi-rotor systems for variable-rate input application, cutting fertilizer costs by enabling centimeter-accurate field mapping.
- EU Green Deal:Carbon monitoring mandates for industrial sites accelerate demand for methane-detecting payloads across Dutch petrochemical clusters and Polish coal transition zones.
- Hybrid Architectures:Logistics operators in Spain and Italy adopt tilt-rotor designs combining VTOL flexibility with fixed-wing endurance for inter-urban medical supply corridors.
Market Restraints
- Lithium Supply Concentration:Battery pack costs fluctuate with Chinese cathode material pricing, squeezing margin structures for mid-tier European assemblers lacking long-term offtake agreements.
- CE Marking Complexity:Module B+C2 conformity assessment under EU 2019/947 extends product launch timelines by eight to fourteen months for novel payload integrations.
- Pilot Certification Bottlenecks:EASA's A1/A2/A3 open-category thresholds create operator training backlogs in member states with limited accredited test centers, particularly Eastern Europe.
Strategic Opportunities
- U-Space Integration:EASA's forthcoming automated traffic management standards enable beyond-visual-line-of-sight cargo routes across Benelux corridors without human spotter requirements.
- Collision-Tolerant Inspections:Confined-space asset monitoring in Scandinavian offshore wind installations remains underpenetrated, favoring spherical-cage designs for turbine internal blade surveys.
- 5G-Edge Convergence:Real-time AI inference on drone-mounted units, enabled by German telecom infrastructure rollouts, opens predictive maintenance contracts for rail network operators.
Industry Challenges
- Embedded Systems Talent:Flight control firmware engineering expertise concentrates in Munich and Toulouse clusters, forcing peripheral operators into costly relocation packages or remote team fragmentation.
- Legacy System Integration:Industrial clients in Baden-Württemberg's automotive belt demand API compatibility with decades-old SCADA architectures, extending deployment timelines.
- RoHS Compliance Costs:REACH substance restrictions on hexavalent chromium plating force supply chain requalification for corrosion-resistant airframe components sourced from Eastern European subcontractors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Commercial Drones Market |
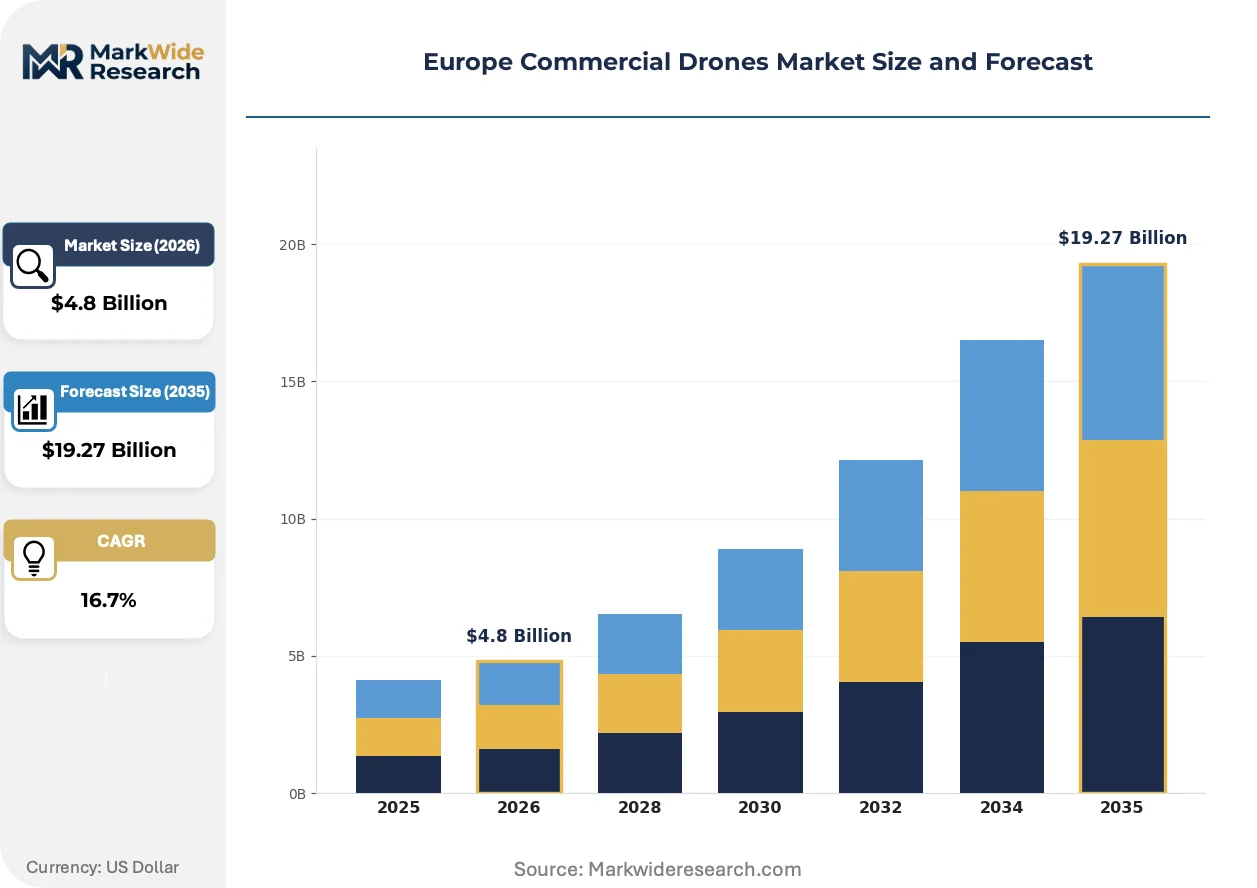
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $19.27 Billion |
| CAGR (2026 – 2036) | 16.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Fixed-Wing, Multi-Rotor, Hybrid, Single-Rotor Application: Agriculture, Surveillance, Delivery, Photography End User: Transportation, Construction, Energy, Logistics Technology: LiDAR, Aerial Imaging, GPS, Collision Avoidance |
| Companies Covered | Onyx Scan Advanced LiDAR Systems, Flyability SA, Parrot Drones, Quantum-Systems GmbH, Delair, Azure Drones SAS, AltiGator Unmanned Solutions, Wingtra, Terra Drone Corporation, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Commercial Drones Market Trends and Innovations
Sensor fusion architectures and edge computing payloads are redefining competitive differentiation, compressing the value capture window for hardware-centric vendors while expanding recurring revenue pools for analytics-integrated platforms.
Hyperspectral imaging payloads for agricultural stress detection is bifurcating the precision farming segment. Bayer Crop Science and BASF digital units in Germany demand laboratory-grade radiometric calibration, while French cooperative networks prioritize cost-optimized NDVI alternatives. This technology divergence is compressing mid-range multispectral offerings and forcing component suppliers to pick premium analytical or volume hardware lanes.
REACH substance restrictions on perfluorinated compounds are reshaping waterproofing material selections for electronics housings. Manufacturers serving Nordic offshore wind clients must reformulate conformal coatings or source alternative IP-rated enclosures from qualified suppliers. Italian and Greek energy operators face extended procurement cycles as they await requalified component certifications under the same framework.
Energy infrastructure buyers in Germany and France now unbundle hardware acquisition from data-analytics subscriptions, treating drone platforms as depreciable capital while purchasing inspection insights through multi-year service agreements. This consumption-pattern shift squeezes pure-hardware margins and elevates software-native vendors with recurring-revenue models. Spanish solar farm operators exhibit the most pronounced preference for outcome-based contracting, paying per identified thermal anomaly rather than per flight hour.
Europe Commercial Drones Market Segmentation
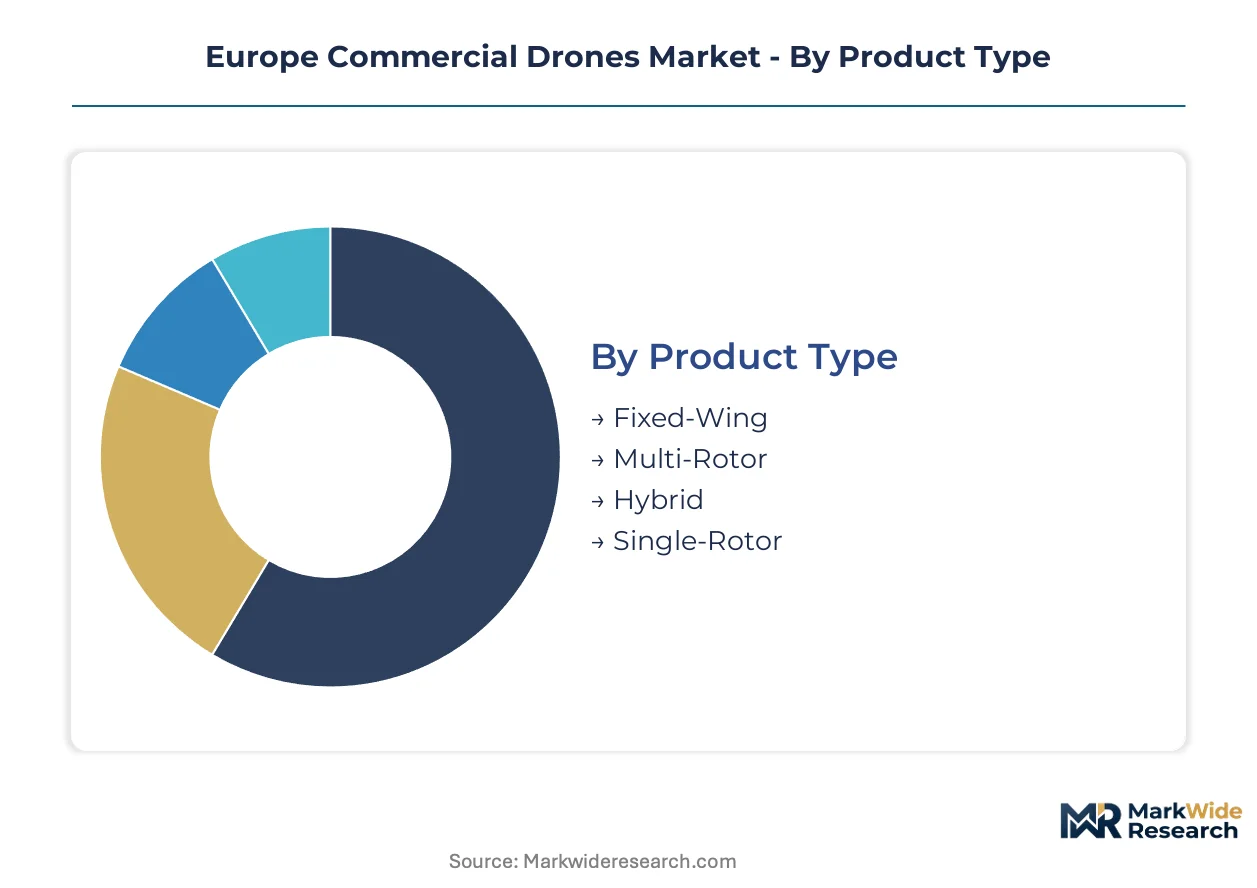
Segmentation in the European commercial drones market reveals how platform architecture, payload integration, and regulatory certification create distinct competitive arenas. Understanding these divides helps vendors allocate R&D resources and navigate EASA's tiered compliance pathways.
Product Type:
Multi-rotor platforms face intensifying substitution pressure from hybrid architectures as logistics operators demand both VTOL flexibility and extended range.
- Multi-Rotor:Vertical takeoff capability with four to eight rotors dominates short-range photography and precision agriculture. German farming cooperatives in Bavaria favor these for centimeter-accurate field mapping under EASA's A3 open category.
- Hybrid:Tilt-rotor designs combine vertical launch with fixed-wing cruise efficiency. Spanish medical supply corridors and Italian inter-urban logistics routes drive adoption where endurance requirements exceed 45 minutes.
- Fixed-Wing:Conventional aerodynamic configurations serve energy corridor mapping across France and Spain. Platforms require runway or catapult launch, limiting deployment flexibility.
- Single-Rotor:Helicopter-style designs with larger payload capacity serve specialized heavy-lift applications. Higher mechanical complexity elevates maintenance costs and operator certification thresholds.
Multi-rotor retains volume leadership; hybrid holds the steepest expansion curve.
Application:
Cost-tier stratification separates premium analytical services from commodity imaging, with agriculture commanding the widest price spread between basic NDVI and laboratory-grade hyperspectral contracts.
- Agriculture:Variable-rate input application via RTK-GPS equipped platforms cuts fertilizer costs for French and German cooperatives. Bayer Crop Science and BASF digital units demand radiometrically calibrated hyperspectral payloads.
- Surveillance:Real-time monitoring for border security and critical infrastructure. Collision-tolerant spherical designs penetrate confined spaces in Scandinavian offshore wind installations.
- Delivery:Last-mile medical and retail logistics across Benelux corridors. EASA's forthcoming U-space standards will enable beyond-visual-line-of-sight operations without human spotters.
- Photography:Aerial cinematography and real estate marketing. Stabilized gimbal systems with sub-25kg MTOW dominate under simplified operator certification.
Photography anchors volume shipments; delivery climbs the fastest as regulatory barriers fall.
End User:
Procurement sophistication varies sharply by sector, with energy buyers unbundling hardware from analytics while construction clients bundle turnkey solutions.
- Energy:Methane detection and thermal anomaly identification for Dutch petrochemical clusters and Polish coal transition zones. Outcome-based contracting pays per identified defect rather than flight hour.
- Logistics:Inter-urban cargo routes and warehouse inventory cycle counting. German automotive suppliers in Baden-Württemberg demand API compatibility with legacy SCADA architectures.
- Construction:Progress monitoring and volumetric surveying. Project managers prioritize rapid deployment over analytical depth.
- Transportation:Rail network inspection and predictive maintenance enabled by 5G-edge convergence. German telecom infrastructure rollouts support real-time AI inference on drone-mounted units.
Energy leads procurement value; logistics gains share fastest through U-space preparation.
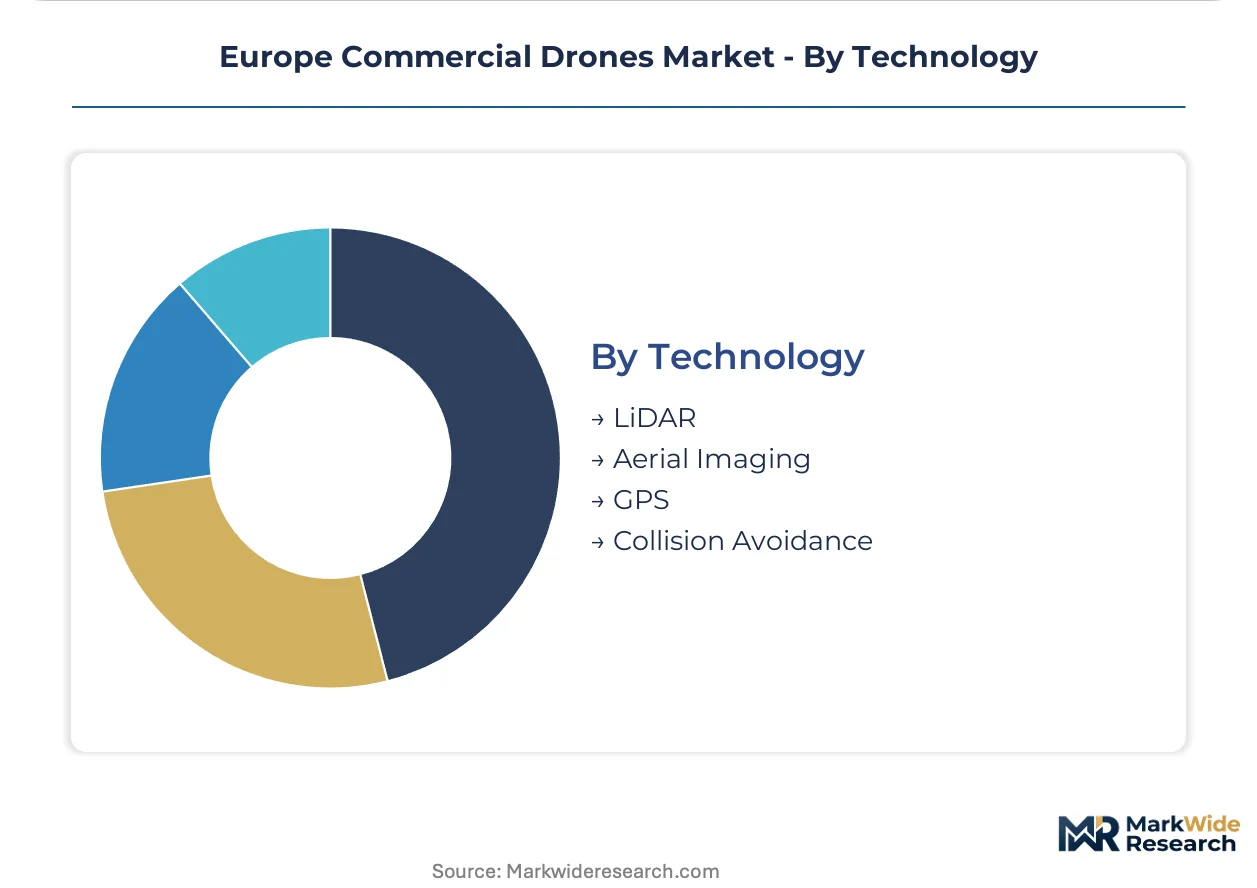
Technology:
Supply concentration in flight control firmware engineering—centered on Munich and Toulouse clusters—constrains scaling for peripheral technology integrators.
- Aerial Imaging:Multispectral and hyperspectral sensors for agricultural stress detection. Technology divergence compresses mid-range offerings between premium analytical and volume hardware lanes.
- Collision Avoidance:Spherical cage designs and optical flow systems for confined industrial inspections. Flyability SA's collision-tolerant platforms target underpenetrated offshore wind internal blade surveys.
- LiDAR:Laser scanning for precision topographic mapping and infrastructure digitization. Higher payload weight pushes platforms into stricter certification categories.
- GPS:Real-time kinematic positioning enabling centimeter-accurate navigation. REACH and RoHS compliance constrains battery chemistry selections for extended endurance.
Aerial imaging dominates installed base; collision avoidance expands most quickly through safety mandates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German industrial buyers command 15-20% pricing premiums over Spanish procurement counterparts for equivalent payload specifications, reflecting certification density and technical support proximity. This asymmetry shapes vendor allocation decisions across the continent.
Germany
Bavarian farming cooperatives deploy RTK-GPS equipped multi-rotor systems for centimeter-accurate field mapping, while Baden-Württemberg's automotive belt demands API compatibility with legacy SCADA architectures. EASA's A1/A2/A3 open-category thresholds create operator training backlogs in eastern states with limited accredited test centers. Munich and Stuttgart clusters concentrate flight control firmware engineering expertise, forcing peripheral operators into costly relocation packages.
France
Bayer Crop Science and BASF digital units in metropolitan France demand radiometrically calibrated hyperspectral payloads for agricultural stress detection, while cooperative networks prioritize cost-optimized NDVI alternatives. ANSM and CNIL oversight adds data governance layers to cross-border operations. Toulouse anchors civilian surveillance payload development alongside Paris-region logistics corridor planning for U-space integration.
Spain
Solar farm operators in Andalusia and Extremadura exhibit pronounced preference for outcome-based contracting, paying per identified thermal anomaly rather than per flight hour. Medical supply corridors between Barcelona and Valencia drive tilt-rotor adoption where endurance requirements exceed 45 minutes. National aviation authorities maintain supplementary no-fly zone databases that fragment route planning software requirements.
Netherlands
Carbon monitoring mandates for industrial sites accelerate demand for methane-detecting payloads across Rotterdam petrochemical clusters and Amsterdam port transition zones. Benelux corridor preparation for EASA's forthcoming U-space standards enables beyond-visual-line-of-sight cargo routes without human spotter requirements. REACH compliance and RoHS directives constrain battery chemistry selections for manufacturers targeting Dutch distribution.
Poland
Coal transition zones in Silesia generate thermal anomaly inspection demand as EU Green Deal implementation accelerates. Eastern Europe's limited accredited test centers extend pilot certification timelines under EASA's harmonized framework. Warsaw and Krakow industrial zones attract mid-tier assemblers seeking proximity to Eastern European subcontractors for airframe component sourcing.
Europe Commercial Drones Market Competitive Landscape
Technology leadership and cost leadership are held by different player archetypes, with sensor-integrated platforms commanding premium positioning against commoditized imaging units. The vendor base spans French R&D-centric specialists, German manufacturing-scale operators, and Swiss collision-tolerance innovators. Three archetypes dominate: premium payload integrators, volume hardware assemblers, and niche safety-technology developers. Competitive moves concentrate on strategic partnerships for U-space readiness and portfolio diversification into analytics subscriptions.
Among French specialists, Parrot Drones anchors premium positioning in civilian surveillance payloads through its domestic R&D base. Flyability SA exemplifies the niche safety-technology archetype with collision-tolerant designs purpose-built for confined industrial inspections. Quantum-Systems GmbH represents German manufacturing-scale capabilities for fixed-wing platforms serving energy infrastructure clients.
| Leading Market Players |
|---|
| Onyx Scan Advanced LiDAR Systems |
| Flyability SA |
| Parrot Drones |
| Quantum-Systems GmbH |
| Delair |
| Azure Drones SAS |
| AltiGator Unmanned Solutions |
| Wingtra |
| Terra Drone Corporation |
| Others |
Pricing and Supply Chain Analysis
Forty-five to sixty-day component lead times for RTK-GPS modules and stabilized gimbal assemblies concentrate pricing power with German and French system integrators who maintain buffer inventories against Chinese cathode material volatility. This inventory discipline separates premium payload vendors from mid-tier assemblers exposed to spot-market lithium pricing.
Pricing Analysis
Configured-to-order premiums for radiometrically calibrated hyperspectral payloads command spreads exceeding standard NDVI-equipped units by substantial margins. Three-tier pricing structure across certified analytical-grade, commercial survey-grade, and basic imaging tiers reflects EASA's A1/A2/A3 certification thresholds as primary price differentiation drivers. Pricing pressure stems from Chinese battery pack cost volatility squeezing mid-tier European assemblers lacking long-term offtake agreements. German energy infrastructure buyers exhibit lowest price sensitivity due to outcome-based contracting models, while Spanish solar farm operators demonstrate highest sensitivity through per-anomaly payment structures.
Supply Chain Analysis
Inventory buffers for collision-tolerant cage components and conformal coating materials extend procurement cycles by eight to fourteen weeks as REACH substance restrictions force requalification of Eastern European subcontractors. Supply concentration centers on Munich and Toulouse for flight control firmware engineering, China for lithium-ion cathode materials, and Poland for airframe component fabrication. Raw material dependencies include cobalt-free cathode formulations, carbon-fiber reinforced polymers, and IP-rated electronics housings. Single-source vulnerability in RTK-GPS module supply from Swiss and German specialty vendors creates bottleneck risk. Distribution runs through direct OEM relationships with energy and logistics end-users, bypassing traditional aerospace distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EASA's U-space regulatory package represents a technological inflection that will automate beyond-visual-line-of-sight operations and reshape competitive positioning across European commercial drone markets.
For Market Incumbents: Fortify recurring-revenue streams by unbundling hardware from analytics subscriptions before pure-software entrants capture inspection-data contracts. Deepen backward integration into flight control firmware development to reduce dependency on Munich and Toulouse engineering clusters. Prioritize U-space certification investment to defend corridor-route exclusivity against logistics specialists. For New Entrants and Emerging Players: Anchor in Scandinavian offshore wind internal blade surveys where collision-tolerant spherical designs remain underpenetrated and procurement specifications favor safety-certified niche platforms. Target Polish and Eastern European pilot training markets where EASA A1/A2/A3 certification backlogs create service-revenue opportunities. Pursue API-first integration strategies for Baden-Württemberg automotive SCADA compatibility requirements. For Investors and Strategic Acquirers: Long-term, this sits as a regulatory-capture play because U-space integration and automated traffic management standards will consolidate route economics around first-mover certification holders. Acquisition target archetype: software-native vendors with recurring-revenue inspection contracts and existing EASA operational authorizations. Signal to watch: Benelux corridor U-space deployment timelines as proxy for scalable BVLOS revenue recognition.| Strategic Initiative | Industry Significance |
|---|---|
| U-Space Certification Investment | First-mover automated traffic management integration secures exclusive BVLOS corridor access across Benelux logistics routes. |
| Backward Integration into Flight Control Firmware | In-house embedded systems development reduces dependency on Munich-Toulouse engineering clusters and accelerates product cycles. |
| Collision-Tolerant Platform Specialization | Spherical-cage designs penetrate underpenetrated Scandinavian offshore wind internal turbine inspections with safety-mandated procurement. |
| Outcome-Based Contracting Transition | Per-identified-defect revenue models align vendor incentives with Spanish solar farm and German energy infrastructure buyer preferences. |
| 5G-Edge Convergence Partnership | Real-time AI inference capabilities on drone-mounted units open predictive maintenance contracts with German rail network operators. |
Research Methodology
Desk research of EASA regulatory filings, EU Drone Regulation implementation databases, and REACH substance restriction updates preceded structured interviews with flight operations managers at energy infrastructure operators, precision agriculture cooperative directors, logistics corridor planners, and embedded systems engineering leads. Primary fieldwork with U-space implementation working groups and secondary validation through customs trade data for drone component imports supported bottom-up platform shipment estimates and top-down addressable market sizing.
Variance decomposition across product architecture, payload integration tier, and regulatory certification category shaped the analytical framework over the projection horizon. Segmentation dimensions modeled include platform type, application vertical, end-user procurement sophistication, and technology integration depth. CAGRs were derived from installed base growth rates and replacement cycle analysis, with cross-checks against EASA operator registration trajectories and battery chemistry cost curves.
Material uncertainties — lithium supply concentration disruptions, U-space implementation delays, and REACH substance restriction scope expansions — sit outside the modeled envelope. Forecasts reflect assumptions about regulatory harmonization progress and technology adoption S-curves rather than deterministic pathways. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
UAV
Commercial UAV Market
UAV
Global Multirotor UAV Market
UAV
Drone Inspection Service Market
UAV
Asia Pacific Commercial Drone Market
UAV
Drone Flight Controller System Market
UAV
Drone Lens Market
UAV
Miniature Drone Market
UAV
Asia Pacific Small UAV Market
UAV
North America Drone Services Market
UAV
Europe Drones Market
UAV
UAV Simulator Market
UAV
Global Smart Commercial Drones Market
UAV
Stratospheric Flying Drone Market
UAV
Europe Drone Light Shows Market
UAV
Rc Helicopter Market
UAV
Rotary Blade UAV Drones Market