
 Salmon Feed Market | 2026-2036
Salmon Feed Market Size, Share, and Industry Trends Forecast 2026-2036
Salmon Feed Market Insights
The EU Green Deal is shifting ingredient sourcing requirements for marine proteins across North Atlantic salmon production. BioMar leverages its Danish R&D centers to reformulate feeds with reduced fish meal dependence. Skretting anchors Norwegian supply through its integrated nutrition platform serving Mowi Feed and independent growers. Cargill competes via backward integration into alternative protein streams for Atlantic salmon diets.
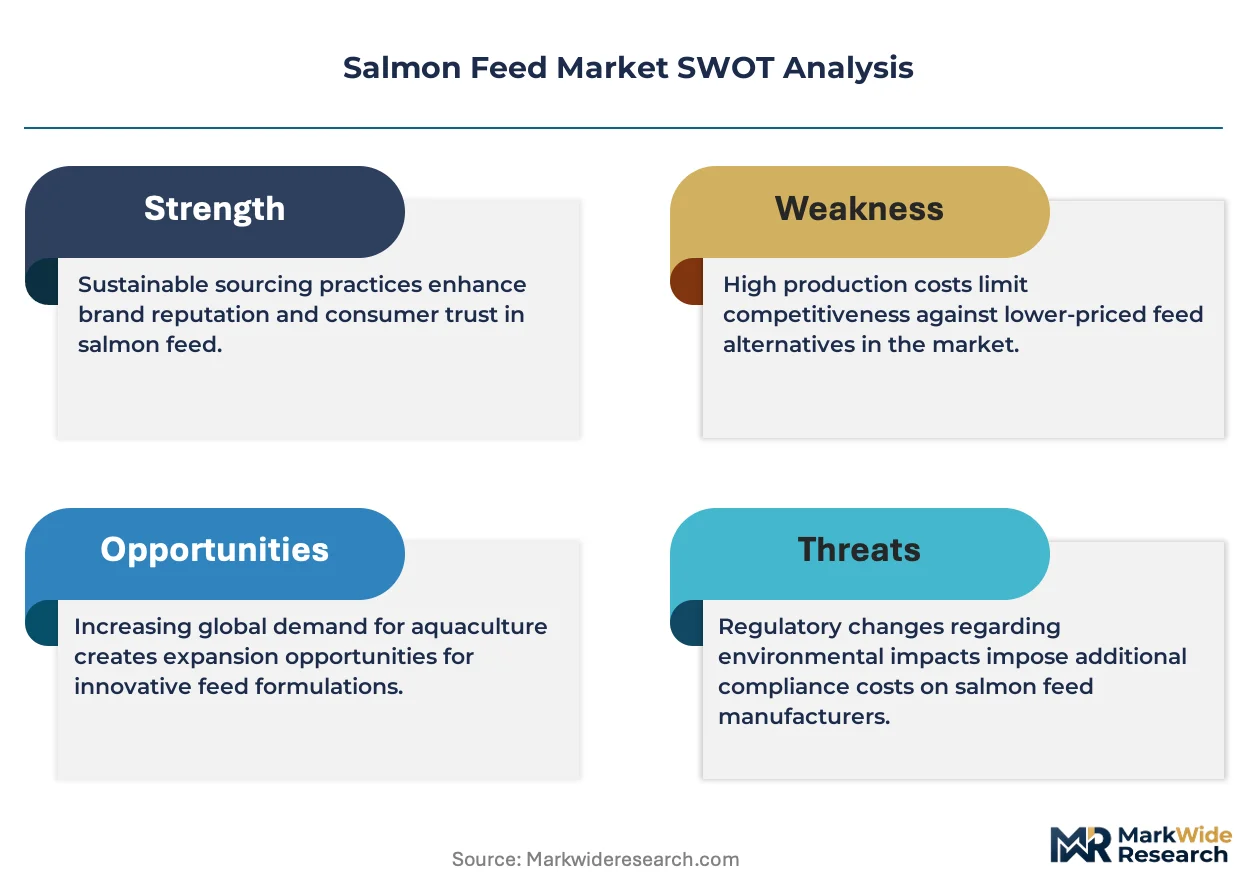
Salmon feed comprises nutritionally complete diets formulated with protein meals, oils, vitamins, and minerals, extruded into water-stable pellets with target digestibility coefficients exceeding 90 percent for optimal feed conversion ratios in cold-water carnivorous fish. The ingredient source dimension shows plant-based proteins displacing fish meal in conventional formulations, though fish meal retains premium positioning in early-stage diets. Formulation type reveals fortified feeds capturing margin pools as producers seek functional additives for disease resistance and pigment retention in harvest-ready salmon.
Norwegian Food Safety Authority standards, EU REACH chemical registration requirements, and Scotland's aquaculture regulatory framework collectively constrain feed additive portfolios and mandate environmental discharge monitoring. These rules elevate compliance costs for compound feed manufacturers while creating technical barriers for unqualified entrants. Stakeholders must track evolving marine ingredient quotas and certification schemes to secure long-term supply contracts with vertically integrated salmon producers.
Market Dynamics
The EU Green Deal's marine ingredient sourcing quotas are restructuring North Atlantic salmon feed procurement, forcing compound feed manufacturers to reformulate around certified alternative proteins while vertically integrated Norwegian producers expand captive milling capacity.
Growth Catalysts
- EU Green Deal marine protein quotas:The tightening framework on wild-caught fish meal usage is accelerating plant-protein adoption in Norwegian and Scottish feed mills.
- Integrated Norwegian coastal producers:Mowi and similar operators are consolidating feed demand through owned milling assets, concentrating volume with qualified compound suppliers.
- Functional additive demand:Pigment retention and disease-resistance formulations are commanding premium positioning as harvest-quality standards tighten across EU retail channels.
Market Restraints
- Marine protein supply concentration:Peruvian and Chilean anchovy fisheries dominate fish meal sourcing, exposing Norwegian formulators to El Niño-driven catch volatility.
- REACH chemical registration costs:ECHA compliance timelines for novel feed additives extend 18-36 months, freezing innovation pipelines for mid-tier compounders.
- Plant-protein digestibility ceilings:Current soybean and rapeseed meal formulations hit protein digestibility coefficients below fish meal benchmarks in early-stage salmon diets.
Strategic Opportunities
- Scottish regulatory divergence post-Brexit:Scotland's aquaculture framework is creating certification arbitrage for feed producers able to navigate dual EU-UK compliance paths.
- Insect protein regulatory approval:EFSA novel food authorizations for black soldier fly meal are opening formulation white space for cold-water carnivorous diets.
- Algae-derived omega-3 platforms:Microalgae oil substitution for fish oil is electrifying R&D investment among Danish and Norwegian nutrition platforms.
Industry Challenges
- Formulation chemist scarcity:The intersection of aquatic nutrition science and EU regulatory navigation commands salary premiums that mid-scale compounders struggle to match.
- Multi-site certification complexity:ASC, GlobalG.A.P., and Marine Stewardship Council chain-of-custody audits require dedicated compliance teams across integrated producer networks.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Salmon Feed Market |
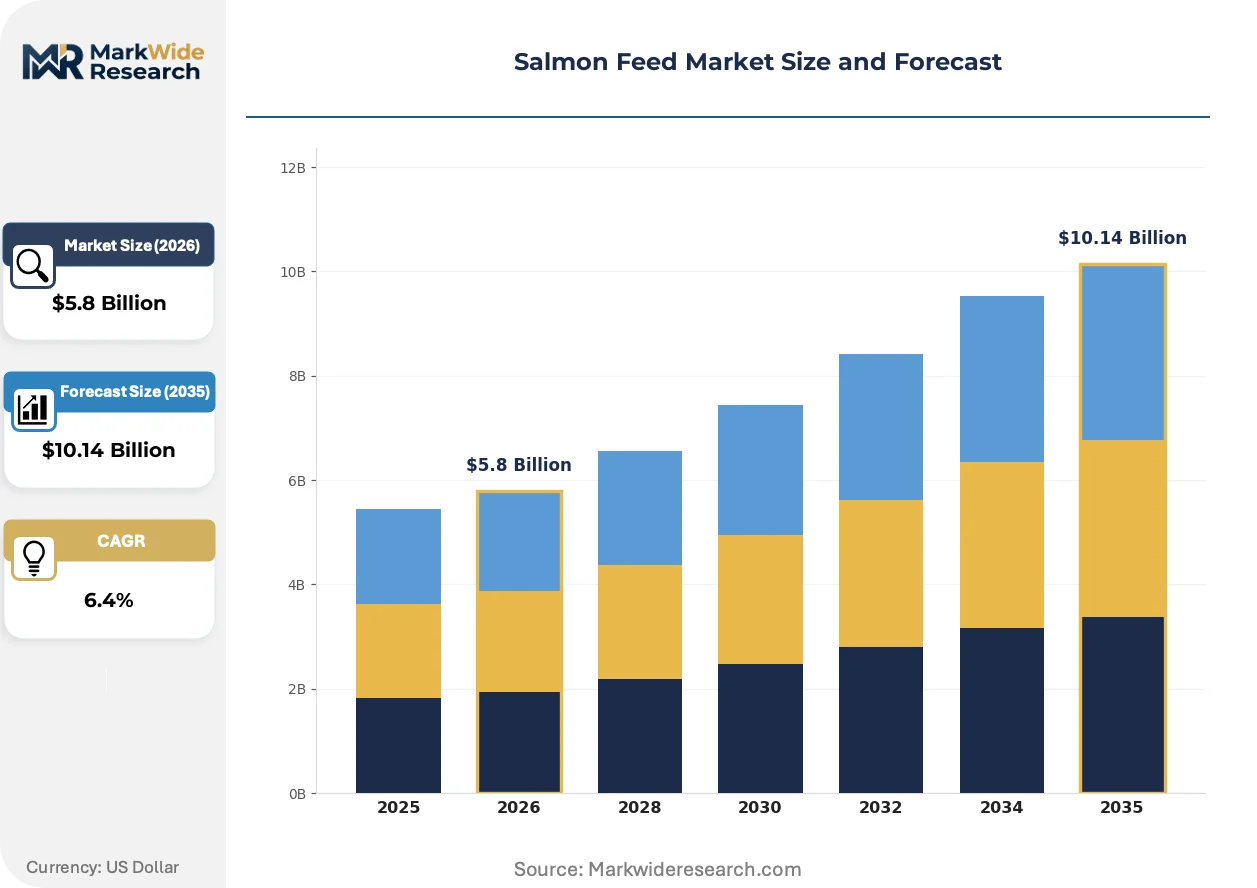
| Market Size in 2026 | $5.8 Billion |
| Market Size in 2035 | $10.14 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Crumbles, Meals, Pastes Ingredient Source: Fish Meal, Plant-Based, Animal By-Products, Synthetic Additives Formulation Type: Conventional, Organic, Non-GMO, Fortified End User: Aquaculture Farms, Research Institutes, Fish Hatcheries, Others |
| Companies Covered | Cargill, BioMar, Skretting, Mowi Feed, Alltech Coppens, EWOS, Nutreco, Aller Aqua Group, ADM, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Salmon Feed Market Trends and Innovations
Reformulation chemistry around marine ingredient reduction is the dominant technical trajectory, with alternative protein streams, functional additives, and precision extrusion systems converging to redefine feed performance benchmarks across North Atlantic production zones.
Single-cell protein derived from methanotrophic bacteria is electrifying early-stage diet formulations, delivering amino acid profiles competitive with fish meal at stable input costs. Norwegian integrated producers are piloting inclusion rates above 15 percent in smolt diets. This biotechnology is compressing reliance on volatile wild-capture fisheries while locking in supply contracts with industrial biotech partners.
REACH authorization requirements for novel feed additives are extending development timelines and elevating R&D capital intensity. ECHA's substance evaluation processes now demand aquatic toxicity data packages that smaller compounders cannot assemble. Norwegian and Danish formulators with established regulatory affairs teams are capturing additive market share as second-tier competitors withdraw from novel ingredient pipelines.
Integrated producers with captive feed mills are consolidating procurement of compound additives while outsourcing base pellet production. This hybrid model concentrates high-margin premix and functional additive demand with specialized nutrition suppliers while commoditizing extrusion capacity. The pattern is most visible across Norwegian coastal zones where Mowi, SalMar, and Leroy operate vertically integrated supply chains.
Salmon Feed Market Segmentation
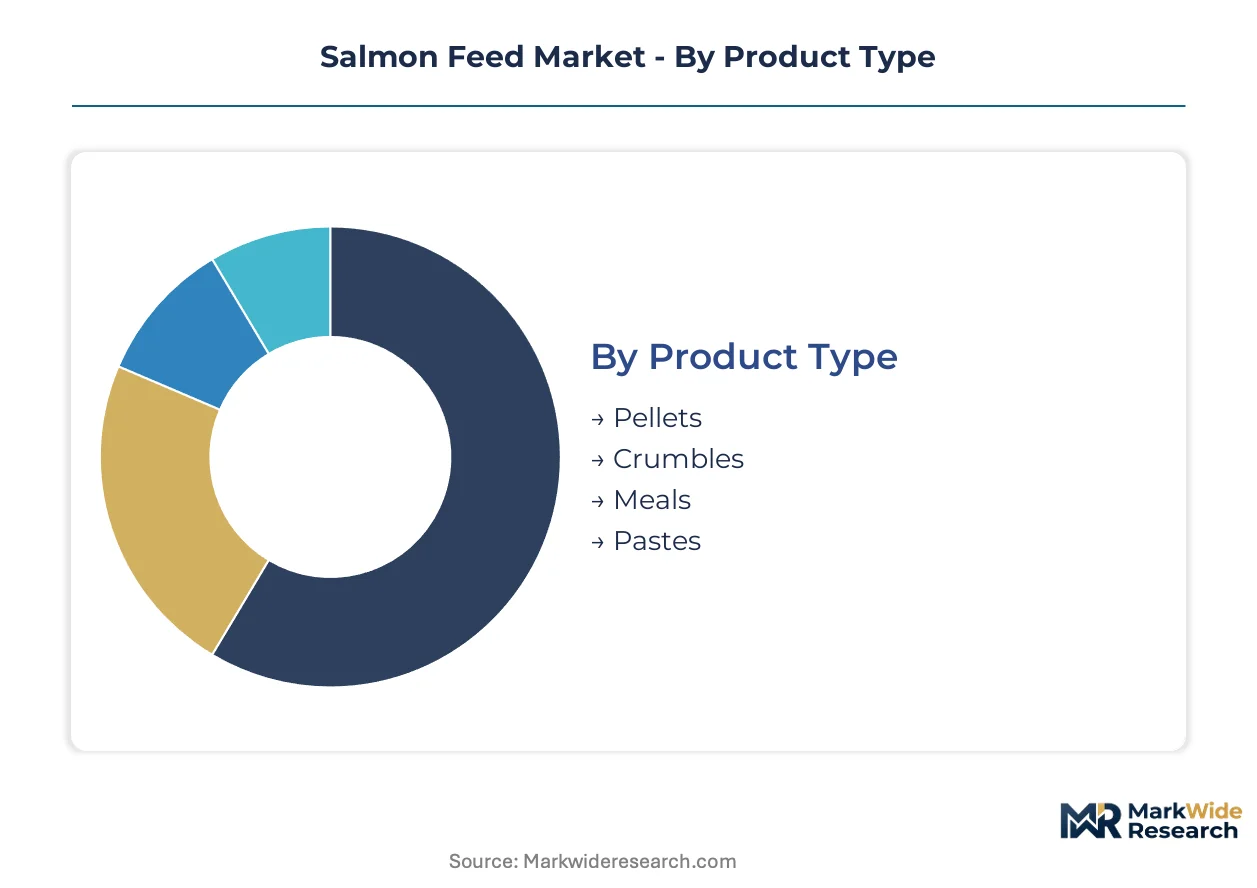
Salmon feed segmentation tracks how formulation chemistry, physical presentation, and procurement standards fragment demand across Norwegian coastal production zones. Each dimension captures distinct margin pools and compliance requirements that compound feed manufacturers must navigate.
Product Type:
Pellet diameter, density, and water stability differentiate this category across grow-out versus nursery applications, with extrusion technology investments driving cost tier stratification.
- Pellets:Extruded cylindrical feeds with controlled buoyancy profiles dominate grow-out operations. Norwegian integrated producers specify sinking pellets for deep-net Atlantic salmon farming, with water stability exceeding 90 minutes to minimize nutrient leaching.
- Crumbles:Broken pellet fractions sized for juvenile salmon transition diets. Scottish hatcheries concentrate procurement here as smolt production scales to meet EU import specifications for harvest-ready fish.
- Meals:Powdered formulations for early larval stages and specialized research applications.
- Pastes:Moist feeds for broodstock conditioning and experimental dietary trials.
Most installed capacity flows through Pellets. Expansion is steepest in Crumbles.
Ingredient Source:
Marine protein quotas under EU Green Deal implementation are reconfiguring procurement priorities, with cost and certification premiums diverging sharply across sourcing strategies.
- Fish Meal:Peruvian anchovy and North Atlantic capelin reduction fisheries supply premium-grade marine protein with amino acid profiles optimized for carnivorous salmonid digestion. Norwegian formulators retain inclusion for early-stage diets despite quota pressures.
- Plant-Based:Soy protein concentrate, rapeseed meal, and pea protein isolates displace marine ingredients in grow-out formulations. Danish compounders lead reformulation chemistry to mitigate antinutritional factors and digestibility ceilings.
- Animal By-Products:Processed poultry meal and rendered proteins serve regional Scottish producers operating outside strict marine ingredient certification schemes.
- Synthetic Additives:Crystalline amino acids, phospholipids, and astaxanthin supplements enable precise nutritional targeting.
Plant-Based sourcing commands the greatest volume expansion. Fish Meal retains the tightest supply concentration.
Formulation Type:
Certification tiering creates pricing stratification that Norwegian and Scottish producers exploit for retail channel positioning, with functional additive premiums widening margin spreads.
- Conventional:Standard compound feeds meeting baseline nutritional specifications without organic or non-GMO certification. Norwegian coastal farms deploy these for cost-efficient grow-out phases.
- Organic:Certified feeds restricting synthetic additives and mandating organic ingredient provenance. Scottish producers targeting premium EU retail channels absorb 15-25% cost premiums for ASC and Soil Association compliance.
- Non-GMO:Identity-preserved supply chains excluding genetically modified soy and corn derivatives. German and Dutch retail buyers increasingly specify this tier for private-label salmon products.
- Fortified:Functional feeds incorporating probiotics, immunostimulants, and pigment enhancers for disease resistance and flesh color optimization.
Conventional formulations carry the largest volume base. Fortified feeds are climbing the fastest as harvest-quality standards tighten.
End User:
Vertical integration intensity fragments demand concentration, with captive milling capacity among Norwegian producers squeezing third-party compounder access to the largest volume pools.
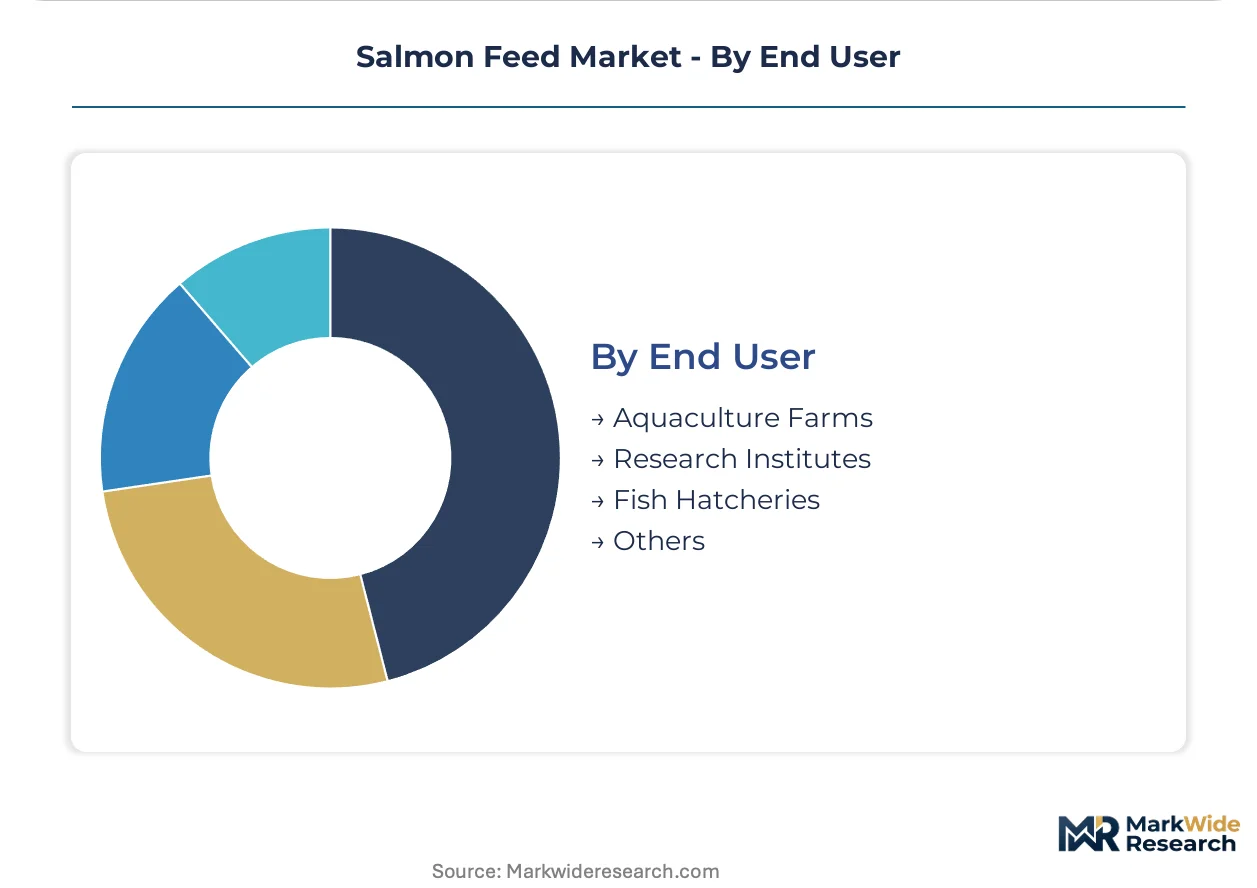
- Aquaculture Farms:Commercial grow-out operations in Norway, Scotland, and Chile constitute the dominant demand segment. Mowi, SalMar, and Leroy operate owned feed mills covering 60-70% of their nutritional requirements.
- Research Institutes:Norwegian Institute of Marine Research and similar facilities drive experimental diet development. Small-batch procurement prioritizes formulation precision over unit cost.
- Fish Hatcheries:Smolt production facilities concentrate in Norwegian fjord regions and Scottish loch systems. Early-stage diet specifications demand higher marine protein inclusion than grow-out feeds.
- Others:Zoological collections, ornamental aquaculture, and specialty breeding operations.
Aquaculture Farms absorb the dominant production share. Research Institutes are gaining procurement sophistication fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Commercial salmon aquaculture emerged from Norwegian fjord operations during the 1970s, establishing production protocols that now dominate cold-water carnivorous fish farming across the North Atlantic basin.
Norway
Integrated coastal producers operate captive feed mills covering the majority of their nutritional requirements. The Norwegian Food Safety Authority enforces strict marine ingredient quotas aligned with EU Green Deal implementation. Bergen and Trondheim harbor clusters concentrate reformulation R&D for plant-protein substitution in grow-out diets.
Scotland
Commercial farms in the Highlands and Islands absorb compound feeds for smolt production and harvest-ready salmon. Scotland's post-Brexit aquaculture framework creates dual compliance obligations alongside retained EU REACH chemical registration requirements. Lochaber and Shetland production zones drive demand for certified organic formulations targeting premium retail channels.
Denmark
Danish compounders leverage centralized R&D infrastructure to supply Norwegian and Scottish producers with reformulated low-fish-meal diets. ECHA authorization timelines for novel additives constrain innovation pipelines for mid-tier manufacturers. Aarhus and Odense nutrition technology clusters specialize in extrusion systems and functional additive development.
Chile
Pacific salmon farms in the Los Lagos and Aysén regions import extruded pellet technology adapted from North Atlantic suppliers. The country's national fishery regulator monitors marine ingredient provenance for export certification to EU and US markets. Puerto Montt serves as the primary logistics hub for Patagonian production zones.
Canada
Atlantic salmon operations in British Columbia and New Brunswick source compound feeds through integrated procurement agreements with North American nutrition suppliers. Health Canada and PMRA jointly oversee feed additive safety assessments for aquaculture applications. Campbell River and Saint John anchor production concentration on opposite coasts.
Salmon Feed Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification-tier and formulation-complexity dimensions. The supplier base organizes around three strategic archetypes: integrated Norwegian producers with captive milling assets, specialized compounders with regulatory affairs capabilities, and diversified agribusiness platforms with backward integration into alternative protein streams. Dominant competitive moves include selective capacity expansion in coastal production zones and technology licensing partnerships for precision extrusion systems.
Within the integrated producer tier, Mowi Feed exemplifies captive supply chain control, while BioMar and Skretting occupy positions as specialized compounders serving external farm operations. These three entities anchor distinct competitive vectors: owned milling for volume security, Danish R&D proximity for reformulation agility, and Norwegian coastal logistics integration for delivery reliability.
| Leading Market Players |
|---|
| Cargill |
| BioMar |
| Skretting |
| Mowi Feed |
| Alltech Coppens |
| EWOS |
| Nutreco |
| Aller Aqua Group |
| ADM |
| Others |
Pricing and Supply Chain Analysis
Aquatic nutrition scientists concentrated around Bergen and Trondheim command salary premiums that compound feed manufacturers must absorb, widening the spread between premium fortified formulations and conventional grow-out diets across Norwegian coastal zones.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels dominates salmon feed procurement, with certification tier (ASC, GlobalG.A.P., Marine Stewardship Council) and functional additive density as the primary price differentiation drivers. Cost compression in conventional grow-out feeds is intensifying because integrated Norwegian producers are consolidating volume through captive milling assets. Research institutes and specialty hatcheries exhibit the lowest price sensitivity, while independent Scottish farms operating without vertical integration face acute margin pressure.
Supply Chain Analysis
Marine protein supply rests on Peruvian and Chilean anchovy reduction fisheries, with Norwegian and Danish compounders drawing from these sources for early-stage diet formulations. Soy protein concentrate from Brazil and rapeseed meal from European crush facilities anchor plant-based substitution streams. Single-source vulnerability in Peruvian anchovy catches during El Niño events creates supply disruption risk. Distribution runs through coastal logistics clusters at Bergen, Trondheim, and Aarhus serving integrated producer networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Salmon feed functions as a stable compounder market where EU Green Deal marine ingredient quotas drive steady reformulation demand and premium pricing for compliant suppliers.
For Market Incumbents: Deepen regulatory affairs capabilities to capture additive market share as ECHA authorization timelines freeze out mid-tier competitors. Expand captive supply of alternative protein streams through biotechnology partnerships with single-cell protein developers. This consolidation lever defends against margin erosion from integrated Norwegian producers outsourcing only base pellet production. For New Entrants and Emerging Players: Direct-to-hatchery digital procurement platforms offer entry routes into Scottish smolt production facilities underserved by Norwegian coastal logistics networks. Target research institute contracts where small-batch precision requirements favor agile formulators over volume-optimized incumbents. A certified organic formulation specialization unlocks premium retail channel access without competing on integrated producer volume terms. For Investors and Strategic Acquirers: Danish and Norwegian compounders with established ECHA navigation teams are the most active acquirer targets in this space, commanding multiples reflecting regulatory moat durability. Long-term viability centers on biotechnology integration capacity rather than extrusion asset scale. Watch EFSA novel food authorizations for insect protein and algae-derived omega-3 platforms as inflection signals for formulation chemistry disruption.| Strategic Initiative | Industry Significance |
|---|---|
| Regulatory Affairs Team Expansion | ECHA authorization expertise captures additive market share as competitors withdraw from novel ingredient pipelines. |
| Single-Cell Protein Supply Contract | Methanotrophic bacterial protein locks in stable input costs while compressing reliance on volatile Peruvian anchovy fisheries. |
| Scottish Hatchery Logistics Footprint | Coastal distribution nodes in Lochaber and Shetland penetrate smolt production demand outside Norwegian integrated networks. |
| Microalgae Oil R&D Partnership | Algae-derived omega-3 platforms substitute fish oil for EU Green Deal compliance and premium retail certification. |
| Hybrid Mill Model Deployment | Outsourced base pellet production with captive premix integration concentrates margin capture for specialized nutrition suppliers. |
Research Methodology
Bottom-up aquaculture farm modeling reconciled against top-down compound feed production tracking forms the analytical core of this study. Primary interviews with formulation chemists, regulatory affairs directors at Danish and Norwegian compounders, procurement managers at Scottish hatcheries, and integrated producer supply chain heads combined with secondary validation from EU REACH registration databases, Norwegian Food Safety Authority discharge monitoring reports, and Marine Stewardship Council chain-of-custody audit records. This triangulation approach ensures demand-side consumption patterns align with supply-side capacity and certification constraints.
Input-output matrices mapping marine protein quota trajectories against plant-protein substitution rates drive volume projections across the modeling period. Segmentation dimensions include formulation type (conventional, organic, fortified), ingredient source tier, end-user integration intensity, and regional regulatory cluster. CAGRs derive from fitted adoption curves for alternative protein streams and elasticity-adjusted price responses to certification tier premiums. Industry-specific forecast inputs incorporate ECHA authorization pipeline status and EFSA novel food evaluation timelines for insect meal and microalgae platforms.
The model assumes a particular technology adoption path; alternative pathways for single-cell protein scale-up or accelerated insect meal regulatory approval would alter the outlook. Forecasts reflect assumptions about EU Green Deal implementation pace, El Niño frequency in Peruvian fisheries, and integrated producer captive milling expansion. A small set of named triggers—EFSA novel food authorizations, Scottish regulatory divergence post-Brexit, and biotechnology supply contract announcements—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Norway Aquaculture Market
Aquaculture Innovations
Marine Life Raft Market
Aquaculture Innovations
Aquaculture Pumps Market
Aquaculture Innovations
Brazil Fisheries and Aquaculture Market
Aquaculture Innovations
United States Shrimp Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
GCC Fish Farming Market
Aquaculture Innovations
Global Aquafeed Market
Aquaculture Innovations
Fish Farming Equipment Market
Aquaculture Innovations
Aquaculture Products Market
Aquaculture Innovations
Aquaculture UAE in Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
China Shrimp Feed Market
Aquaculture Innovations
United Arab Emirates Fisheries and Aquaculture Market
Aquaculture Innovations
Ecuador Shrimp Feed Market