
 South America Aqua Feed Market | 2026-2036
South America Aqua Feed Market Size, Share, and Industry Trends Forecast 2026-2036
South America Aqua Feed Market Analytics
Brazilian aqua feed capacity expansion is reshaping regional supply dynamics for marine and freshwater species diets. Cargill leverages its integrated oilseed processing network to secure soybean meal supply chains across the Amazon basin. Nutreco NV anchors premium shrimp feed formulations through its Brazilian subsidiary operations. BioMar Group specializes in high-performance salmonid diets from its Ecuadorian production base.
Aqua feed comprises nutritionally complete diets formulated for farmed aquatic organisms, typically containing 25-50% crude protein with precise amino acid profiles and lipid levels tailored to species metabolism. Pellet feeds dominate commercial aquaculture due to their water stability and controlled nutrient leaching properties. Soybean meal substitution for fish meal is accelerating as the fastest-growing feed ingredient trend, driven by cost volatility in Peruvian anchovy harvests. Direct sales channels capture the largest volume share through long-term contracts between major feed manufacturers and industrial shrimp farms.
Brazil's MAPA enforces mandatory feed safety registrations that constrain import flexibility and favor domestic production scale. Ecuador's national aquaculture chamber coordinates with health authorities to manage early mortality syndrome prevention protocols. ANVISA in Brazil oversees veterinary drug residues in feed additives, shaping product formulation boundaries. Stakeholders must track how pending sustainability certification requirements for soy sourcing will alter procurement standards and supplier qualification timelines.
Market Dynamics
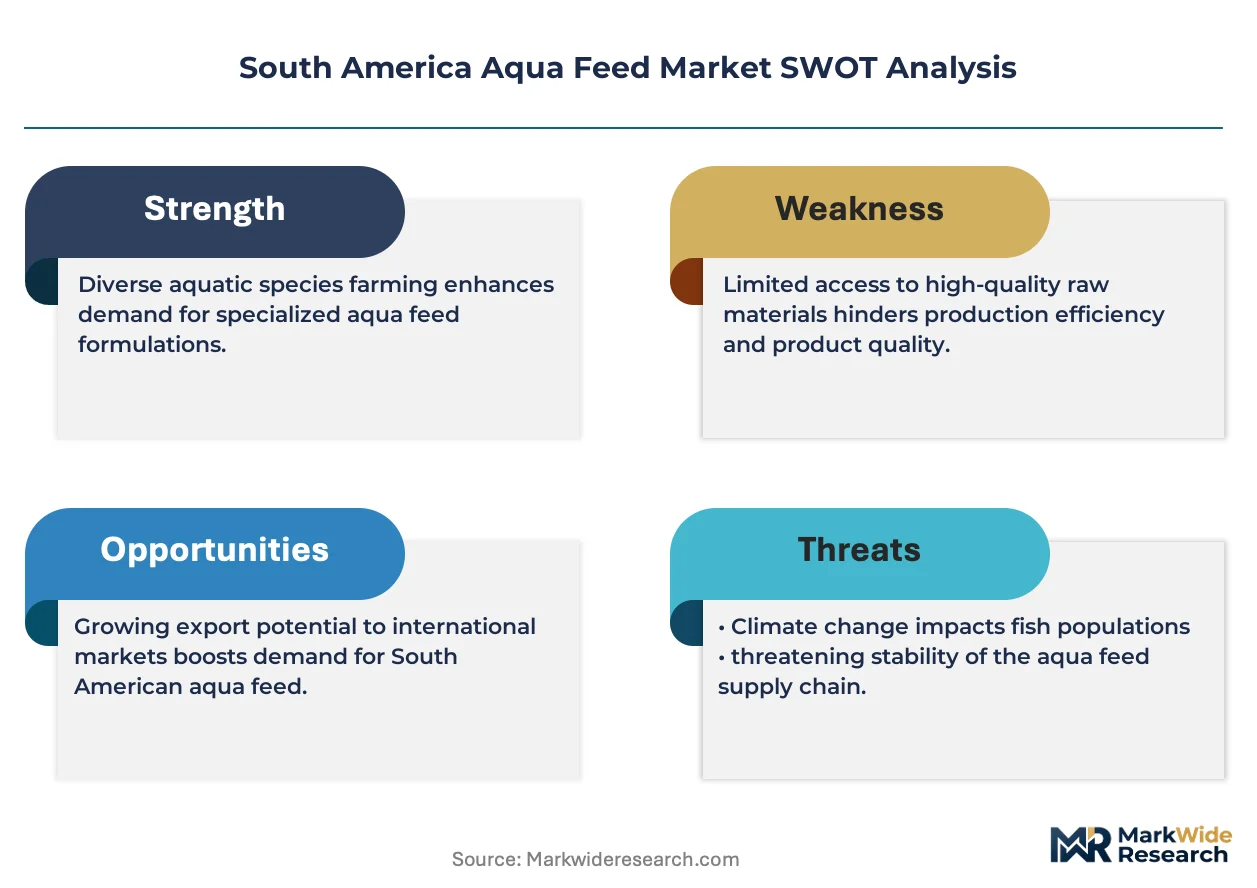
Brazilian MAPA feed safety registrations are compressing import flexibility while accelerating domestic production scale across the Amazon basin and coastal aquaculture zones. This regulatory architecture is reshaping competitive entry barriers and supply chain localization patterns.
Growth Catalysts
- Ecuadorian shrimp farm consolidation:Industrial-scale operators in Guayas and El Oro provinces are locking in multi-year feed contracts that stabilize offtake volumes for specialized marine diets.
- Soybean meal substitution acceleration:Peruvian anchovy harvest volatility is forcing coastal aquaculture producers toward plant-based protein concentrates with superior amino acid balancing.
- ANVISA additive pathway expansion:Veterinary drug residue protocols are clarifying formulation boundaries that enable faster product registration timelines for domestic manufacturers.
Market Restraints
- Fish meal cost volatility:Peruvian anchovy quota fluctuations transmit directly into marine diet pricing, squeezing margin structures for shrimp feed producers.
- Amazon basin logistics concentration:Soybean meal supply chains depend on Pará and Mato Grosso crushing capacity with limited alternative routing to coastal aquaculture zones.
- MAPA registration friction:Mandatory safety documentation requirements extend import qualification timelines beyond domestic production ramp schedules.
Strategic Opportunities
- Colombian Pacific coast underpenetration:Buenaventura and Tumaco aquaculture clusters lack dedicated feed milling capacity, creating white space for coastal production facilities.
- Sustainability certification tailwinds:Pending soy sourcing standards from Brazil's national agricultural confederation will reward early-adopter suppliers with preferred procurement status.
- Precision nutrition convergence:Integration of real-time pond monitoring systems with automated feeding algorithms is opening subscription-based service revenue streams.
Industry Challenges
- Aquaculture nutritionist scarcity:Brazilian universities produce insufficient marine species specialists to staff formulation laboratories at expanding production facilities.
- Feed mill capex intensity:Extrusion and pelleting equipment for water-stable marine diets requires capital deployment that stretches mid-tier manufacturer balance sheets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South America Aqua Feed Market |
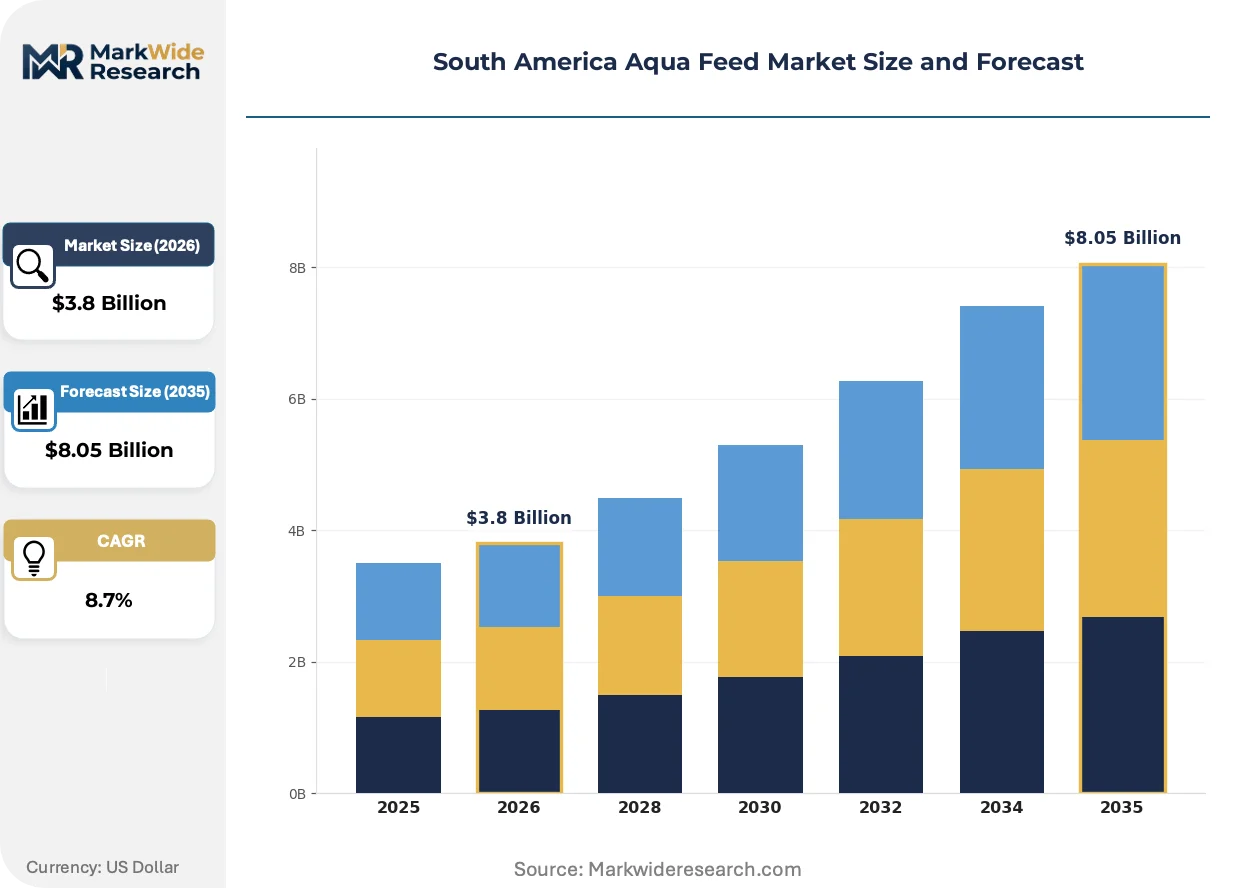
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Pellets, Crumbles, Powders, Granules Feed Ingredient: Fish Meal, Soybean Meal, Corn Gluten, Wheat Bran End User: Aquaculture Farms, Research Institutions, Feed Manufacturers, Nutritionists Distribution Channel: Direct Sales, Online Retail, Distributors, Wholesalers |
| Companies Covered | ADM, Cargill, Alltech, Nutreco NV, BioMar Group, Skretting, Aller Aqua, Charoen Pokphand Foods, Evonik Industries, Others |
| Regions Covered | South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South America Aqua Feed Market Evolving Landscape
Digital feed management systems are penetrating shrimp pond operations at accelerating rates, compressing the gap between formulation science and on-farm consumption patterns. This technological layer is redrawing competitive differentiation around data integration rather than commodity protein sourcing.
Precision feeding algorithms are virtualizing traditional manual distribution methods across Ecuadorian industrial shrimp farms. Camaroneras in Guayas province are deploying sensor networks that adjust pellet delivery based on real-time consumption telemetry. This virtualization is compressing feed conversion ratios and displacing scheduled feeding labor pools.
Brazil's MAPA is tightening veterinary drug residue surveillance through expanded ANVISA testing protocols for imported additive premixes. The industrial consequence is a qualification bottleneck forcing international suppliers toward Brazilian subsidiary registration. Marine shrimp feed categories face the steepest compliance ramps as early mortality syndrome prevention drives antibiotic scrutiny.
Industrial shrimp operators are consolidating procurement decisions into centralized technical committees with formulation scientists and pond managers. Direct manufacturer relationships are displacing traditional distributor networks in Ecuador's El Oro province. This concentration is most visible among vertically integrated exporters seeking batch traceability for European retail certification requirements.
South America Aqua Feed Market Segmentation
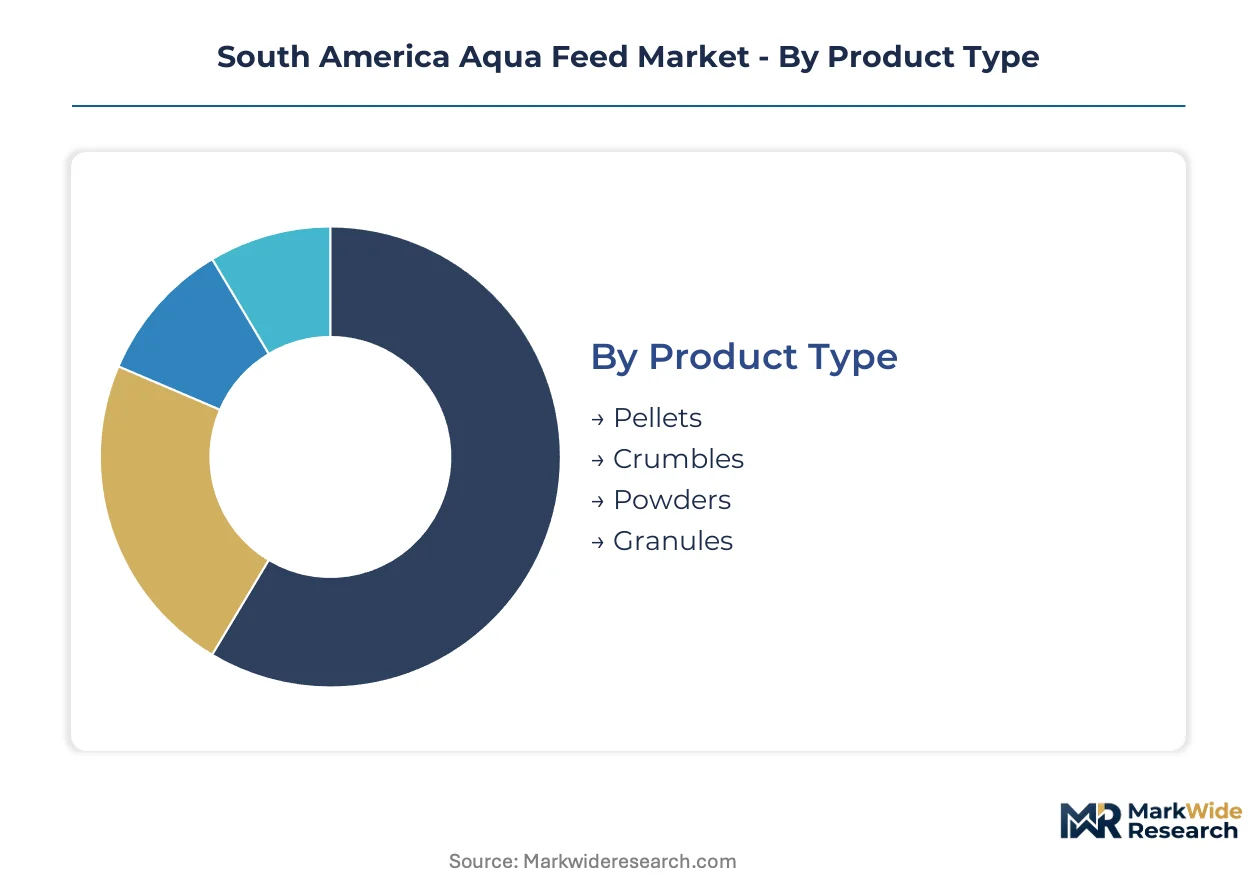
Aqua feed segmentation in South America reflects divergent service intensity across species life stages and farm operational scales. Feed manufacturers calibrate technical support depth, formulation customization, and delivery frequency to match each segment's biological and economic requirements.
Product Type:
After-sales service intensity peaks with water stability demands and feeding precision requirements across larval to grow-out transitions.
- Pellets:Extruded formulations achieve 4-6 hour water stability through starch gelatinization and lipid coating. Industrial shrimp farms in Ecuador's El Oro province specify sinking rates and hardness tolerances that trigger dedicated technical field support. Pellet durability directly correlates with feed conversion ratios in high-density pond systems.
- Crumbles:Fragmented pellet structures suit post-larval shrimp and juvenile finfish with underdeveloped mouthparts. Hatcheries in Brazil's Ceará state demand particle size gradations below 500 microns that necessitate on-site feeding protocol training. Crumble specification precision determines survival rates during the first 30 days of culture.
- Powders:Micro-particulate diets for larval stages require suspension properties and slow-sink characteristics.
- Granules:Intermediate density feeds bridge crumble and pellet applications for transitional growth phases.
By volume, Pellets leads. By growth pace, Crumbles is climbing the fastest as hatchery intensification spreads.
Feed Ingredient:
Ingredient sourcing geography dictates margin exposure to commodity volatility and certification compliance costs.
- Soybean Meal:Defatted soy protein concentrate delivers 44-48% crude protein with lysine supplementation requirements. Brazil's Mato Grosso crushing capacity anchors supply chains reaching coastal aquaculture zones. Substitution momentum accelerates as Peruvian anchovy quota instability transmits into fish meal price spikes.
- Fish Meal:Peruvian anchovy-derived protein retains irreplaceable amino acid profiles for marine carnivores despite cost volatility. Ecuadorian shrimp feed formulators maintain 8-15% inclusion rates for premium export-grade diets. ANVISA residue surveillance tightens procurement documentation burdens for imported marine meals.
- Corn Gluten:Yellow corn processing byproduct contributes xanthophyll pigments for salmonid flesh coloration.
- Wheat Bran:Binding agent and carbohydrate source in freshwater omnivore diets with regional milling proximity advantages.
By procurement volume, Soybean Meal dominates. By formulation innovation intensity, Fish Meal commands premium positioning.
End User:
Technical sophistication gradients separate volume purchasers from specification-driven niche consumers.
- Aquaculture Farms:Industrial operators in Brazil's Rio Grande do Norte and Ecuador's Guayas provinces consolidate multi-year supply contracts with embedded pond monitoring services. Farm-scale procurement committees now integrate formulation scientists directly into purchasing decisions. Batch traceability requirements for European retail certification drive supplier consolidation.
- Research Institutions:Brazilian university marine science programs and INTA Argentina facilities source experimental diets with precise nutrient density modifications. Research procurement volumes remain limited but shape commercial formulation trajectories through publication influence.
- Feed Manufacturers:Compounders purchasing premixes and base mixes for private label production.
- Nutritionists:Independent consultants advising farm operators on diet optimization and feed conversion management.
By revenue concentration, Aquaculture Farms leads. By influence on industry standards, Research Institutions sets the pace.
Distribution Channel:
Channel selection reflects farm scale, credit requirements, and technical service bundling preferences.
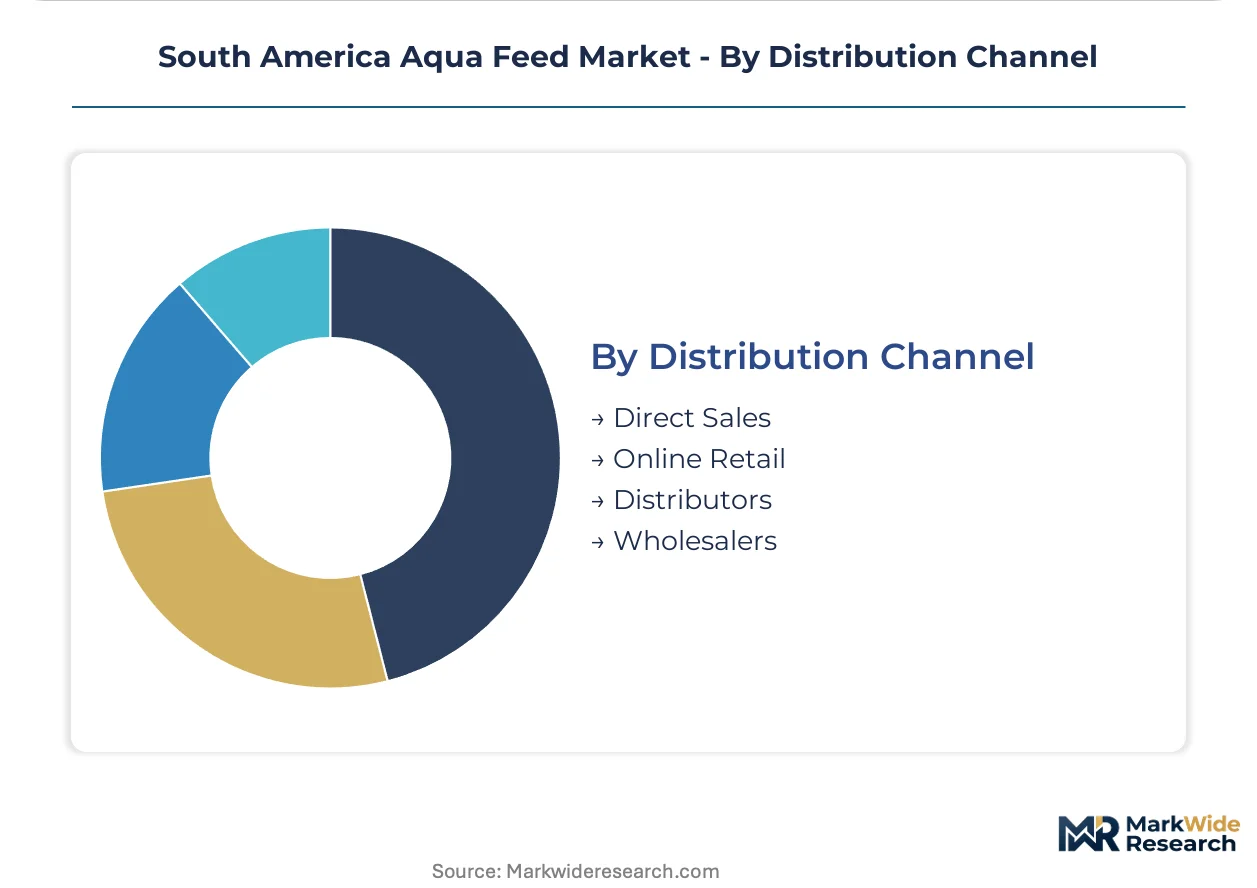
- Direct Sales:Long-term contracts between Cargill, Nutreco NV, and BioMar Group subsidiaries with industrial shrimp operators eliminate intermediary margins. Direct relationships enable real-time formulation adjustments based on pond health telemetry. Credit terms and technical advisory services bundle into contract structures.
- Distributors:Regional networks serve mid-tier farms in Colombia's Pacific coast clusters lacking volume for manufacturer direct relationships. Distributor inventory buffers address logistics gaps in Amazon basin routing constraints.
- Online Retail:E-procurement platforms penetrate smallholder freshwater fish operations with standardized diet specifications.
- Wholesalers:Bulk aggregators serving remote aquaculture zones with limited cold chain infrastructure.
By volume flow, Direct Sales leads. By accessibility expansion, Online Retail is gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Soybean crushing capacity clusters in Brazil's interior dictate feed ingredient flows toward coastal aquaculture zones. Ecuador's shrimp belt commands specialized marine diet formulation expertise. Colombian Pacific clusters remain underserved by dedicated milling infrastructure.
Brazil
Industrial shrimp farms in Rio Grande do Norte and Ceará states drive specialized diet procurement from domestic formulators. MAPA enforces mandatory feed safety registrations that compress import flexibility and accelerate local production scale. Amazon basin soybean meal supply chains route through Pará and Mato Grosso crushing facilities toward coastal aquaculture zones.
Ecuador
Camaroneras in Guayas and El Oro provinces consolidate multi-year feed contracts that stabilize offtake volumes for marine diets. The national aquaculture chamber coordinates with health authorities to manage early mortality syndrome prevention protocols. Guayaquil anchors formulation laboratories serving industrial operators seeking European retail certification compliance.
Colombia
Buenaventura and Tumaco aquaculture clusters lack dedicated feed milling capacity, creating white space for coastal production facilities. The national fisheries authority oversees import documentation for additive premixes entering Pacific coast ports. Antioquia-based distributors currently bridge supply gaps for mid-tier farm operators.
Peru
Anchovy harvest volatility in Pacific waters transmits directly into fish meal pricing for regional shrimp feed producers. The national production ministry manages anchovy quota allocations that determine marine protein concentrate availability. Callao port infrastructure handles bulk fish meal exports toward Ecuadorian and Brazilian formulators.
Chile
Salmonid producers in Los Lagos and Aysén regions source high-performance diets from specialized marine feed compounders. The national fisheries service enforces residue surveillance protocols for veterinary drug additives in Atlantic salmon operations. Puerto Montt concentrates extrusion capacity serving Patagonian aquaculture zones.
South America Aqua Feed Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in ingredient and additive supply. The supplier base organizes around three functional layers: integrated oilseed processors with captive protein supply, specialized aquaculture formulators with species-specific expertise, and regional compounders serving price-sensitive freshwater operations. Strategic moves concentrate on backward integration into soybean crushing assets and geographic expansion toward underpenetrated Pacific coast clusters.
Within the integrated processor tier, Cargill leverages its Amazon basin oilseed network to secure meal supply chains for coastal aquaculture zones. Nutreco NV and BioMar Group anchor the specialized formulator segment, with the former occupying a position in Brazilian shrimp nutrition and the latter exemplifying salmonid diet expertise from Ecuadorian production bases. These three entities represent divergent scale-and-specialization archetypes competing for industrial farm procurement committee relationships.
| Leading Market Players |
|---|
| ADM |
| Cargill |
| Alltech |
| Nutreco NV |
| BioMar Group |
| Skretting |
| Aller Aqua |
| Charoen Pokphand Foods |
| Evonik Industries |
| Others |
Value Network & Pricing Analysis
Mato Grosso soybean crushing clusters anchor protein concentrate flows toward Brazil's coastal aquaculture zones, concentrating cost-setting power among integrated oilseed processors. MAPA registration requirements compress import arbitrage opportunities, allowing domestic manufacturers to maintain formulation premiums against landed alternatives.
Pricing Analysis
ANVISA veterinary drug residue protocols dictate the pricing tier structure across marine shrimp feed categories, with antibiotic-free certification commanding premium positioning. Three-tier pricing structure across premium, standard, and economy levels separates export-grade diets with full traceability from domestic pond operations. Cost compression in standard tiers is intensifying because Peruvian anchovy quota instability transmits into fish meal substitution cycles. Mid-tier freshwater farms in Brazil's interior exhibit highest price sensitivity, while vertically integrated Ecuadorian exporters absorb premiums for European retail compliance.
Supply Chain Analysis
Extended payment terms from Cargill and Nutreco NV subsidiaries anchor working capital structures for industrial shrimp operators facing 90-day grow-out cycles. Geographic supply concentration centers on Brazil, Ecuador, and Peru, with soybean meal drawing from Mato Grosso-Pará crushing corridors and fish meal sourcing from Callao export terminals. Single-source vulnerability runs through Amazon basin logistics chokepoints where Pará port capacity constraints delay coastal deliveries. Distribution runs through direct manufacturer contracts with farm procurement committees, displacing traditional distributor networks in Guayas and El Oro provinces.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among industrial shrimp farm procurement committees in Ecuador and Brazil, with technical committees now integrating formulation scientists directly into multi-year contract negotiations.
For Market Incumbents: Insulate margin structures by securing captive soybean meal supply through backward integration into Amazon basin crushing assets. Accelerate ANVISA-compliant additive premix registration to forestall international supplier qualification bottlenecks. Certification investment in Brazil's national agricultural confederation sustainability standards will lock in preferred procurement status before pending sourcing mandates take effect. For New Entrants and Emerging Players: Colombia's Pacific coast underpenetration offers white-space acquisition of mid-tier farm relationships in Buenaventura and Tumaco clusters lacking dedicated milling infrastructure. Precision nutrition subscription services bundling real-time pond monitoring with automated feeding algorithms penetrate faster than commodity feed manufacturing. Target hatchery crumble specifications as the entry vector, where particle size precision demands create technical stickiness absent in grow-out pellet commoditization. For Investors and Strategic Acquirers: Long-term, this sits as a consolidation play because specialized aquaculture formulators with species-specific expertise face escalating capex barriers to extrusion capacity expansion. Acquisition targets should screen for Brazilian MAPA registration portfolios and Ecuadorian marine diet formulation libraries. The signal to watch is ANVISA additive pathway expansion velocity, which determines whether domestic manufacturers maintain registration timeline advantages over international competitors.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Soybean Crushing | Cargill's Amazon basin network secures meal supply chains against Peruvian anchovy volatility. |
| ANVISA Additive Premix Registration | Domestic qualification timelines compress import flexibility for international suppliers. |
| Precision Nutrition Platform Deployment | Sensor networks in Guayas province compress feed conversion ratios through automated delivery. |
| Coastal Production Facility Expansion | Colombia's Pacific clusters lack dedicated milling capacity for Buenaventura aquaculture operations. |
| Sustainability Certification Investment | Brazil's national agricultural confederation standards reward early-adopter suppliers with preferred status. |
Research Methodology
Desk research of trade flow databases, MAPA registration filings, and ANVISA additive protocols preceded structured interviews with aquaculture farm procurement managers, feed formulation scientists, and crushing facility operations directors. Primary fieldwork validated secondary estimates of soybean meal substitution rates and fish meal inclusion percentages across marine diet categories. Bottom-up volume aggregation from farm-level contract disclosures triangulated against top-down ingredient flow analysis from Pará and Mato Grosso export terminals.
Forecast assumptions held MAPA registration friction constant and ANVISA surveillance intensity at observed levels across the analysis window. Segmentation modeling incorporated product type, feed ingredient sourcing geography, end-user scale tier, and distribution channel structure. CAGRs derived from exponential smoothing of historical volume trajectories adjusted for hatchery intensification trends and precision nutrition adoption curves. Anchovy quota allocation volatility and sustainability certification mandate timing served as scenario variables.
The forecast holds incumbent behavior within observed patterns; aggressive moves by integrated oilseed processors or international formulators establishing Brazilian subsidiaries would shift outcomes. Macroeconomic deviation in commodity protein markets, regulatory acceleration in soy sourcing standards, or technological breakthroughs in single-cell protein production would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Aquaculture Innovations
China Aquafeed Market
Aquaculture Innovations
Smart Aquaculture Systems Market
Aquaculture Innovations
Sandfish Market
Aquaculture Innovations
Aquaculture Feed and Pharmaceuticals Market
Aquaculture Innovations
Asia Pacific Aqua Feed Market
Aquaculture Innovations
Europe Aqua Feed Market
Aquaculture Innovations
Fish Breeding Tank Market
Aquaculture Innovations
Vietnam Aquafeed Market
Aquaculture Innovations
Hatchery Product Market
Aquaculture Innovations
Qatar Fisheries and Aquaculture Market
Aquaculture Innovations
Clams, Cockles, Ark Shells Market
Aquaculture Innovations
Perch Market
Aquaculture Innovations
Fish Farming Market
Aquaculture Innovations
United States Ornamental Fish Market
Aquaculture Innovations
Aquaculture Cage Market
Aquaculture Innovations
Fish Oil for Aquafeed Market