
 Latin America Logistics Market | 2026-2036
Latin America Logistics Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Logistics Market Insights
Brazil's southeastern logistics corridor is narrowing capacity gaps between port throughput and inland distribution networks. Maersk leverages its integrated container logistics footprint to anchor ocean-to-warehouse flows through Santos. DHL Group sustains express delivery dominance by controlling last-mile stations across São Paulo and Mexico City. DB Schenker specializes in temperature-controlled pharmaceutical logistics, a high-margin niche gaining share in regional trade lanes.
Latin America logistics encompasses the planning, execution, and control of goods movement across multimodal networks spanning roads, ports, railways, and air cargo terminals, typically operating within temperature bands from ambient to frozen depending on cargo class. The sector coordinates inventory flows, customs clearance, and final-mile handoffs to enable industrial supply chains and consumer commerce. Transportation and freight forwarding together capture the largest value pools, though warehousing margins are compressing as automated fulfillment centers from IoT and automation deployments reshape cost structures. Last-mile delivery under the delivery model dimension is expanding fastest, pressured by e-commerce customer type requirements for same-day and scheduled windows that strain legacy route optimization.
ANTT in Brazil, SCT in Mexico, and Argentina's CNRT each enforce axle-load limits, driver hour rules, and emissions benchmarks that directly affect fleet replacement cycles and route economics across the region. These frameworks elevate compliance costs for older vehicle pools while creating market access advantages for operators with newer, certified assets. Stakeholders must weigh capital allocation between green fleet upgrades and digital infrastructure as regulatory enforcement tightens and customer service-level expectations harden.
Market Dynamics
E-commerce fulfillment networks across Mexico and Brazil are compressing delivery windows from days to hours, forcing logistics operators to reconfigure warehouse placement and fleet deployment around urban consumption clusters rather than traditional port-centric distribution.
Growth Catalysts
- ANTT emissions mandates:Brazil's tightening truck fleet standards are accelerating replacement cycles, opening demand for certified logistics providers with newer asset pools.
- Port modernization at Santos:Container throughput expansion is pulling inland distribution infrastructure investment into the São Paulo corridor.
- Pharmaceutical cold chain:Temperature-controlled biologics trade is expanding specialized logistics requirements across regional trade lanes.
Market Restraints
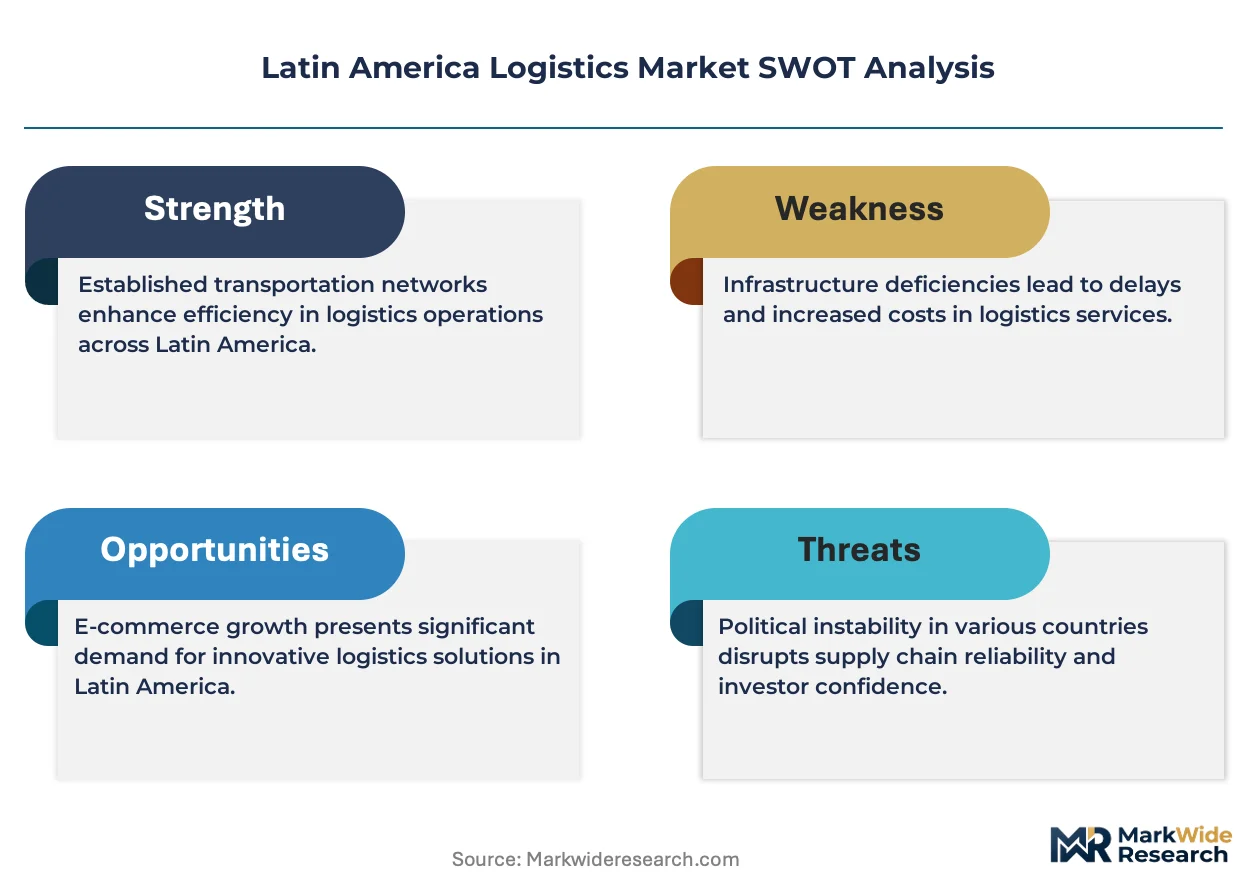
- Fuel price volatility:Diesel cost swings directly erode trucking margins across Brazilian and Mexican long-haul corridors.
- Single-corridor concentration:São Paulo–Santos handles disproportionate freight volume, creating systemic vulnerability to port disruptions.
- Last-mile labor scarcity:Driver hour regulations from SCT and ANTT constrain fleet utilization rates during peak e-commerce windows.
Strategic Opportunities
- Northern Mexico manufacturing zones:Nearshoring production growth is creating demand for cross-border logistics infrastructure linking Monterrey to US distribution networks.
- Rail freight modernization:Intermodal investment connecting Brazilian agricultural interior to Atlantic ports offers modal shift capture.
- Scheduled delivery windows:E-commerce platforms are contracting for time-definite fulfillment, opening premium service tier development.
Industry Challenges
- Warehouse automation integration:Legacy fulfillment centers face retrofit complexity when deploying robotics and IoT inventory systems.
- Customs clearance latency:Documentation friction at Mercosur borders compresses transit time reliability for regional freight.
- Driver certification pipelines:Qualified heavy-vehicle operator shortages limit fleet expansion velocity despite equipment availability.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Logistics Market |
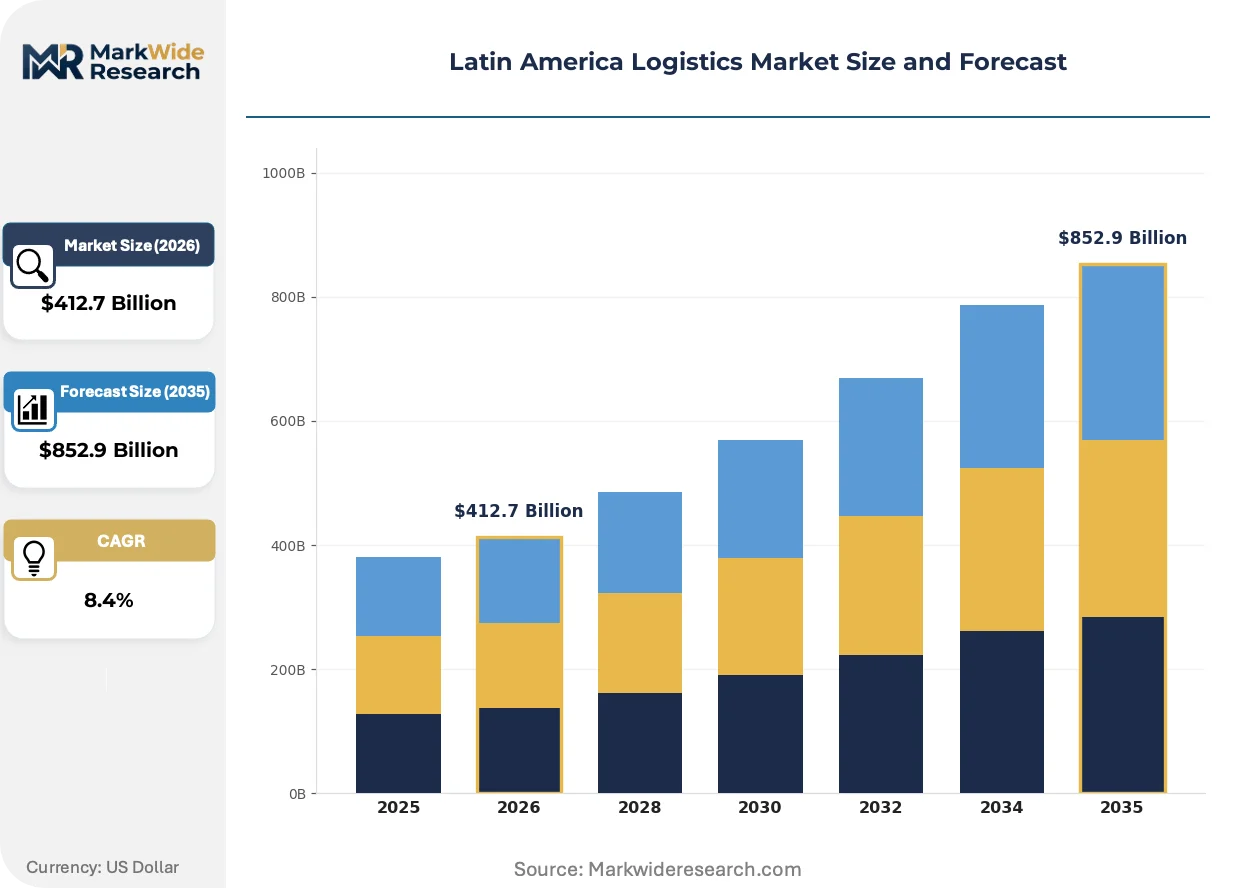
| Market Size in 2026 | $412.7 Billion |
| Market Size in 2035 | $852.9 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Transportation, Warehousing, Freight Forwarding, Courier Delivery Model: Last-Mile, Cross-Docking, Same-Day, Scheduled Customer Type: E-Commerce, Retail, Manufacturing, Wholesale Technology: IoT, Artificial Intelligence, Blockchain, Automation |
| Companies Covered | CEVA Logistics, DSV A/S, DB Schenker, Loggi, DP World, DHL Group, FedEx Corporation, Maersk, Kuehne+Nagel, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Logistics Market Trends and Innovations
Digital freight platforms and automated fulfillment systems are restructuring how cargo moves from port to doorstep across Latin American logistics networks.
Internet-of-Things sensors embedded in refrigerated containers are collapsing visibility gaps between origin and destination for temperature-sensitive pharmaceutical shipments. Brazilian cold chain operators are deploying these systems at scale to meet ANVISA traceability requirements. Real-time monitoring is collapsing insurance premiums and spoilage liability for high-value cargo lanes.
SCT in Mexico is enforcing stricter driver rest mandates and electronic logging device requirements for cross-border freight. Fleet operators must upgrade cab technology and restructure route planning to maintain compliance. The regulatory pressure is accelerating consolidation among smaller trucking firms lacking capital for certified asset replacement.
Same-day delivery guarantees from e-commerce marketplaces are compressing traditional distribution hierarchies that relied on regional DCs and extended delivery cycles. Direct-to-consumer fulfillment is displacing wholesale-to-retail logistics patterns in São Paulo and Mexico City metropolitan zones. Urban micro-fulfillment centers are proliferating in dense neighborhoods to meet compressed service-level agreements.
Latin America Logistics Market Segmentation
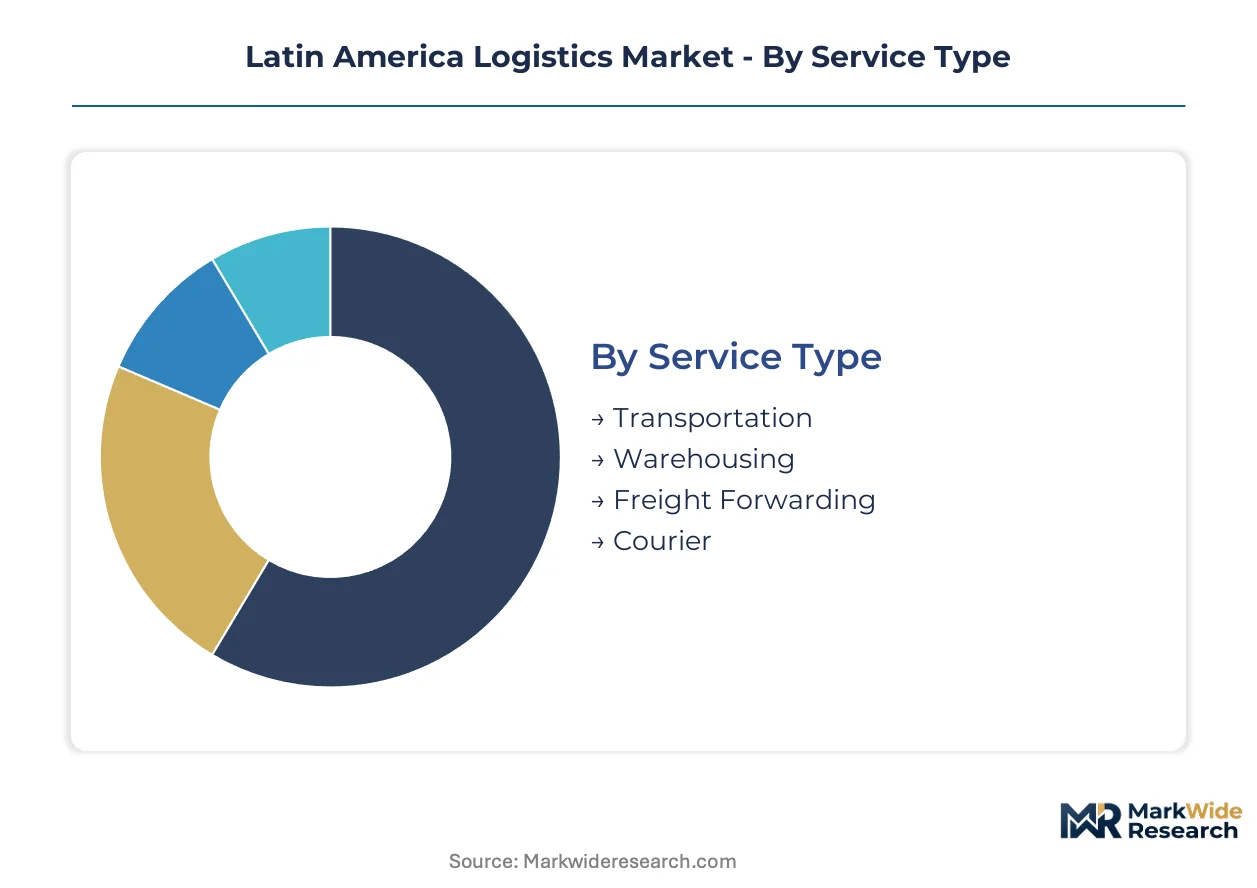
Logistics operators in Latin America configure service portfolios around distinct operational capabilities, each demanding specialized asset bases and technology stacks. Segment boundaries determine pricing power, margin sustainability, and competitive defensibility across the São Paulo–Santos corridor and Mexican manufacturing zones.
Service Type:
After-sales service intensity varies sharply across service types, with temperature-controlled and time-definite offerings requiring dedicated maintenance networks and 24/7 operational support.
- Transportation:Road freight dominates volume flows across Brazilian and Mexican long-haul corridors, with fleet operators managing ANTT and SCT compliance burdens through certified vehicle replacement programs. Demand concentrates in the São Paulo–Santos axis, where port throughput expansion is pulling refrigerated and dry van capacity into dedicated lane contracts.
- Warehousing:Automated fulfillment centers with IoT inventory systems and robotics deployment are reshaping cost structures in São Paulo and Mexico City metropolitan zones. E-commerce platforms are contracting for urban micro-fulfillment locations to meet compressed delivery windows, pressuring legacy facilities to retrofit or exit.
- Freight Forwarding:Customs brokerage and documentation management services navigate Mercosur border friction and ANVISA traceability requirements for pharmaceutical shipments.
- Courier:Express document and parcel services operate through station networks controlled by integrated operators, with last-mile density determining unit economics in dense urban cores.
Transportation holds the largest share; momentum sits with Warehousing as automation investments accelerate.
Delivery Model:
Cost tier differentiation separates premium time-definite services from standard deferred offerings, with pricing spreads widening as e-commerce service-level agreements harden.
- Last-Mile:Final delivery to residential and commercial endpoints operates through contracted driver fleets and gig-economy networks, with SCT and ANTT hour rules constraining utilization during peak windows. São Paulo and Mexico City density supports dedicated route optimization, while secondary cities rely on hybrid models.
- Same-Day:Compressed fulfillment cycles demand urban micro-warehouse positioning within 15-kilometer radii of consumption clusters, with inventory pre-positioning driven by demand forecasting algorithms.
- Cross-Docking:Consolidation and deconsolidation facilities minimize inventory holding costs for high-velocity consumer goods moving through Brazilian retail distribution networks.
- Scheduled:Time-window delivery contracts for industrial and healthcare customers command premium pricing, with ANVISA cold chain certification required for pharmaceutical lanes.
Last-Mile holds the largest share; Same-Day is climbing the fastest as marketplace guarantees compress delivery expectations.
Customer Type:
Application-specific requirements drive service configuration, with pharmaceutical and automotive supply chains demanding qualitatively different capabilities than consumer retail flows.
- E-Commerce:Marketplace platforms and direct-to-consumer brands are the dominant demand source for automated warehousing and same-day delivery infrastructure across Mexico and Brazil. Returns processing and flexible delivery windows strain legacy logistics architectures optimized for wholesale distribution.
- Manufacturing:Northern Mexico industrial zones and Brazilian automotive corridors require inbound parts logistics and finished goods distribution with production-line synchronization. Nearshoring growth is expanding cross-border freight volumes linking Monterrey to US distribution networks.
- Retail:Omnichannel fulfillment combines store replenishment with direct-to-consumer shipments from shared inventory pools.
- Wholesale:Bulk distribution to independent retailers operates through traditional regional DC networks with extended delivery cycles.
E-Commerce holds the largest share; Manufacturing is gaining share fastest on nearshoring investment flows.
Technology:
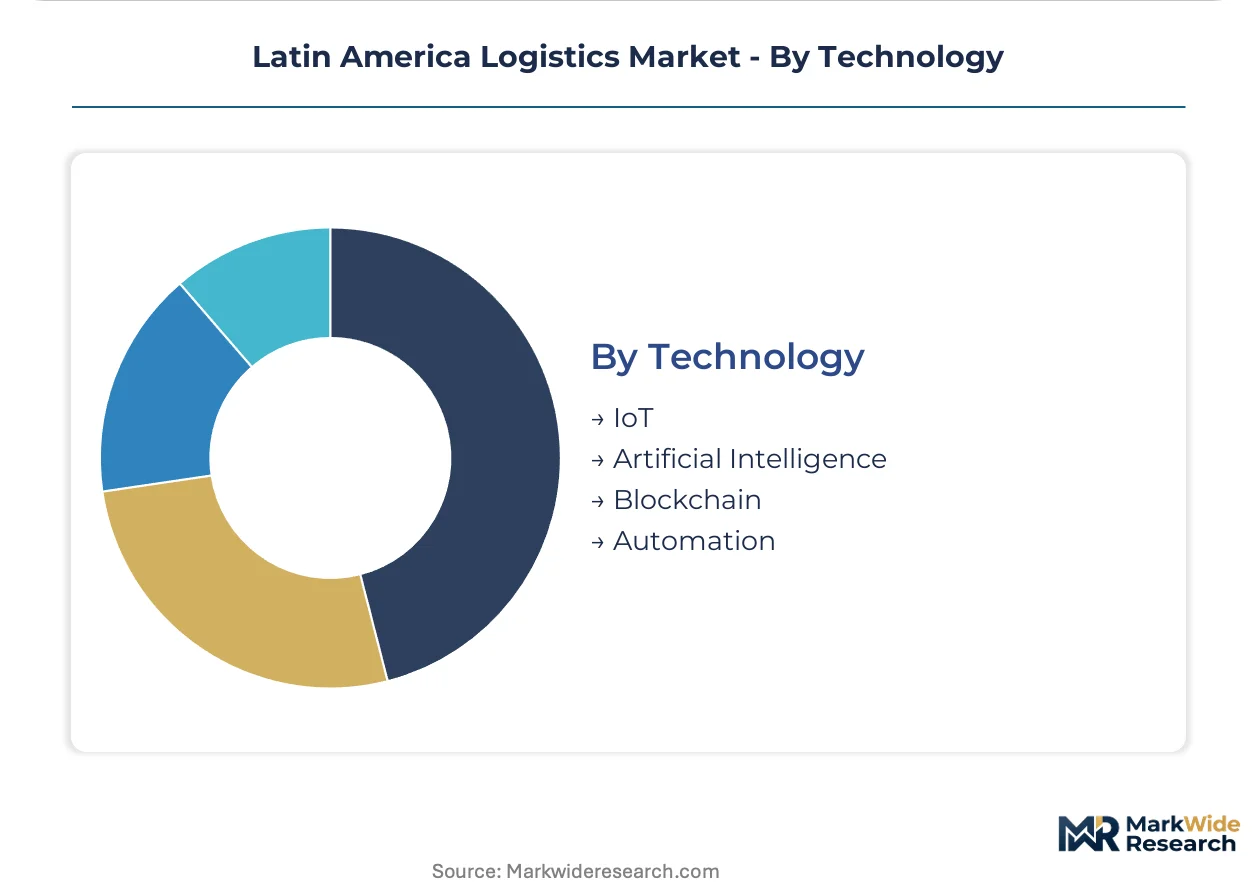
Maturity curves separate proven deployments from experimental implementations, with IoT and automation commanding capital allocation while blockchain remains in pilot phases.
- IoT:Sensor networks embedded in refrigerated containers and vehicle fleets provide real-time visibility for temperature-sensitive pharmaceutical shipments, collapsing insurance premiums and enabling ANVISA compliance documentation. Brazilian cold chain operators are deploying these systems at scale.
- Automation:Robotics and automated storage and retrieval systems in São Paulo and Mexico City fulfillment centers are displacing manual picking operations, with retrofit complexity limiting deployment in legacy facilities.
- Artificial Intelligence:Demand forecasting and route optimization algorithms improve asset utilization, though data fragmentation across Latin American markets constrains model training.
- Blockchain:Distributed ledger pilots for customs documentation and supply chain traceability remain limited by interoperability standards and regulator acceptance.
IoT holds the largest share; Automation shows the steepest expansion trajectory as labor costs and service-level pressures intensify.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Santos port complex anchors Brazil's logistics gravity, with container throughput expansion pulling inland distribution investment into the São Paulo corridor. Northern Mexico's manufacturing zones are generating cross-border freight demand linking Monterrey to US distribution networks. Chile's Valparaíso corridor and Colombia's Bogotá–Cartagena axis complete the region's multimodal backbone.
Brazil
E-commerce fulfillment networks and agricultural export flows drive capacity demand across southeastern logistics corridors. ANTT enforces tightening emissions standards for freight fleets, accelerating replacement cycles for older truck pools. The São Paulo–Santos corridor concentrates port modernization and inland connectivity upgrades, narrowing capacity gaps between maritime throughput and distribution networks.
Mexico
Nearshoring manufacturing growth and cross-border trade expansion generate freight volumes linking industrial zones to US distribution networks. SCT enforces stricter driver rest mandates and electronic logging device requirements for cross-border freight operations. The Monterrey–Nuevo Laredo corridor anchors manufacturing logistics, with Mexico City metropolitan zones driving last-mile infrastructure deployment.
Argentina
Agricultural commodity exports and pharmaceutical distribution sustain logistics demand despite macroeconomic headwinds. CNRT regulates axle-load limits and driver hour rules affecting fleet economics across long-haul corridors. The Rosario–Buenos Aires grain belt concentrates bulk freight flows, with port congestion creating demand for alternative routing through Uruguay.
Chile
Copper concentrate exports and retail import consumption sustain multimodal logistics demand across the central valley. The country's national transport regulator enforces weight limits and safety standards for trucking operations serving mining and consumer sectors. The Valparaíso–Santiago corridor anchors container throughput, with dry port development expanding inland distribution capacity.
Colombia
Energy sector logistics and consumer goods distribution drive freight demand across Andean and Caribbean corridors. The national infrastructure agency oversees concession contracts for port and highway modernization programs. The Bogotá–Cartagena axis concentrates warehousing investment, with Buenaventura port expansion pulling Pacific coast logistics development.
Latin America Logistics Market Competitive Landscape
Platform integrators command the system tier; component specialists sit upstream in niche service segments. The market structures around integrated ocean-to-warehouse operators, express delivery networks, and temperature-controlled specialists, with consolidation pressure elevating scale advantages. Three archetypes dominate: asset-heavy port-to-door integrators, station-network express operators, and certified cold chain specialists. Competitive moves center on fleet greening to meet ANTT and SCT mandates, plus urban micro-fulfillment positioning for e-commerce compression.
Within the integrated logistics tier, Maersk and DHL Group occupy positions spanning ocean freight through last-mile delivery, while DB Schenker exemplifies the temperature-controlled pharmaceutical specialization gaining share in regional trade lanes. Among regional digital platforms, Loggi represents the technology-native challenger archetype targeting same-day delivery compression in Brazilian metropolitan zones.
| Leading Market Players |
|---|
| CEVA Logistics |
| DSV A/S |
| DB Schenker |
| Loggi |
| DP World |
| DHL Group |
| FedEx Corporation |
| Maersk |
| Kuehne+Nagel |
| Others |
Pricing and Supply Chain Analysis
Fuel price volatility across Brazilian and Mexican long-haul corridors determines both margin compression in economy-tier trucking and the accelerated fleet replacement cycles reshaping competitive positioning. ANTT emissions mandates and SCT driver hour rules feed directly into cost structures that separate certified operators from legacy asset holders.
Pricing Analysis
Volume-discount tiering structures separate contract-based long-haul freight from spot-market transactional pricing across the São Paulo–Santos corridor. Price differentiation hinges on ANVISA cold chain certification and fleet emissions compliance grade, with certified pharmaceutical lanes commanding substantial premiums over ambient cargo. Cost compression in standard deferred delivery is intensifying because e-commerce platforms are squeezing service-level agreements toward same-day windows. Small and mid-sized retailers exhibit the highest price sensitivity, while pharmaceutical manufacturers demonstrate minimal elasticity due to traceability requirements.
Supply Chain Analysis
Tariff exposure between Mercosur members and external trade partners dominates supply chain risk calculus for regional freight forwarding. Manufacturing inputs for automotive and electronics assembly concentrate in Mexico, Brazil, and China, with cross-border chassis and component flows drawing from Pacific Rim supplier networks. Single-corridor vulnerability at Santos port creates systemic chokepoint risk for containerized imports. Distribution runs through port-centric regional DCs that are now fragmenting into urban micro-fulfillment nodes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin America logistics functions as a defensive-moat market where regulatory entrenchment through ANTT and SCT certification creates sustainable switching costs for compliant operators.
For Market Incumbents: Insulate market position by accelerating green fleet replacement ahead of ANTT Phase 2 emissions deadlines and deepening backward integration into captive warehousing at São Paulo and Mexico City consumption clusters. Digital freight platforms represent the primary substitution threat; counter by deploying proprietary IoT visibility layers that lock in pharmaceutical and automotive contract renewals.
For New Entrants and Emerging Players: Northern Mexico manufacturing zones outside Monterrey offer the most penetrable white space, with nearshoring production growth outpacing dedicated logistics infrastructure deployment. Target temperature-controlled pharmaceutical corridors where ANVISA certification scarcity limits incumbent density. Lead with asset-light digital brokerage models that aggregate fragmented trucking capacity before committing to owned fleet.
For Investors and Strategic Acquirers: The market sits at a consolidation phase that favors certified mid-cap specialists with established SCT and ANTT compliance records. Long-term viability rests on operators capable of bridging port-to-door integration across the next decade. Monitor cross-border freight volume inflections at Nuevo Laredo as the signal for nearshoring momentum acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Fleet Certification | ANTT emissions compliance unlocks contract access with multinational manufacturers in São Paulo corridor. |
| Urban Micro-Fulfillment Expansion | 15-kilometer radius positioning captures same-day delivery premiums from e-commerce marketplaces in Mexico City. |
| Cold Chain IoT Deployment | Real-time temperature monitoring collapses insurance costs and satisfies ANVISA pharmaceutical traceability mandates. |
| Cross-Border Infrastructure Partnership | Monterrey-Nuevo Laredo corridor investments capture nearshoring freight flows to US distribution networks. |
| Rail Intermodal Modernization | Brazilian agricultural interior-to-port connections offer modal shift alternatives to diesel-dependent long-haul trucking. |
Research Methodology
A spread of perspectives from fleet operations directors, pharmaceutical supply chain managers, port authority planners, and customs brokerage executives converged on the working assumptions underpinning this analysis. Primary fieldwork combined structured interviews with secondary validation against ANTT regulatory filings, SCT enforcement bulletins, Santos port throughput statistics, and customs trade databases. Bottom-up capacity modeling and top-down demand aggregation were triangulated to establish segment-level estimates.
Demand-supply-balance framing anchored the analytical approach across the projection horizon. Segmentation dimensions modeled include service type, delivery model, customer category, and technology deployment maturity. CAGRs were derived from capacity expansion pipelines, fleet replacement cycles, and e-commerce fulfillment infrastructure investment trajectories. Forecast inputs incorporated ANTT regulatory phase-in schedules and nearshoring manufacturing relocation patterns.
The forecast holds incumbent behavior within observed patterns; aggressive fleet electrification moves by integrated ocean-to-warehouse operators would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Logistics and Shipping
Digital Freight Forwarding Market
Logistics and Shipping
Internet of Things (IoT) in Logistics Market
Logistics and Shipping
Global Connected Logistics Market
Logistics and Shipping
Cambodia Freight and Logistics Market
Logistics and Shipping
Asean Freight and Logistics Market
Logistics and Shipping
North America Logistics Market
Logistics and Shipping
Germany Contract Logistics Market
Logistics and Shipping
Europe Full Container Load (FCL) Market
Logistics and Shipping
Netherlands Freight and Logistics Market
Logistics and Shipping
Asia-Pacific Logistics Automation Market
Logistics and Shipping
North America Shipping Supplies Market
Logistics and Shipping
Last Mile Delivery Transportation Market
Logistics and Shipping
Czech Republic Freight and Logistics Market
Logistics and Shipping
Germany Express Delivery Market
Logistics and Shipping
China Freight and Logistics Market
Logistics and Shipping
Digital Freight Management Market