
 Emergency Showers Market | 2026-2036
Emergency Showers Market Size, Share, and Industry Trends Forecast 2026-2036
Emergency Showers Market Analytics
Buyer concentration in the emergency showers market is decoupling from traditional heavy-industry procurement patterns as mid-sized chemical processors and regional healthcare systems fragment the customer base. Bradley Corporation leverages its vertical integration into stainless-steel fabrication to control cost structures across wall-mounted and pedestal product lines. Hughes Safety Showers anchors its competitive position through specialized engineering for extreme-temperature outdoor installations serving North Sea oil and gas platforms.
Emergency showers are pressurized safety fixtures designed to deliver immediate, sustained water flow for decontamination of personnel exposed to hazardous substances, typically requiring minimum flow rates and specific spray patterns to meet operational effectiveness standards. Wall-mounted units dominate commercial installations due to space efficiency and lower plumbing complexity, while portable systems represent the fastest-growing category as remote construction sites and temporary chemical handling operations expand their safety protocols. Stainless-steel construction commands premium positioning in corrosive environments, though fiberglass alternatives gain traction in coastal installations where salt-air degradation accelerates metal fatigue.
OSHA's General Industry Standards and the EPA's Risk Management Program shape installation mandates across United States chemical and manufacturing facilities, with non-compliance penalties driving replacement cycles for outdated equipment. The EU's ATEX directives and CE marking requirements for equipment used in potentially explosive atmospheres create parallel compliance obligations for European chemical processors. Stakeholders must monitor evolving regulatory harmonization between national safety codes and international ISO standards for emergency eyewash and shower equipment to anticipate certification requirements that will determine market access.
Market Dynamics
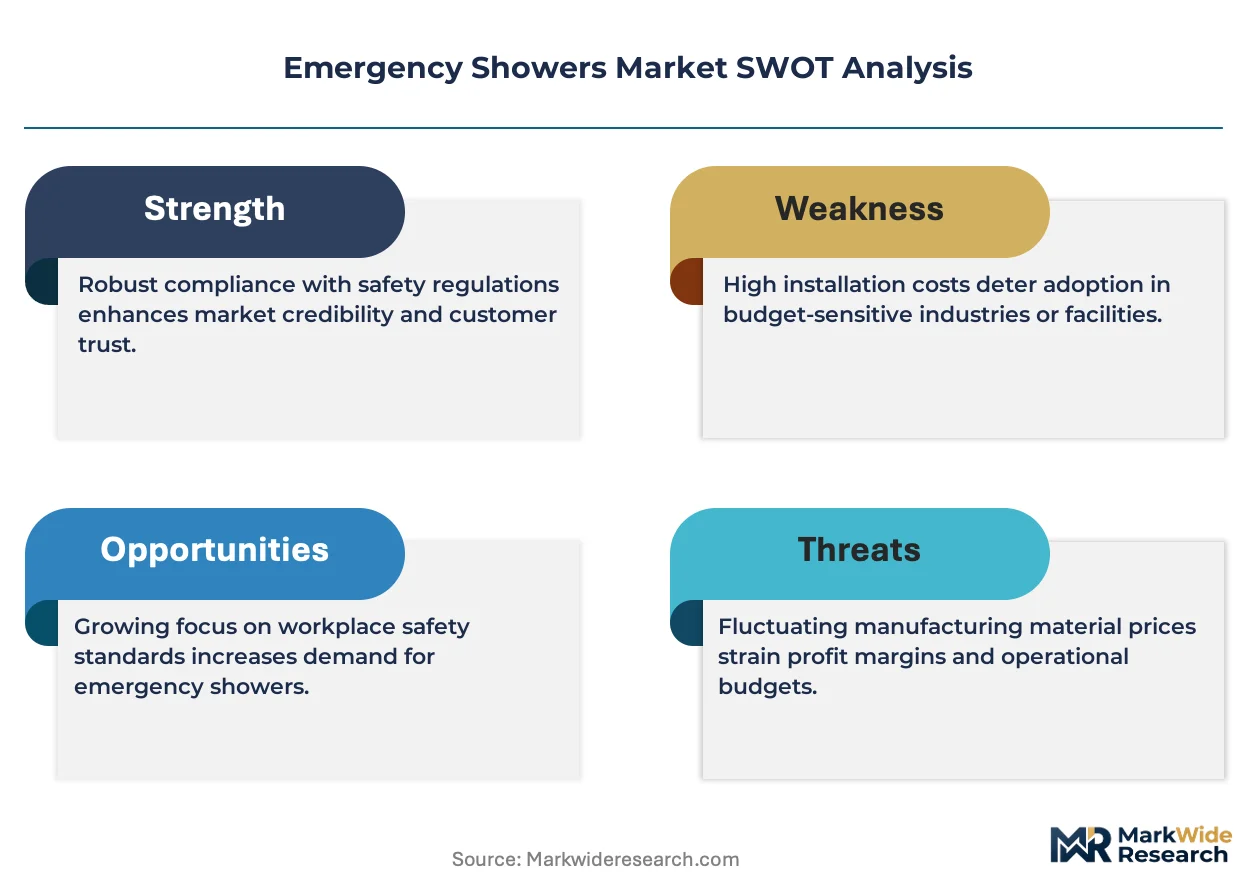
OSHA's enhanced enforcement of workplace safety standards is tightening compliance timelines for chemical processors, forcing accelerated replacement cycles for aging decontamination infrastructure across manufacturing facilities.
Growth Catalysts
- OSHA Enforcement Intensification:The agency's stricter inspection protocols for chemical handling facilities are mandating immediate upgrades to emergency eyewash and shower systems, creating replacement demand across legacy installations.
- Stainless-Steel Fabrication:Advances in corrosion-resistant alloys are extending equipment lifespan in aggressive chemical environments, reducing total cost of ownership for pharmaceutical manufacturers.
- Germany's Chemical Corridor:Concentrated capital expenditure on worker protection systems along the Rhine-Ruhr industrial belt is driving specification-grade demand for ATEX-certified emergency fixtures.
Market Restraints
- Copper and Nickel Volatility:Stainless-steel feedstock price swings compress margins for fabricators serving mid-tier chemical processors with fixed-budget safety mandates.
- Specialized Installer Scarcity:Certified plumbing contractors capable of meeting ANSI/ISEA Z358.1 flow-rate and temperature specifications are concentrated in mature industrial regions, delaying rural deployments.
- Fiberglass Substitution:Composite alternatives are capturing coastal installations where salt-air degradation accelerates metal fatigue, eroding stainless-steel's traditional dominance.
Strategic Opportunities
- Remote Construction Sites:Temporary chemical handling operations in mining and energy extraction are adopting portable self-contained shower units with heated water reservoirs.
- EU Green Deal Alignment:Water-recirculation and low-flow emergency systems qualify for sustainability-linked procurement preferences in European chemical facilities.
- IoT Convergence:Connected flow sensors and automated testing diagnostics are enabling predictive maintenance contracts that unbundle hardware from service revenue streams.
Industry Challenges
- ANSI/ISEA Z358.1 Certification Timelines:Third-party testing bottlenecks for novel materials and valve designs delay product launches by 8-14 months.
- Legacy Plumbing Integration:Retrofitting wall-mounted units into pre-1990s chemical plants requires custom manifold fabrication to achieve required flow rates without full infrastructure replacement.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Emergency Showers Market |
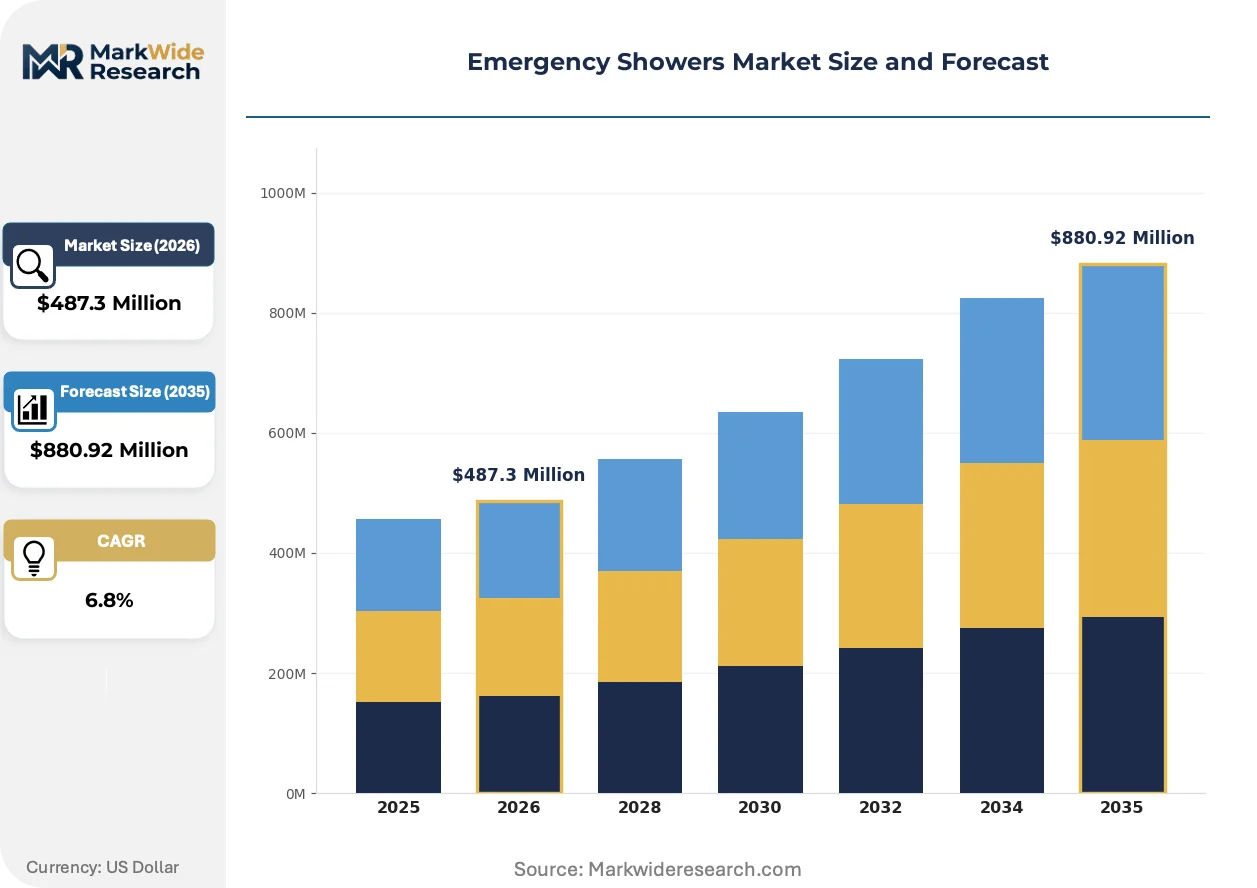
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $880.92 Million |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Wall-Mounted, Portable, Pedestal, Eye Wash Station End User: Manufacturing, Healthcare, Chemical, Construction Installation Type: Fixed, Mobile, Outdoor, Indoor Material: Stainless Steel, Plastic, Fiberglass, Carbon Steel |
| Companies Covered | Bradley Corporation, Hughes Safety Showers, Haws Corporation, Guardian Equipment, Encon Safety Products, Speakman Company, Honeywell International, Acorn Safety, Aqua Safety Showers, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Emergency Showers Market Evolving Landscape
Product differentiation is pivoting from raw material specifications toward integrated safety ecosystems, with connectivity and automated compliance documentation reshaping procurement criteria for facility managers.
Thermostatic mixing valves with digital temperature monitoring are overtaking mechanical-only designs in pharmaceutical cleanroom installations. Johnson & Johnson's manufacturing division specifies these units to eliminate scalding risk during emergency activation. The technology is compressing specification cycles as insurers tie liability premiums to documented temperature compliance.
REACH's expanded substance restrictions on nickel release are forcing European fabricators to reformulate stainless-steel grades for skin-contact applications. Chemical processors in Belgium and the Netherlands now require material certifications demonstrating compliance with Annex XVII nickel migration limits. This regulatory pressure is fragmenting supply chains as Asian manufacturers without EU-notified body accreditation lose specification status.
Facility managers are consolidating vendor relationships around full-service safety equipment providers capable of delivering eyewash stations, showers, and testing documentation through single-source contracts. Distributors with captive installation crews are displacing product-only resellers in the US Gulf Coast petrochemical corridor. This consolidation is most visible in Texas and Louisiana, where integrated safety contractors now specify equipment brands during front-end engineering design phases.
Emergency Showers Market Segmentation
Emergency shower procurement patterns diverge sharply across facility types, with chemical processors prioritizing corrosion resistance while healthcare systems emphasize space constraints and temperature precision. Understanding these segment boundaries clarifies where specification-grade requirements override cost considerations.
Product Type:
Buyer differentiation centers on permanence versus flexibility needs, with capital-intensive facilities favoring hard-plumbed installations and temporary operations demanding rapid deployment capability.
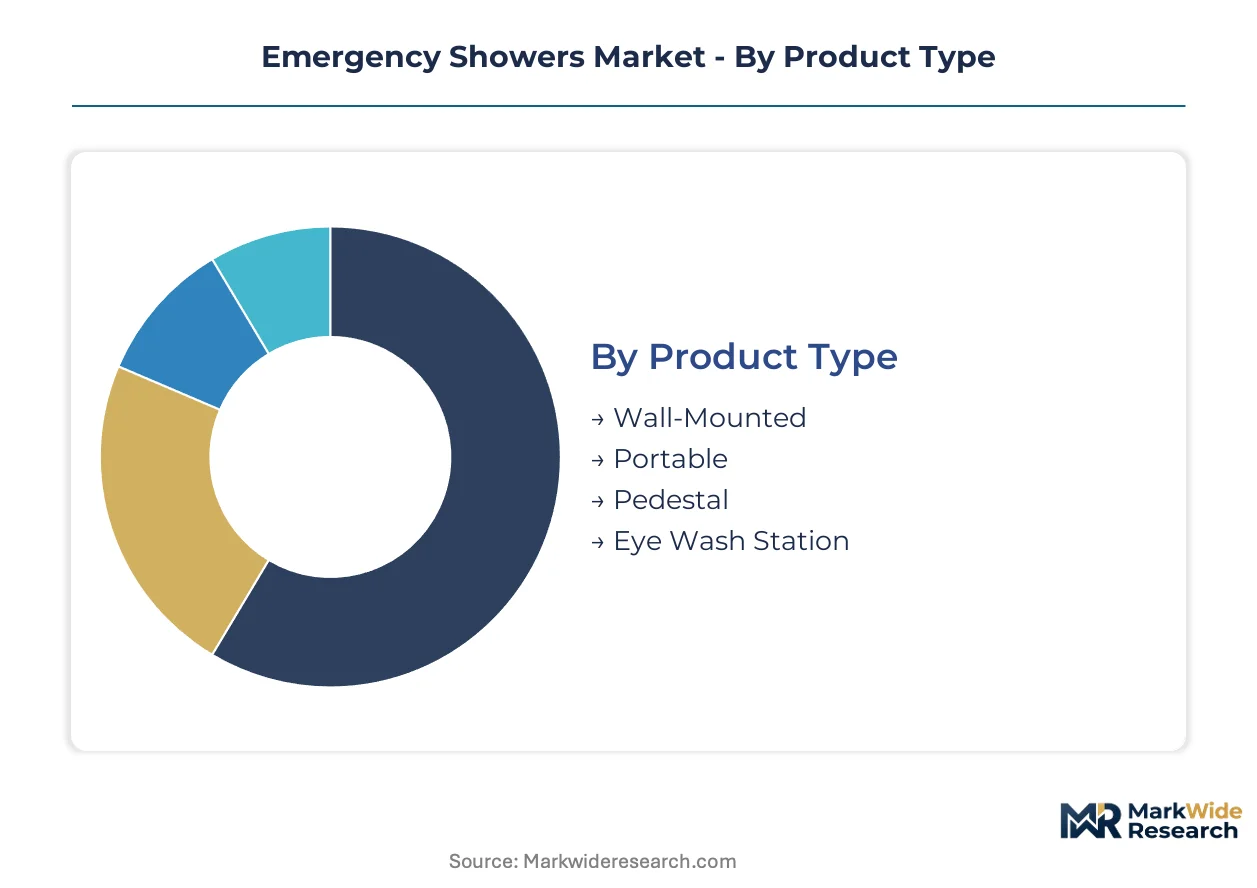
- Wall-Mounted:Fixed-position units with direct plumbing integration dominate commercial and industrial installations where floor space optimization matters. Chemical processing plants along the US Gulf Coast specify these for permanent decontamination stations, driven by OSHA's strict flow-rate mandates for stationary hazardous material handling zones.
- Portable:Self-contained systems with pressurized tanks or water reservoir connections serve remote construction sites and temporary laboratory setups. Mining operations in Western Australia and Canada's oil sands regions are expanding procurement of heated portable units to maintain ANSI/ISEA Z358.1 temperature compliance in sub-zero conditions.
- Pedestal:Freestanding floor-mounted fixtures with integrated drainage basins accommodate facilities lacking wall structural capacity.
- Eye Wash Station:Dedicated eyewash-only units or combination shower-eyewash systems address specialized ocular decontamination protocols in pharmaceutical cleanrooms.
Volume sits with Wall-Mounted; growth tilts toward Portable.
End User:
Regulatory exposure intensity separates these buyers, with chemical and pharmaceutical facilities facing the most stringent inspection regimes and penalty structures.
- Chemical:Petrochemical refineries, specialty chemical manufacturers, and bulk handling terminals require ATEX-certified fixtures for explosive atmospheres. Germany's Rhine-Ruhr corridor and the US Texas-Louisiana petrochemical belt concentrate replacement demand as aging infrastructure faces enhanced enforcement.
- Manufacturing:Metal fabrication, electronics assembly, and battery production facilities deploy emergency showers for acid, caustic, and solvent exposure risks. Automotive battery plants in South Korea and Hungary are expanding safety infrastructure to meet ISO 45001 certification requirements.
- Healthcare:Hospitals and research laboratories prioritize thermostatic mixing valves to prevent scalding in patient-accessible areas.
- Construction:Infrastructure and energy project sites adopt rental-based portable systems for contract-duration compliance.
Procurement value concentrates in Chemical; Healthcare shows the steepest specification upgrade trajectory.
Installation Type:
Environmental exposure severity determines material and engineering specifications, with outdoor installations demanding freeze-protection and UV-stability features absent from climate-controlled indoor deployments.
- Outdoor:Exposed installations on offshore platforms, pipeline stations, and remote mining sites require insulated enclosures and trace-heating systems. North Sea oil operators specify Hughes Safety Showers' extreme-temperature engineering to maintain operational readiness in maritime conditions.
- Indoor:Climate-controlled environments in pharmaceutical manufacturing and semiconductor fabrication allow standard stainless-steel construction without thermal protection add-ons.
- Fixed:Permanent hard-plumbed connections with dedicated supply lines and drainage infrastructure.
- Mobile:Trailer-mounted or skid-based systems repositioned across multi-phase construction or exploration projects.
Fixed installations dominate unit volume; Outdoor specifications command the widest premium spreads.
Material:
Corrosion resistance versus capital cost trade-offs fragment this category, with coastal and chemical-intensive environments justifying premium alloys while budget-constrained buyers accept shorter replacement cycles.
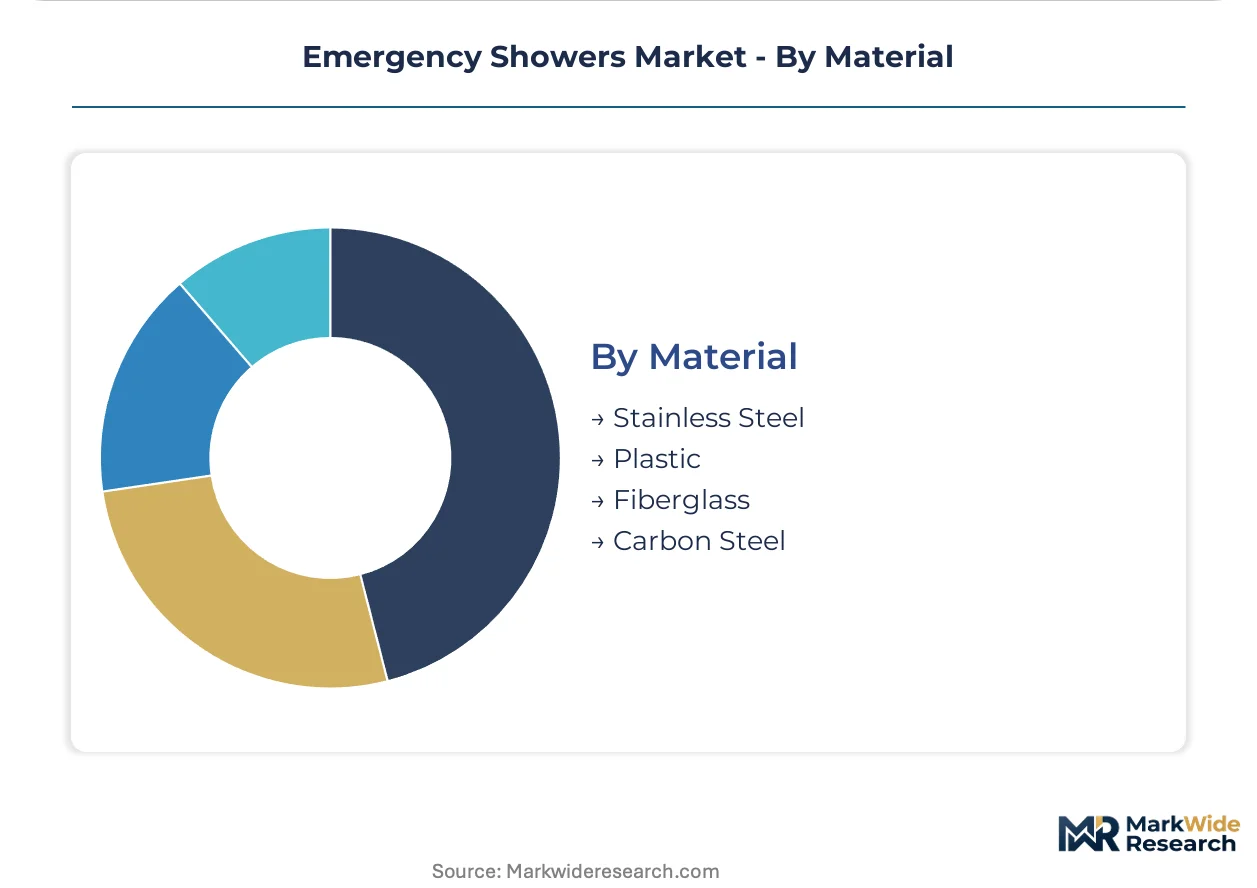
- Stainless Steel:Austenitic grades with molybdenum additions resist chloride attack in coastal chemical plants and pharmaceutical cleanrooms. REACH Annex XVII nickel migration limits are forcing European fabricators to certify 316L low-nickel formulations for skin-contact applications in Belgium and the Netherlands.
- Fiberglass:Glass-reinforced polymer construction eliminates galvanic corrosion in marine atmospheres and aggressive chemical fume environments. Coastal installations from Singapore to Norway's fjord-industrial zones are displacing metal fixtures where salt-air degradation accelerates structural failure.
- Plastic:Polyethylene or PVC units serve light-duty laboratory and educational facility applications with minimal chemical exposure severity.
- Carbon Steel:Epoxy-coated or galvanized budget options for dry, controlled environments with scheduled replacement programs.
Stainless Steel anchors revenue share; Fiberglass is expanding most quickly in coastal geographies.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Stainless-steel feedstock availability from German industrial mills anchors European supply chains for corrosion-resistant emergency fixtures. Chemical corridor concentration along the Rhine-Ruhr belt drives specification-grade demand for ATEX-certified equipment. North American enforcement intensity and Asian manufacturing scale complete the tripartite regional structure.
United States
OSHA's intensified inspection protocols for chemical handling facilities are accelerating replacement cycles across legacy installations. The agency's General Industry Standards mandate minimum flow rates and accessibility requirements that outdated equipment cannot satisfy. Texas and Louisiana's Gulf Coast petrochemical belt concentrates procurement volume as integrated safety contractors specify brands during front-end engineering design.
Germany
REACH Annex XVII nickel migration limits are forcing reformulation of stainless-steel grades for skin-contact applications in pharmaceutical and chemical plants. The EU's ATEX directives create parallel compliance obligations for equipment used in potentially explosive atmospheres. The Rhine-Ruhr industrial corridor sustains capital expenditure on worker protection systems as aging infrastructure faces enhanced enforcement.
China
GB standards for workplace safety equipment are tightening certification requirements for emergency shower manufacturers serving domestic chemical processors. The country's national safety regulator is harmonizing local codes with international ISO standards for emergency eyewash and shower equipment. Yangtze River Delta chemical parks are expanding safety infrastructure investments as foreign-invested pharmaceutical facilities raise specification benchmarks.
United Kingdom
Post-Brexit regulatory divergence from EU ATEX frameworks is creating dual certification burdens for equipment suppliers serving both markets. The Health and Safety Executive maintains inspection regimes for chemical and manufacturing facilities that parallel pre-exit enforcement intensity. North Sea oil and gas platforms demand extreme-temperature engineering for outdoor installations exposed to maritime conditions.
Australia
Western Australia's mining operations are expanding procurement of heated portable units to maintain ANSI/ISEA Z358.1 temperature compliance in sub-zero conditions. The country's national workplace safety regulator enforces standards adapted from international codes with additional local amendments. Coastal installations from Perth to Queensland's industrial zones are displacing metal fixtures with composite alternatives where salt-air degradation accelerates structural failure.
Emergency Showers Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue connected diagnostics and predictive maintenance services as differentiation vectors. The vendor base clusters around three strategic archetypes: vertically integrated stainless-steel fabricators controlling cost structures, specialized engineering houses serving extreme-environment installations, and diversified safety conglomerates leveraging distribution scale. Competitive moves concentrate on captive installation crew buildouts and IoT-enabled service contract unbundling.
Among North American fabricators, Bradley Corporation exemplifies the vertically integrated archetype through captive stainless-steel fabrication capabilities. Hughes Safety Showers anchors the specialized engineering tier with positioning around extreme-temperature outdoor installations. Haws Corporation occupies a position representing the established standards-compliant tier serving broad commercial and industrial segments.
| Leading Market Players |
|---|
| Bradley Corporation |
| Hughes Safety Showers |
| Haws Corporation |
| Guardian Equipment |
| Encon Safety Products |
| Speakman Company |
| Honeywell International |
| Acorn Safety |
| Aqua Safety Showers |
| Others |
Value Network & Pricing Analysis
Certified plumbing contractors concentrated in Germany's Rhine-Ruhr industrial belt and the US Gulf Coast command wage premiums that widen pricing spreads between specification-grade and economy-tier emergency shower systems. Labor-cost differentials between these skilled installer hubs and secondary markets force fabricators to absorb margin compression or pass through regional delivery premiums.
Pricing Analysis
Volume concentrates in standard-grade wall-mounted units while margins concentrate in ATEX-certified outdoor systems with thermostatic mixing valves. Price differentiation rests on ANSI/ISEA Z358.1 certification tier and stainless-steel grade specification, with pharmaceutical cleanroom installations paying premiums for REACH-compliant low-nickel alloys. Pricing pressure stems from fiberglass substitution in coastal geographies eroding stainless-steel's traditional premium position. Mid-sized chemical processors exhibit highest price sensitivity due to fixed-budget safety mandates, while North Sea oil operators show lowest sensitivity given liability exposure.
Supply Chain Analysis
Third-party testing bottlenecks for ANSI/ISEA Z358.1 certification gate market access and elongate supplier qualification timelines. Manufacturing concentrates in Germany, the United States, and China, with German mills anchoring European stainless-steel feedstock availability. Raw material dependencies center on nickel, molybdenum, and specialized thermoplastic resins for valve components. Supply chain risk hinges on REACH Annex XVII nickel migration restrictions fragmenting European qualification status for Asian fabricators. Distribution runs through integrated safety contractors with captive installation crews displacing product-only resellers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a cost-of-compliance story where OSHA's intensified enforcement creates a barrier-to-entry moat for players with certified installation networks and documented testing protocols.
For Market Incumbents: Lock in specification-grade positioning by acquiring captive installation crews in the Texas-Louisiana petrochemical corridor and certifying low-nickel stainless formulations ahead of REACH Annex XVII expansion. Defend against fiberglass substitution by extending corrosion warranties for coastal deployments and embedding IoT flow sensors to unbundle predictive maintenance revenue from hardware sales. For New Entrants and Emerging Players: The mid-tier price-point gap between Hughes Safety Showers' extreme-environment engineering and economy-grade plastic units offers white-space entry. Target portable heated systems for Western Australian mining and Canadian oil sands operations where ANSI temperature compliance commands rental premiums. Pursue EU Green Deal alignment through water-recirculation technology to qualify for sustainability-linked procurement preferences. For Investors and Strategic Acquirers: Re-rating potential sits with vertically integrated fabricators controlling stainless-steel production given nickel price volatility and certification moats. Long-term viability favors players with IoT-enabled service contracts and predictive maintenance capabilities. Monitor OSHA inspection protocol expansion as the inflection signal for replacement cycle acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Captive Installer Crew Acquisition | Integrated safety contractors in Texas and Louisiana now specify brands during front-end engineering design phases. |
| Low-Nickel Alloy Certification | REACH Annex XVII compliance in Belgium and Netherlands forces material reformulation and fragments Asian supplier access. |
| IoT Flow Sensor Integration | Connected diagnostics enable predictive maintenance contracts that unbundle hardware from recurring service revenue streams. |
| Portable Heated System Development | Sub-zero mining operations in Western Australia and Canada expand procurement for ANSI temperature-compliant mobile units. |
| Water-Recirculation Technology | EU Green Deal sustainability-linked procurement preferences favor low-flow emergency systems in European chemical facilities. |
Research Methodology
Independent corroboration across facility safety managers, certified plumbing contractors, and chemical plant procurement leads underwrites the qualitative findings. Primary interviews with maintenance directors, OEM specification engineers, and aftermarket service heads combined with secondary validation from OSHA enforcement records, ANSI/ISEA standard documentation, and EU ATEX directive filings. Bottom-up triangulation across product-type demand curves and top-down validation against chemical sector capital expenditure patterns anchored volume estimates.
Rate-of-change decomposition across the projection horizon separates replacement-cycle velocity from new-installation growth in chemical processing and pharmaceutical manufacturing segments. The analytical framework models product type, end-user industry, installation environment, and material specification dimensions throughout the forecast period. CAGRs derived from regression against chemical sector employment growth, regulatory enforcement intensity indices, and stainless-steel price elasticity assumptions.
Inputs from OSHA inspection databases and EU notified body certification registries were available through the study window; gaps in real-time nickel price volatility data introduce uncertainty bands around margin projections. Forecasts reflect documented assumptions regarding enforcement continuity and harmonization timelines between national safety codes and international ISO standards. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Safety Equipment and Personal Protective Equipment (PPE)
Middle East and Africa N95 Mask Market
Safety Equipment and Personal Protective Equipment (PPE)
Tourniquet Market
Safety Equipment and Personal Protective Equipment (PPE)
Drone Safety Solutions Market
Safety Equipment and Personal Protective Equipment (PPE)
Scuba Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
US Law Enforcement PPE Market
Safety Equipment and Personal Protective Equipment (PPE)
Active Protection System Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Explosion Proof Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Smart Helmet Market
Safety Equipment and Personal Protective Equipment (PPE)
Global Rodent Control Market
Safety Equipment and Personal Protective Equipment (PPE)
Head Protection Equipment Market
Safety Equipment and Personal Protective Equipment (PPE)
Self-Contained Breathing Apparatus (SCBA) Cylinders Market
Safety Equipment and Personal Protective Equipment (PPE)
Cut Resistant Gloves Market
Safety Equipment and Personal Protective Equipment (PPE)
China Hand Sanitizer Market
Safety Equipment and Personal Protective Equipment (PPE)
Padlock Seals Market
Safety Equipment and Personal Protective Equipment (PPE)
Splash Shield Market
Safety Equipment and Personal Protective Equipment (PPE)
Healthcare Personal Protective Equipment (PPE) Market