
 North America Programmatic Advertisement Market | 2026-2036
North America Programmatic Advertisement Market Size, Share, and Industry Trends Forecast 2026-2036
North America Programmatic Advertisement Market Analytics
Single-source reliance on walled-garden inventory is decoupling as advertisers diversify toward independent demand-side platforms. The Trade Desk Inc. leverages its unified ID framework to sustain open-internet competitiveness outside dominant ecosystem control. Alphabet Inc. anchors search and YouTube inventory through its integrated buy-side infrastructure. Magnite Inc. competes as the largest independent sell-side platform, specializing in connected television supply paths.
North America Programmatic Advertisement denotes the automated, algorithm-driven buying and selling of digital advertising inventory through real-time auctions and reserved deal mechanisms, utilizing data management platforms and demand-side software to match audience segments with impression opportunities at millisecond latency. Its primary commercial purpose eliminates manual insertion orders while enabling granular frequency capping, dynamic creative optimization, and return-on-ad-spend measurement across fragmented consumer touchpoints. Mobile and video platform types command the dominant share of transaction volume as consumption shifts to handheld and streaming environments, while private marketplace purchase methods represent the fastest-expanding structural category as brand safety concerns elevate direct publisher relationships over open exchange volatility. Retail and technology verticals anchor current spending concentration, though automotive advertisers are migrating budgets into programmatic guaranteed formats for premium inventory access.
The Federal Trade Commission enforces consumer protection standards against deceptive ad targeting practices, while state attorneys general in California and Virginia operationalize privacy statutes that restrict third-party data flows and mandate opt-out mechanisms. These frameworks compel platform operators to reengineer identity resolution toward first-party data strategies and consent-based measurement. Stakeholders must monitor the fragmentation of addressability standards across state jurisdictions and assess whether contextual targeting capabilities can offset signal loss from deprecated mobile identifiers.
Market Dynamics
Identity deprecation across mobile operating systems and browser environments is forcing advertisers to rebuild audience targeting on first-party data foundations and authenticated user relationships.
Growth Catalysts
- Connected Television Expansion:Streaming platforms are opening inventory to automated buying, enabling retail brands to apply digital targeting precision to living-room screens.
- The California Consumer Privacy Act:This framework's opt-out requirements are accelerating investment in consent management platforms and clean-room data collaboration infrastructure.
- Private Marketplace Adoption:Canadian advertisers are prioritizing direct publisher relationships through programmatic guaranteed deals to secure brand-safe inventory.
Market Restraints
- Signal Loss from Identifier Deprecation:Apple's App Tracking Transparency and Google's Privacy Sandbox are compressing addressable audience pools and degrading attribution fidelity.
- Supply Path Concentration:A handful of dominant sell-side platforms control premium connected television inventory, elevating take rates and reducing buyer leverage.
- Cross-State Regulatory Fragmentation:Divergent privacy statutes across California, Virginia, Colorado, and Connecticut are multiplying compliance architectures for national campaigns.
Strategic Opportunities
- Retail Media Networks:First-party purchase data from grocery and big-box retailers is enabling closed-loop measurement that bypasses third-party cookie dependencies.
- Digital Audio Automation:Podcast and streaming music platforms remain underpenetrated by programmatic buying, creating inventory arbitrage potential for early movers.
- Unified ID Convergence:Interoperable identity frameworks are absorbing fragmented authentication standards, enabling cross-publisher audience resolution without device-level tracking.
Industry Challenges
- Data Engineering Talent Scarcity:Shortages of privacy-preserving measurement specialists and clean-room architects are delaying first-party data strategy execution.
- Legacy Workflow Integration:Automated buying platforms must reconcile with entrenched media planning processes and finance approval hierarchies at established agencies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | North America Programmatic Advertisement Market |
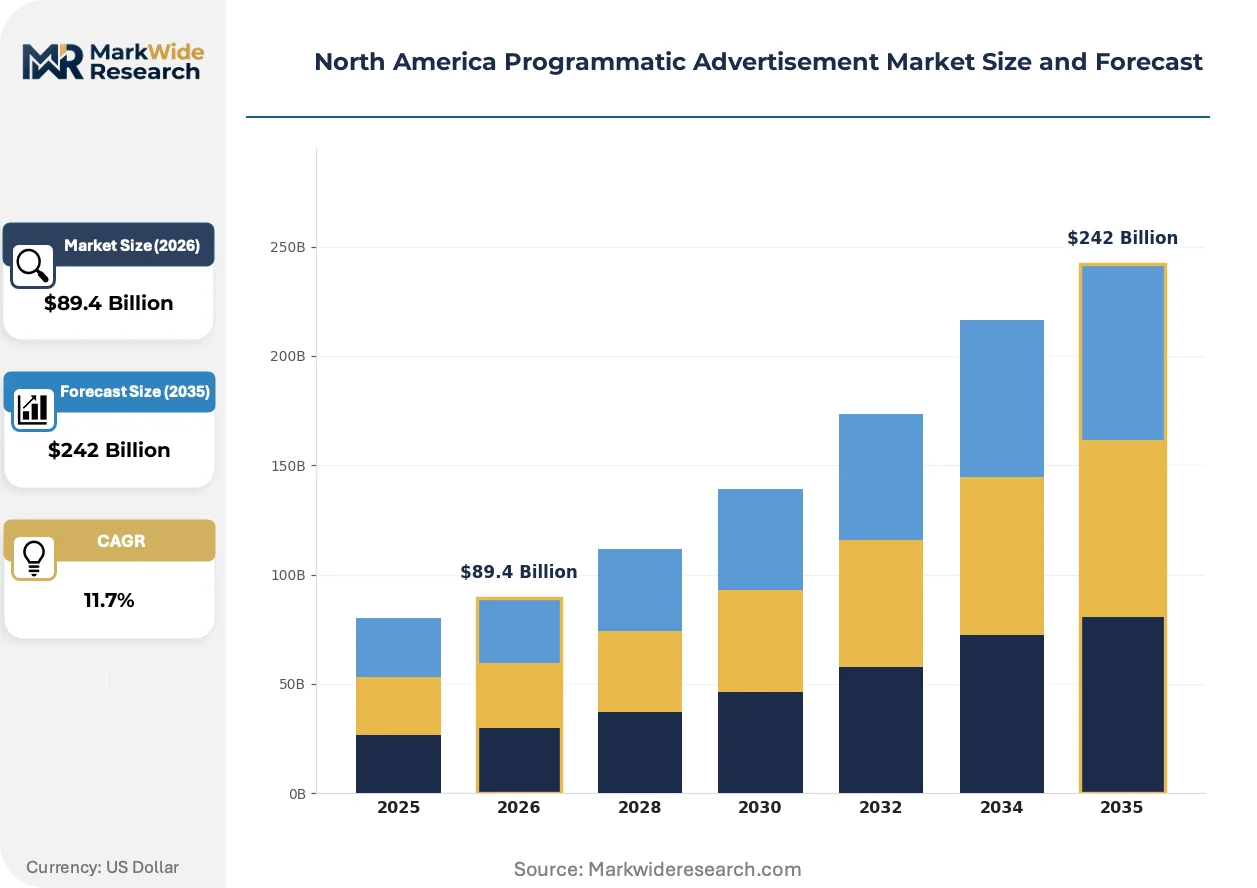
| Market Size in 2026 | $89.4 Billion |
| Market Size in 2035 | $242 Billion |
| CAGR (2026 – 2036) | 11.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Platform Type: Desktop, Mobile, Video, Social Media Ad Format: Display, Native, Audio, Video Ad Industry Vertical: Retail, Entertainment, Automotive, Technology Purchase Method: Direct, Programmatic Guaranteed, Real-Time Bidding, Private Marketplace |
| Companies Covered | The Trade Desk Inc., PubMatic Inc., Alphabet Inc., Xandr, Amazon Advertising, Adobe Advertising Cloud, MediaMath, Magnite Inc., OpenX, Others |
| Regions Covered | North America: US, Canada, Mexico |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
North America Programmatic Advertisement Market Evolving Landscape
Algorithmic optimization is migrating from impression-level bidding toward outcome-based allocation, compressing the distance between ad exposure and commercial transaction.
Server-side ad insertion technology is absorbing the technical burden of stitching personalized creative into streaming content before delivery to consumer devices. Broadcasters and premium publishers are adopting this infrastructure to preserve user experience quality while enabling addressable targeting. The technology is absorbing latency costs that previously forced trade-offs between personalization and playback performance.
The Federal Trade Commission's heightened scrutiny of dark patterns in digital interfaces is reshaping consent flow design across demand-side platforms. Advertisers must now engineer opt-out mechanisms that match the prominence of opt-in pathways, elevating user experience investment. This enforcement posture most acutely affects mobile app install campaigns and retargeting sequences that rely on granular behavioral triggers.
Outcome-based media buying is compressing traditional upfront commitment cycles as advertisers demand payment terms tied to verified business results. Retail and direct-to-consumer brands are piloting cost-per-acquisition guarantees with supply-side partners, displacing CPM-based guaranteed contracts. This shift is most visible in the United States, where performance marketing cultures and attribution infrastructure maturity enable closed-loop verification.
North America Programmatic Advertisement Market Segmentation
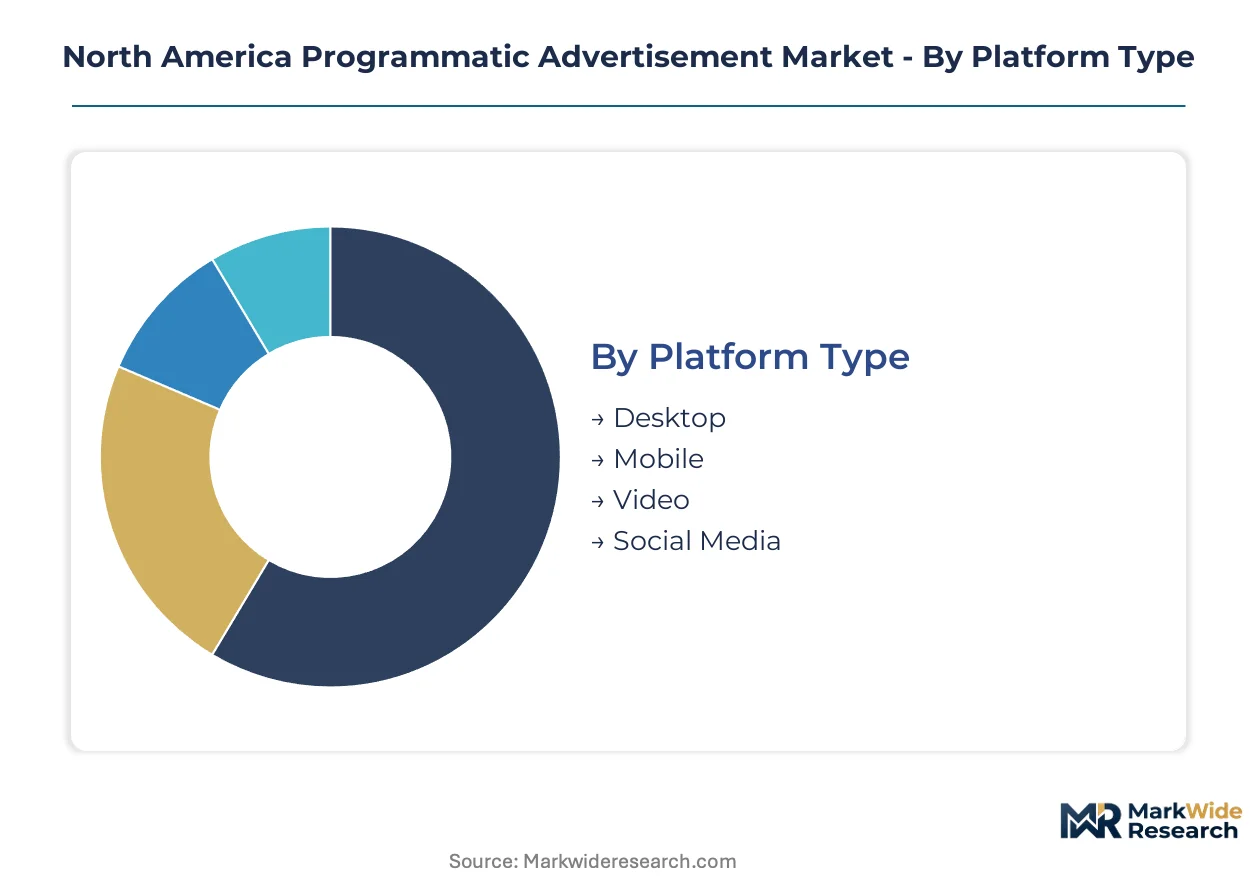
Segmentation in programmatic advertising determines where capital efficiency concentrates and where technical complexity escalates. Buyers allocate infrastructure investment across platform types and purchase methods based on inventory access costs and data integration requirements.
Platform Type:
Capital intensity peaks in video infrastructure, where server-side ad insertion and streaming compatibility demand substantial upfront engineering investment.
- Mobile:In-app and mobile web inventory commands the dominant transaction volume across North American markets. Retail advertisers in the United States concentrate automated buying here to capture on-the-go purchase intent, though Apple's App Tracking Transparency has degraded addressability and forced migration toward first-party authentication.
- Video:Connected television and over-the-top streaming inventory requires the heaviest technical infrastructure for server-side ad insertion and creative personalization. Canadian advertisers are accelerating investment in this segment as broadcasters open premium living-room inventory to automated buying.
- Desktop:Browser-based display and video inventory retains relevance for B2B targeting and high-consideration purchase journeys. Cookie deprecation is compressing addressable scale here faster than on mobile environments.
- Social Media:Walled-garden platforms operate proprietary auction mechanisms with closed measurement loops. Technology verticals maintain substantial allocation here despite higher effective CPMs and limited cross-platform frequency management.
Most installed capacity flows through Mobile. Expansion is steepest in Video.
Ad Format:
Technical production costs and creative versioning complexity vary sharply across formats, with video and audio demanding specialized studio partnerships.
- Video Ad:Pre-roll, mid-roll, and connected television placements enable dynamic creative optimization with sequential storytelling. Automotive advertisers in the United States prioritize this format for model launches, leveraging interactive end cards and shoppable overlays.
- Display:Banner and rich media units remain the workhorse for retargeting and prospecting at scale. Retail brands use programmatic direct deals to secure above-the-fold placements on premium publisher properties.
- Native:In-feed and recommendation widget placements match editorial context for reduced ad avoidance. Technology advertisers favor this format for thought leadership content distribution.
- Audio:Podcast and streaming music inventory remains underpenetrated by automated buying, creating arbitrage potential for early movers with creative assets suited to voice-activated environments.
Display absorbs the largest share of transaction volume. Audio is climbing the fastest as infrastructure matures.
Industry Vertical:
Customer lifetime value and purchase cycle length determine how aggressively verticals invest in first-party data infrastructure and attribution modeling.
- Retail:Grocery and big-box retailers operate the most sophisticated retail media networks, leveraging closed-loop purchase data for audience targeting. Walmart and Target have built demand-side infrastructure that rivals independent platforms.
- Technology:Software and consumer electronics brands concentrate spending in private marketplaces to control frequency and context around product launches. This vertical leads in outcome-based contract adoption.
- Automotive:OEMs and dealer networks are migrating budgets into programmatic guaranteed formats for premium inventory access, prioritizing viewability and brand safety over cost efficiency.
- Entertainment:Streaming services and studios use automated buying for subscriber acquisition, with heavy reliance on video and connected television inventory for trailer distribution.
Retail deploys the most capital into data infrastructure. Automotive is gaining share fastest as guaranteed deal adoption accelerates.
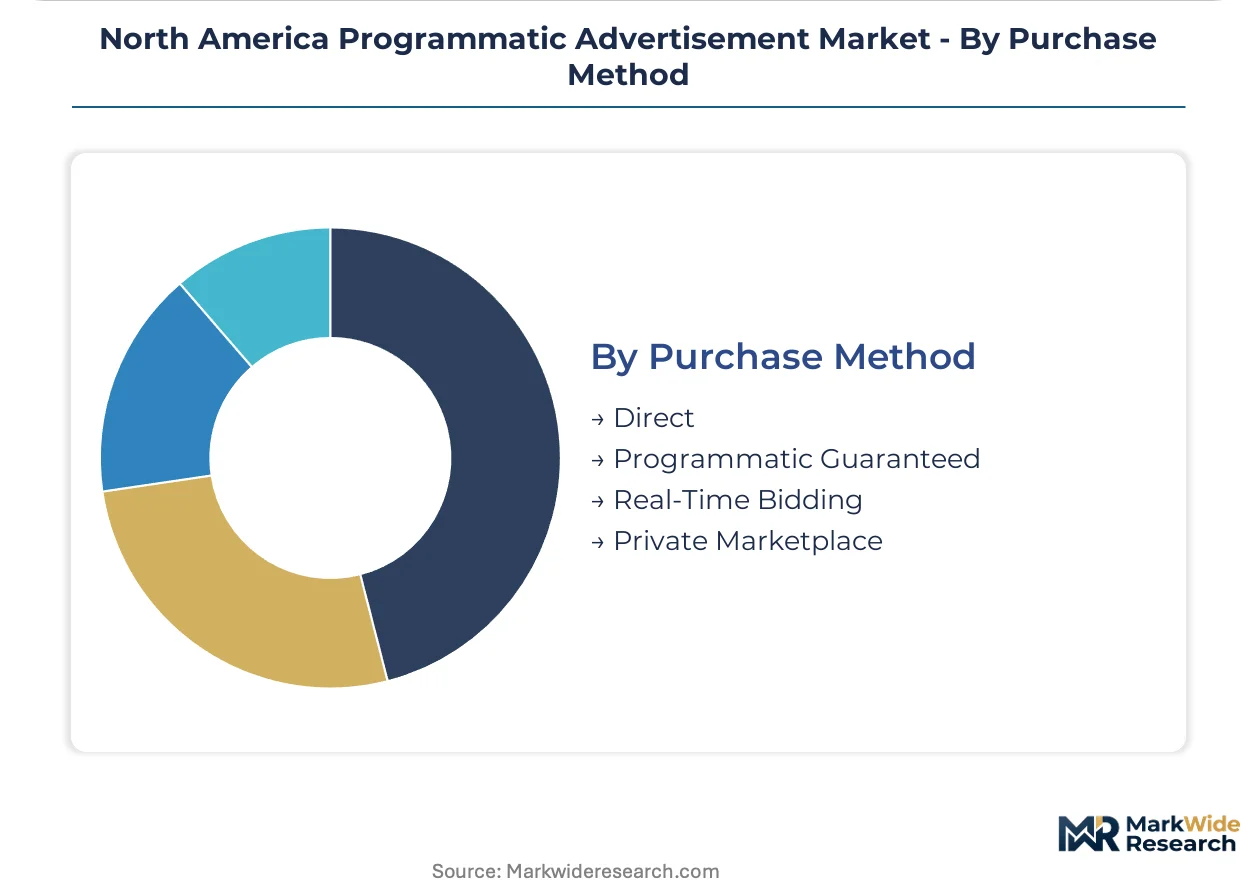
Purchase Method:
Contract structure determines working capital requirements and risk allocation between buyer and seller.
- Private Marketplace:Invitation-only auctions with preferred publisher relationships command premium CPMs in exchange for priority access and reduced fraud exposure. Canadian advertisers prioritize this method for brand safety assurance.
- Real-Time Bidding:Open exchange auctions offer maximum reach and liquidity but introduce supply path opacity and viewability risk. Technology verticals with strong attribution infrastructure tolerate this volatility.
- Programmatic Guaranteed:Fixed-price, reserved inventory deals combine automation with upfront commitment security. Automotive and retail brands use this for high-impact tentpole campaigns.
- Direct:Manual insertion orders persist for sponsorships and custom content integrations that resist standardization. Entertainment studios rely on this for premiere events and talent-aligned placements.
Real-Time Bidding processes the highest transaction volume. Private Marketplace is expanding most quickly as brand safety concerns escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's demand-side platform cluster anchors North American programmatic advertising infrastructure development. Canadian private marketplace adoption accelerates alongside Mexican over-the-top streaming inventory opening to automated buying. Regulatory fragmentation across state and provincial jurisdictions reshapes data governance requirements throughout the continent.
United States
Retail media networks and connected television inventory command the dominant share of automated media investment. The Federal Trade Commission enforces consumer protection standards against deceptive ad targeting practices while state attorneys general in California and Virginia operationalize privacy statutes. New York and Los Angeles metropolitan areas concentrate demand-side platform engineering talent and premium publisher headquarters.
Canada
Private marketplace transactions and programmatic guaranteed deals absorb the fastest-growing share of Canadian advertiser budgets. Health Canada and the Office of the Privacy Commissioner coordinate federal oversight while Quebec's provincial framework imposes additional consent requirements. Toronto's media buying agencies prioritize direct publisher relationships for brand safety assurance in financial services and telecommunications verticals.
Mexico
Over-the-top streaming platforms and mobile in-app inventory present underpenetrated opportunities for programmatic infrastructure expansion. The Federal Institute of Telecommunications regulates digital advertising transparency while consumer protection agencies enforce data processing disclosures. Mexico City anchors the national market with concentrated advertising agency headquarters and broadcaster operations.
North America Programmatic Advertisement Market Competitive Landscape
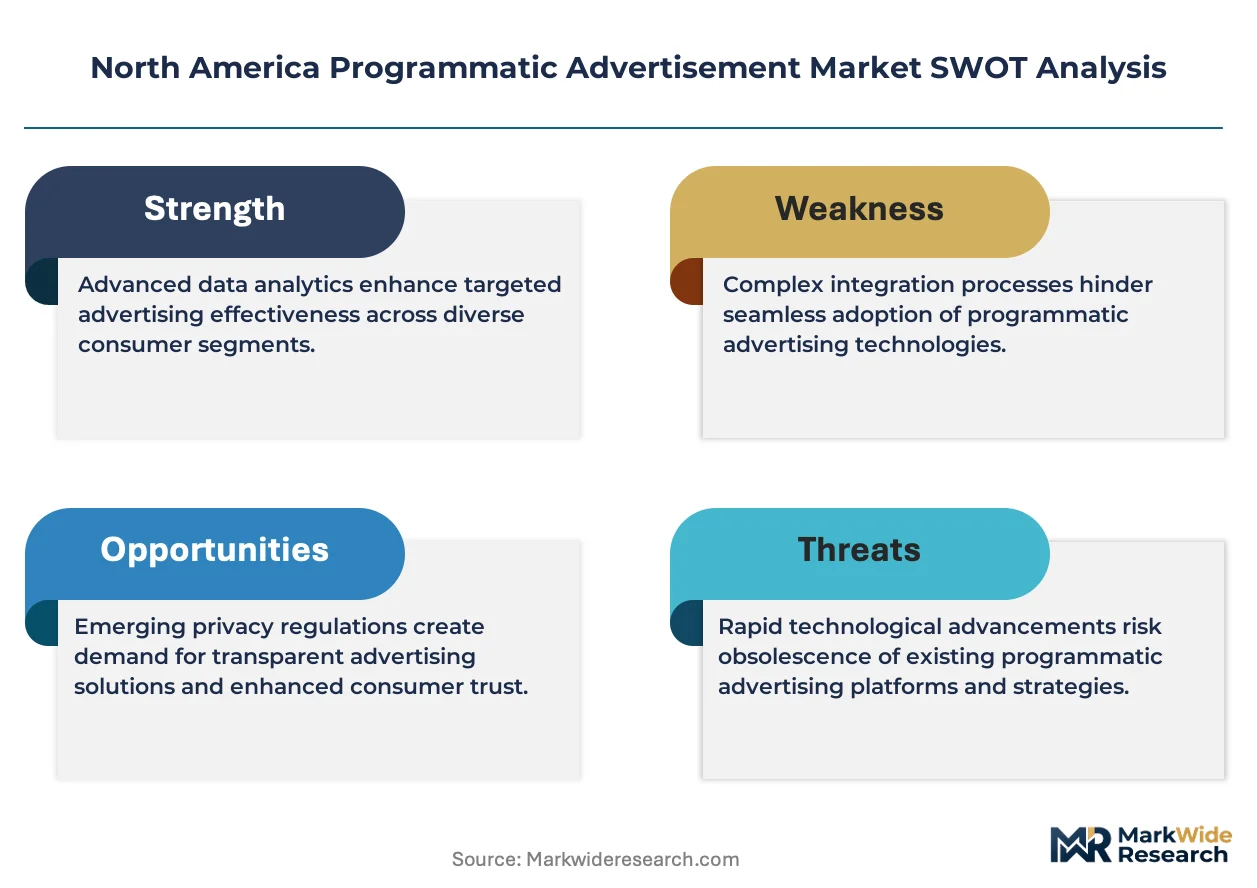
Established producers occupy the standard tier; emerging entrants pursue retail media network specialization and unified identity resolution. The vendor base concentrates around three structural tiers: integrated technology conglomerates operating proprietary walled gardens, independent demand-side platforms competing on open-internet inventory access, and sell-side platforms optimizing publisher yield management. Dominant competitive moves include strategic partnerships between retailers and ad tech infrastructure providers alongside portfolio diversification into clean-room data collaboration services.
Within the independent platform tier, The Trade Desk Inc. and Magnite Inc. occupy positions exemplifying demand-side and sell-side specialization respectively. Alphabet Inc. anchors the integrated conglomerate archetype through search and video inventory control. These three entities represent the primary competitive vectors shaping automated media buying infrastructure across North American markets.
| Leading Market Players |
|---|
| The Trade Desk Inc. |
| PubMatic Inc. |
| Alphabet Inc. |
| Xandr |
| Amazon Advertising |
| Adobe Advertising Cloud |
| MediaMath |
| Magnite Inc. |
| OpenX |
| Others |
Value Network & Pricing Analysis
Private-equity-rolled-up demand-side platforms and sell-side aggregators have consolidated auction infrastructure across North American markets, compressing intermediary margins while elevating take-rate discipline at dominant exchange nodes. This ownership concentration feeds directly into pricing power asymmetries between independent platforms and walled-garden operators, reshaping how advertisers allocate working capital across inventory tiers.
Pricing Analysis
Input-cost pass-through from cloud compute and data infrastructure expenses flows disproportionately into SaaS-tiered platform fees rather than per-impression transaction costs. Pricing stratifies across premium private marketplace, standard open exchange, and economy remnant inventory tiers, with differentiation driven by viewability certification levels and first-party data enrichment depth. Cost compression in open exchange CPMs is intensifying because identifier deprecation has degraded addressable audience precision, forcing budget migration toward authenticated premium tiers. Mid-market advertisers exhibit the highest price sensitivity, while enterprise retail brands with closed-loop measurement tolerate elevated effective CPMs for guaranteed inventory access.
Supply Chain Analysis
Regional distribution centers for ad serving infrastructure concentrate in Northern Virginia, Dallas-Fort Worth, and Chicago, forming hub-and-spoke patterns that minimize latency to major media markets. Supply draws from proprietary cloud deployments, third-party CDN partnerships, and edge computing nodes across the United States, Canada, and Mexico. Raw material dependencies span server hardware components, bandwidth provisioning contracts, and clean-room data collaboration software licenses. Single-source vulnerability concentrates around hyperscaler cloud contracts that dominate server-side ad insertion workloads. Distribution runs through direct platform integrations, agency trading desk relationships, and publisher self-service portals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in programmatic advertising rests on automation of manual workflow layers and premium-tier migration of brand safety-conscious advertisers away from commoditized open exchange inventory.
For Market Incumbents: Deepen first-party data infrastructure investments to offset signal loss from mobile identifier deprecation, while consolidating supply path relationships to reduce auction duplication. The Trade Desk's unified ID framework and Magnite's CTV yield optimization represent defensive moats against emerging retail media networks. Vertical integration into clean-room measurement services offers the strongest lever for sustaining platform differentiation as third-party cookie deprecation accelerates. For New Entrants and Emerging Players: The price-point gap between premium connected television guaranteed deals and economy mobile open exchange inventory creates white-space opportunity for mid-tier private marketplace specialists. Canadian financial services and telecommunications verticals remain underpenetrated by independent platforms, offering the most penetrable geography for direct publisher relationship building. A go-to-market angle anchored in Quebec-specific consent management compliance and French-language creative versioning can bypass entrenched US-centric competitors. For Investors and Strategic Acquirers: Valuations sit cheapest among independent sell-side platforms with connected television inventory concentration but limited demand-side platform diversification. Long-term viability across the projection horizon hinges on interoperability with retail media networks and authentication-based identity resolution. Acquisition target archetypes include clean-room infrastructure specialists and podcast ad insertion technology providers. The signal to watch is consolidation velocity among mid-tier demand-side platforms as identifier deprecation forces scale thresholds upward.| Strategic Initiative | Industry Significance |
|---|---|
| Retail Media Network Partnership | Walmart and Target's closed-loop data enables advertisers to bypass third-party cookie dependencies entirely. |
| Server-Side Ad Insertion Deployment | Broadcasters adopting this infrastructure preserve user experience while enabling addressable targeting in streaming environments. |
| Unified ID Framework Adoption | Interoperable authentication standards reduce fragmentation costs for cross-publisher audience resolution. |
| Clean-Room Data Collaboration | Privacy-preserving measurement architectures satisfy California Consumer Privacy Act requirements while maintaining attribution fidelity. |
| Private Marketplace Expansion | Direct publisher relationships command premium CPMs in exchange for reduced fraud exposure and brand safety assurance. |
Research Methodology
Direct dialogue with demand-side platform product managers, sell-side platform yield directors, agency trading desk leads, and retail media network executives grounded qualitative insights in operational reality. Secondary validation drew from SEC filings of publicly traded ad tech companies, Federal Trade Commission enforcement actions, state attorney general privacy statute implementations, and IAB technical standards documentation. Bottom-up transaction volume estimates triangulated against top-down advertising spend allocation surveys to reconcile measurement discrepancies.
Segment-level outputs across the analysis window reflect modeled projections for platform type, purchase method, ad format, and industry vertical dimensions. CAGRs derived from historical transaction velocity patterns, inventory expansion trajectories in connected television and digital audio, and regulatory impact assessments on addressable audience scale. Forecast inputs incorporated clean-room infrastructure adoption curves, retail media network competitive dynamics, and cross-state privacy compliance cost escalation.
Caveats apply where Federal Trade Commission enforcement intensity, state-level privacy statute fragmentation, or mobile operating system identifier deprecation timelines could materially shift the outlook. Forecasts reflect assumptions about authentication-based identity resolution adoption rates and retail media network competitive positioning. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Global Contextual Advertising Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
India OOH and DOOH Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Billboard and Outdoor Advertising Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Global Programmatic Advertising Platform Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Advertisement Management Solutions Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Kids Digital Advertising Market
Advertising and Marketing Media
Digital OOH Advertising Market
Advertising and Marketing Media
United States OOH and DOOH Market
Advertising and Marketing Media
Multiscreen Advertising Market