
 Global Contextual Advertising Market | 2026-2036
Global Contextual Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Global Contextual Advertising Market Foresight
The EU AI Act is decoupling automated ad placement from opaque behavioral profiling across European campaigns. Google LLC leverages its search index dominance to sustain keyword-targeting revenue streams. Amazon.com Inc. anchors retail media budgets through first-party purchase data. Microsoft Corporation competes on enterprise cloud integration for programmatic contextual workflows.
Contextual advertising matches promotional content to the surrounding editorial environment using natural language processing, sentiment scoring, and real-time page classification rather than user identity graphs. Its primary commercial purpose is delivering relevance without relying on personal data trails that regulators now restrict. Native ads and video ads command the strongest brand safety premiums as advertisers flee unpredictable user-generated environments. Semantic targeting is displacing keyword matching as the fastest-growing targeting technique because it captures intent beyond literal term frequency.
The Federal Trade Commission, the European Data Protection Board, and China's SAMR each enforce distinct consent and transparency standards that fragment platform compliance architectures. The EU Green Deal's digital sustainability reporting through CSRD now extends to ad tech carbon footprints, reshaping infrastructure procurement for delivery networks. Stakeholders must monitor how the WTO's emerging digital trade rules intersect with national data localization mandates before committing to cross-border platform investments.
Market Dynamics
Privacy regulations are systematically dismantling behavioral tracking infrastructure, forcing advertisers to rebuild targeting systems around content signals rather than user identity graphs. This structural pivot elevates contextual intelligence from tactical option to core operational necessity.
Growth Catalysts
- GDPR enforcement:The European Data Protection Board's consent requirements have collapsed third-party cookie viability, redirecting programmatic budgets toward page-level semantic analysis.
- E-commerce expansion:Retail media networks on Amazon and Walmart properties are normalizing first-party contextual placements at point-of-purchase decision moments.
- Natural language processing:Transformer architectures now classify page sentiment and intent in under 50 milliseconds, enabling real-time ad matching without latency penalties.
Market Restraints
- Compute cost volatility:Real-time semantic analysis requires GPU-intensive inference, exposing margins to cloud provider pricing power concentrated in AWS, Azure, and Google Cloud.
- Inventory quality fragmentation:Premium publisher supply concentrates among legacy newspaper groups and broadcasters, constraining scalable brand-safe placement volume.
- Technical limitation:Current NLP models struggle with multilingual nuance across Arabic, Hindi, and Southeast Asian languages, limiting addressable inventory in high-growth markets.
Strategic Opportunities
- Connected TV expansion:Programmatic video placements on Roku, Samsung, and LG interfaces remain underpenetrated for contextual targeting relative to mobile and desktop.
- EU AI Act compliance services:Automated transparency documentation for ad placement algorithms represents an emerging revenue layer for ad tech intermediaries.
- Gaming environment integration:In-game audio and visual contextual signals on Unity and Unreal Engine platforms offer unmapped inventory for endemic brand categories.
Industry Challenges
- Computational linguistics talent scarcity:The intersection of advertising operations and transformer model fine-tuning requires skill sets concentrated among Silicon Valley and London specialists.
- Legacy DSP integration friction:Demand-side platforms built for cookie-based audience buying require architectural overhaul to ingest page-level contextual taxonomies.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Contextual Advertising Market |
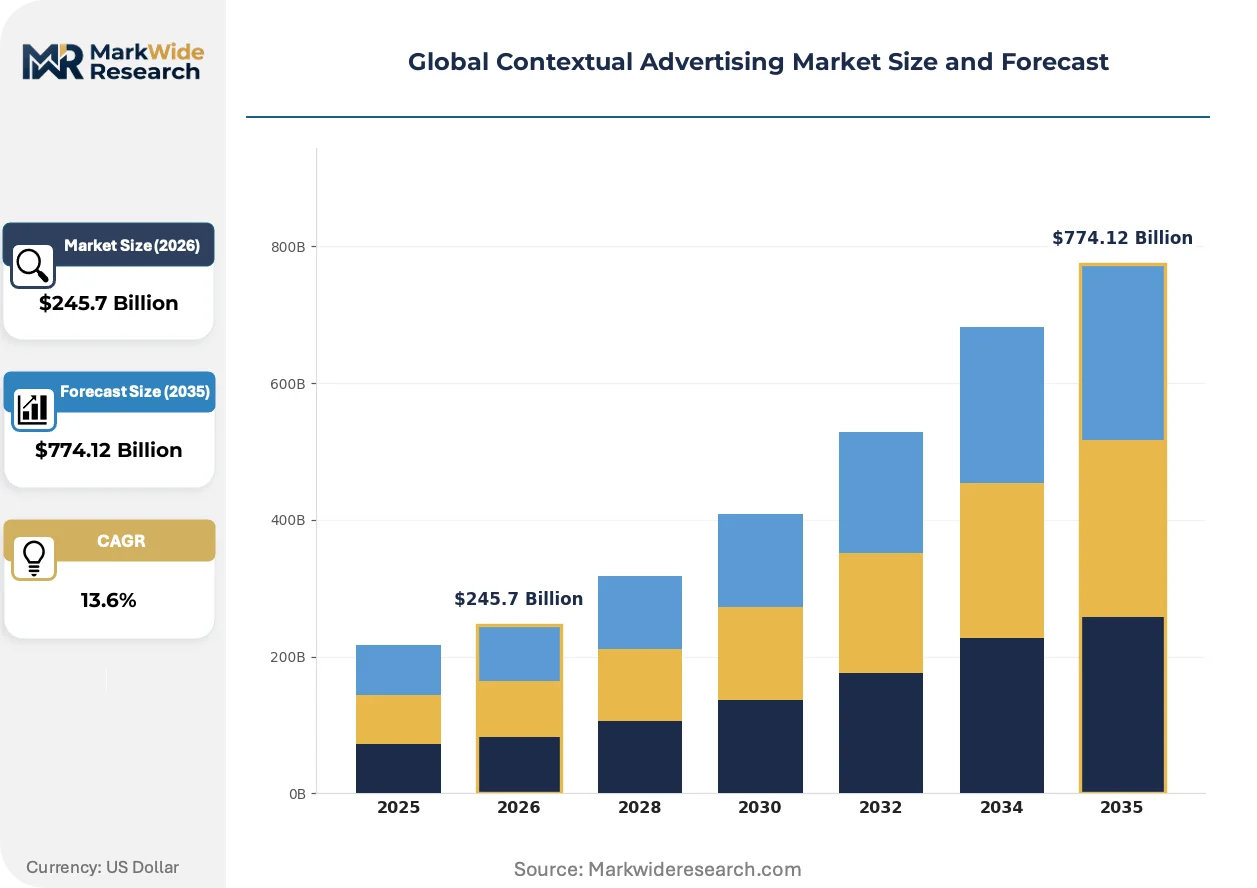
| Market Size in 2026 | $245.7 Billion |
| Market Size in 2035 | $774.12 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Ad Format: Display Ads, Video Ads, Native Ads, In-App Ads, Audio Ads Targeting Technique: Keyword Targeting, Topic Targeting, Semantic Targeting, Behavioral Contextual, Sentiment Analysis Application: Brand Awareness, Lead Generation, E-Commerce Promotion, Content Marketing, Customer Engagement End User: Advertisers, Publishers, Digital Agencies, Content Creators, Marketing Firms |
| Companies Covered | Google LLC, Facebook Inc., Amazon.com Inc., Microsoft Corporation, Adobe Inc., Taboola, Outbrain Inc., Media.net, Oracle Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Contextual Advertising Market Shifts & Advancements
Generative AI is compressing creative production cycles while multimodal models expand contextual understanding beyond text into image and video environments. These capabilities are redefining what "relevance" means in automated placement.
Multimodal foundation models are converging with ad serving infrastructure to enable real-time analysis of video frames, audio transcripts, and image composition alongside page text. Streaming platforms and connected TV publishers are adopting these systems to unlock contextual video inventory previously sold on demographic proxies. The technology is converging with existing programmatic pipes to collapse the gap between content analysis and bid decisioning from seconds to milliseconds.
The EU AI Act's risk classification framework is mandating algorithmic transparency documentation for high-stakes ad placement decisions affecting financial services and healthcare categories. Publishers serving these verticals must now maintain audit trails linking placement logic to specific content signals. German and French regulators are already requesting this documentation in preliminary investigations, establishing precedent that will propagate across member states.
Brand safety verification is unbundling from media buying to become a standalone procurement decision with dedicated budget lines. Major advertisers in CPG and automotive verticals are now contracting directly with specialist vendors like Integral Ad Science and DoubleVerify rather than accepting bundled platform assurances. This pattern is most visible in the United States, where procurement teams have gained authority over martech vendor selection previously controlled by media planning functions.
Global Contextual Advertising Market Segmentation
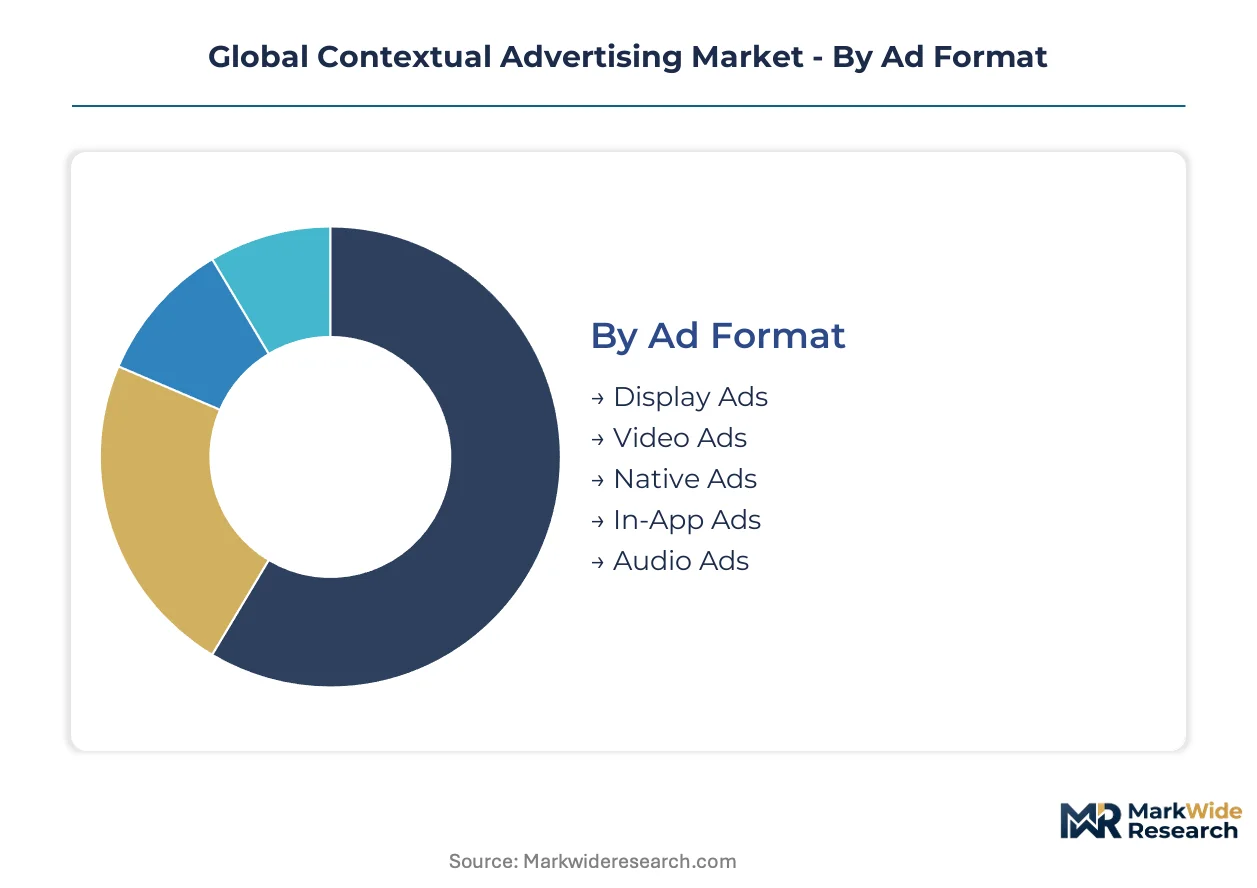
Segmentation in contextual advertising reveals how technology capabilities, buyer priorities, and regulatory constraints fragment investment patterns. Advertisers now select formats and targeting methods based on privacy compliance requirements rather than reach efficiency alone. Understanding these splits enables precise vendor positioning and budget allocation across divergent operational models.
Ad Format:
Format selection tracks the upgrade cycle from static display inventory toward immersive video and native placements that bypass ad-blocking detection.
- Display Ads:Standard banner and rich media units remain the workhorse for programmatic scale, though demand is plateauing as advertisers migrate budget toward less intrusive formats. Publishers in Germany and the United States still derive majority revenue from display, but brand safety premiums are compressing as inventory commoditizes.
- Video Ads:Pre-roll, mid-roll, and connected TV placements command the highest CPMs due to completion-rate advantages and brand recall metrics. Streaming platforms on Roku and Samsung interfaces are driving expansion as advertisers abandon linear television for addressable digital alternatives.
- Native Ads:In-feed sponsored content matches editorial styling to reduce banner blindness and ad-blocker interception. Demand concentrates among content marketing teams seeking engagement metrics over impression volume.
- In-App Ads:Mobile SDK-integrated placements leverage first-party device signals where cookie deprecation has minimal impact. Gaming and utility app publishers in China monetize through rewarded video and interstitial formats.
- Audio Ads:Podcast and streaming music placements use transcript analysis for contextual matching without visual inventory. Spotify and Pandora infrastructure enables real-time insertion based on episode topic classification.
Volume placements concentrate in Display Ads; the faster expansion belongs to Video Ads.
Targeting Technique:
Technique adoption follows cost-tier logic, with premium semantic and sentiment capabilities displacing legacy keyword matching as NLP infrastructure costs decline.
- Keyword Targeting:Legacy exact-match and broad-match bidding on page term frequency remains prevalent among small advertisers with limited technical resources. Google's search index dominance sustains this approach for bottom-funnel conversion campaigns.
- Topic Targeting:Pre-defined content category classification enables scalable placement without custom model training. Mid-market advertisers in the United States deploy this for brand safety filtering at lower computational cost than semantic alternatives.
- Semantic Targeting:Transformer-based models interpret latent intent and conceptual relationships beyond literal term matching. Enterprise advertisers in France and Germany are prioritizing this capability for EU AI Act compliance documentation.
- Behavioral Contextual:Hybrid approaches combine content signals with anonymized cohort data from privacy-preserving APIs. This bridges legacy audience targeting and pure contextual methods during the transition from third-party cookies.
- Sentiment Analysis:Real-time emotional tone scoring prevents placement adjacent to negative news or crisis content. Financial services advertisers in the United Kingdom mandate this for reputation risk management.
Budget share clusters in Keyword Targeting; the steepest expansion trajectory belongs to Semantic Targeting.
Application:
Application segmentation reflects customer-type divergence between performance marketers optimizing immediate conversions and brand teams building long-term equity.
- Brand Awareness:Reach-maximizing campaigns prioritize viewability and brand safety over direct response metrics. Automotive and CPG verticals in the United States allocate dedicated procurement budgets to verification vendors.
- Lead Generation:Form-fill and call-to-action placements demand precise contextual alignment to capture intent signals. B2B technology advertisers deploy semantic targeting on trade publication inventory.
- E-Commerce Promotion:Point-of-purchase placements on Amazon and Walmart retail media networks convert first-party purchase data into contextual relevance. This application is displacing traditional prospecting budgets.
- Content Marketing:Sponsored editorial and native distribution builds authority through association with premium publisher environments. Professional services firms in Germany favor this for thought leadership objectives.
- Customer Engagement:Retention-focused placements use contextual signals to maintain relevance without personal data dependency. Subscription services deploy this for churn reduction campaigns.
Spend concentrates in Brand Awareness; E-Commerce Promotion is climbing the fastest.
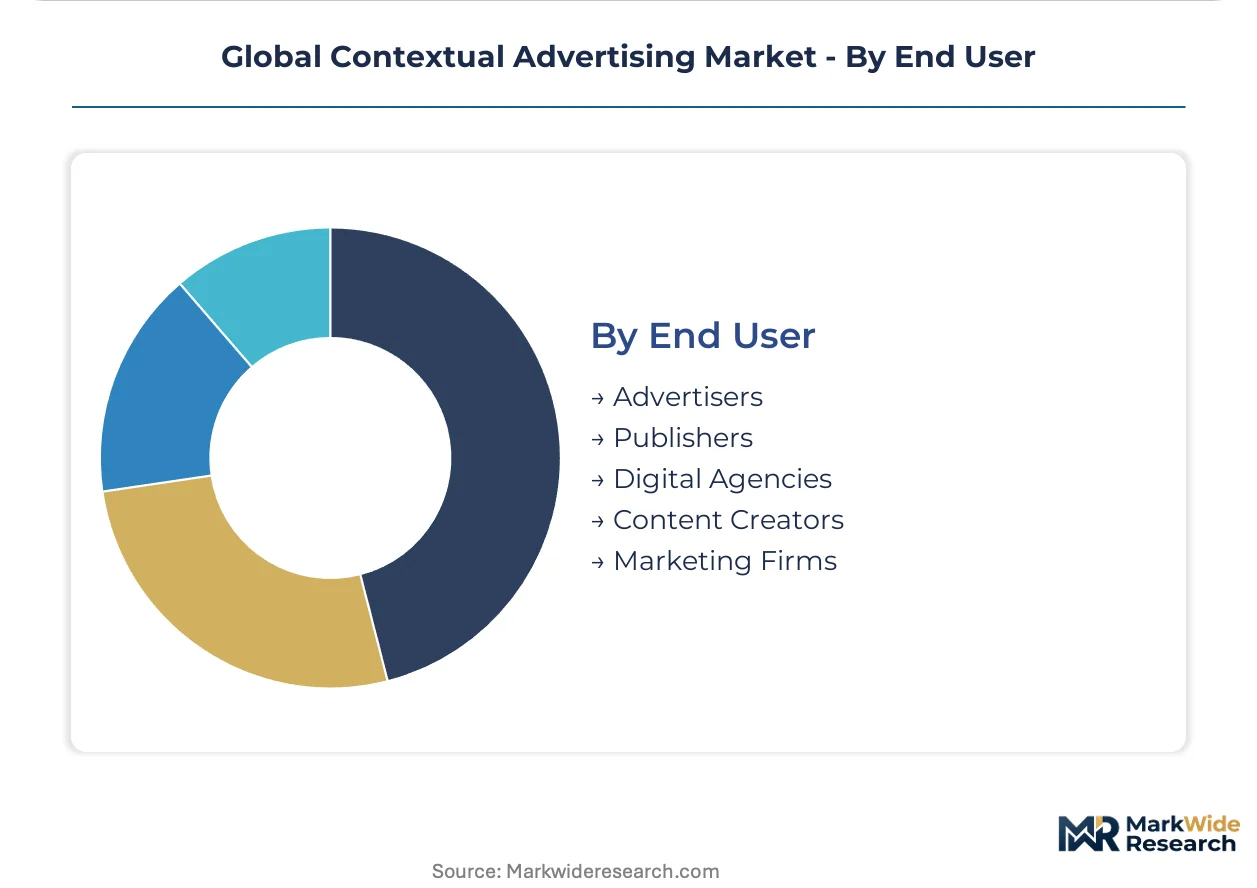
End User:
End-user structure maps to supply chain maturity, with self-service platforms displacing agency intermediaries for standardized campaign types.
- Advertisers:Direct brand teams are bringing contextual planning in-house through self-serve DSP interfaces. This shift accelerates as procurement gains vendor selection authority previously held by media agencies.
- Publishers:Inventory owners are deploying first-party data and contextual tools to compete with platform intermediaries. Newspaper groups in the United Kingdom and Germany are building direct-sold contextual packages.
- Digital Agencies:Full-service and programmatic specialists manage complex multi-channel campaigns for mid-market clients. Their value proposition is migrating from media buying to creative and measurement services.
- Content Creators:Individual influencers and niche publishers use automated contextual matching to monetize without dedicated sales teams. YouTube and Substack infrastructure enables this segment.
- Marketing Firms:Consultancies and brand strategy advisors are integrating contextual capabilities into broader transformation engagements. This segment captures enterprise clients seeking organizational change beyond campaign execution.
Revenue concentrates among Digital Agencies; Content Creators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Silicon Valley's concentration of ad tech engineering talent anchors North American contextual advertising development, while regulatory divergence across Washington, Brussels, and Beijing fragments platform compliance architectures.
United States
Retail media networks on Amazon and Walmart properties drive first-party contextual adoption at point-of-purchase moments. The FTC enforces consent and transparency standards that reshape programmatic infrastructure procurement. New York and Los Angeles media clusters concentrate brand safety verification vendor relationships for CPG and automotive verticals.
Germany
Automotive and industrial advertisers prioritize EU AI Act compliance documentation for algorithmic transparency. The country's Federal Cartel Office scrutinizes platform dominance in ad tech intermediation. Berlin and Munich house publishing groups building direct-sold contextual packages to compete with platform intermediaries.
China
E-commerce platforms normalize contextual placements through first-party device signals where cookie deprecation has minimal impact. SAMR enforces data localization mandates that constrain cross-border platform investments. Beijing and Shenzhen clusters concentrate gaming and utility app publishers monetizing through rewarded video formats.
United Kingdom
Financial services advertisers mandate sentiment analysis for reputation risk management in programmatic buying. The Information Commissioner's Office enforces GDPR consent requirements that collapsed third-party cookie viability. London's newspaper groups deploy first-party data and contextual tools to rebuild direct advertiser relationships.
France
Enterprise advertisers prioritize semantic targeting capabilities for EU AI Act compliance in high-stakes placement decisions. The CNIL requests algorithmic transparency documentation in preliminary investigations, establishing precedent across member states. Paris-based luxury brands anchor brand safety premium budgets for native ad placements.
Global Contextual Advertising Market Competitive Landscape
The competitive structure tilts toward platform-scale intermediaries with search index or retail media dominance. Concentration persists among technology conglomerates with proprietary data assets, while specialist verification vendors unbundle from media buying. Three archetypes dominate: search-index platforms leveraging keyword infrastructure, retail media networks monetizing first-party purchase data, and independent ad tech intermediaries offering transparency services. M&A activity concentrates on NLP capability acquisition and brand safety verification assets.
Within the platform-scale tier, Google LLC and Amazon.com Inc. anchor opposing revenue models—search-index keyword targeting versus retail media first-party data monetization. Microsoft Corporation occupies a position emphasizing enterprise cloud integration for programmatic workflows. These three exemplify how infrastructure control over data pipelines, compute resources, or commerce platforms determines competitive positioning without reliance on third-party identity graphs.
| Leading Market Players |
|---|
| Google LLC |
| Facebook Inc. |
| Amazon.com Inc. |
| Microsoft Corporation |
| Adobe Inc. |
| Taboola |
| Outbrain Inc. |
| Media.net |
| Oracle Corporation |
| Others |
Supply & Pricing Matrix
Enterprise advertisers in financial services and healthcare verticals concentrate procurement authority with dedicated brand safety budgets, anchoring value-based pricing models that tie CPMs to verification outcomes rather than impression volume alone.
Pricing Analysis
Value-based pricing anchors contextual advertising contracts to measurable brand safety outcomes and completion-rate guarantees. Pricing stratifies across premium verification tiers, mid-market semantic bundles, and economy keyword-matching tiers, with differentiation driven by NLP sophistication and audit-trail depth. Cost compression in economy tiers intensifies as small advertisers migrate to self-serve platforms. Mid-market agencies exhibit highest price sensitivity; enterprise direct buyers accept premium tiers for EU AI Act documentation.
Supply Chain Analysis
ISO 27001 and SOC 2 Type II certification gating restricts publisher onboarding to ad exchanges, filtering inventory quality before bid decisioning. GPU cloud infrastructure concentrates in the United States, Ireland, and Singapore, feeding real-time inference pipelines. Supply chain risk centers on single-source vulnerability for transformer model training data licensed from proprietary content corpora. Distribution runs through programmatic pipes linking publisher SSPs to advertiser DSPs with sub-100-millisecond latency requirements.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race where control over first-party data pipelines and NLP training corpora determines margin capture. Downstream ownership of advertiser relationships through self-serve platforms represents the decisive lever.
For Market Incumbents: Anchor defensive positioning through exclusive publisher data partnerships and in-house transformer fine-tuning capabilities. Threat from privacy-preserving cohort APIs demands accelerated first-party graph construction. Certification investment in EU AI Act transparency tooling preserves enterprise account access. For New Entrants and Emerging Players: The EU AI Act in Germany and France opens a window for compliance-native ad tech stacks unburdened by legacy cookie infrastructure. Gaming environment integration on Unity and Unreal Engine platforms offers the most penetrable inventory segment. Go-to-market through direct publisher relationships bypasses platform intermediary concentration. For Investors and Strategic Acquirers: The window for entry favors NLP specialist acquisitions with multilingual model capabilities and established publisher integrations. Long-term viability hinges on amortizing training costs across expanding addressable inventory. Signal to watch: regulatory enforcement velocity on algorithmic transparency documentation requests from the CNIL and European Data Protection Board.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Pipeline Acquisition | Secures deterministic targeting signals as third-party cookies deprecate across Chrome and Safari browsers. |
| Multilingual NLP Model Development | Unlocks inventory in Arabic, Hindi, and Southeast Asian markets where current models underperform. |
| EU AI Act Compliance Service Launch | Captures enterprise budgets mandating algorithmic audit trails for financial services and healthcare placements. |
| Connected TV Integration Partnership | Extends contextual targeting to Roku and Samsung interfaces where video CPMs command strongest premiums. |
| Brand Safety Verification Unbundling | Establishes standalone procurement relationships with CPG and automotive advertisers in the United States. |
Research Methodology
Document review covered SEC 10-K filings from ad tech platforms, EU regulatory submissions to the European Data Protection Board, and hyperscaler capex disclosures, complemented by interviews with programmatic trading desk directors, publisher ad operations leads, brand safety verification engineers, and retail media network strategists. Secondary sources included IAB programmatic spend surveys, GDPR enforcement case databases, and cloud provider infrastructure expansion announcements. Bottom-up publisher revenue estimates were triangulated against top-down advertiser budget allocation data.
Output projections across the analysis window reflect modeled segmentation by ad format, targeting technique, application objective, and end-user type, with additional dimensioning by regional regulatory cluster and inventory quality tier. CAGRs were derived from trend extrapolation of privacy regulation enforcement velocity and NLP infrastructure cost decline curves. Key inputs included GPU cloud pricing trajectories from AWS, Azure, and Google Cloud, plus publisher adoption rates for semantic classification tools.
The model assumes a particular technology adoption path where transformer architectures displace keyword matching; alternative pathways for lightweight on-device inference would alter the outlook. Forecasts reflect assumptions on regulatory harmonization timelines and cloud provider pricing power persistence. A model refresh is warranted upon material change in EU AI Act enforcement precedent or breakthrough multilingual model releases.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
United Kingdom Marketing Agencies Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market
Advertising and Marketing Media
Digital Out of Home (OOH) Advertising Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
United States Marketing Agencies Market
Advertising and Marketing Media
Europe OOH and DOOH Market
Advertising and Marketing Media
Social Video Advertising Market
Advertising and Marketing Media
Global Programmatic Advertisement Market