
 Thailand OOH and DOOH Market | 2026-2036
Thailand OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
Thailand OOH and DOOH Market Insights
Thailand's NBTC digital broadcasting and spectrum allocation mandates is expanding the addressable infrastructure for connected out-of-home displays across metropolitan transit corridors. VGI PCL leverages its exclusive concession agreements with Bangkok Mass Transit System to dominate platform and train-wrap inventory. Plan B Media PCL sustains nationwide coverage through retail mall and airport digital networks that anchor premium brand budgets. JCDecaux Thailand Ltd. competes on street furniture concessions in central Bangkok, where municipal advertising rights control scarce roadside visibility.
Out-of-home and digital out-of-home advertising encompasses physical and electronically displayed promotional content deployed in public spaces, transit systems, and commercial venues, typically using LED panels with brightness ratings of 5,000-10,000 nits for daylight visibility and content management systems enabling real-time playlist updates. Its primary commercial purpose is to capture consumer attention during non-discretionary dwell periods such as commuting, queuing, or pedestrian movement. Digital displays within the media type dimension lead revenue contribution due to programmatic trading capability and dynamic creative optimization, while static billboards retain volume share in provincial markets where capital replacement cycles lag. The deployment model dimension shows hybrid installations—combining static structural frames with interchangeable digital faces—growing fastest as operators balance yield improvement against infrastructure write-down schedules.
Thailand's Office of the National Broadcasting and Telecommunications Commission governs spectrum use for connected digital signage, while the Bangkok Metropolitan Administration controls outdoor advertising permits through zoning ordinances that restrict placement near historical monuments and government buildings. The Department of Land Transport regulates transit advertising dimensions and safety clearance on buses and vans operating interprovincial routes. Stakeholders must monitor how municipal decentralization of advertising permit authority to provincial administrations reshapes market access costs outside Bangkok.
Market Dynamics
The Bangkok Metropolitan Administration's zoning ordinances restricting roadside advertising near historical monuments is compressing available inventory, forcing operators toward transit corridors and retail mall networks where concession rights command premium valuations.
Growth Catalysts
- NBTC spectrum licensing:Thailand's National Broadcasting and Telecommunications Commission digital broadcasting mandates accelerate connected display deployment across metropolitan transit infrastructure.
- BTS-MRT corridor density:Commuter concentration along Bangkok's elevated and underground rail systems validates premium placement rates for platform and train-wrap inventory.
- Programmatic trading platforms:Real-time bidding systems enable dynamic creative optimization and yield management for digital screen networks.
Market Restraints
- LED panel import dependency:Display component sourcing concentrates through East Asian manufacturing hubs, exposing operators to shipping cost volatility and currency fluctuation.
- Municipal permit fragmentation:Decentralization of advertising authority to provincial administrations outside Bangkok multiplies compliance costs and approval timelines.
- Static billboard replacement cycles:Provincial markets lag capital conversion to digital faces, constraining addressable inventory expansion in secondary cities.
Strategic Opportunities
- Chiang Mai-Mae Kha canal corridor:Northern Thailand's tourism and university districts remain underpenetrated for transit-connected digital networks.
- Hybrid installation models:Structural frames with interchangeable digital faces balance yield improvement against infrastructure write-down schedules.
- Airport concession expansion:Suvarnabhumi and Don Mueang international terminals offer captive dwell-time audiences for premium brand budgets.
Industry Challenges
- Content management system integration:Legacy static billboard operators face technical complexity migrating to real-time playlist update capabilities.
- Brightness calibration expertise:Daylight visibility requirements of 5,000-10,000 nits demand specialized technician training scarce in provincial labor markets.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Thailand OOH and DOOH Market |
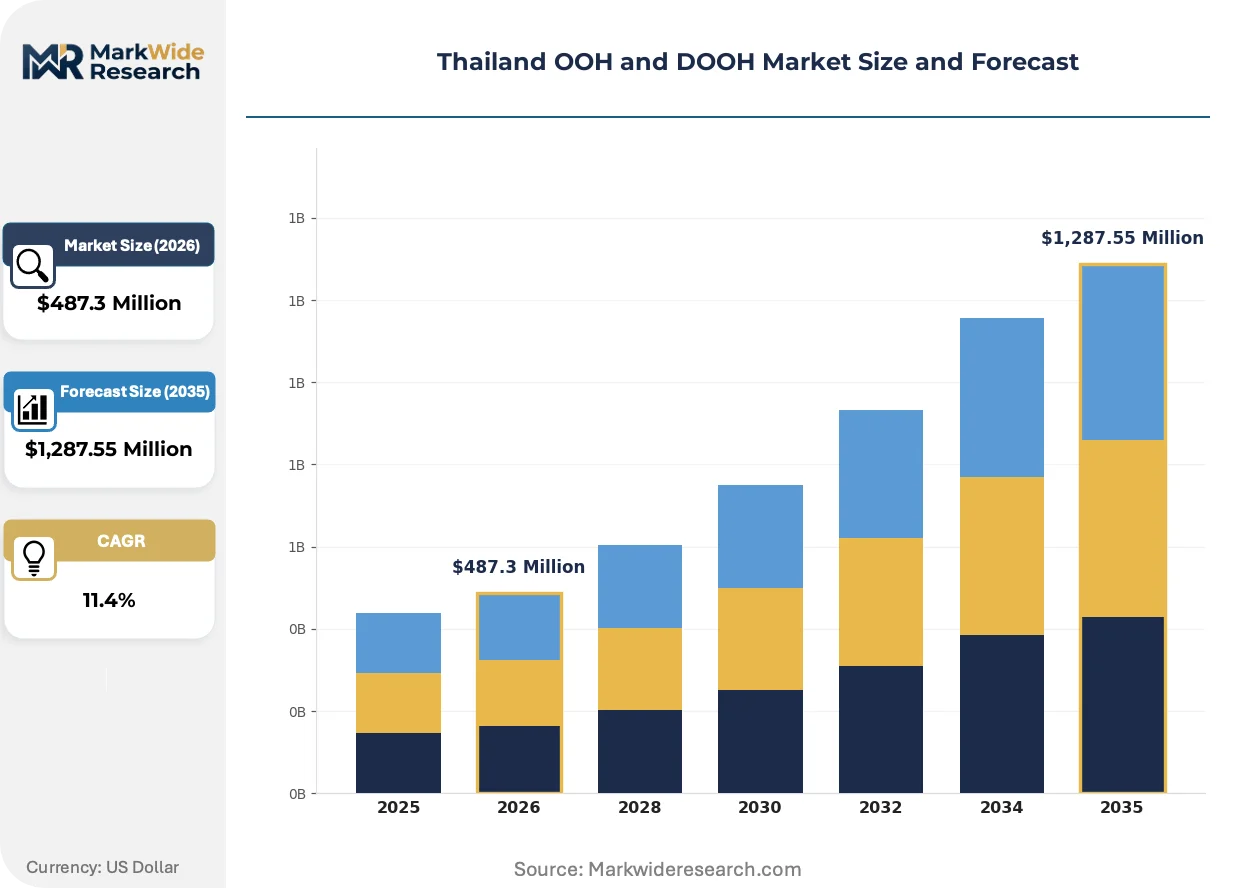
| Market Size in 2026 | $487.3 Million |
| Market Size in 2035 | $1,287.55 Million |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Transit Advertising, Street Furniture, Digital Displays Deployment Model: Static, Digital, Hybrid, Interactive End User: Retailers, FMCG Brands, Automotive, Entertainment Content Type: Video, Static Images, Promotions, User-Generated Content |
| Companies Covered | VGI PCL, Plan B Media PCL, JCDecaux Thailand Ltd., Clear Channel Outdoor Thailand, Hivestack Inc., Vistar Media, Rocktech Global PCL, AsiaPac Net Media Ltd., AJ Marketing Pte Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Thailand OOH and DOOH Market Trends and Innovations
Content management systems with real-time playlist capabilities are restructuring how inventory is monetized, while regulatory pressure on roadside visibility concentrates investment toward transit and retail environments.
Programmatic trading platforms for out-of-home inventory are consolidating media buying workflows previously fragmented across static and digital formats. Brand advertisers in FMCG and automotive verticals are adopting these systems at accelerating pace. This consolidation is compressing the role of traditional media buyers and enabling direct publisher-to-brand transactions.
Thailand's NBTC spectrum allocation framework for digital signage connectivity is mandating technical standards for connected displays. The industrial consequence is accelerated infrastructure deployment with interoperability requirements. Transit corridor operators in Bangkok are responding by upgrading network backhaul to meet licensing conditions.
Buyer concentration among multinational FMCG and automotive brands is shifting contract structures toward guaranteed audience impression models. Media agencies are losing ground to direct platform relationships. This pattern is most visible in Bangkok's central business district where VGI PCL and Plan B Media PCL operate competing digital networks.
Thailand OOH and DOOH Market Segmentation
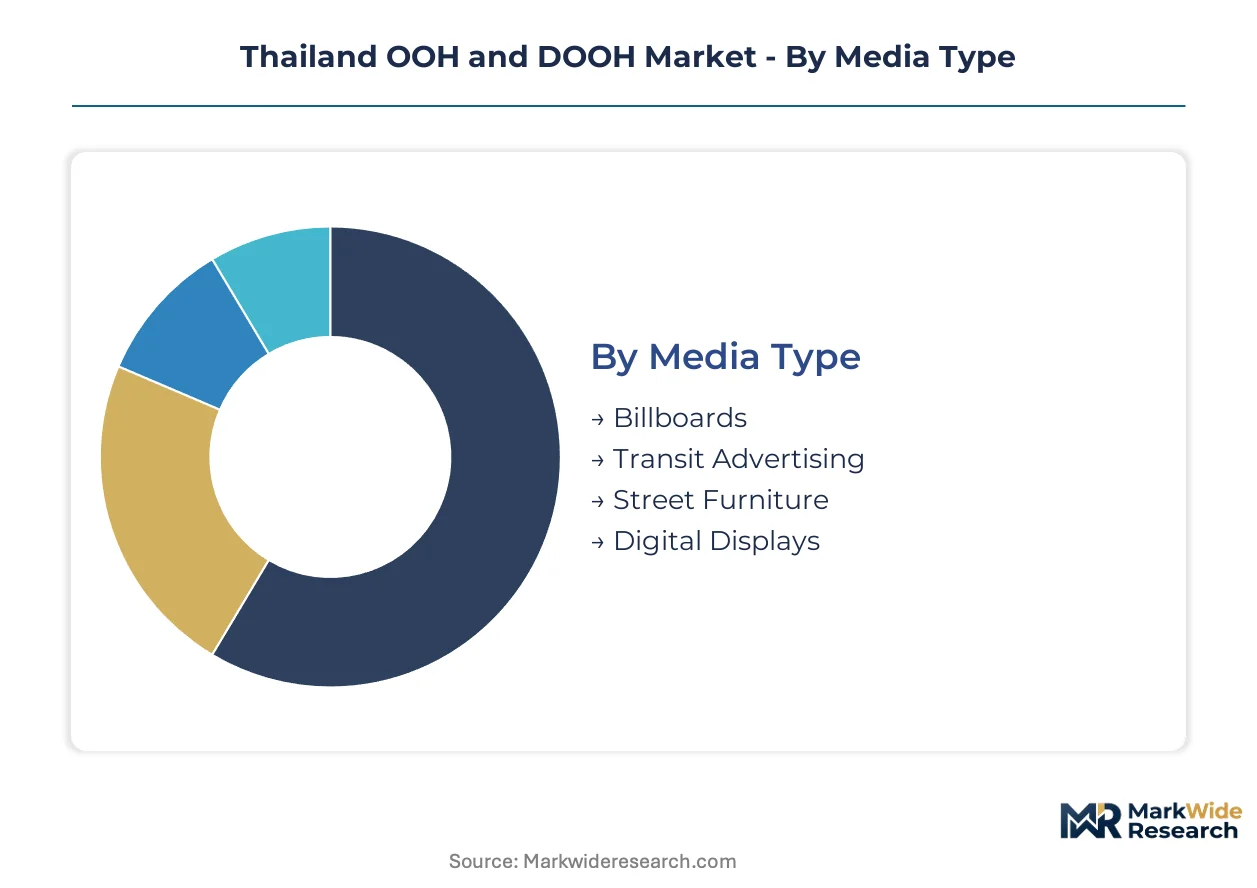
Thailand's OOH and DOOH market segments reflect infrastructure maturity gaps between Bangkok's transit corridors and provincial markets. Deployment models and media types diverge sharply based on NBTC spectrum access, municipal permit density, and capital replacement cycles.
Media Type:
Volume concentration sits with traditional formats in secondary cities. Premium yield is concentrating in connected digital networks along commuter corridors.
- Billboards:Large-format static structures dominate provincial highways and peri-urban zones where permit costs remain low. Thailand's Department of Land Transport regulates dimension and safety clearance on interprovincial routes, constraining inventory expansion outside municipal boundaries.
- Transit Advertising:Platform displays, train wraps, and station dominations command the highest placement rates. BTS Skytrain and MRT subway corridors absorb the majority of new digital screen deployment as commuter density validates premium pricing.
- Street Furniture:Bus shelters, kiosks, and benches in central Bangkok face zoning restrictions near historical monuments. Bangkok Metropolitan Administration ordinances compress available roadside inventory, forcing operators toward concession-based municipal contracts.
- Digital Displays:LED panels with 5,000-10,000 nits brightness ratings enable daylight visibility. NBTC spectrum licensing mandates are accelerating connected display deployment across metropolitan transit infrastructure.
Mature deployment sits with billboards. Newer deployment is concentrated in digital displays.
Deployment Model:
Capital intensity separates segments. Static formats require minimal technical infrastructure. Digital and interactive models demand continuous connectivity investment.
- Static:Printed vinyl and painted surfaces retain volume share in provincial markets where capital replacement cycles lag. These installations carry lower upfront costs but lack dynamic creative optimization and real-time yield management.
- Digital:Network-connected LED and LCD screens enable programmatic trading and playlist automation. Content management systems with real-time update capabilities are restructuring inventory monetization in Bangkok's retail mall and airport terminals.
- Hybrid:Structural frames with interchangeable digital faces balance yield improvement against infrastructure write-down schedules. This model allows operators to convert premium static locations without full site redevelopment.
- Interactive:Touch-enabled screens and motion-sensor displays integrate user engagement metrics. Deployment concentrates in high-dwell environments such as Suvarnabhumi and Don Mueang international terminals where captive audiences justify technical complexity.
Volume leadership belongs to static installations. Steepest expansion trajectory is climbing in hybrid models.
End User:
Buyer concentration patterns reflect brand budget allocation between awareness and activation objectives.
- Retailers:Department stores and mall operators deploy in-house digital networks for tenant advertising and wayfinding. Siam Paragon and CentralWorld anchor premium inventory demand in Bangkok's retail corridor.
- FMCG Brands:Multinational consumer goods companies are shifting contract structures toward guaranteed audience impression models. Direct platform relationships are displacing traditional media agency intermediation.
- Automotive:Vehicle manufacturers concentrate spending on high-visibility transit corridors and airport terminals. Premium brand budgets validate placement rates in BTS-MRT network dominations.
- Entertainment:Film studios and streaming platforms exploit short-flight campaigns with rapid creative turnaround. Digital screen networks enable day-part targeting for opening weekend promotions.
Established demand flows from FMCG brands. Entertainment verticals are gaining share fastest.
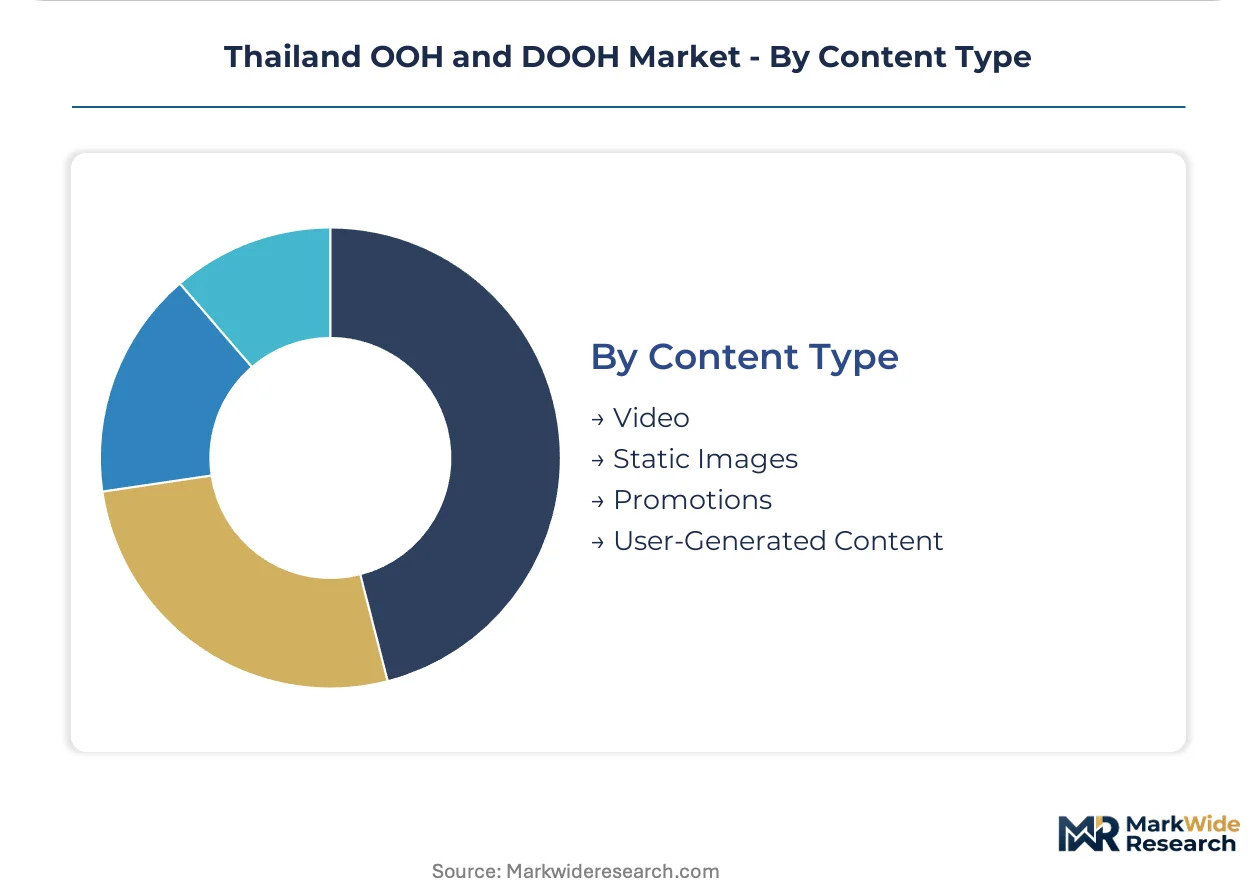
Content Type:
Production cost and technical capability requirements segment content strategies.
- Video:Motion creative with 15-30 second loops dominates digital screen networks. File compression and bandwidth optimization are critical for real-time playlist distribution across NBTC-licensed connectivity infrastructure.
- Static Images:High-resolution JPEG and PNG formats persist in hybrid installations and legacy digital displays. Lower data throughput requirements suit provincial markets with constrained network backhaul.
- Promotions:Time-sensitive offers and location-triggered discounts integrate with retail loyalty programs. QR code and NFC-enabled activation bridges physical exposure to digital conversion.
- User-Generated Content:Social media aggregation and audience-submitted creative drive engagement in interactive installations. Moderation workflows and brand safety protocols add operational complexity.
Volume concentration remains with static images. Video content is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Bangkok's transit corridors dominate Thailand's out-of-home advertising infrastructure, with the BTS Skytrain and MRT subway networks absorbing the majority of digital screen deployment. Provincial markets lag in connected display penetration due to fragmented municipal permitting and slower capital replacement cycles. The analysis examines five sub-regions where infrastructure maturity and regulatory frameworks diverge sharply.
Greater Bangkok Metropolitan Area
Commuter density along elevated and underground rail corridors validates premium placement rates for platform displays and train-wrap inventory. The Bangkok Metropolitan Administration enforces zoning ordinances that restrict roadside advertising near historical monuments, compressing available inventory toward concession-based transit networks. Siam Paragon and CentralWorld anchor retail mall digital networks that command the highest brand budgets in the country.
Central Thailand
Provincial highway billboards retain volume share in peri-urban zones surrounding Bangkok where permit costs remain low. The Department of Land Transport regulates dimension and safety clearance on interprovincial routes, constraining inventory expansion outside municipal boundaries. Ayutthaya and Nakhon Pathom corridors see static format dominance where capital replacement to digital faces has stalled.
Northern Thailand
Chiang Mai's tourism and university districts remain underpenetrated for transit-connected digital networks despite rising visitor volumes. Provincial administration decentralization multiplies compliance costs and approval timelines outside the capital. The Mae Kha canal corridor presents untapped potential for hospitality-targeted screen deployment.
Eastern Thailand
Industrial zones around Chonburi and Rayong attract automotive and manufacturing brand spending on highway-facing static structures. The Eastern Economic Corridor development framework is accelerating infrastructure investment, though digital signage connectivity lags behind transport logistics priorities. Pattaya's entertainment district sustains demand for short-flight promotional campaigns.
Southern Thailand
Phuket and Krabi tourism corridors support seasonal surges in entertainment and hospitality advertising. Island geography limits transit network density, concentrating inventory in airport terminals and resort retail environments. The Tourism Authority of Thailand's destination marketing programs indirectly subsidize premium placement rates during peak visitor months.
Thailand OOH and DOOH Market Competitive Landscape
Premium-margin players sit above commodity-margin players across concession exclusivity and connectivity infrastructure quality. The market structures around exclusive transit agreements versus open municipal permit systems, creating divergent yield profiles. Three archetypes dominate: concession-holding transit specialists, retail mall network operators, and street furniture concessionaires competing for scarce roadside visibility. Consolidation pressure is mounting through exclusive concession renewals and spectrum licensing advantages, while technology partnerships with programmatic platforms reshape trading workflows.
Among Thailand-based operators, VGI PCL and Plan B Media PCL occupy positions anchoring the premium tier through exclusive infrastructure control. JCDecaux Thailand Ltd. represents the multinational street furniture archetype competing on municipal concession relationships. These three entities exemplify how concession duration and transit corridor density separate market tiers.
| Leading Market Players |
|---|
| VGI PCL |
| Plan B Media PCL |
| JCDecaux Thailand Ltd. |
| Clear Channel Outdoor Thailand |
| Hivestack Inc. |
| Vistar Media |
| Rocktech Global PCL |
| AsiaPac Net Media Ltd. |
| AJ Marketing Pte Ltd. |
| Others |
Pricing and Supply Chain Analysis
Exclusive concession tenure for BTS-MRT corridor inventory separates premium-yield operators from commodity-margin roadside competitors, with transit density commanding placement rates that static provincial billboards cannot approach while LED panel import costs and spectrum licensing fees concentrate capital deployment in Bangkok's metropolitan core.
Pricing Analysis
Value-based pricing anchored to guaranteed audience impression volumes dominates contract structures between network operators and multinational FMCG and automotive brands. Three-tier pricing structure across premium transit dominations, standard retail mall networks, and economy-grade provincial billboards reflects concession exclusivity and connectivity infrastructure quality. Pricing pressure stems from municipal permit fragmentation outside Bangkok multiplying compliance costs. Price-sensitive buyers cluster among provincial static billboard advertisers, while premium brand budgets show low sensitivity to transit corridor rate premiums.
Supply Chain Analysis
Logistics and freight costs for LED panel imports from China, South Korea, and Taiwan expose operators to shipping volatility and currency fluctuation against the Thai baht. Display component sourcing concentrates through East Asian manufacturing hubs, with SMD LED chips, driver ICs, and power supplies forming critical dependencies. Single-source vulnerability in advanced panel technology creates supply chain risk. Distribution runs through Bangkok-based systems integrators serving metropolitan operators, while provincial markets rely on fragmented local installation contractors with limited technical capability.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarce concession rights along Bangkok's transit corridors constrain inventory expansion, with exclusive BTS-MRT agreements propping premium placement rates that validate capital-intensive digital deployment.
For Market Incumbents: To counter programmatic trading platforms displacing traditional media agency intermediation, operators should deepen direct brand relationships through guaranteed impression models and invest in real-time content management system capabilities that match dynamic creative optimization demand from FMCG buyers. For New Entrants and Emerging Players: NBTC spectrum licensing in Thailand opens a window for connectivity infrastructure plays in underpenetrated northern corridors, specifically targeting Chiang Mai-Mae Kha canal hospitality networks and university district transit adjacencies with hybrid installation models that balance yield improvement against capital constraints. For Investors and Strategic Acquirers: Re-rating potential sits with concession-holding transit specialists given exclusive BTS-MRT agreement renewals and programmatic platform integration capabilities. Long-term viability over a 5-10 year window favors operators with spectrum-licensed connectivity infrastructure and direct brand platform relationships. Watch for municipal decentralization of advertising permit authority as an inflection signal for provincial market access costs.| Strategic Initiative | Industry Significance |
|---|---|
| Exclusive Concession Renewal | Secures BTS-MRT corridor inventory access that validates premium placement rates against roadside competitors. |
| Programmatic Platform Integration | Enables real-time bidding workflows that displace traditional media agency intermediation for FMCG brands. |
| Hybrid Installation Deployment | Balances yield improvement against infrastructure write-down schedules in premium static locations. |
| NBTC Spectrum Licensing Compliance | Accelerates connected display deployment with interoperability mandates across metropolitan transit infrastructure. |
| Direct Brand Platform Relationship | Captures guaranteed audience impression contracts that compress media buyer role in budget allocation. |
Research Methodology
Independent corroboration across primary interviews with transit network operators, retail mall asset managers, and municipal permitting officers, combined with secondary validation through NBTC spectrum allocation records, Bangkok Metropolitan Administration zoning ordinances, and Department of Land Transport safety clearance filings, underwrites the qualitative findings. Bottom-up deployment counts across BTS-MRT corridors, Suvarnabhumi and Don Mueang terminals, and provincial highway networks triangulate against top-down media spending estimates from brand budget disclosures.
Rate-of-change decomposition across the projection horizon separates volume growth from yield expansion, with segmentation dimensions spanning media type, deployment model, end-user vertical, and regional infrastructure maturity. CAGRs derive from fitted adoption curves for digital display penetration against static replacement cycles, incorporating NBTC licensing velocity, commuter density trajectories, and programmatic trading platform adoption rates as industry-specific forecast inputs.
The model assumes a particular technology adoption path; alternative pathways for hybrid installation models or interactive screen deployment would alter the outlook. Forecasts reflect assumptions about concession renewal timelines, spectrum licensing enforcement, and brand budget migration to direct platform relationships. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Native Advertising Market
Advertising and Marketing Media
Europe Public Relation Services Market
Advertising and Marketing Media
Europe Digital OOH Advertising Market
Advertising and Marketing Media
Global Music Copyright Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Singapore OOH and DOOH Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market
Advertising and Marketing Media
Australia OOH and DOOH Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Retail Media Creative Optimization Market
Advertising and Marketing Media
Qatar OOH and DOOH Market