
 United States OOH and DOOH Market | 2026-2036
United States OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
United States OOH and DOOH Market Insights
The FCC's broadband infrastructure rules and corresponding state-level clean energy mandates for digital displays is restructuring procurement criteria across municipal and commercial buyers. Clear Channel Outdoor Americas leverages its nationwide billboard portfolio to sustain inventory density in the top designated market areas. Lamar Advertising Co anchors rural and highway coverage through owned land leases and manufacturing capabilities. Outfront Media competes in transit and street furniture through exclusive agreements with major metropolitan transit authorities.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display systems deployed in public spaces for commercial messaging, including LED and LCD screens with brightness ratings exceeding 5,000 nits for daylight visibility, static vinyl and paper substrates, and networked content management platforms enabling remote scheduling. The primary commercial purpose is to capture consumer attention during transit, dwell, and shopping occasions where mobile and desktop media cannot reach. Billboards occupy the largest revenue pool within media type segmentation, while programmatic buying within engagement models is expanding fastest as advertisers demand impression-level verification and automated optimization. Place-based media in retail environments commands premium CPMs due to measurable proximity to purchase decisions.
The FCC governs spectrum allocation for wireless content delivery to digital displays, while the EPA enforces energy efficiency standards affecting LED component selection and operational compliance. State-level public utilities commissions in California, Texas, and New York impose additional standby power restrictions and e-waste recovery obligations on deployed hardware. Local zoning boards and municipal transportation authorities control permitting density, sightline restrictions, and digital brightness curfews that directly constrain inventory expansion rates. Stakeholders must monitor evolving FCC spectrum reallocation proceedings and patchwork municipal ordinances to anticipate deployment bottlenecks and capital timing decisions.
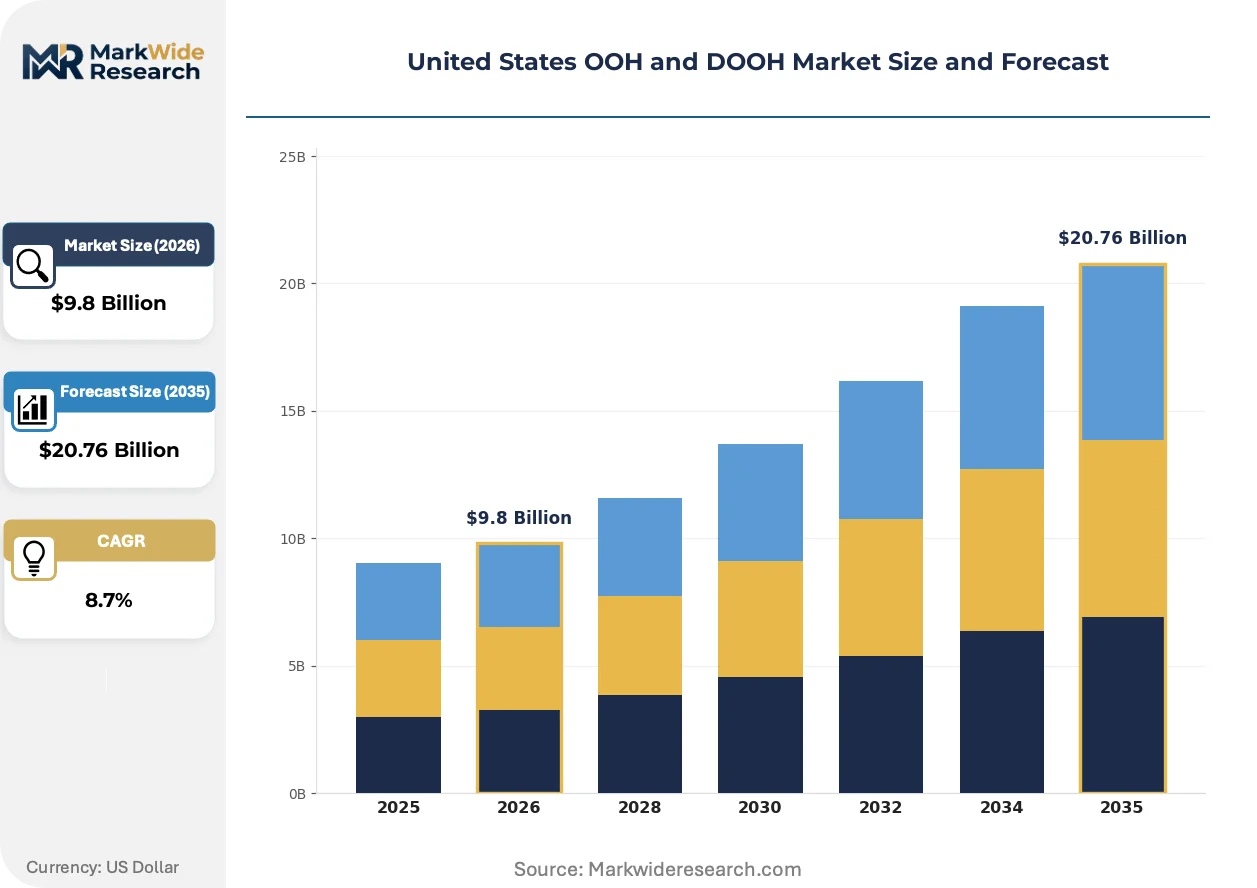
Market Dynamics
Programmatic buying platforms are compressing sales cycles and collapsing the traditional separation between media planning and real-time inventory allocation across the United States OOH and DOOH Market. This technology shift is redistributing margin from network operators to data-enabled intermediaries.
Growth Catalysts
- IRS Section 179 Deductions:Accelerated depreciation allowances for digital display capital expenditures are compressing payback periods for municipal transit authorities and commercial landlords upgrading static assets to programmable LED systems.
- Smart City Infrastructure Bundling:Texas, California, and Florida are packaging street furniture digital displays with 5G small cell deployments and EV charging stations, creating multi-revenue municipal contracts that subsidize network buildout.
- Programmatic Verification Standards:Impression-level measurement protocols developed by the MRC and OAAA are enabling performance-based media buying that pulls digital-native advertising budgets into OOH channels previously excluded from automated planning workflows.
Market Restraints
- FCC Spectrum Reallocation Uncertainty:Pending 6 GHz band proceedings threaten wireless content delivery architectures that rely on unlicensed spectrum for real-time playlist updates to roadside and transit displays.
- LED Component Supply Concentration:Dominant Asian substrate manufacturers control gallium nitride wafer supply, exposing domestic display fabricators to input cost volatility and extended lead times for high-brightness diode arrays.
- Municipal Zoning Fragmentation:Patchwork brightness curfews and sightline ordinances across 19,000+ local jurisdictions create permitting friction that constrains inventory expansion velocity in high-value urban corridors.
Strategic Opportunities
- Retail Media Network Convergence:Grocery and big-box retailers are deploying in-aisle digital screens that merge first-party transaction data with location-based creative, capturing CPG budgets that previously flowed to endemic websites.
- Rural Highway Digitization:Interstate corridors in Montana, Wyoming, and North Dakota remain substantially underpenetrated by programmable displays, offering first-mover returns on owned land leases in high-visibility locations.
- EPA Energy Star Certification Pathways:Emerging federal efficiency standards for commercial displays are creating procurement preference windows for LED manufacturers that achieve standby power thresholds below 0.5 watts per square foot.
Industry Challenges
- Creative Production Bottlenecks:Short-form video asset adaptation for 5,000+ nit daylight-visible screens requires specialized color grading and motion design capabilities that outpace current talent pipeline output in major media markets.
- Legacy CMS Integration Complexity:Transit authorities operating decades-old scheduling software face API incompatibility when attempting to merge real-time train arrival data with dynamic advertising content on platform displays.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States OOH and DOOH Market |
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $20.76 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Media Type: Billboards, Transit Advertising, Street Furniture, Place-Based Media Format: Digital Signage, Posters, Banners, Static Displays Industry Vertical: Retail, Automotive, Entertainment, Real Estate Engagement Model: Programmatic Buying, Direct Advertising, Sponsorship, Partnership |
| Companies Covered | JCDecaux Group, Clear Channel Outdoor Americas, Inc., Lamar Advertising Co, Outfront Media, Inc., Pattison Outdoor Advertising, Broadsign International LLC, Daktronics, Focus Media, oOh!media Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States OOH and DOOH Market Trends and Innovations
Data fusion between mobile location signals and impression verification is collapsing the attribution gap that historically separated OOH from digital channels. This convergence is attracting performance-marketing budgets that previously bypassed physical media entirely.
Content management platforms is unifying previously siloed creative libraries, traffic data feeds, and sales inventory systems into single-stack architectures. National retail chains and transit operators are migrating to these integrated environments within 18-24 month replacement cycles. The technology is unifying operational workflows that previously required three separate vendor relationships and manual spreadsheet reconciliation.
The FCC's digital infrastructure guidelines are mandating cybersecurity hardening for networked displays receiving over-the-air content updates. Equipment manufacturers must now embed hardware security modules and encrypted boot protocols to maintain type certification. Transit authorities in California and New York are responding by requiring SOC 2 compliance documentation from all network vendors bidding on street furniture contracts.
Advertisers are consolidating planning authority within in-house media operations that previously outsourced OOH entirely to agency trading desks. Brands with direct data science capabilities are building proprietary audience models that bypass traditional demographic proxies. This concentration is most visible among quick-service restaurant chains and direct-to-consumer retailers operating dense store networks in Texas and Florida metropolitan areas.
United States OOH and DOOH Market Segmentation
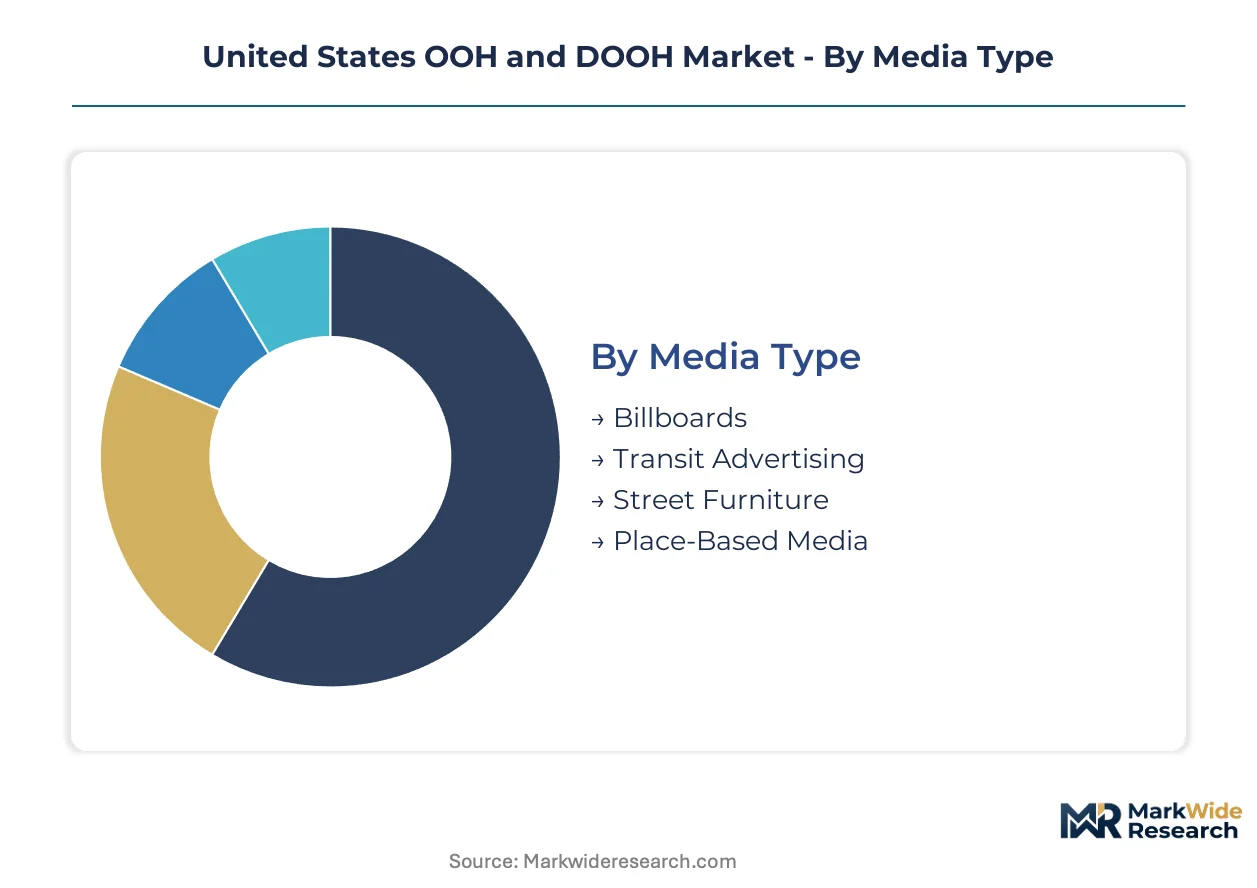
OOH and DOOH segmentation reveals how inventory characteristics, buyer sophistication, and measurement capabilities redistribute value across the advertising supply chain. Format and engagement model choices directly determine capital intensity, margin structure, and competitive defensibility for network operators.
Media Type:
Billboards dominate volume deployment while transit and place-based formats command premium pricing through captive audience dwell time.
- Billboards:Highway and arterial roadside structures using vinyl, paper, or LED substrates sized for 500-foot sightline visibility. Texas, California, and Florida municipal authorities are accelerating digital conversions through smart city infrastructure bundling with 5G small cells and EV charging stations.
- Transit Advertising:Interior and exterior placements on buses, rail cars, and station platforms with dwell-time advantages during commutes. Demand is concentrating among municipal transit authorities in dense urban corridors where IRS Section 179 deductions compress payback periods for LED upgrades.
- Street Furniture:Bus shelters, newsstands, and kiosks integrating digital displays with municipal services. FCC cybersecurity hardening requirements are reshaping procurement specifications for networked content delivery.
- Place-Based Media:Screens deployed in retail, healthcare, and entertainment venues capturing proximity-to-purchase moments. Grocery and big-box retailers are merging first-party transaction data with location-based creative to capture CPG budgets.
Mature deployment sits with Billboards. Newer deployment is concentrated in Place-Based Media.
Format:
Digital formats are displacing static substrates as programmatic verification standards enable impression-level buying, though paper and vinyl retain cost advantages in rural corridors.
- Digital Signage:LED and LCD screens exceeding 5,000 nits brightness for daylight visibility with remote content management. EPA Energy Star certification pathways below 0.5 watts per square foot standby power are creating procurement preference windows for qualifying manufacturers.
- Posters:Paper-based 30-sheet and 8-sheet displays for short-term local campaigns and test markets. Static formats persist in Montana, Wyoming, and North Dakota interstate corridors where digital penetration remains limited.
- Banners:Vinyl and fabric substrates for building wraps, construction barriers, and event overlays. Municipal zoning fragmentation across 19,000+ jurisdictions constrains expansion velocity for large-format urban placements.
- Static Displays:Non-illuminated paper and painted surfaces requiring physical replacement for creative rotation. Legacy inventory in rural highway markets offers first-mover returns on owned land leases where digitization has not yet occurred.
Static Displays anchor rural coverage. Digital Signage is climbing the fastest as advertisers demand automated optimization.
Industry Vertical:
Vertical specialization determines creative production requirements, with retail and automotive buyers driving data integration demands that reshape network operator capabilities.
- Retail:In-aisle and storefront displays targeting proximity-to-purchase decisions with first-party data integration. Quick-service restaurant chains and direct-to-consumer retailers in Texas and Florida are building proprietary audience models bypassing traditional demographic proxies.
- Automotive:Highway billboards and dealer-lot digital screens capturing consideration-phase consumers. Dealership networks concentrate spending in designated market areas with owned inventory density.
- Entertainment:Venue-based and transit placements for film, streaming, and live event promotion. Short-form video asset adaptation for high-brightness screens requires specialized color grading capabilities.
- Real Estate:Development site signage and property listing displays in high-transit corridors. Local zoning boards control permitting density and sightline restrictions that directly constrain inventory expansion.
Real Estate maintains traditional static preferences. Retail is expanding most quickly through media network convergence.
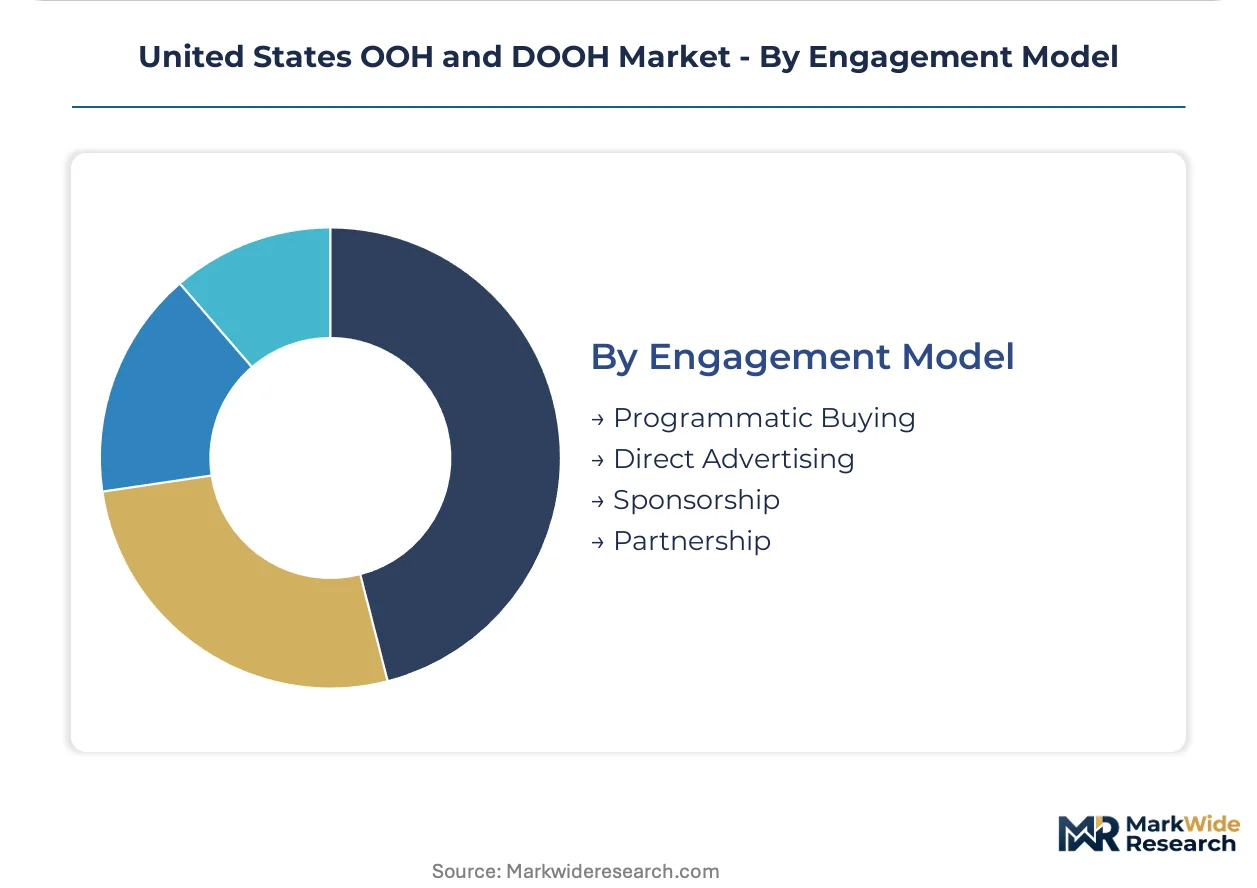
Engagement Model:
Buying mechanism segmentation tracks the technology shift collapsing separation between media planning and real-time inventory allocation.
- Programmatic Buying:Automated impression-level purchasing through demand-side platforms with MRC and OAAA verification protocols. Performance-marketing budgets previously bypassing physical media are entering OOH channels through this mechanism.
- Direct Advertising:Negotiated annual or quarterly contracts between brands and network operators for guaranteed inventory. Clear Channel Outdoor Americas and Lamar Advertising Co sustain margin through long-term highway and rural highway commitments.
- Sponsorship:Exclusive category rights for transit systems, street furniture networks, or venue displays. Outfront Media competes through exclusive agreements with major metropolitan transit authorities.
- Partnership:Revenue-sharing arrangements between display owners and municipal or commercial landlords. Smart city infrastructure bundling in Texas, California, and Florida creates multi-revenue contracts subsidizing network buildout.
Direct Advertising retains the largest revenue pool. Programmatic Buying is gaining share fastest as margin redistributes to data-enabled intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Los Angeles anchors deployment velocity for digital billboards and transit displays, with municipal authorities bundling street furniture with 5G infrastructure across the metropolitan corridor.
California
Urban density and smart city investments in Los Angeles and San Francisco are accelerating digital display conversions. The California Public Utilities Commission imposes standby power restrictions that reshape LED procurement specifications. Transit authorities in the Bay Area are merging real-time arrival data with dynamic advertising through upgraded platform displays.
Texas
Dallas-Fort Worth and Houston corridors concentrate highway billboard inventory and retail media network expansion. State-level infrastructure bundling packages digital displays with EV charging stations. Municipal contracts in Austin are subsidizing network buildout through multi-revenue smart city agreements.
New York Metro
Transit advertising density peaks in subway and commuter rail systems serving Manhattan and outer boroughs. The Metropolitan Transportation Authority requires SOC 2 compliance documentation from network vendors bidding on street furniture contracts. Brooklyn and Queens are seeing accelerated platform display upgrades with real-time content integration.
Florida
Miami and Orlando metropolitan areas concentrate place-based media in retail and entertainment venues. State-level smart city investments are creating favorable deployment conditions for digital street furniture. Tampa and Jacksonville transit authorities are compressing payback periods for LED upgrades through federal tax incentives.
Illinois
Chicago anchors Midwestern deployment with dense transit and street furniture networks. Municipal zoning boards control permitting density and brightness curfews that constrain inventory expansion along the Magnificent Mile. O'Hare corridor highway inventory remains a focus for digitization among national network operators.
United States OOH and DOOH Market Competitive Landscape
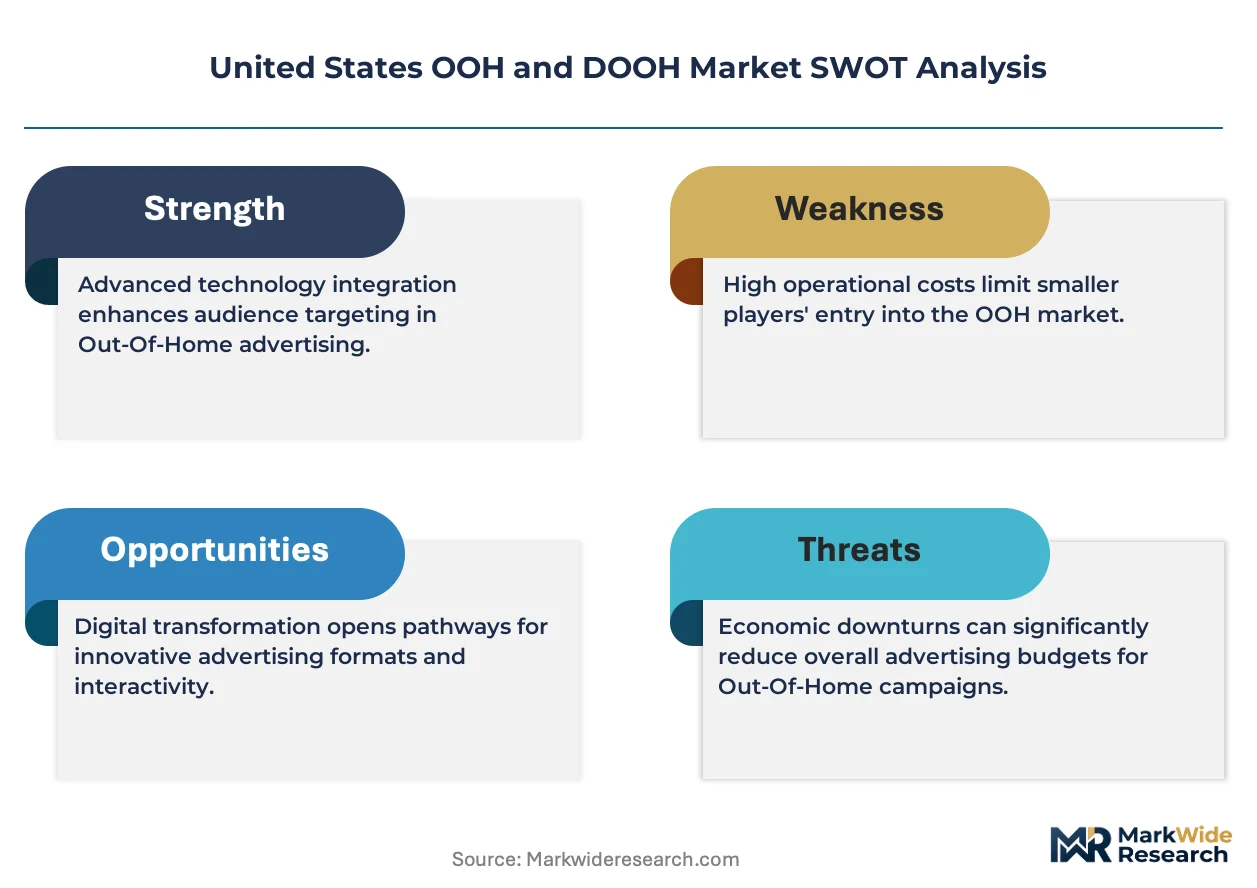
Premium-margin players sit above commodity-margin players across inventory quality and data integration capabilities. The market structures around three tiers: national network operators with owned real estate, regional specialists with exclusive municipal agreements, and technology vendors supplying content management platforms. Strategic archetypes include integrated real estate owners, transit-exclusive concessionaires, and programmatic enablement platforms. Competitive moves concentrate on smart city infrastructure partnerships and vertical integration into display manufacturing.
Among national network operators, Clear Channel Outdoor Americas exemplifies the integrated real estate archetype through nationwide billboard portfolio density. Lamar Advertising Co occupies a position anchoring rural and highway coverage through owned land lease structures. Outfront Media represents the transit-exclusive model through agreements with major metropolitan authorities. These three companies illustrate how competitive positioning diverges between real estate-heavy and concession-based revenue models.
| Leading Market Players |
|---|
| JCDecaux Group |
| Clear Channel Outdoor Americas, Inc. |
| Lamar Advertising Co |
| Outfront Media, Inc. |
| Pattison Outdoor Advertising |
| Broadsign International LLC |
| Daktronics |
| Focus Media |
| oOh!media Limited |
| Others |
Pricing and Supply Chain Analysis
Captive supply of gallium nitride wafers from dominant Asian substrate manufacturers anchors both the procurement position and pricing power for domestic LED display fabricators. This vertical lock-up creates cost pass-through capability toward municipal transit authorities and commercial landlords while exposing buyers to input volatility.
Pricing Analysis
Outcome-based pricing tied to impression verification and dwell-time metrics anchors premium tiers in the United States OOH and DOOH Market. Three-tier pricing structure across premium, standard, and economy levels separates programmatic-enabled digital networks from static vinyl placements and remnant rural inventory. Cost compression in standard-tier highway billboards is intensifying because national network operators compete for fixed advertising budgets with retail media networks. Quick-service restaurant chains and direct-to-consumer retailers operating in Texas and Florida show least price sensitivity due to proprietary audience modeling capabilities.
Supply Chain Analysis
Refurbishment flows for legacy LED arrays and controller boards create secondary supply channels that extend equipment lifecycles and dampen new hardware demand. Manufacturing concentrates in China, South Korea, and Taiwan for high-brightness diode substrates, driver ICs, and LCD panels. Domestic assembly draws from gallium nitride wafers, aluminum extrusions for structural framing, and copper wiring for power distribution. Single-source vulnerability in MOCVD reactor equipment for LED epitaxy creates bottlenecks. Distribution runs through national network operator procurement divisions, regional integrators, and direct municipal contracting channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
FCC cybersecurity hardening mandates for networked displays create a cost-of-compliance moat that favors incumbent operators with existing SOC 2 infrastructure and dedicated regulatory affairs teams.
For Market Incumbents: Hedge against margin erosion from programmatic intermediaries by deepening in-house data science capabilities for proprietary audience modeling. Acquire exclusive municipal transit concessions in secondary markets before federal tax incentive windows narrow. Defensive consolidation of rural highway land leases in Montana and Wyoming blocks emerging competitor expansion paths. For New Entrants and Emerging Players: Begin with rural interstate corridors in North Dakota and Wyoming where digital penetration remains limited and permitting friction is lower than urban jurisdictions. Target grocery and big-box retail media networks where first-party transaction data integration commands CPM premiums unavailable to traditional OOH operators. Pursue revenue-sharing partnerships with EV charging infrastructure deployers as the go-to-market angle. For Investors and Strategic Acquirers: Exit pathways concentrate in platform consolidation plays where content management software capabilities command strategic premiums over pure real estate holdings. Long-term viability hinges on operators' ability to merge location data with closed-loop attribution. Monitor FCC spectrum reallocation proceedings as the inflection signal for wireless-dependent network architectures.| Strategic Initiative | Industry Significance |
|---|---|
| Smart City Infrastructure Partnership | Multi-revenue municipal contracts in Texas and California subsidize network buildout through 5G and EV bundling. |
| Programmatic Platform Integration | MRC-verified impression buying attracts performance-marketing budgets from digital-native advertisers. |
| Retail Media Network Convergence | First-party transaction data integration captures CPG budgets that previously flowed to endemic websites. |
| EPA Energy Star Certification | Standby power thresholds below 0.5 watts per square foot create procurement preference windows for qualifying manufacturers. |
| Rural Highway Digitization | Owned land leases in underpenetrated interstate corridors offer first-mover returns before national operators consolidate. |
Research Methodology
Multi-period observation of municipal permitting velocity, LED component lead times, and programmatic transaction volumes anchored the trend analysis, supplemented by interviews with network operations executives, transit authority procurement managers, municipal zoning administrators, and digital display integrators. Secondary validation drew from FCC spectrum proceeding dockets, EPA Energy Star certification databases, IRS Section 179 guidance publications, and OAAA industry metrics. Bottom-up inventory counts across designated market areas triangulated against top-down advertising spend allocations.
Segment-weighting across media type, format, engagement model, and industry vertical dimensions shaped the analytical framework over the projection horizon. CAGRs derived from unit economics modeling of digital conversion payback periods and static inventory replacement cycles. Forecast inputs incorporated smart city infrastructure bundling adoption curves and FCC cybersecurity compliance cost trajectories.
Underlying measurement precision varies by segment; programmatic-enabled digital networks carry tighter precision than static rural billboards due to impression verification protocols. Forecasts reflect assumptions about federal tax incentive continuity and municipal procurement cycle timing. Practitioners should monitor FCC 6 GHz band proceedings and state-level clean energy mandate evolution for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Spain OOH and DOOH Market
Advertising and Marketing Media
Middle East and Africa Sports Betting Market
Advertising and Marketing Media
Copyright Licensing Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
Middle East Marketing and Advertising Agency Market
Advertising and Marketing Media
South East Asia Digital Out-Of-Home (Dooh) Market
Advertising and Marketing Media
Saudi Arabia OOH and DOOH Market
Advertising and Marketing Media
US Healthcare Advertising Market
Advertising and Marketing Media
Saudi Arabia Marketing and Advertising Agency Market
Advertising and Marketing Media
Media Advertising in Southeast Asia Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
United Kingdom Public Relation Services Market
Advertising and Marketing Media
Internet Advertising Market
Advertising and Marketing Media
Indoor LCD Advertising Players Market
Advertising and Marketing Media
South East Asia Advertising Market
Advertising and Marketing Media
Mexico OOH and DOOH Market