
 Global Programmatic Advertising Platform Market | 2026-2036
Global Programmatic Advertising Platform Market Size, Share, and Industry Trends Forecast 2026-2036
Global Programmatic Advertising Platform Market Foresight
The EU Digital Services Act is expanding compliance obligations for ad targeting transparency across European inventory. The Trade Desk sustains its position through an open-internet identity framework that reduces reliance on browser cookies. Google Display & Video 360 dominates YouTube and Google properties inventory access globally. Adobe Advertising Cloud leverages its Creative Cloud integration to serve enterprise advertisers with unified workflow tools.
A programmatic advertising platform is an automated software infrastructure that executes media buying through real-time algorithmic auctions, processing bid requests within 100 milliseconds against user profile data and inventory metadata. Its primary commercial purpose is to replace manual insertion orders with data-driven allocation of advertising budgets across fragmented digital channels. Demand-side platforms anchor the highest-margin pool as advertisers prioritize self-service buying tools with deterministic attribution. Supply-side platforms face compression as header bidding commoditizes publisher yield management. Cloud-based deployment leads solution delivery, though hybrid architectures are gaining traction among financial services advertisers with data residency requirements.
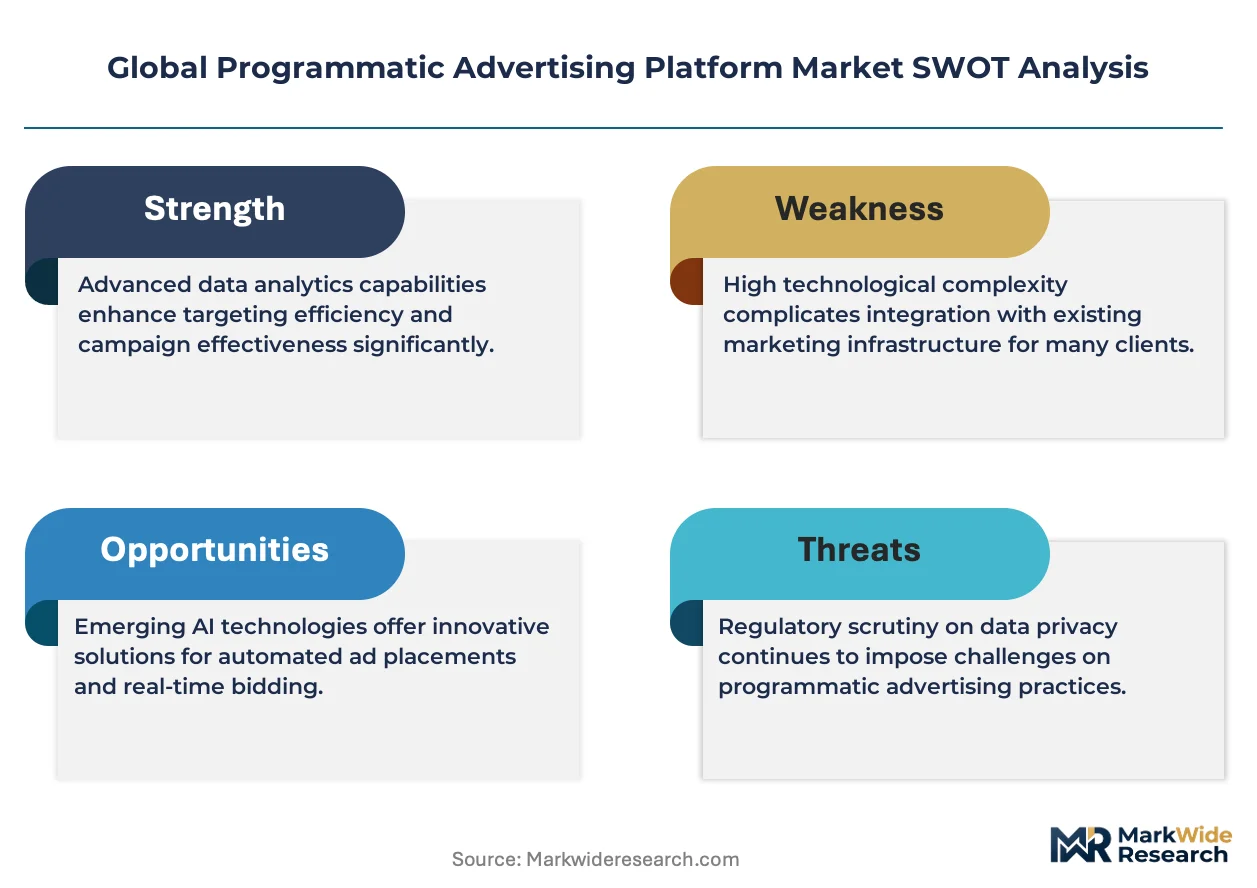
The EU GDPR and the EU AI Act impose algorithmic accountability requirements on automated ad decisioning systems used in European campaigns. The US FCC enforces telemarketing and consumer privacy rules that shape how programmatic platforms handle opt-out signals and consent strings. Stakeholders must monitor regulatory divergence between Brussels and Washington as compliance architecture becomes a competitive differentiator rather than a cost center.
Market Dynamics
Cookie deprecation is forcing a structural rebuild of identity resolution infrastructure across the entire programmatic stack, with first-party data pipelines and clean-room technologies displacing third-party tracking as the primary targeting mechanism.
Growth Catalysts
- Retail Media Networks:Walmart and Amazon are capturing brand budgets migrating from linear television and social platforms into closed-loop commerce environments with deterministic attribution.
- Connected TV Expansion:Streaming inventory aggregation through unified auction mechanics is unlocking premium video budgets previously reserved for upfront buying cycles.
- EU Digital Services Act:Transparency mandates for algorithmic ad delivery are accelerating investment in auditable decisioning systems among European inventory suppliers.
Market Restraints
- Identity Fragmentation:Apple's App Tracking Transparency and Google's Privacy Sandbox are bifurcating addressability standards across iOS and Android ecosystems.
- Supply Concentration:Meta and Google properties command disproportionate share of available impression volume, constraining independent platform yield optimization.
- Technical Latency:Real-time bidding infrastructure requires sub-100-millisecond response windows that limit sophisticated machine learning deployment at auction time.
Strategic Opportunities
- India Digital Infrastructure:Unified Payments Interface integration with retail media stacks enables closed-loop measurement in a market with nascent programmatic penetration.
- Audio Programmatic:Podcast and streaming music inventory remains under-automated relative to display and video, presenting yield arbitrage potential for early platform entrants.
- EU AI Act Alignment:Automated decisioning systems that demonstrate algorithmic accountability will qualify for preferential treatment in European public procurement frameworks.
Industry Challenges
- Data Engineering Talent Scarcity:First-party data pipeline construction requires specialized privacy-preserving computation expertise that outstrips current labor supply.
- Cross-Platform Measurement Integration:Walled garden data silos resist unified attribution modeling, forcing advertisers into expensive multi-source reconciliation projects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Programmatic Advertising Platform Market |
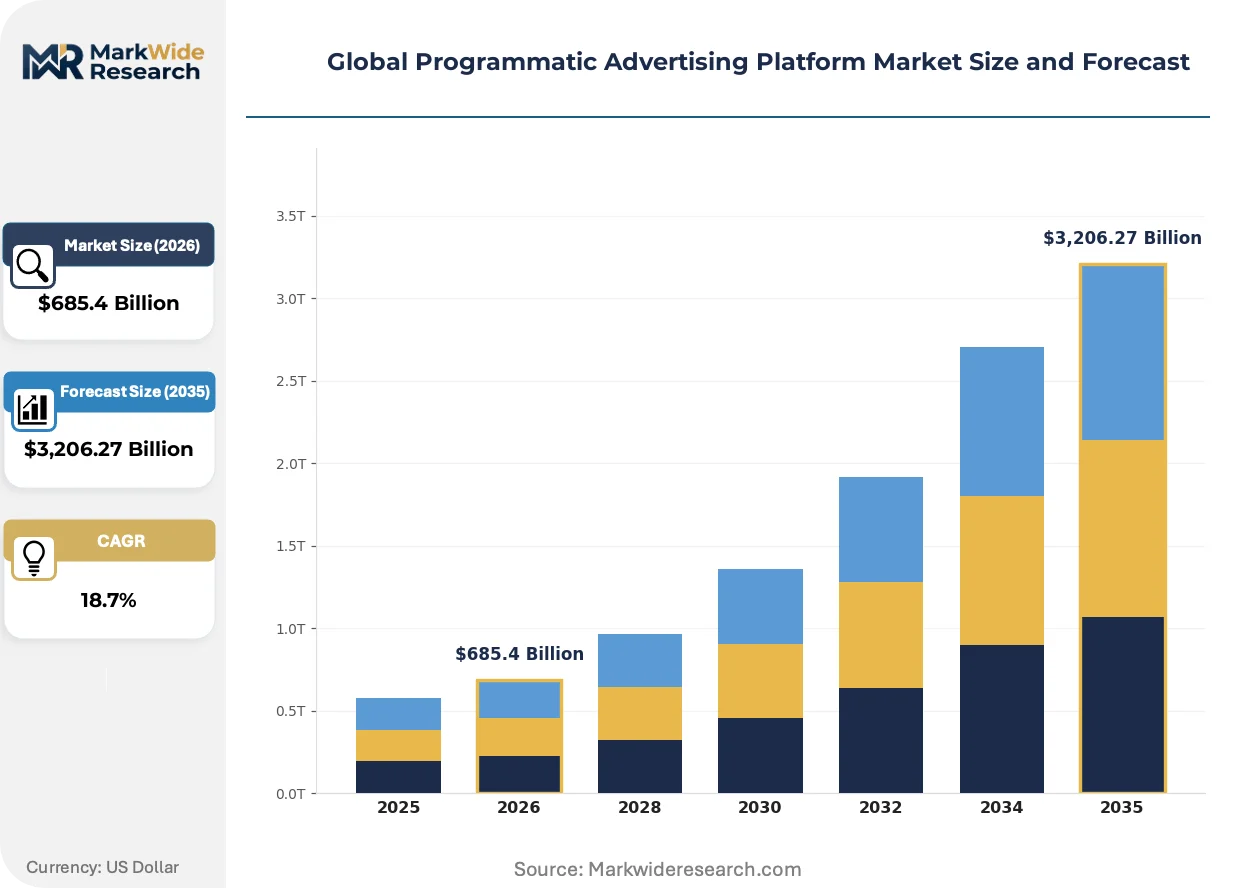
| Market Size in 2026 | $685.4 Billion |
| Market Size in 2035 | $3,206.27 Billion |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Deployment: Cloud-Based, On-Premise, Hybrid, Managed Service Solution/Offering: Demand-Side Platform, Supply-Side Platform, Data Management Platform, Ad Exchange Application: Real-Time Bidding, Audience Targeting, Campaign Management, Attribution & Analytics End User Type: Advertisers, Publishers, Agencies, Ad Networks, Brands |
| Companies Covered | Xandr, Adobe Advertising Cloud, The Trade Desk, StackAdapt, Amazon DSP, MediaMath, Google Display & Video 360, SmartyAds, PubMatic, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Programmatic Advertising Platform Market Shifts & Advancements
Identity infrastructure is fragmenting into federated architectures that reduce dependency on any single browser or device manufacturer, while regulatory pressure accelerates investment in transparent algorithmic systems.
Server-side ad insertion technology is modularizing how streaming publishers monetize inventory, decoupling ad decisioning from content delivery to reduce client-side latency. Broadcasters and premium publishers in the United States and United Kingdom are adopting this architecture to preserve viewer experience while maintaining addressability. The structural consequence is compression of client-side header bidding complexity as auction logic migrates to cloud infrastructure.
The EU AI Act imposes risk-tiered accountability requirements on automated ad targeting systems deployed in European campaigns. High-risk classification for behavioral profiling triggers mandatory documentation, human oversight, and third-party auditing obligations. Demand-side platforms serving European advertisers are rebuilding decisioning engines to generate explainable output logs that satisfy regulator inspection.
Advertiser procurement of programmatic services is consolidating toward outcome-based compensation structures that tie platform fees to verified business metrics rather than media volume. Enterprise brands in consumer packaged goods and financial services are leading this shift, pressuring platforms to demonstrate incrementality through controlled experiments. France and Germany show the fastest adoption of these performance-guaranteed contracting models.
Global Programmatic Advertising Platform Market Segmentation
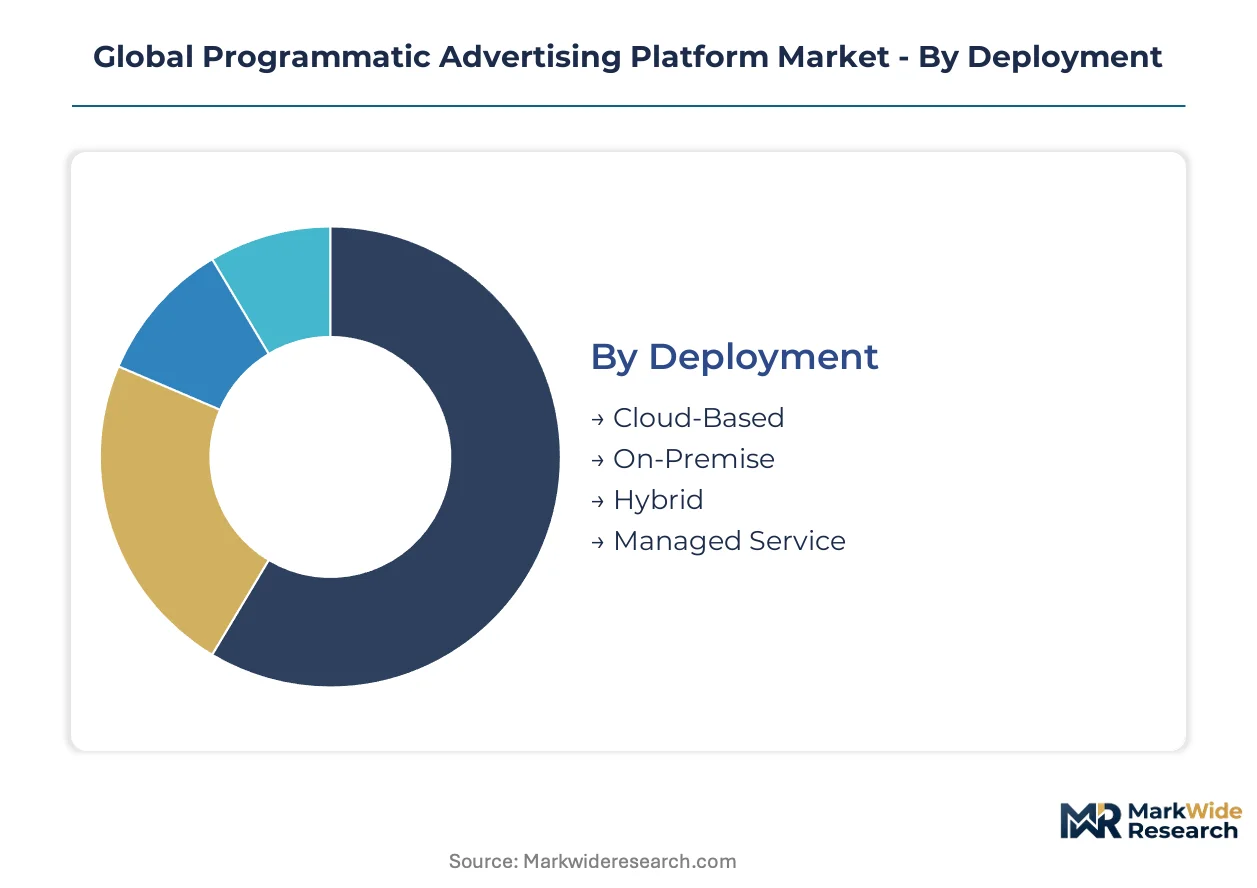
Programmatic advertising platforms fragment across four structural dimensions that determine technical architecture, commercial pricing, and buyer decision criteria. Deployment mode shapes data residency compliance. Solution type governs margin capture and platform stickiness. Application layer defines competitive differentiation. End user category determines sales cycle complexity and support requirements.
Deployment:
Customization versus standardization spans a spectrum from fully managed SaaS to self-operated infrastructure with bespoke compliance overlays.
- Cloud-Based:Multi-tenant architectures deliver elastic compute for real-time bidding auctions without capital expenditure. Demand concentrates among mid-market advertisers in the United States and Germany seeking rapid campaign activation without engineering overhead. The model sacrifices data sovereignty for speed-to-market.
- Hybrid:Split architectures process auctions in cloud environments while retaining first-party data in private infrastructure. Financial services advertisers in London and Singapore drive adoption to satisfy GDPR and MAS cross-border data rules. This configuration commands premium pricing for compliance engineering.
- On-Premise:Self-managed installations within advertiser or publisher data centers.
- Managed Service:Outsourced platform operations with dedicated technical account management.
Most installed capacity flows through Cloud-Based deployments. Expansion is steepest in Hybrid configurations.
Solution/Offering:
Cost tier stratification separates high-margin software licensing from lower-yield infrastructure services.
- Demand-Side Platform:Advertiser-facing buying tools execute algorithmic bidding across inventory sources with deterministic attribution modeling. Enterprise brands in consumer packaged goods and automotive verticals concentrate demand in the United States and United Kingdom. Self-service interfaces reduce reliance on managed media trading desks.
- Data Management Platform:First-party data unification infrastructure segments audiences and activates identity graphs. Retail media networks at Walmart and Amazon deploy proprietary instances to close attribution loops. Privacy-preserving computation requirements drive engineering investment.
- Supply-Side Platform:Publisher yield optimization technology aggregates inventory and routes bid requests.
- Ad Exchange:Neutral auction infrastructure matching buy-side demand with sell-side supply.
Revenue concentration sits with Demand-Side Platforms. Data Management Platforms are gaining share fastest.
Application:
Volume distribution correlates with campaign lifecycle stage, from auction execution through performance verification.
- Real-Time Bidding:Millisecond auction infrastructure processes bid requests against user profiles and contextual signals. Streaming publishers in the United States deploy this application for connected TV inventory monetization. Sub-100-millisecond latency constraints limit machine learning model complexity.
- Attribution & Analytics:Multi-touch measurement systems assign credit across programmatic and direct channels. Advertisers in France and Germany prioritize this application to satisfy EU Digital Services Act transparency mandates. Incrementality testing through controlled experiments differentiates platform offerings.
- Audience Targeting:Identity resolution and segment construction for precision delivery.
- Campaign Management:Workflow orchestration across creative trafficking, budget pacing, and frequency capping.
Transaction volume concentrates in Real-Time Bidding. Attribution & Analytics shows the steepest expansion trajectory.
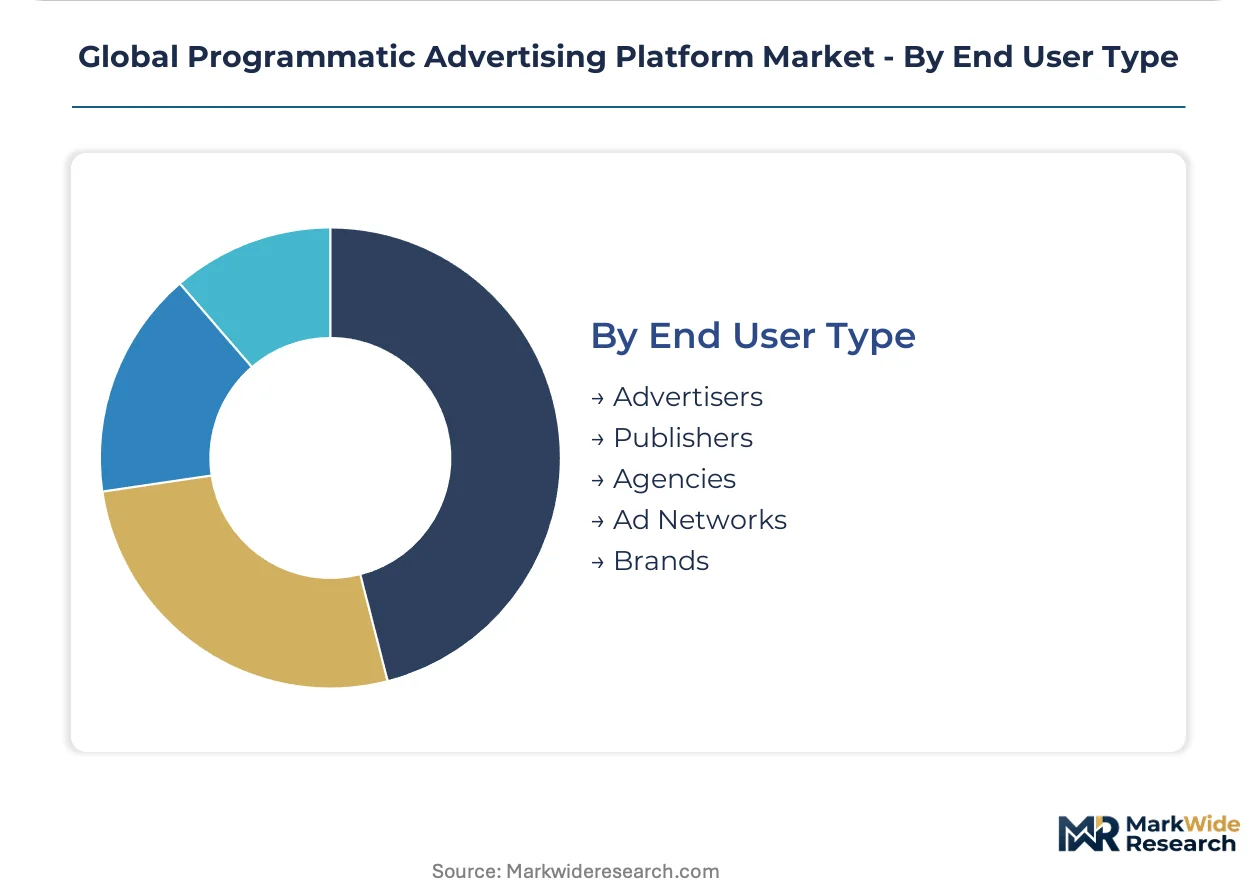
End User Type:
Customer type segmentation maps to procurement sophistication and technical integration depth.
- Brands:Direct advertiser procurement of programmatic technology bypasses agency intermediaries. Fortune 500 consumer brands in the United States build in-house trading capabilities to capture data ownership and margin. Procurement teams negotiate outcome-based compensation tied to verified sales lift.
- Agencies:Media buying services firms aggregate advertiser demand and negotiate platform access. Holding companies in London and New York consolidate tech stack relationships to improve negotiating leverage. Trading desk specialization creates service differentiation.
- Advertisers:Performance-focused buyers with campaign-specific platform relationships.
- Publishers:Inventory suppliers monetizing owned and operated properties.
- Ad Networks:Intermediary aggregators of niche or remnant inventory supply.
Platform engagement concentrates among Agencies. Brands are expanding their direct technology relationships most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Data engineering talent pools in San Francisco, London, and Bangalore anchor platform development capacity across three continents. Regulatory divergence between Brussels and Washington shapes compliance architecture investment. Connected TV infrastructure deployment varies sharply by national broadband penetration and streaming subscription density.
United States
Connected TV inventory aggregation draws premium video budgets from linear upfronts into programmatic auctions. The FCC enforces telemarketing and consumer privacy rules governing opt-out signal handling. New York and Los Angeles media clusters host trading desk specialization and brand direct procurement teams building in-house capabilities.
Germany
Automotive and financial services advertisers drive demand for outcome-based compensation tied to verified sales lift. The KBA and BSI impose data residency requirements favoring hybrid cloud deployments. Berlin and Frankfurt host compliance engineering specialists serving EU-wide campaigns.
United Kingdom
Agency holding companies consolidate tech stack relationships to improve negotiating leverage with platforms. The Information Commissioner's Office enforces GDPR-derived transparency mandates for algorithmic ad delivery. London's trading desk concentration supports pan-European campaign execution.
India
Unified Payments Interface integration with retail media stacks enables closed-loop measurement in a market with nascent programmatic penetration. The RBI and TRAI shape digital payment and telecom data governance. Bangalore and Mumbai clusters build privacy-preserving computation expertise for first-party data pipelines.
Japan
Enterprise brands in consumer packaged goods prioritize deterministic attribution modeling for closed-loop commerce environments. METI guidelines influence automated decisioning system accountability frameworks. Tokyo's advertising technology corridor hosts platform localization engineering for Asia-Pacific expansion.
Global Programmatic Advertising Platform Market Competitive Landscape
Capital-heavy infrastructure providers compete with asset-light software designers for margin capture across the programmatic stack. The vendor base concentrates around three tiers: walled garden operators commanding impression volume, independent platforms differentiating through open-internet identity frameworks, and specialized providers serving niche inventory categories. Strategic archetypes include self-service demand-side platforms, supply-side yield optimizers, and neutral exchange infrastructure. Dominant competitive moves encompass first-party data partnership formation and server-side ad insertion technology licensing.
Within the independent platform tier, The Trade Desk and StackAdapt exemplify open-internet positioning that reduces reliance on browser cookies. Google Display & Video 360 anchors the walled garden archetype through privileged access to proprietary inventory. Adobe Advertising Cloud occupies the enterprise workflow integration segment, leveraging creative production software relationships.
| Leading Market Players |
|---|
| Xandr |
| Adobe Advertising Cloud |
| The Trade Desk |
| StackAdapt |
| Amazon DSP |
| MediaMath |
| Google Display & Video 360 |
| SmartyAds |
| PubMatic |
| Others |
Supply & Pricing Matrix
Cloud compute costs for real-time bidding infrastructure cascade through SaaS subscription tiers, compressing margins for mid-market demand-side platforms while hybrid deployments command premium pricing for financial services advertisers in London and Singapore. The cost structure favors asset-light software designers over capital-heavy infrastructure providers, with data residency compliance engineering emerging as the primary price escalator.
Pricing Analysis
Bundled SaaS tiers dominate advertiser procurement, separating self-service interfaces from managed service overlays with dedicated technical account management. Price differentiation hinges on deterministic attribution granularity and first-party data pipeline depth, with enterprise brands in consumer packaged goods showing lowest price sensitivity due to outcome-based compensation models. Cost compression in mid-market cloud deployments intensifies as header bidding commoditizes publisher yield management. Small and medium advertisers exhibit highest price sensitivity, prioritizing rapid campaign activation over compliance engineering.
Supply Chain Analysis
Reverse-logistics flows for server-side ad insertion hardware and refurbished bidding infrastructure concentrate in the United States, Germany, and India. The supply chain draws from Taiwan for semiconductor components, Ireland for data center equipment, and domestic cloud regions for edge computing nodes. Single-source vulnerability in identity resolution software licenses poses structural risk. Distribution runs through direct enterprise sales teams for Fortune 500 brands and agency holding company consolidators for mid-market access.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Programmatic Advertising Platform Market functions as a geographic-arbitrage play where EU AI Act compliance costs in Brussels create pricing headroom for Washington-based platforms serving European campaigns through regulatory technology overlays.
For Market Incumbents: Deploy first-party data partnership networks to defend against retail media network encroachment from Walmart and Amazon. Capture server-side ad insertion licensing revenue from broadcasters migrating auction logic to cloud infrastructure. Consolidate trading desk relationships through outcome-based compensation guarantees that tie fees to verified sales lift metrics. For New Entrants and Emerging Players: Capture audio programmatic inventory in podcast and streaming music environments where automation lags display and video. Target India through Unified Payments Interface integration with retail media stacks enabling closed-loop measurement. Pursue white-label demand-side platform licensing to agency holding companies seeking differentiated trading desk capabilities. For Investors and Strategic Acquirers: Consolidation pressure builds where privacy-preserving computation expertise outstrips labor supply for first-party data pipeline construction. Long-term viability favors platforms with open-internet identity frameworks reducing browser cookie dependency. Monitor EU Digital Services Act enforcement intensity as inflection indicator for European inventory supplier valuations.| Strategic Initiative | Industry Significance |
|---|---|
| First-Party Data Partnership Formation | Walmart and Amazon retail media networks close attribution loops through proprietary data management platform deployment. |
| Server-Side Ad Insertion Technology Licensing | Broadcasters in the United States and United Kingdom reduce client-side latency while preserving viewer addressability. |
| EU AI Act Compliance Engineering Investment | Demand-side platforms serving European advertisers generate explainable output logs satisfying regulator inspection requirements. |
| Outcome-Based Compensation Structuring | Enterprise brands in France and Germany tie platform fees to verified business metrics through controlled incrementality experiments. |
| Audio Programmatic Platform Development | Early entrants capture yield arbitrage in podcast and streaming music inventory segments with nascent automation penetration. |
Research Methodology
Bottom-up advertiser procurement modeling reconciled against top-down platform revenue tracking forms the analytical core of this study. Primary interviews with demand-side platform product managers, supply-side platform yield engineers, agency trading desk directors, and brand marketing procurement leads inform segmentation assumptions. Secondary validation draws from FCC privacy enforcement records, EU Digital Services Act transparency filings, SEC 10-K disclosures from advertising technology vendors, and IAB programmatic spend surveys. Triangulation between bottom-up campaign volume estimates and top-down platform reported revenue ensures dimensional consistency.
Input-output matrices map deployment mode adoption rates against solution type margin capture across the projection horizon. Segmentation dimensions modeled include deployment architecture, platform solution category, application layer function, and end user procurement sophistication. CAGRs derive from logistic diffusion curves fitted to identity infrastructure transition timelines and retail media network budget migration patterns. Forecast inputs incorporate connected TV inventory aggregation velocity and EU AI Act risk-tier classification thresholds for behavioral profiling systems.
Cookie deprecation acceleration, regulatory enforcement divergence between Brussels and Washington, and retail media network budget capture velocity are the dominant revision risks to modeled outputs. Forecasts reflect assumptions about identity resolution technology adoption curves and cross-platform measurement integration feasibility. Practitioners should monitor FCC rulemaking on opt-out signal handling, EU AI Act third-party audit mandate timing, and UPI-retail media integration milestones in India for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
GCC OOH and DOOH Market
Advertising and Marketing Media
Global Programmatic Advertisement Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Advertising Services Market
Advertising and Marketing Media
Outdoor Advertising Market
Advertising and Marketing Media
Vietnam OOH and DOOH Market
Advertising and Marketing Media
Thailand OOH and DOOH Market
Advertising and Marketing Media
Qatar OOH and DOOH Market
Advertising and Marketing Media
South Korea OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Russia OOH and DOOH Market
Advertising and Marketing Media
Europe Programmatic Advertising Market
Advertising and Marketing Media
Indonesia OOH and DOOH Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
North America Public Relation Services Market
Advertising and Marketing Media
LED Billboard Market