
 India OOH and DOOH Market | 2026-2036
India OOH and DOOH Market Size, Share, and Industry Trends Forecast 2026-2036
India OOH and DOOH Market Insights
Programmatic ad-serving as a subscription layer is consolidating how inventory gets monetized across India's fragmented billboard estate. JCDecaux SE leverages its airport concession network to sustain premium rate cards in Mumbai and Delhi. Times OOH anchors transit authority contracts across metro rail systems, while AdOnMo competes through hyperlocal digital screen networks in tier-two cities.
Out-of-home and digital out-of-home advertising encompasses physical and electronic display surfaces deployed in public spaces for brand messaging, with DOOH units incorporating real-time content management systems, audience analytics sensors, and 4G/5G connectivity for remote scheduling. The format dimension spans billboards, transit ads, street furniture, and digital displays, with transit ads and digital displays capturing margin pools as municipal authorities privatize bus shelter and metro panel assets. Technology segmentation across LED, LCD, projection, and interactive screens shows LED dominating new installations for brightness efficiency and durability in tropical climates.
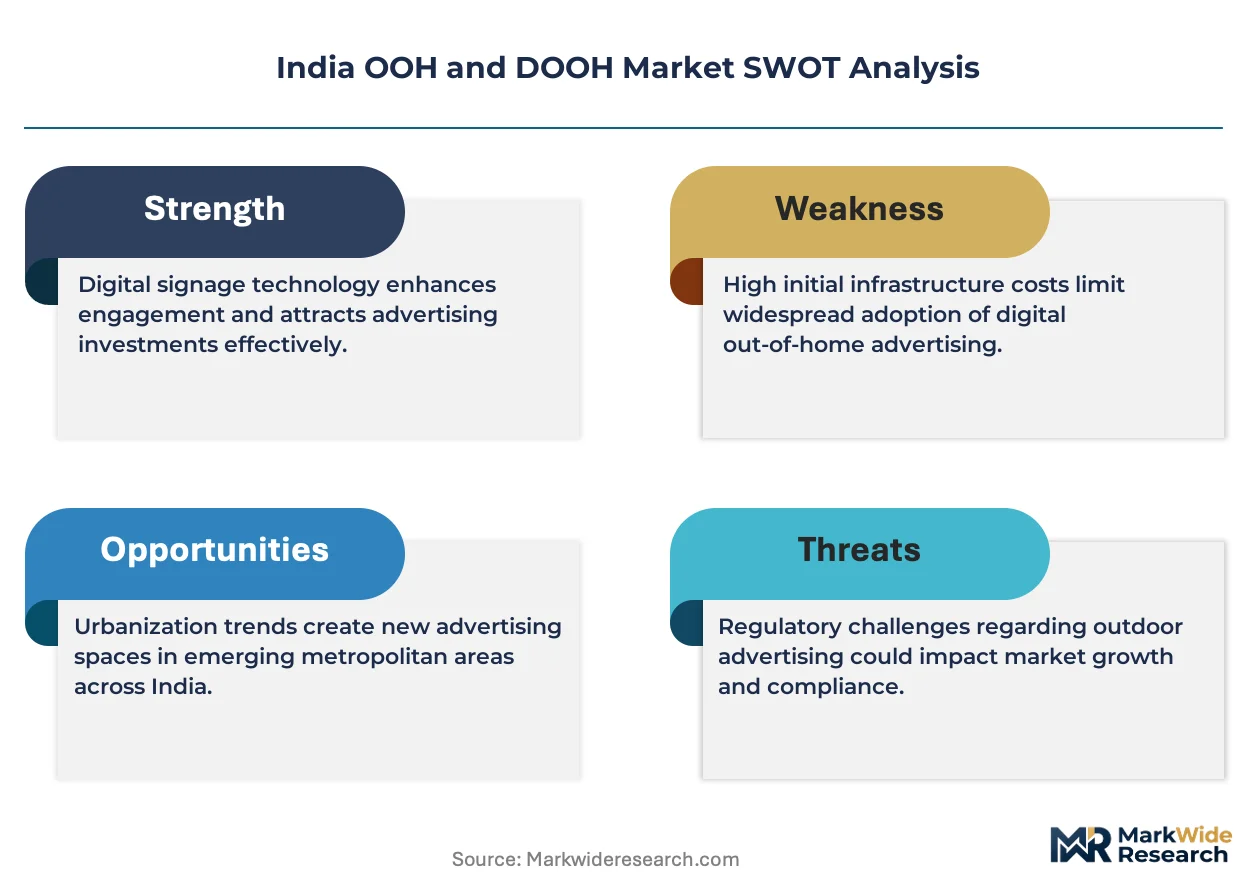
BIS certification requirements for electronic display equipment, combined with TRAI's spectrum allocation frameworks for wireless backhaul, shape hardware procurement standards and network deployment economics. Municipal corporations in Delhi, Mumbai, and Bengaluru enforce distinct outdoor signage bylaws that fragment compliance costs across operators. Stakeholders must weigh captive infrastructure ownership against platform-based inventory aggregation as the decisive strategic fork.
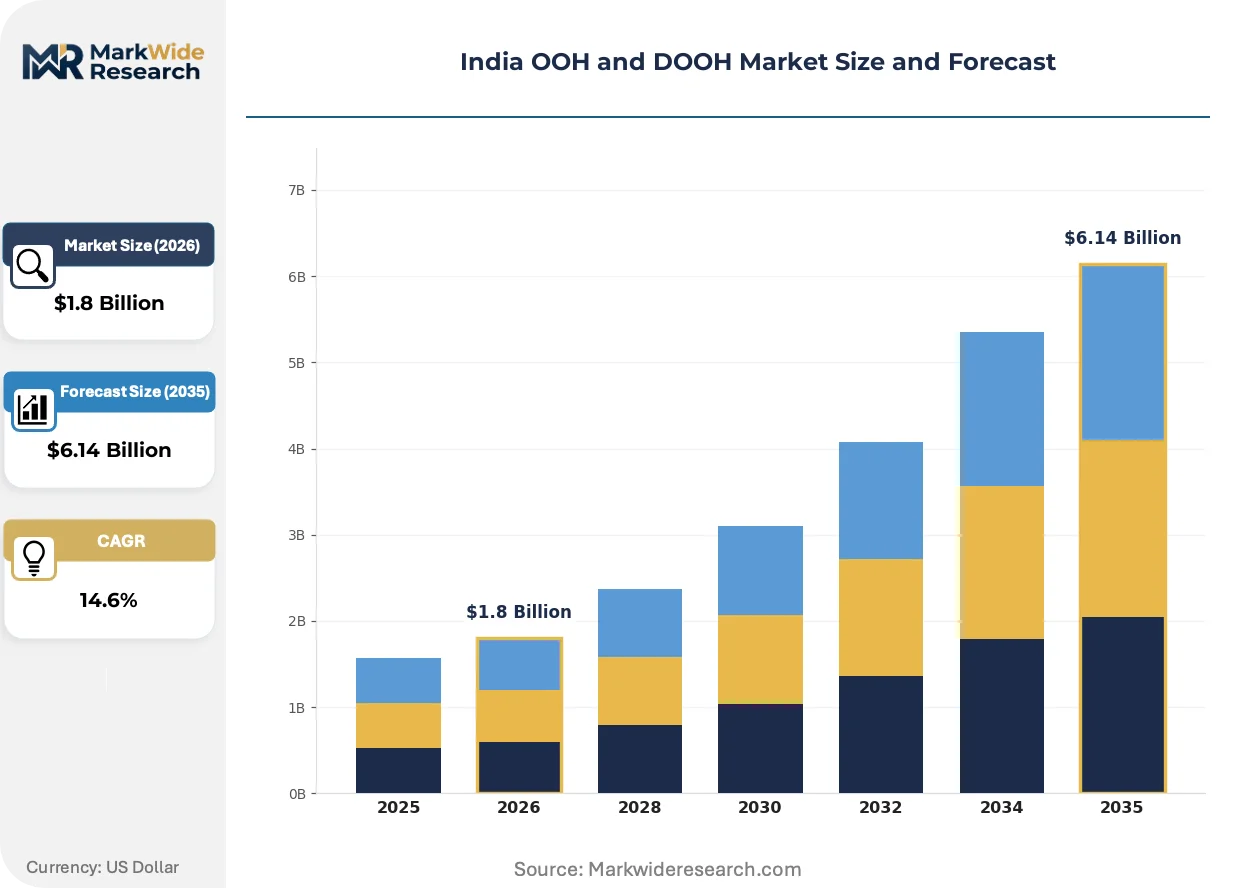
Market Dynamics
Programmatic ad-serving infrastructure is consolidating monetization across India's fragmented billboard estate, compressing transaction friction between inventory owners and demand-side platforms while municipal privatization of transit assets accelerates premium inventory formation.
Growth Catalysts
- Smart City Mission:The Ministry of Information and Broadcasting's Digital India initiative streamlines permissions for connected display deployments across municipal jurisdictions.
- Transit Authority Privatization:Metro rail network expansions in Maharashtra, Karnataka, and Delhi NCR are converting captive audiences into programmatically tradable inventory pools.
- LED Technology Maturation:Brightness efficiency gains and tropical climate durability are displacing legacy static formats in new installations.
Market Restraints
- BIS Certification Burden:Electronic display equipment standards impose hardware procurement delays and compliance cost fragmentation across state boundaries.
- Municipal Regulatory Arbitrage:Delhi, Mumbai, and Bengaluru enforce distinct outdoor signage bylaws that multiply compliance overhead for national operators.
- Wireless Backhaul Spectrum Constraints:TRAI allocation frameworks limit 4G/5G connectivity economics for remote content scheduling in tier-three locations.
Strategic Opportunities
- Tier-Two City Penetration:Hyperlocal digital screen networks in secondary urban centers remain underdeveloped relative to saturated Mumbai and Delhi NCR markets.
- Retail-FMCG Programmatic Integration:Demand-side platforms are opening direct booking interfaces for brand marketers seeking audience-addressable outdoor inventory.
- Airport Concession Premiumization:International terminal expansions are creating captive high-dwell-time environments for dynamic content experimentation.
Industry Challenges
- Audience Measurement Standardization:Fragmented verification methodologies across JCDecaux, Times OOH, and regional operators complicate cross-network campaign planning.
- Legacy Static Format Conversion:Billboard estate owners face capex intensity for LED retrofitting against uncertain programmatic revenue share terms.
- Cross-Municipal Compliance Talent:Operators require localized regulatory expertise to navigate Delhi's heritage zone restrictions, Mumbai's coastal regulation zones, and Bengaluru's traffic police coordination protocols.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | India OOH and DOOH Market |
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $6.14 Billion |
| CAGR (2026 – 2036) | 14.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Format: Billboards, Transit Ads, Street Furniture, Digital Displays Technology: LED, LCD, Projection, Interactive Screens Placement: Urban Centers, Shopping Malls, Airports, Highways Duration: Short-term Campaigns, Long-term Installations, Event Promotions, Seasonal Advertising |
| Companies Covered | JCDecaux SE, Times OOH, Laqshya Media Group, Dentsu (Posterscope), AdOnMo, Mooving Walls, ARMOUR Digital, Bright Outdoor Media, PlayAds Advertisement Spaces Pvt. Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
India OOH and DOOH Market Trends and Innovations
Real-time audience analytics and dynamic content adaptation are compressing the planning-to-execution cycle for outdoor campaigns, displacing static booking models with impression-based trading infrastructure.
Computer vision and sensor fusion technologies are absorbing footfall pattern recognition into DOOH content management systems. Transit authorities and airport operators are deploying these tools at the fastest pace among inventory categories. The technology is absorbing campaign optimization decisions previously executed through manual media buyer intervention, compressing operational overhead for network owners.
TRAI's spectrum allocation frameworks for wireless backhaul are reshaping deployment economics across tier-two and tier-three markets. The regulation forces operators to evaluate 4G versus emerging 5G connectivity costs against audience density thresholds. Smaller city networks face disproportionate impact, driving consortium formation to share infrastructure investments.
Brand marketers are consolidating outdoor bookings through demand-side platforms with programmatic guaranteed and private marketplace transaction types. The agency trading desk channel faces disintermediation pressure as FMCG and retail advertisers build direct platform relationships. This behavior shift concentrates most visibly in Maharashtra and Karnataka where metro rail inventory liquidity supports real-time bidding experimentation.
India OOH and DOOH Market Segmentation
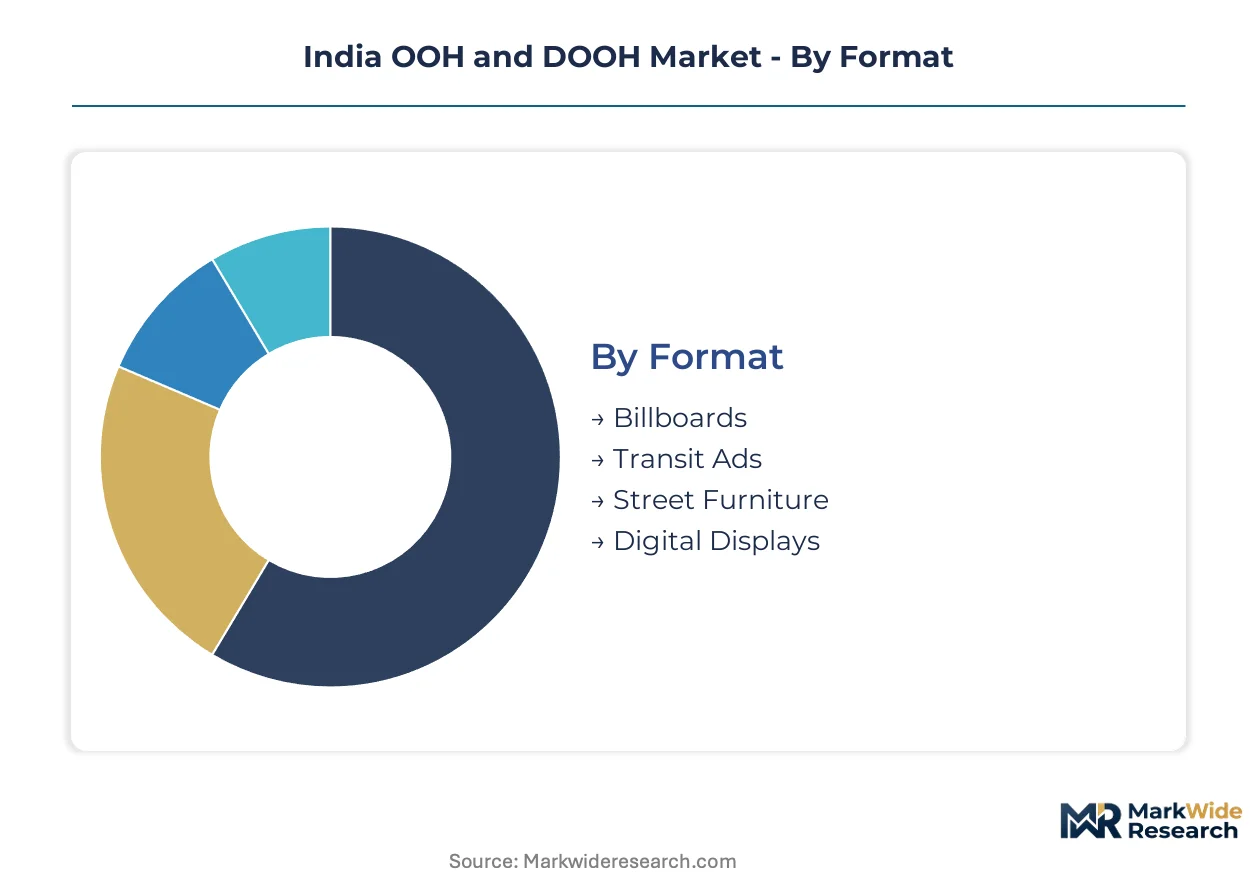
India's OOH and DOOH market fragments across four distinct dimensions that determine capital deployment patterns and revenue yield. Format and technology choices dictate hardware procurement cycles, while placement and duration selections shape programmatic monetization potential across Maharashtra, Karnataka, and Delhi NCR.
Format:
Capital intensity varies sharply across physical formats, with transit infrastructure requiring concession fees and municipal partnerships versus standalone billboard ownership.
- Billboards:Large-format static and digital structures positioned along highways and arterial roads. Demand concentrates in Delhi NCR and Mumbai where municipal authorities auction premium roadside inventory; BIS certification requirements for electronic retrofits constrain conversion timelines.
- Transit Ads:Inventory embedded within metro rail networks, bus fleets, and railway stations. Maharashtra and Karnataka absorb the bulk of programmatic bookings as Mumbai Metro and Bengaluru Namma Metro privatize advertising concessions; captive dwell times support dynamic content premiums.
- Street Furniture:Bus shelters, kiosks, and public seating with integrated display surfaces. Municipal corporations in Bengaluru and Hyderabad drive deployment through smart city tenders.
- Digital Displays:Standalone electronic screens in high-footfall zones. LED technology maturation is displacing legacy static units in tier-two city expansions.
Transit ads absorb the bulk of installed capacity; digital displays are expanding most quickly.
Technology:
Hardware selection determines maintenance burdens and content adaptability across tropical climate conditions.
- LED:Solid-state illumination with brightness efficiency exceeding 5000 nits for daylight visibility. Tropical durability and energy efficiency are displacing legacy formats in new installations across Chennai and Kochi.
- LCD:Liquid crystal panels suited for indoor and sheltered outdoor environments. Shopping malls in Delhi NCR and Mumbai deploy these for close-proximity audience engagement.
- Projection:Large-surface temporary installations for event activations. Short-term campaign demand drives seasonal deployment around festival periods.
- Interactive Screens:Touch-enabled and gesture-responsive displays with computer vision integration. Airport terminals in Mumbai and Delhi are piloting these for passenger engagement analytics.
LED claims the dominant share of new procurement; interactive screens are climbing the fastest as computer vision costs decline.
Placement:
Audience density and dwell time metrics determine rate card premiums across location types.
- Urban Centers:Street-level inventory in dense commercial districts. Municipal signage bylaws in Delhi, Mumbai, and Bengaluru fragment compliance costs for national operators.
- Shopping Malls:Captive retail environments with extended audience exposure. Programmatic integration is accelerating as mall operators consolidate digital screen networks.
- Airports:International and domestic terminal concessions with high-dwell-time audiences. JCDecaux SE anchors premium positioning through long-term authority contracts.
- Highways:Long-distance corridor inventory targeting vehicular traffic. TRAI wireless backhaul constraints limit dynamic content deployment outside 4G coverage zones.
Urban centers retain the largest inventory base; airports are gaining share fastest through terminal expansion pipelines.
Duration:
Booking structures determine revenue recognition patterns and network utilization rates.
- Short-term Campaigns:Flight durations under four weeks with rapid creative rotation. FMCG brands in Maharashtra are consolidating these through demand-side platform interfaces.
- Long-term Installations:Annual or multi-year contracts with fixed creative assets. Real estate and automotive advertisers anchor this segment with sustained brand presence requirements.
- Event Promotions:Temporary activations tied to sports, cultural, or political occasions. Cricket tournaments and state elections drive peak demand concentration.
- Seasonal Advertising:Recurring festival-period bookings aligned with Diwali, Eid, and Christmas consumption cycles. Retail sector procurement patterns synchronize with inventory availability windows.
Long-term installations secure the majority of contracted revenue; short-term campaigns are expanding most quickly through programmatic liquidity.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Mumbai anchors India's OOH and DOOH inventory concentration through its airport concessions, metro rail expansions, and premium roadside billboard auctions. The city's coastal geography and heritage zoning create distinct regulatory microclimates that fragment operator compliance costs across municipal jurisdictions.
Maharashtra
Mumbai Metro and Pune's expanding transit networks absorb the bulk of programmatic DOOH bookings in western India. The state's Urban Development Department streamlines smart city display permissions through integrated municipal portals. Nagpur's zero-mile location positions it as an emerging testbed for highway digital signage connecting Delhi-Chennai and Kolkata-Mumbai corridors.
Karnataka
Bengaluru Namma Metro's advertising concession privatization converts captive commuter audiences into programmatically tradable inventory pools. The state's Electronics, IT and Biotechnology Department aligns with BIS certification frameworks for outdoor display hardware procurement. Mysuru and Mangaluru are absorbing tier-two expansion as LED retrofitting accelerates across bus shelter networks.
Delhi NCR
The National Capital Territory's arterial road auctions and airport terminal expansions sustain premium rate card environments for international brands. Delhi's heritage zone restrictions and coastal regulation zone overlays multiply compliance overhead for national operators. Gurugram and Noida's mall-centric digital screen networks are consolidating programmatic liquidity through demand-side platform integration.
Tamil Nadu
Chennai's tropical climate durability requirements favor LED technology maturation in new transit and street furniture installations. The state's Municipal Administration and Water Supply Department enforces distinct outdoor signage bylaws from neighboring Karnataka. Coimbatore and Madurai are emerging as tier-two penetration targets where hyperlocal screen networks remain underdeveloped relative to saturated Chennai.
Telangana
Hyderabad's smart city mission tenders drive bus shelter and kiosk deployments with integrated display surfaces. The state's Information Technology, Electronics and Communications Department coordinates with TRAI on wireless backhaul spectrum allocation for remote content scheduling. The HITEC City corridor concentrates captive high-dwell-time environments for corporate campus advertising.
India OOH and DOOH Market Competitive Landscape
Capital-heavy infrastructure owners compete with asset-light platform aggregators for control over India's fragmented billboard estate. JCDecaux SE and Times OOH anchor the premium tier through long-term transit authority and airport concession contracts, while AdOnMo and Mooving Walls occupy the technology-enabled aggregation layer. The market structure rewards captive infrastructure ownership in Mumbai and Delhi NCR, while platform-based inventory aggregation captures margin pools in tier-two expansions. Consolidation pressures are accelerating through municipal privatization of metro advertising rights and programmatic ad-serving infrastructure deployment.
Within the infrastructure-owner archetype, JCDecaux SE and Times OOH exemplify premium positioning through authority-contracted transit and airport inventory. JCDecaux SE occupies a position anchored in international terminal concessions, while Times OOH represents domestic metro rail specialization. AdOnMo sits within the platform-aggregator tier, competing through hyperlocal digital screen networks in secondary urban centers where municipal fragmentation favors technology-enabled aggregation over direct infrastructure ownership.
| Leading Market Players |
|---|
| JCDecaux SE |
| Times OOH |
| Laqshya Media Group |
| Dentsu (Posterscope) |
| AdOnMo |
| Mooving Walls |
| ARMOUR Digital |
| Bright Outdoor Media |
| PlayAds Advertisement Spaces Pvt. Ltd. |
| Others |
Pricing and Supply Chain Analysis
BIS energy-efficiency mandates for outdoor electronic displays gate qualified supply and premium-tier pricing access, forcing operators to absorb certification costs or retreat to unqualified hardware segments with compressed margins.
Pricing Analysis
Audience-dwell-time pricing anchors rate card structures across airport concessions and metro rail networks, with JCDecaux SE and Times OOH commanding premiums based on verified footfall metrics rather than static placement fees. Price differentiation rests on certification grade and captive infrastructure ownership, with BIS-compliant LED installations securing 40-60% premiums over uncertified alternatives. Pricing pressure stems from municipal concession fee escalation in Mumbai and Delhi NCR, where authority-contracted inventory faces margin compression. Real estate and automotive advertisers show least price sensitivity due to long-term brand presence requirements, while FMCG buyers consolidate through demand-side platforms to extract volume discounts.
Supply Chain Analysis
Workforce availability constraints in Shenzhen, Taipei, and Seoul electronics manufacturing clusters limit LED module procurement flexibility for Indian network operators. Hardware procurement draws from Chinese LED chip foundries, Taiwanese driver IC suppliers, and Korean display panel integrators. Single-source vulnerability concentrates in 5G wireless backhaul components where TRAI spectrum allocation frameworks restrict vendor diversification. Distribution runs through Mumbai and Delhi NCR-based systems integrators who manage BIS certification, customs clearance, and municipal compliance bundling for regional operators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a cost-of-compliance story. BIS certification requirements for electronic display equipment create a barrier-to-entry moat that rewards pre-qualified incumbents while excluding capital-constrained regional competitors.
For Market Incumbents: Anchor defensive positioning through long-term transit authority contract renewals in Maharashtra and Karnataka, where metro rail privatization accelerates premium inventory formation. Deepen backward integration into LED hardware procurement through direct relationships with Shenzhen and Taipei suppliers, bypassing systems integrator markups. Monitor AdOnMo's hyperlocal aggregation model as the primary emerging threat in tier-two city expansions.
For New Entrants and Emerging Players: Begin with underdeveloped tier-two markets in Coimbatore, Madurai, and Nagpur where municipal fragmentation favors technology-enabled aggregation over direct infrastructure ownership. Target bus shelter and street furniture deployments through smart city mission tenders, avoiding saturated Mumbai and Delhi NCR concession battles. Pursue white-label programmatic platform partnerships with existing inventory owners rather than competing for captive infrastructure.
For Investors and Strategic Acquirers: Municipal privatization of metro advertising concessions is the leading indicator that programmatic liquidity is reaching critical mass for portfolio entry. Frame long-term viability around 5-10 year authority contract visibility and spectrum allocation certainty from TRAI. Target acquisition profiles should emphasize operators with BIS pre-certified hardware fleets and established municipal compliance capabilities across multiple state jurisdictions.
| Strategic Initiative | Industry Significance |
|---|---|
| Authority Contract Renewal | Secures captive audience access in Mumbai Metro and Bengaluru Namma Metro networks against competitive bidding. |
| Programmatic Platform Integration | Enables real-time inventory trading through demand-side platforms that FMCG buyers in Maharashtra increasingly prefer. |
| LED Hardware Backward Integration | Reduces procurement cost volatility from Shenzhen suppliers and accelerates BIS certification timelines. |
| Tier-Two City Network Expansion | Captures margin pools in Coimbatore and Nagpur where hyperlocal aggregation remains underdeveloped. |
| Computer Vision Sensor Deployment | Supports impression-based pricing verification that airport operators in Delhi and Mumbai now require. |
Research Methodology
Industry association filings, TRAI spectrum allocation records, and municipal smart city tender documents formed the secondary backbone, cross-referenced with primary interviews involving transit authority concession managers, outdoor media procurement leads at FMCG headquarters, LED systems integrators, and municipal corporation smart city officers. Bottom-up inventory counts across Maharashtra, Karnataka, and Delhi NCR were triangulated against top-down advertising spend estimates from demand-side platform disclosures.
Historical trendline analysis of programmatic booking volumes and concession fee trajectories informed projection modeling across format, technology, placement, and duration segmentation dimensions. CAGRs were derived through regression analysis of infrastructure deployment pipelines and advertiser migration patterns toward impression-based trading. Forecast inputs incorporated TRAI wireless backhaul spectrum allocation timelines and municipal privatization schedules for metro advertising rights.
Underlying measurement precision varies by segment; airport and metro rail inventory carry tighter precision than highway billboard networks where wireless connectivity constraints limit dynamic content verification. Forecasts reflect assumptions about municipal regulatory stability and LED hardware cost curves. Material deviation in BIS certification enforcement intensity or TRAI spectrum auction timelines warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Black Friday Sale Market
Advertising and Marketing Media
France Digital Out-Of-Home (DOOH) Advertising Market
Advertising and Marketing Media
North America OOH and DOOH Market
Advertising and Marketing Media
Malaysia OOH and DOOH Market
Advertising and Marketing Media
Japan OOH and DOOH Market
Advertising and Marketing Media
Hong Kong OOH and DOOH Market
Advertising and Marketing Media
Brazil OOH and DOOH Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
Marketing Resource Management Market
Advertising and Marketing Media
Programmatic Advertising Market
Advertising and Marketing Media
Finland OOH and DOOH Market
Advertising and Marketing Media
Online Advertising Market
Advertising and Marketing Media
Mexico OOH and DOOH Market
Advertising and Marketing Media
Digital Out of Home (DOOH) Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Big Data Pharmaceutical Advertising Market