
 Billboard and Outdoor Advertising Market | 2026-2036
Billboard and Outdoor Advertising Market Size, Share, and Industry Trends Forecast 2026-2036
Billboard and Outdoor Advertising Market Analysis
North American digital billboard fabricators are recalibrating production schedules to match municipal permit backlogs. Lamar Advertising leverages its land-bank position to sustain premium roadside placements across Sun Belt interstate corridors. JCDecaux anchors European transit advertising through long-term concession agreements with Paris, London, and Berlin transport authorities. Clear Channel Outdoor competes on programmatic digital inventory, connecting roadside screens to demand-side platforms.
Billboard and outdoor advertising encompasses static and digital display structures positioned in high-visibility public spaces, typically employing LED arrays with pixel pitches ranging from 4mm to 16mm for digital formats, designed to deliver brand messaging to vehicular and pedestrian traffic. The primary commercial purpose centers on building unskippable brand awareness in locations where consumers cannot deploy ad-blocking technologies. Digital displays command the fastest expansion as programmatic buying and real-time creative rotation reshape advertiser expectations, while street furniture maintains stable margins through exclusive municipal contracts that limit competitive entry. Static billboards retain volume leadership in rural interstate corridors where digital conversion economics remain unfavorable.
The US Federal Highway Administration coordinates with state departments of transportation to regulate billboard spacing and lighting standards under the Highway Beautification Act framework, directly constraining inventory growth along federally funded roadways. The EU's F-Gas Regulation and national energy codes in Germany and France are tightening efficiency standards for digital display operation, elevating total cost of ownership calculations for operators. China's MIIT and SAMR jointly oversee digital display content review and network security protocols for programmatic systems. Stakeholders must weigh concession renewal timelines against capital requirements for LED compliance upgrades and connected infrastructure.
Market Dynamics
Digital programmatic trading is compressing sales cycles and fragmenting buyer concentration across roadside and transit inventory, forcing operators to restructure yield management systems around real-time demand curves rather than annual contract blocks.
Growth Catalysts
- EU Green Deal efficiency mandates:Municipalities across Germany and France are accelerating LED retrofit timelines, creating replacement demand for compliant display hardware.
- Transit corridor densification:São Paulo-Rio de Janeiro concession renewals favor technology-enabled operators with connected screen networks and dynamic content capabilities.
- Programmatic demand-side platforms:Advertisers now execute audience-targeted buys across dispersed digital billboard networks, collapsing the traditional direct-sales model.
Market Restraints
- LED component supply concentration:Display module production clusters in East Asian manufacturing hubs, exposing operators to shipping volatility and tariff exposure.
- F-Gas Regulation compliance costs:Cooling system retrofits for large-format digital displays elevate total cost of ownership calculations for European operators.
- Static inventory lock-in:Rural interstate corridors where digital conversion economics remain unfavorable trap capital in depreciating vinyl-based assets.
Strategic Opportunities
- Brazil corridor expansion:Underpenetrated secondary highways connecting São Paulo to regional manufacturing centers offer concession bidding opportunities with lower competitive density.
- Street furniture digitalization:Bus shelter and kiosk networks in Paris, London, and Berlin remain partially analog, presenting retrofit white space under long-term municipal contracts.
- 5G-connected screen networks:Convergence of cellular infrastructure and display hardware enables real-time creative rotation and audience measurement integration.
Industry Challenges
- Programmatic talent scarcity:Operators lack sufficient data science and ad-tech engineering capacity to manage yield algorithms and SSP integrations.
- Concession renewal capex cliffs:Municipal contract rebidding cycles synchronize with LED compliance upgrade requirements, compressing capital deployment timelines.
- Legacy vinyl-to-digital integration:Hybrid portfolios require dual maintenance capabilities and bifurcated sales teams, complicating operational rationalization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Billboard and Outdoor Advertising Market |
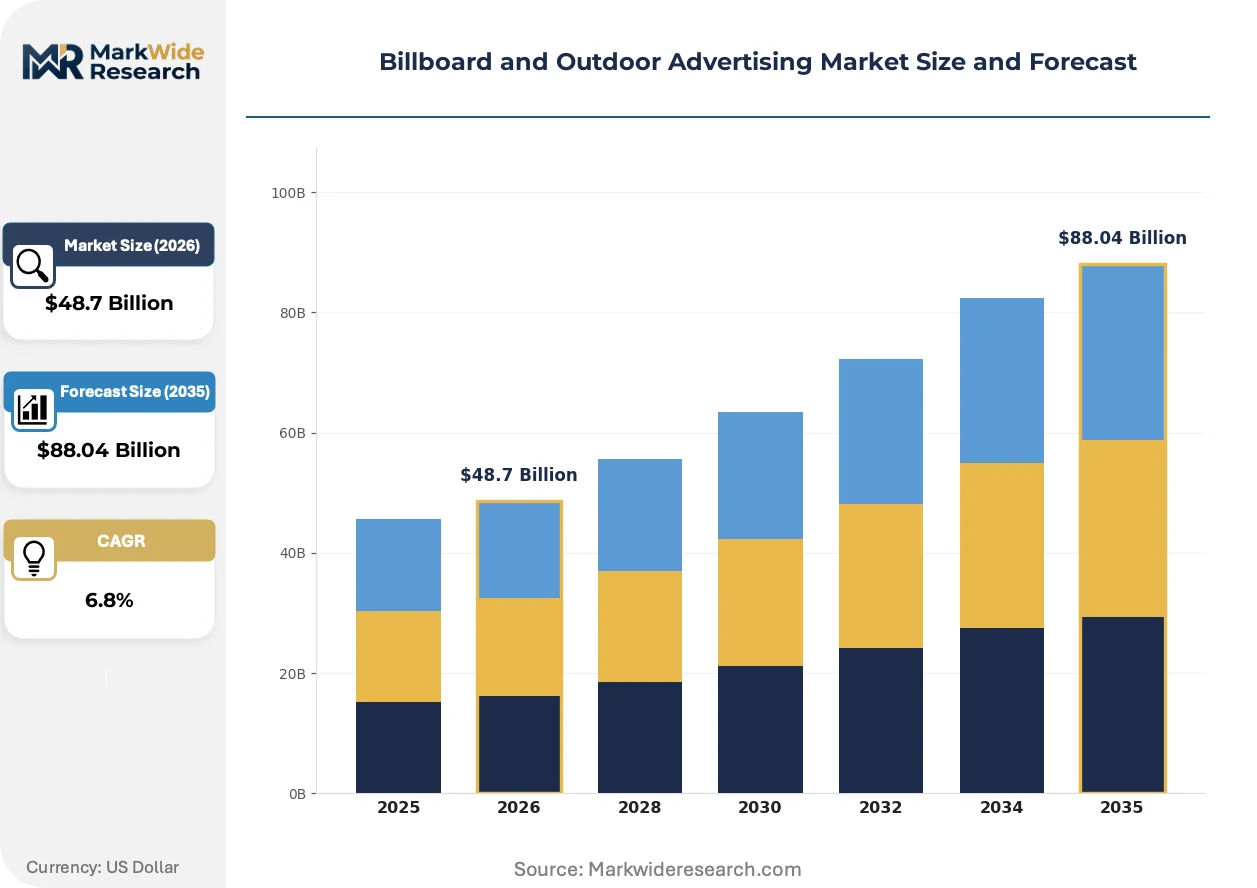
| Market Size in 2026 | $48.7 Billion |
| Market Size in 2035 | $88.04 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Advertising Medium: Billboards, Transit Advertising, Street Furniture, Digital Displays End User: Retailers, Automotive Brands, FMCG Companies, Entertainment Type: Outdoor, Indoor, Digital, Static Deployment Method: On-premise, Third-party, Managed Services, Self-serve |
| Companies Covered | Outfront Media, Focus Media, JCDecaux, oOh! media, Global, Clear Channel Outdoor, Ströer, Pattison Outdoor, Lamar Advertising, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Billboard and Outdoor Advertising Market Emerging Trajectories
Programmatic infrastructure is dissolving the boundary between outdoor and digital media buying, forcing operators to adopt audience measurement tools and dynamic creative capabilities that match online advertising precision.
Pixel-dense LED modules with sub-6mm pitch are expanding into premium urban roadside and transit environments where pedestrian proximity demands visual clarity. Luxury and technology advertisers now specify these formats for brand safety and creative impact. The technology is expanding into territory previously dominated by static premium placements, compressing the addressable market for vinyl superstructures.
The EU F-Gas Regulation and Germany's national energy codes are tightening operational efficiency standards for digital display cooling and power systems. Operators must now engineer thermal management into new installations rather than retrofitting compliance. Transit authorities in Paris and Berlin are embedding these requirements into concession tender specifications, favoring vendors with pre-certified hardware portfolios.
Media buyers are consolidating outdoor spend through demand-side platforms that aggregate inventory across competing operators. Direct sales teams lose share to automated buying workflows that optimize reach and frequency across fragmented screen networks. This consolidation is most visible in North American and Western European markets where advertiser procurement functions have centralized under holding company structures.
Billboard and Outdoor Advertising Market Segmentation
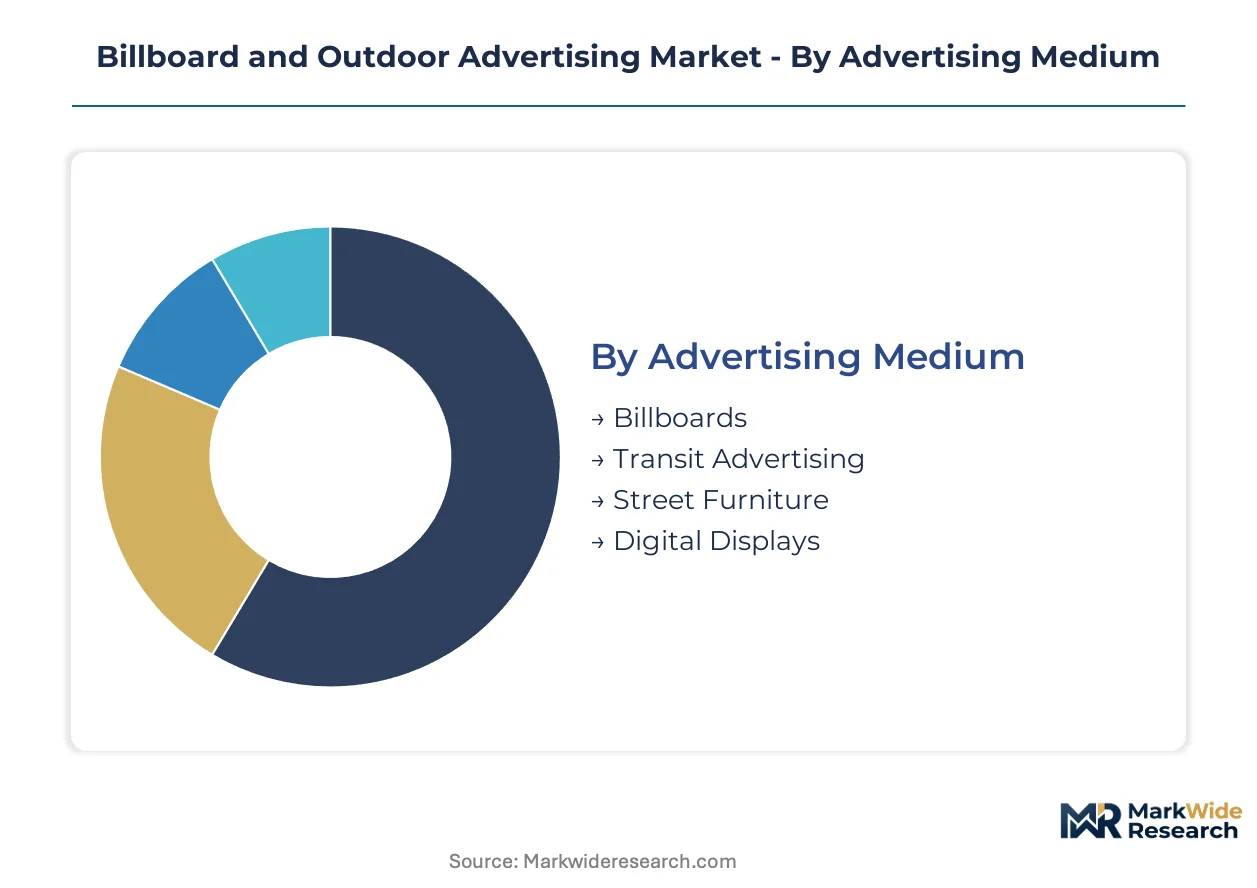
Segmentation in billboard and outdoor advertising reveals divergent capital requirements, concession structures, and technology refresh cycles. Operators must match portfolio composition to municipal contract timelines and advertiser procurement preferences.
Advertising Medium:
Capital intensity varies dramatically across physical formats, with digital infrastructure demanding 10-15x the upfront investment of static equivalents.
- Billboards:Large-format roadside structures employ vinyl wraps or LED arrays positioned along interstate corridors and urban arterials. São Paulo-Rio de Janeiro concession renewals prioritize operators with connected digital capabilities along this corridor.
- Transit Advertising:Interior and exterior placements on buses, rail cars, and station infrastructure. JCDecaux anchors European volume through long-term agreements with Paris, London, and Berlin transport authorities.
- Street Furniture:Bus shelters, kiosks, and public seating with integrated display surfaces. Stable margins derive from exclusive municipal contracts that limit competitive entry in dense urban cores.
- Digital Displays:Programmable LED screens enabling real-time creative rotation and audience-targeted delivery. EU Green Deal efficiency mandates are accelerating LED retrofit timelines across Germany and France.
Billboards absorb the bulk of installed capacity; digital displays are expanding most quickly.
End User:
Buyer concentration patterns reflect sector-specific campaign cycles and brand safety requirements.
- Retailers:Seasonal promotional calendars drive demand for high-frequency creative rotation near point-of-sale locations. Grocery and fashion advertisers prioritize programmatic inventory for flash sale activation.
- Automotive Brands:Long purchase cycles favor sustained awareness campaigns along interstate corridors targeting commuter demographics. Premium pixel-dense formats command specification for brand safety considerations.
- FMCG Companies:Mass-market reach objectives align with transit and street furniture networks in dense metropolitan zones. Procurement functions increasingly consolidate spend through demand-side platforms.
- Entertainment:Compressed release windows require rapid campaign deployment across fragmented screen networks. Studio advertisers specify dynamic creative capabilities for day-and-date activation.
Automotive brands commit the longest contract durations; entertainment buyers are driving fastest adoption of programmatic workflows.
Type:
Technology maturity and regulatory exposure create distinct operational profiles across format categories.
- Outdoor:Public-space placements subject to municipal zoning and federal highway spacing regulations. US Federal Highway Administration constraints under the Highway Beautification Act limit inventory growth along federally funded roadways.
- Indoor:Captive-audience environments including airports, malls, and transit terminals. Higher CPMs reflect dwell-time advantages and reduced competitive clutter.
- Digital:Programmatic-enabled screens with real-time content management and audience measurement integration. China's MIIT and SAMR jointly oversee content review and network security protocols.
- Static:Vinyl and paper-based displays with fixed creative periods and lower maintenance overhead. Rural interstate corridors retain volume leadership where digital conversion economics remain unfavorable.
Static inventory retains the largest installed base; digital formats are climbing the fastest on revenue contribution.
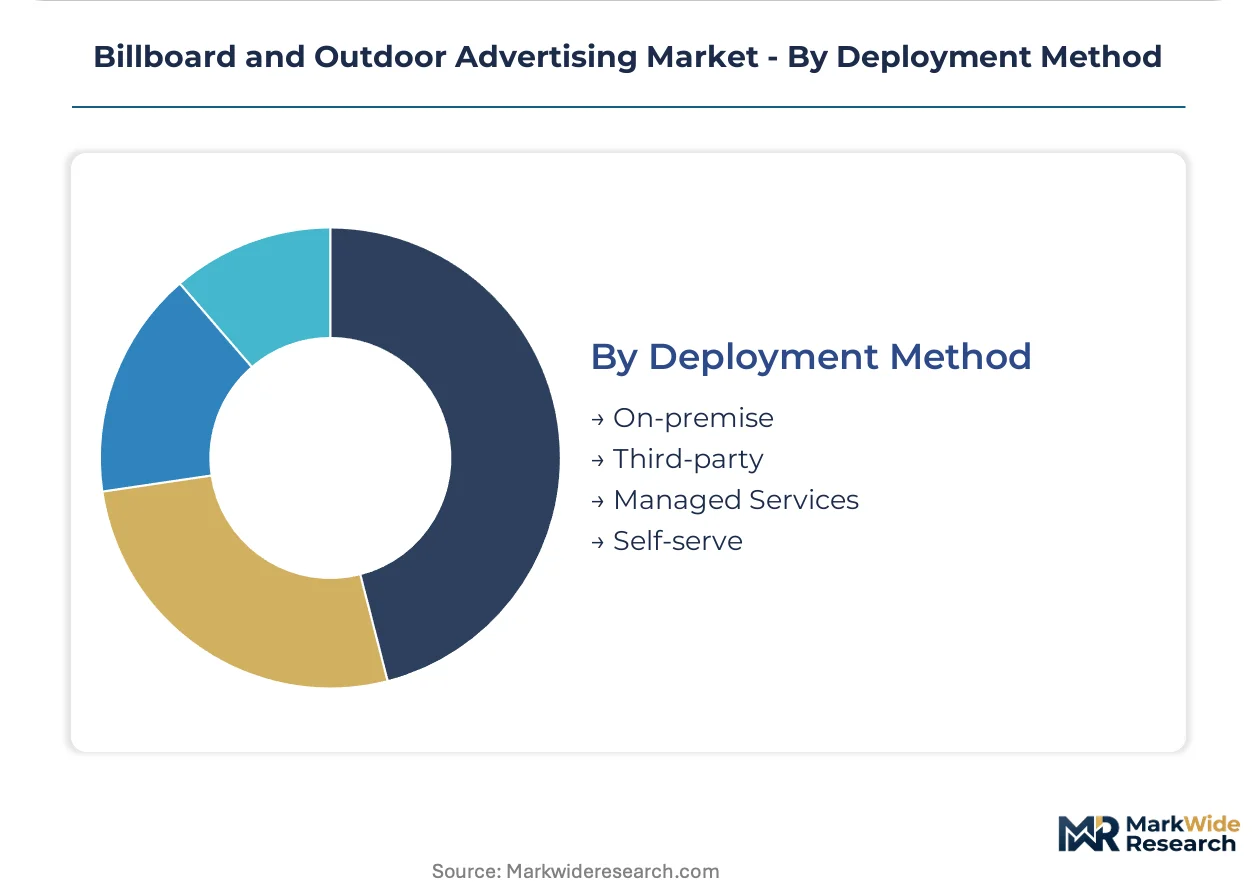
Deployment Method:
Service model selection determines capital deployment timing and recurring revenue predictability.
- On-premise:Advertiser-owned installations on private property, common for automotive dealerships and retail anchors. Direct control over creative scheduling offsets higher capital burden.
- Third-party:Inventory leased from independent operators under fixed-term agreements. Flexibility for campaign testing without long-term infrastructure commitment.
- Managed Services:Full-service packages encompassing creative production, media planning, and performance reporting. Appeals to mid-market advertisers lacking in-house programmatic expertise.
- Self-serve:Platform-based buying tools enabling direct campaign execution without sales team intermediation. Consolidation through demand-side platforms is compressing traditional direct-sales margins.
Third-party deployment captures the majority of transaction volume; self-serve platforms are gaining share fastest among digitally mature advertisers.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Aluminum and steel fabrication clusters in the US Midwest supply structural components for billboard infrastructure across North American interstate corridors. Regional demand patterns diverge sharply between mature digital markets and vinyl-dependent rural networks.
United States
The Federal Highway Administration enforces spacing standards under the Highway Beautification Act, constraining new inventory along federally funded roadways. Lamar Advertising leverages land-bank positions across Sun Belt interstate corridors to sustain premium roadside placements. State DOTs in Texas and Florida are processing permit backlogs that delay digital conversion timelines.
Germany
National energy codes and the EU F-Gas Regulation are tightening efficiency standards for digital display cooling systems. Ströer operates street furniture networks under long-term municipal contracts in Berlin and Hamburg. Transit authorities in the Rhine-Ruhr corridor are embedding LED compliance requirements into concession tender specifications.
China
MIIT and SAMR jointly oversee content review and network security protocols for programmatic display systems. Focus Media anchors urban digital inventory in Shanghai and Beijing through elevator and commercial building networks. Manufacturing clusters in Guangdong Province produce LED modules for domestic installation and export markets.
Brazil
Municipal concession renewals in the São Paulo-Rio de Janeiro corridor favor operators with connected screen networks and dynamic content capabilities. ANVISA regulates advertising content for pharmaceutical and health-related campaigns. Secondary highways connecting São Paulo to regional manufacturing centers present underpenetrated bidding opportunities.
United Kingdom
Transport for London maintains exclusive concession frameworks for transit advertising across the Underground and bus networks. Clear Channel Outdoor competes on programmatic digital inventory connecting roadside screens to demand-side platforms. JCDecaux anchors national volume through long-term agreements with Transport for London and regional transit authorities.
Billboard and Outdoor Advertising Market Vendor Landscape
Global majors compete with regional champions across concession-based infrastructure networks, creating a tiered structure where scale advantages clash with local regulatory relationships. The vendor base separates into three archetypes: land-bank aggregators holding premium real estate positions, transit concession specialists with municipal exclusivity, and programmatic platform operators connecting dispersed inventory to automated buying systems. Dominant competitive moves include concession renewal bidding synchronized with LED compliance upgrades, and strategic partnerships integrating 5G connectivity into screen networks.
Within the land-bank aggregator tier, Lamar Advertising exemplifies the North American model of securing interstate corridor positions, while JCDecaux occupies a parallel position in European transit infrastructure. Among Asia-Pacific platform operators, Focus Media represents the commercial building and elevator network specialization that dominates urban Chinese inventory.
| Leading Market Players |
|---|
| Outfront Media |
| Focus Media |
| JCDecaux |
| oOh! media |
| Global |
| Clear Channel Outdoor |
| Ströer |
| Pattison Outdoor |
| Lamar Advertising |
| Others |
Supply Flow & Price Mechanics
Aluminum LME spot pricing cascades through billboard fabrication tiers, compressing margins for vinyl-static operators while LED module manufacturers pass through East Asian component costs to programmatic digital networks.
Pricing Analysis
Warranty and maintenance bundling separates premium digital operators from unbundled static vendors, with full-service packages covering LED thermal management and real-time content support commanding sustained premiums. Three-tier pricing structure across premium pixel-dense urban placements, standard highway digital, and economy rural vinyl reflects certification grade and after-sales depth. Cost compression in static inventory is intensifying because municipal concession renewals favor connected screen networks. Retail and entertainment buyers exhibit highest price sensitivity due to compressed campaign windows, while automotive brands accept premium positioning for brand safety assurance.
Supply Chain Analysis
Regional distribution centers in Guangdong Province, South Korea, and Taiwan anchor hub-and-spoke patterns for LED module delivery to North American and European assembly facilities. Display production draws from gallium nitride substrates, aluminum structural extrusions, and copper power cabling. Single-source vulnerability concentrates in advanced LED driver IC fabrication. Distribution runs through operator-managed installation fleets rather than third-party logistics, reflecting the specialized rigging requirements for large-format roadside structures.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Consolidation pressure from programmatic platform mandates will force out operators lacking data science capacity or SSP integration capabilities.
For Market Incumbents: Deepen vertical integration into LED module refurbishment and thermal engineering to capture EU F-Gas compliance upgrade cycles. Secure concession renewals in São Paulo-Rio de Janeiro corridor ahead of LED retrofit deadlines. Threat from demand-side platform consolidation favors operators with pre-certified hardware portfolios.
For New Entrants and Emerging Players: 5G-connected screen networks offer a technology-first wedge into underpenetrated secondary highways linking São Paulo to regional manufacturing centers. Target partially analog street furniture networks in Paris and London where municipal contracts limit incumbent expansion. Go-to-market through self-serve programmatic platforms bypasses direct sales team requirements.
For Investors and Strategic Acquirers: Distressed-cycle entries favor land-bank aggregators with premium interstate corridor positions in Texas and Florida. Long-term viability hinges on concession renewal timelines synchronized with LED compliance mandates. Watch municipal tender specifications embedding energy efficiency requirements as inflection signal for replacement demand acceleration.
| Strategic Initiative | Industry Significance |
|---|---|
| LED Retrofit Program Acceleration | EU F-Gas Regulation and Germany energy codes force cooling system upgrades across European digital networks. |
| Programmatic Platform Integration | SSP-DSP connectivity collapses direct sales cycles and fragments buyer concentration across roadside inventory. |
| 5G Network Infrastructure Partnership | Cellular convergence enables real-time creative rotation and audience measurement for transit authorities. |
| Concession Renewal Bidding Synchronization | Municipal contract cycles in Brazil and Germany align with LED compliance capex requirements. |
| Street Furniture Digitalization | Bus shelter and kiosk retrofit captures white space under exclusive Paris, London, and Berlin municipal contracts. |
Methodological Framework
Independent corroboration across municipal transit authority procurement officers, outdoor advertising operations directors, and LED display manufacturing engineers underwrites the qualitative findings. Primary fieldwork with programmatic platform engineers and media buying agency executives combined with secondary validation against US Federal Highway Administration permit databases, EU concession tender publications, and China MIIT content review protocols. Bottom-up triangulation of installed base counts with top-down revenue estimates anchors the market sizing.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include advertising medium, deployment method, end-user industry, and regional regulatory cluster. CAGRs derive from logistic diffusion curves applied to digital penetration rates and static replacement cycles. Forecast inputs incorporate LED component cost trajectories and municipal concession renewal timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under tariff escalation on East Asian display modules or accelerated EU energy code enforcement. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advertising and Marketing Media
Asia-Pacific Marketing Agencies Market
Advertising and Marketing Media
United States Public Relation Services Market
Advertising and Marketing Media
Argentina OOH and DOOH Market
Advertising and Marketing Media
Indonesia Digital Advertising Market
Advertising and Marketing Media
United Kingdom OOH and DOOH Market
Advertising and Marketing Media
Global Advertising Software Market
Advertising and Marketing Media
Magazine Advertising Market
Advertising and Marketing Media
Mobile Advertising Market
Advertising and Marketing Media
Italy OOH and DOOH Market
Advertising and Marketing Media
Nigeria OOH and DOOH Market
Advertising and Marketing Media
ASEAN OOH and DOOH Market
Advertising and Marketing Media
In-Game Advertising Market
Advertising and Marketing Media
Social Media Advertisement Market
Advertising and Marketing Media
Teleshopping Market
Advertising and Marketing Media
In-App Advertising Market
Advertising and Marketing Media
Global Social Advertising and Social Media Market