
 Reconstituted Meat Market | 2026-2036
Reconstituted Meat Market Size, Share, and Industry Trends Forecast 2026-2036
Reconstituted Meat Market Analytics
The gap between premium whole-muscle reconstituted products and commodity-grade ground formats is shifting procurement priorities across the value chain. Tyson Foods leverages its integrated poultry supply base to control input costs for reformed product lines. Marfrig anchors its South American operations with large-scale beef trimming and binding capabilities for export markets. JBS S.A. differentiates through vertical integration into collagen and protein extraction for texture optimization.
Reconstituted meat denotes processed protein products manufactured from comminuted muscle tissue, non-meat binders, and functional additives, typically containing 60-85% meat content and restructured through mechanical or enzymatic means to emulate whole-muscle integrity. The primary commercial purpose centers on delivering standardized portion control, yield optimization, and cost predictability for foodservice and retail channels. Extruded formats dominate volume production due to throughput efficiency, while hybrid segments capture margin expansion as brands blend animal and plant proteins to meet clean-label expectations. High-pressure processing leads technology adoption for pathogen reduction without thermal degradation, though 3D printing occupies niche positioning in premium foodservice trials.
FDA oversight of meat and poultry products in the United States enforces composition standards that directly shape permissible protein content claims and binder ratios. The EU Green Deal and EFSA nutrition profiling constrain reformulation options while creating compliance costs for exporters. USDA grade specifications and FSIS labeling rules further segment market access between domestic and import-oriented suppliers. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate reformulation investments and certification requirements.
Market Dynamics
Foodservice labor cost inflation across North America and Europe is accelerating adoption of pre-portioned reconstituted proteins that reduce kitchen preparation time and skill requirements. This operational pressure is restructuring procurement relationships between institutional buyers and meat processors.
Growth Catalysts
- EU Green Deal Farm to Fork Strategy:Sustainability labeling mandates are creating compliant product categories that command shelf space in German and French retail chains. Processors reformulating to meet these thresholds capture preferential listing agreements.
- High-Pressure Processing (HPP):Cold pasteurization technology eliminates thermal degradation of protein matrices while achieving log-reduction pathogen standards. Foodservice distributors are specifying HPP-treated products for hospital and school nutrition contracts.
- Hybrid Protein Formats:Blended animal-plant reconstituted products are securing placement in European retail premium tiers. These formulations address clean-label expectations while maintaining cost structures accessible to mainstream consumers.
Market Restraints
- Collagen and Binder Input Volatility:Industrial gelatin and modified starch prices fluctuate with tannery byproduct availability and grain commodity cycles. Reformulation to reduce binder dependence requires capital-intensive extrusion equipment upgrades.
- South American Beef Trimming Concentration:Export-grade beef raw material for reconstitution concentrates in Brazilian and Argentine slaughterhouse networks. Geopolitical trade friction or sanitary restrictions disrupt supply continuity for European and Asian processors.
- Clean-Label Technical Ceiling:Consumer rejection of phosphate additives and synthetic binders limits water-holding capacity in reduced-salt formulations. Product developers face texture degradation when removing these functional ingredients.
Strategic Opportunities
- India Foodservice Penetration:Quick-service restaurant chains in Mumbai and Delhi are piloting reconstituted chicken products for standardized portioning. Local poultry processors lack binding and restructuring capabilities, creating partnership entry points for technology licensors.
- Cellular Agriculture Convergence:Cultivated muscle fiber scaffolding combined with plant protein binders is emerging in Singapore and Netherlands regulatory sandboxes. Hybrid products using this architecture may bypass conventional slaughter-dependent supply chains.
- Direct-to-Institution E-Procurement:Digital platforms connecting meat processors to hospital and corporate cafeteria operators are disintermediating traditional broadline distributors. These channels enable custom specification of protein content and portion weights.
Industry Challenges
- Protein Extraction Technologist Scarcity:Enzymatic hydrolysis and shear-cell processing require specialized food engineering expertise that outpaces university program output. Processors compete for limited talent pools in Netherlands, Denmark, and Wisconsin clusters.
- Dual Jurisdiction Certification Timelines:Simultaneous USDA and EFSA approval for novel binding systems extends product development cycles by 18-24 months. Synchronized regulatory submissions demand dedicated compliance infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Reconstituted Meat Market |
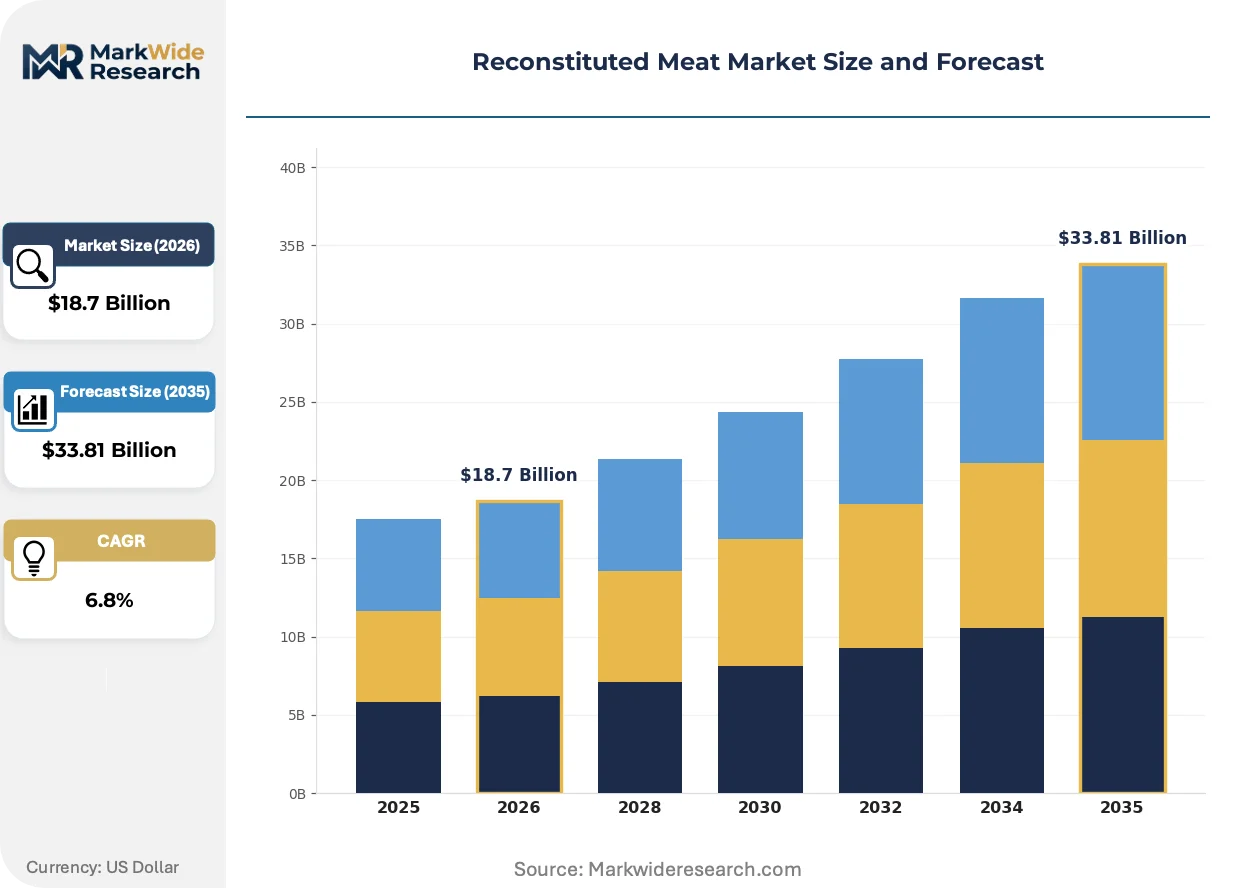
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $33.81 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Plant-Based, Extruded, Reformed, Hybrid End User: Foodservice, Retail, Wholesale, Direct-to-Consumer Processing Technology: High-Pressure Processing, 3D Printing, Texturing, Fermentation Form: Patty, Sausage, Nuggets, Fillet |
| Companies Covered | Marfrig, Danish Crown, Tyson Foods, Olymel, Maple Leaf Foods, Cargill, Vion Food Group, Givaudan, JBS S.A., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Reconstituted Meat Market Evolving Landscape
Reconstituted meat processing is experiencing technology-driven fragmentation of production scale, with distributed manufacturing systems challenging centralized plant economics. These shifts are compressing the viable minimum efficient scale for protein restructuring operations.
Shear-cell extrusion technology is decentralizing reconstituted meat production by enabling continuous protein texturization at throughput rates previously achievable only in industrial-scale facilities. Mid-sized regional processors in Spain and Poland are installing these systems to serve foodservice accounts with shorter lead times. This diffusion is compressing the geographic radius of economically viable supply, reducing transportation cost exposure for perishable intermediate products.
EFSA nutrition profiling regulations under the EU Green Deal are restricting permissible sodium and saturated fat content in processed meat products sold to schools and public institutions. Reformulation to meet these thresholds requires replacement of traditional phosphate binders with alternative hydrocolloid systems. German and Dutch processors are investing most heavily in compliant product lines, anticipating mandatory adoption timelines that lag in Southern European markets.
Specification-driven procurement by contract foodservice management companies is displacing traditional spot-market purchasing for reconstituted proteins. Sodexo and Compass Group operators in France and the United Kingdom are consolidating supplier relationships around processors capable of delivering batch-level traceability documentation. This concentration is most visible in hospital and aged-care nutrition contracts where allergen control and portion standardization carry liability weight.
Reconstituted Meat Market Segmentation
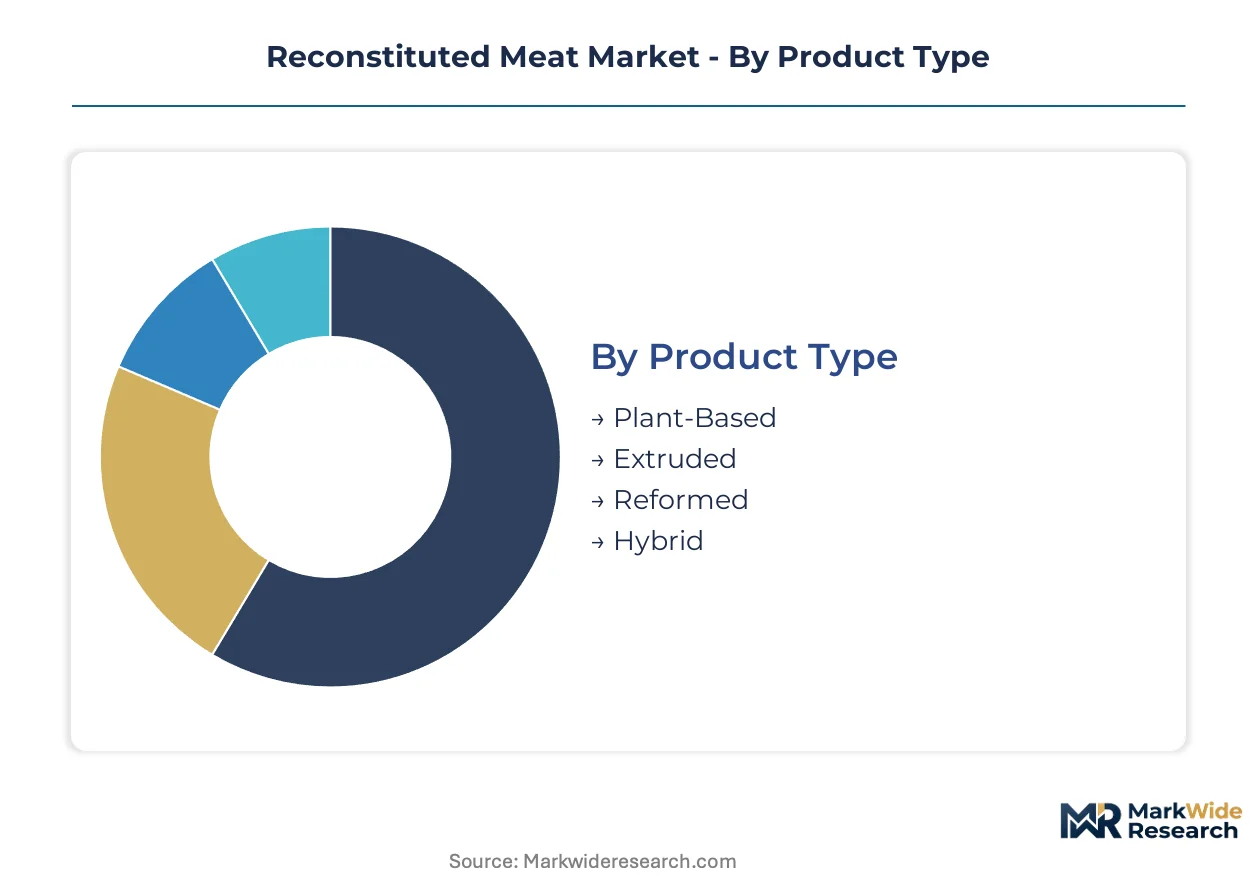
Reconstituted meat segmentation reflects divergent buyer priorities across cost predictability, portion standardization, and clean-label positioning. Procurement patterns vary sharply between institutional foodservice operators seeking yield optimization and retail chains prioritizing ingredient transparency.
Product Type:
Cost tier and margin structure separate buyers in this category, with premium formats commanding specification-driven procurement while commodity grades compete on throughput efficiency.
- Extruded:Continuous mechanical texturization of comminuted muscle tissue achieves throughput rates exceeding 5,000 kg per hour in industrial configurations. German and Polish processors dominate European foodservice supply contracts for this format, driven by hospital and school nutrition procurement specifications demanding pathogen log-reduction documentation.
- Hybrid:Blended animal-plant protein matrices incorporate 20-40% plant-derived binders to reduce saturated fat content while maintaining texture integrity. French and German retail chains are scaling shelf space for these formulations ahead of anticipated EU Green Deal nutrition profiling enforcement timelines.
- Plant-Based:Fully denatured protein reconstitution without animal tissue input targets vegan certification requirements in Netherlands and UK foodservice channels.
- Reformed:Sectioned and formed whole-muscle pieces bound with collagen or alginate systems serve premium foodservice accounts requiring knife-and-fork presentation standards.
Volume sits with Extruded; growth tilts toward Hybrid.
End User:
Application environment dictates specification intensity, with institutional contracts demanding batch traceability while retail channels prioritize shelf-life extension.
- Foodservice:Contract management companies including Sodexo and Compass Group operators in France and the United Kingdom specify protein content tolerances of ±2% and portion weight standardization within 5-gram bands. These procurement relationships now require HACCP documentation at the production batch level, displacing spot-market purchasing for reconstituted proteins.
- Retail:Supermarket private-label programs in Germany and Spain are consolidating supplier bases around processors capable of delivering clean-label ingredient declarations without phosphate additives. Reformulation to meet these specifications compresses water-holding capacity, requiring alternative hydrocolloid systems at 15-25% cost premium.
- Wholesale:Broadline distributors serving independent restaurants and catering operations purchase standard-grade extruded formats with minimal specification layering.
- Direct-to-Consumer:Subscription meal-kit providers in Netherlands and UK pilot premium reformed products with batch-level provenance documentation.
Procurement concentration favors Foodservice; margin expansion is steepest in Retail.
Processing Technology:
Capital intensity and technical talent availability constrain adoption curves, with cold pasteurization requiring specialized equipment while enzymatic methods demand scarce food engineering expertise.
- High-Pressure Processing:Isostatic pressure treatment at 400-600 MPa achieves 5-log pathogen reduction without thermal protein denaturation. Foodservice distributors in Germany and France now specify HPP-treated products for hospital and aged-care nutrition contracts where immunocompromised consumer protection carries liability weight.
- Texturing:Shear-cell and extrusion-cooking systems enable continuous protein restructuring at capital costs 60-70% below HPP installations. Mid-sized regional processors in Spain and Poland are deploying these systems to serve foodservice accounts with lead times under 72 hours, compressing the economically viable supply radius for perishable intermediates.
- 3D Printing:Layer-by-layer deposition of protein pastes with precision fat marbling occupies niche positioning in premium foodservice trials in Netherlands and Singapore regulatory sandboxes.
- Fermentation:Microbial protein enhancement of reconstituted matrices remains pre-commercial, with pilot-scale operations in Denmark targeting mycoprotein integration for hybrid product lines.
Installed base concentrates in Texturing; capability investment flows toward High-Pressure Processing.
Form:
Portion geometry determines binding system selection and cooking loss tolerance, with flat formats allowing higher moisture content than three-dimensional shapes.
- Patty:Flat, uniform-thickness portions dominate quick-service restaurant procurement in North America and European fast-casual channels. Standardized diameter and weight specifications enable automated grilling equipment compatibility, with 80-85% meat content formulations most common in US foodservice.
- Nuggets:Battered and breaded three-dimensional forms require structural integrity through freeze-thaw cycles. German processors lead European supply for school nutrition programs, with phosphate-free binding systems now mandatory in several federal state tenders.
- Sausage:Cased or skinless cylindrical formats incorporate higher fat retention and emulsion stability requirements.
- Fillet:Whole-muscle emulation products command premium positioning in UK and French retail premium tiers.
Throughput volume clusters in Patty; specification intensity peaks with Nuggets.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Düsseldorf anchors European reconstituted meat processing, with German industrial clusters driving formulation standards that cascade across neighboring markets. Foodservice procurement concentration in the Rhineland shapes continental supply chain configurations.
United States
Quick-service restaurant chains in Chicago and Dallas-Fort Worth metro areas drive standardized patty procurement at scale. FDA and USDA FSIS labeling rules enforce protein content disclosure thresholds that constrain binder ratio flexibility. Tyson Foods maintains integrated poultry supply operations across Arkansas and Texas to serve reformed product lines.
Germany
Retail chains in Berlin and Hamburg are scaling hybrid-format shelf space ahead of EU Green Deal enforcement timelines. EFSA nutrition profiling under the Farm to Fork strategy restricts sodium and saturated fat thresholds for school nutrition tenders. The Ruhr industrial corridor hosts extrusion equipment clusters serving hospital and aged-care contract specifications.
Brazil
Beef trimming concentration in São Paulo and Mato Grosso slaughterhouse networks supplies export-grade raw material for European and Asian processors. ANVISA sanitary regulations align with EU import standards, though geopolitical friction periodically disrupts trade continuity. Marfrig anchors large-scale binding and restructuring capabilities for international markets from southern operations.
Netherlands
Foodservice distributors in Rotterdam and Amsterdam specify high-pressure processed products for immunocompromised consumer protection in healthcare contracts. EFSA compliance infrastructure enables synchronized regulatory submissions for novel binding systems. Wageningen University clusters supply scarce protein extraction technologists to regional processors.
India
Quick-service restaurant pilots in Mumbai and Delhi are testing reconstituted chicken products for portion standardization. FSSAI processed food regulations govern additive permissibility and labeling claims for hybrid formulations. Local poultry processors lack binding capabilities, creating partnership entry points for technology licensors in Bangalore and Hyderabad.
Reconstituted Meat Market Competitive Landscape
Premium-margin players sit above commodity-margin players across formulation sophistication and clean-label certification depth. The vendor base clusters around three strategic archetypes: integrated protein processors controlling upstream supply, specialized restructuring technology licensors, and hybrid-format innovators bridging animal-plant boundaries. Dominant competitive moves include backward integration into collagen extraction and strategic partnerships for enzymatic binding system access.
Among North American processors, Tyson Foods and Cargill occupy positions spanning integrated supply control and foodservice contract scale. JBS S.A. represents the South American archetype with export-oriented beef trimming concentration. Danish Crown exemplifies European cooperative structures with retail private-label penetration and EFSA compliance infrastructure.
| Leading Market Players |
|---|
| Marfrig |
| Danish Crown |
| Tyson Foods |
| Olymel |
| Maple Leaf Foods |
| Cargill |
| Vion Food Group |
| Givaudan |
| JBS S.A. |
| Others |
Value Network & Pricing Analysis
Beef trimming and collagen input costs cascade through three distinct pricing tiers, with Brazilian slaughterhouse networks and European tannery byproduct availability setting the floor for commodity-grade extruded formats while German hybrid products command shelf-space premiums under EU Green Deal compliance thresholds.
Pricing Analysis
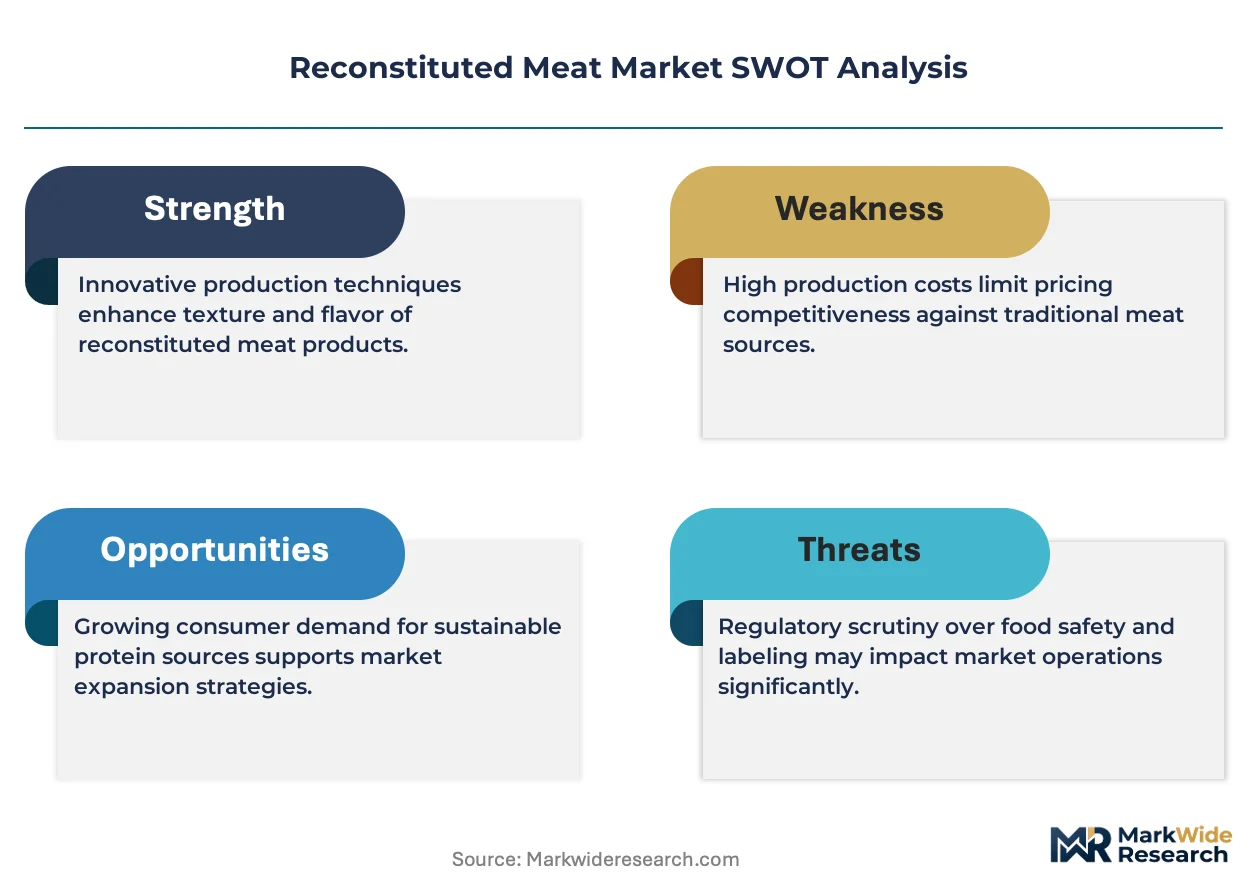
Yield-per-kilogram throughput anchors value-based pricing for foodservice contract buyers, with protein content tolerances of ±2% and portion standardization within 5-gram bands differentiating premium reformed products from commodity extruded formats. Pricing stratifies across premium, standard, and economy tiers based on clean-label certification depth and HPP treatment documentation. Cost compression in standard-grade segments is intensifying because phosphate-free reformulation requires 15-25% cost premium alternative hydrocolloid systems. Institutional buyers in hospital and school nutrition channels exhibit lowest price sensitivity due to liability-weighted procurement specifications, while independent restaurant operators through broadline distributors show highest elasticity.
Supply Chain Analysis
Regional distribution centers in Düsseldorf, Rotterdam, and Chicago operate hub-and-spoke patterns serving foodservice accounts with 72-hour lead time requirements. Supply concentrates in Brazil, Germany, and Poland, with São Paulo and Mato Grosso slaughterhouse networks feeding export-grade beef raw material to European processors. Raw material dependencies rest on tannery-derived industrial gelatin, modified starch from grain commodity cycles, and poultry trimmings from integrated processors. Single-source vulnerability in South American beef trimming concentration creates structural risk from geopolitical trade friction or sanitary restrictions. Distribution runs through contract foodservice management companies consolidating supplier relationships around batch-level traceability documentation.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race, with players pursuing backward integration into collagen extraction and captive poultry supply bases to control input cost volatility for reformed product lines.
For Market Incumbents: Anticipate EFSA nutrition profiling enforcement timelines by accelerating phosphate-free reformulation investment ahead of mandatory adoption windows. Consolidate supplier relationships around HPP-treated product specifications for hospital and aged-care contracts where immunocompromised consumer protection carries liability weight. Threat substitution from cellular agriculture scaffolding in Singapore and Netherlands regulatory sandboxes demands enzymatic binding system R&D partnerships to maintain texture integrity in next-generation hybrid formats. For New Entrants and Emerging Players: The price-point gap between premium reformed fillet products and economy-grade extruded formats creates entry space for mid-tier hybrid formats in French and German retail chains scaling shelf space ahead of EU Green Deal enforcement. White-space targets include India foodservice penetration where local poultry processors lack binding capabilities, and direct-to-institution e-procurement platforms disintermediating traditional broadline distributors. Go-to-market angle should emphasize technology licensing partnerships with Bangalore and Hyderabad processors rather than greenfield capacity buildout. For Investors and Strategic Acquirers: Simultaneous USDA and EFSA approval submissions for novel binding systems extending product development cycles by 18-24 months is the leading indicator that regulatory compliance infrastructure will separate viable acquisition targets from stranded assets. Long-term viability favors processors with dual-jurisdiction certification capabilities and shear-cell extrusion technology deployment in Spain and Poland regional markets. Acquisition target archetype: mid-sized European processors with EFSA compliance infrastructure and established hospital nutrition contract relationships. Signal to watch: batch-level traceability documentation becoming mandatory specification in Sodexo and Compass Group procurement tenders.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Collagen Extraction | Tyson Foods and JBS S.A. control tannery byproduct supply chains for binding system cost predictability. |
| High-Pressure Processing Capacity Expansion | German and Dutch processors secure preferential hospital and aged-care nutrition contract listings with HPP documentation. |
| Hybrid Format Product Line Launch | French and German retail chains capture clean-label positioning ahead of EU Green Deal nutrition profiling enforcement. |
| Technology Licensing Partnership | European equipment licensors access India foodservice penetration where local poultry processors lack binding capabilities. |
| Direct-to-Institution E-Procurement Platform | Digital platforms disintermediate broadline distributors for custom protein content and portion weight specifications. |
Research Methodology
USDA FSIS labeling filings, EFSA nutrition profiling documentation, and customs/trade data from Brazilian and German export records formed the secondary backbone, combined with primary interviews with protein extraction technologists, foodservice procurement managers at Sodexo and Compass Group operators, hospital nutrition directors, and retail category buyers at German and French chains. Bottom-up and top-down triangulation validated segment-level protein content and portion standardization specifications across foodservice and retail channels.
Bottom-up modeling anchored volume projections to installed extrusion and HPP equipment capacity across German, Polish, and Spanish processor facilities, while top-down analysis cross-checked against foodservice labor cost inflation trends and EU Green Deal compliance investment flows. Segmentation dimensions spanned product type, end user, processing technology, and form geometry. CAGRs were derived from trajectory analysis of hybrid format shelf space expansion and phosphate-free reformulation adoption curves, with inputs from shear-cell extrusion throughput rates and collagen input price volatility indices.
Inputs from USDA and EFSA regulatory filings were available through the study window; gaps in real-time tannery byproduct pricing and South American beef trimming export volumes introduce uncertainty bands around cost structure assumptions. Forecasts reflect documented protein content thresholds, pathogen reduction standards, and clean-label ingredient permissibility. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Meat Products
Chicken Buckets Market
Meat Products
United States Edible Meat Market
Meat Products
North America Processed Pork Meat Market
Meat Products
Saudi Arabia Edible Meat Market
Meat Products
Global Beef Market
Meat Products
Bahrain Poultry Meat Market
Meat Products
Bacon Market
Meat Products
Western Europe Ready-To-Eat Meat Market
Meat Products
Canned Pork Market
Meat Products
Global Edible Meat Market
Meat Products
Germany Meat Products Market
Meat Products
Asia-Pacific Processed Meat Market
Meat Products
Binders and Scaffolders for Meat and Meat Substitutes Market
Meat Products
Low Fat Beef Market
Meat Products
3D Printed Meat Market
Meat Products
Organic Eggs Market