
 Cyclohexylamine Market | 2026-2036
Cyclohexylamine Market Size, Share, and Industry Trends Forecast 2026-2036
Cyclohexylamine Market Analysis
Technical service contracts for corrosion inhibitor formulation is realigning how cyclohexylamine suppliers capture value beyond commodity volumes. BASF SE leverages its integrated amines platform to bundle application engineering with bulk supply, sustaining margin pools in European water treatment. Huntsman Corporation anchors North American demand through captive consumption into downstream rubber chemicals, while Shandong Yufeng Chemical Co., Ltd. competes on cost-advantaged cyclohexanone feedstock access in China's Shandong province.
Cyclohexylamine is a secondary aliphatic amine produced via catalytic hydrogenation of aniline or reductive amination of cyclohexanone, typically supplied at purity levels from 98.5 percent for industrial applications to 99.5 percent-plus for pharmaceutical synthesis; it functions primarily as a chemical intermediate for accelerators in rubber vulcanization, corrosion inhibitors in steam boiler systems, and precursor molecules for sulfenamide-class accelerators. Industrial grade material dominates volume throughput due to rubber chemical and agrochemical intermediate demand, while pharmaceutical grade commands premium pricing through CDMO qualification requirements and FDA-compliant documentation burdens. Agricultural chemicals application is expanding fastest among end-use categories as N-substituted cyclohexylamine derivatives gain registration for fungicide and herbicide synthesis in Brazil and India.
EPA oversight of boiler water treatment chemical discharge limits shapes North American product formulation standards, while REACH registration requirements under ECHA enforce full toxicological dossiers for European volume holders. China's MEE enforces dual carbon goals that pressure coal-based aniline feedstock routes, nudging producers toward cyclohexanone-derived pathways with lower carbon intensity. Stakeholders must monitor regulatory divergence between EU F-Gas Regulation analogs for process emissions and India's BIS certification timeline for imported amine specifications.
Market Dynamics
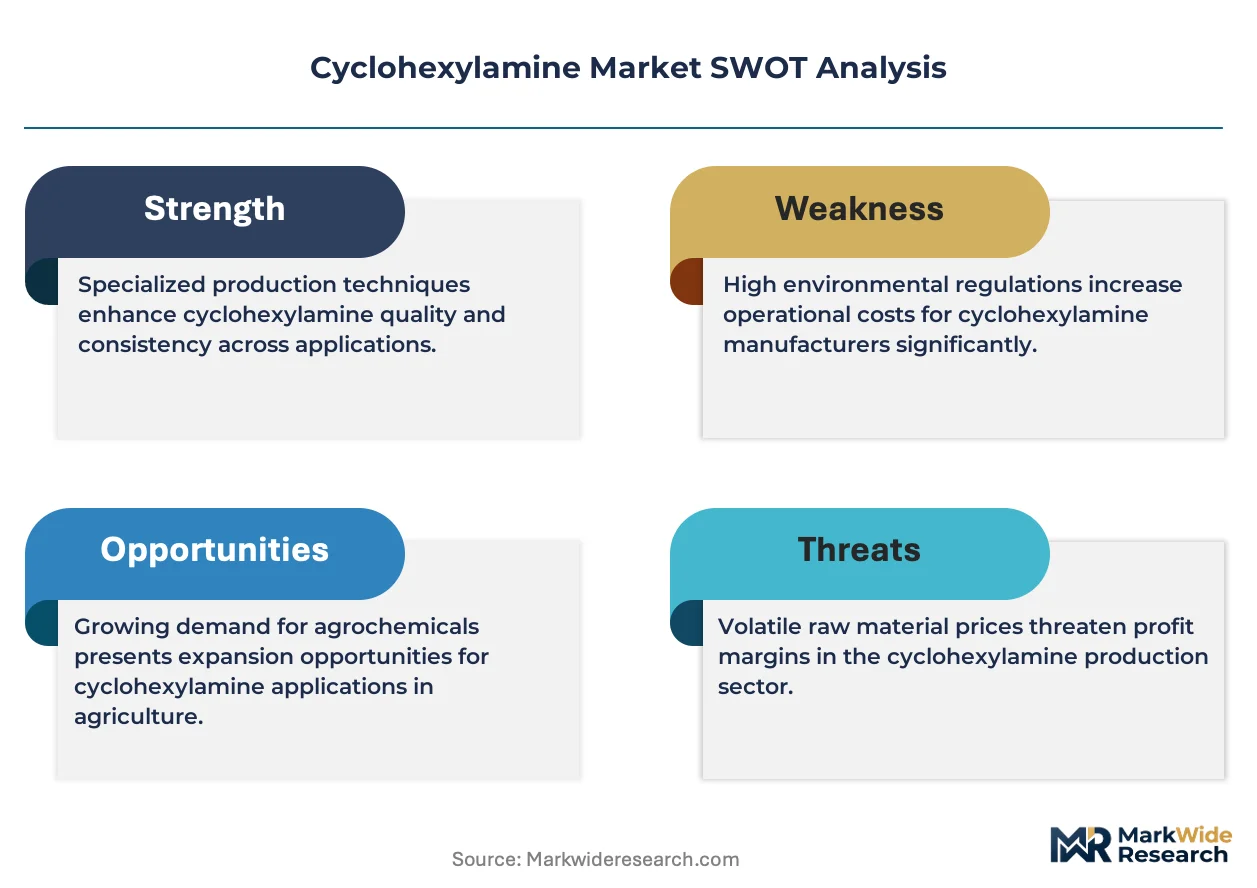
REACH-compliant corrosion inhibitor formulations are displacing legacy amine chemistries in European water treatment, forcing suppliers to requalify product lines and shifting procurement toward integrated technical service bundles.
Growth Catalysts
- REACH registration mandates:ECHA's full toxicological dossier requirements for volume holders are filtering out non-compliant producers, consolidating qualified supply positions for incumbent European registrants.
- Rubber accelerator demand:Tire manufacturers in East China's chemical corridor are scaling sulfenamide-class accelerator output, pulling cyclohexylamine through captive cyclohexanone-to-amine production clusters.
- Agricultural chemical expansion:N-substituted cyclohexylamine derivatives are gaining fungicide and herbicide registrations in Brazil and India, opening derivative synthesis pathways beyond traditional industrial applications.
Market Restraints
- Aniline feedstock volatility:Coal-based aniline routes face carbon intensity pressures under China's MEE dual carbon goals, elevating input cost uncertainty for hydrogenation-derived material.
- Shandong-Jiangsu supply concentration:Integrated production clusters in two Chinese provinces control disproportionate export volume, creating geographic single-point vulnerability for international buyers.
- Morpholine substitution:Alternative neutralizing amines in boiler water treatment are capturing specification share in North American utility procurement, compressing cyclohexylamine's traditional corrosion inhibitor position.
Strategic Opportunities
- Pharmaceutical CDMO qualification:FDA-compliant documentation and 99.5 percent-plus purity standards create defendable premium pricing tiers for qualified European and North American producers.
- Brazilian agrochemical registration:Underpenetrated fungicide intermediate demand offers first-mover positioning for suppliers with established ANVISA regulatory navigation capabilities.
- Technical service bundling:Application engineering contracts for corrosion inhibitor formulation allow margin capture beyond commodity volumes in European water treatment accounts.
Industry Challenges
- Dual carbon compliance timeline:China's MEE enforcement of carbon intensity benchmarks requires capital reconfiguration of coal-based hydrogenation assets toward cyclohexanone-derived pathways.
- CDMO qualification duration:Pharmaceutical-grade certification cycles span 18-24 months, locking working capital and technical resources before revenue recognition.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Cyclohexylamine Market |
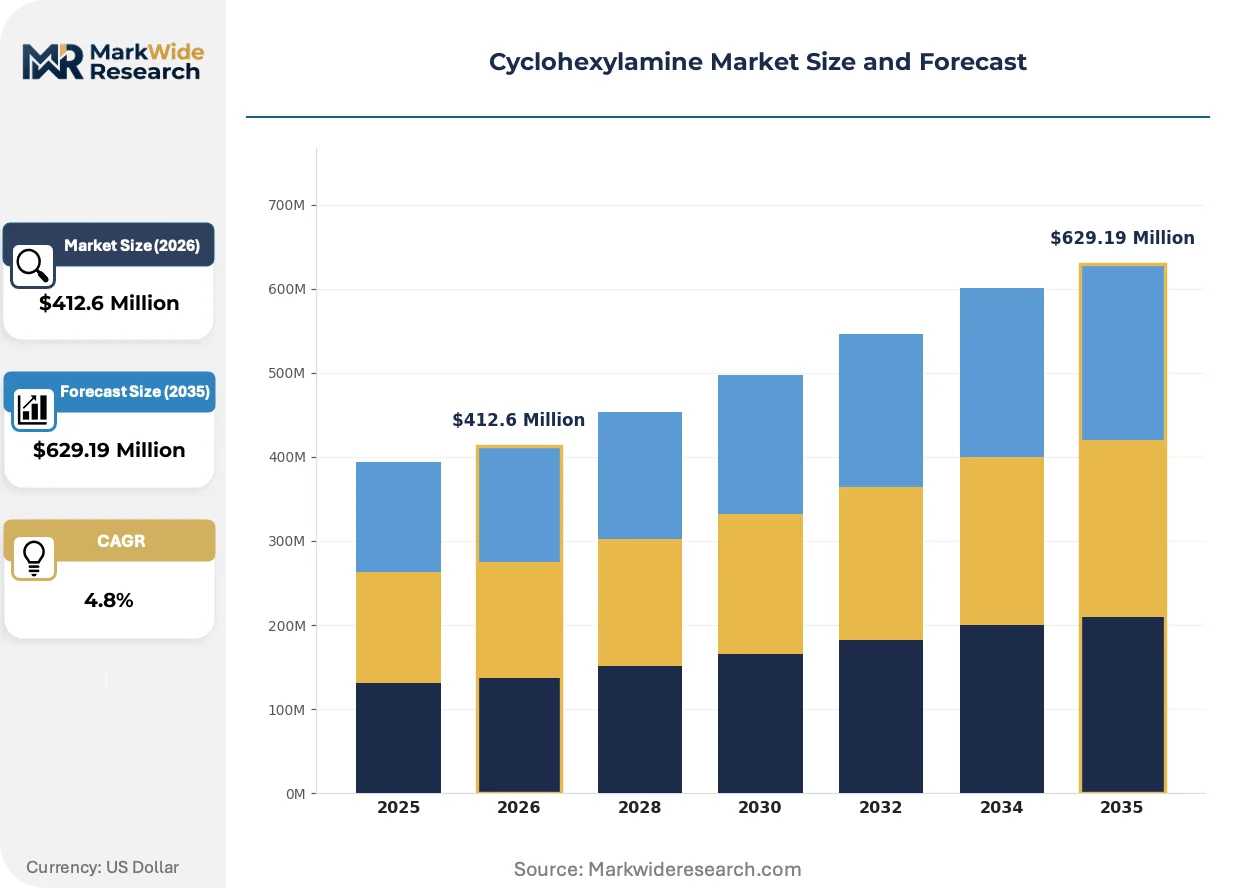
| Market Size in 2026 | $412.6 Million |
| Market Size in 2035 | $629.19 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Analytical Grade, Reagent Grade, Pharmaceutical Grade Application: Agricultural Chemicals, Pharmaceuticals, Dyes, Rubber Chemicals End User: Chemical Manufacturers, Pharmaceutical Companies, Agriculture Sector, Research Laboratories Distribution Channel: Direct Sales, Online Sales, Distributors, Wholesalers |
| Companies Covered | Aditya Birla Chemicals, Evonik Industries, BASF SE, Shandong Yufeng Chemical Co., Ltd., Alkyl Amines Chemicals Limited, Huntsman Corporation, LANXESS, Arkema Group, Eastman Chemical Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Cyclohexylamine Market Emerging Trajectories
Process chemistry optimization and regulatory-driven formulation shifts are compressing legacy production economics while opening premium positioning for qualified suppliers with integrated technical capabilities.
Continuous catalytic hydrogenation reactor designs are expanding into industrial-grade cyclohexylamine production, replacing batch aniline hydrogenation with lower-energy intensity flow chemistry. Shandong and Jiangsu producers are piloting these systems at scale, reducing carbon footprint per ton while maintaining 98.5 percent purity thresholds for rubber chemical buyers. This technology is expanding into cost-competitive export supply, pressuring European batch producers on energy-adjusted unit economics.
ECHA's REACH authorization timeline for existing substance dossiers is tightening toxicological data requirements for cyclohexylamine volume holders, elevating registration maintenance costs for smaller producers. The regulation is forcing consolidation among EU-based suppliers unable to sustain full safety study portfolios, concentrating registered supply among integrated amines platforms with dedicated regulatory affairs infrastructure. Water treatment formulators are responding by dual-sourcing from REACH-registered EU suppliers and pre-registered Asian exporters to manage authorization risk.
Specification-driven procurement is consolidating buyer power among large water treatment chemical distributors, compressing spot market liquidity for unqualified material. These distributors are integrating backward into formulation engineering services, unbundling traditional supplier relationships and capturing margin that previously accrued to commodity producers. The shift is most visible in German and French industrial boiler service markets, where technical service contracts now specify performance outcomes rather than input chemical volumes.
Cyclohexylamine Market Segmentation
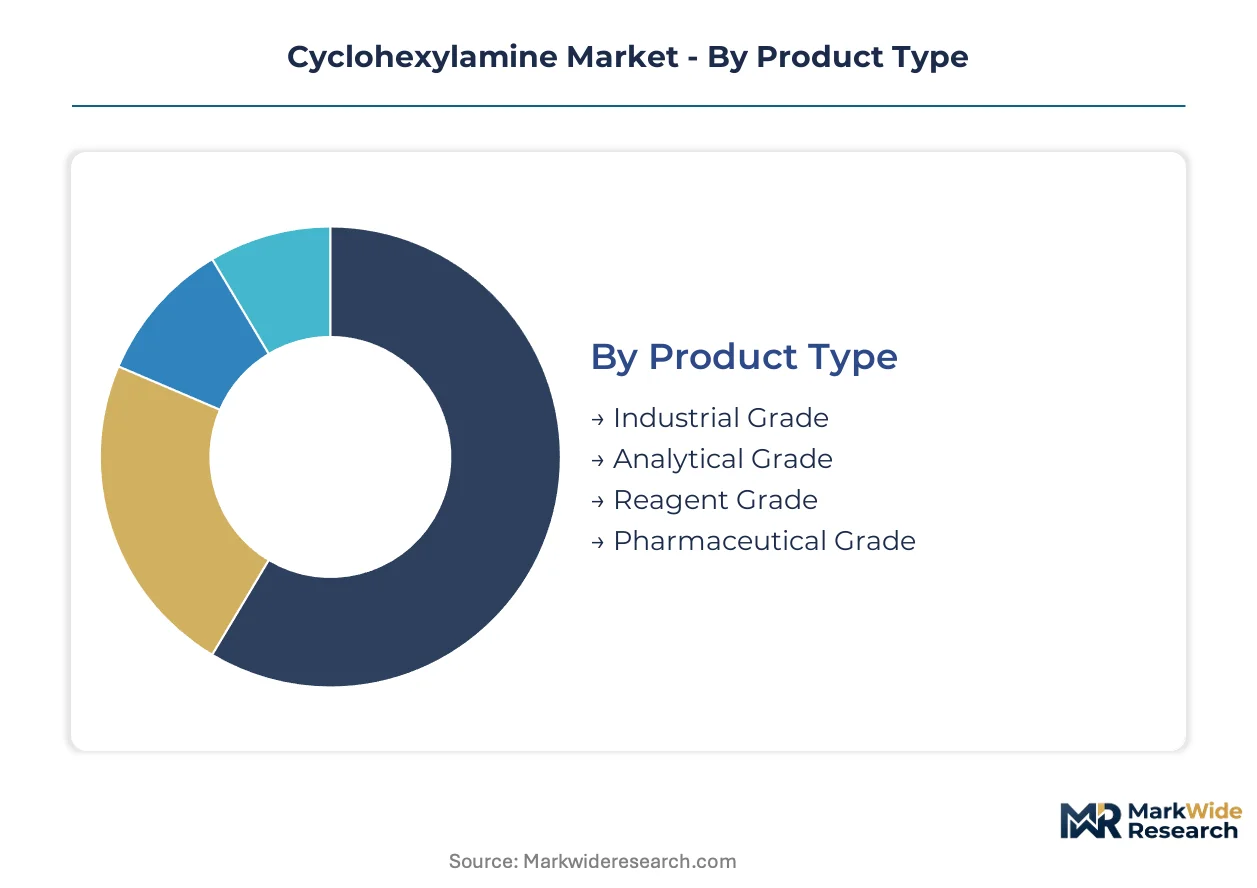
Cyclohexylamine's market structure reflects divergent purity requirements across downstream applications. Specification tiers create distinct margin pools, with pharmaceutical-grade material commanding qualification premiums while industrial-grade volumes anchor commodity throughput.
Product Type:
Standalone formulations dominate high-purity segments, while embedded intermediate use characterizes industrial grades.
- Industrial Grade:Supplied at 98.5 percent purity for rubber accelerator synthesis and boiler water treatment formulations. Demand concentrates in East China's Shandong-Jiangsu chemical corridor, where integrated cyclohexanone-to-amine clusters serve domestic rubber chemical manufacturers.
- Pharmaceutical Grade:Requires 99.5 percent-plus purity with FDA-compliant documentation and CDMO qualification. European and North American producers capture premium pricing through 18-24 month certification cycles that lock out unqualified competitors.
- Analytical Grade:Standardized for laboratory quality control and method validation protocols.
- Reagent Grade:Purified for research-scale organic synthesis and academic procurement.
Volume placements concentrate in Industrial Grade; the faster expansion belongs to Pharmaceutical Grade.
Application:
Cost tier stratification separates commodity intermediate demand from premium synthesis applications.
- Rubber Chemicals:Sulfenamide-class accelerator production consumes the largest volume share, with tire manufacturers in China's chemical manufacturing corridor pulling material through captive production clusters. REACH-compliant corrosion inhibitor formulations are displacing legacy amine chemistries in European water treatment, forcing requalification of product lines.
- Agricultural Chemicals:N-substituted cyclohexylamine derivatives are gaining fungicide and herbicide registrations in Brazil and India, opening derivative synthesis pathways beyond traditional industrial applications.
- Pharmaceuticals:Precursor molecules for active pharmaceutical ingredients require documented purity and regulatory compliance.
- Dyes:Intermediate use in azo dye synthesis and pigment manufacturing.
Volume placements concentrate in Rubber Chemicals; Agricultural Chemicals is climbing the fastest.
End User:
Customer type determines procurement modality, with large chemical manufacturers favoring direct supply contracts.
- Chemical Manufacturers:Integrated rubber chemical producers in China consume industrial-grade material through backward-linked cyclohexanone feedstock access. BASF SE leverages its integrated amines platform to bundle application engineering with bulk supply in European water treatment.
- Pharmaceutical Companies:CDMO-qualified buyers enforce 99.5 percent-plus purity standards with full toxicological dossiers under ECHA REACH requirements.
- Agriculture Sector:Formulators in Brazil and India drive N-substituted derivative demand for fungicide synthesis.
- Research Laboratories:Fragmented procurement of analytical and reagent grades through distributor channels.
Volume placements concentrate in Chemical Manufacturers; the steepest expansion trajectory belongs to Pharmaceutical Companies.
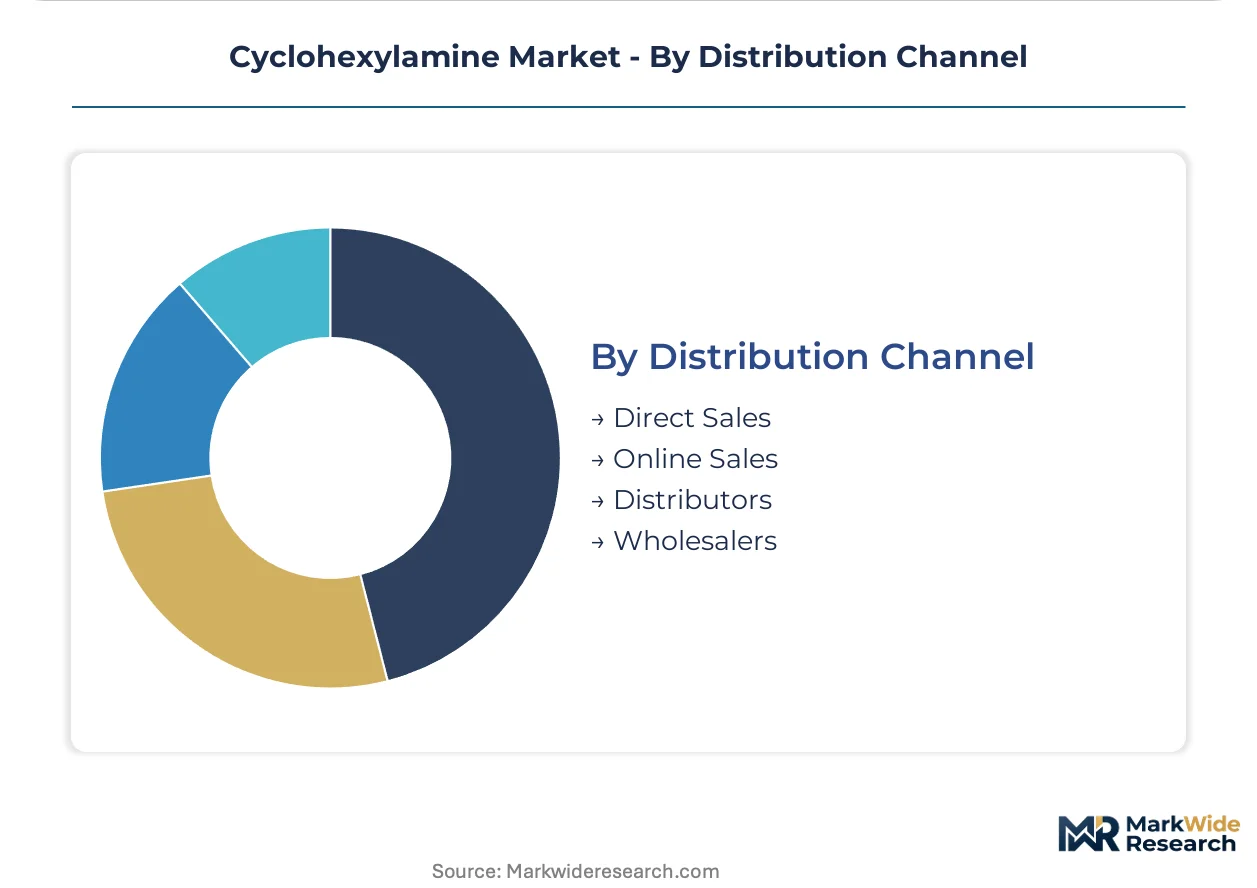
Distribution Channel:
Supply concentration geography shapes channel selection, with clustered production favoring direct procurement.
- Direct Sales:Large water treatment chemical distributors in Germany and France are integrating backward into formulation engineering services, unbundling traditional supplier relationships and capturing margin through technical service contracts specifying performance outcomes.
- Distributors:Specification-driven procurement is consolidating buyer power among large distributors, compressing spot market liquidity for unqualified material.
- Online Sales:Research-grade material procurement for academic and laboratory buyers.
- Wholesalers:Regional bulk supply for smaller industrial formulators.
Volume placements concentrate in Direct Sales; margin expansion belongs to Distributors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China manufactures the majority of global cyclohexylamine output through Shandong-Jiangsu corridor clusters, while consumption concentrates in tire-producing regions and European water treatment systems. This production-consumption divide shapes trade flows and regulatory arbitrage strategies across major markets.
China
Shandong and Jiangsu provinces host integrated cyclohexanone-to-amine production clusters serving domestic rubber accelerator manufacturers. MEE dual carbon goals pressure coal-based aniline feedstock routes, nudging producers toward lower-intensity cyclohexanone-derived pathways. East China's chemical manufacturing corridor pulls captive cyclohexylamine through backward-linked feedstock access for sulfenamide-class accelerator output.
Germany
REACH-compliant corrosion inhibitor formulations displace legacy amine chemistries in industrial boiler water treatment, consolidating procurement toward ECHA-registered suppliers. ECHA's full toxicological dossier requirements filter out non-compliant producers, concentrating qualified supply among integrated amines platforms. BASF SE leverages its Ludwigshafen complex to bundle application engineering with bulk supply in German and French industrial service markets.
United States
Tire manufacturers and rubber chemical producers anchor North American demand through captive consumption into downstream accelerators. EPA oversight of boiler water treatment chemical discharge limits shapes product formulation standards for water treatment distributors. Huntsman Corporation anchors regional supply through integrated rubber chemicals production in Texas and Louisiana manufacturing corridors.
India
Agricultural chemical formulators expand offtake as N-substituted cyclohexylamine derivatives gain registration for fungicide and herbicide synthesis. CDSCO and BIS certification timelines for imported amine specifications create qualification barriers for unregistered foreign suppliers. Alkyl Amines Chemicals Limited and domestic formulators in Maharashtra and Gujarat serve regional agrochemical intermediate demand.
Brazil
Underpenetrated fungicide intermediate demand offers first-mover positioning for suppliers with established ANVISA regulatory navigation capabilities. ANVISA registration requirements for agrochemical precursors enforce toxicological data standards that favor qualified exporters from REACH-registered jurisdictions. São Paulo and Minas Gerais states concentrate agrochemical formulation capacity pulling imported cyclohexylamine derivatives.
Cyclohexylamine Market Vendor Landscape
Capital-heavy producers compete with asset-light formulators across distinct value capture layers in cyclohexylamine supply. Integrated petrochemical majors with captive amines platforms dominate bulk industrial-grade throughput, while specialized CDMO-qualified producers capture pharmaceutical-grade premiums. Three archetypes define competitive positioning: integrated multinational chemical conglomerates with regulatory affairs infrastructure, regional Chinese producers with cost-advantaged cyclohexanone feedstock access, and specialty amine houses with pharmaceutical qualification capabilities. Capacity expansion in East China and REACH registration maintenance in Europe represent the dominant competitive moves reshaping supply concentration.
Among integrated multinational conglomerates, BASF SE and Evonik Industries exemplify the regulatory-capability archetype, leveraging ECHA-registered positions to bundle technical services with commodity volumes. Shandong Yufeng Chemical Co., Ltd. occupies a distinct position as a Chinese producer with integrated cyclohexanone feedstock access in Shandong province, representing the cost-optimized supply archetype for industrial-grade material. These three companies anchor the tiered competitive structure, with BASF SE and Evonik Industries sitting within the premium-regulatory tier and Shandong Yufeng Chemical Co., Ltd. anchoring the scale-driven export tier.
| Leading Market Players |
|---|
| Aditya Birla Chemicals |
| Evonik Industries |
| BASF SE |
| Shandong Yufeng Chemical Co., Ltd. |
| Alkyl Amines Chemicals Limited |
| Huntsman Corporation |
| LANXESS |
| Arkema Group |
| Eastman Chemical Company |
| Others |
Supply Flow & Price Mechanics
Pharmaceutical-grade certification ladders create a bifurcated value capture architecture, with 99.5 percent-plus purity material commanding sustained premiums through CDMO qualification barriers while industrial-grade volumes trade on cyclohexanone feedstock economics in East China's Shandong-Jiangsu corridor. This tier divergence manifests in pricing power concentration among ECHA-registered European suppliers and supply chain clustering around integrated amines platforms with dedicated regulatory affairs infrastructure.
Pricing Analysis
Margin tightening in industrial-grade material reflects continuous catalytic hydrogenation reactor deployment by Shandong and Jiangsu producers, compressing energy-adjusted unit economics for batch-based European competitors. Three-tier pricing structure across pharmaceutical-grade, REACH-registered industrial-grade, and unqualified spot material separates qualification-burdened premium tiers from commodity export volumes. Cost-down pressure on unqualified material accelerates as specification-driven procurement consolidates buyer power among German and French water treatment distributors. Rubber chemical manufacturers in East China exhibit highest price sensitivity due to captive cyclohexanone feedstock access, while pharmaceutical CDMOs demonstrate lowest sensitivity given 18-24 month certification lock-in.
Supply Chain Analysis
Cyclohexanone feedstock supply rests on Shandong and Jiangsu petrochemical complexes, with aniline-derived hydrogenation routes tethered to coal-based chemical economics under MEE dual carbon enforcement. Raw material dependencies span cyclohexanone, aniline, and hydrogen feedstocks, with catalytic hydrogenation catalysts sourced from specialty chemical producers. Geographic supply concentration in two Chinese provinces creates single-point vulnerability for international buyers dependent on export volumes. Distribution runs through direct sales contracts for large water treatment formulators and distributor channels for smaller industrial buyers.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Cyclohexylamine competitive dynamics are accelerating into a vertical-integration race, with producers pursuing backward control over cyclohexanone feedstock to defend margin pools against continuous flow chemistry cost compression.
For Market Incumbents: Deepen captive cyclohexanone supply integration in East China to offset MEE carbon intensity pressures on coal-based aniline routes. Expand REACH registration maintenance infrastructure to filter out smaller competitors unable to sustain full toxicological dossiers. Prioritize technical service bundling in German and French water treatment accounts to capture formulation engineering margins beyond commodity volumes. For New Entrants and Emerging Players: ANVISA registration pathways in Brazil open a window for first-mover positioning in underpenetrated fungicide intermediate demand. Target agricultural chemical formulators in São Paulo and Minas Gerais states with N-substituted derivative offerings qualified for REACH-equivalent toxicological standards. Deploy regulatory navigation capabilities as core go-to-market wedge against established commodity exporters. For Investors and Strategic Acquirers: Re-rating potential sits with CDMO-qualified pharmaceutical-grade specialists given FDA documentation burdens that lock out unqualified competitors. Long-term viability favors producers with integrated cyclohexanone feedstock access and ECHA-registered positions spanning the analysis window. Watch MEE dual carbon enforcement timelines as inflection indicator for hydrogenation route economics.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Cyclohexanone | Shandong producers secure feedstock cost advantage against aniline-route competitors facing MEE carbon benchmarks. |
| REACH Registration Maintenance | ECHA dossier requirements consolidate supply among integrated amines platforms with dedicated regulatory infrastructure. |
| Continuous Flow Chemistry Deployment | Shandong-Jiangsu pilots reduce energy intensity per ton while maintaining 98.5 percent purity thresholds. |
| Technical Service Bundling | BASF leverages Ludwigshafen complex to capture formulation engineering margins in German boiler service markets. |
| ANVISA Regulatory Navigation | First-mover suppliers establish qualified positions in Brazilian agrochemical intermediate demand ahead of competitor entry. |
Methodological Framework
Trade association data, regulatory filings, and customs records anchored secondary inputs, cross-referenced with primary interviews involving rubber chemical procurement managers, water treatment formulators, pharmaceutical CDMO technical directors, and agricultural chemical R&D leads. Bottom-up volume triangulation against top-down value estimates incorporated ECHA REACH registration databases, MEE environmental compliance disclosures, and ANVISA agrochemical precursor filings. Primary fieldwork validated cyclohexanone-to-amine production economics and continuous hydrogenation reactor deployment timelines.
Segment-level granularity modeled purity tiers, end-use applications, and regional production hub configurations across the projection horizon. CAGRs derived from elasticity-adjusted demand modeling for rubber accelerator, corrosion inhibitor, and agricultural derivative offtake. Industry-specific forecast inputs included tire production capacity expansion in East China and ECHA authorization timeline assumptions for existing substance dossiers.
Caveats apply where MEE dual carbon enforcement intensity, REACH authorization delays, or ANVISA registration timeline shifts could materially shift the outlook. Forecasts reflect stated assumptions on feedstock route economics and regulatory compliance trajectories. A small set of named triggers—carbon intensity benchmark revisions, ECHA dossier requirement tightening, and Brazilian agrochemical registration acceleration—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Bulk Chemicals
Ferric Sulphate and Polyferric Sulphate Market
Bulk Chemicals
Activated Bleaching Earth Market
Bulk Chemicals
Aerospace and Defense Chemical Distribution Market
Bulk Chemicals
Precipitated Fine Hydrate Market
Bulk Chemicals
Gypsum-Free Lactic Acid Market
Bulk Chemicals
Europe Carbon Black Market
Bulk Chemicals
North America Methyl Acrylate Market
Bulk Chemicals
United States Calcium Chloride Market
Bulk Chemicals
Carbon Disulfide Market
Bulk Chemicals
USA and Canada Potassium Sulfate Market
Bulk Chemicals
Magnesium Chloride Market
Bulk Chemicals
Potassium Carbonate Market
Bulk Chemicals
Caustic Potash Market
Bulk Chemicals
FT Wax Market
Bulk Chemicals
Bromacil Market
Bulk Chemicals
North America Malic Acid Market