
 N-Hexyl Chloride Market | 2026-2036
N-Hexyl Chloride Market Size, Share, and Industry Trends Forecast 2026-2036
N-Hexyl Chloride Market Analytics
Specialty chemical distribution channels serving Asian pharmaceutical intermediates is reconfiguring around consolidated supplier networks. Evonik leverages its German manufacturing base to sustain high-purity supply lines into European laboratories. CABB Chemicals anchors chlorination expertise through integrated production assets in Central Europe. Mainchem competes on flexible packaging configurations for drum and bulk container shipments across Pacific Rim markets.
N-hexyl chloride is a straight-chain alkyl halide with formula C6H13Cl, typically synthesized via thionyl chloride or phosphorus trichloride conversion of n-hexanol, and functions primarily as an alkylating agent and solvent in organic synthesis. Industrial grade material dominates volume flows into agrochemical intermediates where margin pools remain thin, while pharmaceutical grade commands premium positioning through stringent impurity controls demanded by FDA and EMA filers. Specialty grade applications in extraction processes represent the fastest-expanding segment as botanical and natural product processors adopt chlorinated solvents for selective compound recovery.
EPA oversight under the Toxic Substances Control Act shapes permissible chlorinated solvent applications in United States manufacturing, while REACH registration requirements in Europe restrict non-compliant import volumes. China's SAMR enforces GB standards on halogenated chemical purity that determine market access for domestic and foreign producers. Stakeholders must monitor evolving MEE environmental enforcement in China and potential F-Gas Regulation extensions that could recategorize chlorinated aliphatics in European climate policy.
Market Dynamics
Pharmaceutical-grade purification specifications are tightening faster than incumbent chlorination capacity can adapt, forcing asset reconfiguration across European and Asian supply bases. The divergence between industrial-grade agrochemical demand and high-purity pharmaceutical requirements is splitting supplier economics into incompatible operating models.
Growth Catalysts
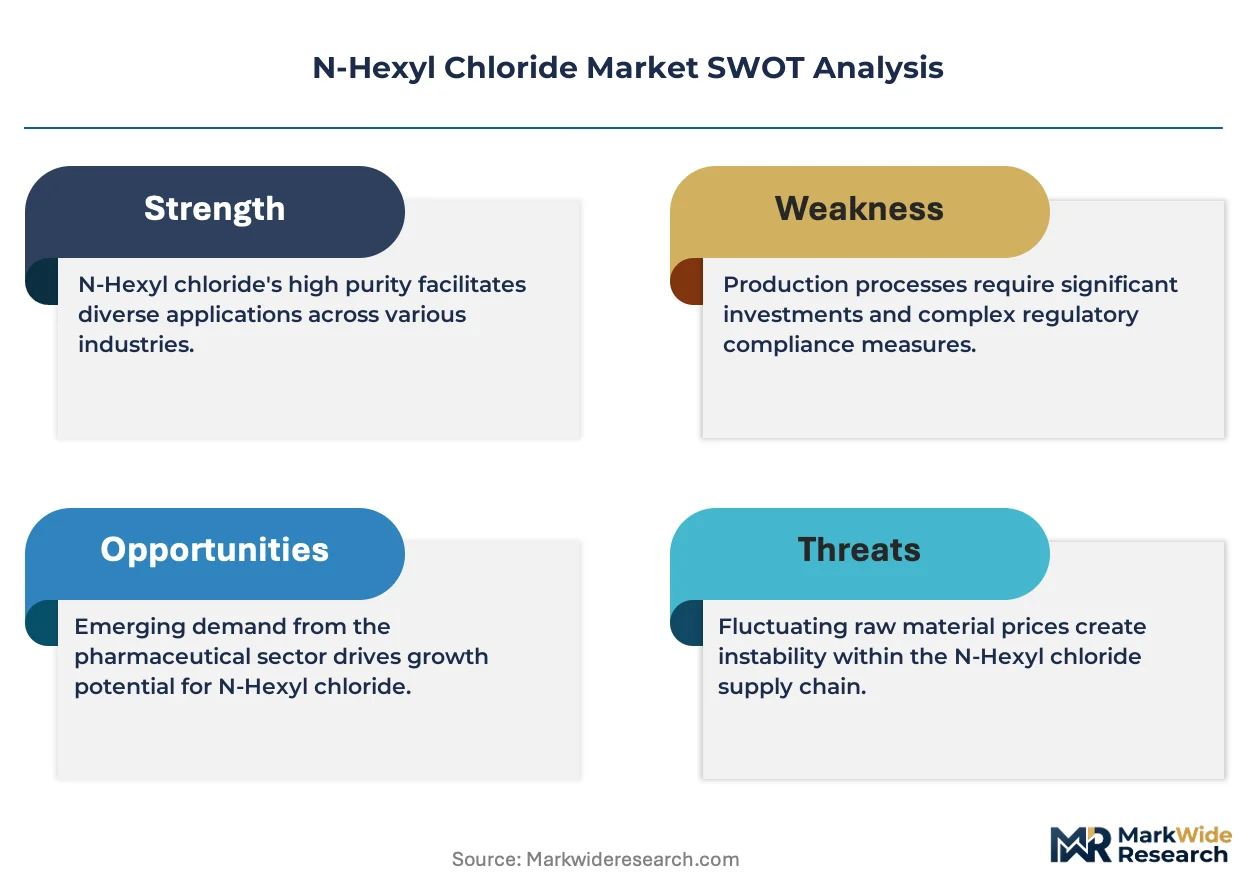
- Pharmaceutical intermediates expansion:Alkylating agent demand from CDSCO-registered Indian manufacturers and NMPA-filing Chinese synthetic drug producers is accelerating batch procurement of 99.5%+ purity material.
- REACH Article 33 compliance:European laboratory chemical distributors are consolidating supplier lists around REACH-registered chlorinated solvent sources, eliminating non-compliant traders from qualified vendor pools.
- Extraction solvent adoption:Botanical processors in East China's Jiangsu-Zhejiang corridor are substituting n-hexyl chloride for legacy hydrocarbon solvents in selective compound recovery workflows.
Market Restraints
- Thionyl chloride feedstock volatility:Sulfur and chlorine input costs swing with energy pricing, compressing margin predictability for batch chlorination operators.
- Central European supply concentration:Integrated chlorination assets in Germany and the Czech Republic control disproportionate high-purity capacity, creating geographic vulnerability to regional energy disruptions.
- Aqueous phase substitution:Enzymatic alkylation methods in early-stage pharmaceutical synthesis are displacing halogenated reagents in select coupling reactions.
Strategic Opportunities
- Indian pharmaceutical corridor penetration:Maharashtra and Gujarat states lack domestic high-purity chlorinated solvent production, creating import substitution openings for compliant exporters.
- SAMR-GB standard alignment:Foreign producers achieving GB 31604 halogenated chemical purity certification gain preferential access to China's state procurement channels for laboratory reagents.
- Specialty grade channel innovation:Direct technical service relationships with botanical extractors bypass commodity chemical distributors, capturing premium pricing through formulation support.
Industry Challenges
- Pharmaceutical validation timeline compression:FDA and EMA filing deadlines for generic drug approvals are compressing supplier qualification windows, straining documentation throughput.
- Multi-jurisdiction registration burden:Simultaneous REACH, TSCA, and NMPA substance notifications require dedicated regulatory affairs capacity that mid-scale producers struggle to staff.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | N-Hexyl Chloride Market |
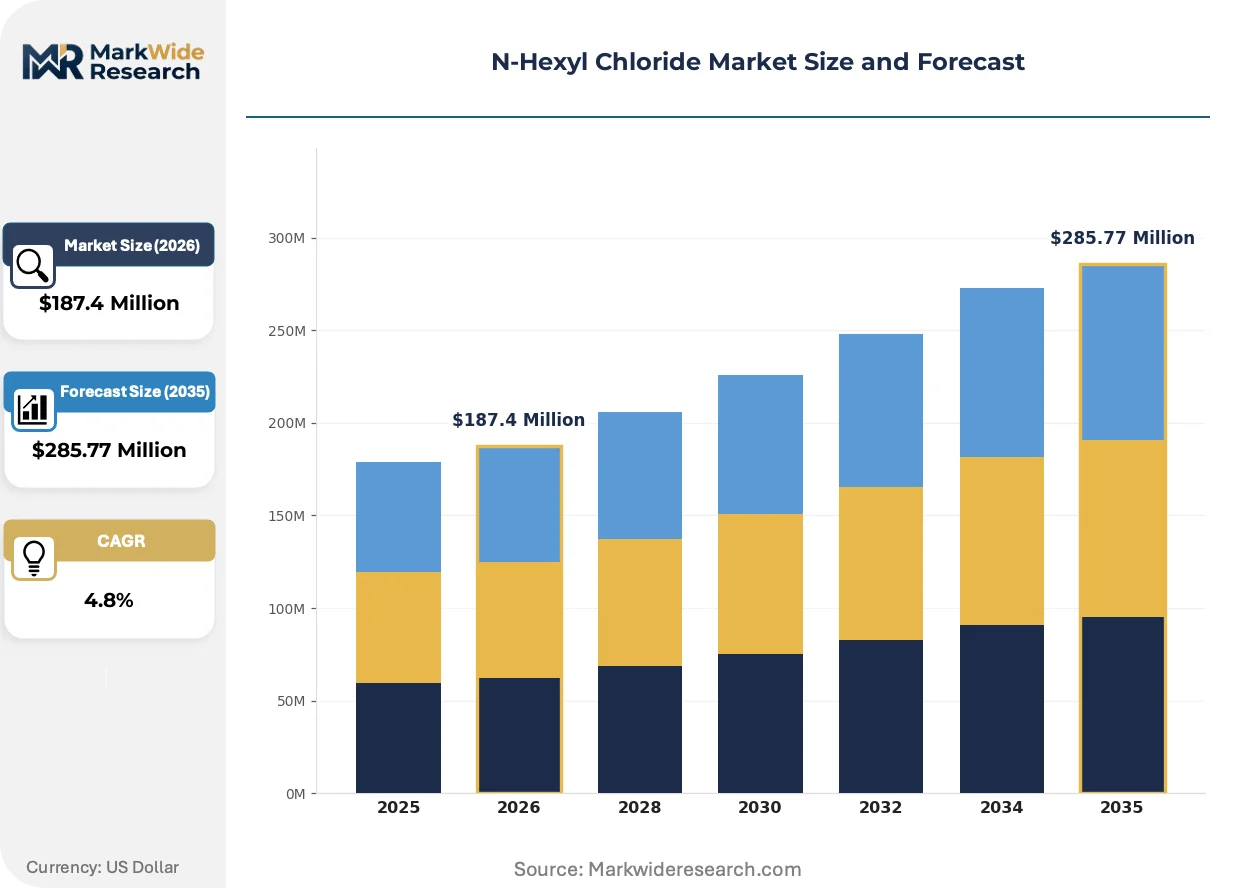
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $285.77 Million |
| CAGR (2026 – 2036) | 4.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Industrial Grade, Pharmaceutical Grade, Specialty Grade, Research Grade Application: Solvent, Intermediate, Chemical Synthesis, Extraction End User: Pharmaceuticals, Agrochemicals, Chemicals, Laboratories Packaging Type: Drums, Bottles, Tankers, Bulk Containers |
| Companies Covered | Sanmenxia Aoke Chemical Industry Co., Ltd., SHANGHAI TRUSTIN CHEMICAL CO.,LTD, Yangzhou City Prince Pharmaceutical Co., Ltd., Wuxi Orient Detergent Technology Company Limited, Evonik, Sigma Aldrich, Mainchem, CABB Chemicals, Parchem, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
N-Hexyl Chloride Market Evolving Landscape
Process analytical technology is penetrating chlorinated solvent production, replacing offline quality control with inline monitoring that compresses batch release cycles. The convergence of digital instrumentation and regulatory data integrity requirements is reshaping how purity is verified and documented.
Inline Raman spectroscopy is digitizing real-time impurity detection during thionyl chloride conversion of n-hexanol, enabling adaptive process control that reduces out-of-specification batches. Pharmaceutical contract manufacturers in Germany and Switzerland are adopting these systems fastest, driven by EMA data integrity guidelines for active pharmaceutical ingredient starting materials. The technology is compressing quality assurance headcount while tightening release documentation.
EPA enforcement under the Toxic Substances Control Act is intensifying for chlorinated aliphatic importers, requiring pre-manufacture notifications for new supply chain configurations. Industrial-grade consumers in US agrochemical synthesis face extended approval timelines for volume increases, pushing some demand toward pre-registered European sources. The policy friction is segmenting the American market between grandfathered high-volume users and constrained new entrants.
Consolidated supplier networks are displacing fragmented trader intermediaries in Asian pharmaceutical procurement. End-users in India's CDSCO-regulated generic drug sector now demand direct manufacturer relationships with audit rights and dedicated inventory buffers. The channel restructuring is most visible in Mumbai and Hyderabad, where large formulation houses have eliminated non-exclusive distributors from approved vendor lists.
N-Hexyl Chloride Market Segmentation
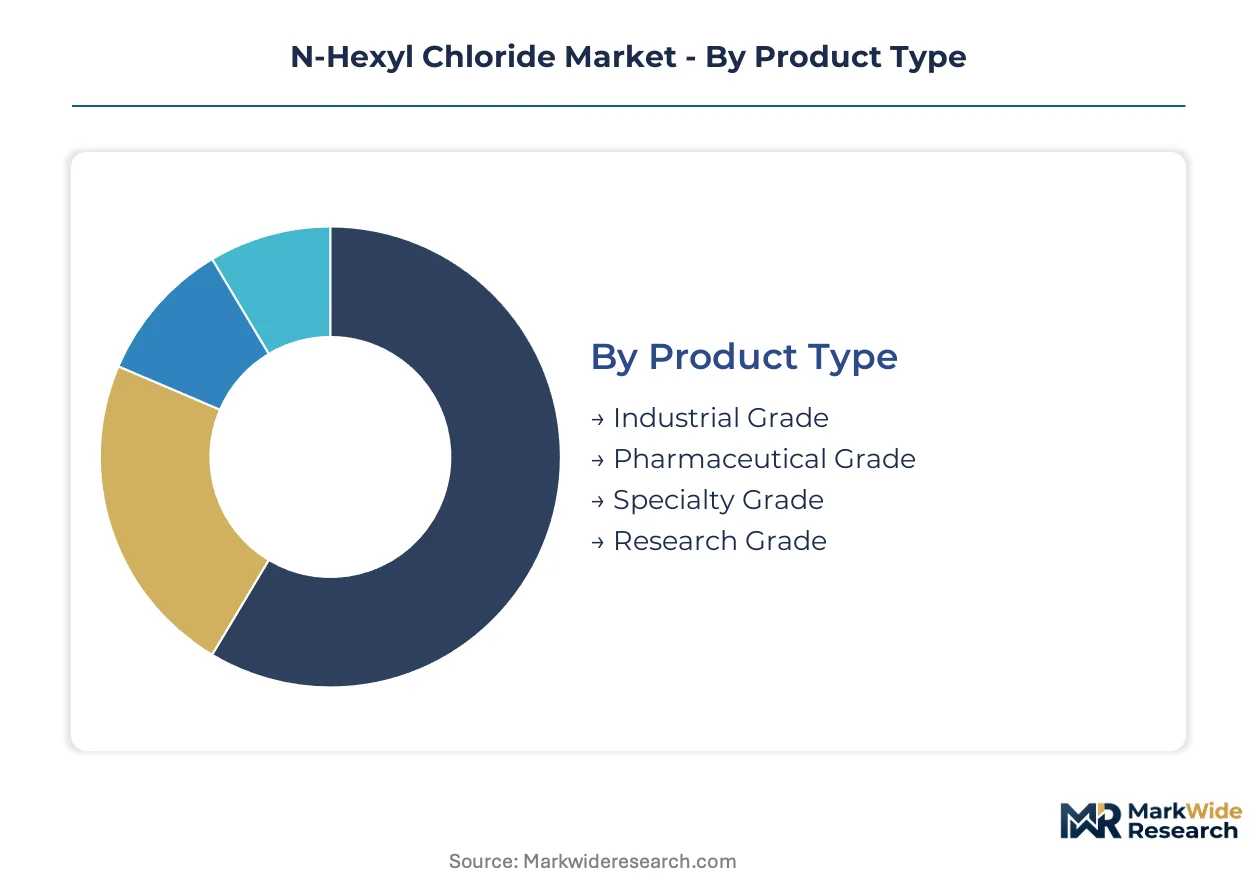
N-hexyl chloride procurement patterns diverge sharply across purity tiers and end-use specifications. Pharmaceutical-grade validation requirements create service-intensive relationships that industrial-grade commodity flows cannot support.
Product Type:
After-sales service intensity escalates dramatically from industrial through research grades, with pharmaceutical and specialty tiers demanding dedicated technical support, regulatory documentation, and batch-specific certification.
- Industrial Grade:Material meeting 95-98% purity specifications serves agrochemical intermediate synthesis where cost minimization dominates procurement decisions. Jiangsu province's pesticide manufacturers absorb the largest volumes, though margin compression from thionyl chloride feedstock volatility limits supplier profitability.
- Pharmaceutical Grade:99.5%+ purity material with controlled impurity profiles supports FDA and EMA filing pathways for alkylating agents. CDSCO-registered Indian manufacturers and NMPA-filing Chinese synthetic drug producers are consolidating procurement around REACH-registered European suppliers with dedicated inventory buffers.
- Specialty Grade:Purified for selective extraction workflows in botanical processing; East China's Jiangsu-Zhejiang corridor processors substitute this material for legacy hydrocarbon solvents in natural product recovery.
- Research Grade:Ultra-high purity lots with comprehensive analytical data packages serve academic and contract research laboratories; Swissmedic-regulated Swiss facilities and German Max Planck Institute networks represent core demand nodes.
Industrial grade holds the largest share; momentum sits with specialty grade.
Application:
Application selection determines regulatory exposure, with solvent uses facing stricter EPA and REACH oversight than captive intermediate consumption.
- Solvent:Functions in organic synthesis and extraction workflows; botanical processors in East China are substituting n-hexyl chloride for legacy hydrocarbons under tightening MEE environmental enforcement.
- Intermediate:Serves as alkylating agent precursor in pharmaceutical and agrochemical synthesis; Maharashtra and Gujarat pharmaceutical corridors lack domestic high-purity production, creating import dependency.
- Chemical Synthesis:General reagent applications span multiple industrial sectors; enzymatic alkylation methods are displacing halogenated reagents in select early-stage pharmaceutical coupling reactions.
- Extraction:Selective compound recovery from natural matrices represents the steepest expansion trajectory as processors adopt chlorinated solvents for targeted botanical isolation.
Intermediate applications dominate current volumes; extraction is gaining share fastest.
End User:
End-user concentration in pharmaceuticals creates qualification bottlenecks that agrochemical and laboratory segments bypass through less stringent purity requirements.
- Pharmaceuticals:CDSCO-registered Indian generic manufacturers and NMPA-filing Chinese synthetic drug producers drive demand for 99.5%+ purity material with full regulatory documentation.
- Agrochemicals:Pesticide and herbicide intermediate synthesis consumes industrial-grade volumes; Jiangsu province manufacturers prioritize cost over certification depth.
- Chemicals:General industrial synthesis applications span multiple sectors; specialty chemical distributors are consolidating supplier networks around compliant sources.
- Laboratories:Academic and contract research facilities require research-grade material with comprehensive analytical data; German and Swiss facilities lead adoption of inline Raman spectroscopy for quality verification.
Pharmaceuticals command premium positioning; laboratories show the most rapid demand acceleration.
Packaging Type:
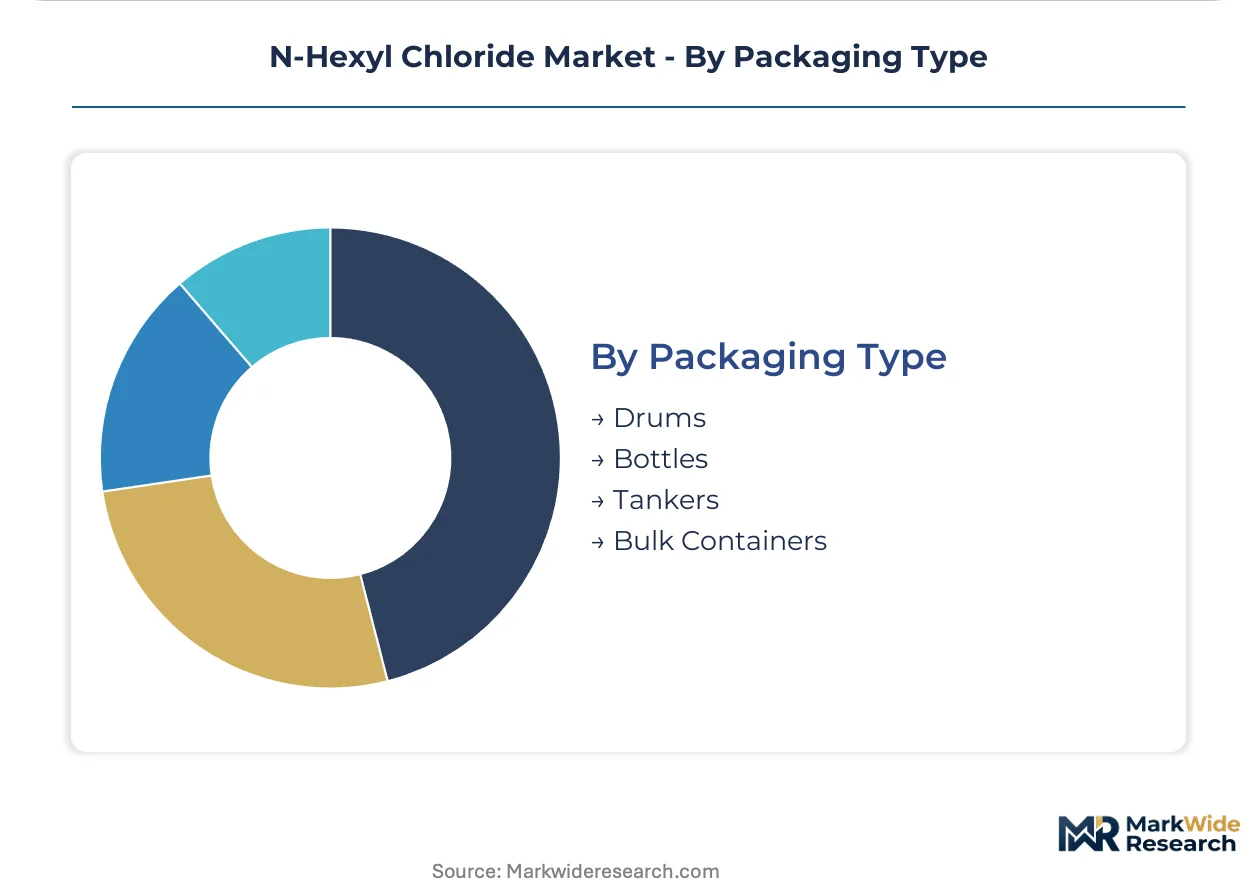
Packaging configuration directly ties to end-user scale and handling infrastructure, with drum shipments dominating fragmented laboratory procurement and bulk containers serving integrated manufacturers.
- Drums:Standard 200-liter steel drums serve mid-scale pharmaceutical and chemical manufacturers; Mainchem competes on flexible drum configurations across Pacific Rim markets.
- Bottles:Small-volume glass and fluoropolymer bottles target research laboratories and pilot-scale operations; Swiss and German facilities prefer dedicated inventory buffers for critical reagents.
- Tankers:Dedicated chemical tankers serve high-volume agrochemical intermediate producers; Central European integrated chlorination assets control disproportionate tanker-shipment capacity.
- Bulk Containers:Intermediate bulk containers and ISO tanks support just-in-time delivery to large formulation houses; Mumbai and Hyderabad facilities have eliminated non-exclusive distributors from approved vendor lists.
Drums retain the largest installed base; bulk containers are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's SAMR anchors the dominant geography through GB 31604 halogenated chemical purity standards that determine market access for domestic and foreign producers. Jiangsu and Zhejiang provinces concentrate the heaviest demand from pharmaceutical and agrochemical manufacturers. Regulatory divergence across major economies is fragmenting supplier qualification pathways.
China
East China's chemical manufacturing corridor around Jiangsu and Zhejiang provinces drives volume demand from pesticide intermediate synthesis and botanical extraction operations. SAMR enforces GB standards on halogenated chemical purity that determine market access for domestic and foreign producers. MEE environmental enforcement is tightening discharge standards for chlorinated solvent processors in the Yangtze River Delta.
Germany
Evonik leverages its German manufacturing base to sustain high-purity supply lines into European laboratories and pharmaceutical contract manufacturers. REACH registration requirements restrict non-compliant import volumes and consolidate supplier lists around registered chlorinated solvent sources. The Rhine-Ruhr industrial region hosts integrated chlorination assets that control disproportionate high-purity capacity for EMA-filing drug producers.
India
Maharashtra and Gujarat states lack domestic high-purity chlorinated solvent production, creating import dependency for CDSCO-registered generic drug manufacturers. The country's national pharmaceutical regulator enforces filing deadlines that compress supplier qualification windows for alkylating agent procurement. Mumbai and Hyderabad formulation houses have eliminated non-exclusive distributors from approved vendor lists.
United States
EPA oversight under the Toxic Substances Control Act shapes permissible chlorinated solvent applications in manufacturing, with pre-manufacture notifications required for new supply chain configurations. Industrial-grade consumers in agrochemical synthesis face extended approval timelines for volume increases. The Gulf Coast petrochemical corridor maintains grandfathered high-volume consumption while new entrants confront regulatory constraints.
Switzerland
Swissmedic-regulated facilities and German Max Planck Institute networks represent core demand nodes for research-grade material with comprehensive analytical data packages. Swiss pharmaceutical contract manufacturers are adopting inline Raman spectroscopy fastest, driven by EMA data integrity guidelines for active pharmaceutical ingredient starting materials. Basel's life sciences cluster demands dedicated inventory buffers for critical reagents.
N-Hexyl Chloride Market Competitive Landscape
Integrated chlorination specialists and flexible packaging distributors split the market between high-purity validation-intensive supply and commodity volume flows. European assets concentrate disproportionate pharmaceutical-grade capacity while Asian traders compete on logistics configuration. Three archetypes dominate: German-based integrated manufacturers, Chinese provincial chemical enterprises, and Pacific Rim packaging specialists. Capacity expansion and regulatory certification investments constitute the dominant competitive moves.
Within the integrated manufacturing tier, Evonik and CABB Chemicals exemplify European high-purity positioning through captive chlorination assets and REACH-registered supply lines. Among China-based producers, Sanmenxia Aoke Chemical Industry Co., Ltd. and SHANGHAI TRUSTIN CHEMICAL CO.,LTD occupy positions serving domestic agrochemical and pharmaceutical intermediate demand. Mainchem represents the Pacific Rim packaging-specialist archetype, competing on flexible drum and bulk container configurations across regional markets.
| Leading Market Players |
|---|
| Sanmenxia Aoke Chemical Industry Co., Ltd. |
| SHANGHAI TRUSTIN CHEMICAL CO.,LTD |
| Yangzhou City Prince Pharmaceutical Co., Ltd. |
| Wuxi Orient Detergent Technology Company Limited |
| Evonik |
| Sigma Aldrich |
| Mainchem |
| CABB Chemicals |
| Parchem |
| Others |
Value Network & Pricing Analysis
Central European integrated chlorination assets in Germany and the Czech Republic concentrate pharmaceutical-grade capacity, anchoring margin pools in REACH-registered supply lines while Asian traders compete on logistics configuration for industrial-grade volumes.
Pricing Analysis
Geographic price spreads between Central European pharmaceutical-grade material and East Asian industrial-grade supply run 40-60% at the dock. Three-tier pricing structure across pharmaceutical, specialty, and industrial grades separates validation-intensive supply from commodity spot transactions. Cost compression in industrial-grade agrochemical tiers is intensifying because thionyl chloride feedstock volatility transfers directly to batch chlorination operators. Agrochemical intermediate manufacturers in Jiangsu province exhibit highest price sensitivity; CDSCO-registered Indian pharmaceutical houses show lowest sensitivity due to regulatory qualification lock-in.
Supply Chain Analysis
Thionyl chloride and phosphorus trichloride feedstocks draw from sulfur and chlorine commodity markets tied to energy pricing swings. Supply concentrates disproportionately in Germany, China, and India across the three purity tiers. Raw material dependencies rest on n-hexanol precursor supply, thionyl chloride conversion capacity, and halogenated solvent logistics infrastructure. Single-source vulnerability sits with Central European high-purity chlorination assets exposed to regional energy disruption. Distribution runs through consolidated supplier networks displacing fragmented trader intermediaries in Asian pharmaceutical procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents face substitution defense as enzymatic alkylation methods displace halogenated reagents in early-stage pharmaceutical coupling reactions, requiring moat reinforcement around regulatory documentation and qualification timelines.
For Market Incumbents: Build regulatory documentation moats through REACH-registered supply lines and dedicated inventory buffers for CDSCO-registered Indian manufacturers. Backward integration into thionyl chloride conversion capacity in Central Europe defends margin position against feedstock volatility. Channel control through direct technical service relationships with botanical extractors in East China captures premium pricing through formulation support.
For New Entrants and Emerging Players: Pursue Maharashtra and Gujarat pharmaceutical corridor penetration where domestic high-purity chlorinated solvent production gaps create import substitution openings. SAMR-GB standard alignment unlocks preferential access to China's state procurement channels for laboratory reagents. Go-to-market angle centers on flexible packaging configurations for drum and bulk container shipments with just-in-time delivery commitments.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with Pacific Rim packaging specialists and mid-scale Chinese provincial chemical enterprises lacking multi-jurisdiction registration capacity. Long-term viability frames around regulatory compliance infrastructure as the primary value determinant across the projection horizon. Acquisition target archetype: REACH-registered European chlorination assets with captive pharmaceutical-grade capacity. Signal to watch: FDA and EMA filing deadline compression accelerating supplier consolidation around qualified vendor pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Thionyl Chloride | Captive feedstock supply insulates margin from sulfur and chlorine commodity volatility. |
| REACH Registration Investment | Registration unlocks European laboratory chemical distributor consolidation around compliant sources. |
| Inline Raman Spectroscopy Deployment | Real-time impurity detection compresses batch release cycles for EMA data integrity compliance. |
| Direct Technical Service Relationships | Bypassing commodity distributors captures premium pricing from botanical extractors in Jiangsu-Zhejiang. |
| Flexible Packaging Configuration Expansion | Drum and bulk container customization serves Pacific Rim just-in-time delivery requirements. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of customs trade data, ECHA REACH registration databases, and SAMR GB standard filings. Primary interviews spanned plant managers at chlorination facilities, procurement leads at CDSCO-registered Indian pharmaceutical manufacturers, distribution channel partners in Pacific Rim markets, and technical R&D directors at European contract manufacturers. Secondary validation drew from SEC 10-K disclosures of listed chemical producers, Cefic sector reports, and NMPA substance notification records. Bottom-up volume triangulation across purity tiers and end-use segments was cross-checked against top-down market sizing from trade flow analysis.
Forecast inputs considered grade tier segmentation, end-use industry demand patterns, packaging format adoption curves, and regional production hub capacity utilization across the modeling period. Analytical framework modeled alkylating agent demand from pharmaceutical intermediates expansion, extraction solvent substitution trends in botanical processing, and aqueous phase displacement risk in early-stage synthesis. CAGRs were derived from regression analysis of historical volume trends against projected regulatory filing timelines and capacity expansion announcements.
Macroeconomic conditions sit as an overlay; deviation in energy pricing, sulfur commodity markets, or regional trade policy would shift the trajectory. Forecasts reflect documented assumptions about REACH enforcement continuity, SAMR GB standard implementation timelines, and EPA TSCA pre-manufacture notification processing capacity. Specific risk factors include MEE environmental enforcement intensification in the Yangtze River Delta and potential F-Gas Regulation extensions recategorizing chlorinated aliphatics. Cross-checking against ECHA registration volume data and Indian CDSCO import records is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Organic Chemicals
Lithium Chemicals Market
Organic Chemicals
2,5-Dimethyl-2,4-Hexadiene Market
Organic Chemicals
North America Organic Acid Market
Organic Chemicals
2-Amino-5-Nitrobenzophenone Market
Organic Chemicals
Acrylonitrile Market
Organic Chemicals
Organic Peroxide Market
Organic Chemicals
Chlorocyclopentane Market
Organic Chemicals
Global Biphenyl Market
Organic Chemicals
Benzethonium Chloride Market
Organic Chemicals
Synthetic and Bio-Based Aniline Market
Organic Chemicals
Behenyl Alcohol Market
Organic Chemicals
Oxo Chemicals Market
Organic Chemicals
Bio-Acetic Acid Market
Organic Chemicals
Organic Polysulfide Market
Organic Chemicals
Organic Chemicals Market
Organic Chemicals
Ethylamine Market